Arkema SA
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good morning. This is the conference operator.
Welcome, and thank you for joining the Arkema Third Quarter 2026 Results and Outlook Conference Call. As a reminder, all participants are in listen-only mode.
After the presentation, there will be an opportunity to ask questions by pressing *1 at any time. Should anyone need assistance during the conference call, they may signal an operator by pressing * and 0 on their telephone.
At this time, I would like to turn the conference over to Mr. Thierry Le Hénaff, Chairman and Chief Executive Officer.
Please go ahead.
Thierry Le Hénaff
Thank you. Good morning, everybody.
Welcome to Arkema's Q3 2026 results conference call. With me today are Marie-José Donsion, our CFO, and the Investor Relations team.
To support this conference call, we have posted, as usual, a set of slides which are available on our website, and I will start with some comments on the highlights of the quarter before letting Marie-José go through the financials. At the end of the presentation, we'll be available to answer your questions.
Let's start with the macroeconomic conditions we encountered in the third quarter, which remained challenging, oil and raw material prices as well as energy and logistics costs rose sharply over the summer as a consequence of renewed tension in the Middle East. Demand was soft overall, with no signs of recovery in Europe.
Asia slowed after several quarters of strong growth, particularly in China, while the US showed better demand compared to last year's Q3. In this environment, mostly challenging, Arkema delivered overall quite a solid performance, which varied across regions and product lines.
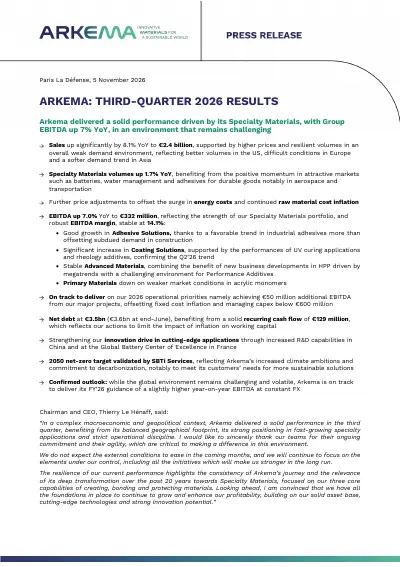
In Q3, sales grew materially by 8% year-on-year, supported by the price effect and driven notably by North America, where we benefit from our well-established footprint and which accounted for around 36% of group sales in Q3. The volume effect was slightly positive, with Specialty Materials delivering a solid 1.7% volume growth.
Besides, we increased our EBITDA by 7% to €330 million, which is significant and highlights once again the quality of our portfolio and the resilience of both our top line and profitability in a challenging environment. Besides, we increased our EBITDA by 7% to €330 million, which is significant and highlights once again the quality of our portfolio and the resilience of both our top line and profitability in a challenging environment.
Our performance was particularly solid considering the adverse impact of the conflict in the Middle East in Q3 and the absence of the acrylic support we saw in Q2. Our EBITDA margin remained stable at 14%.
This is a good performance to the extent that the dilutive impact of the pricing linked to inflation is around 1%. I'd like also to underline that our adjusted earnings per share increased strongly by 23% compared to last year.
Most importantly, all of this earnings growth came from our Specialty Materials, which are at the heart of our strategy and now represent 90% of group EBITDA. Looking at Specialty Materials segment, Adhesive and Coating Solutions showed particularly strong performances driven by richer product mix.
More precisely, Adhesive Solutions led the way with EBITDA up a strong 9%, building on the positive momentum seen in Q2. This was supported by the strength of industrial adhesives and acceleration in higher value-added solutions, especially in adhesive for durable goods in aerospace, transportation, and industrial application, while demand remained subdued in construction.
Coating Solutions EBITDA was up more than 20%, extending the positive Q2 dynamic in the modern downstream businesses, namely UV-curing application and rheology additives. Advanced Materials was roughly stable, benefiting from our new business development in high-performance polymers, while Performance Additives continued to suffer from the situation in Middle East.
Behind this performance of Specialty Materials, we continue to accelerate the commercialization of high-value-added solutions in attractive markets such as batteries, water management, and adhesive for durable goods. As a result, our EBITDA continuously benefit from the shifts in our product mix.
At the same time, we continue to benefit from the ramp-up of our major projects, which are expected to contribute to an additional €50 million of EBITDA in 2026 compared with last year. Given the ongoing growth in PVDF, the new capacity in the US starting at the end of Q2 came at the right time, and the same is true for our new Rilsan clear transparent polyamide unit in Singapore, which has enjoyed strong growth since the start of the year.
In Q3, we remained firmly focused on what we can control. As you see on slide number 4, we are on track to offset fixed costs inflation by year-end, with €55 million of cost savings delivered year-to-date.
We are also making good progress on headcount, with a reduction of more than 2% achieved by end September through natural attrition with no additional separation cost. We also remain highly disciplined on capital allocation.
We continue to tightly manage working capital and keep CapEx under strict control. Marie-José will comment this in more detail.
We are equally disciplined on pricing, taking the necessary action to offset raw material inflation and, more recently, the sharp rise in energy costs, particularly in Europe. Far, we have been able to offset these inflationary pressures.
On energy costs, as you see on slide number 5, our portfolio is significantly less energy-intensive than our European peers. In addition, we have much higher exposure to non-carbon sources of energy.
We benefit, for example, from our biomethane supply contract in Adhesive Solutions and from the 20% increase in energy efficiency at our Carling site. On our top line, we remain fully focused on high-growth market driven by global megatrends.
One Arkema is really a powerful differentiator, bringing together our expertise in creating bonding and protecting materials to accelerate innovation and unlock new opportunities. Bio-based adhesives and battery are great examples.
In battery in particular, combining technology across our segments enables us to deliver more integrated solutions and greater value to leading manufacturers. Innovation is at the heart of this strategy.
Our expanding R&D center in Shanghai and Battery Center of Excellence in France will accelerate innovation in key growth market and bring us even closer to our customers. More than ever, Arkema is becoming an innovation-driven company, and this ambition goes hand in hand with sustainability, as illustrated by the recent validation of our net-zero targets by SBTi services.
In an increasingly volatile and uncertain world, Arkema keeps moving forward. We have consistently executed our strategy to build a global leader in Specialty Materials, which have a significantly higher share of our group EBITDA, contributing strongly to the resilience of the results of Arkema.
We have already come a long way, but there is more to come thanks to our well-invested asset base, our technology competencies, and strong innovation capabilities. I will now hand it over to Marie-José for a more in-depth look at the financials before we discuss the outlook at the end of the presentation.
Marie-José Donsion
Thank you, Thierry. Good morning, everyone.
I'll start with Arkema's revenues. At €2.4 billion, Q3 sales were up 8.1% year-on-year, driven primarily by a positive 6% price effect, reflecting the group's ongoing pricing actions across all businesses to offset raw material and energy cost inflation.
Volumes were also up 0.6% despite subdued demand overall. All three segments—Adhesives, Advanced Materials, and Coating Solutions—contributed to the 1.7% growth of Specialty Materials.
By contrast, Primary Materials volumes declined 5.1%, reflecting weak demand in acrylic monomers mainly. I would like to mention that currencies had a positive 1.8% impact in Q3, driven by the year-on-year appreciation of the US dollar and Chinese yuan against the euro.
Q3 EBITDA came in at €332 million, up 7% year-on-year, with an EBITDA margin at 14.1%. As commented by Thierry, Adhesive Solutions delivered a solid quarter, with EBITDA up 9% year-on-year and EBITDA margin reaching 13.7% despite a dilutive impact from price increases of around 80 bps on that segment.
Advanced Materials delivered a slightly better EBITDA year-on-year and a margin at 19%. This was mainly supported by high-performance polymers that continued to benefit from attractive markets in batteries, cables, and consumer goods, notably in PVDF and PA11.
Coating Solutions delivered another strong quarter, with EBITDA up 23%. Additives performed particularly well, with ongoing growth at Sartomer in Europe and in the US as well as at rheology additives.
This improved mix contributed to lifting EBITDA margin to 12.9%. Lastly, Primary Materials EBITDA declined under weaker market conditions in acrylic monomers, while old generation refrigerants improved slightly.
Depreciation and amortization stood at €176 million, leading to a recurring EBIT of €157 million, up 11%, and to a REBIT margin broadly stable at 6.6%. Non-recurring items amounted to €42 million and included €34 million of PPA depreciation and amortization.
Financial expenses stood at 30 million—at -€30 million, comparable to last year. Consequently, Q3 adjusted net income [was €96 million?]
, which corresponds to a €1.23 per share, up 23% compared to last year. Moving on to cash flow and net debt, recurring cash flow reached €129 million, while working capital remained well controlled under 17% of annualized sales.
Actually, this reflects a strong discipline in the management of inventories and cash collection in a context where inflation has an adverse mechanical impact on working capital value. We actually expect inflation to have an adverse impact of around €150 million on working capital for the full year 2026.
CapEx amounted to €110 million this quarter, keeping us firmly on track to deliver below €600 million CapEx for the full year. Net debt and hybrid bonds at the end of September amounts to €3.5 billion, including €800 million of hybrid bonds.
The net debt to last 12 months EBITDA ratio currently stands at around 2.8x. Thank you for your attention, and I'll now hand it over to Thierry for the outlook.
Thierry Le Hénaff
Thank you, Marie-José. Going into Q4, we assume the macroeconomic will remain challenging in continuity with the past quarter, which mean marked by low visibility, weak demand, we don't expect so far the external condition to ease in the coming months.
If we take into account the macro and our performance year-to-date, we remain confident in our ability to deliver our full-year guidance, with EBITDA slightly higher than last year at constant currency. If I may, I'd like to point out that this guidance was delivered early in the year, before the conflict in the Middle East started, but, and this is good, we have been able to keep it unchanged despite the additional headwinds.
To conclude, I would like to add that the earnings growth delivered so far this year by Arkema, supported by a richer product mix—this is important, you could see that also in Q3—also supported by our innovation, advanced customized solution, demonstrate the increasing resilience of our business model and the progress we are making in strengthening our financial performance. Thank you very much for your attention, and together with Marie-José, we are now ready to answer your questions.
Operator
Thank you. This is the conference operator.
We will now begin the question and answer session. Anyone who wishes to ask a question may press * and 1 on their touchtone telephone.
To remove yourself from the question queue, please press * and 2. Please pick up the receiver when asking questions.
Anyone who has a question may press * and 1 at this time. The first question comes from Katie Richards with Barclays.
Please go ahead.
Katie Richards
Hi, thank you for the call. My first question would be that we've started to see some signs of improving construction activity in Europe, with some of the players in the space having noted a visible upturn.
Would it be fair to say that you are not seeing this translate into your construction volumes yet, given your commentary today? Is it because you need the US to turn here?
Then my second question, please, would be on PVDF following the announcement from Europe about the investigations into PVDF imports from China and some other countries. Could you explain to us how you have seen competitive intensity for these imports evolve in Europe?
You've previously talked about shifting towards suspension-grade PVDF away from some of the emulsion grades, where I understand Arkema is predominantly positioned. How far through this transition are you, and have you observed it translate into better pricing or margins?
Thierry Le Hénaff
Okay. Hello, Katie.
Thank you for your questions. With regard to the first question with construction in Europe, which we could address maybe more globally, no, so far, we don't see really any change in trend in Europe.
We see that interest rates are increasing, as you could see. I don't think this is favoring construction.
What is clear is that if we look at our businesses which are most impacted by, or let's say, involved in construction, with regard to adhesives, which really delivered a strong quarter, as you could see, for us, it's really came from industrial adhesives, not construction. Construction was flattish, but certainly not recovering, flattish, let's say, but really the growth in adhesives came from industrial.
With regard to coatings, overall, it was a superb performance on the quarter by coatings, and because overall, as we mentioned, the performance of the quarter has been driven by adhesives and coatings. I would say again, and you know that we are more positioned both for adhesives and coatings on residential and renovation, we have not seen so far any improvement, but on the other side, our more industrial-related business are behaving very well, including supported by megatrends.
On PVDF, I don't want to be too specific. What we can say is that we are continuing to deliver regular growth and strong performance worldwide on PVDF.
We are happy with our technology. We have been really a good winner over time.
If you take the example of battery, you know that the batteries, LFP, is really developing far faster than NMC, which is good for our technology. I think we are happy with the volumes and trends and on PVDF.
With regard to investigation, I don't want to comment specifically.
Katie Richards
Thank you.
Thierry Le Hénaff
You're welcome.
Operator
The next question comes from Laurent Favre with BNP. Please go ahead.
Laurent Favre
Good morning. Two questions, please.
The first one is regarding the 130 million of CapEx spent in Carling, which I think was just completed. Can you talk about just the competitiveness of the site now and whether I guess at currently low-cycle conditions, it's transforming the EBITDA generation of that site significantly?
I guess low double-digit EBITDA millions, maybe? The second question for Marie-José is on CapEx, guidance below 600.
I think you're run-rating, well, technically below 500, but I know Q4 is lumpy. Can you maybe help us with a little bit more specific guidance on CapEx for this year and also an early look on 2027?
Thank you.
Thierry Le Hénaff
Okay. Hello, Laurent.
Thank you for your questions. With regard to Carling, first of all, good news, and you could see the press release.
This very important transformation of of the process of Carling has been quite successful, this means we can say today that the site is really working well, and it was a breakthrough technology. I think it's a good let's say it rewards the quality and the efforts of of the team.
The competitiveness, I would say, is the combination of two things: the scale and and the quality of the process. Carling on these two sticks, the two boxes, I would say, because it's a world is a world size is a scale world scale size site.
Secondly, the process now puts the site of Carling in good position in the in the first quartile. In terms of competitiveness, it's quite competitive.
Now, as you mentioned wisely, currently the condition of of acrylics in after Q2 where Q2 where we had a little bit of a bump came back to low-cycle condition. As long as we are in a low-cycle condition, I would say the the EBITDA is is more one single digit, you know that.
After that, this is a cyclical business, and it can generate, as we have seen in the in the past, a lot of cash when the cycle is coming back. Yes, we confirm that so far we are in low-cycle conditions.
Marie-José, on the CapEx?
Marie-José Donsion
Regarding CapEx, actually, you can see the trend yourself. It's fair to say that the 20 million of let's say lower spend in Q3 comes after lower spend in Q1 and Q2, cumulatively we are now €70 million below let's say the last year CapEx spend trend.
That's why we are comfortable, let's say, to confirm that we see no reason we should not beat, let's say, the guidance on CapEx to be below €600 million. I have no less say further update to make.
Regarding next year, at this point, considering the macro, I guess we could expect something quite similar.
Laurent Favre
Merci.
Operator
The next question comes from Chetan Udeshi with J.P. Morgan.
Please go ahead.
Chetan Udeshi
Hi. Thanks for taking my questions.
I had one question which I probably try to ask every 18 months or so to you. We see some sort of an acceleration in terms of consolidation, M&A, portfolio actions, and I'm aware that Arkema has done a lot in the last 10 years.
How do you see your current structure? I'm quite curious on your adhesives business because I appreciate the mix is different between your business and some of your peers, but when I've compared your volumes in this business, it just seems like it's lagged quite considerably over the last 7, 8 years, especially since the COVID-19 pandemic.
Why do we think, or maybe if you can help us understand, why is Arkema the best owner of this business, and why would you not look at strategic options for this given your multiple versus some of the pure-play peers as well in that industry? Thank you very much.
Thierry Le Hénaff
Yes, hello, Chetan. No, I think the answer is very simple and very clear and very obvious for everybody who follows Arkema.
The strategy of Arkema is very clear around Specialty. Adhesive is a clear pillar of our Specialty Materials strategy, which is on three pillars, one Arkema, completely integrated within Arkema.
We have created a fantastic value on adhesives. We have, if you take the starting point, which was our very nice acquisition from Total, we have very significantly increased the profitability.
We have really upgraded the portfolio. We have still a long way to go.
This is fantastic because there is a limited potential in the adhesives, low CapEx, is perfectly integrated in our strategy. We want to continue, as everybody knows, to continue to develop adhesives, to upgrade the margin, to make acquisition, bolt-on M&A in adhesives, and we are a very happy owner of the adhesive segment.
Again, very very part of this strategy on three legs, on raw material, we stick materials, we make materials, we coat materials. You have the Adhesive segment, you have the Advanced Materials segment, and you have the Coating segment.
I'm sure you knew the answer to the question. Okay?
Chetan Udeshi
Got it. If I follow up, some of your peers, actually, most of them seem to be quite upbeat in terms of order books, October trends.
I guess you don't seem to be as upbeat in terms of what you are seeing across your divisions in terms of order book. I don't know if you want to maybe shed some light on perhaps some of the divisions and if there is any real pickup that you see in your business as we think about Q4 versus what you've seen in the last few quarters?
Thierry Le Hénaff
I think everybody has a different style of communication. I think you know us since now many years.
Some of you since 20 years. We have always a cautious communication, and we'll continue to do so.
Results and facts are facts, and results are results. I think our release of the Q3 is quite solid.
We increased EBITDA by 7%. By the way, we increased EBITDA on adhesives by 9%, which is quite significant.
Back on your question on adhesives, the volume are quite okay, even if we compare to peers. Some of our peers are negative volumes.
Overall, I think we consider that we have quite a solid and robust in current context, but we are not here I would say to make anything. I think overall, the macro remains challenging, and inflation is there everywhere, geopolitics is complex, and I think in this context, we do quite a good job, and you can see that this year and particularly on the Q3, the fact that we confirm our full-year guidance, I think, is a good sign because certainly the overall macro is more complicated than people would have thought.
After that, for the same macro, everybody can have a different way of expressing. Our cautious way of expressing things.
This is our style. I don't think we will change it.
Chetan Udeshi
Appreciate that. Thank you.
Thierry Le Hénaff
You're welcome.
Operator
The next question comes from Jean-Luc Romain with CIC CIB. Please go ahead.
Mr. Romain, your line is open.
Maybe you are on mute. We cannot hear you.
The next question comes from Matthew Yates with Bank of America. Please go ahead.
Matthew Yates
Hey, good morning, everyone. Thierry, I had a couple of questions about innovation and the direction you're trying to take the company in, and in the answer, please go easy on me with the chemistry so that I understand, but can you just elaborate a little bit more on rheology?
Because obviously, per your comments, it's not like end coatings volumes are particularly robust. What is it that's driving the growth that you see in rheology?
Is that a new product you've launched? Is that some sort of regulatory change?
Is that customers reformulating to save cost, etc., if you could talk about that? Then secondly, in the presentation, you talked about PI reducing the thickness to now about a third or so.
Can you elaborate on what incremental sort of opportunities and markets that opens up for you by having such a thinner product, to speak? Thank you.
Thierry Le Hénaff
Okay. With regard to rheology, but if I may, I would like to extend it also to UV-curing because if you take the coatings, okay, it's a very nice overall and it's a very nice resin and additives product range.
In this product range, you have really a very high-value product with accelerating growth which we are seeing on rheology, but also UV-curing. By the way, if you take the Q3 performance, this is a whole Coating Solutions I would say business which is doing well in terms of growth.
We appreciate, but I would say that our UV-curing business supported by electronics, 3D, medical, semiconductor has really accelerated their growth this year. I wanted to mention it because it's more I would say UV-curing than rheology.
As such, now rheology, it's a very nice additive, as because it change, by nature, the rheology of different additives and of the product of our customers, including paints, but also even if I don't want to mention all applications, in plenty of application, in construction, and in water treatment, in mining, because for example, transfer of products, it can bring a lot by changing the rheology of the product of our customers. Again, I would say that for the Q3, growth has more come from Sartomer UV-curing products than from rheology.
With regard to PI films, I think there is a lot of need, especially in electronics, for miniaturization of needs and for thermal quality, including thermal dissipation. You have less and less reduced space in all end application, and you know that our customers, they don't want that we are too specific on the application we have with them.
It's really this concept of miniaturization, of reduced space, of lightweighting, where the fact to have films of significantly reduced thickness bring a constant performance, which is an important point, is really increasing the needs for PI films and for PI in general. Okay.
Matthew Yates
Thank you, Thierry.
Thierry Le Hénaff
You're welcome.
Operator
The next question comes from Jaideep Pandya with Onfield Research. Please go ahead.
Jaideep Pandya
Thank you. First question is on thiochemicals.
Just want to know what's happening here with regards to the legacy sort of business where you are supplying to methionine industry, given that we've seen announcements that CJ might permanently shut down and obviously Evonik has pursued backward integration. Curious about thiochemicals as a business unit, what is really happening here.
The second question is really around the acrylics market. Thierry, very rightly you're saying that when the market returns, this is a very profitable business.
I just want to understand if you compare the new plants in China in terms of size, production process, or the catalysts that they use and with the plants in Europe and US, how are they benchmarked today? Are they better, and therefore they are able to produce at a lower cost?
That's my second question. The last question really is just a follow-up around the Nutrien project, just update on what is happening there.
Has the project started? Are you seeing already the benefits or not?
Thank you.
Thierry Le Hénaff
Okay. Thank you for all these questions, which are of different nature.
On thio, I know that our supply to methionine is because methionine is something which is more marketed or more known, easier to follow, often you can relate thio to methionine, but in fact our thio business is far beyond what we supply to methionine, which is for methionine, sort of base product, which is used for methionine customer, on which we are very competitive, and also our customer. I would say it's still an important business for Arkema, but
Operator
[speaking foreign language]
Thierry Le Hénaff
Sorry? [unclear] I continue?
Marie-José Donsion
Yes,
Thierry Le Hénaff
I don't know. I would say methionine remain an important business, but we have, for example, DMDS, which is a far bigger business, which is based on sulfur.
In fact, all sulfur chemicals of Arkema are within thio chemicals. As you mentioned, CJ has some challenges, and we don't comment, as on commercial contracts and what is happening with customer.
I would say we remain, especially in the other region, quite well-positioned on this base product for methionine. As I mentioned, thio remained a key element of Arkema with some very strong product line like DMDS and other product line based on sulfur.
The element which is not linked to your question, but we have mentioned several times this year on thio is that they are like other performance additives, certainly inside Arkema, the business line which is affected by this Middle East situation because we have many customers in Middle East, because we have this increase of sulfur, which is quite significant, and other elements, they are impacted by this kind of external element. With regard to acrylics market, I would say if you put aside the input costs, this means, for example, the propylene or other base element which enter into the acrylics or acrylic esters, I would say for the process themselves, we are relatively comparable in terms of competitiveness between the three regions of the world.
Where we have the difference, which is not just on acrylics, is on many products, is that the base raw material, the olefin, for example, in Asia significantly lower cost than in other region. At the end, the cost of making acrylic like other chemicals, but the example are by hundred in the chemical industry, the cost of making product in China is significantly lower than in other region of the world, but not by the process itself, by the input cost that the process is using to make the final product.
In terms of competitiveness, we are comparable, at least for Arkema, between the three regions of the world. With regard to Nutrien, we are making very strong progress, we have benefits already this year, which are part of the €50 million additional EBITDA guidance for the major project because Nutrien is one, we start to see the benefit, and we should have a significant ramp-up next year.
From a technological standpoint, we have made a very significant improvement. I would like also to mention that, with regard to the polyamide 11 amino 11 and polyamide 11 in Singapore, which is another major project of Arkema, for the one who are interested in following it, we have reached record production, now in terms of production, we are really exactly where we thought we would be, which is really rewarding the effort of our teams.
Jaideep Pandya
Thank you so much.
Thierry Le Hénaff
You're welcome.
Operator
The last question comes from James Hooper with Bernstein. Please go ahead.
James Hooper
Thank you very much for taking my questions. I've got two left.
The first is almost a continuation, Thierry, from your last answer. I know you just mentioned PA11, but can you contextualize the 50 million of EBITDA from additional projects this year?
Can you give us a steer into 2027, what the project should be that we're thinking about and how the ramp-up continues there? Then the second question is around leverage.
It's been creeping up again to I think 2.8x that you have in the presentation. Can you just give us an indication of the moving parts that would allow that to come down you expect to see in the coming quarters?
Thank you.
Thierry Le Hénaff
With regard to the first question, which is €50 million of of this year, the ramp-up will continue in the coming years. As in in the normalized condition that we were expecting at the beginning for all these projects, we were more in a pace per year of plus €100.
In the current kind of macro context, we are more at 50, 60. Last year, we were at we were at 60.
This year, it should 50. It will depend, and it's too early to to have this visibility for us, for you, for next year.
It depends what will be the macro for next year. I would say if you have a continuation of the macro, we should add around €50 million, which is the addition for by this major project in this kind of of macro.
If the macro is better, then it can go to 60, 70, 80. What is sure is that at the end, we we plan to add, compared to the end of '24, the €400 million that we have defined.
I think the long-term target is is remaining the same. It's just the pace that it is slower than expected, but it's still quite a good contribution year year after year.
On the leverage ratio, maybe, Marie-José, you want to comment?
Marie-José Donsion
Actually, when you look at the leverage, it's not very different from the leverage of last year at the same time. In reality, the main difference is the impact of inflation on the working capital, together with the seasonality of the working capital itself over the quarters.
As our Q4 tends to be pretty positive in terms of working cap variance, which has the ability to generate cash and lower the ratio. I'm expecting definitely a little bit better ratio by year-end.
James Hooper
Thank you.
Operator
The very last question is from Martin Roediger with Kepler Cheuvreux. Please go ahead.
Martin Roediger
Yes, thanks for squeezing me in. Can you quantify the energy cost build this year and how you are hedged?
Secondly, the EU Commission intends to protect the chemical industry from unfair competition, especially from Asia, by implementing tariffs and quotas. I do not mean fluorogas, but other products.
Do you have a view on that?
Thierry Le Hénaff
What's your view on that? A view on that.
On the EU protection. Okay.
With regard to the energy costs, as so first of all, energy is about what, 6, 7% of our total variable costs. I would say of this, we could say half is nat gas, and half is electricity.
The electricity is mostly Europe, while nat gas is more shared around the world. On electricity, Europe, we can say we are nearly 100%, or at least 80%, okay, we are quite hedged.
We have a natural hedging. I would say, in our hedging policy, we consider that the large part of the hedge is on electricity.
On that gas, we hedge partly, okay, but less than 50%. Overall, on the whole energy cost of Arkema, I would say we are hedged at least a good 50%.
I would say if you include electricity and nat gas, and the view is different depending on which region. Okay?
On the EU protection, it's a case-by-case. For example, you know we have a anti-dumping case on acrylics.
You have different ways you will get the local content also, on which EU is working I would say for certain applications. It's difficult to have one view on that.
What is clear is that you have more awareness of the EU on the fact that we cannot let just Europe open easily on every product, but it has to be a case-by-case. There is not one answer.
Depending on which chemical product line, the answer has to be different. For what is Arkema concerned, and we don't share it openly, we have a few cases where we consider that it's not bearable by our site in Europe.
It's not all across the board, but is on certain sites where we consider that the competition is not fair, and Europe needs to protect his industrial plants. We say that as a global player, as you know.
We are very global, but it's important also to try to protect the sites which really deserve to be protected because competition is not at par.
Martin Roediger
Thank you.
Thierry Le Hénaff
You're welcome.
Operator
Mr. Le Hénaff, there are no more questions registered at this time.
Thierry Le Hénaff
Okay. I would like to thank you all for your attention, your good questions, and as usual, the IR team is at your disposal if you want to further explore some element of the release.
Thank you very much. Have a good day.
Operator
Ladies and gentlemen, thank you for joining. The conference is now over.
You may disconnect your telephones. Thank you.