CT Real Estate Investment Trust
Q3 FY2026 · Earnings Call TranscriptNovember 10, 2026
Operator
Thank you for standing by. My name is Rivkah, and I'll be your conference operator today.
At this time, I would like to welcome everyone to CT REIT's Q3 2026 earnings results conference call. All lines have been placed on mute to prevent any background noise.
After the speakers' remarks, there will be a question-and-answer period. If you would like to ask a question during that time, simply press *11 on your telephone keypad.
To withdraw your question, please press *11 again. The speakers on today's call are Kevin Salsberg, President and Chief Executive Officer of CT REIT; Jodi Shpigel, Senior Vice President, Real Estate; and Lesley Gibson, Chief Financial Officer.
Today's discussion contains information that may constitute forward-looking information within the meaning of applicable securities laws. Although CT REIT believes that the forward-looking information in today's discussion is based on information, estimates, and assumptions that are reasonable, such information is necessarily subject to a number of risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied in such forward-looking information.
For information on these material risks, uncertainties, factors, and assumptions, please see the REIT's Q3 2026 and full-year 2025 MD&A, as well as the 2025 AIF, which are available on our website and filed on SEDAR+. The REIT does not undertake to update any forward-looking information, whether written or oral, except as required by applicable laws.
I will now turn the call over to Kevin Salsberg, President and Chief Executive Officer of CT REIT. Kevin?
Kevin Salsberg
Thank you, Rivkah. Good morning, everyone, and thank you for joining us today.
I am pleased to report that CT REIT delivered a very strong third quarter. Our results reflect a combination of reliable organic growth from our existing portfolio, contributions from the investments we have made over the past several years, and the continued financial discipline that underpins our business.
CT REIT is Canada's premier net lease REIT, and our primary objective is to provide investors with strong risk-adjusted returns and stability, while delivering reliable, durable, and growing results for our unitholders. The performance we have reported this quarter is an example of that value proposition in action.
From an operating perspective, our portfolio remains exceptionally stable. Occupancy remained at 99.5% at quarter-end, same-property NOI increased by 3.8%, and total NOI grew by 8.5% year-over-year.
This growth translated into a 7.7% increase in AFFO per unit and a 9.2% increase in FFO per unit on a diluted basis. While the quarter benefited from lease surrender revenue, the underlying results were still compelling.
Excluding that revenue, total NOI would still have increased by 6.5%, with AFFO per unit increasing by 4.2% and FFO per unit by 6.2%. Taken together, these results demonstrate the multiple and complementary ways in which CT REIT generates growth, including contractual rent escalations, successful lease renewals, intensifications, acquisitions, and developments.
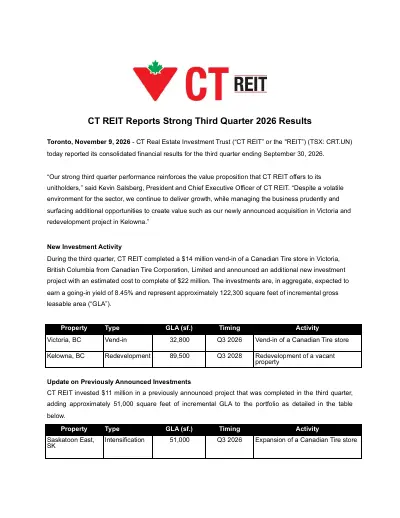
We continue to invest in the portfolio during the quarter, completing the intensification of our Saskatoon East property and acquiring a Canadian Tire store in Victoria, adding approximately 84,000 square feet of gross leasable area. Through the first nine months of the year, we have completed approximately $114 million of acquisitions and intensifications, adding approximately 368,000 square feet to the portfolio.
As we have discussed in the past, the individual investments we complete often differ in size, geography, and even by real estate intervention. Collectively, however, they tell a consistent story about our ability to find attractive and strategic ways to deploy capital.
We continue to leverage our relationship with Canadian Tire, our existing portfolio, and our market knowledge to source new opportunities that all serve to improve the quality of our asset base and contribute to long-term growth. Our newly announced redevelopment in Kelowna is another good example of just that.
The Canadian Tire store formerly located at the property has relocated to another CT REIT-owned location, and we are now repositioning the former store to create approximately 90,000 square feet of new, modern retail space. This allows us to support Canadian Tire's growth plans while creating a new source of income and value from an existing property.
At the same time, we continue to advance the balance of our substantially pre-leased development pipeline. At quarter-end, we had approximately 557,000 square feet of GLA under development, approximately 87% of which was committed to lease.
Importantly, we are delivering this growth while maintaining the conservative financial profile that is central to CT REIT's strategy. As Lesley will relay, our indebtedness ratio, total indebtedness to EBITFV, and interest coverage ratio all continue to improve, and we have ample liquidity through our credit facilities to continue to fund our capital needs.
Our near-term refinancing requirements are also manageable. We have no unsecured debentures maturing for the remainder of 2026, and only approximately 12% of our total indebtedness maturing in 2027, primarily through two series of unsecured debentures with June and December maturity dates.
CT REIT's well-laddered maturity profile, combined with our liquidity, investment-grade credit rating, and significant unencumbered asset base, provides us with considerable flexibility and will help us minimize the headwinds from today's higher-rate environment. When we look at our overall business, we see a high-quality portfolio producing strong and growing cash flows, a visible pipeline of largely pre-leased development opportunities, and a conservatively financed balance sheet with limited near-term refinancing exposure.
At CT REIT, we remain focused on the factors that we can control: growing earnings and distributions, investing capital prudently, enhancing our portfolio, and maintaining financial flexibility. We believe that consistent execution against these priorities is the most effective way to demonstrate the underlying value of CT REIT over time.
Overall, we were very pleased with the quarter. CT REIT continues to deliver strong growth without compromising the stability, balance sheet strength, or financial discipline that differentiates our business.
Those attributes provide a resilient foundation for today and position us well to continue creating value for our unitholders over the long term. With that, I will now turn the call over to Jodi to discuss our investment, development, and leasing activities in more detail.
Jodi?
Jodi Shpigel
Thanks, Kevin, and good morning, everyone. As Kevin noted, we completed one previously announced investment during the quarter: the intensification of our Saskatoon East property in Saskatchewan that added approximately 51,000 square feet of GLA to our portfolio.
As well, in the quarter, we completed the acquisition of a well-located Canadian Tire store in Victoria, British Columbia, which added approximately 32,800 square feet of GLA to our portfolio. Through the first nine months of 2026, we have completed a total of five acquisitions and four intensifications, representing a total investment of approximately $114 million and adding approximately 368,000 square feet of GLA to our portfolio.
We also just recently commenced a redevelopment project in Kelowna, British Columbia, which was added to our development pipeline in the quarter. As Kevin mentioned, this project is the redevelopment of a former Canadian Tire store, which relocated to a recently developed CT REIT-owned location.
We are already making great progress on this new project, with over half of the building committed to lease. The redevelopment is expected to be completed in the third quarter of 2028.
Turning to development activity, including Canada Square, we currently have nine projects at various stages. These projects represent approximately 557,000 square feet of total GLA and development costs of approximately $391 million.
To date, we have invested approximately $215 million and expect to invest approximately $176 million more to complete these developments. Over the next 12 months, we expect to invest approximately $76 million on our development activities.
As at quarter-end, we had committed lease agreements for approximately 484,000 square feet, representing 86.9% of total GLA under development, of which 81.8% has been leased to Canadian Tire. At Canada Square, the office retrofit remains scheduled for completion in the fourth quarter of 2028.
At CT REIT's proportionate share, the project represents approximately 340,000 square feet of GLA, with 310,000 square feet committed to lease. CT REIT and our co-owner continue to advance the modernization of 2180 and 2200 Yonge Street, which will deliver approximately 680,000 square feet of office space upon completion, over 80% of which will be anchored by Canadian Tire.
To date, approximately 22% of the project's budget has been spent. Turning to leasing, renewal activity completed in the third quarter totaled approximately 36,000 square feet of GLA, all relating to third-party tenants, at a rental increase of 6.9%.
Through the first nine months of the year, renewal activity totaled approximately 994,000 square feet of GLA at a blended rental increase of 9.1%, including approximately 658,000 square feet of Canadian Tire store renewals at a 10.8% increase. As of quarter-end, the weighted average lease term for the portfolio was 6.7 years.
Our leases with Canadian Tire average 6.9 years, and occupancy remained strong at 99.5%. I will now turn it over to Lesley to discuss our financial results.
Lesley?
Lesley Gibson
Thanks, Jodi. Good morning, everyone.
We were very pleased with the REIT's financial performance in the third quarter. Our results reflect solid organic growth, as well as contributions from acquisitions and developments.
AFFO per unit grew 7.7%, and FFO per unit grew 9.2% year-over-year. Same-property NOI, which includes the impact of intensifications, grew by a healthy 3.8% compared to Q3 2025.
Driving this growth was primarily the contractual rent escalations in the Canadian Tire leases, higher property operating cost recoveries, as well as contributions from intensification projects completed this year. Overall NOI increased 8.5% year-over-year, or approximately $10.2 million.
This increase reflects the contributions from properties acquired and developed in '25 and '26, as well as approximately $2.5 million in lease surrender revenue. Excluding this lease surrender revenue, overall NOI would have still increased 6.5% for the quarter compared to Q3 2025, and AFFO per unit and FFO per unit would have been 4.2% and 6.2% respectively, still very compelling results.
General administrative expenses were $3.7 million or 2.3% of property revenue, compared with $4 million or 2.6% in the comparable quarter. The decrease was primarily due to the fair value adjustments on unit-based awards, and partially offset by the timing of expenses being incurred.
Excluding fair value adjustments, the adjusted G&A as a percentage of property revenue is 2.8% for the quarter, compared to 2.5% in Q3 2025. Year-to-date, adjusted G&A was 2.9% of property revenue, the same as 2025.
The fair value adjustment on investment properties was $20.8 million in the third quarter. The Q3 2026 fair value adjustment was primarily driven by contractual rent increases and a development completion.
FFO per unit on a diluted basis was 36.9 cents, up 9.2% from the 33.8 cents in Q3 2025. AFFO per unit on a diluted basis was 33.7 cents, up 7.7% from the 31.3 cents in the prior year.
Growth in FFO and AFFO per unit reflects the growth in overall NOI, partially offset by higher interest costs and G&A expenses. Cash distributions paid in the quarter increased 3.5% to 24.5 cents per unit, reflecting the higher monthly distribution rate that became effective in July 2026.
The AFFO payout ratio was 72.7%, compared to 75.7% in Q3 2025, as AFFO per unit growth exceeded the increase in distributions. Turning to the balance sheet, our interest coverage ratio for the quarter improved to 3.56 times from 3.37 times in Q3 2025.
The improvement primarily reflected the redemption of the Series G unsecured debentures, higher capitalized interest on properties under development, and growth in EBIT fair value, partially offset by the issuance of the Series K unsecured debentures. Our indebtedness to EBIT fair value improved to 6.49 times from 6.77 times at Q4 2025, as growth in EBIT fair value exceeded the growth in total indebtedness.
Our indebtedness ratio has also improved in the quarter and was 38.7%, compared to 39.8% at Q4 2025. With only $175 million or 5.6% of debt maturing next June, and a further $200 million or 6.4% maturing in December 2027, we are well poised to continue to benefit from our strong interest coverage and debt to EBIT fair value credit metrics.
With respect to liquidity, we ended Q3 with approximately $5.8 million of cash on hand and approximately $298.6 million available on our committed $300 million bank credit facility, for total liquidity of over $304 million. In addition, approximately $179.6 million remained available on our uncommitted $300 million credit facility with Canadian Tire.
As Kevin mentioned, our strong balance sheet, conservative credit metrics, and ample liquidity provide a solid foundation and the financial flexibility to fund future growth initiatives. With that, I'll turn the call back to the operator for any questions.
Operator
At this time, I would like to remind everyone that in order to ask a question, please press *11 on your telephone keypad. We ask that you please limit your questions to one question and one follow-up.
We'll pause for just a moment to compile the Q&A roster. Our first question comes from the line of Lorne Kalmar of Desjardins.
Your line is now open.
Lorne Kalmar
Thanks. Good morning, and congrats on a really solid print here.
Just quickly on the lease term income, can you give us some color as to what that was related to and if you guys expect any more over the balance of the year into the beginning of '27?
Kevin Salsberg
I wouldn't say we would expect any more through the balance of the year or into '27. It related primarily to our Kelowna property that entered our development pipeline this year.
As you recall, we built Canadian Tire a new store down the street from the old location that completed at the end of last year, and they still had term left, and for us to launch the redevelopment, we had to finalize the terms of a lease surrender, and that's what this is.
Lorne Kalmar
That's pretty straightforward answer there. Then the other question I had, there was an announcement I think maybe last week about CTC looking to do a big refresh on Mark's.
Do you guys expect to have any or get any benefit of that new strategy?
Kevin Salsberg
Probably not, Lorne. The announcement was $200 million in their BBB Mark's concept.
It's a really great new version of Mark's, much bigger stores, greater assortment, you should check it out if you haven't already. Because of the size requirements, at call it 35,000 to 50,000 square feet, we don't have a lot of that vacancy currently, and I think they're taking advantage of market opportunities with some of the bankruptcies and larger vacancies that are sitting out there to occupy more space and showcase obviously the great assortment they have there.
Lorne Kalmar
Great. Thank you so much.
Operator
One moment for our next question. Our next question comes from the line of Himanshu Gupta.
Your line is now open.
Thank you, and good morning. Just on Canada Square, you're almost halfway there on phase one.
Maybe can you now provide an expected stabilized yield on the office retrofit, and any surprises or cost escalations you have seen so far?
Kevin Salsberg
We're about 20%, a little over 20% through in terms of the spending on the project. If you'll recall, it'll be stabilized at the end of 2028.
We still have a little bit more to go, Himanshu, on the project. It is still on time and on budget.
We haven't provided a stabilized yield because we have a partner on the project, and obviously have some confidentiality provisions that we have to respect. We've sort of said it approximates a market development yield for a project of this size, stature, and location.
I know that's not all that helpful for you, but that's about the best we can do at this point.
Got it. Fair enough.
Then on the Kelowna development, which was, I think, just announced, looks like you have already pre-leased half of that space. How are rents compared to previously in-place Canadian Tire rents?
Jodi Shpigel
Good morning, Himanshu. Yes, as you noted, we've pre-leased just over 50% of the former Canadian Tire store.
We are very pleased with the rents. They do represent market rents for Kelowna, so that market is quite strong, as you can imagine.
We're quite pleased. Yes, they would be higher than the previous rents from Canadian Tire because that was a previous lease from a different time.
We're happy overall, and we're commencing with the redevelopment.
They were higher. Fair enough.
Thank you, and maybe just a last question here on maintenance capex. What drove the reason to go for normalized capex assumption here versus actual capex for AFFO calculation?
Thank you.
Lesley Gibson
Himanshu, yeah, we moved to using the actual maintenance capex earlier this year. You'll see that obviously everything we spend every quarter is what we're estimating through.
By the time we get to the year-end, our deduction in the AFFO will reflect the actual spend. We have normalized that during the year.
We did make a change this quarter and increase that amount because we expect to spend a little bit more than we had originally anticipated earlier in the year, but Q3 and the cumulative amount that we have taken as a deduction that reflect the run rate that we expect for the balance of the year.
Thank you so much, and I'll jump back.
Operator
One moment for our next question. Our next question comes from the line of Tal Woolley of CIBC Capital Markets.
Your line is now open. Hi,
Tal Woolley
good morning. Just on the Canadian Tire credit facility, I think it comes up for renewal this year.
I'm assuming there'll be no real issue with that, or are you planning to term out what you've got on that facility?
Lesley Gibson
No, Tal, we're expecting that we'll continue to work with CTC. It is a one-year term, but typically in the past, it has continued to be renewed for one year at a time.
Really, who we borrow from really depends on what sort of the overall cash position is. That will really depend each quarter as we go through.
Tal Woolley
Okay. Then just on the Kelowna relocation, the existing site that you're redeveloping now, that's not a CTC store,
Kevin Salsberg
or... It's a former CTC store.
No. We...
No. It was a former CTC store.
They moved down the street, we built the new location, and now this is the backfill and re-demise of the old location. Right,
Tal Woolley
but there is not another CTC dealer going into that spot.
Kevin Salsberg
No. The lease we've done is with a fitness user, and then we are working on the backfill for the balance.
Tal Woolley
Got it. I think this is maybe sort of the first time we've kind of seen this sort of relocation and then you guys are redeveloping the existing property.
It's an interesting avenue to grow the portfolio. Do you think there's more opportunities like this as Tire looks to improve its footprint?
Yeah.
Kevin Salsberg
Tal, if you recall, we've done this a couple of times. Most recently, the Lloydminster redevelopment that we completed with a Loblaw store and The Brick, where we built Canadian Tire a new store down the road as well.
Typically, when a store reaches a certain productivity or capacity, and we are landlocked to a certain extent where the site can't accommodate further expansion, that would be the rationale for them to relocate. That's what happened in Lloydminster, and that's what happened here in Kelowna.
We think it's a great opportunity when we can facilitate something better for Canadian Tire, get a development project out of it for the REIT, and also create value through the repositioning and redevelopment of the former location. We don't have any of those currently within the pipeline right now, but Canadian Tire is always looking at their store network and optimizing it.
I do believe in the future there will be similar opportunities. We just don't have anything to talk about at this point in time.
Tal Woolley
Okay. Then just lastly, maybe you can talk a little bit.
Obviously, it's still a very tight retail market in Canada. It would certainly seem your results would reflect that.
Are you sensing any shift at all really in demand from tenants right now? You feel that if you were looking out a year, a year and a half, you still think the market's going to be pretty tight?
Kevin Salsberg
I think the strong tenants are still pursuing new locations aggressively. I do think most retailers are cognizant of the macro environment and are proceeding probably with a little bit of cautious optimism.
We have a couple redevelopment, development, or leasing projects that are underway in various parts of the country, and I would say the demand is robust for all different types of spaces in terms of geographies and sizes and users. I'm not seeing anything slow down at this point.
Tal Woolley
That's great. Thanks very much, everybody.
Kevin Salsberg
Thank you.
Operator
One moment for our next question. Our next question comes from the line of Giuliano Thornhill of National Bank.
Your line is now open.
Giuliano Thornhill
Hey guys. Good morning, everyone.
Just had a question on Canada Square on the remaining space not committed to a lease. Did you guys have an update there related to it?
Is it tracking towards your underwriting just given how much space you're adding to that market? I know it's a year away, but I'm just wondering if that's tracking as expected.
Kevin Salsberg
No specific update. The total amount of space that's left is about 60,000 square feet.
The intention between us and Oxford was always to wait till we were closer to stabilization and the completion of the construction. The building in which it resides, 2200 Yonge Street, is a construction site right now, it's hard to tour tenants and give them a flavor of what the building will become.
I think the other thing that's happening is the office market is improving, waiting is actually in our best interest right now, as I think market rents are creeping up, and hopefully that trend will continue. I don't think we'll have an update on that probably until 2028, because that's really when we'll probably launch the active leasing of that remaining space.
Giuliano Thornhill
Okay. The third-party kind of space coming online in H2 of 2028?
Kevin Salsberg
Hopefully, yes.
Giuliano Thornhill
That'd
Kevin Salsberg
be great.
Giuliano Thornhill
Thanks, I'll turn it back.
Operator
As a reminder to ask a question, please press *11 on your telephone and wait for your name to be announced. As there are no further questions at this time, I will turn the call over to Kevin Salsberg, President and Chief Executive Officer, for closing remarks.
Kevin Salsberg
Thank you, Rivkah, and thank you all for joining us today. We look forward to speaking with you again in February after we release our fourth quarter and full-year results.
Thank you.
Operator
This concludes today's call. You may now disconnect.