a.k.a. Brands Holding Corp.
NNYSE:AKAQ4 FY2025 · Earnings Call TranscriptMarch 5, 2026
Operator
Let's double-check all speaker names and details: - Operator: "Welcome to a.k.a. Brands Holding Corp.'
s Fourth Quarter and Fiscal 2025 Earnings Conference Call..." - Emily Schwartz (Head of Investor Relations) -> "Emily Schwartz (Head of Investor Relations):" - Ciaran Long (CEO) -> "Ciaran Long (CEO):" - Kevin Grant (CFO) -> "Kevin Grant (CFO):" - Operator: "Thank you.
We will now be conducting a question-and-answer session..." - Operator: "Our first question comes from Brian Myers with Lake Street Capital.
You may proceed with your question." - Brian Myers (Lake Street Capital): "Hey guys, thanks for taking my questions..."
- Kevin Grant (CFO): "Yeah, thanks, Brian, for the question..." - Brian Myers (Lake Street Capital): "Okay, got it.
Then just switching to the retail business..." - Ciaran Long (CEO): "Yeah, Brian, this is Ciaran..."
- Brian Myers (Lake Street Capital): "Got it. Thank you for taking my questions."
- Operator: "The next question comes from the line of Dana Telsey with Telsey Group. You may proceed with your question."
- Dana Telsey (Telsey Group): "Hi, good afternoon everyone..." - Ciaran Long (CEO): "Yeah, sure Dana..."
- Dana Telsey (Telsey Group): "Got it. Just lastly, the shaping of the year..."
- Kevin Grant (CFO): "Yeah, Dana..." - Dana Telsey (Telsey Group): "Thank you."
- Operator: "The next question comes from the line of Eric Beder with SCC Research. Please proceed with your question."
- Eric Beder (SCC Research): "Good afternoon. Can you talk a little bit..."
- Ciaran Long (CEO): "Yeah, Eric, I think really..." - Eric Beder (SCC Research): "Okay.
Australia, New Zealand..." - Ciaran Long (CEO): "Yeah, it is great to see four quarters in a row of growth..."
- Eric Beder (SCC Research): "And just to follow up on that. What is the average size of the Culture Kings stores outside of the Brisbane store in Australia, New Zealand?"
- Ciaran Long (CEO): "Yeah, traditionally they were more in that kind of 8 to 10,000 square foot size..." - Eric Beder (SCC Research): "Great.
Thank you." - Operator: "Our last question comes from Ashley Owens with KeyBanc Capital Markets.
Please proceed." - Ashley Owens (KeyBanc Capital Markets): "Hi, great.
Thanks so much. Maybe to start, and correct me if I'm wrong..."
- Kevin Grant (CFO): "Yeah, hey, Ashley..." - Ashley Owens (KeyBanc Capital Markets): "Okay, that's super helpful..."
- Kevin Grant (CFO): "Yeah, for sure..." - Ashley Owens (KeyBanc Capital Markets): "Great.
Thank you so much." - Operator: "Ladies and gentlemen, this now concludes our question-and-answer session..."
- "Your final response must contain ONLY the transcript text (no preamble, no closing remarks, no markdown fences or blockquotes)." - "Identify speakers: begin each speaking turn with the speaker's name and role when they are stated on the call (e.g.
"John Smith (CFO):"). When the operator introduces the next caller by name and firm, or hands the call to a named person ("I will now turn the call over to Jane Doe, CFO"), use that identity for the immediately following turn.
Reuse exactly the same label whenever the same voice returns." - "Every paragraph must begin with a speaker label, including the operator's opening and the first prepared remarks.
Never output an unlabeled paragraph." - "Use "Operator:" for the conference operator."
- "Normalize punctuation and capitalization into clean, readable sentences, but keep the spoken words verbatim. Do not paraphrase, summarize, shorten, or fix grammar."
- "Preserve all numbers exactly as spoken. Write monetary amounts and percentages with digits and symbols (e.g.
$55 million, 44.3%, 64 cents)." - "Mark uncertain speech: if a word or short passage is hard to hear, wrap your best guess in [brackets?]
; if it is unintelligible, write [unclear]." - "Output format: plain text, one paragraph per speaker turn, each starting with "Speaker Name: ".
No timestamps, no headers, no commentary, no markdown." - Operator: - Emily Schwartz (Head of Investor Relations): - Ciaran Long (CEO): - Kevin Grant (CFO): - Brian Myers (Lake Street Capital): - Dana Telsey (Telsey Group): - Eric Beder (SCC Research): - Ashley Owens (KeyBanc Capital Markets): Welcome to a.k.a.
Brands Holding Corp.' s Fourth Quarter and Fiscal 2025 Earnings Conference Call.
At this time, all participants are in a listen-only mode. A question-and-answer session will follow the formal presentation.
If anyone should require operator assistance during the conference, please press star and the number zero on your telephone keypad. Please note this conference is being recorded.
I will now turn the conference over to Emily Schwartz, Head of Investor Relations. Thank you, and you may begin.
Emily Schwartz
Good afternoon. Thank you for joining a.k.a.
Brands to discuss our fourth quarter and fiscal 2025 results released this afternoon, which can be found on our website at ir.aka-brands.com. With me on the call today is Ciaran Long, Chief Executive Officer, and Kevin Grant, Chief Financial Officer.
Before we get started, I'd like to remind you of the company's safe harbor language. Management may make forward-looking statements, which refer to expectations, projections, and other characterizations of future events, including guidance and underlying assumptions.
Forward-looking statements involve risks and uncertainties that could cause actual results to differ materially from those expressed. For further discussion of risks related to our business, please see our filings with the SEC.
Please note, we assume no obligation to update any such forward-looking statements. This call will also contain non-GAAP financial measures, such as adjusted EBITDA, adjusted EBITDA margin, and constant currency net sales.
Reconciliations of these non-GAAP measures to the most comparable GAAP measures are included in the release furnished to the SEC and available on our website. With that, I'll turn the call over to Ciaran.
Ciaran Long
Good afternoon, everyone. Thanks for joining us today to discuss our fourth quarter and full year 2025 results.
I'm pleased to report that we delivered another year of growth, reflecting the continued strength of our brands and the power of our business model. Despite a dynamic environment, we executed on our strategic priorities, strengthened our foundation, and entered 2026 positioned for accelerated growth and expanding margins.
I want to thank our teams across the business for their focus and disciplined execution throughout the year. Their commitment and hard work were central to the progress we made and the momentum we carry into the year ahead.
Let me start with a few highlights from the year. For the full year, we grew net sales 4.4% to $600 million, marking another consecutive year of growth.
Our U.S. region, which remains our largest and fastest-growing market, delivered net sales growth of 7% to $394 million.
On a two-year stack, the U.S. is up 25%, further reinforcing our conviction in our U.S.
expansion plans. The U.S.
now makes up 66% of the business. Princess Polly continued to deliver strong performance throughout the year, generating double-digit net sales growth and advancing its omnichannel expansion strategy.
The brand opened seven new stores in the U.S. in 2025 and launched its first location in Australia in the fourth quarter, ending the year with 14 stores globally.
Wholesale continued to perform well across the portfolio, with our partnership at Nordstrom exceeding expectations, with both Princess Polly and Petal & Pup delivering strong results. We also strengthened the leadership team, operations, and go-to-market strategy within our streetwear brands.
These actions improve merchandising discipline and inventory productivity, positioning Culture Kings and mnml for accelerated growth and stronger margin contribution in 2026. Importantly, we exited the year with inventory down 10% year-over-year, reflecting our continued disciplined approach to inventory management as we improve turns and transition our streetwear business to the test-and-repeat merchandising approach.
In 2025, we also completed an important structural transformation of our supply chain. As discussed in prior quarters, given the rapidly evolving macro environment, we accelerated the diversification of our sourcing strategy to enhance long-term flexibility and resilience.
That work is now substantially complete, with approximately 50% of our U.S. sourcing from outside of China, in line with our targets, along with our ability to quickly move to different regions as necessary moving forward.
Our test-and-repeat merchandising model and short lead times, while core to our agility and inventory efficiency, meant we couldn't pre-buy inventory ahead of our elevated tariffs implemented in 2025. Despite the margin headwinds faced throughout the year as we sourced product at the higher tariff rates, we delivered 30 basis points of gross margin expansion to 57.3% for the year.
We estimate that the tariff headwinds, offset by our mitigation efforts, negatively impacted fiscal 2025 gross margins by approximately 100 basis points. Looking ahead, we're better positioned to adapt quickly to any future trade policy changes while maintaining our competitive advantages in speed and inventory efficiency.
The progress we've made over the past two years provides a strong foundation as we look ahead towards 2026 and beyond. In 2024, we stabilized the business and returned to growth.
In 2025, we built on that momentum by growing the top line, strengthening our supply chain, expanding our omnichannel presence, and continuing to invest in our brands. As we enter 2026, we have improved operational discipline, stronger inventory health, and a clear path to accelerating growth and expanding margins.
I'm confident that momentum in our business is picking up, with first-quarter-to-date net sales growth of mid-single digits driven by growth in our U.S. online channels.
Our 2026 strategy remains focused on three core priorities: first, attracting and retaining customers through our direct-to-consumer channels with exclusive, trend-driven merchandising and innovative marketing; second, expanding brand awareness and our total addressable market through physical retail and strategic wholesale partnerships; and third, we remain committed to streamlining our operations and strengthening our financial foundation. As part of this, we are actively embedding AI across the organization to enhance the customer experience and drive operational excellence.
Our portfolio model and flexible asset-light technology stack enables us to rapidly test and refine solutions at the brand level, scale what works, and unlock value across the entire platform. We're already seeing measurable impact in product imagery, marketing productivity, and inventory and markdown optimization.
These capabilities are already improving conversion, sharpening creative execution, and enabling smarter, faster, data-driven decision-making across the business. We expect AI to be a meaningful driver of margin expansion in the coming years, and we're scaling these initiatives with discipline and speed.
With that, I'll share highlights from each of our brands and the growth drivers for the coming year. Starting with Princess Polly, our largest brand, which comprises more than half of the portfolio, Princess Polly continues to resonate with next-generation customers through its trend-driven merchandising, authentic customer connections, and disciplined social-first marketing approach.
I'm confident that there's tremendous runway ahead for continued global growth. As mentioned, in 2025, Princess Polly delivered double-digit net sales growth driven by the success in both its direct-to-consumer business and its omnichannel expansion.
The team continues to execute its test-and-repeat model with discipline, delivering consistent weekly newness that supports strong full-price sell-through. Importantly, the improvements we made to our supply chain position the brand to operate with stronger in-stock levels and capture demand more efficiently in 2026.
From a marketing standpoint, Princess Polly continues to meet its customers where they are, maintaining a presence across more than 20 social and digital platforms, complemented by in-store events and broader brand initiatives. TikTok remains an important demand generation channel, and in 2025, the brand increased its focus on TikTok LIVE, creator collaborations, and search-driven discovery, driving stronger engagement and efficient customer acquisition.
Beyond its online performance, Princess Polly continued to expand its retail footprint, with results exceeding expectations from both a financial and brand awareness perspective. Princess Polly successfully opened seven new stores in the U.S.
in 2025, ending the year with a total of 13 stores in the U.S. As mentioned, the brand opened its first store in Australia in Bondi Beach, Sydney in December.
The Bondi store has been very well received and reinforces our confidence that Princess Polly's omnichannel strategy resonates well globally. Princess Polly's wholesale business also continued to perform well in the fourth quarter, further expanding brand reach and reinforcing our strategy of meeting customers wherever they choose to shop.
Princess Polly will continue to expand and optimize its TikTok Shop and wholesale partnerships, ensuring strong brand presentation across key retail partners. Looking at 2026, Princess Polly has a clear runway for sustained global growth, supported by several strategic initiatives.
The brand will continue to fuel e-commerce growth by refining its test-and-repeat strategy and reinforcing brand and product storytelling. Princess Polly will deliver consistent newness, focusing on proven, best-selling party styles while also expanding its casual and basic categories to increase share of wallet.
From a marketing perspective, the brand will prioritize influencer-led content and product storytelling across social platforms to drive engagement and full-price demand. Princess Polly will continue expanding its U.S.
retail footprint, with eight new store leases fully executed and additional locations expected to be announced throughout the year. As shared in a related press release today, store openings in the second half of 2026 include Houston and Frisco in Texas, Orlando, Florida, and Edina, Minnesota, and locations in Jacksonville and Boca Raton in Florida, Nashville, Tennessee, Charlotte, North Carolina planned for early 2027.
While the existing fleet continues to meet our profitability and payback expectations, driving solid four-wall profitability, each new opening provides an opportunity to further refine execution and enhance store productivity. Lastly, Princess Polly is beginning to lay the foundation for international growth to broaden reach and expand its global presence.
Later this month, in partnership with a third-party logistics provider, Princess Polly will unlock distribution in the UK, improving customer lead times and enhancing the overall experience in the region. This establishes the operational foundation for moderate growth in the UK in 2026, with further expansion in the coming years.
Turning now to our other women's brand, Petal & Pup. The brand continues to resonate with its core customer through a curated assortment of trend-forward, feminine occasion-driven styles at accessible price points.
In 2025, Petal & Pup delivered solid performance, supported by continued strength in dresses and event wear, while broadening its assortment to capture more everyday demand and repeat purchases. The brand's growing wholesale presence, particularly at Nordstrom, exceeded expectations.
Petal & Pup has established a meaningful presence within Nordstrom's Trend section across all categories, with particular strength in dresses and more casual styles, expanding brand awareness and introducing new customers to the brand. In the fourth quarter, Petal & Pup successfully launched on the rental platform Nuuly, Nykaa Fashion in India, and Australian department store David Jones, with strong initial results out of the gates.
Plans to further expand on each of these platforms are already underway. Looking ahead to 2026, the focus remains on deepening product differentiation and strengthening brand equity.
Petal & Pup will continue to expand its range with a clear emphasis on outfitting its core customer across every aspect of her life. This includes a stronger push into casualwear and elevated separates, particularly tops and knitwear, to complement the brand's established strength in dresses.
By building a more balanced and versatile assortment, the brand aims to drive increased repeat rate over time. This strategy will be underpinned by a continued commitment to enhanced quality, compelling price points, effortless outfitting, and trend-led perspective.
Petal & Pup is also elevating its brand storytelling and community engagement, shifting beyond purely product-led campaigns towards more cohesive and authentic brand narratives. The recent refresh of its branding, website, and visual identity supports this evolution, alongside the launch of an evergreen brand campaign across social channels and key out-of-home placements this month.
Omnichannel and international expansion also remains a key growth driver for Petal & Pup. In addition to continued expansion with Nordstrom, Nuuly, and existing partners, Petal & Pup will launch with Dillard's, Von Maur, and select independent boutiques in 2026, further extending its reach and awareness in the U.S.
market. I am confident that Petal & Pup is well positioned for continued growth in 2026 as it strengthens its assortment and expands its reach.
Turning now to our streetwear brands. Culture Kings remains one of the most distinctive experiential retail concepts in the market, blending global streetwear, music, sports, and culture into a highly immersive customer experience.
In 2025, the focus was on strengthening the fundamentals of the business in both the U.S. and Australia to position the brand for accelerated growth in 2026 and beyond.
Culture Kings' exclusively designed in-house brands are a key differentiator and central to its growth strategy. In 2025, the company intensified its focus on this portfolio, including brands such as mnml, Loiter, 73 Studio, Carre, Saint Morta, and American Thrift, by evolving its merchandising approach, relaunching priority brands, and elevating product quality.
Investments in Loiter drove double-digit revenue and gross profit dollar growth in 2025, validating the strategy. Building on that momentum, 73 Studio and American Thrift were relaunched in the fourth quarter with a refined design direction and stronger go-to-market execution.
Early sell-through and improved new-style velocity from the refreshed brands has been encouraging, reinforcing confidence in the own-brand strategy heading into 2026. Own-brand penetration is expected to continue expanding, supported by faster product cycles, tighter assortment, and a clearer brand point of view.
This more focused product strategy is designed to drive stronger full-price sell-through and support margin expansion in the year ahead. In addition to the in-house brands, Culture Kings continues to enhance its third-party assortment from leading national headwear and footwear brands such as New Era, ASICS, adidas, and more to complete the streetwear outfit.
Beyond its online channel, Culture Kings' retail footprint and retailtainment ethos remains central to the model. The stores, including the Las Vegas flagship and nine locations across Australia and New Zealand, serve as meaningful revenue drivers and powerful marketing engines.
Each location delivers a differentiated and immersive experience that builds loyalty, drives customer acquisition, and reinforces the brand authority in streetwear. In the fourth quarter, the team relocated the Brisbane store into a newly renovated 5,000-square-foot format designed to serve as a more productive and repeatable model.
While the store retains high-impact features such as the hat wall and half basketball court, the format is being tested as a prototype for future U.S. expansion.
Early results have been encouraging, and the learnings from Brisbane will directly inform the next phase of U.S. store growth.
We're actively pursuing a location for the second U.S. store and will provide updates on future calls.
Looking ahead to 2026, I'm confident that Culture Kings is set up for success, with operational improvements in the rearview, a healthier inventory position, strong and accelerating performance at its in-house brands, and more stores on the horizon. I'm encouraged by the progress and excited for the future.
Before I turn it over to Kevin, I want to again express my gratitude to our incredible team. The past year required agility, resilience, and an unwavering focus on execution.
Our teams across all functions rose to the challenge, successfully navigating the supply chain transformation while continuing to deliver compelling products and experiences to our customers. I'm confident that we have the right operational foundation, the right team, and the right strategic priorities to drive accelerating growth in 2026 and beyond.
With that, I'll turn it over to Kevin.
Kevin Grant
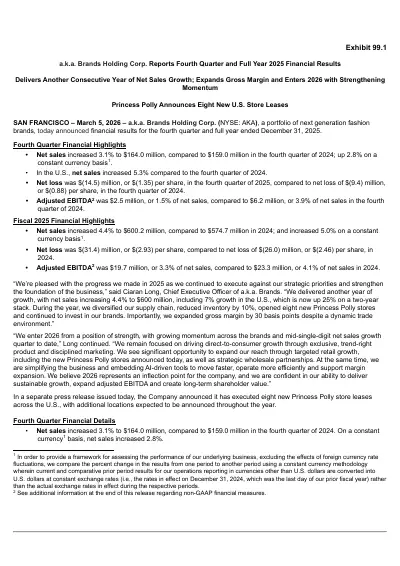
Thanks, Ciaran. Turning to our financial results for the fourth quarter, net sales increased 3.1% to $164 million, in line with our guidance.
As we noted on our third-quarter call, due to the accelerated supply chain transition, we entered October with meaningful out-of-stock positions in key best-selling styles, which limited sales in the early part of the quarter. Inventory levels stabilized as we moved through the quarter and we ramped up our marketing engine to regain sales momentum.
Net sales in Australia were also in line with expectations, increasing 1.6% to $58.1 million. As Ciaran mentioned, we entered 2026 with strong momentum with first-quarter-to-date net sales growth in the mid-single digits.
As a reminder, as we continue expanding across channels, the shape of the P&L will continue to evolve, though we expect overall margin dollars to increase as we pursue the growth opportunity ahead of us. Total orders were 2.2 million, up 6.4% year-over-year.
Trailing 12-month active customers, excluding wholesale, were 4.18 million, compared to 4.07 million a year ago. Average order value was $76, down 2.6% year-over-year.
Turning to our profitability metrics, gross margin declined 30 basis points to 55.6%, compared to 55.9% last year, reflecting the impact of the out-of-stocks in bestsellers in October, partially offset by a higher mix of retail stores. Selling expenses were $51 million, or 31% of net sales, reflecting the retail footprint expansion and one-time fulfillment charges.
Marketing expense was $20.5 million, or 12.5% of net sales. General and administrative expenses were $30.3 million, or 18.5% of net sales.
G&A expenses increased year-over-year primarily due to charges for a non-recurring legal matter, as well as an increase in head count to support our channel expansion strategy. We delivered adjusted EBITDA of $2.5 million, or 1.5% of net sales.
For the full year, net sales increased 4.4% to $600 million, in line with our expectations, and compared to $574.7 million a year ago. On a constant currency basis, net sales increased 5%.
Adjusted EBITDA for the year was $19.7 million, or 3.3% of net sales, compared to $23.3 million, or 4.1% of net sales a year ago, as tariffs and inventory disruptions pressured results. As Ciaran mentioned, the tariff headwinds, partially offset by our mitigation efforts, negatively impacted margin by approximately 100 basis points.
Turning to the balance sheet, we ended the year with $20.3 million in cash and cash equivalents, compared to $24.2 million at the end of the fourth quarter of 2024. Debt at the end of the quarter was $111.1 million, compared to $111.7 million at the end of the fourth quarter of 2024.
As a reminder, we successfully refinanced our debt in October and extended maturity to 2028. As Ciaran mentioned, we're really pleased with the progress we've made improving the quality and quantity of our inventory.
We ended the quarter with $86.2 million in inventory, down 10% compared to $95.8 million at the end of the fourth quarter of 2024. Turning now to our outlook, we are entering 2026 with momentum and a stronger operating foundation.
Our outlook is based on the tariff rates in place exiting 2025 and does not include the impact of any potential refunds as a result of the Supreme Court's decision to overturn the IEEPA tariffs. For fiscal 2026, we expect net sales to be between $625 to $635 million, representing growth of 4.2% to 5.8%.
We expect adjusted EBITDA of between $27 and $29 million. For modeling purposes, we anticipate fiscal 2026 stock-based compensation of approximately $6.5 to $7 million, depreciation and amortization expense of roughly $20 to $21 million, interest and other expense of approximately $16 to $18 million, an effective tax rate of -10%, CapEx between $18 to $20 million, and weighted average diluted share count of approximately 11 million.
For the first quarter, as mentioned, quarter-to-date net sales growth is tracking mid-single digits, with strength on our online channels in the U.S. As a reminder, in March of last year, Princess Polly and Petal & Pup launched across all Nordstrom stores, creating a more challenging wholesale comparison as we progress through the quarter.
For the first quarter, we expect net sales to be between $130 and $132 million, reflecting a low-single-digit growth rate. For modeling purposes, for Q2 through Q4, we expect high-single-digit growth on a two-year stack.
Due to the timing of tariff impacts, adjusted EBITDA comparisons will be more challenging in the first quarter before normalizing in the second quarter. We expect adjusted EBITDA between $1.5 and $2 million in the first quarter.
For modeling purposes, for Q2 and Q3, we expect EBITDA margin expansion of about 100 basis points, and a larger expansion in Q4 compared to the same periods last year. In closing, entering 2026, the business is operating from a position of greater strength.
The progress we made in 2025 across supply chain diversification, inventory discipline, and omnichannel expansion has positioned the business to accelerate growth and improve profitability in the year ahead. As a result, we believe 2026 represents an inflection point for the company, with clear drivers to support top-line growth and margin expansion.
With that, we'll open the call for questions.
Operator
Thank you. We will now be conducting a question-and-answer session.
If you would like to ask a question, please press star and the number one on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press star and the number two if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
One moment while we poll for questions. Our first question comes from Ryan Meyers with Lake Street Capital.
You may proceed with your question.
Ryan Meyers
Hey guys, thanks for taking my questions. First off, just thinking about the EBITDA guide for 2026, obviously pretty significant step up here from what you guys reported in 2025.
Can you just walk us through kind of the key drivers of that? Is most of that coming from the gross margin side?
Are we seeing any operating expense leverage? Then are there any lower non-recurring costs?
Just kind of bridge that gap for us would be helpful.
Kevin Grant
Thanks, Ryan, for the question. We're coming out of the quarter with good momentum.
That strong performance for the year, the over 4% growth, 5% on a constant currency basis. We mentioned we've seen mid-single-digit growth so far in Q1.
The guide for the year on the top line is that sort of mid-single digits. Then from a profit perspective, we mentioned EBITDA we expect over the entire year about 120 basis points of EBITDA expansion.
I would say the bulk of that, Ryan, comes from gross margin. We mentioned the headwind of 100 basis points in gross margin in FY 25, we'll be moving past that in the year.
We're finishing inventory in a really strong position, down 10% year-over-year and down 10% sequentially, we feel feeling great about that. We'll have some channel mix impact in the gross margin as well.
The balance of the EBITDA improvement will come across the rest of the operating expense lines. As mentioned, we'll continue to see the shape of the P&L move as the channels change shape of the P&L.
Overall, feel really good about that guidance. Then on the non-recurring charges, no, not really anything of note for the guide for FY 26.
Ryan Meyers
Got it. Then just switching to the retail business, can you guys tell us what percentage of the revenue mix now does come from retail?
Obviously pretty significant store openings in 2025, expected again here in 2026. Is that starting to become a more meaningful percentage of the overall revenue mix?
Then how should we think about the growth of the stores or the revenue growth at the stores relative to the direct-to-consumer business? Is the growth outpacing that there?
Just any more details on that as it's becoming a larger portion of the business.
Ciaran Long
Ryan, this is Ciaran. We are really happy with the store performance and I think for us, seeing really good productivity on a square foot in the Princess Polly stores, also really strong four-wall profitability, and I think really feel good about the opportunity that we have to continue to lean into stores.
There's now 13 open in the U.S., which is great progress, as we mentioned, signed eight more leases and I would say kind of four to five of them will open in FY 26. We're going to continue to lean into the opportunity that we have at the stores.
I think tremendous growth. It's also great for us, bringing in new customers.
We're also seeing a nice halo effect to the online business from the store, I think just kind of more and more ahead of us.
Ryan Meyers
Got it. Thank you for taking my questions.
Operator
The next question comes from the line of Dana Telsey with Telsey Group. You may proceed with your question.
Dana Telsey
Hi, good afternoon everyone. As you think about the Princess Polly business and the opening of the eight stores, how do you envision the business retail versus wholesale and your direct online?
What do you want the complexion to look like? Can you talk about what the gross margin differentials is between?
Thank you.
Ciaran Long
Sure Dana. Look, I think there is tremendous opportunity and just as a reminder, Princess Polly is about half the revenue for the group at the moment.
13 stores open, also a great presence in Nordstrom across all Nordstrom doors in the U.S., just like the Petal & Pup brand has, and seeing really good response rate really across all of the channels from new and existing customers. I think look, from a long-term perspective, we're going to continue to grow the online business.
We think we are still have a lot of opportunity there, but obviously from a wholesale and stores perspective, we are extremely early. I think, as it relate to those, I would see the more focus from the Polly team is on opening stores and building out that store footprint.
I would say on the Petal team, they're more focused on the wholesale opportunity in front of them, and we mentioned a few of the new partners that they have this year and coming in 2026. From a margin perspective, I would say look, they're all profitable channels, they're all bringing in new customers.
We do see gross margins a little bit higher in the stores than online, as the stores are a little bit less promotional at this stage. Obviously gross margins lower in the wholesale channel, but very limited selling expenses, marketing in those channels as well.
Kind of on a contribution profit basis, pretty similar across them all, and really gives us confidence to kind of our ability to push into them all and that they'll all be margin accretive. Got it.
Dana Telsey
Just lastly, the shaping of the year, how are you thinking of the cadence with top line and adjusted EBITDA, given the lapping of tariffs and the supply chain transition that you had? Thank you.
Kevin Grant
Dana. From a top-line perspective, we've talked about that sort of mid-single-digit growth for the full year and the guide for FY 26.
As you alluded to, there's definitely a lot of disruption with the tariffs and supply chain issues in FY 25 that sort of disrupts our normal cadence. That's why we're guiding from a top-line perspective the growth from Q2 through Q4 on a two-year stack.
It's sort of that high-single-digit perspective. We mentioned EBITDA over the balance of the year expanding about 120 basis points, with that really picking up in Q2.
Q2 and Q3 look very similar, and will be about 100 basis points higher than FY 25, with a little bit of a larger impact in Q4.
Dana Telsey
Thank you.
Operator
The next question comes from the line of Eric Beder with SCC Research. Please proceed with your question.
Eric Beder
Good afternoon. Can you talk a little bit, I know, a little bit about the inventories here.
That's a really nice number down 10%. I'm assuming given the tariffs, that a SKU count, that's down even more.
Is that something that what we should be thinking about that going forward for this year given the kind of ups and downs in the tariffs last year?
Ciaran Long
Eric, I think really it really good to see kind of inventory down 10%, and doing that in a period where we're growing the overall business of 4.4% for the year, and in a period when such progress on diversifying our sourcing last year as well. I would say a big driver of that change in inventory is just the progress we've made at the Culture Kings business and moving them on to test-and-repeat.
It's a slow build to change that and kind of such a transformational difference for the group, but I think the leadership team that's been in there now for 12 months and longer have just made huge progress, and that's a big driver of the inventory change. I think look, I think philosophically we always want to have lower inventory growth than sales growth, and that's how we're looking to go through this year.
Eric Beder
Okay. Australia, New Zealand, four quarters of growth here.
Is this market back, and how can you leverage that even more now that pretty much the inventories have been cleaned up and some of the other positives have rolled through there?
Ciaran Long
It is great to see four quarters in a row of growth in the Australia region, and I think look, Petal & Pup and Princess Polly have been doing well there because they have been on that test-and-repeat model. I think know that Culture Kings is and the new leadership and kind of ways of working that the team has there, we're really seeing progress there.
We're seeing real improvements in productivity for new products and new SKUs that we're bringing in. I think back to growth there is great.
Also as we talked about, we relocated a store in Brisbane for Culture Kings, down at a 5,000-square-foot kind of size. It's a new model that we can testing there, we can do that quickly and then leverage the rollout in the U.S.
I think for us, we are expecting moderate growth in Australia, but I think glad that it's back to growth and will be consistently there.
Eric Beder
Just to follow up on that. What is the average size of the Culture Kings stores outside of the Brisbane store in Australia, New Zealand?
Ciaran Long
Traditionally they were more in that kind of 8 to 10,000 square foot size, and as a reminder, the Vegas store in the U.S. bigger again.
For us really figuring out as we look to scale in the U.S., how do we retain those key aspects of the retailtainment that is just core to Culture Kings, sets it apart from anybody else out there, and is really the opportunity for us to show off the great 1P brands that we have in that business. Look, we're fortunate that you can test a bit quicker down in Australia from a store side and also being the off-season there does give us a good view into what should be bestsellers in the U.S.
going forward.
Eric Beder
Great. Thank you.
Operator
Our last question comes from Ashley Owens with KeyBanc Capital Markets. Please proceed.
Ashley Owens
Hi, great. Thanks so much.
Maybe to start, and correct me if I'm wrong, but I believe I heard that the 1Q quarter-to-date growth has been mid-single digits. Could you just provide more detail as to what's shaping the key assumptions driving deceleration from current trends in the quarter, maybe from a brand perspective where that moderation is coming from, or if this is just general conservatism built in?
Kevin Grant
Hey, Ashley. A good observation.
We've seen strong mid-single-digit growth so far in the quarter, and that's largely coming from the U.S. online business, which is great to see.
Just as a reminder, we launched in all the Nordstrom doors for both Polly and Petal in March of 25, and that's what's driving kind of that more difficult comp as we move through the quarter, and kind of explains why we're guided for Q1.
Ashley Owens
That's super helpful. Then maybe just to follow up, thinking about some of the other drivers of growth in 2026, how we should break this down, or balance between order growth and AOV as the primary drivers?
I know AOV was declining through the first half of the year, then we're also lapping really strong order volume in 2Q and then a little bit in 3Q as well, just any insight there would be helpful. Thank you.
Kevin Grant
For sure. We're pleased really to see in the year that growth in our active customers as well as that strong growth in orders.
Q4 order growth was over 6%, and that's really what drove the top-line performance. Listen, with our evolving channel mix, we're going to see some up and down in the AOV.
We've got channels like wholesale will drive the AOV up, we've got other channels like TikTok and new categories that will drive the opposite. We've modeled AOV flat for FY 26, with the top-line growth really coming from growth in orders.
Ashley Owens
Great. Thank you so much.
Operator
Ladies and gentlemen, this now concludes our question-and-answer session and does conclude today's conference as well. Thank you for your participation.
Please disconnect your lines and have a wonderful day.