APA Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good day, and welcome to APA Corporation's third quarter 2026 financial and operational results. At this time, all participants are in a listen-only mode.
After the speakers' presentation, there will be a question-and-answer session. To ask a question, you will need to press *11 on your touch-tone telephone.
Please note this call is being recorded. I would now like to turn the call over to Stefan Aka, Managing Director of Investor Relations.
Please go ahead.
Stefan Aka
Good morning, and thank you for joining us on APA Corporation's third quarter 2026 financial and operational results conference call. We will begin the call with an overview by CEO John Christmann.
Ben Rodgers, CFO, will share further color on our results and outlook. Steve Riney, President, and Tracy Henderson, Executive Vice President of Exploration, are also on the call and available to answer questions.
We will start with prepared remarks and allocate the remainder of time to Q&A. In conjunction with yesterday's press release, I hope you have had the opportunity to review our financial and operational supplement, which can be found on our Investor Relations website at investor.apacorp.com.
Please note that we may discuss certain non-GAAP financial measures. A reconciliation of the differences between these measures and the most directly comparable GAAP financial measures can be found in the supplemental information provided on our website.
Consistent with previous reporting practices, adjusted production numbers cited in today's call are adjusted to exclude non-controlling interest in Egypt and Egypt tax barrels. I'd like to remind everyone that today's discussion will contain forward-looking estimates and assumptions based on our current views and reasonable expectations.
However, a number of factors could cause actual results to differ materially from what we discuss on today's call. A full disclaimer is located with the supplemental information on our website.
With that, I will turn the call over to John.
John Christmann
Good morning, and thank you for joining us. Today, I will review our third quarter results, discuss our fourth quarter outlook, and outline our preliminary plans for 2027.
APA's strategy is anchored by three priorities: delivering top-tier operational performance, building a high-quality portfolio, and maintaining financial discipline. Together with our long-term commitment to oil and gas, these core principles guide our investments, operations, and capital returns framework.
By honing these priorities over the past 2 years, we are continuing to strengthen our operating capabilities, resulting in another quarter of excellent performance. More efficient development programs, a structurally lower cost base, and higher commodity prices are driving stronger free cash flow.
In addition, the carry agreement under our joint venture in Suriname further enhances our financial flexibility, allowing us to fund only 10% of GranMorgu's development capital while retaining our 40% working interest and significant exposure to the project's future cash flows. This has enabled us to advance this world-class opportunity while reducing debt, returning cash to shareholders, and building the long-term future of the company.
Turning to the third quarter, we delivered strong performance across our core assets. US oil production again exceeded guidance, Egypt sustained gross BOE production, and GranMorgu continues to progress toward first oil in mid-2028.
Capital investment in the Permian and Egypt, as well as total operating costs, were in line with guidance. We generated approximately $700 million in free cash flow and returned over $500 million to shareholders through dividends and buybacks.
We also took additional steps to strengthen the balance sheet, which Ben will discuss shortly. In the US, oil production of 128,000 barrels per day exceeded our guidance through a combination of high uptime, earlier turn-in-lines, and robust new well performance.
Total US production averaged 294,000 BOEs per day, also above guidance. Our focus remains on improving capital productivity through continued drilling and completion efficiency gains and maintaining reliable base production.
In Egypt, gross production was relatively flat quarter-over-quarter at 206,000 BOEs per day. Gross gas production of 542 million cubic feet per day exceeded our guidance, driven by strong well performance and more resilient base production.
Average gas realizations increased to $4.34 per Mcf from $4.23 in the second quarter. Adjusted production was approximately 64,000 BOEs per day, slightly below guidance due to PSC impacts, primarily from higher oil prices.
In Suriname, our partner Total continues to advance GranMorgu on budget and on schedule for first oil in mid-2028. Third quarter development capital was approximately $40 million, which was below our guidance.
A portion of capital shifted into the fourth quarter, primarily due to the timing of equipment deliveries and rig upgrades, but our full-year outlook remains unchanged. Shifting to our fourth quarter and updated full-year outlook.
In the Permian, drilling and completion efficiency gains continue to improve capital productivity. These improvements have driven an increase in full-year US oil production guidance to 124,000 barrels per day, above our initial guidance of 120,000 to 122,000 barrels per day.
Faster drilling cycle times are also enabling us to accelerate some frac activity into the fourth quarter, resulting in a modest increase in 2026 capital spending that will support a smoother production profile entering 2027. Fourth quarter oil production is expected to moderate with the timing of turn-in-lines during the year and reflecting seasonal weather impacts.
In Egypt, we expect gross BOE production to increase slightly for the fourth quarter and full year. Across the portfolio, our priorities remain operational execution, continued cost management, and strong free cash flow generation as we close out 2026.
Looking ahead to 2027, we will continue generating significant free cash flow from our core producing assets while advancing GranMorgu towards first oil. The strength of our core business provides the financial flexibility to further enhance the balance sheet and return capital to shareholders while pursuing several high-impact exploration opportunities.
Our preliminary estimate for upstream capital next year is approximately $2.5 billion. Exploration and GranMorgu development account for roughly 60% of the increase from 2026, with the remainder driven by Permian activity and modest inflation.
We expect this investment program to result in similar US and Egypt production year-over-year. In the Permian, activity will increase relative to 2026, with a greater percentage in the Delaware Basin, while Egypt activity and capital allocation across oil and gas will remain consistent with 2026.
GranMorgu investment will increase as development drilling begins. On the exploration side, capital investment will return to our targeted range of 10% to 15% of annual upstream capital.
These investments across our differentiated portfolio could establish new sources of long-term production, free cash flow, and substantial value for shareholders beyond our existing development assets. In Suriname, two exploration wells are planned with our partner Total, targeting additional resource potential to extend GranMorgu's production plateau or even support a second development.
In Alaska, this winter's program includes one exploration well and an appraisal test of our Sockeye discovery. In Uruguay, we expect to spud our OFF-6 well with Eni in late 2027.
We will provide a more detailed outlook in February. In closing, our third quarter results demonstrate continued execution across the portfolio.
Our Permian and Egypt businesses are delivering reliable performance and significant free cash flow, enhanced by a structurally lower cost base and improved capital efficiency. This foundation, combined with our advantageous joint venture in Suriname, puts APA in a unique strategic position.
Our carry agreement with Total significantly reduces our upfront capital outlay for GranMorgu while preserving our ownership interest and full share of future profit allocations. As a result, we are able to advance a material, high-impact exploration program while reducing debt and returning significant capital to shareholders.
Few companies have the financial flexibility to fund world-class growth opportunities of this scale while strengthening their balance sheet and delivering significant shareholder returns. We are accomplishing all of these priorities simultaneously, with GranMorgu less than 2 years from first oil and a transformational increase in free cash flow on the horizon.
With that, I'll turn the call over to Ben.
Ben Rodgers
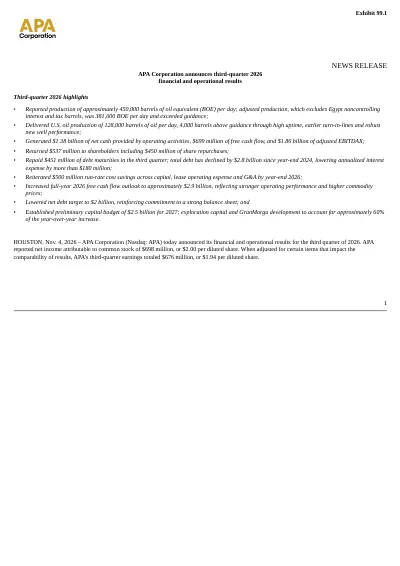
Thank you, John. For the third quarter, APA reported net income attributable to common stock of $698 million, or $2 per diluted common share.
Consistent with prior periods, these results include items outside of core earnings. The largest after-tax adjustment was an unrealized derivative gain of $17 million.
Excluding this and other smaller items, adjusted net income was $676 million, or $1.94 per diluted common share. We generated $699 million of free cash flow, bringing our year-to-date total to more than $1.9 billion.
These results reflect strong execution across our core assets and the benefits of structural cost improvements and capital efficiencies achieved over the past 2 years. Building on this performance, higher expected production in the US and Egypt and stronger commodity prices have increased our 2026 free cash flow outlook to $2.9 billion, up $600 million from August.
This supports significant returns to shareholders and continued debt reduction through year-end. We accelerated the pace of capital returns during the quarter, repurchasing 10.5 million shares at an average price of $42.78, for approximately $450 million.
Including $87 million of dividends, we returned $537 million to shareholders. Through October, we've repurchased $762 million of shares this year, reducing our outstanding share count by approximately 5% since year-end 2025.
At current strip pricing, we expect approximately $650 million of additional share repurchases by year-end. Together with dividends, these repurchases are consistent with our commitment to return at least 60% of annual free cash flow to shareholders.
We also retired approximately $450 million of debt during the third quarter, opportunistically repurchasing bonds across near-term and longer-dated maturities. We ended the quarter with total debt of $3.3 billion and net debt of $3.2 billion.
Our debt reduction since year-end 2024 has lowered annualized interest expense by more than $180 million compared with 2024. G&A expense for the quarter was $112 million, including $56 million of stock-based compensation, primarily due to the increase in our share price.
Turning to capital, third quarter upstream investment was $466 million, approximately $30 million below guidance, mostly due to GranMorgu spending that shifted into the fourth quarter. For our 2026 capital outlook, we have increased full-year upstream capital guidance by $30 million to $2.1 billion, reflecting the additional Permian activity John mentioned.
Separately, we've reduced full-year ARO spending by $15 million, reflecting the deferral of certain North Sea activities as we optimize the program. This partially offsets the cash flow impact of the higher upstream capital spending.
We've increased full-year LOE guidance by $25 million, primarily due to higher stock-based compensation expense allocated to LOE. Underlying operating cost performance remains strong, with savings across our asset base absorbing $40 million of higher diesel costs in Egypt this year.
Moving to our gas trading portfolio, which has been a significant cash flow contributor for several years and represents a differentiated financial advantage for APA. While contributions will vary with market conditions, we expect the portfolio to continue generating substantial free cash flow.
At current strip pricing and inclusive of basis hedges, we expect approximately $1.1 billion in pretax cash flow this year and $950 million next year. As we close out the year, I'd like to put our cost reduction progress over the last 2 years into perspective.
When we launched this initiative in early 2025, we targeted $350 million in annualized savings by the end of 2027. We achieved that milestone 2 years ahead of schedule and subsequently increased our target to $500 million, which we expect to reach by the end of this year.
Combined with the $180 million in annualized interest savings already in place, reaching our year-end target would bring total annualized savings to approximately $680 million compared with our cost structure as we exited 2024. For context, that is equivalent to roughly 80% of APA's total free cash flow in 2024.
These improvements span our entire business, from greater capital efficiency and lower operating costs to a simpler, more efficient organization. The result is a structurally lower cost base that improves investment returns and supports more resilient free cash flow through commodity cycles.
Our employees deserve tremendous credit for these results. Their commitment to finding better ways to operate has translated directly into tangible value for shareholders.
Looking ahead to 2027, our focus is on sustaining these gains and driving further reductions as we navigate industry-wide inflationary pressures. On capital, our preliminary outlook for the Permian program John described already incorporates mid-single-digit cost inflation.
We are pursuing additional efficiencies from increased Delaware Basin activity and other initiatives that could help offset those pressures. These potential capital savings are not reflected in our outlook.
On operating costs, projects implemented in both Egypt and the Permian are already lowering LOE, with more savings to come in 2027. In Egypt, we are expanding power projects to reduce diesel consumption and operating costs.
In the Permian, we will benefit from a full year of savings from projects implemented this year alongside new initiatives to drive further reductions. Strong free cash flow and continued cost discipline also position us to take the next step in strengthening our balance sheet.
We are approaching our $3 billion net debt target and expect to achieve it in the near future. Looking beyond this milestone, we are establishing a new net debt target of $2 billion.
Further debt reduction will lower interest expense and fixed cash obligations, supporting free cash flow through commodity cycles. It also preserves flexibility to fund future developments from exploration success while continuing to return at least 60% of annual free cash flow to shareholders.
In closing, our financial progress this year is translating into meaningful shareholder value. With $2.9 billion of expected free cash flow, we are funding significant share repurchases while strengthening our balance sheet.
We expect to achieve our $3 billion net debt target about a year and a half after announcing it, positioning us to establish a new target from a stronger financial foundation. Our cost savings progress across operations and overhead has been central to these results.
Sustaining these gains and building on them remains a priority as we look ahead. Over the next 5 years, we see a compelling opportunity to grow free cash flow per share through sustained cost discipline, lower interest expense, GranMorgu startup, and continued share repurchases.
Importantly, this growth does not depend on additional exploration success, which would provide further upside. With that, I'll turn the call over to the operator for Q&A.
Operator
Thank you. If you would like to ask a question, please press *11.
If your question has been answered and you'd like to remove yourself from the queue, press *11 again. We ask that you please limit yourselves to one question and a follow-up.
Our first question comes from Doug Leggate with Wolfe Research. Your line is open.
Doug Leggate
Oh, thanks, fellas. I wonder if I could touch first on exploration and specifically in Alaska.
I know Tracy's on the call, I don't know if you want to defer to her maybe, but my question is specifically related to the King Street well that you drilled some time ago. My understanding is there was a deeper target and a shallower formation that may have helped de-risk part of the Chinook target that you're going to drill early next year, and I just wonder if you could confirm that or characterize how you see the risk profile of Chinook.
That's my first question. My follow-up is just that obviously you're generating an enormous amount of free cash flow, credit to Steve for being unhedged, perhaps, but I wonder, where does the ARO, the abandonment liability, stack up in the seriatim of priorities for that cash flow between buybacks, debt reduction, and so on?
I'll leave it there. Thank you.
John Christmann
Thank you, Doug. I'll jump in and then let Tracy add any color to exploration, and then I'll let Ben take the ARO question.
No, we're excited about what we have in the Lagniappe play in Alaska. We've really de-risked the play with two discoveries.
King Street was the first that really confirmed a working petroleum system and high-quality reservoir, and that was really, really important. Sockeye was the second well, and we drilled it next.
It was not our largest feature, but it was the one that we had the best seismic data over at the time, and what Sockeye did was really tie our interpretations to the seismic and the geologic model to the actual well results. Both of those wells are very, very important for the whole Lagniappe area.
We've got plans next year to appraise Sockeye with the Hungry Horse well and then test a larger, separate feature with Chinook. I'll let Tracy comment a little bit more on Chinook.
Tracy Henderson
Good morning. I'll just comment a little bit specifically on your question, Doug, regarding the King Street well and what we'd reported previously on that.
I think what I would say is it was very encouraging. We saw accumulation at depth that we reported, and as you mentioned, some shallower things that looked encouraging as well.
To get the well down at Chinook, I would say it's encouraging that we see a lot of hydrocarbons in these Alaska wells and some that are roughly in the same stratigraphic zones, but we're basically interpolating a bit too much to say that there's an direct connection or de-risking of Chinook based on the seismic from what we see, but it is encouraging to see hydrocarbons in those age-equivalent zones that gives us some confidence that going into Chinook that we feel pretty good about it.
John Christmann
Ben on the ARO?
Ben Rodgers
Sure. Just on your second question, Doug, yes, we obviously have the ARO liability in the North Sea and the contingent liability in the Gulf of America that we're managing.
Hats off to the teams. They've done a great job in the past years in Gulf of America in decommissioning those assets, and we just started decommissioning this year in the North Sea, and that'll continue for years to come.
When you look at what we've done on the balance sheet, you can see from our maturity profile, we've got less than $200 million due in the next 9 years, and that gives us flexibility not only from a shareholder return and funding exploration and other items, but also allows us flexibility to flex up or down based on commodity cycles for how we decommission those assets, with that being really the only liability we have to manage. This year it's pretty close to $300 million, would expect the same next year, and dollars in that zip code are going to be very manageable for us as we're continuing to execute on those plans.
When you look at our leverage stats, we talk a lot about debt to EBITDA, at the end of this year, we're looking at close to 0.4 times, but even when you include that liability at the end of this year, it's close to 3/4 turn leverage, and that is significantly different than the past here at Apache. We think we're well positioned.
We're focused on lowering total liabilities, including the ARO. Those are long-term.
The team's doing a good job of de-risking that, and total debt coming down definitely helps too.
Doug Leggate
Great opportunity to clean up, aye? Appreciate the answers, guys.
Thank you.
Operator
Thank you. Our next question comes from John Freeman with Raymond James.
Your line is open.
John Freeman
Thank you. You've currently got four rigs running in Midland, one in Delaware.
John, you mentioned that the plan is for Delaware activity to increase next year, I assume we should take that sixth rig that gets added and assume that goes to the Delaware next year, kind of a 4-2 kind of split next year in the Permian?
John Christmann
You're going to see us, John, like we said, go add back. We've been fortunate this year that due to the heavy TIL count in the back half of '25 and the DUCs, we were able to get down to four rigs this year.
Next year, we will be adding back in. This year we were kind of in the 85-15% ratio of Midland to Delaware.
Longer term, it's more 60-40. You'll see us probably more on the 2/3, 1/3, but we'll give you more specifics in February.
Steve, anything you want to add?
Steve Riney
Just to be clear, right now we have three rigs running in Midland, one running in Delaware, and right around the beginning of the turn of the year from '26 to '27, we'll be adding two more rigs. As John said, it's 85-15 for the current year, and over the next few years, we'll be migrating to what is reflected in our economic inventory that we talked about in February, which is 60% Midland Basin, 40% Delaware Basin.
We'll eventually get to that type of a ratio.
John Freeman
Got it. Thanks for that clarification.
Then just following up, Ben, on your comments on the balance sheet, obviously, leverage is in great shape. You've got the new long-term net debt target of $2 billion.
Just want to kind of think about how we should be sort of kind of modeling this, because when I look at the kind of debt stack, there's very little left obviously on the '29s. Those will be gone soon.
Then, after that, you don't really have any near-term maturities. It's pretty low coupon, and none of that is really able to get called at par, at least for a number of years.
I'm just trying to think about, when you think net debt target, should we just assume that maybe in the near term that outside the '29s, that a lot of it's just building cash, or just sort of how to think about that net debt target?
Ben Rodgers
Sure. Stepping back, just on the target itself, in August of last year, we outlined the $3 billion, and we said at strip pricing, we'd expect to achieve that in 3 to 4 years.
Obviously, over that last 18 months, we've experienced higher than strip pricing and were able to achieve that milestone here likely by the end of this year. When you look at this new $2 billion target, similar timing, at mid-cycle pricing, it's likely by the end of the decade, and if higher prices play out, then again, we could achieve that in a much shorter time period.
We'll continue to be opportunistic, John, as we look at the debt stack. It's a pretty strong benefit that we have that $2.8 billion of debt is past the 2040 time frame.
There are some other 2030 bonds that we could potentially go after. A lot of that longer-dated debt, just given the current interest rate environment, is trading below par, you get a little bit additional deleveraging, but definitely recognize that that's also a benefit to have 17 years average maturity there.
We'll be balanced and thoughtful on that. Obviously, for our shareholders, doesn't make a lot of sense to sit on hundreds of millions of dollars of cash for a long period of time.
It's meant to be a guiding star as we continue to develop our assets, continue to explore, and return capital to shareholders. We'll be balanced.
We've done a lot of clean-up on the balance sheet so far, and it's really just meant to be a guiding star for us as we continue in the next few years. What bonds we go after, we'll be very thoughtful about that as we think about maturities and refinancing risk, etc.
John Freeman
Great. Thanks, guys.
Appreciate it.
John Christmann
Thank you, John.
Operator
Thank you. Our next question comes from Arun Jayaram with J.P.
Morgan Securities. Your line is open.
Arun Jayaram
Good morning, gentlemen. I wanted to see, John, if you could elaborate a little bit more on your Suriname exploration plans for 2027 with Total.
Maybe elaborate on what you plan to do with the drill bit outside of GranMorgu.
John Christmann
Sure. Suriname, if you go back to when we announced the Krabdagu appraisal wells at the time that I said that those Krabdagu wells did more than just appraise Krabdagu, they actually de-risked an entire exploration fairway and tied it back to our seismic.
You'll see in our supplement, slide 19, we put out a map. It's actually a map that Total's also used and put out.
We've outlined kind of four wells over the next 2 years that we'll start back with. They are very similar to what we've done at Krabdagu and Sapakara, we're very excited about them.
I do believe them de-risked. I'll also point out that they will be wells that are drilled within the current development area, they will be cost-recoverable under the existing project.
Most importantly, they provide the potential at a minimum to extend the plateau, but we also believe you move on these early because you want to understand the materiality and the potential for possible additional infrastructure, either a second boat or possibly even the ability, we're in water depths where you could set some fixed structures and get creative on what you might be able to do with the infrastructure. I think it's important that you get after them early because it gives you some clues on what you might be able to do with it versus if they were only going to be plateau extenders and you'd be more inclined to drill them later in the life cycle.
We're very, very excited. It's something that is relatively de-risked, and it's something that both us and our partner are excited to get after because they're definitely going to add more resource.
Arun Jayaram
Got it. I'll stay with the exploration theme.
I know you and your partner, Eni, in Uruguay have contracted a deepwater floater to drill that well with Noble in the fourth quarter. Could you talk a little bit about the prospect that you plan to drill in 4Q of next year and maybe a little bit more around your thoughts around exploration in Uruguay?
John Christmann
Yes, Arun, we have entered into a contract with Noble for the Black Hawk. It's a block now that we'll hold 60% and Eni will hold 40%.
They're going to cover most of the well costs. I've got Tracy here, I'll let Tracy, high level, talk about kind of what we're going after with Eni in our OFF-6 block in Uruguay.
Tracy Henderson
Sure, John. It is a basically deepwater depositional system in the Cretaceous that's worked in multiple places around the Cretaceous margin on the Atlantic margins, most notably Namibia, which is our analog for this, and the conjugate margin.
It is a really petroleum systems test on the Latin American side for what has worked on the African margin. The prospect itself, as I said, is very much like a lot of the deepwater Cretaceous turbidite depositional systems that we've seen that have worked in large scale in other parts around the circum-Atlantic.
Big well, but we are excited to get it down and very happy to have Eni in as a partner.
Arun Jayaram
Great. Thank you.
Operator
Thank you. Our next question comes from Neal Dingmann with William Blair.
Your line is open.
Neal Dingmann
Morning, John. Thanks for the time.
John, my first question is on, for maybe you or Steve, on the gas trading. Specifically, could you speak to what we might expect next year with what I would call your three buckets there with Cheniere, the contract, and the FT, given certainly what looks like to be a volatile commodity market?
John Christmann
Yes, Neal, I'll have Ben jump in on this one.
Ben Rodgers
Sure. At strip pricing from last week, which we do for every earnings, we set it the week before, at strip pricing, as we look for next year across LNG, Waha, NYMEX, and Houston Ship Channel, that gas trading portfolio is going to generate about $950 million of pretax cash flow.
Current prices, they continue to move around. I'd say it's probably in the mid-to-high 8s now, still a significant contributor there.
What you see is that this year, obviously, a lot coming from the pipelines, and then LNG, they were more balanced. Just kind of given how the curve is next year, the Permian FT portion has shrunk, and that's expected.
You've seen a lot of new pipelines not only be FID'd recently, but also coming on this year, and that's going to continue into early next year, you're seeing Waha strengthen. The Gulf Coast prices are still pretty low compared to global LNG prices, still expect that to continue next year just given some of the global infrastructure damage that's done through the conflict in the Middle East.
Just stepping back, it's been a very, very differentiated source of cash flow for us. If you look through this year alone, that business has generated $2.5 billion.
You look at adding next year, you're going to be over $3 billion from that book of business for us. It's differentiated, it goes into our shareholder returns, and we expect that to continue for many years.
Neal Dingmann
Perfect. Then my second question just on Egypt.
John, yes, given going on Middle East, it appears you've been spared and doesn't seem like there's been any issues there. Again, I guess first question, do you think that'll continue to be the case?
Then, secondly, just maybe talk about workover activity there. It seems like you've been able to keep production very stable, just if you could address that.
John Christmann
No, Neal, two good questions. I would say first in Egypt, they've been a long-term peacemaker over there and have done a really good job in difficult time periods.
We've seen that over the last couple of years starting with Gaza and now what's happening here, and now things have moved into the Red Sea. Egypt's done a great job.
We continue to be in very, very close contact with both the Egyptian government and the US Embassy. Obviously, our highest priority is the safety and well-being of our employees over there, but things continue to be something we keep a close eye on, but Egypt's done a really, really admirable job thus far.
I would expect that to continue, but it's something we watch very, very closely. Steve, anything you want to comment on the workovers?
Steve Riney
Neal, you might remember a few years ago we had an issue with some mounting workover backlog in Egypt, and we ended up with about 20 workover rigs running in Egypt back then. Since that time, we've concentrated quite a bit of activity around increasing workover rig efficiency and making sure that we're getting after the workover opportunities as quickly as possible.
Just recently, we're currently running 23% more jobs per workover rig than we have in the recent past. We've gotten really quite good at this.
At any point in time, we'll be running today between 15 and 20 workover rigs in Egypt, and that backlog has been worked down to a pretty small number now. Workover activity in Egypt is a really important part of what we call base resilience, which is just keeping the base running as efficiently and as effectively as possible.
John Christmann
The last thing I'll add on Egypt there, Neal, is we got current last September on our PDRs, and they've done a really good job of staying current. It's been a real good situation.
We've been bringing on gas, which has been helping them. They're importing and buying LNG, and so that's been a big deal.
Then, of course, they got current with the rest of the industry in June of this year. I really applaud them for doing a really, really good job in a difficult time period.
Neal Dingmann
Great point. Thanks again, John.
Operator
Thank you. Our next question comes from Chris Baker with Evercore ISI.
Your line is open.
Chris Baker
Hey, guys. Good morning.
I wanted to follow up on the '27 outlook. I think, Ben, you mentioned that further efficiency gains are not part of the initial look that you all have outlined today.
Just curious, to the extent that you do see some of those efficiency gains continue and offset some of the cost pressures, more likely to see that show up in terms of lower capital or perhaps higher volumes?
Ben Rodgers
Sure. Just we made so much progress over the past 2 years across the company in all three buckets that we've talked about on controllable spend with capital, LOE, and G&A.
On the capital side, a lot of that progress has been in the Permian. Concentrated this year in the Midland Basin, and the ability to park rigs over DSUs and have them just really work drives lower drilling days and a lot of different efficiencies, and that's even beyond other development design and other changes that the team has implemented.
We've done all of that with higher production. Hats off to the team there.
The main takeaway is, as John and Steve alluded to earlier, higher increase in the Delaware Basin. We've made progress on certain wells there, but we just don't have as many at-bats in the Delaware, and that'll increase next year.
We'll see how many of those learnings from the Midland Basin can be carried over to the Delaware Basin from an efficiency standpoint on both drilling and completions and even through to equipping and facilities. We think that there's upside there.
We didn't include that right now, just want to make sure that we get over there and get some wells down in the Delaware, and we'll update folks as we continue throughout next year.
Chris Baker
Great, thanks. Then just a follow-up, you mentioned some projects around driving continued cost savings in LOE.
Just curious, in terms of any split you can offer between what you've locked in with projects this year versus new initiatives that could potentially show up as further benefits for 2027?
Steve Riney
Chris, it's Steve. We did announce at the beginning of the year, we had about $100 million of what we call LOE projects, and that probably doesn't do justice to the projects because they also include benefits in reliability and runtime and uptime.
It actually shows up both in LOE reduction, but also in production efficiency and production resilience, as we call it. That $100 million was being spent it's primarily in the Permian Basin.
It's primarily around things like ESP conversion to gas lift, more efficient gas treatment, primarily through larger scale gas treatment, and facility consolidation type of project. These are brownfield types of projects.
That $100 million worth of projects, we said would save about $40 million of LOE on a run-rate basis. We're delivering those projects on time and as expected in terms of the anticipated results.
There will be more of those projects. The budget for 2027 does include some, not as much as $100 million, but a meaningful amount of projects.
I would say that that's still a preliminary budget for 2027. There are things that we can do even beyond 2027 on the facility side.
Most of the type of stuff, as you can imagine, would be done in front of the drilling rigs. We're not going to go out and do work that we don't need to do because we're not drilling in a certain area.
Chris Baker
Great, makes sense. Thank you.
Operator
Thank you. Our next question comes from Michael Scialla with Stephens.
Your line is open.
Michael Scialla
Good morning. Wanted to ask about the debt, you're getting your net debt down to your target of $3 billion.
Ben, you mentioned the low leverage. Can you talk about the decision to lower that net debt target further to $2 billion rather than changing your free cash flow framework?
Ben Rodgers
Sure. We're thoughtful across our capital returns and our debt balance.
One of the things that we take into consideration is obviously funding our exploration program, but we've got a differentiated free cash flow inflection coming from GranMorgu in '28, and that continues through the end of the decade. We look at that and understand we need to continue to delever the balance sheet so that we can be more opportunistic in debt funding potential growth opportunities and believe that, instead of being defensive on our debt balance, now we can be more on the offensive as opportunities arise, and that will be accretive to shareholders over the long term.
We take that into consideration, but just realize we need to continue to pay down debt as we have the different priorities that we're managing across development capital, exploration capital, continuing to get after our decommissioning assets, and lower debt is going to really just make Apache stronger over the long term and give us a lot of options as we look even beyond 2028 with additional free cash flow from GranMorgu. Set us up well.
We didn't want to plant a flag and say we're done, continued work there, but it's not going to come at the cost of anything else across the priorities that the company has.
Michael Scialla
Makes sense. Appreciate that, Ben.
Wanted to follow up on Alaska, looking at the appraisal well you have planned for Sockeye. It strikes me that it's pretty good distance away from the discovery well, I think 8 miles.
That seems like a pretty large step-out, and you mentioned that Chinook is potentially larger than Sockeye. I'm just thinking about the resource here.
I don't want to pin you down on any number, but it looks like obviously a large potential resource. Wondering how you're thinking longer term, if you do have success here with the 50% working interest.
Are you comfortable maintaining that, or would you look to bring in a partner like you did in Suriname?
John Christmann
Mike, when we announced the Sockeye discovery, we said it was a stratigraphic feature that was 25,000 to 30,000 acres. Now clearly, we're stepping out a pretty good distance from that with Hungry Horse, and I think it's over 6 miles as a crow flies.
It's something we're very excited about. It looks fantastic.
We did reprocess the seismic data last year, and one thing we did learn is that we did not drill Sockeye initially in the thickest part. That's something that the seismic told us.
We are anxious to appraise it with Hungry Horse. It is a pretty big step-out appraisal well.
Then we do have a very large prospect in Chinook that we're also very excited about. There's tremendous resource up here.
We think 50% is a good starting point for us today with the Savant acquisition that we have on cue. It kind of brings us some starter-kit things that we can work with: a pipeline, a big gravel pad, there's a dock, there's a runway, a lot of things, and we're going to have a lot of flexibility.
We want to get these two wells down and come back after that, but I think we like having the 50% where we sit today is a good place for us to be.
Michael Scialla
Very good. Thanks, John.
John Christmann
You bet.
Operator
Thank you. Our next question comes from Charles Meade with Johnson Rice.
Your line is open.
Charles Meade
Yes, good morning, John, to you and your whole team there. Tracy, I want to start by saying that circum-Atlantic, that's a new word for me, but I think I understand what it means.
John, if I could ask you to go back to the earlier question around the exploration in Suriname. If I understood you correctly, I think what I infer from that is that these other prospects that you and Total plan on drilling are similar in, and maybe similar age and similar settings to Krabdagu, as opposed to a different or new kind of play type.
I'm wondering if I'm understanding that correctly. Then also, all other things being equal, which of course they're not, but it looks like the most interesting one to drill would be that one to the west of Sapakara, where it looks like you could test two different prospects with one wellbore.
I wonder if you could just comment on my interpretation there.
John Christmann
No, I'd say it is exactly similar reservoirs, right? Same play, same age rock.
Actually, while Sapakara is really one primary zone, Krabdagu actually has multiple targets, and we've been clear on that. We do see multiple targets to the west there of Sapakara, but, as I've said, these are very, very similar to what we already understand and are part of the development plan for GranMorgu.
Anything you want to add, Tracy?
Tracy Henderson
No, I think, John, that's spot-on. We do see, as John mentioned, like in Krabdagu, multiple locations where we've got more than one zone that's hydrocarbon-bearing.
I don't think that's going to be uncommon as we continue to drill these out.
Charles Meade
Great. That's it for me.
Thank you.
John Christmann
Thank you, Charles.
Operator
Thank you. Our next question comes from Bob Brackett with Bernstein Research.
Your line is open.
Bob Brackett
Good morning. Staying with the theme of Suriname, you mentioned interestingly on the Q&A that the prospects you're targeting are ring-fenced within the development license.
Does that mean that if you did pursue a second development, that development could access the cost-oil pool from the existing operations and therefore be fairly capital-efficient?
John Christmann
Bob, I'll just say they're inside the existing bucket, right? Yes.
Bob Brackett
Interesting. The other question I might have is, typically in a PSC such as this one, there's an exploration phase, and you'll relinquish parts of the block that you deem non-perspective over time.
I'm thinking back to, say, Bonboni, for example. When you chose these prospects, have you relinquished other parts of the block that you've deemed non-perspective, or is there a chance to go out and look at a different system or a play idea?
John Christmann
At this point, we have not relinquished any of 58. In 53, we relinquished everything except for the little corner that we've got mapped there around Baja.
We've still got some time and some work to do with Staatsolie in terms of Block 58. I think we'll be able to keep a big piece of this for quite a while, but there are some things in the future where we do have procedures in place that we have to work through with Staatsolie.
Bob Brackett
Super clear. Thank you.
John Christmann
You bet. Thank you.
Operator
Thank you. Our next question comes from Leo Mariani with ROTH.
Your line is open.
Leo Mariani
I wanted to follow up quickly here on Alaska. Obviously, you've got some wells drilling over the winter.
Just wanted to kind of get a sense of is there sort of a minimum success case in terms of maybe a couple hundred million barrels or something like that that you need to kind of be comfortable with to proceed with development? Anything you can kind of do to help us out would be great there.
John Christmann
Leo, it's a great question. I'll just say it's early.
We announced the discovery well, the two wells, with Sockeye. We have not come back to started talking about what we would need in an FID case or anything at that point at this time.
We want to appraise Sockeye first, get Chinook down, and then when we're ready to come back and talk about some things, we can give more color and more detail there.
Leo Mariani
Okay. Then just in the US, obviously, you're doing a little bit more shifting of activity towards the Delaware, it sounds like next year.
Just trying to get a sense, is some of that just driven by the fact that you've had such strong gains on efficiency in the Midland that you're believe you can probably replicate some of that in the Delaware, which maybe makes it kind of more competitive? Then secondly, you still think there's kind of wood to chop on efficiency gains overall in the Permian?
John Christmann
I think there's definitely wood to chop. We keep staying after it.
I think it's more just the function of our portfolio and the prospectivity over time. What we've tried to do is efficiently develop resource.
We've made great progress in the Midland. We've also made good progress in the Delaware, but when you just look at our inventory longer term, post Callon, we picked up a lot of potential.
We've got a lot of shallow zones, a lot that's in our technical inventory bucket to be moved over. Our natural progression with what our acreage footprint today is would be more of a 60-40 split, and you just see us shifting slightly to that.
It's just kind of the natural progression of our program. Definitely see as been outlined well, we see room for more efficiencies in the Delaware, like we've been able to extract in the Midland.
Leo Mariani
Thanks.
Operator
Thank you. Our next question comes from the line of Noah Hungness with Wells Fargo.
Your line is open.
Noah Hungness
Morning. I just have one quick one here, and it was on your comment there, John, about the de-risking some of the technical upside locations in the Permian.
When we're thinking about your program next year and in a success case, how could we think about the amount of inventory that you guys could de-risk in your '27 program?
John Christmann
Noah, we came out in February with a good look at both what we'll call our development inventory and then our technical locations. At some point, we'll come out with another refresh of that.
As that's something we're constantly working on, we're always testing things. As we're consuming inventory in a well in a year, we're also testing things and moving things over.
We'll come back at some point and give an update and a fresh look on that. We are constantly appraising, and industry's also appraising.
We have a lot of HBP acreage, there is a progression there that has taken place this year. There's more taking place now, and we'll come back and update that.
We'll figure out the appropriate cadence, but we rolled that all out in February of earlier this year.
Noah Hungness
Thanks for the color.
Operator
Thank you. This concludes the question-and-answer session.
I'd like to turn the call back over to John Christmann, CEO, for closing remarks.
John Christmann
Thank you. In closing, I will leave you with the following thoughts.
First, we continue to deliver strong operational and financial performance, supporting substantial shareholder returns and debt reduction in 2026. Second, improving capital efficiency and ongoing cost savings are enhancing the long-term durability of our core assets in the Permian and Egypt.
Lastly, with GranMorgu less than 2 years from startup, we have a clear path to a step-change in production and free cash flow through the end of the decade and beyond. Combined with our world-class exploration portfolio, we are very well positioned to deliver differentiated long-term shareholder value.
Thank you.
Operator
Thank you for your participation. You may now disconnect.
Good day.