Antero Resources Corporation
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Greetings, and welcome to the Antero Resources Corporation third quarter 2026 earnings call. At this time, all participants are in a listen-only mode.
A question-and-answer session will follow the formal presentation. If anyone should require operator assistance during the conference, please press *0 on your telephone keypad.
As a reminder, this conference is being recorded. It is now my pleasure to introduce Dan Katzenberg, Vice President of Investor Relations.
Thank you. You may begin.
Dan Katzenberg
Thank you for joining us for Antero's third quarter 2026 investor conference call. We'll spend a few minutes going through the financial and operating highlights, and then we'll open it up for Q&A.
I would also like to direct you to the home page of our website at anteroresources.com, where we have provided a separate earnings call presentation that will be reviewed during today's call. Today's call may contain certain non-GAAP financial measures.
Please refer to our earnings press release for important disclosures regarding such measures. Joining me on the call today are Mike Kennedy, CEO and President; Brendan Krueger, CFO; Dave Cannelongo, Senior Vice President of Marketing and Transportation; and Justin Fowler, Senior Vice President of Natural Gas.
I will now turn the call over to Mike.
Mike Kennedy
Thank you, Dan. Good morning, everyone.
We are at a supply-demand inflection point for the natural gas market. LNG and power projects are expected to increase demand for natural gas by more than 40 Bcf per day across the US by 2030, including more than 15 Bcf per day in our local Appalachian region.
As we have seen through our marketing efforts and highlighted by the numerous transactions announced this year, demand for natural gas assets continues to increase. The scarcity of core natural gas acreage is becoming apparent, which is resulting in higher and higher values placed on quality natural gas assets.
Antero is well positioned to benefit from this inflection point, supported by more than 20 years of core drilling inventory, our integration with Antero Midstream, and being one of the few investment grade companies. Combined with our ongoing cost reduction initiatives, we expect these advantages to drive peer-leading free cash flow per share growth over the coming years.
As depicted on slide number 3, per recent public analysis by Enverus, we have more than 1,400 core drilling locations remaining. That gives Antero a multi-decade runway of premium inventory at a time when high-quality drilling locations are becoming increasingly scarce.
As demand moves ahead of supply, we believe this inventory advantage will become increasingly valuable. Now let's move to slide number 4, which summarizes some of our quarterly highlights.
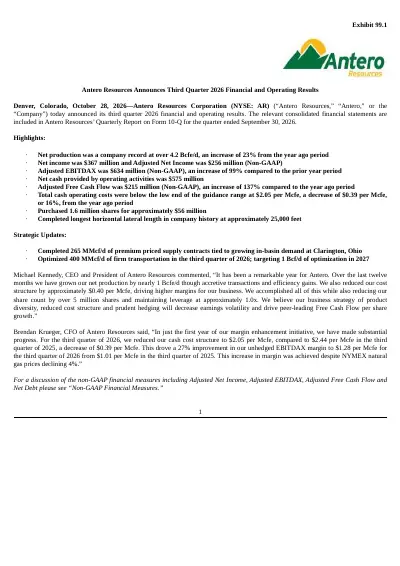
Production increased 23% year-over-year to a company record of 4.2 Bcfe per day. This was achieved while curtailing in excess of 100 million per day during the quarter.
Second, as a result of our cost reduction and margin enhancement initiative, we realized our lowest cash cost level in company history, 16% lower than a year-ago period. Third, the diversity of our production and a lower cost structure led to our unhedged EBITDAX margin increasing 27% year-over-year, despite natural gas prices declining 4%.
We used this strong financial performance to repurchase 1.6 million shares during the quarter and now have reduced our share count by more than 5 million shares since the beginning of 2025. Turning to slide number 5, I'll provide an update on our margin enhancement progress.
Based on transactions we've executed on to date, we expect to achieve $140 million of our $300 million target by mid-2027. The overriding royalty interest transaction we entered into in 2020 met the return hurdles, resulting in 85% of the cash flow now reverting back to Antero on July 1st, 2026, or $60 million of annual free cash flow uplift.
We also executed on our firm transportation optimization strategy during the third quarter, resulting in 400 million per day of agreements and $20 million in annualized free cash flow. During the fourth quarter, we are launching a formal process to expand on this strategy.
Based on increasing demand pull interest that we are seeing, we expect approximately 1 Bcf per day of firm transportation optimization agreements, resulting in an annualized free cash flow increase of $50 million. Next, the VPP transaction will expire in the third quarter of 2027, resulting in an annualized increase in free cash flow of $30 million.
Beyond mid-2027, increased dry gas development and the expiration of liquids firm transport in 2028 puts us comfortably on track to hit our initial $300 million margin enhancement target. In addition, during the quarter, we entered into attractive natural gas term sales deals with multiple parties at the Clarington market.
In addition to these sales, since announcing Antero Midstream's Eastside Express Pipeline last quarter, we have seen increased interest from multiple downstream counterparties seeking access to our natural gas at interconnects on the pipeline. This project gives us widespread connectivity to numerous long-haul pipelines, providing exceptional optionality for contracting with end-user demand.
This project also reduces our all-in transport cost, resulting in higher margins. I'll end with brief comments on the NGL macro.
The start of the fourth quarter has seen NGL prices increase 50% above the third quarter level. We expect NGL strength to continue in 2027, driven by robust global demand and low international inventories that require significant US exports to return to sufficient levels.
Following a recent industry transaction, Antero is now the only producer with meaningful NGL exposure going forward. We remain unhedged on our NGLs, providing considerable upside to our free cash flow.
Now, to provide more detail on the current liquids and NGL fundamentals, I'm going to turn it over to our Senior Vice President of Marketing and Transportation, Dave Cannelongo, for his comments.
Dave Cannelongo
Antero's liquids pricing increased throughout the third quarter, following the Strait of Hormuz ceasefire ending in July, and global liquids pricing rising steadily thereafter. The pricing momentum seen at the end of the third quarter has continued, with Antero's C3+ spot liquids realizations now testing levels not seen since early 2022.
The current geopolitical situation has had the greatest influence on the heavier end of the NGL barrel, particularly butanes and pentanes plus. These products are critical components in gasoline blending and, therefore, are being bolstered by the current strength in gasoline prices, as well as robust export demand for butane.
As shown on slide number 6, US butane exports set all-time records in May this year at 893 barrels per day and remained elevated throughout the third quarter, according to ship-tracking data, as international buyers scrambled to replace a steadily increasing number of lost Middle Eastern butane cargoes. The price impact of these dynamics is seen on slide number 7.
The chart on the left shows the volume percentages of Antero's C3+ NGL barrel. The chart on the right shows the revenue contribution by product and realized pricing in the third quarter.
Despite Antero's propane volume making up 57% of the C3+ barrel, propane only contributed 43% of the revenue in the third quarter, as butanes and pentanes plus prices were exceptionally high. However, the propane story has vastly improved since the third quarter.
We have had a significant increase in propane pricing in recent weeks, as winter restocking and revised market beliefs of a more prolonged duration to the conflict in the Middle East are requiring buyers to address the realities of the lost global supply heading into peak heating demand season. On the export side, robust domestic demand for winter seasonal gasoline blending has tempered butane exports and immediately opened up more export capacity for propane at existing terminals.
Second-half 2026 propane exports are up nearly a quarter of a million barrels per day compared to the same period in 2025, according to ship-tracking data, which is double the year-over-year increase seen in the first half of 2026, when there was intense competition with butane for dock space. The impact of these trends on US propane balances is already apparent and will likely be amplified throughout the coming winter withdrawal season.
As shown on slide number 8, strong export demand in September and October has returned propane inventories to historical norms in the five-year range, in sharp contrast compared to the second quarter, when stocks were well above the five-year range. As a result, the EIA has reported a withdrawal six of the last seven weeks, compared to just one withdrawal in 2025 over the same period.
This signals that the start of the withdrawal season is happening much earlier than typical. This is being reflected in pricing already, as Mont Belvieu propane prices have rallied 34 cents per gallon since the start of October.
Going forward, prices for both propane and butane will see tailwinds from new dock expansions coming online in the end of 2026 and into 2027. The increase in LPG export demand is well timed, as VLGC ship deliveries in 2027 will be at an all-time high of 47, up from 38 expected deliveries in 2026, as illustrated on slide number 9.
The debottlenecking of dock capacity from export expansions paired with new ship deliveries points to supportive forward netbacks and continued historical highs for propane and butane export volumes. The chart on slide 9 shows the VLGC ship order book is consistent and likely to set another ship delivery record in 2029 as we finish out this decade.
As mentioned in my remarks a moment ago, Antero's current spot C3+ NGL prices are at the highest levels realized since 2022. Given the current geopolitical and supply-side realities, the bullish trends impacting NGL prices are expected to continue and likely even escalate in the coming quarters.
International propane prices are now trading just below record pricing levels seen back in March of 2026, at the start of the Operation Epic Fury conflict. As dock premiums have tightened to single-digit levels, Mont Belvieu prices have risen as a result, consistent with Antero's predictions in prior earnings calls.
Critically, Antero has far more exposure from increasing NGL prices than any other producer, due to our high percentage of liquids production and completely unhedged portfolio. With that, I will turn it over to our Senior Vice President of Natural Gas, Justin Fowler.
Justin Fowler
Thanks, Dave. Let's start on slide number 10, that illustrates the regional demand that is expected in our Appalachian Basin.
On past quarterly calls, we have focused on projections for regional demand from power projects. This chart details this demand, which today is estimated at nearly 10 Bcf per day, which includes approximately 6 Bcf that is already in service or under construction, and another 4 Bcf that is waiting on FID.
Now, in addition to this regional power demand, there has more recently been significant momentum on incremental demand-pull pipelines, which we estimate could be over 6 Bcf per day. What is noteworthy about these new pipelines is that they're being underwritten by end-user demand, such as utilities and LNG facilities.
This compares to the past when producers had to take on these commitments to push volumes out of the basin. This shift from producer push to demand pull ultimately improves pricing netbacks and margins for Antero.
Unique to Antero, this demand provides significant competition for our natural gas volumes and firm transportation capacity. As we enter the latter part of this decade, natural gas fundamentals continue to strengthen.
Incentivized by a sharp increase in international prices, LNG exports have recently hit record levels of over 21 Bcf per day, with utilization rates near all-time highs. Higher international pricing and low storage levels are likely to ensure that this significant backlog of LNG projects, which is projected to nearly double towards 40 Bcf by the end of the decade, come to fruition.
Antero remains differentiated from its peers as the only producer with significant exposure to both this regional power demand and the LNG fairway through our firm transportation portfolio. With that, I will turn it over to Brendan Krueger, CFO of Antero Resources.
Brendan Krueger
Thanks, Justin. In my comments today, I will focus on the financial benefits that we are already achieving from our margin enhancement strategy.
Starting on slide 11, we look at a comparison in benchmark prices year-over-year. Despite natural gas prices declining 4% year-over-year, we were able to increase our unhedged EBITDAX margin by 27 cents per Mcfe, or 27%, as we benefited from a lower cost structure and high liquids exposure.
Turning to slide 12, we increased production by 23%, driven by the HG acquisition and several transactions that increased working interest in our gross production base. Notably, we were able to accomplish this net production growth without impacting the basin's gross production, which has remained essentially flat at 35 to 36 Bcf a day during this period.
Looking across our peer group, production was essentially flat year-over-year. Second, we reduced our total cash cost 16% year-over-year, which compares to the natural gas peer group average, which saw costs increase 4%.
Third, we produced the highest volume of NGLs as a percent of total production, which drives margin improvement during periods of lower natural gas prices. The 27% increase in unhedged EBITDAX margin occurred while our peer group saw EBITDAX margins essentially flat during that same period.
This represents the true rate of change story at Antero. Importantly, this is just the early stages of reducing our cost structure and enhancing margins.
We have a clear line of sight to significant further improvements over the next 24 months. Looking beyond 2028, we are already in significant discussions around firm sales agreements that will drive material margin improvement, and anticipate that total margin improvement could double our $300 million target by early next decade.
Slide 13 compares free cash flow per share growth of the Appalachian peer group. We generated substantial free cash flow of over $1 billion over the last year, driven by a lower cost structure, high liquids exposure, and an attractive hedge book.
We use this free cash flow to fund HG and other bolt-on transactions, reduce debt, while also reducing our share count by more than 5 million shares. This resulted in a 139% increase in our free cash flow per share year-over-year, compared to the peer group average that was approximately flat.
Looking ahead, we see the opportunity to nearly double our free cash flow per share, driven by the execution of our margin enhancement strategy, organic production growth from a three-rig and two-completion-crew development plan, and meaningful share repurchases. With that, I will now turn the call over to the operator for questions.
Operator
Thank you. At this time, we'll conduct our question-and-answer session.
If you would like to ask a question, please press *1 on your telephone keypad. A confirmation tone will indicate that your line is in the question queue.
You may press *2 if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
Our first question comes from Neil Mehta with Goldman Sachs. Please state your question.
Neil Mehta
Thanks for the rundown, team. I guess the first question is just on the volume guide for Q4.
If there was a quarter to come in a little softer on the volumes, probably this one, given the pricing environment. Just your perspective on how much of the curtailment was because of third-party outages.
We've heard about the Stonewall challenges there. Then how much of that was economic curtailment as a result of the soft Appalachia pricing environment?
Mike Kennedy
The guidance is at 4.3 Bcf with a 15 to 20 Bcf curtailments. All of those are related on when you have downstream issues in shoulder months in September and October, you have weak pricing.
We now have the flexibility with our local dry gas to shut in local dry gas when the prices are at $1.25 levels or below and still produce all of our liquids, with our liquids receiving over $60 a barrel. We, of course, produce all of those.
Then any local dry gas exposure we have, we shut that in. Also remind you, all of that local dry gas is hedged at basis around the 90 cents level.
We are protected from that standpoint, but no reason to sell at those levels when a couple months later you can sell for $3 and $4.
Neil Mehta
Perfect. Thank you.
Then thanks for the color on the improvement in NGL pricing in Q4 sequentially. Just give us a sense of how you're seeing that pricing tailwind.
How should we think about that as a benefit sequentially into your fourth quarter? While we're on it, any thoughts on the '27 setup for NGLs?
Mike Kennedy
There's a lot of thoughts on it. Q4 will basically essentially double your free cash flow from Q3.
Then when you look out, even with the backwardation in '27, you're above $3 billion of EBITDA with today's prices. You have substantial increase in revenues.
That's even with a much lower backwardated price in '27 and just looking at $60 for Q4. It's obviously, clearly, significant to us.
Just to remind everyone on the call and yourself, we produce 45 million barrels of C3+ annually. If you're talking $20 incremental increase from this past quarter, that's $900 million of incremental free cash flow.
Or $225 million a quarter.
Neil Mehta
Yep. Big numbers.
Thanks, team.
Mike Kennedy
Yeah.
Operator
Your next question comes from Gabe Daoud with Truist. Please state your question.
Gabe Daoud
Thanks, operator. Morning, guys.
Thanks for taking my questions. I think maybe we could start with to follow up on Neil's questions, just on the realizations again, just kind of flipping from premium to discount.
Obviously, you noted some of the challenges. How should we expect the differential to NYMEX to change as we progress through '27?
Differential to NYMEX and then also the differential to international propane and NGLs, and also domestic. Just curious how that capture kind of looks moving forward.
Mike Kennedy
Differentials, obviously, third quarter is always the weakest in the industry. You've always got September and October as kind of your widest differential.
Now that we have local dry gas, you'll see a little weakness there. It was a little more pronounced in Q3 just because of some downstream outages, and that's why we're at that 30 cents level.
You look at Q4, you're maybe in the 20 cents range. You get a little bit of improvement.
When you look at '27, you're maybe at flat to a dime back. Also remember, a lot of that's our firm transportation optimization, we're able to get others to pay us a bit of a premium at the index by have more index exposure and not have the transport expense.
There is a benefit on our cash cost that's more than offsetting those differentials.
Gabe Daoud
Okay. Yep.
Understood. Thanks for that.
That's helpful. Then I guess, just as a follow-up, could you maybe talk a bit more about the Clarington supply agreement?
I think maybe it's M2 plus a premium. Is that how we should expect most of these deals to kind of materialize at an M2 plus a little bit of a premium?
Brendan Krueger
I think that's a fair assessment. If you look at those transactions, a little over 250 million a day.
We have about 400 million a day today going to the Clarington market. You'd probably expect to see us do a bit more of those transactions over time.
That Clarington market is in the 20 to 25 cents above M2 if you can do longer term deals. If you're selling on the month or on the day, it's probably closer to an M2+10, +15.
It does add some nice margin to the business when you can lock it out longer term. Then I'd just say, overall, I think we see very strong demand at that Clarington market, a lot of demand pull coming from that market.
I'd expect us to move more volumes up to that market over time, just given the demand pull and the inbounds we continue to get as it relates to that demand pull at that market.
Gabe Daoud
Awesome. Sounds good.
Thanks, guys.
Operator
Your next question comes from Arun Jayaram with JPMorgan. Please state your question.
Arun Jayaram
Good morning, team. You guys are about halfway through your margin enhancement program, at least through 2028.
Can you just elaborate on the next, call it, $160 million of FT optimizations and the liquid FT, and just maybe the timing of that, and remind us what is happening there in terms of capturing that margin growth?
Mike Kennedy
That's right. One of those is obviously just the expiration of our liquids transport.
I believe it's $100 million of the 160 remaining. The other 60 is more dry gas development and these deals that Brendan's touched on, local getting premium pricing on that as other transport rolls off.
That's the other $60 million. But $100 million is just the expiration of those liquids contracts.
You can see that on our commitment table.
Arun Jayaram
Got it. Then, Mike, as we think about kind of cash production expense, you did 2.05 in the quarter, guides a little bit higher for 4Q, going to 2.10 to 2.20.
How do you anticipate that kind of trending as we think about '27? Again, given the margin enhancement activities that which are well underway.
Mike Kennedy
Trends down over that time. Just to remind, on Q4, it's just a tad up only because of fuel expense, a little higher commodity prices.
Nothing on the base business. The base business is kind of flat at that 2.05 level currently, but that goes lower as we continue to execute on these firm transport optimization agreements, and also as we kind of book continued natural gas sales agreements locally with firm transport rolling off, that continues to trend down.
Definitely trends down in '27.
Arun Jayaram
Great. Thanks, Mike.
Appreciate it.
Operator
Your next question comes from Kevin MacCurdy with Pickering Energy Partners. Please state your question.
Kevin MacCurdy
Hey, good morning. Mike, you mentioned Eastside Express in your prepared remarks, and I wonder if you could expand a little bit on where that project gets your gas, and what the conversations are like with end users, and will that be filled with new production or would you be shifting gas from other markets there?
Mike Kennedy
Now that's basically goes east-west across our dry gas acreage that one of the last few Tier 1 dry gas undeveloped acreage, the 100,000 acres that we have on the east side, building that all the way across basically to connect with our Sherwood kind of transport in that area, you have the optionality to flow it on multiple different pipelines. I think we have seven or eight interconnects.
We're getting so much interest on that. I don't know which way it's going to go or which pipes it's going to go.
That's what it does. It connects that 100,000 acres and allows for that dry gas development to find the best price.
That will be a little bit, I think, of maybe some dry gas growth, but really kind of replacing liquids production as well. We don't forecast much gross gas, but just more of kind of a portfolio approach around our production mix going forward.
Kevin MacCurdy
Appreciate that answer. Then for my second question, maybe on the operations side, I know in prior quarters you've talked about bringing on a lean gas pad late this year, but just checking, is that liquids-rich pad new, and is that in response to kind of the high propane and butane prices you were seeing?
Mike Kennedy
No, in my initial remarks this year, we have one pad called the Barndance pad that was a DUC that we were going to wait to see where prices were to complete it. It's a 1,300 Btu pad.
We're completing it right now on the western side of our field. Obviously, with C3+ prices $60+, we're completing that right now.
Kevin MacCurdy
Perfect. Thank you.
Mhm.
Operator
Your next question comes from David Deckelbaum with Stifel. Please state your question.
David Deckelbaum
Hi, everyone. Hey, Mike.
Thanks for taking my questions. Just wanted to ask the update, obviously, on continuing the growth program makes a lot of sense with $60 a barrel C3+ pricing.
As we get into next year, I think you talked about high-single-digit growth, which I guess would approach that 4.5+ level on average. I guess how much growth capital would you be contemplating for next year?
Should we think about that similarly to '27 in such a rich C3+ pricing environment?
Mike Kennedy
Think about it the same way this year. Our goal is to be the most capital-efficient operator in the basin, and we kind of proved that out over the past couple years that we are.
That's keeping a consistent program of three rigs and two completion crews, and that's what our intention will be. We will always have a discretionary component to whether we complete a couple pads in the Q4, just depending on commodity prices, because we're not going to complete into known weak commodity prices in the winter or known weak liquids prices.
You saw kind of that strategy play out this year. We were patient and disciplined.
Then we looked, and in September, we decided, well, let's just hedge our lean gas at $3.50. You saw those hedges we added during the quarter, basically, 100 million+ a day of hedges at $3.50 for '27 and '28, to protect those economics.
Then, of course, complete the liquids pad with $60+ NGLs. I think you can expect a similar capital plan next year as we had this year.
David Deckelbaum
Appreciate that. Can we talk a little bit about some of the firm sales agreements?
It seems like a pretty interesting source of upside to margin in the coming years. With this first deal here, how do we think about, I guess, the duration of these contracts relative to maybe some of the firm sales agreements you've looked at in the past?
If we're seeing incremental demand from utilities and sort of this Clarington area as we get down there, should we expect that the duration of some of these contracts to be longer than what we've seen, or are these fairly one- to two-year-type agreements?
Brendan Krueger
I think it depends on which firm sales and which markets you're talking about. In the Clarington market and when we have FT rolling off as well.
In the Clarington market, a lot of times you can roll these one to two years and get those premiums. I think over time, you'll likely see those contracts extend.
Then I think Mike talked about the Eastside lateral earlier as well. I think the benefit there is when we have FT rolling off, and I'll call out one in particular.
We've got a contract that's about 200 million a day that we're having many discussions on just replacing that selling volume off of Eastside, the Eastside Express. If you replace this 200 million a day contract with volume at a M2+ contract off of that pipe, it's upwards of $75 to $80 million of margin enhancement.
That's just one 200 a day contract. That gives you some magnitude of the margin enhancement we've talked about.
Obviously, we've got the $300 million by year-end '28, and then we talked about doubling that beyond 2028. That doubling is really related to selling some of these longer term deals in-basin, both at the Clarington market, but also off of Eastside Express.
There may be additional pipes down the road that will sell off of AM-built pipes as well that we see significant margin tick-up on.
David Deckelbaum
Appreciate the color, guys.
Operator
Your next question comes from Jacob Roberts with TPH Research. Please state your question.
Jacob Roberts
Good morning.
Mike Kennedy
Morning.
Jacob Roberts
I wanted to touch base on the 400 million a day optimization. Just want to make sure, is that inclusive or included in the $1 billion target?
Then when we think about that uplift of 50 million on the billion a day, or Bcf a day, is that including the lower realizations, 35% realization haircut you framed in Q2?
Mike Kennedy
Yes to both. That 400 is inclusive in that 1 Bcf, it's a total 1 Bcf.
Then the 50 million is net of the realization impact.
Jacob Roberts
Perfect. Then kind of a minor modeling question.
When we're thinking about that high-single-digit growth in 2027 potentially, is the right starting point the 4.3 or kind of a 4.5 on an uncurtailed basis?
Mike Kennedy
It's the average of '26, high-single-digit growth over the average '26.
Jacob Roberts
Perfect. Year-over-year.
Got it.
Mike Kennedy
Yes.
Jacob Roberts
Thank you so much.
Mike Kennedy
Sure.
Operator
Your next question comes from Betty Jiang with Barclays. Please state your question.
Betty Jiang
Hi, good morning. A lot of my questions have been answered.
Just maybe follow up on the 1 Bcf per day that FT. Which markets are you willing to effectively trade away for that lower transport cost?
Is there markets that you would not want to reduce your exposure to? Since within Gulf Coast, there you have three sub-hubs that you have exposure to, just would love to get some more color on that.
Mike Kennedy
Hi, Betty. We're not trading it away.
We're optimizing it. It's not really market-dependent.
It's just wherever there's some demand pull that has going to pay us premiums. We'll go out with much more than a Bcf.
The Bcf is just our target. Then we'll see where we get the best response and best margin improvement.
Betty Jiang
Got it. It could be coming from anywhere within your FT portfolio.
Mike Kennedy
That's correct.
Betty Jiang
Great. Then on the Clarington, Ohio opportunity out of your 16 Bcf per out of your 16 Bcf per day power demand outlook, maybe how much do you see that coming from Clarington?
How big could that market become over time?
Brendan Krueger
I think I mentioned we've got 400 a day flowing there today. I think, given the demand pull we're seeing at that market, of that 16 Bcf a day, you have at least I'd call it 5 to 6 Bcf a day being pulled out of that market.
Taking that 400 up another Bcf a day is not unrealistic in terms of going additional volume at that Clarington market. Just again, given the demand pull that we're seeing there and the inbounds we're getting as it relates to folks needing supply.
Betty Jiang
Thanks.
Operator
Your next question comes from Phillip Jungwirth with BMO Capital Markets. Please state your question.
Phillip Jungwirth
Thanks. Good morning, guys.
Mike Kennedy
Morning.
Phillip Jungwirth
Just on the liquids FT optimization, recognizing you're not going to be recontracting for ethane capacity on ATEX, but is there a way this pipe could still be beneficial to Antero if it were converted to some other C3+ line, and just separately on C3+ realizations, what are the puts and takes of elevated freight rates on Antero's export netbacks or Belvieu prices?
Dave Cannelongo
I think we still expect that pipeline to remain in ethane service. It's possible you could see another product move on it, and that's certainly out there as an idea.
We still think a number of folks in the basin will rely on that pipe for ethane transportation, don't really see that as a something that we're going to spend a lot of time or attention on. Just overall, the basin realizations, our entire strategy has been around margin enhancement, you're going to see us optimize our portfolio as things expire at the end of 2028.
Realizations may come down, but overall costs will come down more than that. I think that's kind of directionally what you'll see from us moving to the late part of the decade.
Phillip Jungwirth
Great. Any thoughts on freight rates, do those stay elevated and impact on export netbacks or Belvieu?
Dave Cannelongo
I think for 2027, the market expectation is things will stay pretty elevated, at least through the first half of the year. As we move through Cal '27, you'll start to see some relief there as well.
I think the big question is, is there actually enough US supply to fill all these dock expansions on day one? I think the answer to that is probably no, not right away.
I think that'll also maybe create some new perceptions in the freight market that may not be there right now. That'll also help temper freight rates.
Phillip Jungwirth
Great. Then I know this comes up from time to time, but just in light of industry M&A, just wondering if you feel like the AR/AM structure is still optimal?
Is there any argument that having AM as wholly owned could improve the competitiveness as it relates to supply deals, or you're still happy with the structure here and view AM's lower cost of capital as maybe even advantaging it, especially as capital investment opportunities increase?
Mike Kennedy
Exactly on that last point. It's still an advantage structure.
You saw that play out in '26. You saw us having M&A from both an upstream and midstream perspective, and being able to value the midstream appropriately and the upstream appropriately really helped us on our R&R large acquisition this year.
In addition, AM's now positioned for the first time in quite some time to have these regional growth projects, and that will benefit from the lower cost of capital as well. One thing you need to do in Appalachia is you need to control the midstream, and we control it.
Strategically, there is no difference. We control the midstream on our development, on our acreage, and we'll always control the midstream.
Having the lower cost of capital is a benefit.
Phillip Jungwirth
Makes sense. Thanks.
Operator
Your next question comes from Subash Chandra with StoneX. Please state your question.
Subash Chandra
Thanks. The October move we've seen so far in C3+, how much of that do you think is sort of war-related, and in the event of peace, what sort of the drivers, and what would your view be revised any for C3+?
Dave Cannelongo
Subash, this is Dave. I'll take that one.
I think oil pricing around $100 WTI, call it $115 Brent. The prices that we're seeing right now for propane and butane in the international market, delivered, are very much in line with historical levels, like what you would see relative to naphtha and oil prices in those markets.
I think your question is a good one around how much of this is war-related driven. Certainly, yeah, it's had an impact, obviously, on liquids prices, refined products availability, etcetera.
I think the thing that we've seen that's been a little bit different, you've seen a greater recovery in oil through the Strait of Hormuz than you have in LPG. If you kind of look globally, we're still down about 25% of waterborne LPG due to the impacts in the Strait of Hormuz.
Just not as much of a recovery on the LPG side in that region. That probably lends itself to additional tailwinds kind of relative to oil for the NGL barrel moving forward if this continues to prolong itself.
Certainly $100 oil is going to lead to a pretty strong NGL price, and that's what you're seeing in our realizations in the fourth quarter.
Subash Chandra
Thank you. Then, I guess, with the liquids pad coming on 4Q, and maybe with some of the curtailments, it doesn't look like there's going to be much of a move, maybe a percent one way or another.
Do you think there'll be a bigger NGL emphasis in the completion schedule you have for next year?
Mike Kennedy
No, it's generally, like we talked about, we want balanced, it's more like 50/50 kind of on a go-forward basis between the dry gas and liquids. That's not on production, that's actually on development pads.
It really doesn't move the needle. You still stay 70% kind of liquids and 30%, or 30% liquids and 70% kind of gas.
Subash Chandra
Yep. Thanks, Mike.
Operator
Your next question comes from Leo Mariani with ROTH. Please state your question.
Leo Mariani
Hey, I just wanted to dive back into the kind of B a day in 2027. Kind of prior to curtailing in 4Q, you guys weren't too far off that, kind of guiding to about 4.45.
I guess that implies some pretty limited organic growth next year. Just any kind of comments around that?
Are you kind of purposely not trying to really put much growth in the system next year, or just how are you thinking about it?
Mike Kennedy
I think it'll be a little, a 4.5's kind of a risked, curtailment kind of number. If you had not unrisking and no curtailments thought about or just put in a range, I think you'd be above the 4.5.
Brendan Krueger
I think on a year-over-year basis, if you go Q4 to Q4, you'll certainly see some growth.
Mike Kennedy
Yeah.
Leo Mariani
Okay. Now that makes sense on the curtailment, obviously you guys are factoring that in.
Certainly makes sense.
Mike Kennedy
Exactly. Also on the same thing on the production on the DUC capital.
We'll always have kind of a DUC component. For the Q4, and that will influence '27, but it will have a little bit of influence on when we turn in line pads, and maybe waiting till December months to turn it on, instead of like a September, October in a year, can influence the production as well.
Leo Mariani
Yep. Okay.
Then just with respect to inflation, are you guys seeing any of that up there in Appalachia at this point in time, and you think that could potentially worsen a bit as we get into '27? Just comments around that.
Mike Kennedy
Not really. We were looking at that yesterday, just trying to get our arms around it.
We're really not seeing anything on the service. You see maybe a 1% on raw materials, on like oil-based mud or a little bit on steel, but nothing material, nothing you would really notice if you weren't trying to dive in and analyze it.
Leo Mariani
Okay. That's helpful.
Then just on your gas price realizations, kind of to start the year in '26, you guys were a little bit more optimistic that you guys would be getting kind of some premiums. I think a lot of it was due to pull from the LNG market, and I guess that really hasn't materialized at this point.
Could you maybe just address that kind of dynamic in terms of maybe kind of what kind of went against you there, and do you expect maybe that trend can reverse a bit, just given the strong LNG pull that we see in '27 and you can kind of get back up to some better gas prices?
Mike Kennedy
I think September and October, we saw the lowest regional gas price we've ever seen, so that wasn't anticipated. There was a couple of weekends where it was 60 cents, 65.
We didn't sell into that, of course, but the weakness was exacerbated by all the downstream issues that occurred in September and October, backed it up on a historic level backups into the region. We, of course, didn't forecast that.
We don't forecast it going forward, but we're obviously flexible enough to not have to sell into that. We have the ability to just wait and sell it in December.
That's kind of what went against us. That, and we've been way more successful in our optimization of firm transport than we thought.
The demand pull is real, and you saw that in the third quarter. When that occurs, you have slightly lower realized price, but much lower cash production expense.
Leo Mariani
Okay. Appreciate it.
Thank you.
Mike Kennedy
Sure.
Operator
Your next question comes from Paul Diamond with Citi. Please state your question.
Paul Diamond
Thank you. Good morning, all.
Thanks for taking the call. Just wanted to touch back in on FT optimization.
In your path to the initial 300, it's been kind of quick and to the point. The additional, I guess, 55 you see in '27 and '28, is that expected to be more chunky or will it be a bit more tick and tie in here and there?
I guess how do you see the timing of that coming through?
Brendan Krueger
I think you'll see that play out more ratable over time in '27 and '28, as we continue to sign some of these sales agreements and pick up incremental margin on each of those agreements. You'll see that $55 million achieved.
Ratable throughout the next couple years is a good way to think about it.
Paul Diamond
Got it. Understood.
Then just actually sticking on the FT optimization beyond '28, I know you guys talked about doubling the current plan, an additional 300 million. I guess is that more on just FT, like contract roll, or should we think about more optimization or sales, or more actionable moves?
Brendan Krueger
The easy way to think about it is you have some portions of our FT portfolio, when you look at the all-in netback and all-in costs, demand, variable, all that it takes to get to certain delivery points, that are upwards of $1.35, $1.40 back of Henry Hub. If you look out at the local price, you're 65 to 70 cents back of Henry.
A lot of these agreements that we're looking at with counterparties that need the supply, they're willing to pay a premium on top of that. If you can replace volume, significant volume, that's $1.35 back of Henry with stuff that's, call it 55 to 60 cents back of Henry in-basin, that's the big driver of that doubling of margin that we see.
We're not even assuming we're going to keep the good FT that goes to the strong LNG pull, but we're going to optimize the FT when it's rolling off and replace that with longer-term sales agreements in-basin. We're seeing, like I said, a lot of interest on those deals, feel very confident about that ability to be able to double that $300 million target.
Paul Diamond
Got it. Understood.
Appreciate the clarity. I'll leave it there.
Operator
Your next question comes from John Abbott with Wolfe Research. Please state your question.
John Abbott
Hey, thank you for taking our questions, and I'm on for Doug. First question is, in your opening remarks, you just talked about the premium being paid for core acreage and how it's a dwindling amount.
How does that change your thoughts about potential M&A from both a buyer or seller perspective? Is more scale necessary since we're seeing more consolidation?
Mike Kennedy
More a buyer of acreage. Being one of the few investment-grade companies with scale already, we have an advantage, plus we have upstream and midstream.
We control a lot of the transport and all the infrastructure, and we are the industrial builder of northern West Virginia. We are the consolidator of West Virginia acreage.
That gives us an advantage. It is scarce, but we do surround a lot of the acreage now, we're probably the only buyer of a lot of this, or only logical buyer.
There's a lot of efficiencies and synergies that we can value, so that makes us a likely consolidator of the West Virginia area.
John Abbott
Appreciate it. Then when you see this sort of spike in NGL pricing in 2027, you are going to continue with your share repurchases.
How do you think about buybacks versus just sort of parking cash on the balance? Do you just continue to buy?
Do you think about this as sustainable? Do you take a more cautious approach?
How do you approach buybacks when you sort of see this sort of outlook?
Mike Kennedy
We're opportunistic. Depending on where the market's at, generally when we have buybacks, a lot of time it's on 10b5-1 plans, and we set in motion a buyback at a share price relative to propane, natural gas price, or it's kind of a two- or three-factor equation.
We assess that every quarter. We look at where we're at versus kind of where the commodities are at, where our free cash flow is at, where our debt's at, where our M&A opportunities are at, and set it then.
We're highly opportunistic. This year, we're happy that we were able to buy in, or over the last, kind of five quarters, 15 or 5 million shares.
We hope to continue to do that. At these levels, the opportunity seems to be there.
John Abbott
Appreciate it. Thank you very much for taking our questions.
Operator
Your next question comes from John Annis with Texas Capital. Please state your question.
John Annis
Hey, good morning, guys, and thanks for taking my questions. For my first one, the HG assets are already showing significant D&C improvements relative to the prior operator.
Can you provide some color on what you've done differently to achieve those efficiencies, and then looking ahead, what additional levers do you see to drive further gains?
Mike Kennedy
We brought the way that we operate to their assets, the way we've done it for the last 15 years. We have over 1,500 wells of experience.
When we brought our operations team, which is the best in the business to do it, one easy one to look at is HG was doing three or four stages per day of completions. We do 13 to 14.
That's always going to lend itself to a lot of efficiencies. The drilling days, too, we're sub-5 days per 10,000 feet.
They were double digits on that metric. Just those two, it's a lot of just bringing our best practices to those assets, and we've done that.
That's how we've been able to achieve those. Those have been ahead of schedule.
The synergies, I think we said 75 million, we're well in the triple digit in that, over 100 million for the year on that, and those will continue going forward.
John Annis
Got it. For my follow-up, as you look to optimize bulk natural gas and liquids transport, I'm curious how you weigh reducing fixed commitments today versus your ability to capture premium pricing or serve new demand later along your FT pathway?
Or is it that the portfolio can become both lower cost and more flexible?
Mike Kennedy
It's both. You see, the benefit that we have is, I think in one of the calls, we have 30 paths, I think I said, it's exactly 28 paths, we know exactly which ones are margin-enhancing and which ones are not.
That knowledge is invaluable as we go forward, and so we'll be able to pick the best ones, capture the highest margins, and then the ones that may not be as margin-enhancing, replace those with those local firm sales or local natural gas sales agreements. We're in a great position.
John Annis
Makes sense. Thanks for the time.
Mike Kennedy
Sure.
Operator
Your next question comes from Josh Silverstein with UBS. Please state your question.
Thanks.
Josh Silverstein
Good morning, guys. Outside of the physical sales agreements, I think every company like you guys, all or your peers are starting to look at ways to enhance the revenue, or kind of look at commercial marketing optimization.
Part of this is maybe storage or looking at different FT capacity. How are you thinking about the revenue side versus just the cost side, which you've outlined?
Mike Kennedy
We already capture it through all the transport we have. Others don't have the transport, they're trying to generate that without actually physically having the ability to flow their equity volumes.
We've captured it through the transport, and then we're going to capture the real margin by floating on that to the best paths, to the coast, and get the arb between the international pricing and the US pricing. That's how we've chosen to capture it, is stay floating, get to the coast, actually have our physical volumes that are being transported, and then that way we could continue to reduce our commitments but still enhancing our margins.
Josh Silverstein
Got it. Then, a record lateral this quarter, around 25,000 feet.
Can you just talk about the ability to keep going down that path, getting towards the 20,000-foot kind of average lateral, and then maybe just some of the thoughts around the economic enhancements by doing this?
Mike Kennedy
Significant economic enhancements. I think next year, our drilling is going to average 18,000 feet, which is a record.
I think this year's maybe 15 to 16. We completed the 25.
You got a lot of cost per foot advantages by going out that much longer. We continue to push it.
I think in the coming years, you'll probably see us, maybe next year and the next, go over 30,000. That's the goal.
We'll continue to push and push. The beauty of HG and now our Eastside Express development of that 100,000 of undeveloped natural gas acres is we can perfectly plan it.
I think you touched on the number. You get five wells going north 20,000 feet, five going south 20,000 feet, and that seems to be the perfect plan with one high-pressure pipe going through the middle of a row of hundreds and hundreds of locations.
That's where we're headed and to optimize that, and I think you'll see that in the coming years.
Josh Silverstein
Thanks.
Mike Kennedy
Sure.
Operator
Thank you. We have reached the end of the question-and-answer session, I will now hand the floor back to Dan Katzenberg for closing remarks.
Dan Katzenberg
I'd like to thank everybody for joining us on the conference call today. If you have any more questions, please feel free to reach out.
Have a good day.
Operator
Thank you. All parties may now disconnect.