ASSA ABLOY AB Class B
Q3 FY2026 · Earnings Call TranscriptOctober 27, 2026
Björn Tibell
Hi, everyone, and welcome to the presentation of ASSA ABLOY's Q3 report in 2026. My name is Björn Tibell.
I'm heading Investor Relations. Joining me here are ASSA ABLOY's CEO, Nico Delvaux, and our CFO, Erik Pieder.
We'll start this conference now with a summary of the report. When we're done with that one, we will open up for your questions.
Nico, I'd like to hand over to you then.
Nico Delvaux
Thank you, Björn. Also, good morning from my side.
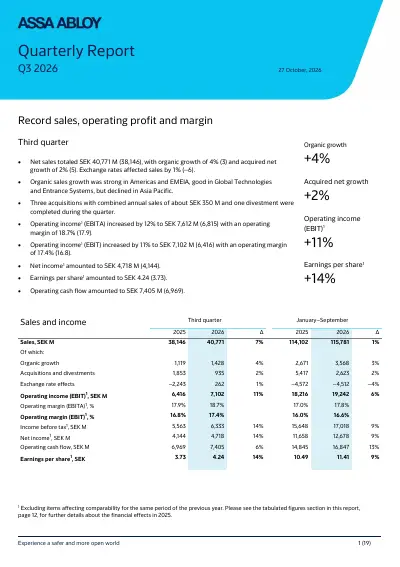
Q3 report, a report with a lot of records. A record top line, for the first time in our history, sales above 40 billion SEK, with a good organic sales growth of 4%, with the Americas division and EMEIA division contributing in the first place.
Also, a record high EBIT, for the first time above 7 billion SEK, and a record EBIT margin of 17.4%. Excellent operating leverage, close to 50%.
Cash flow, second-best cash flow ever, an increase of the cash flow of 6% versus last year. Also this quarter again, strong growth of our electromechanical product category; they had an organic sales growth of 9% in our regional divisions.
Then we completed three acquisitions, and we will also launch our new manufacturing footprint program, MFP 11, in Q4. If we look a little bit into the numbers, sales of almost 41 billion SEK, 7% up, 4% organic growth, 2% net acquired growth, and this quarter again a positive effect on FX, that's because of the weaker SEK, plus 1%.
A record EBITDA margin of 18.7%, 80 basis points up. EBIT margin, like I mentioned, 17.4%, 60 basis points up.
EBIT above 7 billion, 11% up. Our earnings per share, 14% up.
If we make a little bit a tour of the world, starting in North America, I would say very similar market conditions as I mentioned in Q2 and perhaps as in Q1. In North America, still very strong market conditions on the non-residential side, commercial and institutional, where we continue to see very high activity.
Residential still much more challenging, now definitely also with the Fed again increasing interest rates, where we don't see that recovery on the new build anytime soon yet, but where at least on the R&R side, we believe the market has bottomed out, and we see a slight recovery of the R&R business in North America. On logistics vertical, important for Entrance Systems, also there still a more flattish development of the market.
If we go to Europe, similar picture as in North America. Also here, very strong non-residential market conditions.
Perhaps on the residential side, a little bit more positive than in North America. Here we see R&R definitely coming back with a lower growth rate, and we even see new build in some markets, like Finland and Sweden, starting to grow again.
Similar on the logistics side, also here logistics side no recovery, if already something the market most probably is still a little bit down in Europe. Then Australia, New Zealand, similar as Europe and North America, also here good, strong market conditions on the commercial side, weaker residential in Australia, and good residential in New Zealand.
LATAM, still good market conditions overall in most markets in LATAM. We have also now had elections in Brazil, let's see how that plays out.
Africa, smaller continent for us. Then in Asia, very mixed picture, where we see good market condition and good growth for us in India, in Southeast Asia, and where we see continued challenging market conditions in South Korea, with housing market down double-digit, and then also in Greater China, where the market is not recovering and where we also are still having negative growth.
Some highlights from around the world. DoorBird expanded its portfolio with the world's first IP video door station with 4G/5G connectivity, mainly for residential and commercial applications.
Entrance Systems expanded their swing door portfolio with a new door operator designed for interior applications, offering a more streamlined solution for everyday use. Then on the project win side, a very nice project win in Germany for a premium automotive manufacturer with our eCLIQ solution, where the contract includes more than 15,000 cylinders, a very nice, big project win.
It's now seven quarters in a row that we see again positive organic growth, and I would say through acquisitions. Top line that goes up, and also an operating margin that goes up towards the higher end of the 16% to 17% bandwidth we want to be in.
Year to date, we are at 16.6%. On a 12-month moving trend, we are at 16.7%.
EBITDA, like I mentioned earlier, also at a record high 17.8% on a 12-month moving trend. Higher top line, better margins, therefore also strong acceleration of our operating income, record above 7 billion SEK for the first time and 81% up if we compare with 2021.
On the acquisition side, like I mentioned, three acquisitions completed in the quarter, 11 completed year to date. Those 11 acquisitions represent an annualized sales of around 3.2 billion SEK.
If I highlight two of them that we did in Q3: Classic Brass, US manufacturer of premium cabinet and door hardware, complementing, extending our core for the Americas division, they had a sales of around 155 million SEK last year; and then PAC-LOCK, an acquisition that complements our organic development of a padlock product range in North America, very excited about this acquisition, it's add expertise in delivering, I would say, customized, high-security solutions, they had a sales of around 155 million SEK last year. If we then dig into the different divisions, starting with EMEIA, EMEIA had another very good quarter, with an organic sales growth of 5%, with very strong sales growth in Central Europe, good sales growth in Middle East, India, Africa, and the Nordics, a small growth in South Europe, and then a stable growth in UK and Ireland, and then an excellent operational execution with an EBIT margin of 15.8%, with a strong operating leverage, 110 basis points, driven by operational efficiencies, of course, the volume growth, and then a good price versus cost realization.
FX was dilutive 10 basis points, and M&A 20 basis points. We continue the positive journey, I would say, in the EMEIA division.
Also very strong quarter for the Americas, with an organic sales growth of 6%, with strong sales growth in the North America non-residential segment, a good sales growth in LATAM and in the North America residential segment. Then I would say excellent EBIT margin of 19.6%, 110 basis points up compared to last year, with an excellent operating leverage, 140 basis points, and M&A dilutive 30 bps.
APAC had an organic sales decline of 1%, a small sales growth in Pacific, Northeast Asia, and a sales decline in Greater China, Southeast Asia, where, as I explained earlier, you should see this as a double-digit negative growth in Greater China and a strong positive double-digit growth in Southeast Asia, a very different, mixed picture. An EBIT margin of 9.8%, with a stable operating leverage, and FX and M&A both dilutive 20 basis points.
The M&A is more an internal transfer. We transferred residential business from HHI in Taiwan to the APAC division.
Global Tech, an organic sales growth of 4%, with strong sales growth in HID and a good sales growth in Global Solutions. I would say an excellent EBIT margin of 20%, even higher than the very high 19.8% number of last year.
Also here, excellent operating leverage, 80 basis points, and FX and M&A both dilutive 30 basis points. Then last but not least, Entrance Systems, an organic sales growth of 3%, strong sales growth in Pedestrian and in Perimeter Security, a small sales growth in Doors & Automation, but then a decline in Industrial, good growth in Service, and an EBIT margin of 17.1% with a strong operating leverage, 40 basis points, and an M&A dilutive 70 basis points, that is related to the bigger Sentrol acquisition we did in Canada, and then also related to acquisition costs for the upcoming Gunnebo Entrance Control acquisition that we are confident we will now be able to close in Q4.
With that, I give the word to Erik for some more details on the financial numbers.
Erik Pieder
Thank you, Nico, and a very good morning also from my side. As mentioned before, we had a record high sales for the first time above 40 billion, 7% up versus same period last year, 4% organic, 2% from acquisitions, and 1% positive from currency.
The impact, of course, since the SEK continues to weaken, we expect, as when we calculate then from end of September, that we're going to have a positive impact from currency in Q4 of about 5%. EBIT also record, first time above 7 billion, up 11%.
Here just to mention that we have released a mid-single dollar mid-single million dollar amount into our results, which sort of slightly helps it positively. EBITDA, as mentioned, 18.7%, up 80 basis points; EBIT up 60 basis points; income before tax, net income, and EPS, all are up with 14%.
Cash flow also very strong at 6%. Should also keep in mind that this quarter also had a higher CapEx, which is related to that we have acquired two buildings in Entrance North America.
If we'd exclude these two buildings, our cash flow would have been 13% up versus last year. Also encouraging to see that our return on capital employed is up with 70 basis points and are touching now the 15%.
Operating value added also up with 10% and is now close to 12 billion SEK. If we look onto the bridge analysis and look on the organic, price was a strong 2, which consequently means that volume was a weaker 2.
The currency, as mentioned before, is related to the SEK. The flow-through ended at 47%, which is driven by the organic leverage then from price versus cost, as well as manufacturing footprint saving this quarter, it was slightly above 200 million, as well as other kind of operational efficiencies that we can do.
Then if you look on M&A, top line, it was contributing with 2%; bottom line, it's dilutive, but it has to do, Nico mentioned before, the Sentrol acquisition and also acquisition costs coming from that, as well as acquisition costs related to Gunnebo, which we hope to close before the end of the year. If we then look into the direct material or the cost breakdown, direct material is 80 basis points better than last year.
Out of that, if I call it the true price versus cost, is plus 60 basis points. We see, however, in the market now that raw material, electronics, plastics are going up, but we're confident that we can mitigate that with additional price increases.
Conversion cost, 20 basis points better, as mentioned before, we have operational efficiencies, MFP, and so forth. SG&A is at the similar level as what it was last year.
We have been able to continue to invest in R&D, as well as selling, and this has been offset by admin and back-office efficiencies, including, I would say, the first results that we see of our AI initiatives. Operating cash flow, as mentioned before, including the buildings, we are 6% better than the same period last year; excluding, 13% better.
If you look on cash conversion in the quarter, it was 117%, and if you look on a 12-month rolling, it's at 109%. Gearing, net debt to equity landed at 54%.
We continue to drive also down the net debt to EBITDA, and was now at 2.0. If you look over a year period, we have been able to lower our debt with roughly 2.5 billion SEK, and we sort of continue to have a very strong balance sheet so we can continue our acquisition strategy going forward.
If you look on the last slide, I mentioned the number before, earnings per share was up with 14% versus same period last year. With that, some concluding remarks, Nico.
Nico Delvaux
Good. Like we said, we believe, up to you to judge, of course, but we believe a very good quarter with a lot of records.
A record top line with a good organic sales development of plus 4%, record operating profit, and record margin, and the second-best cash flow in our history. Like we mentioned, we will launch now in Q4 our manufacturing footprint program number 11.
I would say that we are proud of what we have accomplished in the first nine months, and we are confident in our ability to deliver another strong year for ASSA ABLOY. With that, I give the word back to Björn for Q&A.
Björn Tibell
Thank you very much. Yes, that means it's time to open up for your questions.
Could I just remind you to please limit yourself to one question each with one follow-up. Then we'll allow everyone to ask questions.
Once you have actually asked your question, feel welcome to put yourself in the queue again. I think it's likely that we will be able to come around the queue and start with you over again.
Operator, that means that we are ready to kick off the Q&A session. Please go ahead.
Operator
Thank you very much. We will now begin the question and answer session.
Anyone who wishes to ask a question may press star and one on the telephone. You will hear a tone to confirm that you have entered the queue.
If you wish to remove yourself from the question queue, you may press star and two. Questioners on the phone are requested to disable the loudspeaker mode while asking a question.
Anyone who has a question may press star and one at this time. Our first question comes from George Featherstone from Barclays.
Please go ahead.
George Featherstone
Hi, yeah. Morning, everyone.
Thanks for the questions. The first one just be on EMEIA.
Obviously, you've talked recently about having some tailwinds from this NIS2 regulation, and the growth has obviously been very strong again. I just wondered if you could parse out for us what the contribution you think is from that regulation in this quarter?
Then just on the margin, obviously, it's trending towards the sort of 16% it was before on the EBIT level in the region, but you're having good volume growth. What's the sort of next step to get us back above 16% from here?
Nico Delvaux
George, as I can say we are very happy with the development of EMEIA over the last four quarters or so, you could say, because we have really seen organic volume growth coming back, and we have seen an acceleration of that organic volume growth. I would say that is very widespread.
Yes, NIS2 contributes, but NIS2 contributes most probably around half a percent organic growth, because NIS2 today still very much DACH-related, you could say, and Nordics-related. It still has to pick up at a higher speed in the rest of Europe, and we are confident that that will happen going forward, because that's normally also how things happen in Europe.
Things first start in the Nordics and perhaps in DACH, and then it spreads more over the rest of Europe as also the local countries start to adapt the European directive into a local law. I would say it's much more widespread.
We see very good volume growth on the commercial side in most, if not all, markets. We have, of course, the emerging part with India, Middle East, Africa that also contributes.
Then, like I said, on the residential side, we're a bit more positive than in North America, where we see R&R slightly coming back and where we even have seen new build a little bit coming back in countries like Sweden and the Nordics. Then, of course, next to the organic volume growth, we have also the price component, as we continue to see higher inflation that also gives us then the possibility to further increase prices in EMEIA.
When it comes to margin, you see if you have a little bit of organic volume growth and you see an acceleration of that organic volume growth, you see also a better volume leverage, and that volume leverage then leads to better bottom-line results. You see in EMEIA the last three, four quarters, they have been able to improve margin sequentially quarter after quarter, and I'm confident that that will continue for the next quarters as we confidently will continue to see that organic volume growth.
They have a very good cost structure that with a little bit of organic volume growth, you can get very good operational efficiencies.
George Featherstone
Thank you very much for that, Nico. Just a follow-up on what you said on Global Solutions as well, mostly in the release.
You talked about this temporary depressed retail segment. Can you just give us a little bit more context and kind of how temporary that will be, when you think it will recover?
Clearly, you can see something in the order book, I guess, otherwise, you wouldn't have said temporary.
Nico Delvaux
I would not say it's depressed. It's perhaps more an operational execution challenge at two of our bigger customers for the, yeah, InVue business.
Because I think HID in Global Tech had a very good quarter, very good solid organic growth. Global Solutions, the same thing if you exclude InVue.
InVue is then very dependent on a couple of bigger customers that have placed very big orders with us, and they have some delays in operational execution of those projects, you could say. Some of that sales is now postponed till Q4 and most probably even to Q1 next year.
I would say it's no drama. It's just a little bit delay in us receiving the sales.
In a way, perhaps it's even good for us, because InVue is very seasonal. Normally, Q1 is very weak.
If we can get now some sales that we should have gotten in the second half in Q1 next year, it will help also a little bit with the seasonality, so that's the reason why perhaps Global Tech is a little bit weaker than anticipated on organic growth side. Perhaps you see just a comment, if you see that if we have a little bit less organic growth, then we also deliver on our promises that at least we will deliver the bottom line and the cash flow, because you've seen very strong bottom line and cash flow.
Sorry. Go ahead.
George Featherstone
I was just going to say, thanks. Can you quantify the amount of the InVue slippage, maybe in terms of organic growth?
Nico Delvaux
I don't know, to be honest, exactly the number, but I would say it's between 1% and on Global Tech level, it's around 1%, I would say.
George Featherstone
Okay. Thank you very much.
Operator
The next question comes from Phil Buller from JPMorgan. Please go ahead.
Phil Buller
Hi, good morning. Thanks for taking the questions.
Firstly, I was hoping if you could help us understand if there's any one-offs on the resi side in the US. Good growth here seems to be at odds with the leading indicators.
Is there a one-off ahead of price increases, and is there anything one-off in the 140 bps operating leverage, such as a tariff refund? Thanks.
That's the first question.
Nico Delvaux
Specifically for the resi, there is no one-offs. I would say that, in general, it's a clean quarter for the group, definitely also a clean quarter for resi.
Yes, we have seen some growth in resi, some price, and some volume. Like we have said at many occasions, we don't need a very strong recovery on the resi side to see very good margin improvement.
As a matter of fact, we had a very good margin for Q3 in resi North America thanks to that volume growth, because we have that cost structure now that a little bit of growth gives immediately very good volume leverage. Has nothing to do with price increases or anticipation.
Then, of course, you should not read too much in one quarter neither. Like I mentioned earlier, we believe that new build is still very challenging in North America and is definitely not improving compared to three months ago with the Fed now further increasing interest rates and you see also mortgage rates further going up.
If already something, I think the recovery of the new build will be further delayed in North America. Like I also mentioned, we believe that at least R&R has bottomed out, and perhaps has started to grow with very low single-digit numbers, perhaps.
Of course, we have a lot of growth initiatives where we try to do better than the market. We have launched a complete new padlock range, product that we did not have in our portfolio before.
We have invested a lot in digital door locks and have a very wide product range today. We have also invested in renewing our mechanical core for Kwikset.
There's a lot of initiatives that we launch to try to do better than the market.
Erik Pieder
Perhaps just to add, because your question was a bit related to tariffs, the mid-single digit million dollar amount that I talked about, that affected Global Tech and Entrance. There's nothing in the Americas result.
Phil Buller
Thank you. Then as a follow-up on that macro uncertainty topic, obviously, there is a lot of uncertainty out there and we've got a new restructuring program.
Is that in anticipation of perhaps markets getting a little bit softer as we think ahead to 2027, or is this more of a reflection that you've identified further cost-out opportunities as part of the current program that you've looked at even if the outlook was less uncertain, I guess? Thanks.
Nico Delvaux
No, it has nothing to do with market conditions. As we do an MFP program every around 18 months, and it's 18 months ago that we did the previous one.
As we continue to buy companies, we continue also to buy factories, warehouses, sales offices that we then can further consolidate. That's what we will do now also in MFP 11.
Drivers are very similar as our previous 10 MFP programs, I would say.
Phil Buller
Thank you very much.
Operator
The next question comes from Ines Lefranc from Goldman Sachs. Please go ahead.
Ines Lefranc
Hi. Thank you very much for taking my question.
My first one is just on the manufacturing footprint program. Could you give us any color on expected restructuring charges, targeted savings, or payback period?
Thank you.
Nico Delvaux
Not really, because we are still finalizing the numbers. Understand that you want to have at least an idea.
Most probably, the new MFP will be a little bit bigger than MFP 10, because that's normal. We have further grown our company.
If you grow, you can also do more restructuring. I think from a dynamic perspective, factories, warehouses, customer centers will be very similar.
I think from which divisions contribute, it will also be very similar. We're very confident that we will have a very good payback on this one as well.
Too early to give you the detailed numbers. That will be something for the next call.
Ines Lefranc
Makes sense. If I could just ask one follow-up on the tariff impact, that mid-single-digit million dollar in Global Tech and Entrance, is that a one-off for this quarter?
Do you expect any tailwinds next quarter, too? Any color would be really useful.
Thank you.
Erik Pieder
If I should sort of elaborate a little bit more on the tariffs, first of all, I would say that, so far, we have received, I would say, a high double-digit million dollar amount in the results in Q3. In reality, then we have a mid-double-digit million dollar amount that has been then going to the results, but then most of that money we have then used for, let's say, writing off PPA, initiatives in R&D, and so forth.
Let's say we have invested that in the business. In Q3, out of that, as I mentioned, it was sort of a mid-single-digit million dollar that impacted the results.
If you have a high, as I mentioned, a high, which means that we still have, let's say, money left also for Q3, we have to see a bit, let's say, how much will in practice then impact the bottom line. That is not really clear yet.
Ines Lefranc
Makes sense. Thank you.
Operator
The next question comes from Aron Ceccarelli from Bank of America. Please go ahead.
Aron Ceccarelli
Hello, hi. Good morning.
Thanks for taking my question. I have a two-part question on North America.
Your largest peers in the US has been printing now stronger pricing than you, at least that's what appears from the numbers, for couple of quarters at least. I was wondering if this because of your deliberate action to potentially gain market share in a weak residential market, or is something different?
Do you expect this gap to persist?
Nico Delvaux
No, I think it's not that we try to gain market share with reducing price or keeping prices lower. Our price is on group level, and the price component has been higher than group average for the Americas division.
That comes because the Americas division is also more steel-related, and steel has seen important pricing inflation. I think another explanation is that we, as the market leader, we were also the first ones to increase prices when things started with tariffs and also inflation.
Our comparison with last year on the pricing component is also more challenging. I think if you look over a longer period, and our colleagues also report price quarter after quarter, if you look over a longer period, over the last three years, you will see that price component most probably is very similar.
Aron Ceccarelli
Thank you.
Operator
The next question comes from Gael de-Bray from Deutsche Bank. Please go ahead.
Gael de-Bray
Thanks very much. I have two questions, please.
Firstly, I'd like you to hear your thoughts on the new partnership between Apple and LG to develop doorbells and smart door locks. I think you already have many products that can integrate with Apple's ecosystem.
Maybe just your views on the risks there would be obviously much appreciated. Perhaps a reminder of your actual exposure to the smart door lock business.
Nico Delvaux
Yeah. This is an initiative in North America.
I would say we like the initiative very much, because clearly Apple has a much bigger marketing budget than we have. I think it's good that people like Apple start to make more publicity in the market for digital door locks, that will help the sales of digital door locks in general.
As you rightly said, we have a very wide range of digital door lock products that are compatible with the Apple ecosystem and with the Amazon and Google ecosystem and with all the new standards that you have in the US. If you see also the positioning of this new product from Apple, it positions rather high in the market.
You could say that it's a little bit a competitor of what we used to have with Yale when we were still the owner of Yale before that divestment when we acquired HHI. Today with Kwikset, we play much more in the middle segment.
Yes, we have the ambition to move up to that, you could say, Yale higher-end segment, but that is still today a smaller part of the market. The big volumes are in that value segment.
I think for us, it's a positive thing. It will create more marketing.
It will create more noise in the market around digital door locks, and it will drive, yeah, more business in that sense. When it comes to a part of our business, I think the digital door locks are around 10 5% 5% they are around 5% 5% of the North America resi business.
It's a smaller part of our revenue today, you could say.
Gael de-Bray
Okay. Understood.
Still pretty small indeed. Then the second question I have is, I did not fully understand the rationale for selling the citizen ID business unit.
It has a strong margin, it includes the SaaS business. Why is it that you cannot grow the business further?
Nico Delvaux
Actually, what we divested was a combination of four companies, four companies that came through acquisitions long, long time ago: ActivIdentity, IdenTrust, Zetes, and then HydrantID. I would say HydrantID was the biggest part.
It's a small business all together. It's around $50 million, $60 million.
This HydrantID, they had this PKI, public key infrastructure certificates, and what they do is they do the lifecycle management of those certificates, you could say. It's a very interesting business, fast-growing indeed, and highly profitable, but with very little synergies with the rest of what we do in HID and with the rest of what we do within the group.
We are a small player in that field. We are far number four, five.
There's a couple of very dominant players. As we have always the ambition to be a leader in what we do.
If you want to become a leader, we could not do that organically, we had to buy the number one or the number two. As these are pure software businesses, multiples are very high in this field.
Paying a very high multiple to become a number one, paying a lot of money for a business that has little or no synergies with the rest of HID and the rest of the group, we thought that there were better ways to allocate capital. Rather than sticking on an interesting asset and over time having the risk that that would go down and dilute, we thought it was a better idea to sell it now at a good price, at a good valuation, and give it to somebody else that is clearly a better owner for that business than us in ASSA ABLOY.
Gael de-Bray
Thank you. If I may, is there any capital gain you expect to book on the transaction?
Nico Delvaux
Yes, we will come back to that in Q4. Like we said, it's a smaller acquisition, also from a dilutive perspective, it will not really move the needle on group level.
Gael de-Bray
Yeah. Thank you very much.
Operator
The next question comes from Alexander Virgo from Evercore ISI. Please go ahead.
Alexander Virgo
Thanks very much for taking the question, gentlemen. Trust you're well.
Could you talk a little bit to the gross margin and Global Tech margins, I guess, as two two questions, but same question on margins. Gross margins close to 44%, I think that's also something of an all-time high.
Just wondering if you can talk a little bit to how we should expect that to evolve over the coming years. In Global Tech, now, I guess, north of 20.5% ex FX and M&A headwinds and strong incremental margins there, are we now back to a sort of a new level in Global Tech as well?
Thank you. Now
Nico Delvaux
if I start with Global Tech, we have always said that we have an ambition for Global Tech to have margins above the 16% to 17% bandwidth. We shoot more about something around that 18%.
Yes, this quarter was an extreme good quarter. Quarter three is always the best quarter for Global Tech.
I think you should see this more over a business cycle and definitely over a full year. Today we are, I think if you look on a nine on year-to-date trend, we are at 18.5% for Global Tech, more in line with that 18% ambition that we have.
For the time being, we believe this above the 17%, 17% to 18% is still the right ambition for us, because, yes, we have a couple of very mature and very profitable businesses in Global Tech, like the PACS business in HID and the hospitality business in Global Solutions, but we have a lot of smaller businesses that we want to invest in R&D, in feet on the street, that are much lower margin and that we want to bring up volume-wise, size-wise to similar levels as PACS or hospitality. That's on Global Tech.
On the gross margin, of course, if you look back the last two, three years, we have had a very good journey when it comes price to cost, direct material versus price increases in the market. We have had quarter after quarter strong accretion of that price versus cost, so that is one big explanation.
I think we have done the MFP programs, like Erik said, also helping on the gross margin side. I think we have done a very good job through our operational organization in I would say using our scale and our growing scale to get also better conditions out of our suppliers.
Then next to that, all the operational efficiencies like VA/VE initiatives that we do in our factories and together with our suppliers. I think it's just a good operational job, well done, explaining the very nice gross margin improvement.
I think that's across all divisions. I think all divisions, you will see similar pictures.
Erik Pieder
Perhaps, Alex, also if we look a little bit more short term, we expect also then for Q4 to have a tailwind on price versus cost. That's a bit how far we see, and then we have to see how it goes in the first quarters next year.
Alexander Virgo
That's super helpful, Nico, Erik. Just to follow up there on that, that 60 bps in Q3 then should be closer to 100 in Q4?
Erik Pieder
I said a tailwind. Normally I would sort of say that I think you're way too high with that.
I think it's going to be positive, and let's see if it reaches the 60 bps.
Nico Delvaux
It should be another good, significant accretion in Q4, Alex, because most probably not on the same level as in Q3, because you see material indexes further going up, you see definitely also energy inflation further going up, logistic inflation, and general inflation. On the other hand, we also continue to increase prices, we will see how the pricing intention we have plays out in the market.
Q4 should be another good, significant price versus cost.
Alexander Virgo
Thank you very much.
Björn Tibell
Before we jump over to the next question, I'm being informed we just have one person in the queue now. If there are any follow-up questions, feel welcome to press, I believe it's star one.
Operator, you can probably help with that.
Operator
Thank you very much. Our next question comes from James Moore from Redburn Atlantic.
Please go ahead.
James Moore
Morning, everybody. Erik, Nico, I wondered if I could ask a little bit about the forward-looking picture.
Maybe you could please talk about specification, I'm sorry if you said it earlier, I got cut off a moment, and by region and globally, and also talk about the momentum into October, if you could, please?
Nico Delvaux
The traditional question we normally get is how was the demand over the quarter and then exit rate and rate in October, that's the question you now ask, James. I would say in Q3, demand has been quite stable over the three months, and now going into October, we see a similar pattern.
We should not forget in Q4, yeah, in theory, we have one working day more, but what you see is, of course, that in October, which is an important month, we have one working day less, and then in November and in December, we have one working day more, but the working day in December is working day more in a holiday month, you could say. Very, very similar from a working day perspective this year versus last year.
The spec business, we have seen high single-digit growth of our spec business. It was a little bit better in the Americas and in Australia, New Zealand, a bit lower in EMEIA.
In EMEIA, it was just a difficult comparison with quarter last year where we had a couple of very big projects that we quoted. If you correct for you could say the outliers also in EMEIA, we had a similar high-single-digit pattern.
Still very, very positive on the specification momentum, still believe good driver going forward.
James Moore
Thanks, Nico. Could I just follow up with some kind of point on that?
We've seen indicators and permits deteriorate in the last three months, and as you point out, rates have gone back up a bit. I was quite surprised to see your underlying US and European results.
It's just a bit better than many thought. Would you characterize that as the market being better before the pain of rates kick back in, or that you have had the initiatives away from those that you talked about in HHI, which you seem to be taking some share in that market?
Do you characterize the US non-res or the European resi, non-res performance as being a function of any kind of indicators or more just like mix where you've got naturally bigger exposure?
Nico Delvaux
If we talk on the commercial, on the non-residential side, as we are late in the construction cycle. I would say that at least as far as we can look forward, perhaps a year or so looking forward, we don't see any slowdown.
You could argue that higher interest rates indeed lead to less projects. On the other hand, if you look, for instance, in the US, if you look at our two main verticals, education, schooling, as it's a lot financed through local bonds, and I think local bonds have never been as high as they are today.
I don't think we see any slowdown there. On the private side, it's money which is deployed in a different way.
Like we mentioned at early occasions, if you want to be in education today in the US, upgrading your access solution is a license to operate with all the security concerns and all the shootings going on. I think a similar picture on healthcare, which is our second-important vertical in North America.
The demographics of population and also the need for healthcare is not going down, on the contrary, we also don't believe we will see any slowdown there. We are still very positive on commercial in North America, and I think similar what I said for Europe.
James Moore
Thanks, Nico.
Operator
We have a follow-up question from Aron Ceccarelli from Bank of America. Please go ahead.
Mr. Ceccarelli, your line is open.
You may proceed with your question.
Aron Ceccarelli
Hello, yes. Sorry, I was on mute.
I believe your tone on Europe seems incrementally positive. Perhaps can you give a little bit of tour by country, what drive this level of confidence increasing?
Thank you.
Nico Delvaux
If we start perhaps in the Nordics and perhaps with Sweden, you know that Sweden was the first ones to reduce interest rates. They were nine months before ECB, they are a bit, you could say, the canary in the mine, they indicate a little bit what happens in the rest of Europe.
We have seen, like I mentioned at earlier occasions, residential market in Sweden coming back, first on the R&R side, and today we also slowly start to see it coming back on the new build side. A similar story is true for Finland, which are the two main markets for us in the Nordics.
Commercial activity is high like it is in all regions in Europe, but is even further boosted by this NIS2 regulation, where, like I mentioned, Nordics is one of the drivers in applying physical hardware around NIS2 with a lot of CLIQ sales and so on. If you go to Central Europe, similar story.
NIS2 further boosts our commercial growth in the DACH region. As in Germany, we are more, if you could call it, a niche player.
We are not or very small on the residential side. We are strong on the commercial side, definitely on the high end of the commercial side.
We profit there also a bit that we are in the best market, you could say, in the DACH region, in Germany in particular, and we see there very good, high-single-digit growth numbers, again, also boosted by NIS2. East Europe, good on residential and commercial side in our main markets like Poland.
If you go to South Europe, I would say a little bit more mixed picture. Spain, Italy have been maneuvering very good through the lower years last year and so on, and we continue to see good development there, where France has been much tougher, definitely also last year.
In France, we have a little bit the advantage that we have now an easier comp. Then we will see how all the unrest that we have seen in recent weeks in France plays out, because France together with UK are two important residential markets for us.
Then UK and Ireland, I would say UK and Ireland has been flat since Brexit, and we have year after year been hoping that UK, Ireland would recovery, that has not really happened so far. We see now at least some early signs that there might be some recovery, definitely on the commercial side in UK.
Hopefully, those early signs get confirmed now in the coming quarters. Then we have the emerging part, like I mentioned, Africa, Middle East, India.
Perhaps surprisingly, but we see still good development in the Middle East. We see very good development in Africa and in India.
We were late to enter India, we only entered India in 2018 when I started in this position. We have seen since then, yeah, good double-digit growth in India, starting from a smaller level, and we are confident that that growth will continue.
Aron Ceccarelli
Thank you very much.
Operator
We have another follow-up question from Andre Kukhnin from UBS. Please go ahead.
Andre Kukhnin
Yes, good morning. Thank you very much for taking my questions, and sorry if there's some repeat, we had some technical issues here.
I just wanted to start with NIS2. Is there any way you could help us quantifying the degree of help that this is creating for the market?
Also, how should we think about it in terms of, is it kind of a one-off boost that we need to think about comping at some point in 2027, or is it a more of a multi-year growth driver where the addressable install base is so substantial that this will take many years to get through?
Nico Delvaux
We answered the question when perhaps you had the technical problems, but NIS2 for EMEIA accounts for around half a percent organic growth, we estimate. The reason being is that today it's still mainly focusing on the DACH region and the Nordics, Sweden and Finland, where we have seen a lot of business for our CLIQ solutions, our electromechanical solutions.
As NIS becomes more widespread in the rest of Europe, we are confident that we will see similar patterns in other markets like France, Italy, Spain, you name it, but they are traditionally always slower or later than the Nordics and perhaps also then DACH, because they are faster in implementing those new European directives into local legislation. We believe it's more a multi-year activity, because even in DACH and in the Nordics, we are far from done.
There is still a lot of companies, basically all mid-size and bigger companies have to do something around cyber security, and not only from a software perspective, but also from a hardware perspective. Even in DACH and in Nordics, we are not done yet, and then, of course, all the other markets still have to come.
We see this as a cherry on the cake, you could say, for EMEIA for several more years to come.
Andre Kukhnin
Great. Thank you.
Apologies for a repeat question. If it's another repeat, then just leave it and I'll come back to the transcript, but I wanted to ask about the MFP program that you're planning to launch during Q4.
You indicated that it will be sort of similar to prior programs, but obviously as the group gets bigger, I just wondered if those MFP programs should also be getting bigger or more frequent over time?
Nico Delvaux
The strength of the message is in the repetition, we also gave an answer on this one. We have said that MFP 11 most probably will be a little bit bigger than MFP 10, because, as you rightly said, we have grown in the meantime, and so we have also more possibilities, and we have continued to do acquisitions, we have more factories, warehouses, sales offices that we can consolidate.
What we said, from a mix and from a concept perspective, it will be very similar to the previous 10 MFP programs, with all the different divisions contributing, and with confidently also a good payback for this MFP 11 program, but too early to give the exact numbers, that will come in our next call.
Andre Kukhnin
Thank you. Thanks for your patience as well.
Operator
Ladies and gentlemen, that was the last question. I would now like to turn the conference back over to Björn Tibell for any closing remarks.
Björn Tibell
Thank you very much. Thanks, everyone, for your participation.
If there are any follow-up questions, feel welcome to reach out to us at Investor Relations. That means we don't have much more to say.
We look forward to speaking and meeting with many of you in the coming days and weeks. We wish all of you also a safe and secure end of the year.
Thank you for your participation again, and have a good day.
Nico Delvaux
Thank you. Thank you.