Asure Software Inc
NNASDAQ:ASURQ3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Good afternoon, and welcome to Asure's Third Quarter 2026 Earnings Conference Call. Joining us for today's call are Chairman and CEO Pat Goepel, Chief Financial Officer John Pence, and Vice President of Investor Relations Patrick McKillop.
Following their prepared remarks, there will be a question-and-answer session for analysts and investors. I would now like to turn the call over to Patrick McKillop for introductory remarks.
Please go ahead, sir. Thank you.
Patrick McKillop
Thank you, operator. Good afternoon, everyone, and thank you for joining us for Asure's third quarter 2026 earnings results call.
Following the close of the market, we released our financial results. The earnings release is available on the SEC's website and our Investor Relations website at investor.asuresoftware.com, where you can also find our investor presentation.
During our call today, we will reference non-GAAP financial measures, which we believe to be useful to investors in understanding our business and exclude the impact of certain items. A description and timing of these items, along with a reconciliation of non-GAAP measures to the most comparable GAAP measures, can be found in our earnings release.
Today's call will also contain forward-looking statements that refer to future events, and as such, involve some risks. We use words such as expects, believes, and may to indicate forward-looking statements, and we encourage you to review our filings with the SEC for additional information on factors that could cause actual results to differ materially from our current expectations.
I'll hand the call over to Pat in a moment, but I wanted to take a moment to remind people of some upcoming investor relations activities. On November 17th, we will participate in the Craig-Hallum Alpha Select Conference in New York.
On November 18th, we will attend the Stephens Annual Investment Conference in Nashville, Tennessee, as well as the ROTH Conference in New York. On November 19th, we will participate in the 7th Annual Needham Virtual Tech Conference.
Finally, on December 16th, we will attend the Northland Capital Markets Virtual Growth Conference. Investor outreach is very important to Asure, and I would like to thank all of those that assist us in our efforts to connect with investors.
Finally, I would like to remind everyone that this call is being recorded, and it will be made available for replay via a link available on the Investor Relations section of our website. With that, I would now like to turn the call over to Pat Goepel, Chairman and CEO.
Pat?
Pat Goepel
Thank you, Patrick, and welcome, everyone, to Asure's third quarter 2026 earnings result call. I'm joined on this call by our CFO, John Pence, and we'll provide a business update for third quarter 2026 results, as well as our updated outlook for the remainder of the year.
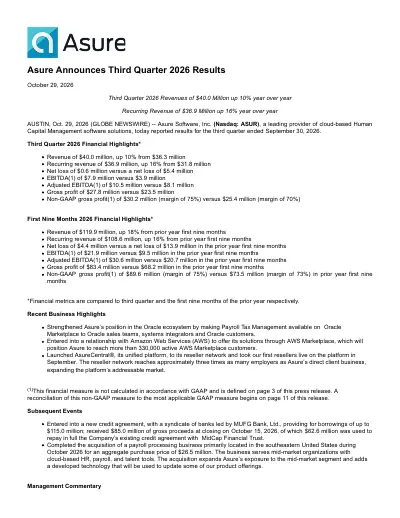
Our third quarter revenues came in at $40 million, representing a growth of 10% compared to the third quarter of 2025. Growth was strong and broad-based, with payroll, benefits, and HR compliance among the key contributors, and we're reaping the benefits of the investments we have made in the business over the last few years.
Our organic growth rate for third quarter 2026 was 9%, compared with 4% in the third quarter 2025, an increase of 500 basis points, and up 5% in second quarter 2026. Organic recurring revenue growth for the third quarter was 14%, which is a continued acceleration driven by the launch of Asure Central a year ago, and continued payroll tax management momentum.
The positive feedback for our products continues to grow, and this is supported by our recent G2 awards announced this fall, where we were rated a high performer in several categories, as well as a momentum leader and a leader in the small business segment. Building on the 9% organic growth and the 14% recurring organic growth we delivered this quarter, we continue to intensely focus on driving double-digit organic growth in the future and increase cross-selling activities, while continuing to grow the embedded tax business.
During the third quarter, we meaningfully expanded the distribution of our payroll tax management solution, which already represents nearly 20% of Asure's revenue. In August, we announced a co-selling arrangement for our payroll tax management solution on the AWS Marketplace, and we began to actively co-sell into its 330,000 customers in September.
AWS customers can procure Asure through the existing purchasing processes, including unused AWS spend, and our sales team co-sells alongside AWS sales teams against our ideal customer profile. Streamlining contracting and private offers can shorten the typically long enterprise sales cycle.
In September, we also made payroll tax management available on Oracle Marketplace, integrated with Oracle Fusion Cloud Human Capital Management. Organizations running Oracle can add multi-jurisdiction payroll tax filing, funding, and money movement without migrating their payroll system of record.
They can then use the payroll system of record as we file across federal, state, and local jurisdictions on their behalf. Together, the AWS and Oracle marketplaces open up new opportunities for payroll tax management.
Indeed, in the payroll tax management business, we have already won approximately 30 major enterprise accounts for payroll tax management, and these partnerships will continue to help grow that segment of the business. In September, at our annual reselling training event, we launched Asure Central to our reseller network, and took our first resellers live on the platform, which we believe will unlock significant cross-sell for our human capital management suite as we have done in the direct business.
Asure Central brings single sign-on, user provisioning, role-based access together with payroll, tax, HR, recruiting, time and attendance, 401(k), benefits, and Luna, all in one environment, and resellers can white label the experience with their own logo. The number of clients purchasing multiple products has increased by 7% versus the third quarter 2025.
With the increase in attach rates, we're also experiencing an uptick in our retention rates versus the second quarter, and we will share updated retention metrics in our one-year, year-end 2026 release. We remain focused on moving clients from an average of a little more than two products per client relationship, towards four or more products per clients over time.
Now, a brief update on AsureWorks, our administrative services outsourcing offering, which lets clients delegate key payroll and HR compliance processes to Asure. The momentum we saw at launch continued into the third quarter.
Our pipeline and new clients continue to grow and set new records. The reception across the target buyers includes small hotel chains, restaurants, HVAC companies, as an example, and remains very, very strong.
These are Main Street businesses that need payroll and HR compliance support, but lack the internal resources to manage it themselves. We are continuing to train more reps for AsureWorks every day, and build out that effort.
Clients who adopt AsureWorks typically represent up to 5 times the revenue of payroll-only clients, and because it is not a PEO model, there is no co-employment risk, which makes it a compelling and flexible alternative for clients constrained by the cost and rigidity of a traditional PEO. On the sales front, we made significant progress in hiring reps.
We're confident in hitting our target of 150 by year-end. The efforts of our recruiters and our sales managers really have paid off, and we're excited to have these new reps on board.
These are full solution sellers who can sit down with a business owner and present our entire product suite, and that consultative, needs-based approach is central to driving both new logo acquisition and multi-product cross-sell within our existing base. The new type of rep we hire typically ramps faster than when we have experienced with prior reps.
Our existing to new customer logo split in the third quarter was approximately 47% to 53%, an improvement versus a year ago of 36% to 64%, but similar to second quarter of this year where we continue to drive towards our 35% new logo, 65% base expansion mix over time. Our contracted backlog is now $86.6 million, and we expect to convert approximately 46% of that backlog over the next 12 months.
We continue to operate in a positive selling environment, as small and mid-sized businesses need the products and solutions Asure offers to help them navigate the complex world of payroll and compliance. In our forecast, we conservatively model flat headcount growth for our clients.
We haven't seen any dramatic shifts in the sales cycle process. On the M&A front, after quarter end in October, we acquired a human capital management payroll processing company based in the southeastern United States for an aggregate purchase price of $26.5 million.
The company serves mid-market organizations with cloud-based HR, payroll, and talent tools, expanding our exposure to the small and mid-market segment and adding an in-developed technology that would be used to update some of our product offerings. We have an active pipeline of potential reseller acquisitions, and will continue to pursue those opportunities.
Also, in October, we closed a new credit facility, which gives us some more flexibility to pursue our strategy, and John will share more details in a moment. On AI, our view hasn't changed: payroll and HR compliance isn't software a generic AI can replace.
We hold money transmitter licenses, interface directly with the IRS, state and local agencies, and manage compliance where the margin of error is effectively zero. That makes Asure a system of record, and our expertise a real moat.
At the same time, AI is a meaningful accelerator for us. Luna conversations grew about 25% in the quarter to more than 26,000, and in her first year, Luna has completed more than 15,000 AI actions for our customers.
At the start of fourth quarter, we released the time import agent, bringing Luna directly into the payroll run, with humans in control at every decision point. I also want to take a moment to recognize and congratulate our Chief Technology Officer, Yasmine Rodriguez Joaquin, a pioneer in payroll tax technology and the compliance infrastructure behind it, who has been named to Women We Admire's Top Women Chief Technology Officers of 2026.
Yasmine, congratulations, and thank you for everything you do for Asure and our clients. With that, I'd like to turn the call over to John to discuss our third quarter financial results in more detail, and provide an update on our 2026 guidance, along with our outlook for 2027.
John?
John Pence
Thanks, Pat. As Patrick noted, several figures discussed today are on a non-GAAP or adjusted basis.
Reconciliations are available in our earnings release and our investor presentation at investor.asuresoftware.com. Third quarter total revenues were $40 million, compared to $36.3 million in Q3 of 2025, representing growth of 10% year-over-year.
Recurring revenue for Q3 2026 was $36.9 million, compared to $31.8 million in Q3 of 2025, an increase of 16% year-over-year. Recurring revenue represented approximately 92% of total revenue in the quarter versus 88% a year ago.
Professional services, hardware, and other revenue was $3.1 million in Q3 of 2026, compared to $4.4 million in Q3 of 2025. The decline versus prior year was primarily due to reduced professional services provided as part of large tax deals in the prior year.
Gross profit for Q3 2026 was $27.8 million, compared to $23.5 million in Q3 2025. GAAP gross margin for Q3 2026 was 70%, compared to 65% in Q3 2025.
Non-GAAP gross margin for Q3 2026 was 75%, compared to 70% in Q3 2025. Net loss for Q3 2026 was $0.6 million, compared to net loss of $5.4 million in Q3 2025.
EBITDA for Q3 2026 was $7.9 million, compared to $3.9 million in Q3 2025. Adjusted EBITDA for Q3 2026 was $10.5 million, compared to $8.1 million in Q3 2025, an increase of 29% year-over-year.
Adjusted EBITDA margin for Q3 2026 was 26%, compared to 22% in Q3 2025, an increase of approximately 400 basis points. We ended the third quarter with cash and cash equivalents of $16.8 million, and total debt of $64.7 million as of September 30th, 2026.
Subsequent to quarter end, on October 15th, we closed a new senior credit facility of up to $115 million with a syndicate of five banks led by MUFG Bank, Ltd. The facility has an $85 million term loan, all of which was drawn at closing, a $10 million, 5-year revolving credit facility, and a $20 million delayed draw term loan facility.
The term loan currently carries a rate of SOFR plus 3%. This adjusts periodically based on our consolidated net leverage ratio, and could be as little as SOFR plus 2.75%, and will not exceed SOFR plus 3.5%.
We used $62.6 million of the gross proceeds to repay in full our existing credit agreement with MidCap Financial Trust. Turning to the southeastern U.S.-based payroll acquisition Pat mentioned, the aggregate purchase price was $26.5 million, paid as follows: $13.5 million in cash at closing; a promissory note in the amount of $3 million to secure the indemnity obligations and other adjustments; and the issuance of shares valued at $10 million.
The purchase price is subject to customary working capital adjustments. Based on the current positive momentum in our business, we are updating our Q4 2026 and full year 2027 guidance.
Please note that the guidance incorporates the recent acquisition we completed in October 2026. We anticipate revenue of $42 million to $44 million, and adjusted EBITDA of $10 million to $12 million for Q4 2026.
This implies full year 2026 guidance of $162 million to $164 million in revenue, and adjusted EBITDA of $40 million to $42 million. Next year, our preliminary guidance for 2027, we anticipate revenue to be in the range of $183 million to $187 million, and adjusted EBITDA margins to be in the range of 26% to 28%.
We expect our cost structure, including capital expenditures and capitalized software development costs, to remain relatively stable on a dollar basis. With that, I will turn the call back to Pat for closing remarks.
Pat Goepel
Thanks, John. Stepping back, I think the third quarter tells a clear story.
We grew revenue 10% to $40 million, and adjusted EBITDA grew 29% to $10.5 million, with adjusted EBITDA margin expanding approximately 400 basis points to 26%. Reoccurring revenue organic growth continues to accelerate, reaching 14%, and we forecast it to be in the double digits again in the fourth quarter.
We're really starting to hit our stride, but we're not slowing down. Our sales team is larger and more productive.
Our clients are buying more of our core payroll and human capital management products. Our unified technology platform enables us to cross-sell, which drives improved retention, and we can scale organically.
We have a very active pipeline of opportunities for payroll tax management, and the new distribution capabilities of Oracle and AWS will help build further opportunities. AsureWorks is gaining traction, and our recent G2 awards reflect the positive feedback our clients have about our products.
Just a few years ago, we laid out a goal of $180 to $200 million in revenue, and with today's forecast for 2027 of $183 million to $187 million, we are close to crossing the goal line. We've worked hard and executed, and all of our metrics are trending up.
Margin expansion and improving profitability are two important characteristics of our model, and AI is helping us lower our costs to serve, while improving the client experience. We're proud of the progress this quarter, and even more excited about what's ahead.
Thank you for your continued support, and for joining us today. Before we open the call for questions, I want to take a moment to acknowledge the recent loss of Dick Strong, a longtime supporter of Asure and a good friend.
Dick was a very smart, talented, kind person, and he'll be greatly missed. On behalf of everyone at Asure, we offer our heartfelt condolences to his family and Donna.
Thank you for your continued support and for joining us today. I will now turn the call back to the operator for questions and answers.
Operator?
Operator
Thank you. We will now conduct a question-and-answer session.
If you would like to ask a question, please press star one on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press star two if you would like to remove yourself from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
Once again, that's star one at this time. One moment while we poll for the first question.
The first question comes from Jeff Van Rhee with Craig-Hallum. Please proceed.
Jeff Van Rhee
Great, thanks. Thanks for taking the questions and congrats on a nice posting here, guys.
A couple for me. First, Pat, maybe on the per employee per month, where are you now?
What does a full suite purchase right now tally to, and where do you think that can evolve to over time?
Pat Goepel
We publish [cough] the art of the possible, which is $100-plus per employee per month. A specific number, we'll start to get a little bit more color in 2027.
If you add brokerage, and you add all those kind of products and services, as much as $180. We're continuing to sell more products and services, and we're training for that.
Then we have Asure software through Asure Central, or we'll do it for you with AsureWorks. We're still in the middle of movie, and there's different sample sizes with different training.
We'll lay out probably a metric around that in 2027. Right now, suffice to say, it keeps going up.
This past quarter, revenue per unit in the payroll business was somewhere up 57%, which was really a nice progression of what we're trying to do. I think in 2027, as we get more mature, I think we can establish that metric and publish that.
Jeff Van Rhee
Got it. Then the southeastern reseller, a bit larger than your typical reseller purchase, I heard in the script.
There's maybe some incremental capabilities there as well that might stand out. Maybe just a second more on what you're getting there with that purchase.
Pat Goepel
The technology is obviously like a reseller acquisition, very simple in integration, etc. They had some kind of unique front ends that we think will help us advance the whole business on some verticals, we're excited about that.
We think that there's some growth in selling. We also think, from an integration perspective, this is what we do, we think we can add scale, add capability, add growth, and, frankly, we thought it was a pretty attractive acquisition for us to do.
Mm-hmm.
Jeff Van Rhee
Then maybe, John, just a couple quick quick numbers questions then. As I look at Q4 in the '27 outlook, what organic growth is embedded in those two numbers?
Then this this reseller, can you give us a little dial it in a bit closer in terms of what the reseller itself brings in terms of Q4 revenue and next year's revenue?
John Pence
I'd say when we bought the business, it was probably at about a $10 million run rate, I would expect a couple million in this quarter to be realized. We think obviously there's some upside to what they were doing historically when we put our sales team behind it and when we start to maximize some of the technologies they've built out.
In terms of next year, I think the guide kind of in the midpoint implies kind of 13%, 14%. I would say, right now, that majority of that's going to be organic, just in terms of the guide for next year.
Jeff Van Rhee
Okay. If I could sneak one last in there, just on free cash flow.
Appreciate the '27 outlook. Is there just a real quick bridge, I keep a close eye on, just curious what that guide implies in terms of free cash flow for '27?
John Pence
Again, we have a little bit of this, and we can talk about it off, but the way we think about it, Jeff, is always thinking about the adjusted EBITDA less the cost to finance. I think, with this new loan, we're expecting probably around $8 million of interest costs for the year, roughly $2 million a quarter, I think.
Jeff Van Rhee
Okay.
John Pence
If you factor that off, and then again if you want to take software cap off the table, that's going to be really consistent. I think we'll probably be in about the $14 million range next year on that.
I think midpoint of what we guided towards is in the 40s, mid-40s. Back off software cap, and I think we're in the low 20s when it's all said and done, from our perspective.
Jeff Van Rhee
Got it. Great.
Congrats on the quarter, guys. Thanks.
John Pence
Thank you.
Pat Goepel
Thank you, Jeff.
Operator
The next question comes from Richard Baldry with ROTH Capital. Please proceed.
Richard Baldry
Thanks. If I look year-over-year, and I add your cost of goods sold and your opex, the numbers are very flat, while revenues were up decent.
Can you talk about the pieces of that sort of cost savings? Is it integration, AI, or just scale, leverage, efficiencies?
Seen a lot of companies across my space noting that AI can drive material cost savings, sort of wondering how far along that spectrum you feel like you are.
John Pence
I'll give you my perspective first, Rich, and then Pat will obviously have his. I think we're just in the early innings.
We've always said, really consistently as long as I've been here, that this is a scale business, and you're now starting to see the benefits of it. That was pre-AI.
I think what you're seeing right now is the pre-AI scaled part of the business. We are implementing AI throughout the business.
We've got it in ops with our call centers. We're using it in the finance area.
Our sales guys are going into it as well with Gong, and some of the other tools that they're using. I think early, early stages of us getting AI benefits.
I think what you're seeing right now is just pure scale part of the business. That's my perspective, and I think there's a lot of opportunities in the future to take more cost out.
Pat Goepel
I would echo with John exactly that. I think the next wave here is, I always say that the end-to-end process starts with the customer, goes to our office, and then comes back to the customer.
I think in the area of workflow, we still have a lot of AI opportunity to take cost out and improve all the way around. I think there's some other things around marketing where marketing and sales and customer acquisition, again with workflow.
The work that we're doing internally, I think we're just getting a productivity factor here every quarter. We'll continue to work in those areas in 2027, and I would say a lot of it's come with scale, but definitely AI is top of mind in how we do business and how we become a better company.
John Pence
I didn't even touch on Luna just in terms of the customer experience, right? Their ease of use of the software.
I think there's just again, lots of opportunities still.
Richard Baldry
All right, then if I look at the fourth quarter specifically, the adjusted EBITDA guide of $10 to $12 million, at the low end of it, it'd be actually down a little bit sequentially. Obviously, the upper end would step up pretty good.
Can you talk about some of the variables to do that? The acquisition and organic growth intend to drive some sequential top-line growth, how do we look at that range and where we'd expect to end up?
John Pence
I think, from my perspective, Rich, we've talked about it throughout the year. We've been running behind in terms of where we wanted to be in the sales headcount.
I think we're finally starting to catch up, so that's one of the headwinds. Headwinds good, bad, in terms of we're finally getting fully staffed on that team.
I do think that there's going to be a little bit of integration work, too, with the acquisition, I'm expecting really good fall-through from that acquisition in terms of EBITDA contribution, but not necessarily on the front end, because I do think there's going to be some work rationalizing that business. I think I feel good about the guide, and I do think that there's a little bit of headwind just with some of the things I mentioned in the fourth quarter.
Yeah.
Pat Goepel
Oh, I'm sorry, Pat.
John Pence
Go ahead.
Pat Goepel
Yeah. If I look at it around fourth quarter, first of all, there's a jumping off point on continued spend in the sales and marketing area.
We feel like we've done a lot of work with technology and the operations. From a sales, marketing perspective, we're close to the 150 target of sales people.
We're going to go up again next year in sales people, fourth quarter, implicit in that, is some ramp costs in sales for '27. Then the other thing is, if you look at the mix in the guide, reoccurring revenue is growing over non-reoccurring revenue to the tune of a little over $2 million in the fourth quarter.
The quality of revenue is super high, and then the integration that John spoke of, operationally, we're continuing to sell more and more products per customer, and we're spending some calories on integration between departments and workflows and customer products that we think will benefit in '27 and beyond. In the immediate quarter, we want to make sure we get those processes right, we're spending some money.
John Pence
Just to put a finer point on it, I think midpoint of the guide is about a 10%, a little under, year-on-year growth for next quarter. It's going to be I think a similar story as this quarter in terms of the mix of recurring and non-recurring.
We're adding a lot more recurring. We had a lot of pro services last year as it relates to some of the big tax deals, we're not expecting that same volume of non-recurring.
We're, yeah, really excited about the mix in terms of the organic growth that's outpacing the non-recurring that's falling off.
Richard Baldry
Got it. Have a good quarter.
John Pence
Thank you.
Pat Goepel
Thanks, Rich.
Operator
The next question comes from Jared Levine with TD Cowen. Please proceed.
Jared Levine
Thank you. To start, I was hoping to get an update in terms of the SMB HCM demand environment more broadly here.
What are you seeing? Has there been any macro impacts or changes, as you kind of look over the course of this year in terms of a demand progression, in terms of where you're seeing on pipeline volumes or even sales cycles?
Pat Goepel
Pipeline's really good. Pipeline's gone up, and we anticipate a really good fourth quarter, first quarter sales.
Pipeline is strong. I would say the multi-product continues to be a focus, whether it's the managed service or software.
A small business wants fewer vendors, a little bit more simplicity. They want a partner that they can hang their hat on with multiple products and services.
Those trends I think will continue. As far as staff, clearly, they want access to capital, they want access to people, they want the easy button so they can focus on growth, and a vendor that can provide more and more of those services.
Then also they want the vendor to have a point of view. In the area of compliance, we're seeing that broader pipeline of HR, payroll, compliance all the way through the stack.
Then, where there's more pressure with the SECURE 2.0 Act around 401(k), especially in the states that have legislated that, we see that as a big demand focus as well.
Jared Levine
Great. Then for my follow-up here, I wanted to touch on float revenue.
Just given the recent 25 basis point increase, can you remind us kind of a framework in terms of how to think about that? I know you do take some duration in terms of a laddering strategy, but just how to think about that benefit from that recent 25 basis point increase as we kind of look over the next four quarters or so?
John Pence
I think, from my perspective, it's worth for us roughly $0.5 million a year every quarter point right now with our current balances. That's a simple way to think about it at a high level.
Jared Levine
Got it. Thank you.
John Pence
Again, we talk to Goldman at least once a quarter, but we had our quarterly update with them last week, and their current view is that there's another quarter point coming in December meeting, as well as another quarter point in March. Going into next year, that we probably will see another half point, at least on their current view of rates.
Hopefully that's a million dollars of upside to this current year in terms of float.
Pat Goepel
Then, Jared,
John Pence
you're only assuming Go ahead, Jared. I'm
Jared Levine
sorry.
John Pence
Go ahead, Jared. I'm sorry.
Jared Levine
I was just going to say, in terms of your guidance for next year, you're just assuming the one hike that has been announced to date?
John Pence
We haven't overestimated, yeah, the float. That's in tight.
In the current guide, it's just like what's in the current rates right now.
Jared Levine
Great.
Pat Goepel
Jared, in the cue is our laddering strategy, as well.
Jared Levine
Awesome, great to hear. Thank you.
Pat Goepel
Thank you.
Operator
Thank you. The next question comes from Eric Martinuzzi with Lake Street.
Please proceed.
Eric Martinuzzi
Had a nice uptick in the gross margins in Q3. I was curious, obviously you've given us a view to revenue and EBITDA margins for 2027, but what's implied as far as gross margin?
Was that Q3 just kind of an outlier, or is there a change in the longer-term gross margin expectation?
John Pence
I think on a GAAP basis, I think we're probably in the 70% range for the year. I think we'll probably get two points or so next year on a GAAP basis.
There's usually about 5-point spread between the GAAP and the non-GAAP. If you think 70 this year, it's probably 75-ish non-GAAP, and I would say, next year, I think we're shooting for about 72% GAAP and about 76%, 77% non-GAAP.
Eric Martinuzzi
Got it. What is behind that?
Is that just efficiencies in the workforce? I'll let you answer the question.
John Pence
I think it's a little bit of what I was talking about with Rich. It's not anything extraordinary, except that we expect our people to continue to be able to ramp with the tools we're giving them, with more and more.
It's just kind of implied in the model. If you think about, we've had this slide in the IR deck for, I don't know, years, where we kind of talk about the breakpoints of the model at different scale levels.
I think it's been out there for quite a while. At 200 million, we're expecting to be kind of 30% adjusted EBITDA, and it scales from there.
There was some modeling behind that. It wasn't just aspirational, and so the model's just kind of playing out the way we were hoping it to.
Then,
Pat Goepel
Eric, just the average customer revenue per unit going up, and the adoption of more products and the attach rate going up, that's allowing us to have a better gross margin tick up over time.
Eric Martinuzzi
Got it. Congrats on the numbers and the outlook.
Pat Goepel
Thank you. Thank you.
Operator
The next question comes from Brett Huff with Stephens. Please proceed with your question.
Colby Sanford
Hey, this is Colby Sanford on for Brett Huff. Appreciate you taking the question and nice to finally be covering you all.
Last quarter, you described the enterprise payroll tax pipeline as really strong. Since then, you've been at Workday, HR Tech Conference, Oracle, and you've added payroll tax management to the Oracle Marketplace, and now AWS as well.
What are you hearing from your enterprise buyers and your ERP partners at these events? Kind of how should we think about these marketplace announcements and how they will generate new leads for y'all?
Pat Goepel
I think, first of all, our team has been in Las Vegas three weeks in a row at a busy time, and I was joking with our President and Chief Revenue Officer, Eyal Goldstein, if he was taking residence up in Nevada, but we've gotten a lot of really good feedback. Our product team's worked really hard.
The strategy of the foundation level lever for us around embedded payroll, tax filing, treasury, etc., is a great foundation for us to be, because it allows us to play up and down the enterprise clients to the medium and small clients, but, frankly, also other payroll companies, because they use some of our foundation tools. The feedback's been really positive.
I was on calls even this morning, and this afternoon right before earnings, with a number of different clients and opportunities and partners that really like our modernization strategy in this area, and that those tools perhaps were underserved by other players in the past, and we have that capability. I think our time is right now.
Sometimes luck is preparation meeting opportunity. We've prepared for this moment, and I think you're going to see a lot of growth here in that area.
You've already seen it, but then '27, '28, I think you're going to see strong growth in that area.
Colby Sanford
Awesome, super helpful and I appreciate it. If I could just sneak one more in there.
A larger competitor of y'all's has been leaning a little bit more into PEO, moving some of their clients out of management solutions and into that PEO business and having their sales team refer some deals into it. Just curious if you're feeling any of that new logo deals in your client base, and just any change in the competitive landscape recently with some of your competitors and just the AI natives?
Pat Goepel
I think, from our perspective, I used to run a PEO, and I was the CEO of a PEO, and that's an environment that can get complicated quickly. I personally think we have all the capabilities of the model if we choose to do that.
We would have the capability to build into that base. As far as I look, we have the capability and kind of what we're doing where you don't have to have things like group insurance and all that, where you can unbundle that, and we have kind of best-in-class tools and managed services without the PEO.
I happen to like that position. As far as the competitive environment, I think, all in all, it's going to be a changing environment.
We're a better company with AI and software, not one or the other, and I think other competitors feel that there's opportunities too. For us, it's an exciting time to be part of a human capital management space, and we think there's market share opportunity to go after, and we're pleased to report really good quarter because of that.
I think the trend towards multiple products, multiple solutions, having tools not only around breadth of products, but also workflow within products is where a good solution looks like. Then agentic AI with the workflows gives more power to the user on a quicker basis and makes good decisions, and we're leading into that strategy as well.
Colby Sanford
Awesome, thank you.
Operator
Once again, ladies and gentlemen, to ask a question, please press star one on your telephone keypad. The next question comes from Greg Gibas with Northland Securities.
Please proceed.
Greg Gibas
Hey, good afternoon, guys. Congrats on the quarter.
Wanted to ask regarding those strengthened positions, one within the Oracle ecosystem, but also payroll tax management available there, and the relationship with AWS. Could you maybe speak to the response you're seeing so far at this point, as it relates to the opportunities with those networks or potential customer bases?
Pat Goepel
Greg, it's so early days, I would say, and I was at two of the trade shows. I didn't have a chance to go to Oracle just with timing of earnings, but our team was there.
I give you an idea, last year, we were at the Workday conference, I think our lead volume was probably triple last year, and it's just the progression of us having a lot of success stories and taking market share, and there's been a good buzz there. The lead flow was really good, HR Tech very similar.
From the feedback I'm getting at Oracle, really good opportunities, some good, serious buyers, and there's an opportunity with the modernization of the work we've done. People really want to engage with us, and that's right where we want to be, and so the early returns are real positive.
A lot of these announcements are over the last 45 days or so, and a lot of this activity has been in the last 30 or so. We'll continue to progress here, but it's probably just a little bit early, but initially, a lot of excitement.
Greg Gibas
That's fair. With respect to the payroll processor you acquired, I think you mentioned some verticals or capabilities that add an incremental opportunity to where Asure sits today, and wondering if you maybe expand on those, and then should we think about the purchase price being pretty close to your two times revenue target?
Pat Goepel
I think purchase price was about 2.6 times revenue. We disclosed that, and how I look at it is we've got nice size, nice capability.
The staff is really strong. They know our products and services, we know their products and services really well, the learning curve is not a long plot.
It's a really easy plot for us. Then when I look at some of the vertical markets they've done and some of the capability, I think some of the scheduling capability, and kind of time opportunity there, in addition to some of the reporting, we think was a nice add to some of our product family and service family, and that we're going to leverage that going forward.
Greg Gibas
Got it. Thanks very much.
Operator
Thank you. At this time, I would like to turn the call back over to management for closing comments.
Pat Goepel
No. Anyway, I'm just seeing if the team had anything.
Hey, third quarter was an outstanding quarter for us. Good momentum, reoccurring revenue going up, we're excited about it.
We think that'll pay dividends as we finish the year of 2026 in a strong way. In '27, it sets us up for really good growth.
John mentioned that in the IR deck, I think it was 3 years ago, we kind of pointed to 180 to 200 million. We're in that sweet spot.
It's been very predictable for us. That scale wins.
The AI, good fortune, we're embedding that in a lot of things we do, which is helping our software. Change is afoot in human capital management.
Our people are at the tip of the spear leading change. We've got a lot of pipeline of opportunities, and I think we're a story to watch here, and I've been here a long time, really, really excited.
From an investor perspective, hey, we lost a good one in Dick Strong, and I want to again wish my sentiment to the family, but right now, I think it's a real good time to look at Asure again, because we got a lot of stuff going on. I really appreciate your time, and have a good day.
Operator
Thank you. This does conclude today's teleconference.
You may disconnect your lines at this time. Thank you for your participation, and have a great day.