Aura Minerals Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 6, 2026
Operator
Good morning, ladies and gentlemen. Welcome to the third quarter 2026 earnings call.
This conference is being recorded and the replay will be available at the company's website at auraminerals.com/investidores. The presentation will also be available for download.
This call is also available in Portuguese. To access, you can press the globe icon on the lower right side of your Zoom screen, and then choose to enter the Portuguese room.
After that, select mute original audio. Para acessar a nossa conferência em português, clique no ícone do globo ao lado inferior direito da sua tela Zoom, e certifique-se de selecionar a opção Portuguese room.
Ao acessar a nova sala, certifique-se de mutar o áudio original. We would like to inform that all attendees will be only listening to the conference during the presentation, and then we will start the question and answer sections when further instructions will be provided.
Before proceeding, we'd like to clarify that any statements that may be made during this conference call regarding the company's business prospects, operational and financial projections, and goals are the beliefs and assumptions of Aura executive board and the current information available to the company. These statements may involve risks and uncertainties, as they relate to future events and therefore depend on circumstances that may or may not occur.
Investors should be aware of events related to the macroeconomic scenario and industry and other factors that could cause results to differ materially from those expressed in the respective forward-looking statements. Present at this conference, we have Rodrigo Barbosa, President and CEO; Kleber Cardoso, CFO; and Glauber Luvizotto, COO.
Now, I turn the conference over to Rodrigo Barbosa. You may begin the conference.
Rodrigo Barbosa
Thank you very much for all participating in this earnings call for the third quarter. Good morning, all.
Before I get started, just a quick reminder that you have here in your screen, scan the QR code. We have our Aura Day happening in New York at Nasdaq on October 30th afternoon.
We will have an important updates about how we are running the operations. We're going to have important updates about the turnaround on MSG, how we are developing Era Dorada, then we are also thinking and doing now this year a zero-based budget.
We're going to walk you through how we are planning the budget also for next year. There's also the transition of the mine fleeting sources that we recently announced.
There will be several updates, including an important advancements in exploration that we will like to share with the market on October 30th. Please, put in your agenda, and if you have availability, be there with us.
That will be an important opportunity to have a more broad conversation and deep conversation about how Aura is performing and how we will perform on the next 3 to 5 years. Let's get started if we can put the first slide in terms of the production and results.
As a quick summary, and as we all do at the same time, same structure, I'm going to go through the main results and how major events that happened during the third quarter, and then Kleber is going to go more in detail about our results and cash flows. As we disclosed to the market, we had an important improvement in operations.
As I mentioned on the last quarter, first and second quarter was the weaker of the year, and we could see that production was pushed towards the second semester. This is an important improvement on Q3, and we project another improvement to Q4, we should continue to grow in terms of production as we are now reaching higher grades or higher productivity in most of our mines.
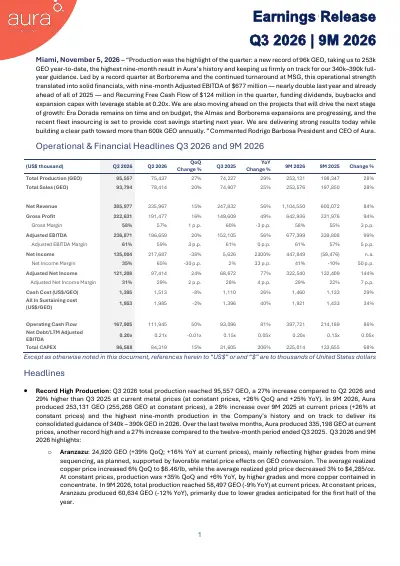
We reached a production of 96,000 gold equivalent ounces. This is a 27% increase compared to the last quarter.
I'm going to walk you through mine by mine the two slides ahead so we can understand what is going on and project what can happen on the fourth quarter. When we see the 9-month, it's 253,000 ounces gold equivalent.
We reiterate our guidance to be between 340 and 390,000 ounces until the end of the year. This higher production means also the record high, slightly above the first quarter of this year, $386 million on revenues, another 15% improvement quarter-by-quarter.
That also translated in an EBITDA, $237 million. When we see the last 12-month, the last 9-month of EBITDA, it's $677 million.
This is already above what we performed the full year of '25. If we look at the last 12-month, it's $886 million, understanding that the fourth quarter, we should have an improvement in terms of production.
In terms of all-in sustaining cash cost, we are now at $1,953. Now we start to have improvements on MSG, that also improvements that I'm going to walk you through that's going to happen on the other operations.
Although, if you compare to the guidance of this year, you're going to see that we are above the guidance, but the improvements that we see happening in the fourth quarter gives us a comfortable zone to meet the guidance for the full year in terms of all-in sustaining cash cost. Recurring free cash flow strong, $124 million, enough to continue to be able to grow, develop projects, invest in exploration, and also pay the dividends.
We continue to be unleveraged company, walking the talk. We've always mentioned to the market that we would be able to develop our greenfield projects, invest in exploration to extend life of mine, and do M&As while keeping a important dividend yield and low leverage.
This is another quarter that we show the market that this is possible due to the very high returns and stronger cash flows we have from our operations. We also declared another strong dividends, 72 cents per share, and when you add that with the $10 million of buyback that happened during Q3, it's a yield of 4% on the last 12-month.
We continue to be one of the highest dividend yielding in the industry while we are growing. Additional important events, and I'm going to have a slide about this, I don't want to give details now, but Era Dorada project, on time, on budget, developing according to the plan.
Kleber also, we raised additional $200 million of syndicated loan. That happened during this quarter and improved our cash position above $400 million.
We also announced the mine fleet insources that will provide us a important opportunity to continue to reduce our all-in sustaining cash cost and control inflation, bravely, the inflation, as we will walk you through the industry all-in sustaining cash cost is going up. We are going up slightly, but yet way below the average of the industry, which put us in the first semester of this year as on the first quartile in terms of all-in sustaining cash cost.
Important event also is Capital World Investors continued to buy more shares on Aura during the third quarter and reached recently about 10% of the capital structure of Aura. Now they have 10.2% of the Aura shares.
Next slide. In terms of safety, we had no lost-time incident during quarter.
It's a very important another quarter without any lost-time incident. I always mentioned that it's important to combine always, not important to combine, but strong results comes along with also a stronger incidents and low incidents level.
Important also that as we are implementing artificial intelligence all over our company, there is also important improvements that we are doing on safety standards going through artificial intelligence so that we gather more information and start acting way above when we predictively, we can predict when and where the next event can have of incident can have event and then prevent on that. That's what all the team is working on to have these advanced tools so that we can improve even further our safety standards.
In terms of stability of structures, all of them has been gone through a due diligence and inspections, and all of that are under the safety levels and according to the Brazilian regulations and all the international regulations. On the left side of this slide, I will highlight the continuous growth.
We've been growing since Q3 '25, actually since Q2 '25 on the last 12-month. Now we are performing 335,000 ounces of production on the last 12-month.
As you can see, record high production on Q3, while we continue to see improvements that's happening even on Q4, that will replace the Q4 of last year with 82,000 ounces with a stronger, so that will continue to be important upward trends in terms of production for Aura Minerals. When we go mine by mine, we had a going from the bottom to the up important improvement in Aranzazu.
We could see that the higher grades would come during the second semester. Management's also working in higher throughput, improving also the through the plant.
The combination of higher grades and better performance lead us to a higher production, and small part of this is also unfortunately due to the lower gold prices than and the higher copper price, so that conversion happens and it's favorable. Most of the improvement comes from productivity and grades.
Apoena, we saw a slight improvement on Q3, and again, Q4 is the quarter that we're going to have a very strong production on Apoena. In Aranzazu, we should continue to see a small improvements for Q4.
Apoena, we'll see a significant improvement in terms of production on Q4. This is just about grades that we already reaching on the pit that we're going to go through the plant.
Minosa, as I mentioned to the investors on last quarter, we had some challenges on piling and stacking during Q2 that we know that's the lag it's a leaching pad, the lag of while you stack and produce happens to have 30, 40, 60 days, we knew that the production would decrease during Q3, and now we know that's going to increase during Q4 because all the challenges has been overcome, and now we are stacking as we projected or even a little bit above what we projected, so that will result in an improved production on Q4. Almas, we knew also that we were hitting a lower grades.
The mine plan is not, as I mentioned, gold We are now sometimes in a very thin veins or straight veins, and grade goes up, grade goes down, it's normal for you to have a stronger and weaker quarter. What cannot be is not predictable, right?
We know that the Q3 would be weaker, and now we know that Q4 can also be slightly better than Q3. Borborema, this again, we hit a strong grades, and also now we already implemented two new filters debottlenecking the plant, we should continue to see strong production in Borborema during Q4.
MSG, the turnaround is still going on, but it's important to see the first signs of what we were talking about, the gain in productivity and gain in production once you invert the top-down to bottom-up and put more and develop more underground. We are now starting to have a small percentage of ore coming from underground on the methodology bottom-up, so that improves the grade to the plant.
Then, on Q4, we'll gradually improve because then we mix low grade that is on the top as open pit with a higher-grade underground, and as we go in a turnaround, as we advance on developing of the underground tunnels, we will be more gradually to more and more increase the underground ore, which will increase average grades to the plant. Also, management's been doing a significant cost savings, cost restructurings, and also debottlenecking the plant so that we can gain even more efficiency for next year, putting us in the position to be able to produce close to 80,000 ounces and close to $2,000 per ounce all-in sustaining cash cost.
In terms of all-in sustaining cash cost, we had a slightly decrease from Q2 to Q3, that came mostly by MSG, that showed some significant improvements. Also, Aranzazu going through a higher grades.
If were not the MSG, our all-in sustaining cash cost would be at $1,673, which is already the first quartile in the industry, although yet we see room to improve. When we look at the next quarter, we will have improvement in MSG, Aranzazu will continue to perform well, we will see a significant improvement in Apoena, good improvement in Minosa, Almas, slightly improvement due to the higher grades, Borborema stable to the fourth quarter, perhaps lower cash cost as well.
We will see fourth quarter coming down in terms of all-in sustaining cash cost, putting us on the comfortable position to meet the guidance, perhaps closer to the top end of the guidance, but yet in the guidance. I would also highlight that when we projected the guidance, the exchange rate was different than what happened during the 9 months was for Brazil, that's more important, was 5.5, while the performance was close to 5.
Now we are back to 5.5, so that only this is 80 ounces per $80 per ounce in terms of all-in sustaining cash cost if we were at the same exchange rate of the budget. During the fourth quarter, we have improvements on grades, improvements in performance, and also a better exchange rate in Brazil.
Era Dorada, we already reached over 13% of physical progress. The earthmoving of the operational plateau is completed.
We started the civil works, and as we can see on the picture in the middle, the CIL tanks start to be built. On the right side, all the infrastructure for cooling the underground as we are advancing on the underground, it will be more and more important gradually to improve the infrastructure and also cooling machines in order to keep the temperature low.
This is a geothermal area that has hot water, and we are pumping already our water out of the underground while cooling so that we created the right environment for everybody to work. On the left side on the pictures, we continue to have a very strong support from the community.
It's now over 1,500 hours of a dialogue with a community members, constant dialogue, open table with each of them. We have a Era Dorada house at the main city that people can come and make questions, it's a full transparency project.
We're hiring local people, we are motivating new suppliers to form within very close to the operations, and while we are investing on the purified water to provide them first municipality in Guatemala to have access to purified water will be the communities around Era Dorada once we finish the investment along next year. Then we'll be able to provide purified water to the communities.
The geothermal plant, we continue to advance on the engineering. We are now looking for potential partners to invest in geothermal with us that can bring the know-how and operate and do the partnership with Aura.
This project will be fully sustainable with renewable energy, renewable water, and also a very strong community relations and focusing on hiring and training local people. We now have 795 people employed as of September, 89% are Guatemalan, understanding that during the construction sometimes you have a very specialized skills doing for the underground development and also for building the plants, and we should gradually increase this percentage hiring local people.
MSG, again, a very important first quarter with just the beginning of the results of the turnaround. We already generated $24 million on EBITDA, and we continue to do advance developing on the underground activities so that we now can gradually invert top-down to bottom-up and mix more high grade from underground instead of a low grade that is on the top.
We'll see improvements going through the Q4, and of course, major improvements going to come during 2027. We will go through in more detail on Aura Day.
Please participate, go directly there in New York or see the video or see the live video that we will walk you through major achievements happening also in safety standards. There'll be important updates in exploration.
Please attend that we can walk you through what's going on in MSG that can become very and has the potential and will become a very important mine for Aura Minerals from '27 and so on. With that, I turn the floor to Kleber to walk you through on the financial results.
Kleber Cardoso
Thank you, Rodrigo. Good morning, everyone.
We're going to start as we always do with a summary of the main financial KPIs for the reporting quarter, for the previous quarters, and accumulated last 12 months at the end of each reporting periods. Starting with the net revenues, we're reporting a net revenues of $386 million is a record high that we're reporting for a single quarter.
That's driven by the increase of production that Rodrigo was showing, and when we look to the last 12 months, our revenues are exceeding $1.4 billion, and we've see there has been a steady progress quarter over quarter, aligned with our growth story. When we go to adjusted EBITDA, it's a similar story.
We're reporting a strong EBITDA, $237 million at this quarter, also driven by the increase in production. The last 12 months now at $886 million and is already the 13th increase in a row of our last 12 months EBITDA, again consistent with our growth story.
Moving to the bottom of the page, in terms of net income, our net income this quarter, $135 million, coming down from previous quarter, but that's mainly because on the previous quarter we had a non-cash, non-recurring gain related to the gold hedges because of the decrease of gold prices during the second quarter. If we exclude that non-cash gain, which was much smaller this quarter, I'm going to show later, we see also an increase in net income.
On the bottom of the page, you see we're coming from a $97 million adjusted net income on Q2 to $121 million now on Q3, consistent with what we see increasing EBITDA. In terms of cash and net debt, we remain in a very comfortable position in terms of cash and balance sheets.
Our net debt basically stable throughout the quarter, ending close to $180 million by the end of Q3. Our financial leverage also basically stable in a couple of quarters already at 0.2 times net debt over EBITDA, and we see a significant improvements in our cash balance and cash position, now close to $420 million at the end of the quarter with the proceeds of the syndicated loan that we closed in September, $200 million, and now we are in a good position to continue funding the growth of the company, especially Era Dorada from now on.
Now, looking the main items that explain the adjusted EBITDA and adjusted net income, between adjusted EBITDA and adjusted net income in the quarter, out of the $237 million adjusted EBITDA, Borborema was the highlights. We saw that was a very strong in terms of production.
Borborema is our lowest cash cost as well, contributing with $70 million EBITDA. Aranzazu also a very strong performance on Q3, combined with favorable copper prices, adding another $60 million.
Always also coming strong, Almas and Minosa, $41, $35 million, and we highlight as well, as Rodrigo mentioned, MSG already reporting $24 million EBITDA in the quarter, still in the turnaround phase. Moving to the next items, we see depreciation, amortization, $30 million, basically consistent with our expectation.
If we compare to same period of last year, there is a important increase, but that's mainly related to the growth of the company. The same period of last year, we didn't have MSG, Borborema was not in commercial production yet, not depreciating, so that explains the increase in depreciation.
Financial expenses, we would highlight, as I mentioned before, the non-cash gain with the mark-to-market of the gold hedge was much smaller this quarter, was only $13 million, and we had a realized losses with gold hedges. We paid $34 million for the gold collars that were settled and paid during Q3.
From now on, if you take November, from November '26 to June 2028, we still have about 141,000 ounces in gold collars that is going to expire monthly now until mid of 2028. Income tax expense pretty much consistent with the results of our operations.
Then we had some smaller items in other income and provisions, bringing the net income to $135 million, and then here on the right side of the page, the conciliation that we always show excluding some non-cash items, mainly the unrealized gain in this case with the gold hedges, bringing our adjusted net income to $121 million in the end of the quarter. Now here, we have all the details that explains the change in cash position throughout the quarter.
On the left side of the page, we start with $248 million in cash at the beginning of the quarter. On this left half of the page is what we call the recurring free cash flow to firm, which is the free cash flow to firm generated by the six mines in production, not including investment for growth, not including what we paid for the hedges.
We show $158 million on the top of this page is those six mines that generated $158 million in recurring free cash flow. Deducting $34 million that we paid in hedge comes to the $124 million recurring free cash flow that we're reporting, although the realized losses with hedges is including the recurring free cash flow.
We remind you that it expires in mid of '28, so that's going to go away after 2028. Then here in the middle of the page, we see investment for growth, $63 million, mainly expansionary CapEx, and now mainly is catching up, ramping up the investments cash out investments in Era Dorada.
To the right side is more the financial-like items, mainly the proceeds, net proceeds from debts. We received $200 million from the syndicated loan, had some debt amortization, we had net proceeds of $182 million.
Dividends and share repurchase, $71 million in Q3, and then if, Rodrigo highlighted at the beginning, if you take the $158 million recurring free cash flow that was generated for the quarter, that paid both for the losses with the hedges, also the dividends and share buybacks, and also paid entirely for the expansion CapEx we had in the quarter. With this, we end the presentation and open to questions.
Thank you.
Operator
We are going to start the question and answer section for investors and analysts. If you wish to ask a question, please press the button Reaction, and then click on Raise Hand.
If your question has already been answered, you can leave the queue by clicking on Put Hand Down. Our first questions comes from Mr.
Marcelo Arazi from BTG Pactual. Mr.
Marcelo, you may proceed.
Marcelo Arazi
Hi, guys. Thanks for the space here.
Two questions on my side. The first one on Era Dorada, it was very nice to see that the project has been evolving on time and within budget and with 13% physical progress.
I would like to understand a little bit more, what are the main milestones and potential execution bottlenecks over the next 12 months, and especially regarding the geothermal side of the project, which remains of a major concern for a few investors that we normally talk to. If I could make a second one about the fleet insourcing announcement.
A few questions here as well. How quickly should these benefits materialize next year?
What are the main risks associated with bringing those operations in-house? What was actually the final trigger for Aura to decide and make this change?
Thank you, guys.
Rodrigo Barbosa
Thank you, Marcelo. I can start answering here a little quick, and then I will ask Glauber that can give you more details about next steps in Era Dorada and also how he sees the insource of the mine fleet upcoming on the next year with the potential also savings.
The geothermal plant, I'm not sure if you ask about the geothermal plant is something that will come along the next few years. We will not start construction anytime soon.
We still need to partner and find the right partner and do the right feasibility study and engineering so that that will probably go into production after 2 or 3 years of operations. In the meanwhile, we have other alternatives to supply the power.
If you were mentioning about the potential high temperature underground, Glauber can also walk you through. That's not unusual conditions to have.
There are a few other mines in the world that run actually even in worse conditions. It's a matter of calculating and do the proper underground infrastructure, pumping hot water, and also bringing cool air down.
Glauber can walk you through more detail of this situation plus what he sees coming up in the next 12 months. Glauber?
Glauber Luvizotto
Hey. Hi.
Good morning. As Rodrigo said, is we are, in terms of construction and preparation of the mine, that we call the pre-operation, we are on track for that.
It's a lot of challenge from the hydrothermal water, but we have the support from the specialists and also a very robust plan to offset that point. Right now, everything that we found is as we expected, but we are just in the beginning, also.
We are pumping the water, because the key point is we should to pump the water in advance. We should go down with the table water to make sure that the moment that we access that region, there is no more hot water in that region and the rock have had time to refresh.
It's what we are doing right now, the pumps are under construction and the wells are under preparation. We are using some old ones.
We are being able to reduce the table water and doing all the mining development on time. In parallel, all the infrastructure that we have like the refrigeration plant and all the other stuff, it's already on-site under commissioning.
I think that the main milestone in the next 12 months from the construction side, we have the main equipments to arrive on-site, the mill and all the other equipment, and also put the mining development in the run rate. We are considering right now we have a contractor doing the underground development.
We are considering as well to have part of the work made by us, we already bought some equipments that are on time to be delivery in the end of this month, in beginning of the next month. We have also some contingency plan to bring to the region some experts, because the main point is find people with experience in the underground that there isn't much in Guatemala, but we are considering we are doing like a task force to train, prepare people, and have some experts to mainly in this beginning to put the mine on track.
The other question from the insource, the key point is that we are seeing a lot of adjustment in the cost when we went to the market to make an assessment about the price and cost to do that primarily by contractor. The costs are being significantly higher than we are practicing.
Also, we feel that we are prepared to considering the maturity that we have in the operations, we are prepared to assume this another part of the work. The process right now, we are in the transition to creating the company that will assume all the assets from the contractor.
We have the gate to be approved on CADE. Once we have that, in the beginning of next year should be fully Aura.
Right now, we are in the transition phase. Everything is going well.
We expected to be more efficient, mainly doing the properly maintenance, to make sure that we have the reliability in the fleet. I think that we can increase productivity from the equipments, and we can also see the impact in our costs.
For next year, in terms of all-in cost, we have see some reduction in the three mines, but most part of the disburse for the equip that we are paying will be next year once we phase it in accordance with we are advancing in the contract that we did. It's going on track, so.
Rodrigo Barbosa
Thank you.
Marcelo Arazi
Thank you, Glauber. Thank you, Rodrigo.
Very complete answer.
Operator
Our next question comes from Mr. Lawson Winder from Bank of America Securities.
Mr. Lawson, you may proceed.
Lawson Winder
Thanks very much, Natacha, and hello, Rodrigo and team. Thanks for the presentation today.
Nice quarter. If I could ask about MSG, I think that would be very helpful place to start, particularly in thinking about the growth trajectory into 2026.
What specifically changed underground at MSG during Q3 in development meters, stope availability, mining flexibility, and then what still needs to be completed before you consider the turnaround finished? Then, all-in sustaining cost for, well, very high in the quarter, like what's your latest thinking on where all-in sustaining cost can go on a run-rate basis for MSG?
Rodrigo Barbosa
I'll let Glauber to answer, but we see all-in sustaining cash cost going close to $2,000 per ounce and production at 80,000 ounces per year probably next year, right? Glauber can go in through details how he sees the progress on Q3 and project to you what can expect in Q4, and most important, next year.
Glauber Luvizotto
Yeah. The key point there is the performance in mine development, we have a combination of two things.
When we assume MSG is a backlog in mine development, in mine preparation, and we also decide to do the change in the mining method that require much more development in advance to go to the bottom of the panel and start to mine bottom-up. We still in preparation, we have some areas in production already, but not fully capacity in the underground mining.
It will take I think that 4, 5 months more to have the mine fully prepared and the reserve release in the time that is required. In parallel, a bunch of change has been made, we are improving the quality in the method that we mine, reduce dilution, increase mining recovery, and also review all the contract with significant reduction in our costs.
We can't see right now how those change will reflect, because we are not in the full capacity. I can say that we are spending more in development, proportionally with what we are producing, once we increase production, we do not will keep the same level of mine development, because once we achieve the stabilization in the mine, we can back for the fully for the normal profile of mine development, but we are being able to feed the plant with more ore from the underground, because right now almost 50% of the ore came from some lower-grade stockpiles from the surface, because we are preparing the mine, but once we are putting much more run-of-mine in the plant with better grade, the production will increase, and also we'll be able to stabilize the mine development in the underground, and the combination of those can give us the production close to the 80,000 ounces per year, and the cash cost or the all-in sustaining cost should reduce significantly.
Rodrigo Barbosa
Again, on Aura Day, we'll provide a full detail on what has been done at MSG, including all the physical measurements, the speed, how we are save the savings. Glauber mentioned having important savings that can go in few areas, 30%, 40%, so that I think it will be important invite everybody to be there and see, and we also bring the manager of MSG so that you interact directly also with him.
Lawson Winder
Yeah. Fantastic.
It's nice to see MSG improving substantially in Q3. If I could ask one more question, it would probably be on the reserve and resource update and your expectations around that globally for the entire firm, whether you anticipate replacing reserves this year mine, but then just particularly with respect to Apoena and Minosa, your two really short mine lives.
Are you starting to see the potential to drive material expansion in mine life there?
Rodrigo Barbosa
We will share what we've been finding during the Aura Day. Apoena, yes.
Now we are opening more, we are focusing a lot on the near-mine, we open a little bit 20 km, 30 km, finding very interesting interceptions that we are now finalizing all the results and be able to publish them then before the Aura Day. On the others, it's still unknown, this is where Minosa is where we are less optimistic about extending life of mine, but Apoena, yes, there will be important improvements, we believe.
Lawson Winder
Okay. That's very helpful.
Thank you, Rodrigo, and thank you, Glauber.
Operator
Our next question comes from Mr. Rabi Nizami from National Bank of Canada.
Please, Mr. Rabi, you may proceed.
Rodrigo Barbosa
Rabi, if you're talking, I think you are on mute. Maybe he has some connection problems.
Let's go to the next one, and then we will still reserve a room for him.
Operator
Our next question comes from Mr. Matheus Moreira from Bradesco BBI.
Please, Mr. Matheus, you may proceed.
Matheus Moreira
Yeah. Thank you.
Good morning, everyone. Thank you, Rodrigo and team, for taking my questions.
Two on my side. First, on CapEx, it caught our attention here that you're tracking well below your growth CapEx guidance for this year with a little bit over $130 million disbursed year-to-date, while the low range of your guidance is of $260 million, right?
I'm just wondering how should we think of this CapEx for the fourth quarter specifically. Do you still expect to reach your guidance, or should we see some spill out towards 2027?
Does this somehow impact your timeline for Era Dorada? That's my first question, and then I ask my second one.
Rodrigo Barbosa
Okay. There's nothing is going different from the schedule, but Kleber can walk you through why you see this CapEx lower than the guidance of the year so far.
Kleber Cardoso
Yeah. Matheus, we at expansion CapEx, we have opportunity to be closer to the low end of the guidance or even below.
That is mainly because and that's actually, it's good news. It's the negotiation have been done with providers of equipment, for example, for the project, we're negotiating lower down payments, so that improves our cash position at the moment.
Then, in terms of whatever we don't spend this year, to your question, yes, that would move to 2027. The CapEx for the project itself wouldn't change.
It's just a matter of having more working capital-like, let's say, not now in 2026 because of these negotiations that we're doing in country.
Matheus Moreira
Great. That that's very clear, Kleber.
Thanks thanks for that. Maybe if I may, a second quick question on MSG as actually follow-up.
It was encouraging to see the operational performance in the quarter, right, which was much better than we were expecting, still I believe far from the operational conditions Aura wants to achieve, but definitely on track. I noticed that your production improved materially quarter-on-quarter, also because of of of higher throughput rates, and this, in turn, was also benefited by some material you recovered from the East pile, right?
I'm just wondering if you could provide more details on this stockpile, how big it is, what are the average grades, and and when do you expect it to wear out. I think you also mentioned a bit in the beginning that as underground mining activities improves, you will rely less on these stockpiles, right?
Just I just wanted to get a sense on on how big and how relevant this this stockpile can be. Thank you.
Rodrigo Barbosa
Glauber, go ahead.
Glauber Luvizotto
The stockpile is not the most relevant part of the plan to recover the production, it's just to complement or to keep the plant fully feed once we weren't able to feed with more ore from the underground mine. The focus is mainly to put the mine in operation, debottleneck the mine, and get some reserves releasing in advance to make sure that we can feed the plant with run-of-mine that is the highest grade that we have, because the stockpile is a marginal ore that was left in the past for the other company.
We are using that as an opportunity once we have this spare capacity in the plant, but is not the base of the plan for the growth.
Rodrigo Barbosa
Yeah. The stockpile is just a buffer that we are using while we are doing the turnaround.
The grades, you asked, can vary: 0.5, 0.6, 0.7, 0.4, but it'll be around this.
Matheus Moreira
Great. Thank you very much, Rodrigo and Kleber.
Operator
Our next question comes from Mr. Rabi Nizami from National Bank of Canada.
Mr. Rabi, you may proceed.
Rabi Nizami
Thanks, Natacha. Can you hear me now?
Rodrigo Barbosa
Yes, loud and clear.
Rabi Nizami
Okay. Thanks, team, for taking my questions, and apologies for that audio issue earlier.
A couple of my questions have been answered, but we'll move on to a few more. On the CapEx run rate, you already answered that, but specifically looking at Era Dorada, how do you expect that the cadence of CapEx spend of that asset to proceed into Q4 and into next year?
I'll let you answer that first, and then I'll move on to the next one.
Rodrigo Barbosa
Yeah. Kleber, go ahead.
Kleber Cardoso
Sorry, Rabi. Can you repeat the question?
It was not clear to me. On
Rodrigo Barbosa
the CapEx for Era Dorada, how you expect this to increase on Q4 and then next year.
Kleber Cardoso
Yeah. On Q4, you should see a important increase, so that's normal, no?
It's if you look at Borborema and Almas was the same. The first few years and first quarters much lower, then ramping up as you start hiring people and capitalizing pre-operational expenses and also receiving the equipment.
In Q4 is expect to have a significant increase, we are expecting to move towards the low end of our expansion CapEx guidance for this year. Then for 2027, expect to spend the balance to complete the project, we're expecting to complete on budget, see if there is a save in '26, that's going to become additional CapEx in '27.
Rabi Nizami
Okay. Thank you for that.
Then, on Borborema, should we still expect an expansion study and a board decision by year-end? What's remaining there on engineering, water supply, anything else there to talk about in terms of timing?
Rodrigo Barbosa
Kleber, you want to answer? Go ahead.
Yeah.
Glauber Luvizotto
We are finalizing the study, we expect to publish to the end of this year. The main points is make sure that we have the best arrangement for the plant and how can we do the position and the expansion without impact the production that is in the run rate.
Also the water, we have some alternatives. We are just finalized the trade-offs that we have between the options and the costs of each one and the risks for each others.
We should be ready to publish it to the end of this year.
Rodrigo Barbosa
In the meanwhile, as we do with all our mines, as if you see Almas, we built, then we started generating cash, then we started doing more exploration, and now we're doing the same with Borborema. We started generating cash last year.
We start doing more investment exploration, geophysical, round drills, and there is a important and interesting information that we will share during Aura Day in Borborema ahead of the feasibility study.
Rabi Nizami
Okay. Thank you for that.
Just in the short term, looking at the strip ratio of Borborema in Q3 at 4.6, is there any guidance you can give us at this time with respect to how that evolves into Q4 and into next year? Yeah.
Glauber Luvizotto
We operate in the beginning once the mine was open when we assumed, they have the past work that they did. The strip ratio was lower, but we should run much more close to what was the Q3, but a little bit higher for next year once we should achieve the average strip ratio for the mine.
Shouldn't be that low as was in the first semester of this year, but should be close to what we have in the Q3 and what we expect for Q4 and next year forward. Okay.
Rabi Nizami
Thank you, Kleber. I'll just ask one quick one and then I'll sign off.
Kleber, you discussed FX rates a bit with your guidance being set at 5.5 and recently that's turned more in your favor. Could you just comment on fuel prices as well going forward?
How does that affect your cost and what should we think about going into Q4 and next year? With that, I'll sign off.
Thank you.
Rodrigo Barbosa
Go ahead, Kleber.
Kleber Cardoso
Yeah. Fuel is impacting us like everyone else, no, but it's not a significant portion of our costs.
It's, depending on the operation, can be between 5% or 8% of the cost matrix, it's not negligible, but it's not that high. FX, for example, Rodrigo was commenting, also the average for the year, and we's being close to R$5.10 and our guidance was R$5.50, for example, last year as well.
FX has been the main impact. Yes, we're feeling some cost pressure, but that has not been the main impact in our numbers.
Rabi Nizami
Yeah. Gotcha.
Thank you very much for taking my questions, and I'll see you at Aura Day in December. Thank you.
Operator
Our next question comes from Mr. Guilherme Nippes from XP Inc.
Guilherme Nippes
Hi, guys. Can you hear me?
Rodrigo Barbosa
Yes.
Guilherme Nippes
Yeah. Thank you for the opportunity.
I have two questions here as well. My first one is on capital allocation.
Now with the balance sheet now carrying very low leverage and, of course, there are the investments on Era Dorada, but how are you thinking about the next phase of capital allocation and potential new targets of investments? Are you guys still looking at copper and gold opportunities, or for now you're holding and seeing what happens next?
How do you see the mix of M&A and cash returns for shareholders as well? My second one is on the mining fleet insourcings.
If you guys also see other potential initiatives to reduce costs and all-in, as you already did with the mining fleet at Apoena, Almas, and Borborema. Those are my two questions.
Thank you.
Rodrigo Barbosa
In terms of M&As, we continue to see opportunities. We continue to invest time understanding what are the interesting M&As to do, invest time trying to do transactions.
M&A continue to be an important part of the story. We know very much how to get up to 600 or more thousand ounces of gold equivalent within the mines that we have or the mines that are going to develop.
We aim to be at a 1 million ounces, and that will happen only if we continue to pursue M&A, and we'll continue to see alternatives. It's gold and copper, right?
We are not looking other alternatives. Whoever invest in Aura wants to be exposed to gold and copper, and in the Americas, right?
We are not looking alternatives in Africa, Asia, or Australia. We prefer Americas, gold and copper, and examples are projects as Borborema, Era Dorada, greenfield that we can develop, or projects that are running like MSG that we see an angle to optimize operations.
Your second question was about the opportunities to reduce cost. We are always looking how to reduce the cost.
We are always looking how to improve our operations. That's one of the reasons that yet we came from a few years ago on third quartile in the industry, now we are first quartile in the industry in terms of all-in sustaining cash cost.
We do see opportunities next year, yes, for the mine insource fleeting. We are also doing a what we call a zero-based budget this year, review line by line each of the areas, and we're already finding some opportunities, but that then we will be able to include in the guidance for next year.
We see, yes, some opportunities for cost reduction along the next years.
Guilherme Nippes
Thank you, Rodrigo.
Operator
Our next question comes from Mr. Henrique Marques from Goldman Sachs.
You may proceed, Mr. Henrique.
Henrique Marques
Hi, everyone. Thank you for taking my question.
Just I wanted to understand, Rodrigo, what is your priorities as we enter 2027? I believe Era Dorada will definitely be the top one for you, but I wanted to know how do you plan to spend your time in each one of your mines?
I know each one of them has its own next stage, next phase, just wanted to understand what really is the priority for you after Era Dorada. If I may add one more question, just regarding the all-in sustaining cash cost of Apoena, it was really high this quarter, and I think it was mostly related to the Nosde CapEx, I just want to understand if this was more of a one-off or is something that we should still see for a while, and if this was already expected to happen at this moment.
Thank you.
Rodrigo Barbosa
Okay. In terms of priorities, as you mentioned, first priority is construction of Era Dorada on time, on budget, together with the turnaround of MSG, be able to produce 80,000 ounces at $2,000 all-in sustaining cash cost.
Then, of course, there's always optimizations on improvements going the operations, but I would highlight then it's continue to invest in exploration, expand the life of mine, so that we can increase resources and reserves. There's very interesting, significant potential for us to continue to do so.
Then, M&As, right? We know very much how to get to 600,000 ounces, and now we won't be able to achieve 1 million ounces.
I invest a significant part of my time prospecting and talking, understanding what would be the potential M&As to do. We don't have a target.
I want to do an M&A next year, but we do want to continue to grow through M&As, right? In the end, is the same strategy that we had 5 years ago: investing in greenfield project, increase production, to increase investing life of mine, increase resources and reserves, and continue to grow through M&A.
That's what we've been doing in the last 5 years, and as what we'll continue to do in the next 3 to 5 years. Then, you asked about all-in of Apoena.
All-in of Apoena this quarter was much higher than the last quarter, but within what we projected. What happened this quarter that we've significantly advanced at the Nosde pit while we didn't reach the high grade for the full quarter, and now we are there already, the strip ratio has mostly been done, we're going to see a higher production and higher grades coming in on the fourth quarter, we will see a reduction on the all-in sustaining cash cost for the fourth quarter.
For next year, we will put on the guidance as we have it probably in January, February.
Henrique Marques
Awesome. Thank you so much.
Operator
Our next question comes from Mr. Graham Tanaka from Tanaka Capital.
Please, Mr. Tanaka, you may proceed.
Rodrigo Barbosa
Mr. Tanaka, if you're talking, you are on mute.
I don't think we hear him, huh? Very well.
With that, I will conclude our earnings call. Just a quick wrap-up.
Aura is walking the talk. We are growing production.
We produced 95,000 ounces. This year will be on the target, 340, 390.
We are developing greenfield project. Era Dorada is moving according to the plan.
We are doing also important investment exploration that invite you again to be in Aura Day so that we can walk you through more in the details of what is going on exploration, when we continue to look alternatives for lowering all-in sustaining cash cost, which we are already in the first quartile, but we are not happy, we see opportunities to continue to decrease our all-in sustaining cash cost while we continue to see M&A. Again, thank you very much.
I didn't say an important thing, right? Doing all of that, paying dividends, significant dividends to our shareholders, 4% dividend yield together with the share buyback while we're doing all this investments in exploration, expansion, and improvements, maintaining the low net debt to EBITDA level.
Again, will be important day, Aura Day on November 30th, New York, Nasdaq. Please be able to attend there so we will be able to guide you in more detail what is going on in Aura.
I appreciate. Thank you.
Operator
Aura's conference is now closed. We thank you for your participation, and wish you a nice day.