Avient Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Good morning, ladies and gentlemen, and welcome to the Avient Corporation's webcast to discuss the company's third quarter 2026 results. My name is Kevin, and I'll be your operator today.
At this time, all participants are on a listen-only mode. We will have a question-and-answer session following the company's prepared remarks.
As a reminder, this call is being recorded for replay purposes. I would now like to turn the call over to George Clark, director of investor relations at Avient.
George Clark
Thank you, and good morning to everyone joining us on the call today. Before we begin, we would like to remind you that statements made during this webcast may be considered forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995.
Forward-looking statements will give current expectations of forecast of future events and are not guarantees of future performance. They're based on management's expectation and involve a number of business risks and uncertainties, any of which could cause actual results to differ materially from those expressed in or implied by the forward-looking statements.
We encourage you to review our most recent reports, including our 10-K, or any applicable amendments for a complete discussion of these factors and other risks that may affect our future results. During the discussion today, the company will use both GAAP and non-GAAP financial measures.
Please refer to the presentation posted in the investor relations section of the Avient website, where the company describes the non-GAAP measures and provides a reconciliation for historical non-GAAP financial measures to their most directly comparable GAAP financial measures. A replay of this call will be available on our website.
Information to access the replay is listed in today's press release, which is available at avient.com in the investor relations section. Joining me on the call today is our president and chief executive officer, Mike Frank, and Joe Di Salvo, senior vice president, chief financial officer.
I will now hand the call over to Mike to begin.
Mike Frank
Thank you, George, and good morning, everyone. I want to start by saying thank you to the global Avient team for welcoming me to the company, and to the board for their trust and support.
I'm truly honored to join Avient, and as I've gotten to know the company, my excitement for the value we can create has only grown. It really comes down to four key themes: the people, the business, innovation, and the opportunity ahead for Avient.
I'll start with the people because they are truly the core of what determines a company's success. In my brief time with Avient, I've been struck by the focus on and the passion for the customer and on innovation that permeates across the entire organization.
In addition, it's clear to me that we have a strong leadership team that's focused on the strategy and our purpose. Over the past few weeks, I've met with several of our stakeholders, including employees at both our headquarters and operating sites, customers, suppliers, and investors.
I came away impressed and excited by the opportunity that lies ahead. We are delivering today with a strategy that is working, but I also believe we have the opportunity to do even more.
Of course, I'm also excited about the business itself and the markets we serve. Avient's diverse portfolio of technologies sits at the intersection of several powerful secular trends, including healthcare, personal safety and protection, lightweighting, electronics, and others.
These trends are creating significant opportunities for innovative material solutions, and positions us well to compete and deliver sustainable organic growth over time. The world is demanding that materials do more, and innovation is the thread that connects all these opportunities.
It's one of Avient's core strengths. By combining deep technical and regulatory expertise with close customer collaboration, we are creating solutions that strengthen our market positions, expand our addressable opportunities, and generate durable growth.
It's only been three weeks, but it's clear to me that we have a strong organization, a differentiated portfolio of technologies, exposure to attractive growth markets, and a proven ability to innovate. The strategy is sound.
The disciplined execution by our operating segments is strong, and the opportunity ahead of us is significant, as evidenced by our third quarter results and updated outlook. The third quarter reflected broad-based strength across the business, with results exceeding expectations and demonstrating the continued effectiveness of the company's strategy.
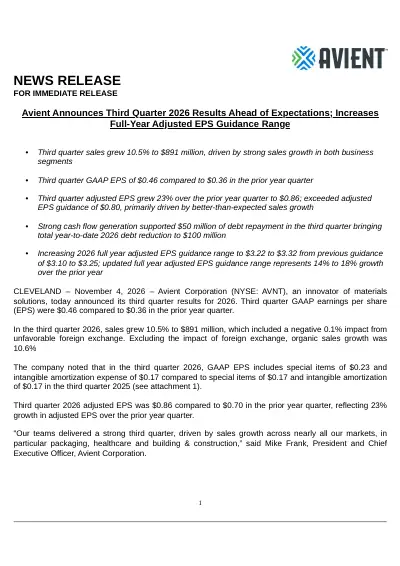
Adjusted EPS of 86 cents came in 6 cents ahead of expectations, and total company organic sales increased 10.6% year-over-year. Our focus on profitable growth, along with the benefit from productivity initiatives, increased adjusted EBITDA margins by 80 basis points over the prior year to a third quarter record of 17.3%.
Given the healthy performance through the first three quarters, we are raising our full year adjusted EPS, adjusted EBITDA, and free cash flow outlook at the midpoint, reflecting our confidence amidst ongoing macroeconomic uncertainty. Joe will cover all the details in the later slides.
From these business results, it's clear we have momentum. Before I comment on my initial impressions and opportunities, allow me to provide some context on the mandate I received from our board.
This is not a turnaround story, and the board believes our strategy is well-defined. However, they also believe we have opportunities to accelerate the growth trajectory of our business, which is core to my mandate.
Again, it's early days, but let me provide three examples of where I see opportunities to start to unlock more value. Firstly, we need to accelerate the translation of innovation into profitable growth.
We have strong innovation capabilities, and we need to find ways to scale our unique technologies across our customer base more quickly. For example, we've innovated some incredible material science solutions for a medical device company, but we're scaling it sequentially instead of simultaneously.
Secondly, our customers are looking for us to bring them solutions to the big challenges they are trying to solve. This is an opportunity to enhance how we approach market segments in a holistic manner.
I have seen some instances when we approach opportunities through the lens of a single technology, business, or individual customer. By strengthening our collaboration between our two segments, I believe we can better leverage the breadth of our portfolio.
Lastly, we have real opportunity to optimize our end-to-end supply chain. I'm taking a fresh look at our operations, including our manufacturing footprint, our product portfolio, and how we go to market.
This effort will help us optimize our cost of service and expand our opportunities for profitable growth in some of our more mature markets. Ultimately, this will not only help to boost growth, but also aid in improving margins as plant utilization increases and complexity decreases.
All of that said, we will not sacrifice the progress we've made on margin expansion to drive growth, and we are committed to maintaining our focus on productivity and cost discipline. Strong free cash flow will be a meaningful measure of success, reflecting our ability to efficiently convert earnings into cash to provide greater financial flexibility and enhancing returns.
That brings me to our capital allocation priorities. First and foremost, we will continue investing in the business to support organic growth and strengthen our competitive position.
Second, we will remain committed to returning capital to shareholders, including through our dividend. Beyond those priorities, we will take a balanced and disciplined approach to deploying excess cash, evaluating opportunities to reduce debt, repurchase shares, or pursue other value-enhancing investments.
Our objective is to allocate capital in a manner that maximizes long-term shareholder value while maintaining the financial flexibility to support future growth opportunities. As such, in the near term, the key metrics I will be focusing on will be profitable sales growth, adjusted EBITDA margins, and free cash flow.
Avient is a company with a clear purpose, a strong foundation, and strategy that's delivering results. I see opportunities to help accelerate that strategy.
I see a company with attractive positions in our core markets and growth vectors, differentiated technologies, deep customer relationships with market leaders, and a talented team that understands how to execute. My objective is to help unlock even more of that potential, increase the pace of execution, and ensure that we're fully capitalizing on the opportunities in front of us to materialize a brighter future.
With that, I will turn the call over to Joe to discuss our third quarter financial results in more detail. Go ahead, Joe.
Joe Di Salvo
Thank you, Mike, and good morning, everyone. I want to reinforce Mike's comments on our strategic framework.
Our teams bring this strategy to life every day, and it continues to deliver results. Our fundamentals are sound, and we are seeing meaningful opportunities to build on this foundation and the momentum we have.
In the third quarter, we delivered 86 cents of adjusted EPS, 6 cents ahead of expectations, driven by better-than-expected sales in the Color, Additives and Inks segment, primarily in the packaging, healthcare, and building and construction markets. Total company year-over-year organic sales growth of 10.6% during the third quarter was supported by pricing, new business wins, and robust demand for our growth vectors, which led to favorable mix and overall volume growth.
Total volume growth was approximately 1% in the quarter, with price and mix contributing the balance of the organic growth. The considerable mix benefit during the quarter was driven by growth in functional additives, such as our chemical foaming agents and barrier technologies.
Chemical foaming agents improve lightweighting while enhancing material performance in the building and construction markets, and barrier additives are primarily used in food and beverage packaging to extend shelf life. While volume growth may appear modest, we are selling more value-added, differentiated products, leading to profitable sales growth.
This and our continued focus on company-wide productivity initiatives helped expand total company adjusted EBITDA margins by 80 basis points year-over-year to 17.3%. Higher sales and margin expansion led to adjusted EBITDA growth of 16% and adjusted EPS growth of 23% over the prior year third quarter.
Healthy cash flow generation in the quarter enabled debt paydown of $50 million, further strengthening the balance sheet. As seen through the September year-to-date results shown on the right-hand side of the slide, our strategy continues to deliver tangible results.
We delivered 4% organic sales growth and 70 basis points of adjusted EBITDA margin expansion. This translated into 8% adjusted EBITDA growth and 13% adjusted EPS growth, excluding the impact of foreign currency translation.
Our momentum was broad-based this quarter, with both segments and every region contributing to growth. Shifting to our segment results.
Our Color, Additives and Inks segment delivered another strong quarter, generating 8% organic sales growth and 15% EBITDA growth, with all regions and end markets contributing. Sales growth was driven by pricing to offset inflation as well as favorable mix from demand for functional additives.
New business wins through our key accounts strategy are also delivering results in packaging and consumer applications, particularly in Asia and Latin America. In the U.S.
and Canada, building and construction grew double digits, driven by demand for applications supporting commercial infrastructure investments. Operating leverage from higher sales and productivity actions offset inflation and higher variable compensation, leading to 120 basis points of EBITDA margin expansion and EBITDA margins of 20.1% for the segment.
Our Specialty Engineered Materials segment organic sales grew 15% in the quarter, with eight out of nine end markets contributing to the year-over-year sales growth. The segment's two largest markets, defense and consumer, accounting for over one-third of the segment's sales, grew double digits in the quarter.
Demand for defense continues to be supported by increased spending by military and law enforcement agencies. Sales growth in the consumer end market is driven by new business gains and favorable year-over-year demand for recreational equipment.
Packaging and telecommunication, particularly in Asia, continue to benefit from demand for our technology used in high-performance computing and electronics, delivering double-digit growth. Applications supporting commercial infrastructure investments in building and construction, energy, and telecom also grew double digits.
I'm pleased to report that healthcare sales in the Specialty Engineered Materials segment returned to double-digit growth in the third quarter. As we highlighted in our last two earnings calls, we are experiencing some rebalancing of inventory levels by our customers, especially for drug delivery and remote monitoring devices.
While this dynamic weighed on the first-half healthcare sales, the underlying demand and secular trends supporting growth remain intact. Our teams continue to build on a solid project pipeline, working closely with leading pharmaceutical as well as medical device and equipment companies.
This broad-based demand led to the segment's strong organic sales growth of 15%. Higher sales combined with productivity initiatives resulted in EBITDA margin expansion of 140 basis points to 21.3% for the segment.
In the third quarter, every region delivered organic sales growth. Pricing actions to offset raw material inflation were a tailwind for all regions, with volume growth contributing in Asia, the U.S.
and Canada, and Latin America. Organic sales growth in EMEA was muted relative to the other regions due to weaker demand for several end markets, including consumer, industrial, and transportation.
Asia grew 20% year-over-year, following 18% growth in the second quarter, with both operating segments delivering double-digit growth. Asia continues to exemplify our strategy in action.
Our key accounts approach is enabling us to win with local customers, while our innovative technologies position us to continue to benefit from secular growth in high-performance computing and electronics. With this backdrop, I will now cover our updated financial outlook for 2026.
We are raising our full year guidance range for adjusted EPS and raising the low end of our range for adjusted EBITDA and adjusted free cash flow. We now expect adjusted EBITDA to be in the range of $593 million to $603 million, adjusted EPS to be in the range of $3.22 to $3.32, and adjusted free cash flow to be in the range of $215 million to $230 million.
Our outlook accounts for continued macroeconomic uncertainty, including demand pressures related to persistent inflation and higher interest rates. Despite these factors, we remain confident in our execution, and momentum through three quarters will enable us to deliver a strong finish to 2026.
We have also updated our full year capital expenditure outlook to approximately $120 million. At this updated level, capital expenditures are expected to be above the $107 million invested in 2025, driven by strategic growth investments.
Our healthy cash flow generation continues to support balance sheet improvement. During the third quarter, we repaid another $50 million of debt, bringing our total debt reduction over the last 18 months to $250 million.
Our expectation for net leverage is to exit 2026 in the range of 2.2 to 2.3 times, compared to 2.6 times at the end of 2025. Going forward, I expect we will take a balanced approach to deploying excess cash for further debt reduction and opportunistic share repurchases.
To that end, to date in the fourth quarter, we have repurchased 281,000 shares for approximately $10.9 million. This is the first share buyback activity since 2022 and represents a notable shift in our capital allocation strategy.
With that, we will now open the line for Q&A.
Operator
Thank you. Ladies and gentlemen, if you have a question or a comment at this time, please press star 1 1 on your telephone.
If your question has been answered or you wish to remove yourself from the queue, please press star 1 1 again. We'll pause for a moment while we compile our Q&A roster.
Our first question comes from Vincent Andrews with Morgan Stanley. Your line is open.
Vincent Andrews
Thank you, and good morning, everyone. Mike, welcome.
Thought I maybe would ask you a little bit on the new strategy. I hear you on the innovation faster to market, you want to gain share, improve the supply chain.
It kind of sounds like the classic more, better, faster approach. Maybe you could do two things.
One, could you talk a little bit about your background, which obviously leans heavy into agriculture, but you've probably done these types of things in prior roles, maybe you could bridge that to Avient for us. Then secondarily, really appreciate the KPIs you're going to follow, but maybe you can give us a little bit of a sense of the speed at which you think you can impact those KPIs, is it 2027, is it 2028, where we will really see an inflection.
If you're not 100% sure on the timing yet because it's early days, maybe you could give us a sense of the signposts ahead that you'll be providing. Thank you.
Mike Frank
Sure. Good morning, Vincent, and thank you for the question, and good to reconnect.
Firstly, on my background, Vincent, as you mentioned, I've got deep agricultural experience, but I think, clearly, there's a learning curve here at Avient in terms of our products and our customers. I think at the core of our business, there's a lot of familiar themes.
What we need to do better than our competition is we need to serve our customers and create more value, and we're doing that through differentiated solutions. We're driving, and we need to continue to drive, higher operational excellence.
That's been core to my background. Lastly, and as important as the first two, we need to ensure that we have a highly energized and efficient organization that's really aligned and focused on the strategy.
Those are the things that I've done in my past, and that's what I'll be doing here at Avient. As we said in our prepared remarks, we have momentum, and the strategy is set, but I'd also say it's early innings in the strategy, we still have more work to do to align the organization, align our resources, to ensure that we can implement with speed against that strategy.
Again, I gave a couple of examples in terms of how we approach our customers. I think we have more opportunity to do more cross-selling and accelerate the pace at which our innovation is being felt in the marketplace.
On the KPIs, again, we talked about margins, organic growth, and free cash flow. Those will be the three things that we're really focusing on.
I think on margins, obviously, there's a lot of levers that we're going to pull there. I think we've demonstrated this year that the price strategy that we've led and got ahead of our inflationary costs has been very effective, and I think that's one of the strengths of Avient.
I also think we need to really unlock volume growth opportunities in addition to pricing. As Joe mentioned in his comments, Europe in particular has been muted in terms of our results there and our volume.
That's an opportunity to really reassess how do we get back to volume growth in Europe and more globally. Then finally, on free cash flow, obviously, as Joe mentioned, we're going to continue to delever the balance sheet.
As we do that, we have more strategic opportunities to think about how we deploy capital, but we're going to continue to really focus on generating free cash flow to give us those strategic options going forward. In terms of the speed at which I think you're going to see the impact, look, we'll have more to say on that, Vincent, when we come to our Q4 earnings in February and talk about our FY '27 operating plan and guidance at that time.
Vincent Andrews
Thank you.
Operator
One moment for our next question. Our next question comes from Mike Harrison with Seaport Research Partners.
Your line is open.
Mike Harrison
Hi, good morning, and welcome aboard, Mike. Wanted to dig in a little bit on the healthcare strength.
You mentioned that you were still maybe seeing some inventory rebalancing in that drug delivery space, but maybe just a little bit more color on how you're seeing healthcare trends, I guess, play out to finish this year and how you're seeing that growth opportunity in healthcare into next year.
Mike Frank
Thank you, Mike, and thanks for the welcome. Let me start with a comment, and I'm going to pass it to Joe to maybe peel the onion back a little bit further.
Obviously, healthcare is one of our growth vectors, and we saw another good quarter in healthcare. There is some components of that in terms of the injectable pens where we're seeing some inventory rebalancing.
Broader than that, we have a number of plays with our technology across healthcare, both in CAI and in our SEM business units. We are seeing a strong growth, even though there was some inventory rebalancing.
I'll pass it to Joe to make some comments as well.
Joe Di Salvo
Thanks, Mike. Mike, if you look back at our healthcare business, it reflects about 8% of sales in both segments, it's similar in both segments and how it contributes to the overall end-market exposure.
If you look back at the last two years, our healthcare sales have been up double digits back-to-back years, and so that's a pretty good testament to what we see in terms of the long-term growth trajectory of that end market. We have really deep customer relationships with the leaders in this space.
These are long-term, sticky relationships. We have differentiated capabilities.
We have certain certifications at our facilities that allow us to participate in this end market. As we said, we had a little bit of a slow start to the first half of the year due to the inventory rebalancing and some of the things that I mentioned in my prepared remarks as well as what Mike said, but long-term, this will be a growth vector for us, and this will contribute to growth in both segments.
Mike Harrison
All right. Thanks for that.
You noted the kind of modest share repurchase in the quarter. The balance sheet's getting to a point where we can start thinking about some more meaningful capital deployment.
It sounds like near-term you're going to be balancing between share repurchase and debt paydown, but maybe a good time to ask Mike how M&A might fit into the capital deployment strategy from here.
Mike Frank
Thanks, Mike. Look, we're going to continue to be very disciplined, as we said in our capital allocation approach.
We're going to fund maintenance capex and dividends, that'll be our priority. I think, in terms of other strategic opportunities, whether they be M&A, growth capex, share buybacks, those will compete for capital.
As we continue to delever, we'll have more and more optionality in terms of how we think about those specific options. Obviously, we did some share buybacks as we started this quarter, and so that's also an option that we're looking at in terms of how we deploy capital.
Joe, you may want to say a few other things there.
Joe Di Salvo
Yeah. Mike, if you look back at the last couple of years, this year included, we're generating a little over $200 million of free cash flow, so that's our operating cash flow less our capital expenditures.
With over $200 million of free cash flow, we need about $100 million a year to fund and sustain our dividend, which we're committed to. Then that leaves excess cash of $100 million at least a year where we can take a more balanced approach now that our balance sheet's in a stronger position, and maybe pay down some debt as well as do opportunistic share repurchases.
Just given where interest rates are going and they're likely to be higher, that I think we need to continue to be balanced in that. We've paid down $250 million of debt in the last 18 months, and so as I look ahead at the next 12 to 18 months, I would say that we would still consider paying down debt, but also look at opportunistic times to buy back our shares where we feel that the value is well below the intrinsic value of the company.
Operator
Thank you. One moment for our next question.
Our next question comes from Laurence Alexander with Jefferies. Your line is open.
Dan Rizzo
Hey, it's Dan Rizzo on for Laurence. You mentioned scaling faster and some of the changes you're going to make.
Over the last few years, have you lost opportunities because you didn't scale fast enough or you didn't meet client needs fast enough, and that's something that needs to be corrected?
Mike Frank
Thanks, Dan. Look, I don't think this is a correction.
This is about how can we accelerate. As you can see in our results, we had very strong results year-to-date and again in Q3.
I don't see this as a correction. I see this really as an opportunity to accelerate.
How do we take our innovation and scale it, as we bring it to one customer, scale it to multiple customers at the same time? I think as we really focus on that being our objective, I do think we can scale our innovation faster.
Dan Rizzo
I guess with that in mind, I guess how bespoke are some of your products? Are there products that are only specifically for one customer, or is it a little broader than that, and something you can work on?
I just was wondering how tailored they are, and how you can kind of overcome that.
Mike Frank
Again, and this gives us stickiness. I would say our products, especially in the CAI business, but also in parts of our SEM business, are highly tailored to the customer needs.
As Joe said, in some markets like healthcare, we're also specked in to those end uses, and so that creates a lot of stickiness. We work very closely.
Our technology teams work very closely with our sales teams at the customer, when their design teams are thinking about innovation for their products that they're selling, we're working with them shoulder to shoulder. We're very embedded with our customers from a technology standpoint, and creating solutions that are quite unique to their end use.
Dan Rizzo
All right. Thank you very much.
Operator
One moment for our next question. Our next question comes from Frank Mitsch with Fermium Research.
Your line is open.
Hi, guys. Good morning.
It's Aziza on for Frank. I also wanted to say welcome, Mike.
We look forward to working with you in this role. My first question was around price versus raws in 3Q.
Can you elaborate further on what you saw there and maybe provide some outlook for 4Q?
Joe Di Salvo
Hey, Aziza. This is Joe.
From a raw material inflation, for the full year, we're probably expecting about mid-single-digit inflation on the total basket of raw materials. Most of that is coming from the hydrocarbon raw materials, as you'd expect, which account for about 35% of our raw material purchases.
Our business model allows us to price contemporaneously, and so we've done a really nice job this year of pricing in line with raws, and so we've been able to offset that increase, and you see that coming through as part of our sales growth, part of that is related to pricing.
Got it. And 3Q saw that pickup in corporate expense.
Can you maybe elaborate further there and give us a guidepost for 4Q on that?
Joe Di Salvo
I think that's probably if you're looking year-over-year, we are up due to our variable compensation, which we talked about at the beginning of the year when we set our guidance. We were expecting about $30 to $35 million of a variable compensation headwind coming into this year.
As you've seen, we've been able to raise our guidance the last couple of quarters, and so the business is performing well, and we're well on track for a little better variable comp payout this year, certainly better than last year. A portion of that $35 million or so, $30 to $35 million is showing up in corporate, and that's the driver of some of that.
Got it. Thanks, guys.
Joe Di Salvo
Thank you.
Operator
One moment for our next question. Our next question comes from Ghansham Panjabi with Baird.
Your line is open.
Ghansham Panjabi
Thank you. Good morning, everybody, and I'll echo Mike, congratulations to you as well, Mike.
Best wishes in your new role. I guess going back to your prepared comments and the comment you made about accelerating growth as part of your mandate by the board for you, which is also one of the most difficult things for any company to do, especially in our coverage.
What do you think it would entail from a change perspective, either internally or through acquired capabilities? What is a realistic timeline as relates to actually seeing that manifest in terms of incremental sales growth?
Thank you.
Mike Frank
Thanks for the question. Look, as we talk about, our company sits at the intersection of several secular trends, and so that in of itself gives us an opportunity to really think about how do we play in those trends.
I think our strategy is quite clear as to how we think about both our core business and our growth vectors. Now, I also believe that, again, we're in the early innings of implementing our strategy, we haven't aligned all of our resources against that strategy in and of itself.
I do believe we still have opportunities to really get our organization really hyper-focused on the growth vectors, get it more leaned out across our core business. As we do that, I think we can expand our margins in the core business, be even more competitive so we can drive both price and volume, and then accelerate our opportunity in the growth vectors.
That's what the plan's going to be, and again, I think some of this has been in the works, but I do think we can now move forward even more aggressively. Again, on the timing of that, look, I think, these growth vectors, we believe are going to play out over the next several years.
We'll have more to say on that, I think as we get into our Q4 earnings. It'd be too early for me to comment specifically in terms of how to think about that in '27 and beyond.
Ghansham Panjabi
Understood. Then, Joe, I may have missed this answer to the last question, but did you break out specifically what volumes were by segment during the third quarter?
I'm just trying to get a sense as to whether the underlying demand patterns have changed in any way, and are you cycling through easier comparisons for both segments as well? Thank you.
Joe Di Salvo
Gotcha. I didn't break out the segment.
I talked about the total company. The third quarter was really in line with the second quarter, about 1% overall volume growth contributed to the sales growth.
In the third quarter, the Engineered Materials segment grew around 3%, and the Color business was slightly down, just about 1%. That's really driven due to the greater exposure to Europe, which we talked about there being a little more muted demand there.
The volume growth in Europe was what challenged the Color segment, and absent that, I think the Color segment would have had a little bit of growth in the quarter as well. Overall, about 1%, SEM grew, and Color was flatish to slightly down due to Europe.
Ghansham Panjabi
Perfect. Thank you so much.
Joe Di Salvo
Thank you.
Operator
One moment for our next question. Our next question comes from Pete Osterland with Truist Securities.
Your line is open.
Pete Osterland
Hey, good morning, Mike and Joe. Thanks for taking the questions.
First, Mike, on the opportunities you walked through, just wanted to ask about the potential to optimize your supply chain and manufacturing footprint. Could you just characterize what the major sources of increased efficiency could be, and what do you expect this to look like at this point?
Is this more targeting gradual, continuous improvement, or are you contemplating potentially implementing a larger, more broad-based restructuring program?
Mike Frank
Good morning, Pete, and yeah, thanks for the question. Look, I would say, we're taking a fresh look at our footprint in particular.
We've got a broad footprint, and one of the strengths, obviously, we're close to our customers, and we're going to continue to have a footprint geographically that serves our local customers in each of our regions. That is important in our business, and we'll continue to have a supply chain that reflects that.
That being said, we do have a lot of plants, and the team has been looking at that, I know, over the past several years, and there's been some progress on that, but I do think that we will look at opportunities to potentially accelerate that, again, consistent with our overall strategy. Again, it'd be too early to talk about or announce any kind of restructuring program, but that'll be one piece.
I would say the second piece is, and this is probably across the entire supply chain, but also within the growth vectors, is, I think there's opportunities in procurement to really leverage our global procurement scale and using tools and technologies, including AI, to really get even more dialed into the opportunities to create savings across our procurement opportunity. Those are a couple of examples of where I believe that there's a step-change opportunity for us in terms of leaning out our supply chain.
Pete Osterland
Very helpful. Thank you.
Then just as a follow-up, I wanted to ask on the bifurcation of the business between kind of a GDP-plus growth and the growth platforms where you're targeting the double-digit growth CAGR. Could you just update us what percent of current revenue sits in what you define as the faster growth platforms, and maybe within that basket, where do you see the strongest growth opportunities ahead over call it the next 12 to 18 months?
Mike Frank
Yeah. We are seeing, obviously, our growth vectors growing at a faster rate.
We think this year they're going to be in the high single digits, really close to double digit. Our core business will be in that GDP-plus range, and so that's exactly how it's playing out this year, and that's what we would expect going forward.
The size of our growth vectors is in the range of $600 million, and so that helps you size in terms of as that business continues to grow in that close to double-digit, high-single-digit range, what kind of leverage we have there. Obviously, as that flywheel gets bigger, then that should help our overall growth as well.
Joe, do you want to make some further comments?
Joe Di Salvo
No, I think you summarized it well. It's been the story the last couple of years, Pete, as you look back at this kind of low-growth, choppy macro environment.
The growth vectors have carried the day, and it's contributed to our ability to grow revenues, at least modestly, over the last couple of years, but it's also contributed to our margin expansion and how we've benefited from favorable mix from growing in these higher-value, higher-margin parts of the business.
Pete Osterland
Great. Thanks a lot.
Mike Frank
Thank you, Pete.
Operator
One moment for our next question. Our next question comes from Alexei Yefremov with Barclays.
Your line is open.
Hey, thanks, and good morning, everyone. This is Ryan Weisen on for Alexei.
First, Mike, just want to echo my congratulations on the new role and looking forward to working together. Joe, I guess question for you.
Can you kind of give us a walkthrough, maybe growth kind of by end market, just in 3Q? Then, I appreciate that it's still early, and there's a lot of uncertainty in the market, but are there markets in which you feel confident about growing volume next year, or maybe areas that you have slightly easier comps and you should see some form of growth?
Appreciate any color. Thanks.
Joe Di Salvo
Sure. Thanks, Ryan.
For the third quarter, pretty much every end market grew. We track nine end markets.
That's what we include in our materials. If you look at all those nine end markets, other than transportation, every end market grew.
Transportation was kind of flatish in the quarter, and that's really just driven by global auto builds, particularly in Asia, have been just down a little bit and slower than what it's been the last couple of years. I think as I think about the end markets into next year, it's going to be a similar story that we've seen the last couple of years, where areas like healthcare, our defense business, those two areas continue to have robust pipeline.
We've talked a lot about high-performance computing, electronics, and that shows up, really primarily in Asia, but primarily in the two end markets of packaging and telecommunications. We continue to see a strong pipeline and demand there.
Then if I look at our packaging, which is our largest end market, I think we'll continue to see solid, stable demand there, just with our functional additives and barrier additives that we supply into that market. Those are the areas that I would expect to be stable to continue to show growth into 2027.
Awesome. Thanks.
Then just a follow-up for me. You guys talk a lot about electronics and high-performance computing and how you're seeing fast growth in Asia.
I think there is some kind of embedded between different end markets, maybe kind of the way you guys describe them, right? I think some shows up in packaging, and you guys are talking about wins there.
Is that primarily within semi, or is that different areas, just if you could kind of help us size where the business kind of sits and where the share gains are coming? Thanks.
Joe Di Salvo
It primarily sits in the Engineered Materials business, and primarily shows up in the telecom end market and the packaging end market. We're providing materials that go into semiconductor, wafer handling and chip handling for semiconductor fabs, as well as high-speed connectors and components that go into data centers.
Then we also have some wire and cable that also can end up in data centers.
Operator
Thank you. One moment for our next question.
Our next question comes from Abigail Eberts with Wells Fargo. Your line is open.
Abigail Eberts
Hi. Thanks for taking my question, and welcome, Mike.
Following up on your commentary about building and construction coming from commercial infrastructure investment, can you just give us a feel for what end markets or sectors that's coming from? Is that from data center infrastructure investment or something else?
Thanks.
Joe Di Salvo
Hey, Abigail. The commercial infrastructure is really showing up in building and construction, it's a combination of the Color business and Engineered Materials.
We have chemical foaming agents that are going into lightweighting and materials that are used in building construction there. Then also our wire and cable business that's going into the infrastructure spend and build-out that's happening there, which shows up in both segments.
Abigail Eberts
Got it. Thanks.
Operator
One moment for our next question. Our last question comes from David Begleiter with Deutsche Bank.
Your line is open.
David Begleiter
Thank you. Welcome, Mike.
Mike, back on innovation to accelerate, do you need more people? Do they need more tools and training?
Do you need different people? Do you need outside help?
Any color on how some of the mechanics of that could work? Thank you.
Mike Frank
Good morning, David. Thank you.
No, look, I don't think we need more people. From an innovation and R&D standpoint, we've got strong investment in both people and technology.
I think it's really about how do we get even more focused. We have a number of growth vectors.
I think sometimes we have some competition across our business units in terms of how to tackle a problem. I think we can synergize and say, how do we bring our technologies best as Avient to solve our customers' solutions, and not necessarily through the eyes of our business segments, but through the eyes of our customers?
I do think it's a bit of a process thing, and then it's getting even more clear on where are we making investments, and where are we making some small bets, but also where are we making some bigger bets. I do think we're having a fresh look at that, and I do believe that that's going to create some opportunity for us.
David Begleiter
Good. Thank you for that.
Just on M&A, Mike, do you need to rebuild the M&A muscle at Avient? Rebuild a target list of potentials?
Before you can begin actually doing M&A, is that part of the process? If so, how long will that take, and has that begun?
Thank you.
Mike Frank
Yeah. I think, David, that you're right.
We've been focused over the last several years on delevering. I wouldn't expect any meaningful M&A in the near term.
Again, as we think about capital allocation, M&A is an opportunity that we do think lies ahead of us, but it's going to compete for other opportunities for capital. I think you framed it well.
We do need to rebuild that muscle. We'll do that in time.
I think we still have opportunity to delever even further. We've got really good uses of capital here in the near term.
M&A will come into a clearer focus, I would say, in the near term, but not immediately.
David Begleiter
Thank you.
Mike Frank
Thank you, David.
Operator
I'm not showing any further questions at this time, and as such, this does conclude today's presentation. We thank you for your participation.
You may now disconnect and have a wonderful day.