BrightSpire Capital, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Good day, and welcome to the BrightSpire Capital, Inc. Third Quarter 2026 Earnings Conference Call.
All participants will be in listen-only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero.
After today's presentation, there will be an opportunity to ask questions. To ask a question, you may press star then one on your touch-tone phone.
To withdraw your question, please press star then two. Please note, this event is being recorded.
I would now like to turn the conference over to David Palamé, General Counsel. Please go ahead.
David Palamé
Good morning, and welcome to BrightSpire Capital's third quarter 2026 earnings conference call. We will refer to BrightSpire Capital as BrightSpire, BRSP, or the company throughout this call.
Speaking on the call today are the company's Chief Executive Officer Michael Mazzei, President and Chief Operating Officer Andrew Witt, and Chief Financial Officer Frank Saracino. Before I hand the call over, please note that on this call, certain information presented contains forward-looking statements.
These statements, which are based on management's current expectations, are subject to risks, uncertainties, and assumptions. Potential risks and uncertainties could cause the company's business and financial results to differ materially.
For a discussion of the risks that could affect results, please see the Risk Factors section of our most recent 10-K and other risk factors and forward-looking statements in the company's current and periodic reports filed with the SEC from time to time. All information discussed on this call is as of today, October 28th, 2026, and the company does not intend and undertakes no duty to update for future events or circumstances.
In addition, certain financial information presented on this call represents non-GAAP financial measures. The company's earnings release and supplemental presentation, which was released yesterday afternoon and is available on the company's website, presents reconciliations to the appropriate GAAP measures and an explanation of why the company believes such non-GAAP financial measures are useful to investors.
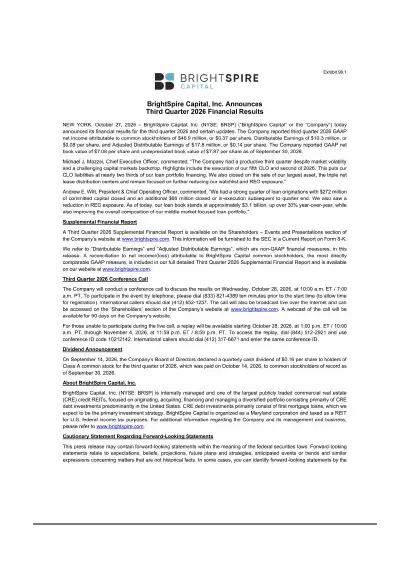
Before I turn the call over to Michael, I will provide a brief recap on our results. The company reported third quarter GAAP net income attributable to common stockholders of $46.9 million or 37 cents per share, distributable earnings of $10.3 million or 8 cents per share, and adjusted distributable earnings of $17.8 million or 14 cents per share.
The company also reported GAAP net book value of $7.08 per share and undepreciated book value of $7.87 per share as of September 30th, 2026. Finally, during this call, management may refer to distributable earnings as DE.
With that, I would now like to turn the call over to Michael.
Michael Mazzei
Thanks, David. Welcome to our third quarter 2026 earnings call.
We are pleased with our performance this quarter, especially given the tremendous volatility in the capital markets. Despite that backdrop, we continue to execute across multiple areas of the business.
Before turning to our third quarter activity, I would like to spend time on the capital markets. During the quarter and through today, we experienced significant volatility in the rates market.
The 10-year Treasury peaked at 5.37%, which at the time marked a 25-year high and represented nearly a 100 basis point move since June 30th. The volatility then reversed direction, with yields falling sharply back below 5%, following a one-day, 20 basis point rally last Friday.
At the same time, the bond vigilantes were joined in their revolt by the credit market investors, as spreads widened across corporate bonds, term loans, and structured products. Also, it is less typical for credit spreads to widen alongside rising interest rates.
That dynamic reflects heightened concerns around the endless financing requirements of the hyperscalers. In addition, there are growing doubts regarding the return on investment for the trillions being spent on AI build-out.
As a result, there is greater focus on the most vulnerable credits in the AI ecosystem, especially given the codependent nature of these counterparties. This is most evident in the yield levels where certain AI-related debt is currently trading.
These dynamics have caused capital market investors to take pause and lean toward a more wait-and-see, risk-off posture. We have seen some of this bleed into the commercial real estate markets, where investment sales transactions have been repriced or simply pulled from the market.
On the CRE debt side, CLO AAAs and bank warehouse repo spreads widened about 10 to 15 basis points, prompting lenders to briefly tap the brakes as well. With that as context, valuations across the public commercial mortgage REIT sector have come under considerable pressure over the past several months, with BrightSpire, along with our public peers, trading at deep discounts to book value.
We have repurchased stock over the past several quarters, including approximately 2.1 million shares during the third quarter. We, of course, recognize that our stock presents an even more compelling opportunity at these current price levels.
However, where public mortgage REITs are trading today reinforces the importance of maintaining market and lender confidence in the strength and durability of our balance sheet. Periods like this, we believe cash liquidity becomes the single most important asset of a mortgage REIT.
That said, we anticipate our liquidity levels may continue to increase over the coming months. A short-term pullback in demand for acquisition financing, coupled with permitting our near-term liquidity to build, could result in slower growth in the loan book than we have experienced in recent quarters.
This may extend our timeline for full deployment, and in turn, a delay in reaching positive dividend coverage. However, we believe in maintaining balance sheet strength and liquidity is the right near-term priority given the current environment.
Now turning to the third quarter, let me highlight a few key developments. First, we had another solid quarter of originations, totaling $272 million.
We continue to positively reshape the portfolio with smaller average loan sizes, greater diversification, and continued greater weighting toward multifamily loans. We also will continue to be deliberate in avoiding large loan concentrations.
As such, in the coming quarters, we expect our loan office exposure and pre-2024 loans will continue to shrink both on a relative and absolute basis. Second, we closed on the sale of our Albertsons triple net investment.
This sale was agreed to when the 10-year Treasury was at 4.42%. Given the subsequent move in rates, it proved a substantially more favorable result for BrightSpire than when it was first announced.
Importantly, it removed a risk of material ROE dilution at refinancing and was sold at only 2% below undepreciated book value. Third, we completed our fifth CLO, which was our second issuance this year.
As a result, approximately two-thirds of our loan book is now in the form of non-recourse, non-mark-to-market CLO liabilities. Completing two CLOs this year is an important validation of our origination and financing capabilities.
This recent CLO includes a $100 million ramp and a 30-month reinvestment window. These features allow us to continue to actively originate new loans while also preserving near-term liquidity.
Furthermore, as a reminder, BrightSpire has avoided employing additional leverage in our capital base. Specifically, we have no preferred stock and no term loan.
Taken together, our third quarter activity builds on the progress we've made year-to-date and demonstrates our continued ability to recycle capital, identify attractive lending opportunities, and thus improve the loan portfolio and strengthen the balance sheet. In closing, we made meaningful progress this quarter, continuing to execute despite a more challenging market environment.
Looking ahead, our focus is on opportunistically deploying our CLO ramp and reinvestment capacity, while maintaining momentum on watch list and REO assets. As we pursue these priorities, we will continue to take our cues from the market.
While the Treasury market appears to have calmed over the past week, it may be because of a flight to quality due to growing concerns in the AI credit markets. In the near term, we will remain disciplined, continue to strengthen our liquidity position, and first and foremost, protect the balance sheet.
As an internally managed company, our interests are aligned with those of our shareholders and lenders. Our leadership team continues to be fully invested alongside our shareholders.
With that, I would like to now turn the call over to our President, Andrew Witt. Andrew?
Andrew Witt
Thank you, Michael. Our third quarter results reflect continued progress across all areas of the business.
As Michael highlighted, BrightSpire's originations activity have been healthy over the past several quarters, driving net loan portfolio growth of over $700 million or 30% year-over-year to $3.1 billion. Importantly, that growth continues to enhance the composition of the portfolio.
The loan portfolio is now 72% multifamily, and with the completion of our second CLO this year, approximately two-thirds is financed with non-recourse, non-mark-to-market financing. The past year was highlighted by significant loan portfolio growth.
However, we expect our loan portfolio growth to moderate in the near term. While our pipeline continues to be robust, we anticipate the current interest rate volatility, the upcoming elections, and seasonality will contribute to moderated transaction activity, a dynamic that is already beginning to emerge in real time.
Looking more closely at our lending activity, we originated seven loans with an aggregate total commitment of $272 million. Repayments totaled $79 million across four positions.
As of quarter end, the loan portfolio is comprised of 111 loans with an aggregate loan balance of approximately $3.1 billion, a net increase of nearly $200 million quarter-over-quarter. The average loan balance across the entire portfolio is $28 million, comfortably within our target range, with a weighted average risk ranking of 3.1.
We continue to make progress resolving REO properties. During the quarter, we closed on the sale of one Mesa, Arizona multifamily REO, and the Fort Worth, Texas multifamily property closed yesterday, further reducing our REO exposure.
We have also initiated a marketing process for our Santa Clara, California REO land asset. Despite the rise in rates, given the strength of the market and the asset, we believe the property will be well received by the market given the substantial demand for housing and favorable market dynamics we're observing in the Bay Area.
Additionally, we anticipate bringing two remaining multifamily REO properties to market in the relatively near term. Our goal is to continue reducing REO exposure, ultimately reducing this segment of the portfolio to the San Jose hotel property, which we also anticipate to market at some point in 2027.
In the interim, as it relates to the hotel, we are making progress on our business plan, addressing deferred maintenance and improving operating performance in anticipation of taking the property to market. As it relates to our watch list loans, we resolved a Denver, Colorado office property during the quarter.
Additionally, we are actively working with borrowers on several assets to evaluate potential exit opportunities while remaining focused on protecting value. Specifically, both the Austin, Texas and Las Vegas, Nevada multifamily loans, as well as the Dallas office loan, have been repositioned and reached stabilized occupancy, positioning them for resolution in the near term.
During the quarter, we downgraded two related office loans to the watch list as risk-rated 4s. The loans are secured by properties within the same complex and have one common borrower.
We expect to have greater clarity on the ultimate resolution of these investments in the coming months. Additional details on REO and watch list loans can be found in the supplement.
Ultimately, our efforts on the REO and watch list segments of the portfolio are focused on reducing exposure that contributes to the difference between book and market value. Reducing REO and watch list exposure should reduce uncertainty and improve the profile of the portfolio.
We believe these are important elements of long-term value creation. Our business plan is straightforward: maintain prudent levels of liquidity, reduce REO and watch list exposure, removing uncertainty in the portfolio.
Over the next few quarters, we will also continue to reduce office exposure. To that end, the property underlying our largest office loan recently went under contract.
As we make further headway across these areas of the portfolio, the focus will naturally shift towards our diversified portfolio of middle-market loans generating current cash flow, supported by our internally managed and vertically integrated platform. In summary, we made substantive progress during the quarter and remain focused on building that momentum across the business.
Looking ahead, our short-term priority will be on maintaining sufficient liquidity and balance sheet management given market volatility, while deploying our CLO ramp proceeds into new investments, and in parallel, addressing watch list and REO assets. With that, I will turn the call over to Frank Saracino, our Chief Financial Officer.
Frank?
Frank Saracino
Thank you, Andrew, and good morning, everyone. For the third quarter, we generated adjusted DE of $17.8 million or 14 cents per share.
Third quarter DE was $10.3 million or 8 cents per share, which includes specific reserves of approximately $7.5 million. Additionally, we reported total company GAAP net income of $46.9 million or 37 cents per share.
GAAP net income reflects a $60.3 million gain on the sale of our Albertsons triple net lease portfolio and approximately $6 million in operating real estate impairment related to a legacy retail triple net investment and the sale of two REO multifamily properties. As Michael highlighted, during the quarter, we closed on the sale of the Albertsons triple net lease investment.
Based on that sales proceeds, we recorded a GAAP gain of approximately $60.3 million and an approximate $8.7 million reduction to undepreciated book value. Regarding the retail triple net lease investment, earlier this year, we received notice of default on mortgage notes payable cross-collateralized by five retail properties.
In August 2026, a receiver was appointed and took possession and full control of one triple net lease Kansas retail property, requiring deconsolidation of the related assets and liabilities from the company's consolidated balance sheet. This resulted in our recording a $3.4 million operating real estate impairment charge in the third quarter.
Importantly, this GAAP impairment charge had an immaterial impact on our undepreciated book value, as we had written down this investment over two years ago. Post the deconsolidation of the Kansas triple net, there are two remaining cross-collateralized retail triple net investments.
Next, as Andrew mentioned, we closed on the sale of one Mesa, Arizona multifamily property and one Fort Worth, Texas multifamily property. Based on the net sales proceeds of both, we recorded GAAP impairment charges of approximately $2.6 million and an approximate $7.2 million reduction to undepreciated book value.
Turning to book value, quarter-over-quarter, undepreciated book value decreased to $7.87 from $8.10. The change is mainly attributable to an increase in our CECL reserves and real estate impairments discussed earlier, offset by share repurchases.
Total company GAAP net book value increased to $7.08 per share from $6.81 in the second quarter. On a net basis, this was driven by the gain on the sale of the Albertsons investment and share repurchases, offset by the increase in CECL reserves and real estate impairments.
Looking at CECL reserves, during the third quarter, we recorded and charged off specific CECL reserves of approximately $7.5 million resulting from the resolution of a risk rank 4 Denver, Colorado office loan. Our general CECL provision increased to $107 million or 332 basis points on total loan commitments, compared to $100 million or 327 basis points reported in the second quarter.
The increase was driven by macroeconomic conditions, originations activity, and other model inputs. As Michael highlighted, during the third quarter, we repurchased 2.1 million shares for approximately $10 million at an average share price of $4.81.
This resulted in a 6 cent increase to the company's undepreciated book value per share. Following this activity, we have approximately $20.5 million remaining under our stock repurchase program.
Our debt-to-assets ratio is 70% and our debt-to-equity ratio is 2.7 times. Finally, our liquidity as of today stands at approximately $181 million.
This includes $106 million of cash on hand and $75 million under our credit facility. This concludes our prepared remarks, and with that, let's open it up for questions.
Operator?
Operator
Thank you. We will now begin the question-and-answer session.
To ask a question, you may press star then one on your telephone keypad. If you are using a speakerphone, please pick up your handset before pressing the keys.
To withdraw your question, please press star then two. We ask that you please limit yourself to one question and one follow-up.
If you have additional questions, you may re-enter the question queue. At this time, we will pause momentarily to assemble our roster.
The first question will be from Gabe Poggi from Raymond James. Please go ahead.
Gabe Poggi
Hey, good morning, guys. Thanks for taking the question.
Michael and team, just at a high level, obviously the world is a much different place today than it was 60, 90-odd days ago. Can you talk about how you're viewing pending loan maturities this quarter or just in the first half of next year amidst varying rate constructs, conversations with borrowers, any conversations or color you can provide would be helpful.
Thank you.
Michael Mazzei
We're going to direct that to Andrew and maybe Matt Heslin. Andrew, you want to lead off with that?
Andrew Witt
Yes. Good morning, Gabe.
As it relates to 2021 and '22 maturities, as part of our proactive asset management process, we're always talking to borrowers well ahead of maturities, and having an in-house asset management group gives us the ability to have direct dialogue with our borrowers. As it relates to the upcoming quarter, we've got about $275 million worth of final maturities.
65% of that is listed for sale right now. We have one additional property from our watch list, which we expect to list in the short term, the Dallas office loan, which brings that number to about 80%.
Michael Mazzei
I don't know if Andrew cut out. Andrew, are you there?
We lost Andy. I think we lost Andrew.
Matt—
Andrew Witt
Hello?
Michael Mazzei
Yep, Andrew, I'm sorry, we lost you for a second. Pardon me.
Andrew Witt
Where did I cut out? We lost you at 80%.
Gabe Poggi
80%.
Andrew Witt
Yes, great, thank you. So 80% with the inclusion of the Dallas office loan, which is on our watch list, which we anticipate will go to market here momentarily.
Then the remainder has been extended. That's really the cadence in which we expect to proceed as we move through the subsequent quarters.
Again, we're having dialogue with borrowers no less than 120 days out, addressing these maturities in a very proactive fashion.
Gabe Poggi
Got it, that's great to hear. Then one follow-up, if I can.
Michael, you talked about being opportunistic, not in a rush to do anything necessarily, as you kind of wait and watch and see how the world shakes out. As you're having conversations on the new origination front, right, you guys have stayed active every quarter on the new origination front, the book's gotten to north of $3 billion.
Are you looking outside of multifamily? Are there other interesting opportunities that you're seeing from a spread perspective, just any incremental color you can give on new lending opportunities would be helpful.
Thank you.
Michael Mazzei
We have Dan Katz, who runs our origination team in LA, on the wire as well. Dan, do you want to take the lead on that question?
Dan Katz
Sure, I'm happy to, thank you. Top of the funnel for us has been multi, it's been about 60%.
When you kind of look at the opportunity set, a lot of it's has been in multi and will likely continue to be. That being said, we're looking at industrial, we're looking at hospitality, we've been looking at retail.
We did a handful of industrial deals this year, we did one hospitality deal earlier this year, we are spending time in the other asset classes as well. Spreads are in the mid-2s right now for us on multi, industrial kind of seems to be in the same spot, and then retail and hospitality a little wider, kind of in the 300s.
We are spending time in all those asset classes, it's just that the bulk of what's coming in is still predominantly multi.
Gabe Poggi
Thanks, guys.
Michael Mazzei
Thank you, Gabe.
Operator
Thank you. The next question will come from Tom Catherwood from BTIG.
Please go ahead.
Tom Catherwood
Thanks. Good morning, everybody.
Michael, I want to go back to your opening remarks on the capital markets environment. It seems that with rate volatility and AI fears and global turmoil, investors have just assumed the worst for commercial real estate, especially on the loan side.
But 3Q results were steady, you're transacting, you're originating. With all the noise that is out there, in your mind, what are the real risks for BrightSpire, and how do you position the company for those right now?
Michael Mazzei
Hi, Tom. The real risk is rates, which went to 5.37 on the 10-year, and at the time, market pundits were talking about six handles in September.
The real risk is long rates stay above 5% and get closer to 5.5, and that could have an effect on cap rates. That is I think the overall number one concern in any market, capitalization.
Cap rates could affect the real estate side significantly, so that's what we're watching for. In Q2, we had dialogue about this, and I was concerned there.
I mentioned on the call that if the 10-year punched above 5%, we would be concerned. Then I recall a conversation you and I had in August where we were both lamenting over the market seemed very quiet, and too weird, very quiet, and what was lurking in the weeds there.
Here we had September breakout, which I think neither of us were expecting on that call. Overall, we think that cap rates are an issue if rates stick much higher.
Refinancing issues are also an issue with Freddie and Fannie rates getting higher. During the quarter, and what is causing us to want to sit on more cash than we normally would have expected, as I said, 100 basis point move in rates in one quarter, albeit it's gotten better recently, but maybe it's gotten better for the wrong reasons.
AAA CLO spreads, as I said in the prepared remarks, they went out 15 basis points, and they didn't go out five basis points a deal. They kind of went out 15 basis points in one deal, and in fact, one CLO issuer dropped from the market, pulled their deal altogether, unhappy with the spread environment.
Then on the corporate side, we had things like Skydance, then when their issue broke in trading, the price dropped by five points on those bonds. You have in the AI sector something like CoreWeave trading at 15%.
When you see things like that, you get concerned. Then our origination team was telling us that during the month of September, there was a national broker who was indicating that their transaction sales pipeline was beginning to go sideways.
In fact, in one city, they had a lot of their transactions just kind of not pulled from the market, but their owners were saying, we have to sit tight and let things calm down, let's not solicit offers at this point. When you see things like that, you start to say, you know what, you're supposed to pay attention.
Then lastly, as a mortgage REIT, the loan books are four times levered. CLOs are a little bit more than four times levered.
When you're operating a model like this, cash liquidity is absolutely essential that you maintain that, and when the market indicates that there's noise out there, unfortunately, it may cause us to slow down the loan book growth, but you have to pay attention. Liquidity is absolutely essential, which is why I'm thinking that until we get more clear visibility, we're going to lighten up and hold that cash.
Now, again, we have a CLO ramp that we have to invest, we have anticipated repayments that we need to reinvest for, we will continue to stay active in the market in Q4. Yes, opportunistically, if something comes along and we want to shoot it, yeah, we'll do that.
Generally speaking, I think we're going to toward the side of letting our cash liquidity build. If that means that the pipeline or the loan book growth has to slow a little bit for the quarter, as Andrew said, it's grown $700 million in the year, we did a good job there.
We originated $900 million of product. If it has to slow for a quarter, it slows for a quarter.
Tom Catherwood
I appreciate that, Michael. Maybe as a follow-up, just want to dig deeper on cap rates.
Again, totally get the fear, higher rates, higher cap rates. We're hearing from the equity REIT side of the world, especially multifamily, maybe 25, maybe 50, given on markets and kind of Class B, Class C assets.
You're still transacting, you're still selling. Kind of two parts are: what have you seen kind of directly in the market cap-rate-wise?
Then second off, what kind of debt yields are you generating on your legacy multifamily, because that would in theory be kind of your cushion against higher cap rates?
Michael Mazzei
I'll take the first part of that, and I'll turn it over to Matt Heslin, our Chief Credit Officer, for the second part of that. We have REO to sell, and given the business model we have, we're not going to sit back and hold REO for another quarter or two and play an interest rate game.
We didn't do that with Albertsons, we're not going to do that in the REO portfolio. We're going to go to market and sell it.
If that means the market is a little less stable, we get nicked here or there, we're going to still sell. Generally speaking, earlier in the year, folks were buying multifamily with some negative leverage upfront with an anticipation that as you move into 2027 and beyond, the supply was going to wane substantially enough that the back-ended rent growth would more than substantiate and overcome any negative leverage upfront.
As we move further into this year and early next year, it's not implausible that those buyers start to look at it and say, we have to factor in some of this negative leverage is getting a little bit too much based on where rates are. You could have an effect on our REO sales, absolutely, and it's going to overall affect valuations only if the 10-year Treasury The negative leverage is kind of a short-term thing.
I do think that the rent growth that we're going to see in '27, '28 is going to be very powerful given how little building is going on, especially given that rates are now higher. Shovels in the ground are going to be less, home ownership is going to drop, secondary home sales are going to drop, more residence into multifamily will be the case in '27 and '28.
We think that the 10-year Treasury staying where it is, fine. If the 10-year Treasury gets to 5.5%, then I think cap rates are going to move by 25 basis points or so.
Matt, do you want to talk about the current loan book?
Matt Heslin
Sure, thanks, Michael. In terms of multi, our current book debt yields above a 6.
You hit the nail on the head in terms of what we've been tracking not only over the last month, but really over the last nine months in terms of rates and where we feel comfortable even on multifamily assets. A good example would be to look at our most recent CLO, going-in debt yield for that deal, which was 95% multi, was 7%.
Compare that to other recently issued all-multi CLO deals, which are generally in kind of the 5%, low 5% range. It's definitely something that's been on our radar.
As we continue to look at more opportunities, as Dan mentioned, which are primarily multi, we'll still be focused on those going-in debt yields even when there is a significant business plan in place that's expected to increase that.
Tom Catherwood
Got it. Appreciate the answers.
Thanks, everyone.
Operator
The next question will be from Timothy D'Agostino from B. Riley Securities.
Please go ahead.
Timothy D'Agostino
Good morning, and thanks for taking the question. It seems like cash and liquidity are kind of of importance for you all, and you could seems like could take a step back on loan origination.
I guess just sitting here with, the that's the CLO completed towards the end of September, as we look out to '27, is the idea to get, one CLO per year, issue one CLO per year? If so, with kind of how we're thinking about the market, and and maybe holding more cash and liquidity, what what might push, a CLO in '27 out to '28?
I know that might be a little far out, but any commentary there would be great.
Michael Mazzei
That's pretty far out. Really, we're targeting getting the loan book, which is now about 3.1, kind of north of 3.5, close to call it 3,750 to pick a number.
That entails probably one more CLO, I think we'll have three managed CLOs outstanding. There's no reason why that doesn't get done in '27.
We've already originated 900 million, we had net loan growth of 700 in the portfolio, I would anticipate that that would not be in 2028, that it would be in 2027. If we're not deploying capital to that extent, then something else has gone on in the market that is affecting all of us.
We don't anticipate that happening, and we would expect one more CLO, and then have three CLOs outstanding all at one time, and much less on repo. Right now, as we said on the call, we want to emphasize that we're two-thirds of the portfolio non-mark-to-market, non-recourse, and match-funded.
That's the highest we've been in our history.
Timothy D'Agostino
Great. I guess just quickly on the loan portfolio size, in earnings calls prior, you had mentioned about 3.5 billion by year-end and then 4 billion by middle of 2027.
I was just wondering, it kind of seems like that may slip out a little bit, and was just wondering if you all were going to provide or maybe talk about how you're thinking about the loan portfolio at year-end '26 and then halfway or midway through '27?
Michael Mazzei
We don't expect the loan portfolio to shrink in the next quarter, and if we could get it to grow modestly, that would be good. The question becomes is the periscope back up in the first quarter?
It very plausibly could be by then. I think things would have to be really very difficult in the market for us to not start originating at some point in time in Q1, and we'll take it as it comes.
Again, I don't think this is going to be a very protracted thing. I think we're just saying right now, we're taking our cue from the market.
The Treasury market appears to have calmed down. We'll see what happens in the credit spread market, in the next CLO that prints, and where our warehouse lenders are.
We are widening spreads on multifamily in tandem with what our banks are telling us and what the CLO market is telling us. I do think that we'll be back in the market.
This is just us being cautious about where we stand today. Also, as Andrew emphasized earlier, the quality of what we're seeing generally in the pipeline hasn't been as good as it was in the first three quarters of the year.
We're seeing a little bit of a tail-off in terms of the type of product that we want to do as well. As we move into year-end, I think that the portfolio stays where it is, maybe grows very modestly, and then we'll re-engage more fully in Q1.
Timothy D'Agostino
Great. Thank you so much for taking the questions today.
Operator
The next question will be from Chris Muller from Citizens Capital Markets. Please go ahead.
Chris Muller
Hey, guys, thanks for taking the questions. You just touched on this a little bit, but you've talked about 500 million of net growth in the back half of the year, and I heard Mike's comments on rates extending timelines and also just being cautious right now.
I guess the flip side of that is repayments have also been pretty low. Net growth seems pretty likely, I guess, in the next couple quarters.
Is positive net deployment, but maybe just a little lighter, a fair assumption given the environment out there?
Michael Mazzei
Matt?
Matt Heslin
I think that's probably a fair assumption. As Michael mentioned, we have 100 million in our ramp that's immediate, right?
We expect to put that to work over the next few months. That would obviously be net growth, that's not as a result of payoffs.
That is our expectation for the coming months before we get additional clarity.
Chris Muller
Got it. Then just looking at leverage, you guys definitely have some capacity to push that higher, it sounds like that's probably not likely in this environment.
I guess just naturally as some of this REO gets sold and then recycled, combined with the new CLO, should we expect that to just push leverage higher just mechanically?
Michael Mazzei
Oh, yes, absolutely, yeah.
Chris Muller
Got it. Appreciate you guys taking the questions today.
Michael Mazzei
We've got low leverage embedded in some of the REO that's either under-levered or unlevered entirely, so as we sell that out, that's going to be the capital that we'll be using to push the loan book north of 3.5.
Chris Muller
Got it. Makes a lot of sense.
Appreciate you guys taking the questions today.
Operator
Thank you. The next question is from Jason Weaver from JonesTrading.
Please go ahead.
Jason Weaver
Hey, good morning, guys. Thanks for taking my question.
Taking into account your comments on some moderating growth in the loan book looking ahead versus wanting to maintain excess liquidity, talk a bit about your appetite to pursue more share repurchase here given the discount that still persists?
Michael Mazzei
Good question. Like I said in the prepared remarks, we bought it at $4.81, it's obviously super compelling at this level.
When you look at the gap between book value and where it's trading right now, it's an astonishing number for the entire sector. We're looking at some of the other capital stacks across the peer group, we're not burdened with prefs, we're not burdened with the term loan, it's just cash and the repo book.
We look at that stock right now, but we also look at the market, as I said, and the market's telling us something. Is it plausible that we purchase some stock again?
It is plausible, absolutely. As I said, it's obviously a point more compelling than where it was when we repurchased during the quarter.
We really have to, as a mortgage REIT, and given the leverage that we run, you really have to look at the market and take your cue from it. We have to really be confident that something else here isn't happening, and that the Treasury doesn't revert to where it was.
When you look at the factors in the duration market, you still have massive deficits, you still have hyperscalers coming at the market with enormous amounts of debt requirements, and oil is still very high. The things that were driving the Treasury market higher, the uncertainties there, those things still exist, which is why I referenced the reason why the market may have come down a lot was because of the first time we had a flight to safety.
We had the hyperscalers be reverse correlation to the Treasury market, the equity market versus where Treasury rates were. That's the first time that's happened in a while, it could just be a flight to quality that is pushing rates down where they are.
When we get a better visibility into what the market's doing, then we'll decide whether we want to venture back in. Right now, to miss a trade on buying some stock here and giving up on liquidity, that's something we're not going to do.
Jason Weaver
Understood. Thank you for that.
Then maybe on the portfolio specifically, I think both the downgrades were Blue Bell, Pennsylvania, and I think those were originally underwritten at some pretty conservative LTVs. Can you talk about what changed within those specific markets that caused you to push them to level 4?
Michael Mazzei
Andrew?
Andrew Witt
Sure. Those properties essentially migrated on to the watch list as a function of upcoming maturities, and the properties are really connected physically in terms of location.
It's about 420,000 square feet of office complex. We downgraded the loans because we're coming up on an upcoming maturity and there's uncertainty around those positions, which we'll provide more insight on in the coming quarters.
Jason Weaver
I appreciate the color. Thank you.
Operator
The next question is from Gaurav Mehta from Alliance Global Partners. Please go ahead.
Gaurav Mehta
Thank you. Good morning.
I wanted to ask you, in the light of slowing loan growth for maybe next one or two quarters, how should we expect the dividend coverage? I know in the past you have said maybe positive dividend coverage by I guess next year.
Michael Mazzei
Right, thank you. Hello.
Right now, the leakage has been about, call it 2 to 3 cents a quarter, which is not significant. Really, it depends on two things.
One, getting back and deploying capital quickly, we don't expect to do a lot of that in the fourth quarter. Things could change, but we don't expect to do a lot of it, which is why we're telegraphing it here.
It really depends on if we're back in the market in Q1 or we still think that there are concerns about the overall market. My guess is that that probably is more likely that we are, but right now, we're being cautious.
It also depends on how we're getting off the sales for the REO. We have a lot that's listed, something listed this quarter, we have a number of things going out in the first quarter.
If we're able to get those deals done, we'll have more capital to deploy, and so that could help us as well. This is something that the board will watch over the course of the next coming quarters to see if we're getting back in the market and we're going to get north of that $3.5 billion number.
Right now, the leakage is modest, it's tolerable, and it really is a question of does the market continue to give us angst where we're not deploying capital. I think for us to do that, it's something that you're going to be watching as well and agreeing with that there's something going on here where we should hold on to cash a little bit longer.
Gaurav Mehta
All right. Maybe on the adjusted EAD sort of run rate, should we expect earnings to remain at around the current levels that you reported in 3Q?
Michael Mazzei
We're not going to give forward guidance, but I think I kind of said 2 to 3 cents a quarter is the leakage. That's probably something that is somewhat consistent.
Other than that, we don't want to give forward guidance.
Gaurav Mehta
All right, thanks. That's all I had.
Operator
Thank you. Ladies and gentlemen, this concludes our question-and-answer session.
I would like to turn the conference back over to Michael Mazzei for any closing remarks.
Michael Mazzei
Thank you all for participating today. For those listening, if there are any one-on-ones that you'd like to request, please contact us, we'll be glad to do so.
Otherwise, we will see you all in the new year. Thank you.
Operator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect.