Aarti Pharmalabs Limited
Q2 FY2027 · Earnings Call TranscriptOctober 29, 2026
Operator
Ladies and gentlemen, good day and welcome to Aarti Pharmalabs Limited Q2 and H1 FY27 earnings conference call hosted by PhillipCapital Private Client Group. As a reminder, all participant lines will be in the listen-only mode and there will be an opportunity for you to ask questions after the presentation concludes.
Should you need assistance during the conference call, please signal an operator by pressing star then zero on your touchtone phone. Please note that this conference is being recorded.
I now hand the conference over to Mr. Omkar Sawant from PhillipCapital Private Client Group.
Thank you, and over to you, Omkar.
Om Sanghavi
Thank you. A very good afternoon everyone.
On behalf of PhillipCapital Private Client Group, I welcome you to the Q2 and H1 FY27 earnings conference call for Aarti Pharmalabs Limited. Joining us today from the management are Mr.
Rashesh Gogri, Managing Director, Mr. Piyush Lakhani, Chief Financial Officer, and Mrs.
Hetal Gogri, Executive Director. I would like to hand over the call to Mr.
Rashesh sir for the opening remarks. Over to you, sir.
Rashesh Gogri
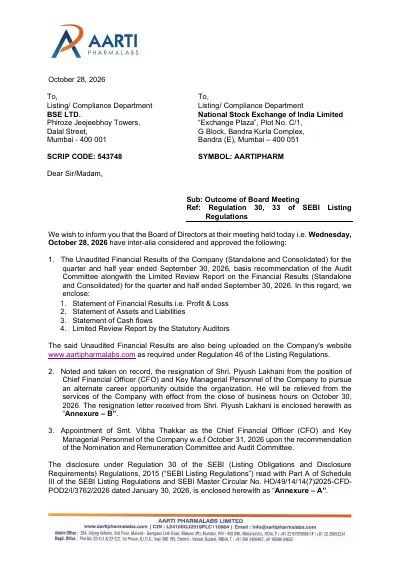
Good evening and thank you for joining us today to discuss Aarti Pharmalabs' second quarter and half year results for financial year 2027. The investor presentation relating to today's results have been filed with the exchanges and is available on our website for your reference.
We continue to make healthy progress in all our business segments and are executing well on our growth strategy. With clear focus on near-term opportunities, we aim to further solidify our standing as a preferred partner in the global pharmaceutical supply chain.
Moving on to our standalone financials for Q2 FY26, Aarti Pharmalabs maintained strong momentum delivering its highest ever quarterly revenue of ₹613 crore as compared to ₹417 crore, which is 47% increase Y-o-Y basis. The EBITDA was ₹136 crore as compared to ₹74 crore in the corresponding previous period of the previous year, and that is an increase of 84% Y-o-Y.
The profit after tax for the Q2 financial year 27 was ₹66 crore as compared to ₹24 crore a year back, which was 2.75 times the increase on last year's low base. The EBITDA margins have remained healthy at 22.2% as compared to 17.7% in the same quarter last year.
Now, I would like to tell you about the specific of the businesses in Q2 FY27. The xanthine derivatives and allied product segment contributed to 50% of the turnover.
The volume split between the beverages and others was 62% and 38% respectively. In terms of the geographical split, the export sales contributed to 59% and the rest was 41% with local sales.
Due to geopolitical turmoil, the raw material costs have stayed elevated and we are passing on the raw material increase to our customers. The API and intermediate business clocked 30% of the turnover.
The sub-segment-wise breakup is 57% for the regulated market, 33% for the ROW market, and 10% for the non-regulated market. Benefiting from the recent capacity expansion undertaken in the steroid API, we have recorded healthy sales in this quarter.
The third segment, CDMO/CMO, has contributed to 13% of the revenue in this quarter, and we are presently working with 23 customers. The number of active projects now is 59, out of which 39 projects are in commercial stages and 20 are under different stages of development, both at customers' end.
We remain on track to achieve our target of 40% to 50% revenue growth over last year on this business segment. The balance 6% turnover was others sales, which includes trading sales, export incentives, and solvent and other scrap sales.
Let me share a brief update about our ongoing projects. The groundbreaking of the Atali dedicated block, that is block number 2, has been done and we target to commercialize this block in the H2 FY28.
The ramp-up of xanthine expanded capacity is progressing and we plan to achieve the full capacity by the end of FY27, and we will achieve the utilization sequentially in the next year. The capacity expansion of the steroid block of API plant was completed and it is started contributing to the production and the revenue.
I would like to share a few words about the strategic outlook. Building over 25 years technical expertise and heavy investments over last 3-4 years, Aarti Pharmalabs has established a solid foundation to transition into robust, multi-pillar global pharmaceutical partner.
The mature xanthine derivative segment, where we hold a dominant market position, continues to serve as a cash cow. The company is also geared up to accelerate growth led by its high-growth CDMO/CMO pillar, followed by API and intermediate segment.
We are working on all fronts for growing these segments. Ultimately, with the capacity addition still underway in the medium term, Aarti Pharmalabs is well-positioned to deepen its global partnerships and drive substantial long-term value creation.
I now request the moderator to open the forum for Q&A. Thank you.
Operator
Thank you so much, sir. Ladies and gentlemen, we'll now begin with the question and answer session.
Anyone who wishes to ask a question may press star and one on their touchtone telephone. If you wish to remove yourself from the question queue, you may press star and two.
Participants are requested to use handsets while asking a question. Ladies and gentlemen, we'll wait for a moment while the question queue assembles.
Also, in order to ensure that the management will be able to address all the questions from the participant, we request you to kindly limit your question to two question only per participant. If you have a follow-up question, please rejoin the queue.
First question comes from the line of Hemant Mada with Unifi Capital. Please go ahead.
Hemant Mada
Thanks for the opportunity. Sir, can you give status on the both the projects, the xanthine one as well as the Atali phase 1?
How has the utilization been, because we still see capital work-in-progress on balance sheet of ₹300 crore plus? How should one read it, the capitalization of the assets and how the both the assets are operational?
Rashesh Gogri
As explained to you on the earlier calls, the xanthine expansion was two-phase. First was to get the finished product out, and that has been fully, as I mentioned on the call speech also, that we plan to ramp up the production to full production capacity by end of this year.
I think the same will continue on the intermediate production also. That also will get fully operational by end of this year.
By end of this year, you will see full capitalization of the xanthine project. The Atali phase 1 is complete and I think in the Q3 we will do the capitalization.
We have taken the trial batches of Atali phase 1B. Trials are actually underway in this week, and we will have full capitalization then on that block as well.
Hemant Mada
Okay. In terms of the CDMO visibility with the both the first phase A plus B both commercializing, and the number of projects increasing as per your disclosures, what sort of visibility currently we have to be able to utilize Atali at the full capacity in the second half?
Rashesh Gogri
Yeah. Basically, the Atali phase 1 A and B are serving different purposes.
The 1B is a smaller line which can take care of, early work for the newer projects, whereas the 1B 1A, which was commercialized, was a commercial line. It was like more scale-up line kind of thing which got commissioned now, in the phases of commissioning now.
It won't have too much difference or too much bearing on overall capacity addition that we will have in Atali by doing the phase 1B. Overall, we see that we will be able to completely utilize this Atali asset in this financial year, second half of this financial year.
Hemant Mada
Sure. On the xanthine front, compared to Q1, Q2 the top line is broadly same.
How should one look at it? Is the volumes have been broadly same and the pricing has been the same or there has been volume increase and price decrease?
There has been some change in the mix also in terms of the domestic sales proportion is much higher compared to the export sales proportion. How should one read it in terms of overall volumes, pricing for xanthine in Q2 compared to Q1?
In terms of Q3, Q4, there should be a significant jump in volumes, it's what we should assume?
Rashesh Gogri
I think xanthine has xanthine plus allied chemistry that we do, we had little bit of lower xanthine sales due to the shipments being held up due to shipment issues, but more sales on allied products. Otherwise, we would have ideally had higher sales in this quarter, but it was restricted due to this dispatch constraints.
I think that will get solved in the current quarter, hopefully. With that, as you say, the sales numbers overall has to increase.
Yeah.
Hemant Mada
Sure. Sir, in terms of API business, we have had some consolidation last few quarters.
There were some price erosion issue and some capacity constraint as well. We have had decent improvement compared to last quarter.
How should one read it in terms of API business? API number of products, etc., that has improved or is that intermediate capacity space because of the Atali being operational, there is some space available in Vapi, you're utilizing that to improve your intermediate production?
How should one read between API and intermediate, and can this run rate sustain or improve going into second half?
Rashesh Gogri
I think API and intermediate sales segment is largely driven by API only, because we continue to occupy actually the intermediate space by CDMO largely. We are not doing too much aggressive sales of intermediates.
In API, with the debottlenecking of steroids, I think, block, we have been able to get the regular sales back into the fold, which was constrained in the Q1. Now Q2 onwards, we anticipate greater sales of steroid products with the expanded capacity continuing.
Hemant Mada
Sure. With the capitalization happening for all assets in second half, should we assume meaningful jump in operating expenses?
Obviously, depreciation and finance cost will go up. On the operating expenses side, you will have capitalized something, the entire cost structures should go up in second half.
That is fair way to assume?
Rashesh Gogri
See, the finance cost would basically remain at almost similar levels because most of the capex kind of financing we have arranged for, and depreciation is likely to go up as we capitalize here. Depreciation cost will go up.
Hemant Mada
Other operating expenses?
Operator
Thank you. I'm sorry to interrupt you, Mr.
Hemant, but please rejoin the queue for more questions.
Hemant Mada
Thank you.
Operator
Ladies and gentlemen, in order to ensure that the management will be able to address all the questions from the participant, we kindly request you to limit your question to two question only per participant. If you have a follow-up question, please rejoin the queue.
Our next question comes from the line of Sudarshan Padmanabhan with Ashika Investment Managers. Please go ahead.
Yes,
Sudarshan Padmanabhan
thank you for taking my question and congrats on great set of numbers. I have two questions from my side.
One is if I look at the mix in this quarter, the mix has primarily been more favorable towards the contract manufacturing business, the gross margins has taken a hit. Would it be primarily because of the raw materials and how much of the price increase has basically been passed?
How do we see the third and fourth quarter as we pass the raw material cost further?
Rashesh Gogri
No, I think over Q1, I think Q2 the CDMO sales was almost double than Q1. In terms of the pass-through, I think in the xanthine and allied chemistry we have been normally doing the pass-on, and also in API also we have got some price increases.
With the raw material cost increasing and the cost being passed on, I think that's why you see the little bit of number erosion on the EBITDA side by a couple of percentage points. I think that is what it is.
Sudarshan Padmanabhan
More or less by the third and fourth quarter we should be catching it up in terms of passing on the increase of prices, would that be right?
Rashesh Gogri
We are already passing it on. Third, fourth quarter will have higher sales of CDMO, overall EBITDA percentage number can improve in the third and fourth quarter.
Sudarshan Padmanabhan
Sure. My second question is on the balance sheet side.
If I'm just looking at the commentary, we have added two commercial molecules compared to the last quarter on the CDMO side. When I look at the balance sheet, we are seeing inventories as well as working capital moving up.
Would it be the right assumption to say given the fact that CDMO is scaling up, that we would have primarily prepared the inventory and this working capital is primarily to fuel the kind of growth that we are expected to see in the second half?
Rashesh Gogri
Overall working capital cycle remains close to 165 days or 167 days for us. What has happened is that since sales has gone up, of course the need of working capital will also go up.
I think the CDMO business is also where the sales normally is more lopsided towards H2, I think in H1 we see the inventory built up. All these three factors combined, I think, have resulted in higher working capital.
I think as we see the growth that we are targeting 40% to 50% growth of the CDMO business this year, and next year also it will further grow, I think we will unfortunately we will have to live with the higher inventory overall within our system. Sure.
Sudarshan Padmanabhan
One final question before I join back the queue is, given that there is capacities coming in, you mentioned about depreciation and financial costs, is below the gross margins, would we have absorbed a fair amount of costs for the expanded capacity or should we see higher costs both on the employees and opex with respect to the expanded capacity?
Rashesh Gogri
I think in H2 it will increase. Overall apportionment because the 1B block of Atali is also will get capitalized.
I think the fully caffeine also the early intermediate also will get capitalized. All that getting capitalized, I think the expenses will also start recurring on the P&L side.
Sudarshan Padmanabhan
Sure, but operating leverage will basically absorb some amount of cost, the margins might not be very different. Probably it could be better, at EBITDA level
Rashesh Gogri
too. I think one percentage point here or there, I think we should be there.
Sudarshan Padmanabhan
Sure. Thanks a lot, sir.
I'll jump back the queue.
Operator
Thank you. Next question comes from the line of Ankit Gupta from Bamboo Capital.
Please go ahead.
Ankit Gupta
Congratulations for good set of numbers. Sir, on the xanthine side, if you look at the past two quarters, we're already at 1,200 crore plus kind of annual run rate without even fully utilizing the capacity or not even nearing the full capacity.
Given how the current prices are, at full capacity would we be expecting 1,500-1,600 crore kind of revenue from xanthine?
Rashesh Gogri
If the prices remain high, we expect this to go up to 1,400 to 1,500 crore.
Ankit Gupta
Okay. Okay.
And...
Rashesh Gogri
If the raw material prices will come down, then the top line will come down because we have pass-through on, yeah.
Ankit Gupta
Okay. Sir, on the Atali expansion, we are almost will be capitalizing the CWIP that we have, which I suppose will largely be from the Atali capex only in Q3.
Despite the operating expenses of that plant coming in in Q3, Q4, with higher CDMO expenses given CDMO revenue given we have done almost 120 crore kind of revenue in first half of this financial year, for us to grow to 40-50% as you have guided, we'll be doing close to 280-300 crore kind of revenue in the second half. With that revenue, CDMO revenue which is at higher margins, we should still expect our margins to be higher than 22% to 23% that we have reported in this quarter, as you had said in your previous question?
Rashesh Gogri
See margin percentage is factor of global raw material pricing plus how much more we are doing CDMO business. If the raw material prices due to this war impact and everything remains high, that will have a lower downward pressure on the margins, and CDMO will give upward.
We have to see how both mixes remain in the second half and that will define the percentage margin. In the absolute number, I think gross margins will keep on increasing whatever as we do more quality business going forward.
Ankit Gupta
Sure, sir. Sir, this last question...
Operator
Thank you. I'm sorry to interrupt, Mr.
Ankit, but please rejoin the queue. Yeah.
Next question comes from the line of Dhwanil Desai with Turtle Capital. Please go ahead.
Dhwanil Desai
Hi, good afternoon everyone and congratulations for a very good set of numbers. Sir, first question is on the API side, I think we have reached a run rate of 180 crores.
If I remember correctly, we have capacity to serve up to 1,000 crore kind of a revenue. As now we are again ramping up once the headwinds are behind on the API side, do we see kind of going to 200 crore run rate by end of this year and then eventually 250 odd crores?
My question tied to that, will we need more capacities to serve API demand thereafter?
Rashesh Gogri
Just to give you that API plus intermediate segment is what 180 crore is. Currently on the API manufacturing side that we have in Tarapur, there is a debottlenecking happening on the anti-cancer side, the block number 3 that we are trying to debottleneck.
Once we have that debottlenecked, we will have the capacity to manufacture more APIs and we can, depending on the product mix, we can achieve higher top line also from the current level. On the intermediate fronts that we manufacture and sell to the market, of course, it is dependent on the capacity that we have and how much we are occupying in the CDMO, and balance we have a buffer product that we keep on producing.
Overall, I think it is a fair idea that this 180-200 could be the base for second half every quarter, and then I think we'll have to see how the next year...
Hetal Gogri
We are also in process of validating few new products which would be the base for the future.
Rashesh Gogri
Yeah.
Hetal Gogri
In this quarter and the next quarter we will do that.
Dhwanil Desai
Got it, got it. Very clear.
Second question on the CDMO...
Operator
Thank you, sir. You have asked already two questions.
Dhwanil Desai
Sir, I already asked one question only. This is second one.
Rashesh Gogri
Yeah. Take it, take it.
Take one question.
Dhwanil Desai
Yeah. Sir, second question on CDMO.
I think we talked about 40% to 50% growth and we are already in H2. How should we look at going into FY28?
Reason I'm asking is that some of the molecules that we are supplying to will get commercialized, will get launched in this year, next year. Approval also will come from obicetrapib.
With all those, three or four molecules that we have, do we expect that 40-50% kind of a growth next year? With all these molecules put together, do we have a visibility to reach 700-800 odd crores once the block 2 also comes into play?
Rashesh Gogri
See, as I mentioned, our target remains $100 million or 1,000 crore, whichever comes first. How we achieve it is dependent on how the customers get approval.
We work on almost 59 projects and there are several projects which are good potential and it is a CDMO/CMO value chain where you can have ups and downs, but with the kind of seeding that we have done, we are fairly confident that we will achieve that number. When we will achieve is one year here or there, we'll stick to that number.
Dhwanil Desai
Got it. Thank you.
Operator
Thank you. Next question comes from the line of Kushal Goenka with Mangal Keshav.
Please go ahead.
Kushal Goenka
Hi, sir. Congratulations on a good set of numbers.
Sir, my question comes back to the previous one of the previous participant who mentioned about the working capital. Now I understand that you mentioned about the inventories, but if you see the trade receivables also, that has also substantially increased and because of that the cash flow from operations are just 30 crores as compared to around I guess 270 crores of EBITDA that we did.
Because of this, I guess short-term borrowings have also increased to around 650, 660 crores. Just wanted your thoughts on this that is the debtors day increasing and any thoughts on the same?
Rashesh Gogri
Basically the debtors would increase in terms of the sales also. Sales also has increased compared to H1 of last year.
If you see the cash conversion cycle, which is what we track, is around 150-160 days, and that is what we basically think that is the baseline for our business.
Kushal Goenka
Sir. Thank you so much.
That's all.
Operator
Thank you. Our next question comes from the line of Rahul Jain with Credence Wealth.
Please go ahead.
Rahul Jain
Hello. Am I audible?
Operator
Yes.
Rahul Jain
Yeah. Thanks for the opportunity and, sir, congratulations on a very good set of numbers.
My first question is with regards to this CWIP of about 300 crores. In the second half, apart from the utility capitalization of this 300 crores, which you said you will do it in quarter 3, any further capex and capitalization to be done in the second half?
Rashesh Gogri
There will be some smaller projects also which... Total capitalization will not exceed this 300 number, it will be lower only because some projects will fall to next year also.
Rahul Jain
Q1 of...
Rashesh Gogri
Q1 of next year, we don't anticipate beyond this any capitalization.
Rahul Jain
Sure. The capex amount in the second half?
Rashesh Gogri
Overall, we have targeted total capex of around 400... For the year.
350 to 400 crore for the year. Sir,
Rahul Jain
my second question is with regards to your guidance, sir. You have been in general being conservative and maintained that EBITDA and revenue growth of around 15% to 18% for many quarters now.
Given what we have done in first half, both in terms of revenue and EBITDA, we are well ahead of that number. Also given the Atali expansion coming through, xanthine ramp-up in next year, plus having visibility on CDMO with the large number of projects, sir, do we feel there is ample scope to upgrade this guidance of 15% to 18%?
Not just for this year, this year তো looks quite certain it will be much higher, but even for FY28 over and above FY27 numbers?
Rashesh Gogri
Overall, see, we are giving three-year guidance, we don't want to give a pointed guidance for this financial year and, half yearly or quarterly volatility, we don't want to comment on this. The overall one thing is what I want to reassure you is that the strategy is working and overall all the three businesses that we run are poised to do the growth in future.
I think we are on track for all our guidance number. I think one year can be higher, one year last year we had a little bit of lower numbers, of course this year looks promising going forward.
Rahul Jain
Just one last small bit, sir. In terms of API, you have mentioned in your presentation as well as your remarks that the headwinds are subsiding.
With regards to the environment, if you can share some more details with regards to the API segment, what exactly is happening? Demand is coming back or prices are much better now?
You can share some insights on that.
Hetal Gogri
In Q1, as Rashesh mentioned earlier, we had one of the major block shutdown, which got over and that is the reason Q2 and then some of the projects, we are trying and converting it to further more regulated markets. See, we are very much focused on regulated business, some of the products are getting matured even further to go for the newer approval with our customers in regulated market and that is giving us a little higher margin compared to the ROW and other markets.
Going forward, in API we are very much focusing on R&D and targeting newer validations going forward, and we will be working towards it. We will see that if we are able to capture as a first source with our customers for a newer project, we would want to improve our margin in that scenario.
Rahul Jain
Sure, sir. Thank you so much and wish you all the best.
Hetal Gogri
Thank you.
Operator
Thank you. Next question comes from the line of Kaushal Sharma with Equinox Capital Venture Private Limited.
Please go ahead.
Kaushal Sharma
Yeah. Hi, sir.
Very good evening. Am I audible?
Hetal Gogri
Yes.
Kaushal Sharma
Just one question on your CDMO side, sir. Out of 39 commercial stage and 20 development stage CDMO projects, what are the key therapy areas and type of molecules you are working on, and how are these projects split across each therapy?
Could you guide on this?
Rashesh Gogri
Basically we have products which are going for antihypertensive, for pain management, anticancer... Anticancer.
or CNS, varied range of products that we do in our basket. They are not concentrated only on the anticancer side or any such side.
Kaushal Sharma
Sir, are we working on any peptide and all because we have R&D, do you have any plans for that?
Rashesh Gogri
We are trying to set up the peptide lab. That is what we did mention earlier that we will set up.
I think by the end of this financial year we will have an operational peptide labs with all the equipments. We have already started recruiting the teams which have experience of peptide and we hope that for the next kind of we'll start getting customer business in next financial year on the peptide and oligonucleotide side.
Kaushal Sharma
In the development stage that we have 20 development stage of CDMO projects, do we have any peptide-based project in that?
Rashesh Gogri
Not any major project. I think, yeah, we have one or two liquid phase ones, but not any major solid phase
Kaushal Sharma
one. In future we are expecting that some development would happen in this?
Rashesh Gogri
I think peptide and oligonucleotide are these two areas where we feel that there is a lot of opportunity, I think, and which we can capture. Of course, these are highly complex chemistry which require very precision in purification and conjugation, all that we will have to get the experience on doing this.
Of course, we are hiring experienced chemists and scientists to work on that. We'll see how it goes.
I think next year will be the year where we will do a start, we'll pitch to the customers and see how it goes. Then I will be able to give you a firm commentary that how we are progressing on this.
Kaushal Sharma
Got it, sir. Thank you very much for answering my question.
All the best.
Operator
Thank you. Next question comes from the line of Dhruv Sitlani with Vyomara Capital.
Please go ahead.
Dhruv Sitlani
Thanks for the opportunity and congratulations on a great set of numbers. Sir, my first question is how much of the growth in API for this quarter was driven by pricing versus volume growth?
Rashesh Gogri
Largely volume-driven. The current growth was largely volume-driven.
Dhruv Sitlani
Okay. Sir, on the API and intermediate business, what sort of growth do we expect over the next three to four years?
Will this largely be again volume or new product-led growth?
Rashesh Gogri
I think both. It will be new product-led as well as the volume growth, and in earlier calls also I have mentioned that we will have 10% to 15% growth every year on this business, or probably in certain years we can have higher growth also.
Dhruv Sitlani
Sir. Thanks for the color.
On the API, sir, competition is primarily Chinese competitor or other API company within India?
Rashesh Gogri
Both.
Hetal Gogri
Both.
Rashesh Gogri
Both.
Dhruv Sitlani
Okay. Thank you.
Operator
Thank you. Our next question comes from the line of Aaryan Mehta with Shawas Capital.
Please go ahead.
Aaryan Mehta
Hi, congrats on the great set. Earlier you mentioned that there was some spillover of the xanthine sales due to shipment issues.
Can you quantify how much that was?
Rashesh Gogri
That would be around 5% of this quarter's xanthine number sales.
Aaryan Mehta
So 5% sort of spillover. Also, our guidance for this year of CDMO, let's say, of 40% to 50% growth, I think we'll need around 280-300 crores more.
There's also our LDL-lowering molecule which is ramping up. How confident are we on meeting the guidance of that 40% to 50% growth?
No,
Rashesh Gogri
as I mentioned, we are maintaining the guidance, we will get to that number.
Aaryan Mehta
Sure. Thank you.
Operator
Thank you. Our next question comes from the line of Arun with Unifi Capital.
Please go ahead.
Hemant Mada
Yeah. Thank you and congratulations on the good set of numbers.
Sir, in August, you had said that the realization per kg would decline in Q2 for xanthine, but on a Q-on-Q basis, the revenue of xanthine is almost flat. Could you break it up between the price fall and how much did the volume grow, sir?
Rashesh Gogri
No, actually what has happened is that xanthine and then we have the allied chemistry, which we do along with xanthine, which is classified under xanthine chemistry. There was a bump in that chemistry.
Xanthine numbers actually have little bit fallen, whereas the allied chemistry that we have gone, in that the top line has increased. Overall, I think on the xanthine side we have some fall in the average realization.
We need to check the exact number, but around some fall on the realization.
Hemant Mada
On the volume side, sir?
Rashesh Gogri
Volume side, I think we have...
Hetal Gogri
As mentioned earlier, there was a 5% material which got stuck, because of that there will be some fall on xanthine and the allied products, the volume and the turnover was higher, so.
Rashesh Gogri
Yeah.
Hemant Mada
Got it. Is Q2 is Q2 the peak in debt or will it rise further, sir, with the remaining capex?
Can you guide on that?
Rashesh Gogri
On the xanthine, we will further improve our top line.
Hetal Gogri
Yeah.
Hemant Mada
My question was on the debt aspect. Debt went up about 150 crore in H1.
Just 250 crore of FY27 capex still to come. Do you see this would be the peak or you would still need more debt to do your capex?
Rashesh Gogri
No, we will need more debt.
Hemant Mada
That would be just for this 250 crore of...
Operator
Thank you, sir. You may please rejoin the queue for more questions.
Hemant Mada
Sure. Thanks.
Operator
Thank you. Next question comes from the line of Ashish with Leo Capital.
Please go ahead.
Congratulations on a good set of numbers, sir. For the xanthine business, how much of our growth was driven by value and volume growth on a quarter on a year-on-year basis for this quarter?
How does xanthine prices compare versus last year and last quarter?
Rashesh Gogri
The xanthine prices, on an average, our realization is up 15 10% to 15% over last year realization. I think overall in this entire year, we will have probably close to 15-20% jump over last year's volume.
Hetal Gogri
Last year was 6,000 tonnes.
Rashesh Gogri
Last year we did close to 6,000.
Hetal Gogri
5,000, I think. Last year was...
Rashesh Gogri
Yeah. We'll have 15% jump on the volume this year over last year.
Got it, and pricing-wise, what was the pricing, sir, on xanthine?
Rashesh Gogri
15% higher this year, average. Okay.
What sort of utilizations are we operating on the expanded capacities on the xanthine business which we added in Q2? By when do we expect full utilization?
Rashesh Gogri
No, full utilization we have not planned for full utilization. Over next two years, we will gradually reach to 90% utilization.
Our capacity nameplate will be 9,600, we will operate around 8,800 or at a highest level in next two years. Next year, we should anticipate 7,500 to 8,000 in that range.
Currently, what is...
Operator
Thank you.
Rashesh Gogri
Near 7,000.
Near 7,000. Thank you, sir.
Operator
Next question comes from the line of Ankit Gupta with Bamboo Capital. Please go ahead.
Ankit Gupta
Thanks for the opportunity again. Sir, the first question is on the CDMO side.
We have been targeting 1,000 crore of revenue as you have indicated in earlier calls, whether it is FY28, '29 or FY30, we'll see. Given the current pipeline that we have and the current set of capacity, including the dedicated block that is supposed to come in the second half of next financial year, is our pipeline and the visibility for 1,000 crore revenue there, plus the capex with this new dedicated block also coming in, we have enough capacity to reach that number of 1,000 crore?
Rashesh Gogri
I think we should have enough capacity to reach 1,000 crore with the new dedicated capacity coming in. I think, as I mentioned earlier, we'll not restrict our capacity to that.
If we have more visibility of the newer projects or the demand of the current projects is also increasing, we'll have to put up additional capacities because the current dedicated block capacity is only planned for few projects. If we have more projects having more visibility, then we'll have to put more manufacturing assets.
Ankit Gupta
This year anyway we are doing 400 crore capex. Next year we have plans for the new dedicated block which is coming in, a part of it will spill over from this financial year to next financial year.
Apart from that also, we're looking to add capacities plus, you've been indicating that, we'll put up more dedicated blocks. As of now, we have, some indications on putting up new capacities for next financial year years, as well as new dedicated blocks?
Rashesh Gogri
No, I think still we are figuring it out. I think next year we will decide how much more needed and where to put it.
Ankit Gupta
Okay.
Rashesh Gogri
Yeah.
Ankit Gupta
Okay. Sir, on the xanthine, once we reach that full capacity utilization by next financial year hopefully, we would be looking to expand capacity or we are not looking to put in any more capex on the xanthine side?
Rashesh Gogri
No, I think we will have second largest capacity in the world and I think we will be happy to maintain this position, I think, for next few years, and then see how it goes. Because we have gone up from 5,000 to 9,000 plus capacity,
Ankit Gupta
yeah. Sir, on pricing side, we have seen there'll be two-part to the pricing.
One will be the impact of the crude and second will be the impact of Chinese government authorities withdrawing the rebates that they were giving to the companies on the exports. Let's say even if the crude prices come down, do you think the prices that we're seeing on the xanthine side will be sustaining or it'll come down?
What is your view on the pricing given how the current scenario is? Sir,
Rashesh Gogri
in xanthine, there are three segments. In the spot segment, the prices will have pressure.
I think the pharma and the beverages section anyway we will have more stability on the pricing.
Ankit Gupta
You think at least on those side, the existing prices can sustain going forward also?
Rashesh Gogri
Existing margin, absolute margin will sustain at least for next financial year, then we'll have to see how the next year goes.
Ankit Gupta
Yeah. Okay.
Thank you and wish you all the best.
Operator
Thank you. Next question comes from the line of Kirtan Donga with Himalaya Capital.
Please go ahead.
Kirtan Donga
Hello. Thank you for the opportunity.
My first question was for the Atali block 1, what sort of asset turns do we expect for the multipurpose block?
Rashesh Gogri
See, multipurpose block as such, Atali total capitalization was done, which has greenfield project, where the block had one value and then there was all the central utility, warehouse, the land development and everything. There the asset turn will not be very high, but I think the newer blocks we have given the guidance that it will have 1.2 kind of 1.2 to 1.4 kind of turn on asset side.
Kirtan Donga
Sir, some numbers is possible?
Rashesh Gogri
I mentioned to you the number, no, on...
Kirtan Donga
No, that was for the new block.
Rashesh Gogri
Assume that current block is also of the same cost and same size, it will have this kind of a turn.
Kirtan Donga
The second question was, do we largely expect Atali to be used for CDMO business or do we also expect generic API business to come from here?
Rashesh Gogri
No, there won't be any API business, some intermediate business plus CDMO. Largely
Kirtan Donga
it will be CDMO only.
Rashesh Gogri
CDMO plus intermediate, yeah.
Kirtan Donga
Okay. Thank you.
Operator
Thank you. Our next question comes from the line of Piyush Bangar with Vidhit Global Securities Private Limited.
Please go ahead.
Piyush Bangar
Thank you for the opportunity. My question is related to the peptides and oligonucleotides business.
As you said that the lab will be operational by the end of FY27 and the numbers will be reflecting from FY28 onwards. What kind of numbers do we anticipate in terms of percentage of total revenue in FY28 and ahead?
Rashesh Gogri
It's too early to give any number or any guidance. We are just setting it up, I think this question next year would be a good question for you to ask.
Currently I can't comment with any greater visibility on this.
Piyush Bangar
Okay. Thank you very much.
Yeah.
Operator
Thank you. Next question comes from the line of Tushar Raghatate with Omega Portfolio Advisors.
Please go ahead.
Tushar Raghatate
Thank you for the opportunity. Sir, my question is on the API.
Historically last three years, our API percentage contribution was near to 40%. In the last three quarters, it has reduced down to 30%.
I could see that we have filed a DMF in the prostate cancer drug. What sort of opportunity do you see in that cancer drug?
Sir, your five-year view on the DMF pipeline which we plan to kind of file. The next question is on the CDMO, the peptides and oligonucleotide kind of research what we're doing.
I just want to understand the next five years, this is for small molecules. Any plans, any aspiration for entering into large molecules and other different types of modalities?
Rashesh Gogri
I think on the first thing, we have a strong pipeline of 61 APIs that we have, out of which next financial year we will have several patent expiries expected. Those products will be launched with our partners in their markets where they have partnered with us.
That will have some sales happening in that region, and we still have to quantify who is getting the market share and how overall the dossier guys with whom we are sold are able to capture, and that will define the growth for us. Second thing is on the current existing products also that we have, we are trying to get newer and newer customers as a AVD program, alter and vendor development, and that's where also we will gain market share.
Coming to your CDMO question on the peptides and oligonucleotides, I think that is a large molecule which we are trying to develop. Apart from that, we are also trying to develop the linkers also as a modality, and I think this few modalities, small molecules, peptides, oligonucleotides, as well as the linkers, ADC linkers, all this will be what we will offer currently to our innovator customers.
Tushar Raghatate
Okay. Sir, just on the API front, what is our right to win for the DMF filing which you plan going forward?
Is there any strategy that we're only filing for where there is a less of a competition? What's our view on the pipeline for the next five years?
Rashesh Gogri
No, we have strong pipeline of onco products, I think largely driven by the onco products and where we have several projects with dossier makers and US market consumers. We have to see who is getting the market share and that will define how the segment will grow.
I think I have given the guidance number on what our aspiration is. We'll have to see what numbers comes on the growth on API side.
Tushar Raghatate
Fair enough, sir. That was helpful.
Thank you.
Operator
Thank you. Next question comes from the line of Ameya Deosthali with ValueQuest.
Please go ahead.
Ameya Deosthali
Hi.
Rashesh Gogri
Given
Ameya Deosthali
the recent filings, whether it be on the onco or anti-depressant on DMF and CEP, what are the targeted therapeutic areas that we want to focus on over the next two, three years, which we can say large mix over the next two years?
Rashesh Gogri
I think antidiabetic range of products, blood thinners, antihypertensives, these are the modalities. Apart from steroid, which goes for the inhalation, I think we have good projects that are getting commercialized there.
Of course, oncology, we have several projects that will get commercialized. All these are the growth areas that will be for us on the API side for next few years.
Ameya Deosthali
In second question, in the peptide R&D, I was just looking at the renovated website. You have given good disclosure on SPPS, LPPS, and the types of peptides that you are starting work on, as you say.
Do we see R&D spends accelerating over the next one or two years? How do we see Aarti Pharmalabs as a company kind of hiring the top R&D talent required for such a intense chemistry like peptides?
Rashesh Gogri
As you rightly mentioned, we as a company, we will invest more in the research and we will have more R&D expense happening going forward. I think attracting talent is an very important function of the management that how we are able to attract talent, and we were glad that we could attract good talent over FY '26, '27 and last year also.
We have the new CSO who has joined since last nine months, and then we are also had a new API R&D head who joined us. We are also further recruiting on the R&D side further team.
I think with the renewed focus on peptides and complex chemistry, we are very sure that we will have good talent in our team to deliver what the strategy that we have defined.
Ameya Deosthali
Just to squeeze a last question. On xanthine, do we have a break-up on what is the spot market sale versus, as you said, the pharmaceutical or the other grade sale?
Hetal Gogri
We don't give that actually.
Rashesh Gogri
We are not giving that breakup currently.
Ameya Deosthali
Thanks. Congratulations and all the best.
Yeah. Thank you.
Operator
Thank you. Next question comes from the line of Rupesh Tatiya with Long Equity Partners.
Please go ahead.
Rupesh Tatiya
Thank you for the opportunity, sir, and congratulations on good set of numbers. First question, sir, is on API segment.
I was looking at some numbers and I think we did, let's say, 920 crores sales in API in FY25, which came down to 650, and in first half, this is around 345, round figures. I think we were aspiring that FY27 API sales will be closer to FY25.
Do you still aspire to get there in this year?
Rashesh Gogri
No, I think the API sales on FY25 was 43% of total sales, and which last year became close to 36%. In the current financial year, we are at close to 30% of the API on the total front.
Yeah. That's where we are.
I think overall numbers are increasing, and I think our xanthine number is increasing faster, overall pie is increasing, and last year we had a dip overall on the API side. We first have to regain to the previous year number, which we, of course, will cross this year and then move forward.
Rupesh Tatiya
Will we get to previous year high this year and then let's say 15-20% growth next year?
Rashesh Gogri
We'll have to see how this year goes. That is our target that we'll get to the new higher number.
Rupesh Tatiya
Okay. That is one.
The second question, sir, is on slide 12, where we're looking at let's say 1,000 crore revenue in CDMO in 2-3 years. Now there are two ways to think about it, right?
One way is that in let's say FY25, FY26, and H1 FY27, last let's say 18 months, six molecules have gone into commercialization, from 33 it has gone to 39. Either the potential of these six molecules is really large that they can be 500-600 crore and then we can go to 1,000 crore, that is one way I can imagine 1,000 crore.
Or other way is that your under-development pipeline has to go from 20 to let's say 100, at least 70-80, because the under-development pipeline has actually not moved at all for last 3-4 years. How can you just address both of these aspects for these six commercial molecules...
No.
Rashesh Gogri
I will explain you how we are keeping the pipeline. The pipeline actually you are seeing the constant number, actually it is a moving number.
I think the pipeline has new additions and also the deletions. The projects which fail in the clinical phases go out also, this is the current pipeline.
This is not a cumulative number which is only one way increasing, okay? The number keeps on churning, I think overall that's why you are seeing that the number is remaining high.
From the 21 under, there will be certains which will go out and that will not get commercialized, okay? Then we'll add more commercial molecules.
We have more certainty on the 39 projects that we have than the 21 projects that we have on the under-development side. On the 39 projects also, we have certain projects that have just been transferred last year and they are campaign products, there was a big increase in projects that moved from China to us as a China plus one strategy, where we were added as additional source and there these projects were not very large, but the number of projects have increased and these projects have a cycle of approval and have a campaign cycle.
All those factors are a little bit complex than the simple justification that you derived to get. However, we have few good projects which will drive bulk of the sales number.
This 80/20 rule of number of projects, 20% project driving 80% revenue still applies in this as well, yeah?
Rupesh Tatiya
Just to summarize, sir, if end markets perform well, which is not in our control, with the existing combination of commercial projects and under-development projects, 800-1,000 crore revenue visibility is there even with the existing set of molecules, that's a fair inference?
Rashesh Gogri
The 10 to 12 projects that we have out of the 60 projects, the 20% projects will drive 700 to 800 crores of the revenue for out of the 1,000 potential that we have overall.
Rupesh Tatiya
Okay. Yeah.
Thank you for answering my questions.
Rashesh Gogri
Yeah.
Operator
Thank you.
Rupesh Tatiya
Thank you.
Operator
As there are no further questions from the participant, I now hand the conference over to the management for the closing remarks. Thank you and over to you.
Rashesh Gogri
I would like to thank everyone who participated our conference. Thank you.
Happy Diwali.
Operator
Thank you so much, sir. Ladies and gentlemen, on behalf of Aarti Pharmalabs Limited and PhillipCapital India Limited, that concludes this conference.
Thank you for joining us and you may now disconnect your lines.