Camtek Ltd.
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Kenny Green
Thank you for standing by. We will start the call in a minute.
Ladies and gentlemen, thank you for standing by. I would like to welcome all of you to Camtek's results Zoom webinar.
My name is Kenny Green and I am part of the investor relations team at Camtek. All participants other than the presenters are currently muted.
Following the formal presentation, I'll provide some instructions for participating in the live question and answer session. I would like to remind everyone that this conference call is being recorded and the recording will be available from the link in the earnings press release and on Camtek's website from tomorrow.
You should have all received by now the company's press release. If not, please view it on the company's website.
With me today on the call, we have Mr. Rafi Amit, CEO, Mr.
Moshe Eisenberg, CFO, and Mr. Ramy Langer, COO.
Before we begin, I'd like to remind you that the statements made by management on this call will contain forward-looking statements within the meaning of the federal securities laws. Those statements are subject to a range of changes, risks, and uncertainties that can cause actual results to vary materially.
For more information regarding the risk factors that may impact Camtek's results, please review Camtek's earnings release and SEC filings, and specifically the forward-looking statements and risk factors identified in the results press release issued earlier today and such other factors discussed in Camtek's most recent annual report on SEC Form 20-F. Camtek does not undertake the obligation to update these forward-looking statements in light of new information or future events.
Today's discussion of the financial results will be presented on a non-GAAP financial basis unless otherwise specified. As a reminder, a detailed reconciliation between GAAP and non-GAAP financial results can be found in today's earnings release.
Now, I'd like to hand the call over to Mr. Rafi Amit, Camtek CEO.
Rafi, please go ahead.
Rafi Amit
Hello, everyone, and thank you for joining us today. Just three weeks ago, many of you joined us at our investors and analysts breakfast event at SEMICON West, where we shared our growth strategy, technology roadmap, and new financial targets.
With that in mind, I will keep my remarks brief today. I will start with a review of our third quarter results, followed by a brief recap of the key messages from that event.
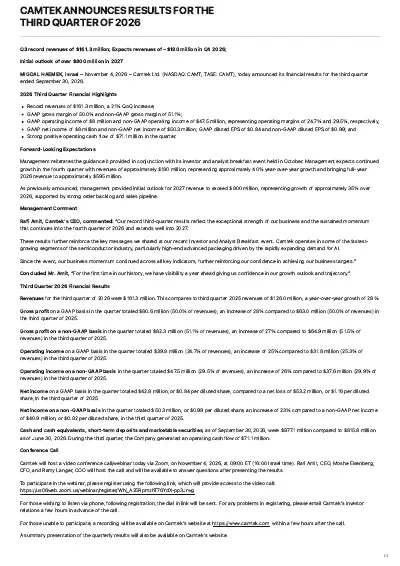
The third quarter marked another record quarter for Camtek, with revenue reaching $161.3 million, exceeding our guidance and representing 28% year-over-year growth and 21% sequential growth. Operating income also reached a record $47.5 million, with operating margin expanding to 29.5%, compared with 27% in second quarter.
These results highlight the strong operating leverage of our business model as robust revenue growth translated into even greater growth in operating profitability. Approximately 80% of our revenue was generated from advanced packaging applications, the majority of which were driven by AI-related demand.
Our new-generation platform, the Eagle G5 and Hawk, accounted for approximately 57% of our systems revenue, and we expect their contribution to continue growing as customer adoption expands. Order momentum remained exceptionally strong.
As we shared at our recent investor and analyst breakfast event less than a month ago, we had received more than $800 million in orders since the beginning of year until that day, and the strong order momentum has continued since then. Approximately 80% of these orders were related to advanced packaging applications, nearly all of which are high-end applications driven by AI demand.
OSATs accounted for slightly more than 50% of total orders, reflecting their increasingly important role in the advanced packaging ecosystem. Importantly, for the past several months, many of our customers have been securing delivery slots through 2027, providing us with strong visibility into sustained demand and continued growth.
We have seen this trend in all territories, including China, and we expect this strength in all regions to continue in 2027. For the first time in Camtek history, we have visibility extending approximately one year ahead.
This gives us greater confidence in our growth outlook. Looking ahead, we expect fourth quarter revenue of approximately $180 million, bringing our full-year 2026 revenue to approximately $595 million.
For 2027, we expect revenue to exceed $800 million, supported by our strong order backlog and sales pipeline. Moshe will provide more details on our financial outlook in a few minutes.
Let us briefly recap the key messages from our Investor and Analyst Day. First, we operate in an exceptionally strong growth market.
Advanced packaging, which is our core business, this market is growing faster than the overall semiconductor industry, while high-end advanced packaging for AI application is growing at an even faster pace. Second, increasing complexity create new opportunities for Camtek.
As advanced packaging becomes more complex, it require more inspection and metrology steps, as well as new tools with more advanced capabilities. Third, we have a clear competitive advantages.
Our advanced technology, combined with an install base of approximately 4,000 systems and strong, long-standing relationships with all leading customers, put us in excellent position to continue gaining market share. Looking ahead to 2027, we plan to introduce new AI-based software products, creating an additional revenue stream for Camtek and further strengthening our competitive advantages.
Fourth, we are ready to scale. Together with our manufacturing partner, who are already expanding their production capacity, we have strengthened our operational infrastructure to support significantly higher revenue level.
In the near term, like the rest of the industry, we are experiencing certain supply chain challenges involving a limited number of suppliers. We are working closely with these suppliers to address the challenges and expect to meet our customer delivery schedule.
All of this support our new long-term target: to double our 2026 revenue and reach $1.2 billion in annual revenue within approximately three years. Importantly, this target is based on organic growth, without factoring in new potential contribution from substantial M&A.
We recognize that this is an ambitious target, but we believe we have the right strategy, strong market opportunities, and the capability to achieve it, assuming the continued trend of our industry. We are fully committed to this goal and are working hard to turn it into reality.
Now, Moshe will review the financial results. Moshe?
Moshe Eisenberg
Thanks, Rafi. In my financial summary, I will provide the results on a non-GAAP basis.
The reconciliation between the GAAP results and the non-GAAP results appear in the table at the end of the press release issued earlier today. Third quarter revenues came in at a record level of $161.3 million, a 28% increase year-over-year and 21% increase compared with the second quarter of 2026.
The geographic revenue split for the quarter was as follows: Asia accounted for 95% and the rest of the world 5%. Gross profit for the quarter was $82.3 million.
The gross margin for the quarter was 51.1%, similar to the 51.4% in the previous quarter. Gross margin came in a bit lower than our expectations.
As Rafi mentioned, there is an industry-wide supply chain demand, which has not only created operational challenges, but also resulted in price pressure on parts, components, and material used in our system, affecting our COGS. We have already started to increase our ASPs, and we expect this to positively impact our gross margin already in 2027.
Further improvement is expected by higher share of our more advanced offerings and by offering new software products. Operating expenses in the quarter were $34.8 million, compared with $32.5 million in the previous quarter.
Most of the increase in operating expenses was in selling and marketing, in line with the higher revenue level. Our operating profit in the quarter reached a record $47.5 million, compared with $36 million in the second quarter and $37.6 million in the third quarter of last year.
Operating margin was 29.5%, up from 27% in the second quarter, reflecting the leverage we have in our model. Financial income for the quarter was $7.1 million, compared with $7 million in the previous quarter.
Net income for the third quarter of 2026 was a record $50.3 million, or 99 cents per diluted share. This is compared with net income of $39.4 million, or 78 cents per diluted share, in the previous quarter.
The total diluted number of shares as of the end of the third quarter was 51.5 million. Turning to some high-level balance sheet and cash flow metrics.
Cash and cash equivalents, including short and long-term deposits and marketable securities, as of September 30, 2026, were $877.1 million. We generated $71.1 million in cash from operations in the quarter.
Accounts receivable increased to $166.2 million, compared to $153.9 million in the previous quarter. DSO remained at similar levels of around 90 days.
Now to the outlook. For the fourth quarter of 2026, we expect revenues of approximately $180 million, up 40% year-over-year.
This will bring our full-year 2026 revenues to approximately $595 million, representing growth of about 20% over 2025. For 2027, based on our backlog pipeline and strong order momentum, our initial revenue outlook is more than $800 million.
Let me briefly remind you of our new target model. We are targeting $1.2 billion of revenues within about three years, substantially organic, with operating margin of 34% to 36%.
With that, Rafi, Ramy, and I will be open to take your questions. Kenny?
Kenny Green
Thank you, Moshe. We'll now open the line for question and answers.
If you have a question, please raise your hand on the platform. We will take our first question from Matt Prisco of Cantor Fitzgerald.
Matt, please go ahead.
Matt Prisco
Hey, guys. Thanks for taking the question.
I guess first on gross margins, just love to hear where we're tracking in 4Q, and then as we move into '27, could you perhaps walk us through the levers as we just think about those cost increases, the pricing increases, the new product mix, higher volumes, a lot of moving parts there. Can you help us just kind of walk through those?
Thanks.
Moshe Eisenberg
Absolutely, Matt. Indeed, we were a bit disappointed by the gross margin level, although we did implement cost reduction initiatives during the quarter, which will benefit us in the future as well.
At the same time, the product mix is also working in our benefits and our favor, and this will continue to favor us in the future as well. What happened this quarter was slightly higher parts and material costs that offset some of these benefits that will remain with us in the future.
Now our plan is obviously, and this is already in motion, is to increase overall ASPs in the market, and together with the software offering that bring to the table, and we plan to improve the gross margin already in 2027. Keep in mind also that over the last few quarters, the exchange rate also was not benefiting our business activities.
The shekel got much stronger against the U.S. dollars, which was slightly an overhang on the COGS cost structure overall and also in the COGS level.
This is definitely beyond our control, and we hope that next year that this will balance out. Did I answer your question, Matt?
Matt Prisco
That's perfect. Then as a follow-up, just can you give us an update on where orders stand today, any particular areas of strength across markets or systems that you would highlight?
Then as we think about that '27 outlook, how much of that is supported by backlog today, and how much upside is there given supply and component issues and all those things? Thank you.
Ramy Langer
Matt, this is Ramy. We are talking about an initial outlook of over $800 million, and definitely I think we cannot give more information at this stage.
We said in our prepared notes and when we met in October that the backlog is significant, and I think this is as far as we can go. To give you some color on the backlog and what we see in those $800 million, definitely we see a very strong, and we said, over 50% came from the OSATs, an area that we have a very strong position.
About 80% is coming from advanced packaging. All in all, our main segment is healthy, and we maintain a good market position, and I think all in all, all the trajectories are up, and we feel very comfortable with these numbers.
Kenny Green
Matt, thanks a lot. Our next question will be from Brian Chin of Stifel.
Brian, please go ahead.
Brian Chin
Hi there. Good afternoon.
Can you hear me okay?
Moshe Eisenberg
Yes, we hear you very well.
Brian Chin
Great. Thank you.
Thanks for the opportunity to ask a few questions. Maybe first, just to follow up on the order commentary, I guess one, to clarify, it seemed, based on that last comment from Ramy, a little bit more of a skew towards AI logic relative to HBM in terms of the booking.
Also, as you book into Q4 and really in the second half, based on sort of where lead times are for equipment, are you booking more towards maybe kind of mid-year next year, maybe even second half '27?
Ramy Langer
We are booking already the second half, and as we said, we have a very good visibility one year ahead of us. This is indeed the case.
I would say as a follow-up from where our discussion, definitely the business is strong across the different regions, including China.
Brian Chin
Great. I have a question about software.
I know that was one of the interesting topics from the Analyst Day a few weeks ago. I believe you mentioned this revenue stream could increase from sort of tens of millions per year to well over $100 million in that kind of three-year target model.
A few questions there. When you think about your 35% initial revenue growth outlook for '27, do you attribute maybe a few percentage points of that growth to software in terms of some of these new products?
Then just kind of thinking forward, is the idea here that you envision some of this AI-related and defect classification software to be effectively bundled with future shipments of Hawk or Gen 5 Eagles?
Ramy Langer
Let me first of all correct you. When we talked about the figure, it included software and service.
Service is growing very fast, the rate of about 35% a year, and has been growing in this respect, at this rate for the past few years, and we see it continuing to grow as a result of the much larger install base and our customers requiring more and more support as the machines are becoming more and more complex. This is one leg of the growth.
The second growth will come from software, and I think we have said in the past in the acquisition of Visual Layer, which brought us a lot of capabilities on AI, but in parallel, it is a platform to develop products that we expect to start to sell in '27, and I hope that even we'll see initial revenues in the first quarter of '27. Definitely combination of the software and the service is going to start to be significant already in '27, and we expect to reach the numbers as we said in the three-year target.
Brian Chin
Great. Thank you.
Kenny Green
Thanks, Brian. Our next question will be from Charles Shi of Needham.
Charles, please go ahead.
Charles Shi
Hey, thanks for taking my question. Want to follow up on the supply chain challenges.
Obviously have seen some of that impact in the reported quarter gross margin, but can you provide a little bit of background on what specific components are in shortage, and is it something more specific to, let's say, your tools, optics, light sources, or maybe it's just some simple things like PCBs or even memory components, etc.? Want to get some thoughts on what exactly is in short right now, and for us to get some sense for how long do you think the shortage situation will last, and when the supply can catch up and no longer being an issue going forward?
Thanks.
Ramy Langer
Thank you, Charles. Let me try and elaborate a little bit more.
These are not specific parts that are made for Camtek. These are general wide industry components.
I think you mentioned memories and CPUs, that's definitely today in shortage, and the prices are higher. This is not something new to anyone.
There are other general-purpose components that are in shortage, mainly on the handling part of the machine. We are working one with our vendors.
In most cases, we have dual sources, this is really a question how to balance between the different sources, make the first source less and bring in the second source. These are things that are in motion.
I expect these topics to be resolved, I would say within three to six months. I think it will balance off.
This is really my feeling. We're not sure about it, but I think we said in the prepared notes that we will not miss any delivery schedules.
We are doing every effort and working very closely with the vendors to keep our planning in place.
Charles Shi
Got it. Thanks.
Maybe a second question, maybe more on the advanced packaging, especially AI-related advanced packaging outlook between 2.5D and HBM. We know there are some unique situation on the 2.5D side, maybe just a '27 issue, maybe going to '28, not really an issue, but on the HBM side, what are you seeing today?
Cuz since the SEMICON West event, a few of the packaging, especially the bonder companies reported, at least there's one thermal compression bonding company saying they are seeing some PCB delays for HBM packaging build-out, wondering what you're seeing there. Maybe you're seeing some offsetting factor, maybe that's not a good read-through to Camtek, but wonder if you can address those issues that has been discussed for a couple of weeks among the investment community.
Thank you.
Ramy Langer
I'm trying to think about your question, but we do not see any change to our plans or predictions. I think we're on track with all the customers in the HBM area, I cannot bring you any more information or anything new based on your question.
Charles Shi
Thank you, Ramy.
Kenny Green
Thanks, Charles. Our next question will come from Michael Mani from Bank of America.
Michael, please go ahead.
Michael Mani
Hi. Thanks so much for taking my question.
To start, nice to see that Hawk and Eagle G5 are more than 55% of sales at this point of the year. If you were to kind of reflect back on the last couple of quarters, were there any areas where maybe your share gain or traction in those new categories progressed faster or better than expected, and what does that tell you about your confidence level in where you could potentially gain share next year in 2027 to deliver upside to that $800 million full view that you gave a couple weeks ago?
Ramy Langer
Indeed, the position in the market continues to be strong. Talking about share in '27, gaining share, it's a little bit too early, as I said previously.
It's really an initial outlook when we talk about '27. I think it's too early to talk about gains.
I think that we are performing very well at our customers, as we see. I think we will definitely maintain position.
I also hope that we will gain share, but it's too early to say in which areas.
Michael Mani
Got it. Thank you.
For my follow-up, just wanted to ask about the OSAT market. I know this has come up repeatedly, but in the last few months, we've heard your peers become more vocal about being able to enter this space.
Obviously Camtek has had a very established position there for a long time and has seemed to defend that for the most part pretty well. When you look at each of the different players that are sort of participating now, whether it is the local Chinese suppliers who are looking to displace Western incumbents to take share, whether it's the smaller process control peers in your ecosystem, whether it's KLA, what do you think is the Camtek value prop against each of those different competitors?
Why do you think your moat is intact from each of those players? When you think about why more competition is coming to the space, do you think it's more of a fact that your customers are looking multi-sourcing away from Camtek, or is it more just to cure a very sort of temporary shortage situation in that market because there simply isn't enough capacity out there to address all the demand?
Thank you.
Ramy Langer
All right. Let me first of all address the competitive situation of many Chinese players.
We do not see any competitive threat from those small competitors in China. We maintain a very strong position, and we expect, if we talk about share gain, we definitely think that China is a place that we can continue and gain share.
This, I would say, about the lower-end competition. I think when you talk about from the other side, that you see the bigger players that are trying to enter the market, and I think this is something that we have seen.
I think the market is becoming lucrative and growing, definitely people are thinking of maybe we can get some share. This is natural.
We never expect that it will be different. I think when I look at our products, the competitiveness, our responsiveness as a company, the products were designed for customization for the dynamic advanced packaging market, that is very, very important.
We hold a dominant position at the OSAT market, and I think will be very difficult for the larger players to enter. I think what is very important is that we have a proven portfolio with dedicated solutions for the advanced packaging.
This includes bump metrology, where we hold a phenomenal market share, includes things like flexible handling, large-scale inspection, and we can continue and talk about it. When you think about it, the larger players do not necessarily have all of these capabilities, and it takes a lot of time to develop it, while we're developing new and other capabilities that are required.
All in all, when you talk about the larger players, I think we discussed it in previous meeting, they're bigger than us, but in the specific market that we play, we're significantly larger.
Moshe Eisenberg
I just want to add one point, Michael, regarding the Chinese market and the domestic, potential domestic competition. I would say that in the last few months, we enjoyed a nice order momentum across the board and specifically in China.
When I look today in our backlog for '27, China will represent a meaningful piece of our business, at least as high as this year. I think that the competition in China does not play a major role in our business at the moment.
Michael Mani
Great. Thank you so much.
Kenny Green
Thanks, Michael. Our next question will be from Jim Schneider of Goldman Sachs.
Jim, please go ahead.
Jim Schneider
Good afternoon. Thanks for taking my question.
I was wondering if you could maybe, as we think about 2027, help us with how you see the linearity of 2027 playing out. Obviously you have much better visibility into the first half than the second, as you mentioned, but should we think about sort of sequential step-up in revenue in the first couple quarters of the first half, and then flattening out into the back half, or maybe any help on that would be helpful.
Thank you.
Ramy Langer
Trying to look, and as I said, it's really an initial outlook. I think the business will be stable.
We're starting to fill the shipments, the capacity as we speak, and as I said, we're already booking a lot of orders for the second half of '27. At least when I look at it, I think it will be stable.
It's initial, it's I would say balanced capacity growth over the fourth quarter, but definitely we are in a very good situation, which we're actually filling already slots in the second half.
Jim Schneider
Thank you. Then, can you maybe talk about the gross margin profile?
Obviously you have mix in your favor. At the same time, you talked about the input cost headwinds.
Can gross margins start to improve further as we get into the back half, or is it too early to call on that?
Moshe Eisenberg
Yeah. The expectation is that gross margin will gradually improve starting from the first quarter of '27.
Again, as I said before, it's a combination of the cost reduction initiatives that are already in place, the favorable product mix that we have, as you saw, already 55%, over 55% of our revenues are related to the high-end products, which carry higher gross margin. I believe that this short-term supply chain constraints will be balanced out.
Starting from Q1, we will see a gradual improvement, together, by the way, with the contribution of the software and the service business that is starting to pick up. Ramy mentioned that we are already looking to see some initial software business in the first quarter.
Gross margin, bottom line, is expected to gradually improve starting from Q1 of '27.
Jim Schneider
Thank you.
Kenny Green
Thanks, Jim. Our next question is from Ed Yang of Oppenheimer.
Ed, please go ahead.
Ed Yang
Hi, guys. Thanks for taking my question.
The first one is, can you size the ASP increase you're contemplating, and maybe talk about initial customer receptivity to that, and was that always embedded in your $800 million revenue view, or is that incremental?
Ramy Langer
I don't think we can say now whether it will be incremental or included. It's really too early.
Let me talk about raising prices. There are two aspects here.
We understand, and I think our customers understand, that due to the increase in prices of components, there will be some increase in the ASPs. I think this is understood, and this is starting, we're starting to implement it, and this will, I think, will gain momentum in the next quarter.
Second aspect is implementing new capabilities into our machines. Definitely this is the area where we can explain to our customers, and our customers are receptive to pay more for a more capabilities on our machines.
We're working on both fronts: raising some due to the increase in prices, our own prices, but I think on a greater scale, getting the new capabilities, the new developments that we are implementing in our machines are reason for additional price increase. These are the two things that we are going to do during 2027, and actually we've already started this year, but it will gain momentum in 2027.
Whether this will be in the 800 initial outlook or not, it's too early to say. I do hope that there is some upside to these numbers as we will go more into next year, but this is something that still has to be seen.
Ed Yang
Great. Thank you, Ramy.
For my follow-up, we're starting to see some demand headwinds in consumer and non-AI electronics, and could you just remind us, do you have any exposure there? I know in the advanced packaging bucket of your business, there is a piece, primarily mobile, I think, that's not high-performance computing related.
Are you seeing any similar softness in that line item?
Ramy Langer
No, we do not see any softening. Yes, there is some piece when we talk about the conventional advanced packaging, which is anywhere in the range of, I would say, 15% in average per quarter.
No, no, we don't see any headwinds, not at this stage.
Ed Yang
Thank you.
Kenny Green
Thanks, Ed. Our next question will be from Craig Ellis of B.
Riley. Craig, please go ahead.
Craig Ellis
Thanks for taking the question, and good afternoon, team. I wanted to ask a few to better understand what we're seeing in our calendar year '27 outlook.
I know at our analyst breakfast at SEMICON West, we talked a lot about hybrid bonding. The question is, hybrid bonding material in that $800 million outlook for '27, or is it really an opportunity that the company sees filling in three years down the road when we're looking for $1.2 billion?
Ramy Langer
The hybrid bonding, there is a lot of development today being done. Yes, we are seeing some business, but really on a low magnitude at this stage.
I believe that this is business that will start to materialize more in the '28 and onwards. I think in '27, I don't expect to see any substantial business coming from hybrid bonding, but as we said in the previous meeting, definitely we have a roadmap to address this market, and we believe that this is an opportunity for us.
Craig Ellis
Got it. Sticking with what's potentially in '27 and where there's additional opportunity beyond the orders that you have in hand now, if we were to categorize potential incremental business as either, A, custom ASICs or XPUs, B, work from semiconductor companies with specific GPU and similar programs, or three, HBM, where do you think there's the most opportunity from what you have in hand today to add to orders for next year?
Ramy Langer
I think the main opportunity for us is to gain market share in 2D for additional steps. This is not really specific that I can tell you whether it's a GPU or HBM or, it's very hard for me from the top of my head to try and assess it.
Definitely, I think, and we discussed it, we have strong portfolio for 2D inspection, but still I think there is a lot more business that we can gain there, and we are putting a lot of focus in this area. I believe if there is upside potential, it will probably come from this area.
Craig Ellis
When do you think you might be able to convert that pipeline activity to orders? Is that something that you see progressing through the fourth quarter, or are these longer-term engagements that might convert one half or mid-year next year?
Ramy Langer
I think we said in the prepared notes, and Moshe also mentioned, that the order momentum continues. At this stage, what we're seeing from our customers, that ordering and really securing deliveries next year.
I think this is, if I would try to put some color on the kind of business that we are, it's really getting and securing slots in 2027. I think this we will see until the end of this year.
I think new upsides, if there will be, I think this we will see in the first and second half of 2027.
Craig Ellis
Very helpful. Thanks, team.
Kenny Green
Thanks, Craig. Our next question will be from Shane Brett of Morgan Stanley.
Shane, please go ahead.
Shane Brett
Great. Thank you for letting me ask a question.
My first question is on services. I want to ask Brian's earlier question on software in a different way.
If I think about the bridge from your service revenue this year of about $40 million to your $140 million target in three years, just how much new software revenue are we adding into the model? Apologies if you've mentioned this previously, but how much software revenue did we have this year?
Thank you.
Moshe Eisenberg
Let me start, Ramy. Our service business, as you indicated, is around $40 million this year.
It's growing at a rate of 35% to 40% annually. Within three years, we will be able to reach around $100 million of service revenues from the existing business, together with obviously the install base that will get bigger.
Additional $40 million was assumed with new software offerings. At this point, we have pretty much zero software offerings.
This will start in next year, in 2027, already in the first quarter, and should gain momentum. We believe that there is potential upside to the $40 million that we've mentioned.
Ramy Langer
I would like to add that we see the software business is going to already be significant next year. I'm expecting double-digit revenues in 2027, and this business has the potential to grow.
We have the platform, the capabilities. We already have some products in the pipeline that we started to introduce to customers, and I expect to gain momentum in this area starting the first quarter of 2027.
Shane Brett
Got it. That's really encouraging to hear.
For my follow-up, your comments on your 3D bump metrology inspection, 3D bump metrology portfolio for HBM from your investor breakfast was very convincing, but just could you help us quantify how much of your HPC revenue will be coming from HBM this year? Is that mix within HPC, sorry, HBM mix within HPC going to go higher or lower for you next year?
Thank you.
Ramy Langer
I'm feeling what the last numbers that we mentioned. I think at the time what we mentioned, and it was two quarters ago, we said that we received $600 million in orders since the beginning of the year, and we said that the HBM was over 20%.
It's going to be significant, and we didn't continue to add it because the order flow on what we call the high-performance computing, the CoWoS and CoWoS-related applications, they don't come together. It's different streams of orders.
I expect that the HBM business, both for inspection and 3D metrology, will be significant in 2027. I cannot comment at this stage on exactly the magnitude.
Shane Brett
Got it. Thank you very much.
Kenny Green
Thanks, Shane. Our next question will be from Vedvati Shrotre of Evercore.
Vedvati, please go ahead.
Vedvati Shrotre
Hi. Thanks for taking my question.
The first one I had was, as we go into 2027, you're seeing the order momentum, but at the same time you're seeing some of the component supply chain constraints creep in. Can you talk about the lead times and how the lead times for your tools have changed?
Have they started to stretch now versus last quarter?
Ramy Langer
I think these are two separate issues. The components issue, it's more I would say of a tactical issue that some of our vendors are just don't have enough capacity, and we need to use second sources, and to overcome, and this is a short-term.
I expect that this will be for one or two quarters, maybe it will be longer, but I'm expecting us to resolve this situation specifically, and I think Rafi said it in his prepared notes. I think in general, because of the level of orders intake, definitely our lead times are increasing, and typically they are three to six months, but in some cases, customers are willing to give us today orders a year ahead, and this is not that they necessarily need the machines today, they just want to secure capacity on our floor for the time that their clean rooms or whatever they need, they want to secure this capacity, and that's the reason that they're already placing orders today.
Vedvati Shrotre
Understood. Then for my second question, you mentioned the Eagle G5 and Hawk is more than 55% of revenues this year.
What happens next year? Does that become a majority, is that 80% and up is that a good estimate on the contribution from these tools next year?
Definitely
Ramy Langer
this will be more than 55% next year, and whether it will reach 80%, it's a question that's very hard to answer. The reason for that, that certain customers do not want to change the machine in production if they have a very quick ramp and they don't want to qualify new machines.
This is really something that is also related to customers. I do expect an increase in the percentage of these products, but I don't know if they will get to 80%.
Eventually they will, but I'm not sure that it will happen in 2027.
Vedvati Shrotre
Understood. Thank you.
Kenny Green
Thanks, Vedvati. That brings us to the end of our question and answer session.
I just would like to remind everybody that a recording of this call will be available from Camtek's investor relations website in the coming hours. Also the Zoom link will also have a link.
I hand back to Rafi for his closing statement.
Rafi Amit
I want to express my gratitude to all of you for your ongoing interest in our business. I look forward to our next conversation in the upcoming quarter.
Thank you, and goodbye.
Kenny Green
That ends our call. You may disconnect.
Thank you very much.