Chord Energy Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good morning, ladies and gentlemen, and welcome to the Chord Energy Third Quarter 2026 Earnings Conference Call. At this time, all lines are in a listen-only mode.
Following the presentation, we will conduct a question-and-answer session. If at any time during this call you require immediate assistance, please press star zero for the operator.
This call is being recorded on Thursday, November 5th, 2026. I would now like to turn the conference over to Bob Bakanauskas, Vice President, Finance.
Please go ahead.
Bob Bakanauskas
Thanks, Julie. Good morning, everyone.
This is Bob Bakanauskas, and today we're reporting our third quarter 2026 financial and operational results. We are delighted to have you on the call.
I am joined today by Michael Lou, our CEO; Darrin Henke, our COO; Richard Robuck, our CFO; as well as other members of the team. Please be advised that our remarks, including the answers to your questions, include statements that we believe to be forward-looking statements within the meaning of the Private Securities Litigation Reform Act.
These forward-looking statements are subject to risks and uncertainties that could cause actual results to be materially different from those currently disclosed in our earnings releases and in our conference calls. Those risks include, among others, matters that we have described in our earnings releases, as well as in our filings with the Securities and Exchange Commission, including our annual report on Form 10-K and our quarterly reports on Form 10-Q.
We disclaim any obligation to update these forward-looking statements. During this conference call, we will make reference to non-GAAP measures, and reconciliations to the applicable GAAP measures can be found in our earnings releases and on our website.
We may also reference our current investor presentation, which you can find on our website. With that, I'll turn the call over to our CEO, Michael Lou.
Michael Lou
Thanks, Bob. Good morning, everyone, and thank you for joining us.
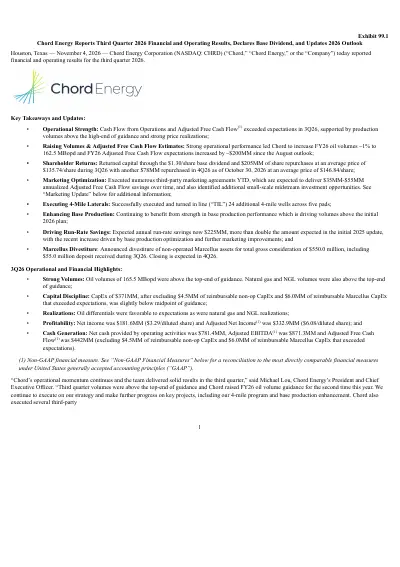
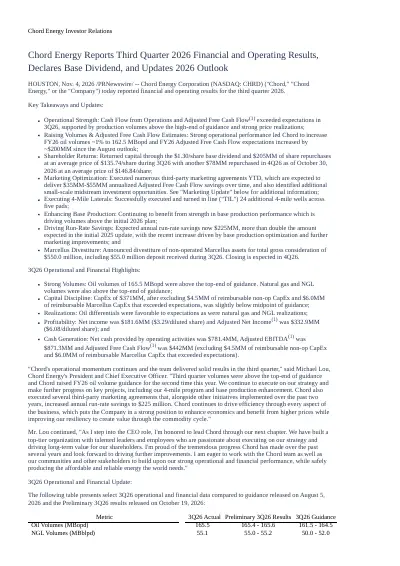
Last night, we issued our third quarter press release and presentation with details on our strategy, operations, and financial performance. As this is my first earnings call as CEO, I'll start with a few thoughts on Chord's progress over the past several years and our priorities going forward.
I'll then review our quarterly results and outlook before we open the call up for questions. For more than five years, I've had the pleasure of working closely with Danny Brown to build a strong foundation for Chord.
Danny's been an incredible leader and a good friend, and I wish him all the best in his next adventure. Over the past five years, through volatile energy markets, the Chord team has strengthened our competitive position and delivered value for our shareholders.
Today, Chord is a more resilient company, positioned to withstand downturns and create value through the cycle. Continuous improvement has been central to that progress.
Our talented team is committed to getting better every day, and our results reflect that commitment. As shown on slide 9 in our presentation, we have grown free cash flow per share by roughly 35% over the past two years on a price-neutral basis through disciplined capital allocation and driving operational excellence.
Over a five-year period, Chord has driven 11% annual growth in oil production per share. This growth has been delivered while we have built a large, resilient production base with low declines, which translates to a low reinvestment rate and higher free cash flow generation.
We have also preserved a deep, low-cost inventory and improved its quality through optimized spacing, longer laterals, faster cycle times, and disciplined acquisitions. Over the past five years, we've completed five acquisitions in the Williston Basin, becoming the largest acreage holder and producer in the Bakken.
These transactions varied in size and scope, but we successfully integrated the assets and captured substantial efficiencies. We also streamlined our portfolio by divesting non-core assets at attractive valuations and reinvesting the proceeds in areas of competitive strength.
Together, these efforts have generated strong, sustainable free cash flow, which alongside sizable share repurchases, significantly increased production per share. We achieved this growth while returning substantial cash to shareholders through dividends and maintaining a strong balance sheet.
Looking ahead, our priorities remain consistent. We will apply the same capital discipline to organic investments and acquisitions.
We will continue to improve performance across the business and evaluate every investment through the lens of shareholder returns. A strong balance sheet will underpin this approach, providing downside protection and the flexibility to pursue opportunities countercyclically.
Turning to the third quarter. We delivered solid operating performance, generated free cash flow above expectations, and returned substantial capital to shareholders.
We also advanced strategic initiatives that we believe will strengthen the business and enhance long-term free cash flow generation. Adjusted free cash flow was approximately $442 million, the majority of which we returned to shareholders.
Beyond our base dividend of $1.30 per share, all capital returned was through share repurchases. Since announcing the Enerplus combination in 2024, we have reduced fully diluted shares outstanding by approximately 10.8 million shares, or 17%.
Said another way, we have repurchased over half of the equity issued for that transaction in a little over two years. Throughout 2026, the Chord team has driven wins across the organization.
This leads us to a fourth quarter volume guidance that is well above both our August expectations and consensus estimates. We've also been seeing more favorable pricing, reflecting external factors and lower marketing fees.
We updated our capital outlook to reflect increased operated and non-operated activity and an additional $20 million of investment in midstream projects. The operated activity is up a bit due to drilling and completion efficiencies, which are leading to a couple more TILs on the year, and the non-operated activity has picked up over the last few months as well.
Turning to continuous improvement initiatives, Chord has made further progress in reducing our marketing costs as the team continues to simplify and optimize contracts across oil, gas, and water. Our latest efforts are expected to deliver $35 million to $55 million in annual savings.
These savings are incremental to those announced a year ago, bringing the total annual savings to approximately $85 million. On the production side, Chord continues to have success with a wide variety of projects aimed at optimizing its large PDP base.
The team has done an amazing job getting more out of the base, and that production continues to outperform. One of the things the team has been focused on and continues to test are various chemical treatments across a broad population of wells, and we expect to determine which treatments to incorporate into our 2027 program by early next year.
Our drilling and completions team continues to improve execution and set new records. We're making progress drilling more of our 4-mile wells in a single run, while frac productivity is improving and cleanouts continue to reach total depth.
As of quarter-end, the company has TIL'd 47 total 4-mile wells. Execution and production results continue to be in line with expectations.
Slide 6 in our presentation shows the progress of all the continuous improvement projects across the company. The Chord team has delivered $225 million of incremental free cash flow generation over the past two years from controllable items, including higher production, better capital efficiency, and improved marketing costs.
Thank you to each person on the Chord team. This is an incredible team effort that has driven a ton of shareholder value.
Far in 2026, we have raised oil volume guidance twice, supported by strong execution and base production optimization. Looking ahead, we are confident in our ability to sustain strong production levels in 2027 and plan to provide detail of our next year's program in February.
Finally, we recently published Chord's 2025 Sustainability Report as part of our commitment to transparency. I want to thank the team for its work on the report, which highlights our efforts in emissions reduction, workforce health and safety, corporate governance, philanthropy, and other areas.
We remain committed to producing affordable, reliable energy in a responsible and sustainable manner. With that, I'll hand the call over to Julie for questions.
Operator
Thank you. Ladies and gentlemen, if you'd like to ask a question, please press star one on your telephone keypad.
If you'd like to withdraw your question, press star two. One moment, please, for your first question.
Your first question comes from Josh Silverstein from UBS. Please go ahead.
Josh Silverstein
Thanks. Good morning, guys.
Nice update on the operational front here. With the better base performance, longer laterals, the faster cycle times, and going more and more toward the 4-mile laterals now, can you talk about maybe what the company's maintenance capex requirements look like?
It seems like it's structurally coming a bit lower, especially with some of the other cost savings.
Michael Lou
Josh, thanks for the question. Certainly, the team's done an incredible job this year.
You'll notice that we've increased guidance a couple times this year on the oil side, on production, starting at 159, going to 162.5. A lot of that's kind of productivity and efficiencies kind of throughout the program.
The base business has done a great job of outperforming on just every well that we currently have in the ground. On top of that, the 4-mile laterals has driven efficiencies.
We've certainly seen a small amount of inflation this year that we've been able to counteract with continued efficiencies this year. All that's been really positive.
That our capital program is kind of on a blended basis now, 146. It's up a little bit because of the additional capital that we're spending a little bit on midstream with some of those opportunities coming around, our efficiencies on the D&C side that allows us to do a few more TILs on the operating side, and a little bit more non-op.
We've had about 30% increase in rig count in the basin over the second half of this year. We're certainly seeing some other operators picking up activity, and we're participating in a little bit more on the non-op side.
All that leads to capital now kind of at that 146 level. It's a little bit higher than where we were at the beginning of the year, but our production is up as well.
That's a good kind of level for this year.
Josh Silverstein
Got it. Then just wanted to think about how you're balancing the free cash flow allocation.
Obviously, a very strong year for oil pricing. You highlighted the continuation of the buyback into the fourth quarter as well.
Just given where the balance sheet is, should we still think about maybe 75% of free cash flow going to shareholder returns? Do you want to build up some cash, just in case oil prices continue to come lower?
How are you thinking about that rate of return? Thanks.
Michael Lou
Good question on the capital allocation side. Obviously, I think we've had a strong focus on that over the last five years, and we'll continue to have that going forward.
As you mentioned, we've got a lot of different levers that we can think about, whether it's this year, certainly since the early part of this year with oil prices up. One of the things is thinking about are there short-cycle kind of projects that we can bring forward?
Volumes, you're seeing a lot of that in a lot of the base work that our team's done. We've been able to do some good acquisitions.
We've, in that timeframe, though, even after the most recent acquisition late last year, brought our balance sheet back in under half a turn of leverage. Now we're back into that 75%-plus of return going back to shareholders, we'll continue to lean into that side.
Then with a good sales of non-core assets in the Marcellus that should close later this year, we'll be in a great position, no matter what the cycle brings. Obviously, we're seeing some volatility in oil prices over the last short while here, but we think that we're going to continue to be in a constructive environment, and we're in great shape on that front.
Josh Silverstein
Thanks, guys.
Operator
Your next question comes from Scott Hanold from RBC. Please go ahead.
Scott Hanold
Thanks. Good morning.
Michael, congrats on the promotion. You've been with the Chord entity a long time, and you gave just some high-level thoughts on Chord's future, but I'd be more interested to hear strategically do you see the business any different, and if you can layer in thoughts about does it make sense for Chord to stay within the Bakken, or, longer term, do you see optionality of stepping out at any point in time?
Michael Lou
Scott, I don't think anything really changes from the way we've been messaging it over the last few years. I think that we're the largest producer in the basin right now.
We also have kind of a vast acreage position kind of across the basin. The nice thing for us is that we see we're 13%, 14% of the basin today in terms of production.
We've still got a lot of room to run to continue to consolidate the basin. We think there are some interesting opportunities that could present themselves over the next few years, and we want to kind of make sure that we have a balance sheet that's ready for that, that we think that we're probably the natural consolidator in the basin.
We think that we can drive more efficiencies than anybody else. We have more overlap than anybody else in a number of these positions.
We think that there's just a lot of opportunities in front of us in the basin. We'll always look at things outside the basin, but we've been doing that for five years, and if you look at kind of track record, we've done five deals, and they've all been within the Williston.
That's where we know what we can drive in terms of value. I don't think the change will be any different.
In the meantime, our focus continues to be on what we have in front of us, and we've talked about that continuous improvement side, and we've got to get better every day on our asset. As we do that, it gives us more of the right to be the consolidator in the basin going forward.
There's going to be a continued focus on just getting better every day in that continuous improvement side.
Scott Hanold
Appreciate that. My follow-up question is a little bit on 2027.
I know you're going to give guidance next year, I won't kind of pin you down to that or anything like this, but your base production has improved quite a bit this year. It looks like at least 3,000 barrels a day.
As you kind of think of the current environment we're in and your prior view of 159 being sort of that baseline level for you all, how do you think about that? That base improvement, should we add that to the prior 159?
Is that how we should think about it, or does that provide you an opportunity to flex down in case something on the macro side becomes uncertain?
Michael Lou
I think we'll always look at what the right thing to do is on that capital allocation side. Obviously, if our shares, we think are in a great place to buy back right now, but if you saw massive weakness in oil price, and capital costs don't come down in the same proportion, and should we allocate more to buybacks, or should we allocate more to the drill bit?
We'll make all those decisions going forward. Right now, we think there's good visibility on some of those production improvements, and we see good visibility on kind of holding that new, call it 162.5 flat going forward.
That's I think what we're looking for next year. We're seeing that base performance really being replicated longer term.
Scott Hanold
That's great. Thank you.
Michael Lou
Thanks, Scott.
Operator
Your next question comes from Gabe Daoud from Truist. Please go ahead.
Gabe Daoud
Thanks, operator. Morning, Michael, and congrats on the promotion.
Was hoping we can maybe start with the marketing upside that you guys have articulated through some renegotiations. I guess, curious if you can maybe frame what the realized run rate is today and how much additional benefit maybe kicks in next year and what drives the ramp towards that high-end number that you guys highlighted?
Richard Robuck
Hi, sure. That's a great question.
I think we've been talking, this is Richard, for some time now about the fact that this organization was put together over the past decade and a half with a bunch of consolidation in the basin where there's small players that have come together, and then we brought together, obviously, kind of the three largest companies in the basin. Over time, each one of those organizations was putting in marketing contracts.
Most of those got put in place in the early 2010s through 15, and they were kind of, call it, 10, 15-year deals. Then over time, they start to expire, and with the consolidation, you just have a lot more flexibility: one, to pivot around with your rigs, to pick and choose the best places to drill from a rock perspective as well as a marketing economics perspective; and then two, you have the ability to put together and optimize around the contracts that you do have.
That whole while, as we were consolidating the basin, a lot more midstream infrastructure was being put in place and being built by all the different midstream folks that you know well that are playing in the basin. With our efforts with the expiring contracts and then just the consolidation we have done, we've had a ton of success.
We announced the incremental uptick today. The way we've articulated that is on an annualized run-rate basis.
A fair amount of what we announced on an incremental basis today is going to be work through this year, early next year. Then there's probably a quarter of it that's still to come in the late '27, '28 timeframe.
There's still stuff that we have put into place that won't occur until a little bit out in time. The marketing team has done an amazing job optimizing on that front, and we still see that there's room to go from the perspective that there's still contracts that are coming due, and the team is trying to optimize around that.
Gabe Daoud
Thanks, Richard. A quick follow-up to that is, and so most of it lands in the GP&T line item, is that fair?
There's maybe more downward pressure on the 2.60?
Richard Robuck
A piece of it is there, obviously. I'm not trying to be opaque, but it is there, but you also see it in realizations as well on the NGLs and gas side, so that's a component of it.
You'll see it on the GBT, and then to a lesser extent, you'll see it on the LOE side as we work on the water contracts as well.
Gabe Daoud
Got it. Okay.
No, understand, just given the contract structure, it can land in different buckets, but that's helpful. Then just my follow-up, guys, is just maybe an update on your 4-mile lateral program.
You noted 47 have been TIL'd to date. Just any maybe updated learnings on the productivity side?
Is it still more or less tracking how you thought the wells would do relative to 2-milers?
Darrin Henke
Gabe, this is Darrin. The 4-mile wells are performing right like we'd expect.
We're drilling them a little bit quicker than what we were earlier in the year. Our drilling costs are down about 9% since the first quarter, and the production performance is as expected at this point.
We're probably a year away from really figuring out what's the full contribution on that last mile, that fourth mile, but to date, all of our tracers are showing recovery clear to the toe. We've cleaned out every single one of our 4-mile wells to the toe, and the team's just performing flawlessly, no surprises there at this point.
Gabe Daoud
Awesome. Thanks, Darrin.
Thanks, everyone.
Darrin Henke
Thanks, Gabe.
Operator
Your next question comes from Kevin MacCurdy from Pickering Energy Partners. Please go ahead.
Kevin MacCurdy
Hey, good morning, and congratulations, Michael. My first question is on the non-op.
Maybe you can give a little bit more color on the size of the non-op increase, and are there indications that that's going to kind of persist into 2027?
Michael Lou
Think about this. We had about a 30% increase in rig count towards the second half of the year.
A lot of other operators with the higher oil prices picking up rig activity, and so what it's doing is it's driving some of that late in year non-op activity that's driving that. With a healthy oil price, I would assume that some of that stays into next year.
Obviously, through a full-year program, we can flex a little bit with our operated program to kind of manage that. Some of this late in year stuff is a little bit more difficult to manage.
They're good projects, right? We're in a constructive oil price.
This is in areas that are good areas that we want to participate, they're good returning projects, we'll participate here at the end of the year. Is that a little bit of that color?
Kevin MacCurdy
Great, I appreciate that. That's helpful.
Then as a follow-up, and I don't want to get too cute on forward guidance, but just the additional capex that you're spending in fourth quarter, and maybe the two new turn-in-lines and the non-op, does that help the kind of decline that we've seen into first quarter over the past couple years at Chord, maybe kind of keeping your production more level-loaded?
Richard Robuck
Kevin, I think that's a great question, but the reality is, we dropped that second frac crew, and so we've been coming down. Our entry to exit, if you will, for even the fourth quarter is, I'd say, higher to lower.
December is going to be the lowest month of our fourth quarter guide, and that's going to trail into the first quarter as well. Then we'll start the frac crew, but we're doing primal fracs and multi-well pads, and so you really won't see, I would say, the pickup until the second quarter.
Like in the past, you'll see 1Q dip, and then we'll start to climb in the second and third quarter. That's a typical program the way that we've been laying out over the last few years.
Kevin MacCurdy
That's helpful. Thanks, guys.
Richard Robuck
Thanks, Kevin.
Operator
Your next question comes from Bert Donnes from William Blair. Please go ahead.
Bert Donnes
Hey, congrats, Michael. Looking forward to seeing what you do with the assets.
Michael Lou
Thanks, Bert.
Bert Donnes
Then on the pull forward of capex on the midstream side, I just want to make sure I understood. I think I heard it described as kind of supporting next year's program, but then, obviously, you guys are holding flat for now at least.
Was that spend to support the flat program, or does that set you up for potential growth next year?
Michael Lou
That midstream capital, think about what Richard was talking about in terms of work with other midstream guys. We've got contracts that are coming up, and we can blend and extend, we can renegotiate, we can go with new providers, there's a lot of different things we can do.
In areas that we feel like we're not getting the best rates, we can do some of that ourselves as well. What we've found is that there's some of these areas where we're doing some of that ourselves, and it's just a little bit higher as we think about stuff that we're setting up for '27.
That's just to support the current program.
Bert Donnes
Got it. It sounds like it was going to happen anyway, you're just moving where the capital's coming from.
Is that right?
Michael Lou
Some of this can happen, or if you get good third-party rates, we're happy to go with third parties, too. It's just some of it's just opportunistic based on what we're seeing in the market and whether or not we're getting kind of aggressive, fair rates from others or if we should do some of that ourselves.
Bert Donnes
Got it. Makes sense.
Then kind of around M&A, but not directly, it's our understanding that Chord isn't the only company that's maybe looking to make an acquisition or expand in the Bakken. Is there any interest because you have 10 years of inventory that maybe pulling in a JV or a carry, and maybe have your capex budget unchanged, but have someone else kind of foot the bill for that tail-end inventory at the end of your stack?
Michael Lou
Good question. It's always about capital allocation, if we find good ways to think about getting better returns for our shareholders, we'll consider everything.
We look at all sorts of stuff all the time.
Richard Robuck
I think it's also fair to say, when you look at the best operators in the basin, we would say we are the best operator, I think we really like to drill and complete our own wells because of this strong economics that we deliver. There are times on a PV basis you might think about it differently, but that's definitely a consideration on how good the team is doing here.
Bert Donnes
Got it. Thanks, team.
Michael Lou
Thanks.
Operator
Your next question comes from Noah Hungness from Wells Fargo. Please go ahead.
Noah Hungness
Morning, Michael, and congrats on the new role.
Michael Lou
Thanks, Noah.
Noah Hungness
For my first question here, I wanted to ask on just well cost inflation, just how you're seeing leading well costs for your 2, 3, and 4-milers, what are they now and how has cycle times kind of offset some of that inflation?
Darrin Henke
This is Darrin. Year to date, we've seen kind of low to mid-single digit types inflation, and through the team's performance, we've been able to offset that with efficiency gains.
As far as specific drill times, I mentioned earlier that we have reduced our drilling costs on our 4-mile wells about 9% since the first quarter. Our frac efficiency year to date, as far as when you think about how many feet per day that we are fracking, that's gone up over 20% year to date as well.
We're actually fracking over a mile a day on average at this current time. Definitely seeing inflation, but the team's done a great job offsetting it with efficiencies, and depends upon commodity price environment next year and what environment we're in, but our team's done a great job historically of offsetting inflation with efficiency, and wouldn't expect anything different at this time looking forward.
Noah Hungness
That's helpful. Then my second question is a bit of a clarification question around the second frac crew that you guys have spoke about that could come back in late '26 or early '27.
Could you just maybe talk about what would drive it to come back earlier rather than later?
Darrin Henke
Really just a function of availability. The frac crews are tight in our industry, and we've contracted that crew.
It's been awarded, and it's really just working with that service provider on their timing and availability relative to the work that they already have scheduled roughly through the end of the year.
Noah Hungness
If it does come back in late '26, does that impact the TIL count that you guys provided on slide 23, or would the TILs still be a '27 story?
Richard Robuck
I would think about that in terms of a frac has a lot of work to do before you bring it online, it's not going to change that piece of the business.
Noah Hungness
Cool. Thank you.
Richard Robuck
Thanks.
Operator
Your next question comes from Oliver Huang from TPH. Please go ahead.
Oliver Huang
Good morning, all, and thanks for [unclear] on another. Good morning.
Just a quick one on hedge philosophy. [unclear] low, leverage [unclear] certainly provided some risk premium.
[unclear]
Richard Robuck
Sorry, Oliver. You're kind of breaking up here.
If you try to repeat the question, otherwise we may have to pick it up offline. You kind of broke up there.
Could you try to repeat it?
Oliver Huang
Being layering on several quarters now. Leverage is pretty low, the war [unclear] is the target that you would want to get to for 2027 and '28?
Richard Robuck
Oliver, this is Richard. We were struggling to hear you.
My hope is that everybody else can hear us, and so I'm going to proceed along those lines, and you can follow up with your question if I didn't address it to what you were looking for. Generally, we've had the same hedge philosophy over the past few years, which is when oil price is higher, hedge more; and when oil price is lower, hedge less.
Then in the near term, we're going to hedge a little bit more, and then over time, we're going to hedge a little bit less. Obviously, with the strength of the balance sheet that we have, we don't have a need to protect the way that others might need to protect if they have a higher leverage.
We're in a really great position there, but we think that it is just prudent to have the discipline on the front end to say, if oil is moving up, start leaning in; and when it's moving down, lean out. It prevents you from times like when we entered the year and oil was $57 and it seemed to be sort of $57 to $60 flat forever, to not go layer in a bunch of hedges, and then to bet that somehow a conflict like we're living in sort of today would last forever as well.
We just have a disciplined hedge program that's instructed both by our balance sheet as well as just trying not to speculate on where oil prices are trading.
Oliver Huang
Maybe question for Darrin [unclear]
Richard Robuck
Oliver, we can't hear you here, and I think it sounds like everybody else can hear us fine, it's probably best if we just try to catch up with you offline.
Oliver Huang
Sounds good. Thanks, guys.
Richard Robuck
Thanks. Yeah.
Operator
Your next question comes from John Abbott from Wolfe Research. Please go ahead.
John Abbott
Hey, good morning, and thank you for taking our questions. Couple of quick ones for us.
I want to go back to the non-op here. If you look at your overall production that you have currently, how much of that is non-op approximately?
Richard Robuck
It's probably in the 10% to 15% neighborhood.
John Abbott
All right, that's helpful. Then the second question is going to be on chemicals.
You'll give us the update in February about what you may proceed with. What treatments are you doing right now that seem to hold the most promise, as you sort of look out there?
What are you waiting for in terms of data? You've been doing this for a little bit of time.
How much data do you actually need to sort of make the decision to go forward?
Darrin Henke
We've pumped a number of chemical treatments. We talked about it on page 7 in our deck.
Be it acid jobs and solvents, surfactants, combination treatments, and, on the production side, we've done hundreds of these type of jobs, and we're evaluating the productivity of those and evaluate which one will give us the best ultimate returns on the dollars invested. On the completion side, while we haven't pumped any chemicals as part of our completion jobs to date, we have been testing several chemicals in a lab situation and likely will result in pumping chemical jobs on completion in 2027.
We're still evaluating that, but anyways, testing it in the lab. Of course, we're always studying what our competitors are doing, not only in the Bakken, but in the Permian, Eagle Ford, etc., as well.
We'll definitely be early adopters as we continue to evaluate it on the completion side, and having great results on the production side.
John Abbott
Thank you very much for taking our questions.
Darrin Henke
Thanks, John.
Operator
Ladies and gentlemen, as a reminder, if you'd like to ask a question, please press star one on your telephone keypad. Your next question comes from Jeff Jay from Daniel Energy Partners.
Please go ahead.
Jeff Jay
Hey, guys. Just a really quick one from me.
You mentioned that frac crews were tight. I'm wondering what you're seeing on the service inflation side kind of apart from fuel pass-throughs and consumables.
Darrin Henke
On average, like we mentioned earlier, kind of in the low to mid-single digits is what we've seen so far this year. Some things are more, some things are less, but that's kind of where it's shaking out at this time, and not certain where '27 will be at this time.
I think it's really going to be a function of commodity price and activity levels.
Jeff Jay
Thank you.
Operator
There are no further questions at this time. I will turn the call over to Michael Lou, CEO, for closing remarks.
Michael Lou
Thanks, Julie. Once again, I'm honored to lead Chord and build on the strong foundation we've established.
I look forward to working with our employees, communities, and other stakeholders to build on that progress. We have an incredibly talented team committed to executing our strategy and creating long-term value for our shareholders.
Continuous improvement will remain a core objective. Additionally, Chord will maintain capital discipline while driving free cash flow per share and preserving a strong balance sheet.
Thank you for your continued interest in Chord and for joining us this morning. We look forward to speaking to many of you in the coming weeks.
Thank you.
Operator
Ladies and gentlemen, this concludes today's conference call. You may now disconnect.
Thank you.