Clorox Company (The)
Q1 FY2027 · Earnings Call TranscriptNovember 2, 2026
Operator
Good day, ladies and gentlemen, and welcome to The Clorox Company fiscal year 2027 first quarter earnings release conference call. At this time, all participants are in a listen-only mode.
At the conclusion of our prepared remarks, we will conduct a question-and-answer session. If you would like to ask a question, you may press *1 on your touch-tone pad at any time.
If anyone should require assistance during the conference, please press the *0 on your touch-tone pad at any time. As a reminder, this call is being recorded.
I would now like to introduce your host for today's conference call, Ms. Lisah Burhan, Vice President of Investor Relations for The Clorox Company.
Ms. Burhan, you may begin your conference.
Lisah Burhan
Thank you, Jen. Good afternoon, everyone, and thank you for joining us.
On the call with me today are Linda Rendle, our Chair and CEO, and Luc Bellet, our CFO. Please note that our earnings release and prepared remarks are available on our website at thecloroxcompany.com.
Linda will share a few opening comments, and then we'll take your questions. During this call, we may make forward-looking statements, including about our fiscal year 2027 outlook.
These statements are based on management's current expectations, but may differ from actual results or outcome. In addition, we may refer to certain non-GAAP financial measures.
Please refer to the forward-looking statements section, which identifies various factors that could affect such forward-looking statements, which has been filed with the SEC. In addition, please refer to the non-GAAP financial information section of our earnings release and the supplemental financial schedules in the investor relations section of our website for a reconciliation of non-GAAP financial measures to the most directly comparable GAAP measures.
I'll now turn it over to Linda.
Linda Rendle
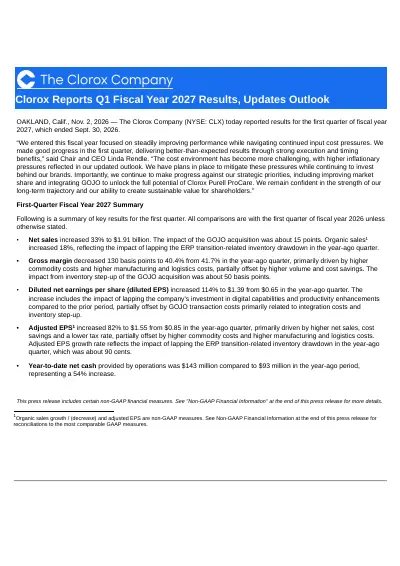
Thanks, Lisah, and thank you for joining us today. We entered fiscal year '27 focused on steadily improving performance and market share while navigating continued input cost pressures.
We made good progress in the first quarter, delivering better than expected results through strong execution and some favorable timing benefits. Importantly, the underlying trajectory of the business continues to move in the right direction, with steady progress in organic sales growth and market share.
At the same time, we continue to advance the priorities that will strengthen our performance over time. We are improving superiority and innovation across our portfolio, integrating GOJO to unlock the full potential of Clorox PURELL ProCare, continuing to evolve our portfolio, and advancing our transformation efforts from a period of significant investment toward one of optimization and value creation.
Together, these priorities are focused on building a stronger business that delivers more consistent, profitable growth. While we are encouraged by the start to the year, we recognize that the operating environment remains challenging and uncertain.
Consumers continue to seek value, competitive activity remains elevated, and increased commodity and transportation costs are putting additional pressure on margins. We have a strong track record of managing cost pressures, and we're taking balanced actions to mitigate their impact while continuing to invest in improving our top-line trajectory.
The pace of that improvement will be driven in large part by our continued progress on superiority. Our updated outlook reflects these realities, along with the actions we're taking to mitigate their impact.
Our focus remains on strengthening brand superiority, improving the consistency of our performance, and creating sustainable value over time. As you saw in our announcement on Thursday, the board has appointed Fabian Garcia as Clorox's next CEO.
Through the process, I've had the opportunity to get to know Fabian, and I've been impressed by both his experience and his perspective on our business. He is an accomplished global consumer products leader with a strong track record of building brands, evolving portfolios, developing talent, and delivering disciplined growth.
Between now and January 5th, I remain fully focused on executing our strategy, delivering our commitments, and maintaining momentum, while supporting a smooth transition and helping Fabian hit the ground running. With that, we'll open the line for questions.
Operator
Thank you, Ms. Rendle.
Ladies and gentlemen, if you have a question, please press *1 on your touch-tone telephone. Our first question today will come from Peter Grom with UBS.
Peter Grom
Great, thank you. Good afternoon, everyone.
Linda, if this is your last earnings call, I just wanted to say thank you for everything, and best wishes moving forward.
Linda Rendle
Thanks, Peter. It is.
I appreciate that.
Peter Grom
No, yeah. Thank you, Linda.
Maybe just to start on the commodity outlook. The commentary in the prepared remarks was very helpful, but just given how volatile the external environment is, can you unpack the underlying assumptions embedded in the updated guidance?
Is there anything you can share on the phasing of that cost pressure as we think about the balance of the year?
Luc Bellet
Sure, I can take that, Peter. As you read in our prepared remark, we now expect input cost inflation for the fiscal year to be about $240 million, and that's about $40 million more than we expected at the beginning of the year.
The increase is mainly driven by just a range of commodities as well as transportation cost. For perspective, the $240 million is about two and a half times higher our historical annual average rate.
Now, what I would say is while oil remained an important variable, it's important to recognize that inflation we're dealing with is broader than energy alone, right? On commodities, we're seeing resin being a significant driver, but we also seeing inflation across a wide range of commodities.
Beyond commodities, we are seeing inflation in broader area of supply chain, including supplier cost increase, as well as transportation and other logistics cost. Now from an oil standpoint, we're assuming that the Brent annual average price would be around $100, but again, keep in mind that the inflationary pressures are proving much more persistent and extend beyond the oil headline.
From a phasing standpoint, we expect inflations would be more pronounced in the first half, and then in the second half. Then in the second half, we'll also see many of our mitigation actions stacking up and ramping up over time.
That's why you're seeing an imbalance between the front-half gross margin and the second-half gross margin.
Peter Grom
That's really helpful. Then, second, you noted some of the moving pieces around 2Q organic sales, including a shipment comparison and some merchandising and timing dynamics that will push organic sales to be flat to -2%.
I know it all depends on where you fall within these ranges, but at first glance, it seems like that would imply a return to growth in the back half of the year to kind of get to flat to up slightly. Am I thinking about that the right way, and if so, can you maybe unpack what drives the confidence that trends will improve in the back half of the year?
Luc Bellet
Sure. Maybe let me actually just get us regrounded on the full year, then talk about the phasing over the both halves, and I can briefly touch on the timing for the second quarter.
For the full year, our organic sales growth rate is expected to be 3.5% to 1.5%, and that includes about 3.5 points of benefit from lapping the ERP transition. Essentially, our guidance is organic sales growth excluding the impact of the ERP is flat to +1% for the full year.
As you mentioned, from a phasing standpoint, we expect organic sales growth excluding the ERP to be down slightly in the front half and up slightly in the back half. Now, the way to think about it, there's a little bit of noise, especially in the front half, between organic sales growth and consumption.
Some of it is driven by the Kingsford trough, some of it is driven by some of the ERP lap. If you really look at the annual retail consumption, it's essentially flat in the front half and then become up slightly in the back half.
As a reminder, last fiscal year, we started in negative low-single digits, and so we've been improving sequentially to the front half of this year and continue to improve in the back half of this year. Essentially, while we're not where we want, you could see that the outlook assumed that the business is moving in the right direction, reflecting steady progress on market share and consumption.
That's for the phasing. Now, specifically to the second quarter, most of it is really reflecting timing and relapping dynamic.
If you exclude that, again, you get to what I mentioned, which is US retail consumption about flat, and then Pro and international business being outsized contributors.
Peter Grom
Great. Thank you so much.
Operator
Pass it on. We'll take our next question from Anna Lizzul with Bank of America.
Anna Lizzul
Hi, good afternoon. Thank you so much for the question.
Linda, congratulations on your amazing career at Clorox. We will all miss you.
Linda Rendle
Thank you, Anna.
Anna Lizzul
I was wondering here if you could elaborate more on the mitigation efforts in light of the cost outlook, just how much of the mitigating actions are coming from cost savings, and then how confident are you in your ability to take that incremental pricing you mentioned in the second half of the fiscal year? Also, you noted your category growth on top line is within your expectations.
Is that still around flattish as you kind of started the year here? Thank you.
Luc Bellet
Hi, Anna. I'll just take your first question on some of the mitigating actions, and then Linda can just add anything and talk about the category growth.
Given the inflationary outlook, as we talked about last quarter, we're leaning strongly in our holistic margin management set of tools, and the majority of the margin recovery is still going to come from productivity and cost savings. We have actually pretty strong cost-savings plan this year.
First quarter, we are off to a good start. This was one of the highest quarterly cost savings on record.
We're also going to implement targeted pricing in the front half, and some in the back half, as well as some RGM initiatives, and most of those will actually play out more in the back half than in the front half. As you think about the recovery, I guess I would mention two things.
The first is balance. We're really going to continue to base our actions thoughtfully and balance rebuilding the margin while maintaining and accelerating the progress we're making on market share.
Then the second, I thought, would be confidence. We're confident in our ability to rebuild margin over time.
We have a strong track record of doing so successfully in much more challenging environments, and we actually feel that we have much stronger sets of tools and capabilities today. As we look at our pipeline and the actions that are ahead of us, we feel confident in our ability to rebuild margin over time.
Now for the fiscal year, as I was talking to Peter, it's going to take time, and some of this is going to phase in the back half. We're seeing gross margin compression on average for the full year, but we'll expect to exit the year with much stronger gross margin.
Linda Rendle
On the category side, Anna, we continue to see the category in line with the expectations we set for the year. That was certainly true in the first quarter, and that the fundamentals of the category are playing out as we've expected.
Recall, we said the category flat to up 1, was certainly within that range this quarter. Moving forward, we're seeing consumers continue to behave in ways that we expect, lots of value-seeking behavior, buying larger sizes, smaller sizes, delaying purchases, etc., but in line with what we expect.
We've seen competitive activity generally in line with what we expect, retailer activity, again, generally in line with what we expect. No indication that our assumptions on category won't hold up for the year.
Then I would just note, because we continue to expect that in the back half, that implies that we would see better share performance in the back half of the year as well.
Anna Lizzul
Great. Thanks so much.
Very helpful.
Linda Rendle
Thank you.
Luc Bellet
Thanks, Anna.
Operator
Our next question will come from Robert Moskow with TD Cowen.
Robert Moskow
Hey, thank you. I was hoping for a little more detail on where specifically you're seeing the market share improvement that you talked about.
Like what categories are you seeing some momentum? Where are you gaining share right now?
Linda Rendle
Sure, Robert. When we talk about market share improving, we're looking at an aggregate number, but I I can break that down by category as well.
If you look at Home Care, which is our largest business, we have continued share momentum on that business, with a very strong quarter, up over a half a share point. That is in large part due to great activation on innovation, as well as our back-to-school merchandising.
We saw strong share growth in Brita. That also was correlated to our back-to-school, back-to-college merchandising and broad-based strength across promotions, as well as innovation.
Hidden Valley grew almost 2 share points this quarter. I think you all know that that category was under a lot of pressure due to the Cyclospora outbreak.
Category was down, we had, saw weeks that were down strong double digits. Hidden Valley, given we are a condiment used on more than just salads, was able to win and deliver strong execution, very strong share growth in Hidden Valley.
I'd note Burt's Bees was about flat, Glad trash about flat. A number of the businesses showing positive share momentum.
The continued story on litter, although we have some green shoots that we're happy about as the plants come in, we are still far from the place we want to be on share, and that continued to be a drag from a company perspective. Then the final one I'd note is on Kingsford.
While the category continues to be under stress given weather, etc., we did see a very strong Labor Day for Kingsford, delivered very strong high-single-digit growth for that period, as well as share growth. That's a good indicator that, as we have made some adjustments on execution, it bears well for fiscal year, excuse me, season year '27 for Kingsford.
That business also, highly event-dependent, and share, you have to win the key holidays to do that, and it was a good indication that Labor Day delivered.
Robert Moskow
Okay. A quick follow-up.
You said that you have good line of sight for synergies for GOJO, and it's moving faster than you expected. At some point, do you think you can raise your accretion estimate for first year on that?
Luc Bellet
I can take that, Robert. We're First on the accretion, and then maybe and then I'll talk a little bit about the synergy.
At the time of the acquisitions, we had estimated that the adjusted EPS impact on year one will be about neutral, and we revised this to positive, right? We didn't share any specific.
This is really a factor of two things. First, the the base business is actually continuing performing very well.
Second, we're actually just progressing very nicely on integration and started accelerating some of the synergies. If you remember, from a cost-synergy standpoint, we had estimated about $50 million, and our initial estimate assumed that we would capture that mostly in year two and three.
Because the good news is we now have, like, line of sight to the entire $50 million, which gives us great we have confidence that we will get at least that and, potentially more. The In addition, because we've been making good progress on integration, we're able to actually start seeing some of those later in the first year, which is in fiscal year '27.
Net, I think, we feel really good about, the progress of both the base business as well as the integrations, and that's starting showing up in our financials.
Robert Moskow
Thank you.
Operator
Our next question will come from Andrea Teixeira with JPMorgan.
Andrea Teixeira
Hi, good afternoon, everyone. Linda, congratulations on your amazing career at Clorox, and wishing you all the best in your next chapter.
I was hoping to, if you can, elaborate a little bit more on what you said about some of the categories where you were able to regain share with basically a lot more merchandising and also potentially promotions. As you think about recovery and continue to recover in the path of getting growth, organic sales growth in the second half, can you talk about how you're planning those actions, and then if there is anything in particular that you're counting on in terms of additional phasing of innovation that would give us confidence that this path is the right or is kind of materialize?
Linda Rendle
Sure. Thanks, Andrea, and thanks for your comments.
If you look at the share results, first, I want to acknowledge that fiscal year '26 was certainly really noisy for the company. We underwent our ERP transition, which is never easy, had a bit of bumpiness in part of that.
A lot of the businesses were facing not only a heightened competitive environment, a weakening consumer, but they were also focused on just operational execution and ensuring that we were able to deliver to retailers and keep in stock, etc. A lot of what you're seeing is us getting back to executing with excellence, now that that noise is well behind us, delivering on our superiority plans, which we invested incrementally behind this year, as well as ensuring that we execute with excellence behind merchandising.
I just want to make sure that I'm clear. The merchandising that we have in the system is the typical merchandising we do, just executed very well.
Back-to-school, we always have strong promotional activity during that time. The team actually made a bet on back-to-school that it would occur a little later this year, given the consumer stress that it was under.
That was a good bet. We actually saw the timing of consumers' consumption move to later in that, and we were prepared for it.
I would just want to make sure I note, this is not us investing a lot in extra merchandising or price reduction outside of targeted activities we've taken, but just executing the things we have to do with excellence. As we move into the back half, there's a few more things that will enhance what we've seen in the front half, and that is most of our innovation launches in the back half.
That happens throughout Q3 and Q4. We have one of our strongest innovation plans on record this year, and we're hoping it will be a record year on innovation.
We've seen good retailer sell-in, and many of these innovations had very, very strong consumer testing behind them, we go in with a lot of confidence that that innovation will work. In addition, some of the innovation is building on current platforms that have been successful, like Clorox Pure, the allergen-removing platform that we have, we already know we have success in market and we can turn that success into additional areas that those products can deliver on for consumers.
The other thing I would note is, as Anna mentioned, we expect the category continue to be in line with our expectations, but we are seeing consumers continue to focus on value. At the beginning, we talked about the fact that we saw consumers stocking up more or buying a smaller size, but we are also seeing them begin to shift their behavior in terms of timing, like I mentioned for back-to-school.
Those are the things we're watching really closely as we execute in the back half, but we feel like we have them well handled and well managed. Those are the things that are kind of, as we look to executing that are on our mind, ensuring we deliver our superiority plans, delivering on innovation, executing with excellence against merchandising and new distribution, and then watching the consumer really closely as they continue to navigate a difficult environment.
Andrea Teixeira
Linda, this is super helpful. Can you talk about the pricing magnitude that you include in, and I think Luc had said some selective pricing and you said that the prepared remarks as well.
What is number one, the magnitude, and number two, the timing of the pricing, and if three is list pricing or selective with innovation? Thank you.
Linda Rendle
I'll start, and I'll hand it over to Luc if there's any more detail that he wants to provide, particularly as it comes to gross margin, although I think he walked through the bridge at the beginning. On pricing, we've implemented already this year targeted pricing across all four of our reporting segments.
We looked at those very carefully to decide where the biggest impact was from a commodity perspective. Glad, for example, is one that is heavily based off of resin pricing.
We took a pricing increase on Glad Trash that was a good magnitude, high-single-digit price increase that we implemented in July. It took a little while for it to get passed through, you're starting to see it in the data now at the end of September.
Then some other targeted pricing actions against those four segments. As you would expect, given the environment and the fact that we're seeing additional cost pressures across the industry, it's logical to assume that we will take additional pricing in the back half, and that's what we're working on right now.
Of course, as Luc has said many times in the past, those actions take a while to see them show up in margin, you see the impact from the increase in costs, and it takes a couple of quarters to start to see those mitigating actions. We'll use the same principles that we did for the first round when evaluating these price increases, going where we're seeing the most commodity pressure, ensuring that we have superiority plans, and to your point, Andrea, timing it when we can with innovation and product improvements so that we balance what Luc mentioned at the beginning, which is our top-line and superiority trajectory alongside recovering margins.
Luc Bellet
I guess the only thing I would add, and maybe that's what you were referring to, Andrea, is that our outlook and our gross margin and our top-line outlook also reflects some targeted investments we're making to improve superiority in some brands. Those investments can come in the form of actually lower prices, either through trade or price pack architecture, and the litter business is one of those, or in other case, it could be in the form of higher cost, where we're really doubling down to step up the product benefit and performance to further strengthen the proposition as part of the innovation in the back half.
That is all contemplated, and that's what you would expect us to do as part of that balancing.
Andrea Teixeira
Thank you both. I'll pass it on.
Linda Rendle
Thanks, Andrea.
Operator
Our next question will come from Kevin Grundy with BNP Paribas.
Kevin Grundy
Great, thanks. Good afternoon, and Linda, of course, wish you and your family nothing but the best.
It's been a pleasure working with you. A couple quick ones, please.
First, just a follow-up on the pricing. Linda, you commented before and it makes sense to price behind innovation here in the back half.
Can you give us a sense of how much of the portfolio will be covered with incremental pricing? I know it's going to come on in a staggered way, we will have to sort of reflect that in our models accordingly.
I guess I'm sort of asking this in the context that there hasn't been as much pricing yet, but it seems like we're at a level with commodity cost pressure where the industry likely will price up. I'm just trying to get a sense if it kind of moves that way, and many categories and the whole basket is moving higher for the consumer, is there potential for even incremental pricing than you may have in your outlook at the moment?
I'll stop there on that, and then I have a quick follow-up for Luc on margins.
Linda Rendle
Sure, Kevin, and thank you for your comments. On the pricing front, it is certainly dynamic and volatile from a commodities perspective and what we're seeing on cost, and we're trying to be as nimble as we can on the pricing front.
Maybe what I'd first say is the vast majority of the portfolio will be covered by RGM. That activity will be broad-based, and we have all of our teams working hard to drive efforts there.
Those are the ones that we can get really sharp on to ensure we have the right price pack architecture, etc. The teams are working hard and fast at delivering those.
On truckload pricing, as I said, we took pricing across the four reportable segments first part of the year. In the back half of the year, we'll continue to look at the opportunities, but we're going to be targeted.
If the environment changes, Kevin, we will have to change that posture, and I think the industry would have to change it. Right now, we still want to keep that balanced approach and make sure that we're making the right investments while taking the right level of pricing.
Right now, I'm not ready to give you a percentage of the portfolio that we would take additional truckload pricing on, just know that if there is additional commodity pressure beyond what we contemplate right now, that will be a tool the industry and certainly we look at using deeper, but really focus right now on RGM and targeted pricing.
Kevin Grundy
Got it. Thanks.
A quick follow-up, maybe it's not quick, Luc. Just you commented on the ability to rebuild margin over time.
I know sometimes there tends to be just a focus on the next 6 to 12 months, but maybe with a longer-term orientation, what's the North Star now for margin, the margin profile at Clorox? Maybe the answer is it's not very different than it's been in recent years and the target is 44% to 45% gross margins and maybe 18% operating margins, but maybe better, right, just given what you're seeing now from a productivity perspective, which is as good as it's been perhaps forever, really.
Some of the highs we're seeing in productivity, what's the longer-term margin target to share with shareholders? I'll pass it on.
Thank you.
Luc Bellet
Sure, Kevin. Maybe before I answer your second question, one clarification on your first question, which is if you look at margin recovery for the fiscal year, the majority is coming from cost savings and productivity.
On the part that's coming from pricing and RGM, the majority is still coming from RGM, with a small portion from pricing. That gives you just how to think about the total margin recovery for the year.
I think to answer your question is, it hasn't changed, which is job one is getting back to historically EBIT margin, right, which were about 18%. The way we want to do that is first rebuilding gross margin, because gross margin helps fuel our investment in our brand and in superiority.
You want to do it through first rebuilding gross margin, and over time, rationalizing OpEx. Job one will be getting back there.
Keep in mind, gross margin historically was 43.5%, 44%. With the GOJO business, it might be a little less initially until we actually just reach out to achieve our cost synergies.
I would say I mentioned that we feel confident in our ability to rebuild margin over time. Again, we're in an inflationary cycle, and so we're seeing the initial inflationary pressure, but beside having a strong track record of doing so in the past, if I look at our pipeline, we have a stronger productivity engine right now.
As we always had a successful cost-savings program, and then we've been adding new tools and capabilities like RGM and design-to-value, and it's been working for us. Two out of the last three years had record-level annual cost savings.
This year is looking really strong as well, I mentioned the first quarter was one of our highest, and we'll see where we finish the year, but we feel confident. There's a few things going on here.
In addition to those new capabilities, we're also going to start getting the contributions of ERP over the next few years, right? We talked about ERP over the past couple of quarters, and it was all about implementation and stabilization, but now we're entering a phase of value creation.
The cost complexities really coming down, and then the benefit are going to ramp up. It will take time.
We just talked about it, where you have to in a lot of the process on the supply chain or on the functional admin, you have to just reengineer through those process, but we have those savings in the pipeline. Then I guess maybe the last thing from a margin standpoint, and this is not part of the productivity or cost savings, but it's the synergies on GOJO.
$50 million is pretty significant number, and we do have line of sight to that number, and hopefully we can drive more. When you consider all those, like I said, I think our productivity engine is just stronger than what it's been, and we'll just have to navigate the current environment, which is we expect it's going to continue to be volatile and uncertain.
Kevin Grundy
Very good. Thank you both.
Good luck.
Linda Rendle
Thank you.
Operator
Our next question will come from Kaumil Gajrawala with Jefferies.
Kaumil Gajrawala
Hey, everybody. Linda, good luck, and thanks for everything along the way.
I guess my first question, maybe the biggest question that we've been having conversations about is given the share trends, if there was going to be a need to rebase or anything. I suppose now that we're seeing the beginning of share trends move in the right direction, would you say that maybe we're sort of nearing escape velocity, and that's not necessarily the case, or is it something still sort of remains to be seen?
Linda Rendle
Kaumil, we've been encouraged by the progress we've made. If you looked at what Luc talked about, we've had sequential improvement on OSG tied to improvement on consumption, as well as market share.
I've highlighted, particularly litter a business where we need to make much more progress, but it is encouraging to see on the other businesses the progress that we've made behind innovation and superiority, and just frankly, getting back to executing without going through an ERP transition. Given the trajectory we're on, we expect to have continued improvements, particularly through the back half, as we have our very strong plans on innovation and superiority launching across all of our businesses.
We feel good about that. We do feel like we have the right levels of investment in the business, and we've talked about that in a number of ways.
First would be advertising and sales promotion that we've held at an elevated level. We used to spend about 10%, we spend about 11% now.
You see the number reported as 10%, but that's because of the GOJO effect, if you look at US retail, it's been about 12%. We feel really good about the advertising we have.
We know our ROIs very well on those businesses. We know where we can invest incremental money, and we are not afraid to move money depending on those numbers, and the businesses aren't afraid to invest more if it's warranted.
Feel good about the level we have there. We've had more money in on trade funds, and we've talked about actually trade funds being a place where we can optimize moving forward, applying the new tools we have from technology, we would expect to get more bang for our buck in the future when it comes to trade spending, but feel good about the overall level of investment we have there.
Then we talked about how investing in superiority, and that comes in a few forms. We've invested in price, cat litter and Glad are two examples that we've given, but we're also investing in product improvements, many of which hit in the back half of the year, and other ways that we can drive superiority through execution and e-com, etc.
I don't know if I would call it reaching escape velocity, but what I would say is we do expect continued improvement. We like the momentum we're seeing, and we would expect, given the plans that we have, we'll make continued progress throughout the remainder of the year and that the investment we have is working for us and at the right levels.
Kaumil Gajrawala
Great. Then maybe just a softer one, which is, congratulations on finding and hiring Fabian.
Is there anything you wanted to share as you went through the process on why he's the right person for the job, what were maybe some of the more appealing characteristics? I'm sure you had met many people.
Why is Fabian the guy?
Linda Rendle
Sure. As we spoke about, the board went through a very comprehensive process and felt really good about the broad-based look that they had in the market to assess who the right next CEO was and landed that Fabian was absolutely the right person for the job.
If you look at Fabian's track record of experiences, of delivering, and also the values that he holds, those are all a great match for this role. He has lots of experience in innovation and brand building.
In fact, he ran teams that just did that and growth in a number of companies. He is a disciplined executer, which is exactly what we need at the moment as we continue to deliver executional excellence and improve that coming out of the ERP transition and some of the disruptions we've had.
He shares our values. Was the first thing he said to our team on Thursday in the video.
He believes in do the right thing, put people at the center, and play to win. I think play to win is high on that list for him, which is going to be great for the company as we move forward into this next phase of growth, and certainly the next set of challenges that we have in the environment.
The board and I are 100% supportive of Fabian. He and I are in regular contact and beginning to transition, and the two of us are committed to a seamless transition where the organization doesn't miss a beat, which means, of course, I will, up until January 5th, be 100% focused on delivering our plans and getting Fabian on day one to be ready to take the reins.
I'm excited to see what he'll do for the company, and I think the company is excited as well. Fresh perspective is always a wonderful thing, and I think he has some good ideas for the company, and he'll continue to talk to you about how he'll implement our strategy once he starts in January, and have a chance to speak to you both at CAGNY and, of course, the February earnings call.
Kaumil Gajrawala
Great. Thank you very much.
Linda Rendle
Thank you. Our
Operator
next question will come from Chris Carey with Wells Fargo.
Chris Carey
Hey everybody. Thanks for the question, and congrats, Linda.
Wishing you all the best. Hey, Luc, going into fiscal Q4, I think you said something to the effect of that gross margins, you expect to exit the year much stronger.
Can you contextualize that a bit? The reason I'm asking is because the fiscal Q2 gross margin is implied to be lowest of the year on worsening inflation.
Inflation presumably carries into the back half of the year. That exit rate, it almost felt like fiscal Q4 gross margin will be the highest of the year based on that comment.
I don't know if that's some of the incremental pricing or productivities, I just wanted to get a bit more context there.
Luc Bellet
Sure, Chris. The main comment I was making is that gross margin in the back half will be higher than the average, right?
Didn't intend to comment specifically on Q4 versus Q3. As I mentioned, inflation is actually going to be a little more pronounced in the front half than the back half.
You have to remember, some of the inflation that we're experiencing now, for us, started showing up in our P&L in March and April. I'm lapping that, but it's not only that, it's just based on the projections.
If I look at also the timing of our margin recovery actions, they'll be more elevated in the back half. That's what's creating essentially a front half that's about a point, point and a half below the average, and then expecting the back half would be a higher.
That's the only thing that I was pointing to.
Chris Carey
Understood. That back-half margin recovery will be more driven by productivity and RGM as opposed to the incremental pricing, is that correct?
Luc Bellet
That's right. On the relative basis, that's correct.
They're all contributing, but on relative basis, that is correct.
Chris Carey
Okay. All right, perfect.
Thank you. Then the second question, just around margin is the SG&A outlook was slightly changed today.
Is that also just the incremental productivity that is flowing through the model? Effectively, both of these questions are just trying to understand kind of core drivers of the anchoring to the full-year guidance, so as to think about durability going into fiscal '28.
Thanks so much for that.
Luc Bellet
Understood, Chris. Maybe let me make two comments.
One, broader on how to think about what changed in our outlook, and then just I can talk a little bit more about SG&A specifically. What changed is mostly the inflation being higher now, $40 million higher.
That's 60 basis points of margin headwinds. We will mitigate part of that in the back half, but what we're going to feel in the second quarter, we're just not going to be mitigated.
That's the main driver. There's a little bit on SG&A, there's two things that I would mention.
One, there is a little bit of favorability as we're accelerating some of the synergies on the GOJO acquisition, and that will show up in the back half. Now I think we adjusted the SG&A from 16% to 15%, so that's a full point, but there's a little bit of rounding in those percentage, keep in mind the benefit of the incremental synergies is probably less than that, maybe a third or so.
That's the main thing on SG&A. There's a lot of noise in SG&A between Q1 and Q2.
I think we talked about it in the prepared remark, but essentially, we had a few discrete items, timing items on both tax and SG&A. Tax was really driven by a restructuring of an international legal entity, which was completed earlier than expected.
Then on SG&A, there was a little bit of timing of certain one-time and project spending. If you look at SG&A, or actually tax for that matter, for the front half, it'd be pretty close, generally, than the rate for the full year.
SG&A might be a little higher for the front half than the full year just because there's some more productivity in the full year, and effective tax rate might be slightly lower because Q1 was so favorable, but Q2 would be above normalized level. That's as you think about your modeling and as you think about OpEx and tax.
Chris Carey
Okay. All right, thank you.
Thank you for all that. Much appreciated.
Operator
We'll move next to Javier Escalante with Evercore ISI.
Javier Escalante
Hi. Good evening, everyone.
Linda, thank you for our discussions. I learned a lot talking to you.
I have a question, I guess is for Luc. Again, the cost savings on the gross margin is one of the highest, I believe, quarterly highest in, I guess, 15 years.
If you can help us understand how much is actual changes of things that you are doing, perhaps because of GOJO allows you better capacity utilization, I do not know. What is driving this step-up in cost savings going through the gross margin line, and how sustainable that is.
Does it carry over into the balance of the year? I have a follow-up.
Luc Bellet
You are correct. I think we mentioned this in the prepared remark.
The cost saving was one of the highest from a quarter standpoint. I'd go back to what I just was sharing earlier is we have a stronger productivity engine than we used to have.
Last year, cost savings were a little limited just because we had to reallocate resources, quite frankly, to deal with the stabilization of the ERP. If you look at the two years before that, you're starting seeing a step-up in our cost-savings contributions relative to the past.
It's a lot of what I just shared is essentially the benefit of having really data and tech-driven capabilities like RGM and design-to-value. We do see this step-up.
It might not always be at the same level every quarter, but the step-up is definitely something that's sustained. I would say we haven't yet seen some of the benefit of the ERP.
It will show probably later in the year, so that will feed that pipeline and that will help maintain a more elevated rate. That does not include some of the synergies on GOJO.
Actually, just most of the synergies will necessarily always show up in the savings numbers. They will, and you'll see this, and some of them will be in the supply chain, but some of it would be in selling and admin as well.
Net, again, we really feel good about our productivity engines. We have a big year ahead of us to deliver, and that's important given the inflation that's ahead of us.
We'll stay close to what's going to happen this year from an inflation standpoint, as we mentioned, it continues to be volatile and uncertain.
Javier Escalante
That's very helpful. I imagine that, in essence, is that the ERP is allowing you to identify savings that you couldn't see before.
I guess this is what I'm explaining to myself. The other thing is, when you look at divisional gross margin, Household Products dropped below 30%.
I know that there is Kingsford, there is cat litter, some of you already are recovering pricing, as you said, on Glad. How much pricing do you think you need to reinvest in cat litter?
Is that all, because we see in Scantrack data price mix down for Fresh Step about -5%. Is that all, or are we going to see even more price investment?
If you can help us understand how you see the Household division now with gross margins below 30%. Thank you.
Linda Rendle
Javier, I'll take that in a couple pieces. First, on Glad, as you note, Glad is one of our more impacted businesses as oil and resin move in the upward trajectory, but also a business we have a long history of taking pricing on, and we just took pricing on Glad Trash, and you're seeing it flow through in the data.
Far, the data looks in line with our expectations in terms of consumer acceptance, volume impact, dollar sales impact, etc. If you look at litter, we have absolutely invested back in price in a portion of our portfolio to get our value equation right.
What we would expect over time as well as innovation hits the marketplace, and we have our first round of innovation in cat litter hitting actually, we'll begin shipping this quarter, but for the most part will be a back half loaded innovation cycle. We would expect, over time, to be able to remove some of those price investments as we deliver a superior product and a better experience to consumers.
For now, we think this is absolutely the right investment. Where we've made that, we're seeing an increase in share, seeing consumption improve, etc.
We're not afraid to make those investments where they're warranted, and certainly on litter, it is at the moment. Over time, as that pricing takes effect, and we'll see what happens with commodities, we would expect the household margin profile to begin to get back to what it was before.
It'll take a little bit of time. As Luc said, we experience all of the cost and the investments up front, and then we work that out.
We're fully confident in our ability to do that given the toolbox that Luc just outlined.
Javier Escalante
Thank you very much.
Linda Rendle
Thanks, Javier.
Operator
We'll move next to Olivia Tong with Raymond James.
Olivia Tong
Great, thanks. Good afternoon.
Linda, wishing you the best of luck with everything, most importantly, your health. We'll miss speaking with you on a regular basis.
Linda Rendle
Thanks, Olivia.
Olivia Tong
Can I ask you about one of the areas that were stronger than expected is price mix, particularly in Health and Wellness? Can you elaborate on that a bit?
Was that primarily GOJO, or did the ERP-related timing shifts have an impact, and how do you think about the contribution from price mix for the remainder of the year? Then secondly, what's your visibility on costs at this point?
Are there hedges in place so that you have visibility on the cost inflation? Have you had those discussions in some cases with pricing that you're planning to take, but haven't implemented yet, with retailers, and a better sense of how long it would take for that pricing to come through given how long it did take with Glad earlier in the year?
Thank you.
Luc Bellet
Hi, Olivia. On your first question, yes, we saw pretty strong price mix in Health and Wellness segment.
I think it was about 7%. About six actually came from the GOJO acquisition, which is a favorable price mix.
Still, we saw about one point of favorable price mix in the base business, and that was a mix of coming from both RGM and some very targeted pricing on some smaller brands. That's for your first question.
I would say on the visibility on cost, maybe a few things. First, obviously, we're operating in an environment, a cost environment that remain fairly uncertain and volatile.
You can imagine we're planning across a range of possible scenarios, and our outlook reflects what we know today and what we believe is the most likely scenario. Now from a hedging standpoint, I think we have a number of mechanism in place to manage cost and commodity volatility.
We selectively use financial hedges for some commodities where the market are liquid and economic make sense. For some others, we manage exposure through contractual agreement, purchasing strategies, or even inventory.
That those mechanism means that there's a different cost flow through the P&L within different timing. Right?
In the case of fuel surcharges, we're going to see it pretty much right away and moves with the market. For other commodities, contractual inventory timing can create lag of any of several months, anywhere from one to over six months.
On average, on aggregate, we generally tend to have good visibility two to three months out. That gives you a sense of the visibility.
As far as pricing, I think you heard from Linda earlier, there's some that already been implemented in market. Some they might come later in the back half, it's still relatively targeted and selected.
Obviously, as part of the scenarios that I'm just talking about, we're contemplating potentially other pricing actions.
Olivia Tong
Thank you. Best of luck.
Linda Rendle
Thanks, Olivia.
Luc Bellet
Thank you.
Operator
This concludes the question-and-answer session. Ms.
Rendle, I'd like to turn the program back to you.
Linda Rendle
Thanks, Jen. Thank you for your time and questions today.
We are focused on continuing to improve our top-line trajectory by strengthening the superiority of our brands and products, advancing consumer-led innovation, and improving execution. At the same time, we're taking balanced actions to mitigate cost pressures and protect profitability, drawing on a track record of successfully managing through periods of volatility.
We're also continuing to advance the strategic work that will strengthen Clorox for the long term: integrating GOJO, evolving our portfolio, and delivering value creation from our transformation investments. We are encouraged by our progress and remain focused on building a stronger company capable of delivering more consistent, profitable growth over time.
Before we close, and as many of you acknowledged, I want to acknowledge that this is my final earnings call as CEO of Clorox. I really appreciate all the comments you made during the call.
It's been an incredible privilege to lead this company through one of the most complex periods it's faced, both operationally and strategically. For years, to have the opportunity to speak with you all about our performance, our strategy, and the opportunities ahead.
Thank you for your engagement, your questions, and the perspective you shared along the way. I'm proud of the stronger foundation we've built, and I have tremendous confidence in our brands, our strategy, and our people.
To our team around the world, thank you. Your work made our strong start to the year possible, and I am deeply grateful for everything you continue to do for Clorox and for one another.
With that, I look forward to supporting Fabian through the transition, and you will have the opportunity to hear from him and Luc on our next earnings call in February. Until then, please stay well, and I wish you all the very best.
Operator
This concludes today's conference call. Thank you for attending.