Cummins Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Greetings, and welcome to Cummins Inc. third quarter 2026 earnings conference call.
At this time, all participants are on a listen-only mode. A question-and-answer session will follow the formal presentation.
If anyone requires operator assistance during the conference, please press *0 on your telephone keypad. As a reminder, this conference is being recorded.
It is now my pleasure to introduce your host, James Hopkins, Vice President, Financial Planning, Capital Management and Investor Relations. Please go ahead.
James Hopkins (Vice President, Financial Planning, Capital Management and Investor Relations):
James Hopkins
Thank you, Donna. Good morning, everyone, and welcome to our teleconference today to discuss Cummins' results for the third quarter of 2026.
Participating with me today are Jennifer Rumsey, our Chair and Chief Executive Officer, and Mark Smith, our Chief Financial Officer. We will all be available to answer questions at the end of the teleconference.
Before we start, please note that some of the information you will hear or be given today will consist of forward-looking statements within the meaning of the Securities Exchange Act of 1934. Such statements express our forecasts, expectations, hopes, beliefs, and intentions on strategies regarding the future.
Our actual future results could differ materially from these projected in such forward-looking statements because of several risks and uncertainties. More information regarding such risks and uncertainties is available in the forward-looking disclosure statement in the slide deck and our filings with the Securities and Exchange Commission, particularly the risk factors section of our most recently filed annual report on Form 10-K and any subsequently filed quarterly reports on Form 10-Q.
During this call, we'll be discussing certain non-GAAP financial measures, and we will refer you to our website for the reconciliation of those measures to GAAP financial measures. Our press release, with a copy of the financial statements and a copy of today's webcast presentation, are available on the website within the Investor Relations section of cummins.com.
With that out of the way, I wanted to share that I look forward to reconnecting with the investment community in my previously announced role overseeing investor relations as the Vice President of Financial Planning, Capital Management and Investor Relations, and continue our dialogue about Cummins' performance and future prospects for profitable growth. I look forward to speaking with many of you in our follow-up conversations after today's call.
With that, I will turn it over to our Chair and CEO, Jennifer Rumsey, to kick us off.
Jennifer Rumsey
Thank you, James. It's great to have you back on our earnings calls as a part of your new role.
Good morning, everyone. I'll start with a few highlights from the third quarter and an overview of our financial results.
I'll then discuss key trends across our markets and provide an update on our outlook for the remainder of 2026. Mark will follow with additional details on our third quarter results and full-year forecast.
Before turning to our financial performance, I want to highlight a few important milestones from the quarter. In August, we announced that our Power Systems business was selected to supply battery energy storage systems for a large US data center project.
These systems will help manage AI-driven fluctuations in power demand, improve grid stability, and enhance power reliability. This will be our largest battery energy storage system deployment to date and an important milestone as we expand our capabilities to meet the evolving power needs of data center customers.
We continue to make meaningful progress and remain on track with the power generation capacity expansion plans we outlined at our recent Analyst Day. This includes strengthening our global supply chain, which remains a key pacing item as we bring additional capacity online to meet exceptionally strong demand in power generation, particularly from data center customers.
Recently, we celebrated the opening of a 500,000 square foot manufacturing facility for our IEA cooling systems business in Somers, Wisconsin. This approximately $100 million investment will more than double IEA's production capacity and strengthen our ability to supply critical cooling systems for our generator sets.
We also made important progress preparing for the upcoming launch of our HELM engine platforms. During the quarter, we completed our 2026 Forever Rising Tour, giving more than 500 customers and dealers the opportunity to experience our 2027 X15 engine alongside our X10 and natural gas X15N engines.
Customer feedback has been very positive, particularly around performance, drivability, and confidence in Cummins' reliability and support network. Hearing directly from customers is an important part of our launch preparations and reinforces our confidence in these products as we prepare to bring them to market.
Together, these milestones demonstrate the progress we're making against our strategic priorities: strengthening our core business, expanding our capabilities, and investing in technologies and capacity needed to support our customers and drive long-term growth. Now let me turn to our third quarter financial performance and key markets.
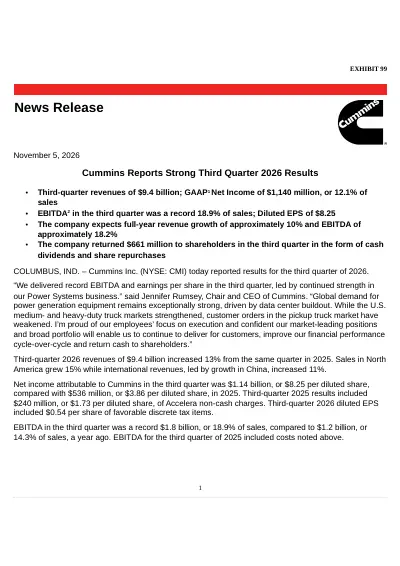
We delivered third quarter revenues of $9.4 billion, an increase of 13% compared to the third quarter of 2025. Growth was driven primarily by improved demand in North America heavy and medium-duty truck markets, record quarterly EBITDA of $1.8 billion or 18.9% of sales, compared to $1.2 billion or 14.3% of sales a year ago.
Last year's results include a $240 million goodwill impairment charge and inventory write-down related to our Accelera business. Excluding these charges, EBITDA margin improved approximately 170 basis points year-over-year, primarily reflecting higher volumes, partially offset by increased variable compensation expenses associated with our expectations for a full-year record earnings.
Turning to our key markets, third quarter revenues in North America increased 15% compared to third quarter of 2025. Industry production of heavy-duty trucks in the third quarter was in line with our expectations at 70,000 units, up 62% from 2025 levels, while our heavy-duty unit sales were 24,000, up 68% year-over-year.
In the medium-duty truck market, industry production increased 77% to 36,000 units, while our unit sales were up 33,000, up 88% year-over-year. Despite this strong year-over-year growth, demand was below our expectations as regulatory uncertainty and the anticipated phased transition to EPA 2027 products continued to delay some customer purchasing decisions.
We shipped 34,000 engines for pickup trucks in the third quarter of 2026, down 16% from a year ago. Demand was weaker than anticipated amid elevated diesel prices and interest rates.
North America Power Generation revenues increased 22%, driven primarily by continued strong data center demand and supported by the additional manufacturing capacity we brought online at the end of 2025. While we achieved record Power Generation sales this quarter, revenues were below our expectations as supply chain constraints limited shipments across both Power Systems and Distribution, which we expect to largely catch up in the fourth quarter.
We continue to see robust order intake and engage in multiyear strategic planning discussions with large data center customers. Turning to our international markets, revenues increased 11% compared to the third quarter of last year.
In China, third quarter revenues, including joint ventures, increased 9% to $1.9 billion, supported by accelerating data center demand. Industry demand for medium and heavy-duty trucks in China was 297,000 units, a decrease of 5% compared to last year.
Domestic demand remained challenged by elevated fuel costs, partially offset by strong export demand, particularly in Africa and Southeast Asia. Our sales in units, including joint ventures, were 42,000, a decrease of 15%, reflecting increased adoption of battery electric trucks in the domestic market.
Industry demand for excavators in China in the third quarter was 62,000 units, an increase of 15% from 2025 levels. We sold 12,000 units, up 28%, driven by export demand associated with mining investments in Africa and Indonesia, as well as domestic demand for rural development.
Sales of power generation equipment in China increased 42% in the third quarter due to accelerating data center demand. In India, third quarter revenues, including joint ventures, were $803 million, an increase of 13% from a year ago.
Industry truck production increased 30% from 2025, driven by increased freight, infrastructure, and mining activity. Now let me provide our outlook for 2026, including comments on several of our key markets.
We have updated our full-year 2026 outlook and now expect revenue growth of approximately 10% and an EBITDA margin of approximately 18.2%, compared to our prior guidance ranges of 10% to 13% revenue growth and 18% to 18.5% EBITDA margin. In North America, we are maintaining our 2026 heavy-duty truck market forecast of 240,000 to 250,000 units.
For medium-duty trucks, we are lowering our forecast to 125,000 to 130,000 units, compared to our prior outlook of 130,000 to 140,000 units, reflecting weaker-than-expected third quarter demand as regulatory uncertainty delayed customer purchasing decisions. Looking ahead, we expect fourth quarter production in both markets to remain strong, near third quarter levels, with supply chain constraints limiting the potential for additional upside.
For our North America pickup truck engine business, we are now lowering our 2026 shipment forecast to 118,000 to 122,000 units, compared to our prior guidance of 125,000 to 140,000 units. We expect demand to moderate further in the fourth quarter, reflecting continued pressure from elevated diesel prices and interest rates.
In China, we continue to expect total revenue, including joint ventures, to increase approximately 15% in 2026, consistent with our prior outlook, primarily driven by strong demand in power generation, particularly from data center customers. For China heavy and medium-duty truck demand, we continue to expect industry demand to range from a decline of 5% to an increase of 5%.
As we saw in the third quarter, elevated fuel prices have contributed to a shift toward battery electric trucks, while export demand for diesel-powered trucks remains strong, particularly in Africa and Southeast Asia. In India, we expect total revenue, including joint ventures, to increase approximately 5% in 2026.
We continue to expect full-year industry truck demand to be approximately flat at the midpoint of our forecasted range, supported by recent tax rate reductions. For global construction markets, we are maintaining our outlook for demand increase 10% to 20%.
In China, we expect export demand to remain strong, while demand in North America is expected to remain relatively flat amid elevated interest rates. In Power Generation, we continue to expect global revenue to increase 15% to 25% this year, consistent with our prior guidance.
We expect to recover most of the shipments delayed by third quarter supply constraints in the fourth quarter, and demand remains exceptionally strong across North America, China, and the broader Asia Pacific region. We're expanding our manufacturing capacity, and demand continues to grow, with customers increasingly ordering smaller displacement generator sets as availability of larger configurations remains constrained.
In mining, we continue to expect engine sales to range from a decline of 5% to an increase of 5% for the year, consistent with our prior guidance. Fleet replacement activity remains supportive in several markets, although elevated inventory levels in others are expected to moderate demand through the remainder of the year.
For Aftermarket, we are maintaining our outlook for revenue growth of 3% to 8% in 2026, supported by aging fleets and increased parts consumption. In summary, we delivered a strong third quarter with record profitability and continued growth across several of our key markets.
Our updated full-year outlook reflects continued strength across most of our business, tempered by lower-than-expected pickup truck demand. As we enter the fourth quarter, we remain focused on executing our strategy and delivering our commitments to customers and shareholders.
We remain on track with the commitments outlined at our recent Analyst Day, including expanding our production capacity and investing in new products and technologies to strengthen our product portfolio. Finally, I want to thank our employees and leaders around the world for their continued commitment to our customers and to each other through a dynamic time.
Their dedication, teamwork, and focus on execution continue to differentiate Cummins and position us to deliver for our customers while creating long-term value for our shareholders. Now, I'll turn it over to Mark.
Mark Smith
Thank you, Jen, and good morning, everyone. Before reviewing our third quarter financial results in detail, I'd like to summarize five key takeaways.
First, we delivered record profitability and strong operating cash flow, putting us on track to extend our record of raising performance cycle over cycle. Second, our year-over-year revenue growth rate continues to accelerate.
After reporting 3% growth in Q1 and 9% in Q2, we reported 13% top-line increase in the third quarter, and implied in our updated full-year guidance is 15% growth in the fourth quarter. Third quarter growth was underpinned by exceptionally strong demand for power generation equipment, particularly among global data center customers, along with improving orders for North America medium-heavy-duty trucks.
My fourth key takeaway is that we returned $661 million to shareholders through share repurchases and cash dividends. As we enter the fourth quarter and expect to generate record full-year operating cash flow, returning excess cash to shareholders remains an important priority.
Finally, we've updated our full-year 2026 outlook. We now expect revenue growth of approximately 10% at the lower end of the prior range and an EBITDA margin of approximately 18.2%, consistent with our prior range of 18% to 18.5%.
Lower-than-expected pickup truck volumes in North America are the primary reason for the downward revision to revenue guidance. Let me now walk through the financials in a little more detail.
Third quarter revenues were $9.4 billion, up 13% from a year ago. Sales in North America increased 15%, while international revenues grew 11%.
EBITDA was a record $1.8 billion or 18.9% of sales, compared with $1.2 billion or 14.3% of sales a year ago. Excluding the $240 million in Accelera goodwill impairment and inventory charges recorded in the prior year, EBITDA margin improved 170 basis points from 17.2% to 18.9%.
Higher volumes contributed to the improved profitability, partially offset by increased variable compensation expense, reflecting our outlook for record full-year earnings. The net impact of tariffs, if you're still asking about that, was immaterial in the quarter.
Gross margin was $2.6 billion or a record 27.7% of sales, compared with $2.1 billion or 25.6% of sales a year ago. The prior year included a $30 million non-cash inventory write-down related to our electrolyzer business included in the Accelera charges discussed earlier.
Excluding the inventory charge, gross margin improved from 26.0% to 27.7%. Higher volumes and favorable pricing, particularly in Power Generation, drove the improvement, partially offset by higher freight costs, some material costs, and increased variable compensation expense.
Selling, administrative, and research expenses were $1.3 billion or 13.4% of sales, compared with $1.1 billion or 13.6% of sales a year ago. The increase in dollars was driven primarily by higher development spending for upcoming North America on-highway platform launches, as well as the new mining and natural gas power generation platforms.
Higher variable compensation expense affected both cost of sales and operating expenses across our segments in the year-over-year comparisons, and I won't repeat that driver in each segment discussion unless it's the principal driver of the variation in results. Joint venture income was $127 million, up $23 million from the prior year, primarily driven by stronger performance in our Chongqing joint venture within Power Systems in China.
Other income was positive $27 million, compared with a loss of $186 million in the prior year. Excluding the prior-year $210 million non-cash goodwill impairment charge, other income was roughly flat year-over-year.
Interest expense was $81 million, down $2 million from a year ago. The all-in effective tax rate was 17.7%, including $75 million of favorable discrete tax items or 54 cents per diluted share.
All-in net earnings were $1.1 billion or $8.25 per diluted share, compared with $536 million or $3.86 per diluted share a year ago. The prior year included $240 million in non-cash Accelera charges, equivalent to $1.73 per diluted share.
All-in operating cash flow was $1.4 billion, compared with $1.3 billion a year ago. During the quarter, we returned $661 million to shareholders, consistent with our longstanding commitment to return approximately 50% of operating cash flow to shareholders.
The quarterly returns included $359 million in share repurchases and $300 million in cash dividends. I will now review segment performance briefly and our guidance for 2026.
Engine business third quarter revenues were $3.1 billion, up 20% from a year ago. EBITDA margin improved 350 basis points to 13.5% from 10.0% a year ago, primarily due to higher North America heavy and medium-duty truck volumes, more than offsetting weakness in the pickup truck market.
For 2026, we now expect revenue growth of 8% to 11%, compared to our prior guide of 9% to 14%, and EBITDA margins of 12.25% to 12.75%, compared with 12.5% to 13.25% previously. This updated outlook primarily reflects lower pickup truck demand.
Components revenues were $2.9 billion, up 23% from a year ago. EBITDA margin improved 180 basis points to 14.3% from 12.5%, primarily driven by higher North American heavy and medium-duty truck volumes.
For 2026, we now expect Components revenue growth of 8% to 11%, compared with our prior guide of 8% to 13%. We have updated our EBITDA margin outlook to 13.25% to 13.75%, compared with 13.5% to 14.25% previously.
These revisions primarily reflect lower-than-expected pickup demand, as well as weaker domestic on-highway demand in China. Distribution revenues increased 4% from a year ago to $3.3 billion, and EBITDA margin declined to 13.9% from 15.5% a year ago, driven by a lower mix of aftermarket revenues.
For 2026, we now expect revenue growth of 10% to 13%, compared with our prior guidance of 9% to 14%, and EBITDA margins of 13.6% to 14.1%, a tightening of the prior range of 13.5% to 14.25%. Power Systems revenues were a record $2.3 billion, up 15% year-over-year, and EBITDA margin increased 250 basis points to 25.4% from 22.9% a year ago, driven primarily by stronger power generation demand globally and favorable pricing.
For 2026, we now expect Power Systems revenue growth of 15% to 18%, compared with our prior range of 14% to 19%, and EBITDA margins at 25.1% to 25.6%, which is a slight tightening compared to the prior range of 25.0% to 25.75%, largely unchanged. For both Power Systems and Distribution, the outlook reflects the anticipated fourth quarter recovery of most of the shipments that were delayed from the third quarter.
Accelera revenues were $103 million, compared with $121 million a year ago, mainly due to lower electrolyzer sales. EBITDA was a loss of $56 million, compared with a loss of $96 million a year ago, excluding the non-cash charges described earlier.
This improvement reflects the benefits of previously implemented cost-reduction actions. For 2026, we now expect Accelera revenues of $350 million to $400 million, and net EBITDA loss of $260 million to $290 million, consistent with our prior guidance.
I also want to highlight an update on our HyLYZER electrolyzer products. During the third quarter, two wholly owned subsidiaries, Hydrogenics and Hydrogenics Europe N.V., issued a stop-use recommendation to customers of HyLYZER electrolyzer products following a planned review of operational data from the installed fleet.
At this time, Hydrogenics has not initiated a recall campaign and continues to evaluate whether any modifications are required to return the electrolyzers to service. The potential financial impact of this remains under evaluation and is not reflected in our guidance.
In summary, we've updated our full-year 2026 outlook for the company. We now expect revenue growth of approximately 10% at the lower end of the prior range, and EBITDA margin of approximately 18.2%, within the prior range of 18% to 18.5%.
Our effective tax rate is expected to be approximately 23% in 2026, excluding any discrete items. Our outlook for capital investments is unchanged between $1.35 billion and $1.45 billion as we continue to make critical investments to support future growth.
Overall, we delivered a strong third quarter: record profitability, solid cash generation, and continued growth across several key markets, demonstrating progress to our 2030 Analyst Day targets. Revenues in Q3 were a little below our own expectations.
Implied in our guidance is stronger fourth quarter revenue, with a key step-up in Distribution revenues, an important driver tied to power generation products, especially data centers. Our strong balance sheet and record cash flow generation give us the financial flexibility to fund long-term growth investments while continuing to prioritize returning excess cash to shareholders.
Far this year, we returned a total of $1.681 billion in the form of cash dividends and share repurchases, reflecting our confidence in our future prospects. I want to thank our employees around the world for their continued dedication and commitment to customers.
Now let me turn it back over to James, who assures me he's greatly missed earnings day and all the call-backs he's looking forward to after this call. Thank you.
James Hopkins (Vice President, Financial Planning, Capital Management and Investor Relations):
James Hopkins
Thanks, Mark. Out of consideration to others on the call, I'd ask that you limit yourself to one question and a related follow-up, and if you have an additional question, please rejoin the queue.
Donna, with that, we're ready for our first question.
Operator
Thank you. As a reminder, ladies and gentlemen, it is *1 if you would like to register a question at this time.
Today's first question is coming from Angel Castillo of Morgan Stanley. Please go ahead.
Hey, good morning. This is Alper on for Angel this morning.
I know you guys talked about fully passing through the NCPs next year. I guess two-part question: one, is that predicated on a disciplined OEM market?
Then two, is there a chance that the EPA won't make its final ruling until after 2027? Any color there would be helpful.
Jennifer Rumsey
We currently anticipate that the EPA will come out with their final rule. As you are well aware, they initiated the draft rule in July, comment period closed at the end of August, and they're making their way through those comments.
Our understanding is we'll likely see that in December. We anticipate that NCPs will be included in the final rule.
The question, and what's driving some underlying market uncertainty, is will they change the amount of those NCPs from the draft rule? We have been working closely with all of our OEM customers around product availability and plans, and we anticipate largely in next year, we'll sell more of the current products, but we've a phased transition that we've announced over the course of the year, launching limited production of the X10 and X15 in January, and then transitioning in the third and fourth quarter to full production of the new product, and then the B will move to the new product at the beginning of 2028.
Mark Smith
Our comments about recovering NCPs are from our customers, where those apply on the older products.
Understood. Thank you.
Then maybe just to follow up on the supply chain constraints you mentioned, could you just share some color on the nature of those bottlenecks? Then as they're resolved, which products do you see or which segments do you think should see the most benefit there?
Mark Smith
We identified a challenge with one of our suppliers in the third quarter in Power Systems. That's been worked on.
We expect to recover most of the engine production, which then flows into Distribution for installation to our customers in the fourth quarter. That's the primary one.
Demand is high, and so increasing supply, investing in capacity along with our suppliers is a key focus going forwards, not just for the fourth quarter, but generally I would say supply is tight both in Power Systems and in some of the on-highway markets. Specifically for the third quarter, the impact was within Power Systems, which had a knock-on impact to Distribution, and that's why you're seeing such a step-up in revenue in the fourth quarter in Distribution.
We would have expected, let's say, about $200 million more of that revenue to occur in the third quarter that's rolled into the fourth quarter. The other part of our revenue miss in the third quarter was market driven, which we try to be clear is tied to the North American pickup truck, heavy-duty part of the pickup truck market.
Operator
Thank you. The next question is coming from Jerry Revich of Wells Fargo Securities.
Please go ahead.
Jerry Revich
Yes, hi. Good morning, everyone.
I'm wondering if you could just talk about within Power Systems if you've seen any movement in the backlog given the election news and otherwise, and if you could just comment on the ability to shift production and deliver more into other regions if we do see movement in the backlog. Just would love you to comment on the broader puts and takes as you look at the production plan.
Jennifer Rumsey
Yeah. Jerry, sure.
Understand the question. I think a lot of people have that question, and you, of course, recognize the conversation that's happening in the US right now around energy use and environmental impact of data centers.
Our focus remains on meeting our customers' demands, and what I can tell you is those demands continue to grow. Our order intake in the third quarter exceeded what we thought it would be.
We continue to see exceptionally strong demand on our larger engine gensets, with orders extending out into the second half of 2028, as well as interest in the next size down from those where we can't meet customer needs with the larger gensets. We have multiyear strategic conversations to plan expectations with our customers, and those remain very strong.
We have contractual commitments with some of our big hyperscaler customers that extend beyond when we have firm order boards. What I'll tell you is we continue to see strong demand, and recall that that demand is global.
We've seen significant rise in China and Asia Pacific this year in addition to the already growing demand in North America. Our investments are in existing plants and assets that have a lot of flexibility to meet various customer global needs in industrial markets as well as various power generation markets.
Mark Smith
That's one of the other advantages of having a global in-house distribution system, that our global customers have that confidence of the support they're going to get wherever they operate.
Jerry Revich
Super. Can I ask you on the capacity expansion, obviously super CapEx efficient plan, can you just update us on how additional production is coming online, how that's going?
Mark, I believe if I've got the math right, fourth quarter implies potentially a step-down in Power Systems margins. I want to make sure that's right.
Looks like that's about 22.5%, but maybe there are moving pieces to think about.
Jennifer Rumsey
I'll talk just about the investments we're making. We're really making good progress, pleased, on track with those investments.
Really two key areas: the capacity investment that we're making, and we will start to see step-up in capacity next year, and then further step-up, most of that coming in the 2028 time frame, that we can use for both backup power as well as prime power applications. Then we're also making good progress with the development of our new 130-liter natural gas engine.
You've seen announcements of selling some of our existing natural gas products into prime power applications as well as BESS, and then we'll have some key development milestones and start to have pilot product in the market for the larger engine in 2028. That revenue really doesn't start to come in in a more meaningful way until 2029, but all of that's tracking to the plans that we had, and as I said, we feel we're well on track for what we committed for 2030 in our May Analyst Day.
Mark Smith
Yep, and then on the margin question, yep, of course your math's right, Jerry. I think Q4 is not going to be a forward-looking run rate.
There's always a bit of natural variation when you're investing in new products, bringing on capacity. You've got a few shorter production days in the fourth quarter.
Yes, the Q4 margins could be a little bit low, but that's not the run rate going forwards. There's no fundamental change in the underlying trajectory of the Power Systems profitability.
It's been a great story, and we're very confident global demand and the prospects for that business.
Operator
Thank you. The next question is coming from Jamie Cook of Truist Securities.
Please go ahead.
Jamie Cook
Hi. Good morning.
I guess my first question, just Mark, there's a lot of debate in 2027 and 2028 with just complications around EPA 2027 and phasing in and your investments on your ability to put up the targeted 25% incremental margins that you guys talked about at your Analyst Day this year. Just trying to understand your confidence level with Cummins' ability to do that, and is it more back-end loaded?
Just thoughts there. Then I guess just my second question, I guess what struck me about the quarter, is we miss on revenues, the margin performance was very strong.
Was there anything unusual that allowed you to put up good margins on a softer revenue base? Then, the margins implied in the fourth quarter are pretty strong, too.
I'm just wondering if the back half of 2026 margins is a good way to think about a starting point for 2027. Thank you.
Mark Smith
That's a wide range of related comments. What I'd say is number one, when we had our Analyst Day, best of my recollection, I tried to paint a picture across the different segments that Power Systems and Distribution would be more of a continuous story, that there would be part of a transition to new products on the engine business and components story.
That it's possible people are misinterpreting some of the comments we've tried to make about migrating to the new products. We are making great progress on revenues, we're making great progress on margins, set aside the individual quarter nuances, towards our 2030 Analyst Day.
Any comments I've tried to make about this transition in products, the engine business, I tried to flag that early at the Analyst Day, and our comments remain consistent with that. We knew we didn't have the EPA rulings when we had Analyst Day, we still don't have the final rulings now, and we're just trying to provide you with an ongoing description of what we expect to happen given more information, but still incomplete information.
The key takeaway overall is that 2030, we're making great progress towards those targets, and we're not in any way trying to signal anything other than strong progress towards them. We'll get to the very specifics next year.
There is nothing significant in the Q3 results, which is why Q4 also looks strong. I mentioned in Q2 we'd have to update our incentive compensation plan expenses, which happens every single quarter.
It just stood out more because of a year-over-year comparison. The trajectory of that incentive compensation is the same as I mentioned three months ago.
The absolute expense was up year-over-year, consistent with record profitability this year. It was down sequentially because we had to true up the full-year view.
In the grand scheme of things, not material. The underlying story is very strong performance.
We didn't quite get out as much revenue as we'd hoped. Our expectations were similar to consensus for what we thought our revenues would be.
Half of it supply chain issues, which we believe will catch up in the fourth quarter, and roughly half of it market conditions, primarily related to lower pickup truck. We feel very good about the profitability and the progress.
We feel very confident that we can do better as we continue to expand our revenues over the next few years. Also, as the CFO, particularly excited about generating record operating cash flow and returning that back on a disciplined basis.
I hope that's clear as I can make it. Next year we'll get into details next year.
Of course, there are complexities, but you should feel like we're entering with a very strong underlying margin basis we exit this year.
Operator
Thank you. The next question is coming from Kyle Menges of Citigroup.
Please go ahead.
Kyle Menges
Great. Thanks for taking my question.
I was hoping if we could dig into Power Systems margins and maybe a framework to think about it exiting 2026 and the incrementals. I think you've talked about maybe 25% to 30% incrementals for that segment going forward.
Understand there's a lot of moving pieces around the capacity ramp, maybe some incremental demand for smaller products, and then this battery opportunity coming in. Just any color you can provide on how to think about the incrementals in that business moving forward with all the puts and takes, seemingly.
Mark Smith
I would say that all those smaller comments are exactly the same. When we tighten the range by fractions of a percent, that's the same guidance.
We've just got one quarter left, we're just tightening up the range with two and a half months to go. Nothing's changed.
Stand by all of those comments. We'll give you the very specific guidance.
If you ask me today, do I expect revenues for Power Systems and Distribution next year to be higher, lower, or the same than this year, they're going to be higher with what we know today, and we expect over time that those businesses are going to deliver more earnings. There's going to be variation in individual quarters given the balance of investment and other things, but we're very excited about the prospects for Power Systems and Distribution.
We'll give you very specific guidance in February when we get there. Nothing's changed.
If anything, demand has gone up.
Kyle Menges
Got it. That's good to hear.
Then just to follow up maybe on North America on-highway. Curious how you're thinking about any potential pre-buy or pre-build of inventory in the back half of 2026 and managing through a potential air pocket in 1Q 2027 in production.
Curious how you're thinking about that. Thank you.
Jennifer Rumsey
Really what we've seen this year has been, we believe, pretty limited pre-buy in the US truck market, and actual growing underlying demand off of a cyclical low. Of course, it stepped up year-over-year significantly in the third quarter, and the industry and we are managing through some supply hiccups and challenges through that.
In the fourth quarter in Jamestown, where we build X15, we're really building at capacity. We believe that this year is largely sold out.
We're navigating some of our own supply challenges in components and axles in particular, and really focused on trying to deliver to customers through the end of this year and into next. We anticipate there'll be continued underlying demand as we go into 2027, but, of course, the uncertainty around where NCPs will be is causing some customers to wait.
We believe the fundamentals have improved, and the demand out there is real and will continue, and are really just focused on trying to execute through the big step-up we see.
Operator
Thank you. The next question is coming from David Raso of Evercore ISI.
Please go ahead.
David Raso
Hi. Thank you.
I was curious, can you help us with your power demand today, the domestic versus international, and any color around the profitability, and if you can incorporate the China JV in that answer? Because back in the day, the geographic color was usually minority US, Canada for power, but just given the recent trends and there's obviously more in the business than just power, can you help us with that mix, and obviously any sense of the profitability domestic versus international would be interesting.
Jennifer Rumsey
I'll just start with how we see the global business and demand. We've seen really strong demand here in the US and also in China and Asia Pacific, and, of course, that's where you see a lot of the AI model development happening that's driving that strong demand.
One of the benefits of Cummins is with our global product and manufacturing footprint and the distribution network, we can support those big customers wherever they go in the world. We have projects happening around the world.
In fact, I was in Spain in September and visiting a couple of our data center customers there. They really are global, but a larger percentage of them sit in US, China, and Asia Pacific.
The demand continues to grow, and as AI use grows in application, we think globally we'll see growing data center demand. Mark, you can talk a little bit more about how you think about margin.
Mark Smith
I think we definitely have strong margins, whether that's domestically or internationally. We're not a company that makes only margins in one particular region.
Depends what the application is. If it's a data center, then typically the EBITDA dollars are greater than another application because we get all the extra installation in our distribution business, but I would say that no significant difference.
The order intake has been very strong in North America for quite some time. It is picking up at a faster pace outside of the US such that the orders are almost on a par now between international and domestic.
That's not going to be a discussion point in our earnings calls in terms of the Power Systems performance on margins. That's not going to be the principal driver.
You're right, we share some of that engine margin depending on which engines we're talking about in the genset in China, if it's made in the joint venture. Our distribution, of course, is 100% Cummins extra slice of the pie.
No big variation. Mark,
David Raso
what you just said about international versus domestic on the orders, were you talking about magnitude of growth or the absolute dollars now international as big as domestic?
Mark Smith
I would say the absolute dollars on data centers. I'm not talking about other power gen, that's probably even bigger internationally.
On data centers, it's now reached a par across all international markets, which China, Southeast Asia is the most fastest accelerating piece, and we're in a very strong position there.
Operator
Thank you. The next question is coming from Rob Wertheimer of Melius Research.
Please go ahead.
Rob Wertheimer
Thank you. I had a couple questions around evolving capabilities for data center, and specifically on the battery backup announcement.
How repeatable is that? Is there a big pipeline for that, and does that in any way intersect with your potential JVs to make cells?
Then just more generally, Jennifer, I think you touched on the rollout of the 130-liter. Any early indications, I don't know if you're taking indications of demand at this point, are they doing pilot production, not this year, and then in '28, but how are you thinking about the commercial gathering of orders and when you start that?
Thank you.
Jennifer Rumsey
On the question around stationary energy storage, obviously early days for us. We have a big announcement.
What I would say is that the conversations and the interest in how to bridge to grid, grid availability, as well as grid unreliability continue only strengthen, especially here in the US. We think there's a real demand there, and so the places that we get a lot of interest, of course, is that stationary energy storage battery system.
To your question on the Amplify joint venture, that joint venture is planning to make a cell for commercial vehicle on-highway that's different than what we're using in those. We're sourcing that cell elsewhere.
On the natural gas product, you've seen a couple of announcements that we've already made around multiyear agreements and use of some of our natural gas product. That's largely our 78-liter that we have in production today.
Yes, there remains a lot of interest in the 130-liter, the larger version of genset that'll better meet that market need, and we're not taking specific orders at this point, really just talking about customer interest and where we want to pilot and build confidence in that product. We're excited to be growing there.
It's really going to be late this decade that we'll see that start to ramp up.
Rob Wertheimer
Thanks.
Operator
Thank you. The next question is coming from Tami Zakaria of J.P.
Morgan. Please go ahead.
Tami Zakaria
Hi, good morning. Thank you so much.
I wanted to ask you about that BESS contract you recently won, which seems exciting. Was this BESS opportunity embedded in your multiyear target?
If not, what kind of incremental revenue lift should we expect over that time frame that you have? Then would incremental margins on this type of revenues be similar to the enterprise target of over 25% through 2030?
Mark Smith
I think that's exciting project. Obviously, there are different forms of these projects evolving over time, but I would just say that's likely to grow, but not be the most significant factor in our Power Systems guidance.
By communicating that, we're just letting you know we're continue to expand our participation in meeting the flexible power needs of our customers, but it's not a fundamental change to the direction of Power Systems or changing in our outlook, which is very bullish for the top line and margin expansion going forwards in aggregate.
Tami Zakaria
Got it. That's helpful.
Then wanted to ask you about the price/cost dynamic in the quarter, and has it changed versus the first half of the year, especially as it relates to the Engine segment?
Mark Smith
I would say, generally, we're starting to see some creeping cost increases, right? Freight's gone up.
There's various bottlenecks around the world or areas of conflict or shortages. I would just say, generally, there's a little bit more creeping cost.
There's positive pricing for the company in total. I would say between price, cost, tariffs, in an environment where we significantly improved gross margins, all of that washed out to a slight negative.
Really it's the volumes and the execution of our operations that's driven the margin improvement. It is more of a slight headwind on price/cost in the second half for now.
Operator
Thank you. The next question is coming from Kristen Owen of Oppenheimer.
Please go ahead.
Kristen Owen
Good morning. Thank you for the question, and forgive me if I'm asking you to repeat yourself here.
I did want to start with the updated guidance for Distribution. That midpoint assumes sequential growth 3Q to 4Q of 23%.
Can you just help us unpack what supports that increase? Is that generator deliveries, installation milestones, service activity, just a little additional color there, please.
Mark Smith
The step-up is really driven by the Distribution didn't receive all of the large engines it expected at the end of the third quarter, and so some of their installations were pushed into the fourth quarter. You're right, it is an outsized number.
I tried to call that out. It's really just catching up the slight delays in the third quarter.
The full-year outlook is not changed. It is not a demand issue.
The demand is there.
Jennifer Rumsey
I think it's important when you think about our Distribution business, there's a few things that this business does. Of course, we have aftermarket and parts and service that happens through that business, and then they're also doing projects, and they're doing a growing number of these large data center power generation projects.
Broadly, we see higher margins in the aftermarket parts part of that business versus the power generation part of that business, which of course has been growing and very attractive, but just a way to think about that business and margins.
Kristen Owen
Great. Thank you.
Then my follow-up relates to the [Circe?] order, the 2 gigawatts there in Texas.
Just what milestones determine the delivery schedule there, and what needs to be in place at the customer level before that equipment ships? Thank you.
Jennifer Rumsey
That order is existing products. We're really working with them in terms of their installation plans and providing that product to them, and then potential for that to continue to grow and evolve as we bring the new product into the market over time.
Mark Smith
Just overall project schedule. Nothing particularly unique about the delivery of that.
Exciting, but not unique.
Operator
Thank you. At this time, I'd like to turn the floor back over to Mr.
Hopkins for closing comments. James Hopkins (Vice President, Financial Planning, Capital Management and Investor Relations):
James Hopkins
Thanks, Donna. I want to summarize five key points as we think now about 2027 and themes that we're anticipating, many of which we've discussed throughout the teleconference.
Number one, we expect continued strength in power generation related to data center customers that will positively impact both Power Systems and Distribution revenue next year as we bring incremental capacity online and is consistent with our data center revenue targets for 2030. Number two, industry expectations are for truck production in North America to be flattish in 2027 versus 2026, supported by increased freight rates in the second half of this year and improved fleet profitability.
Number three, the vast majority of our North America truck engine production next year will be on our legacy platforms. Number four, we plan to pass on NCPs to our customers.
Number five, we expect another year of strong operating cash flow and returning 50% of that operating cash flow to investors as we are on track to do this year. We'll give more detailed guidance, as Mark mentioned, when we get to our Q4 earnings call in next February, but those are some of the key themes that we're anticipating that will drive profitable growth as we head into 2027.
That concludes our teleconference for the day. I want to thank you all for participating and your continued interest.
As always, the Investor Relations team will be available for questions after the call.
Operator
Thank you. Ladies and gentlemen, this concludes today's event.
You may disconnect your lines or log off the webcast at this time and enjoy the rest of your day.