Claros Mortgage Trust, Inc.
Q1 FY2026 · Earnings Call TranscriptMay 7, 2026
Operator
Good morning, and welcome to Claros Mortgage Trust first quarter earnings conference call. My name is Tracy, and I will be your conference facilitator today.
All participants will be in a listen-only mode. After the speakers' remarks, there will be a question-and-answer period.
If you would like to ask a question at that time, please press *1 to raise your hand. To withdraw your question, press *1 again.
I would now like to hand the call over to Anh Huynh, Vice President of Investor Relations for Claros Mortgage Trust. Please proceed.
Anh Huynh
Thank you. I'm joined by Richard Mack, Chief Executive Officer and Chairman of Claros Mortgage Trust, and Mike McGillis, President, Chief Financial Officer, and Director of Claros Mortgage Trust.
We also have Priyanka Garg, Executive Vice President who leads credit strategies for Mack Real Estate Group. Prior to this call, we distributed CMTG's earnings release and supplement.
We encourage you to reference these documents in conjunction with the information presented on today's call. If you have any questions, please contact me.
I'd like to remind everyone that today's call may include forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Actual results may differ materially from those indicated by these forward-looking statements as a result of various important factors, including those discussed in our other filings with the SEC.
Any forward-looking statements made on this call represents our views only as of today, and we undertake no obligation to update them. We will also be referring to certain non-GAAP financial measures on today's call, such as distributable earnings, which we believe may be important to investors to assess our operating performance.
For reconciliations of non-GAAP measures to their nearest GAAP equivalents, please refer to the earnings supplement. I would now like to turn the call over to Richard.
Richard Mack
Thank you, Anh, and thank you all for joining us this morning for CMTG's first quarter earnings call. As we look ahead to the coming year, we believe that despite record highs in the equity markets, uncertainty will remain a defining theme across the broader financial markets as investors continue to navigate concerns around the impact of monetary policy and geopolitical events on the economy.
In particular, real estate capital markets appear to be relatively resilient amid heightened geopolitical risks and renewed concerns around inflation. We continue to see encouraging signals.
Transaction volume has improved modestly as compared to a year ago, and real estate credit spreads remain tight. At the asset level, multifamily deliveries and building permits have dropped dramatically nationwide.
In the industrial sector, we continue to observe strong tenant demand in many markets. Office is also beginning to emerge from the shadows as fundamentals recover in many markets, and reset valuations have started to attract renewed investor interest.
As we look to the broader capital markets, we have been observing the recent repricing in the private credit markets and considering the potential implications of this for real estate. One view is that the pullback in private credit will spill over into real estate.
However, real estate has already absorbed a meaningful reset in asset values because of the prolonged high-interest-rate environment. This should provide some protection against further declines in asset values, and perhaps at this moment, real estate represents a compelling relative value opportunity.
We might even see institutional investors rotating back into real assets as a protection against devaluations in private credit and the stock market generally. Regardless of how these market dynamics ultimately play out, we intend to build on the progress and momentum we established in 2025.
Our strategic priorities continue to be centered on turning over the portfolio, resolving watch list loans, repositioning our REO assets, and deleveraging the balance sheet. Successful execution on these priorities will position CMTG to evaluate new capital deployment opportunities towards the end of the year.
This may include new originations, additional deleveraging, reinvestment in select REO assets, and share repurchases. I'm pleased to report that we had a strong start to the year in meeting our goals.
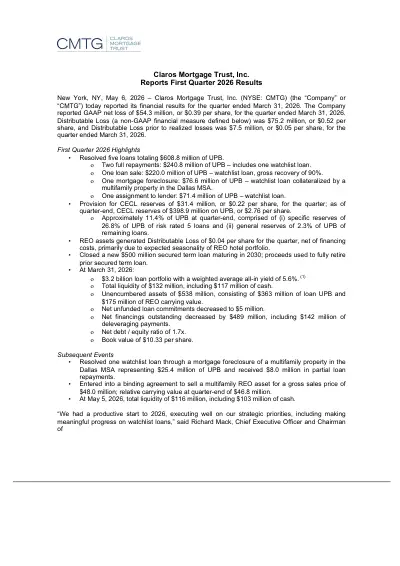
For the first quarter, we reported $609 million in loan resolutions, representing five loans, including four watch list loans. In addition, as previously reported, we retired the Term Loan B that was scheduled to mature later this year with a new $500 million senior secured term loan from HPS with four years of duration.
Mike will provide additional color on our financial and operating results later on the call. We believe that 2026 will be a pivotal year for CMTG.
Our first quarter results have built on the progress we made last year, and while uncertainty remains on the horizon, our team has demonstrated our ability to execute and drive outcomes in this environment. In 2026, we will continue to progress the cleanup of our balance sheet while selectively and opportunistically holding and improving REO assets.
While generally not something we speak about, we believe our stock is undervalued. We expect that with time, the continued execution of our strategic priorities will ultimately be recognized by the market.
Towards that end, we look forward to updating you on our progress throughout the year as we continue to deliver on our stated priorities. I will now turn the call over to Mike.
Mike?
Mike McGillis
Thank you, Richard. For the first quarter of 2026, CMTG reported a GAAP net loss of 39 cents per share and a distributable loss of 52 cents per share.
Distributable loss prior to realized losses was 5 cents per share. CMTG had an active first quarter and continued to execute our strategic priorities, completing approximately $600 million of loan resolutions related to five investments, four of which were watch list loans.
As discussed in our fourth quarter earnings call, we resolved two loans via regular-way repayment. The first was a 2-rated $174 million multifamily construction loan in Salt Lake City, which we originated in 2022.
The second was a 4-rated watch list loan, a $67 million New York City land loan originated in 2019. We also resolved two 5-rated loans during the quarter: a $77 million Dallas multifamily loan resolved through foreclosure and a $71 million Seattle office loan resolved by transferring our rights and interests to the financing counterparty.
Our fifth loan resolution of the quarter occurred in March. We completed the sale of a $220 million loan secured by a luxury hotel property located in Northern California.
Our loan had matured in August 2025, and as of year-end 2025, we had not agreed to modification terms with the borrower, resulting in a downgrade to a 4 risk rating. This is a unique, irreplaceable asset located in highly desirable submarket, which we believe may be worth in excess of our basis over time.
However, given our stated 2026 goals, we ultimately negotiated a quick off-market sale of our loan at 90% of par, which accounting for general reserves we had allocated to the loan at year-end, approximated our carrying value and allowed us to significantly delever one of our financing facilities. We view this as a positive and efficient resolution aligned with our strategic priorities.
Subsequent to quarter end, we resolved one additional watch list loan through foreclosure. A $25 million loan was collateralized by a multifamily property in Dallas, Texas and was previously 5-rated.
We believe we can create more value for our shareholders as owners of this asset rather than selling the loan. As a result of the resolution activity during the quarter, CMTG's held-for-investment loan portfolio continued to decline, decreasing to $3.2 billion at March 31st compared to $3.7 billion at December 31st.
We reduced our hospitality exposure from $807 million to $592 million and also reduced our land exposure from $187 million to $120 million. With our continued goal of turning over the book, we currently have eight lender-driven sale processes in various stages across our watch list loan and REO portfolios.
These collective measures could result in additional resolutions of approximately $861 million of loans at UPB and REO assets at carrying value and allow us to accretively redeploy repatriated capital. Turning to portfolio credit, the pace of credit migration has significantly slowed, with only two loans moving this quarter.
During the first quarter, we downgraded one multifamily loan from a 3 to a 4 risk rating and placed another 4-rated multifamily loan on nonaccrual. The downgrade is related to a $127 million loan collateralized by a portfolio of Texas multifamily assets and is due to the borrower being unwilling to invest additional equity ahead of the loan's June 2026 maturity date.
The loan that was moved to nonaccrual status is a $155 million loan collateralized by a Phoenix multifamily property and is related to continued loan delinquency and a lack of progress made on modification terms with the sponsor. CMTG is evaluating a variety of paths to resolution of both of these loans.
As of March 31, 2026, our portfolio consisted of 13 4- and 5-rated loans, down from 24 4- and 5-rated loans March 31, 2025, demonstrating our commitment to resolving watch list loans. During the first quarter, we recorded a provision for CECL of $31 million.
This consisted of a $32 million provision to our specific CECL reserve prior to charge-offs and a $27 million increase in CECL reserves on accrued interest receivable prior to charge-offs, primarily attributable to the previously mentioned loan sale at 90% of par. These items were offset in part by a $28 million decrease in our general CECL reserves, primarily attributable to first quarter loan resolutions.
As a result, our total CECL reserve on loans receivable held for investment decreased from $443 million, or 10.9% of UPB, at December 31st to $399 million, or 11.4% of UPB. Our general CECL reserve decreased from $78 million at December 31st, or 2.9% of loans subject to our general CECL reserve, to $50 million at March 31st, or 2.3% of UPB of loans subject to our general CECL reserve.
As discussed on our prior earnings call, in January, we retired our existing Term Loan B, which was scheduled to mature in August 2026, and replaced it with a $500 million senior secured term loan from HPS. The new term loan is a four-year term with prepayment flexibility, maturing in January 2030, and is priced at SOFR plus 675 basis points.
We concurrently aligned financial covenants across all of our financing facilities, which allows for enhanced flexibility to execute our business plan. We remain focused on deleveraging the portfolio.
During the first quarter, we reduced outstanding financings by $489 million, including $142 million of deleveraging payments. As a result, our net debt-to-equity ratio has decreased meaningfully.
At March 31st, 2026, our net debt-to-equity ratio was 1.7x compared to 1.9x at December 31, 2025 and 2.4x at March 31st, 2025. At quarter end, we had $132 million in liquidity.
In 2026, we continue to prioritize turning over the portfolio, resolving watch list loans, repositioning our REO assets, and deleveraging our balance sheet. We look forward to sharing our progress towards the goal of being in a position to make capital allocation decisions later this year.
I would now like to open up the call to Q&A. Operator?
Operator
Thank you. We will now begin the question-and-answer session.
If you would like to ask a question, please press * and the number 1 now to raise your hand. To withdraw your question, press *1 again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by now while I compile the Q&A roster. Your first question comes from the line of Jade Rahmani with KBW.
Your line is open, please go ahead.
Jade Rahmani
Thanks very much. I was wondering, the nonaccruals currently total $1.55 billion on 11 loans, around 44% of the portfolio.
Where do you expect that to trend over the next few quarters, or is there a year-end target?
Mike McGillis
Jade, why don't I start, and Priyanka can add to that. We have a number of sale processes in process that I mentioned on the call earlier, and that includes a number of these nonaccrual loans.
We expect to continue to chip away at that. It's hard to give a precise number as to where we're going to be at various points of the year.
The overriding objective is to get these non-earning assets, as well as sub-earning assets, off the books, use proceeds to pay down existing leverage, and reduce our interest expense and also generate incremental liquidity. We are actively looking at moving out of a number of these right now.
Jade Rahmani
Okay. I don't know if Priyanka wants to chime in, but maybe if you could just quantify the range of dollars of sale processes that are underway?
Mike McGillis
I think, Jade,
Priyanka Garg
as
Mike McGillis
I mentioned, there's eight active sale processes going on, as well as other activity. Those eight active sale processes involve about $860 million of asset value, either UPB with respect to loans or carrying value with respect to REO.
Priyanka Garg
Jade, it's Priyanka. Just to add to that, half of those, four out of eight, are loans, and it's about three-quarters of the $860 million that relates to loans.
All four are on the watch list, and all four are on nonaccrual. It's a good chunk of the nonaccrual number.
Jade Rahmani
Okay. Is there a target, when I look at risk 4, 5 loans, $1.75 billion, and then REO, $765 million?
Is there a target that you want that to get to by say year end or over the next 12 months? That all adds up to about $2.5 billion.
How much of that do you think is line of sight into somehow exiting in the next few quarters?
Priyanka Garg
As Richard and Mike both said, we're very, very focused on turning over the book. Our watch list loans at January 2025 was at $2.7 billion.
We're now down to $1.4 billion on the watch list. I think we've demonstrated over five quarters that we're very committed to bringing that number down.
Like I said, we have a number of those loans already on the market in various stages of sale processes. We've been really positively encouraged by the amount of activity, particularly given all the uncertainty going on in the world right now.
Hard to handicap how that occurs, but we're very focused on those resolutions. We had the hospitality loan that was on the watch list come off at the end of the first quarter.
Again, I think it's really hard to pin ourselves down to a number, but I would say the progress that we made over the last five quarters, we intend to keep pushing forward in the same way.
Jade Rahmani
Thanks very much.
Operator
A reminder that if you would like to ask a question or a follow-up at this time, please press *1 on your telephone keypad now to do so. I will pause for a moment to compile the Q&A roster.
It appears we have no further questions at this time, I would now like to turn the call back over to Richard Mack for closing remarks.
Richard Mack
Thank you, and again, thank you all for joining us. I will just reiterate that 2026 is going to be a year of continued execution on our priorities.
We've already had a first quarter of quite strong resolutions, and we're going to continue to sell into the market to the extent that we can, make sure that we push borrowers to refinance us now that the financing markets are stronger, so that we can clear troubled loans in REO, pay down debt, begin to increase cash, and pivot to offense, hopefully by the end of the year. Again, thank you all for joining, and we look forward to speaking to you all again next quarter.
Thank you.
Operator
This concludes today's call. Thank you all for attending.
You may now disconnect.