Cricut, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 3, 2026
Operator
Please be advised that today's conference is being recorded. I would now like to hand the conference over to your first speaker today, Chris Belfiore, Director of Investor Relations.
Chris Belfiore
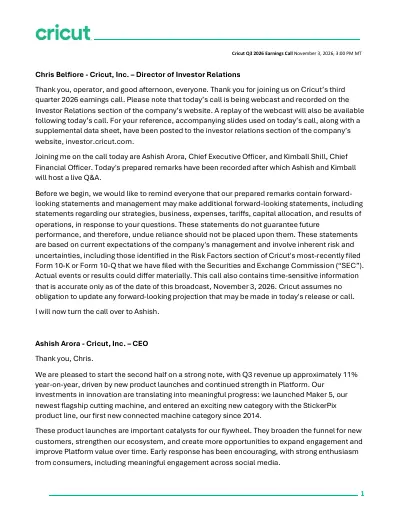
Thank you, operator, and good afternoon, everyone. Thank you for joining us on Cricut's third quarter 2026 earnings call.
Please note that today's call is being webcast and recorded on the Investor Relations section of the company's website. A replay of the webcast will also be available following today's call.
For your reference, accompanying slides used on today's call, along with a supplemental data sheet, have been posted to the Investor Relations section of the company's website, investor.cricut.com. Joining me on the call today are Ashish Arora, Chief Executive Officer, and Kimball Shill, Chief Financial Officer.
Today's prepared remarks have been recorded, after which Ashish and Kimball will host a live Q&A. Before we begin, we would like to remind everyone that our prepared remarks contain forward-looking statements, and management may make additional forward-looking statements, including statements regarding our strategies, business, expenses, tariffs, capital allocation, and results of operations in response to your questions.
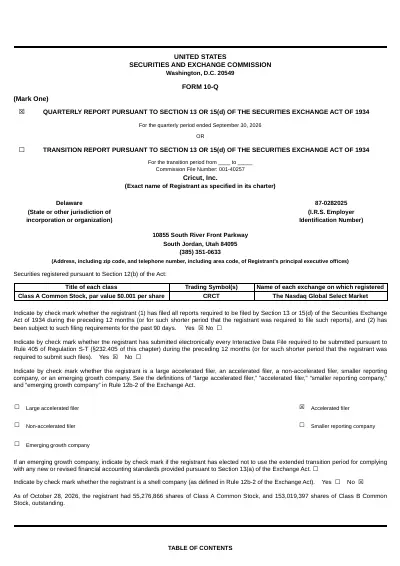
These statements do not guarantee future performance, and therefore, undue reliance should not be placed upon them. These statements are based on current expectations of the company's management and involve inherent risk and uncertainties, including those identified in the Risk Factors section of Cricut's most recently filed Form 10-K or Form 10-Q that we have filed with the Securities and Exchange Commission.
Actual events or results could differ materially. This call also contains time-sensitive information that is accurate only as of the date of this broadcast, November 3rd, 2026.
Cricut assumes no obligation to update any forward-looking projection that may be made in today's release or call. I will now turn the call over to Ashish.
Ashish Arora
Thank you, Chris. We are pleased to start the second half on a strong note, with Q3 revenue up approximately 11% year-on-year, driven by new product launches and continued strength in platform.
Our investments in innovation are translating into meaningful progress. We launched Maker 5, our newest flagship cutting machine, and entered an exciting new category with the StickerPics product line, our first new connected machine category since 2014.
These product launches are important catalysts for our flywheel. They broaden the funnel for new customers, strengthen our ecosystem, and create more opportunities to expand engagement and improve platform value over time.
Early response has been encouraging, with strong enthusiasm from consumers, including meaningful engagement across social media. Machine sell-out remained strong in our core cutting machine segment, and further helped by our new StickerPics category, increasing double digits for the second straight quarter.
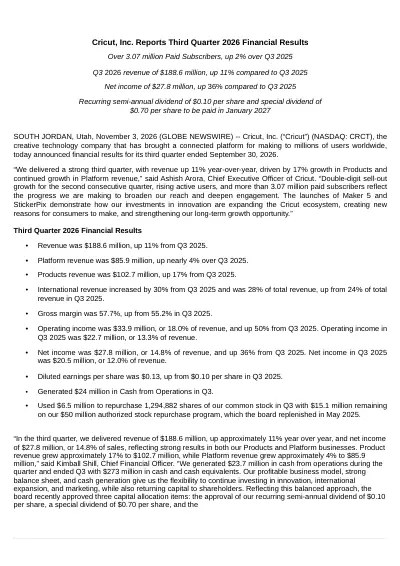
Platform revenue increased approximately 4% year-on-year to $85.9 million, while products revenue grew approximately 17% to $102.7 million. International revenue increased 30% year-on-year to $52.8 million, and represented 28% of the business.
Active users continued to increase, up 2% year-on-year, while 90-day engaged users remained flat. Paid subscribers grew 2% year-on-year, but declined sequentially, as expected.
We are excited about the opportunity ahead. Our investments are working to create a more compelling, accessible Cricut experience.
This year, we have launched three new cutting machines with all-new architectures and a more compelling value proposition. We are expanding the value of our platform for both new and existing users through continued innovation in content, AI-powered tools, and services.
With Cricut StickerPics, we entered a new category that lets users make custom stickers and photo prints at home in minutes. We are focused on translating this broader innovation pipeline into stronger execution, accelerating development cycles, expanding awareness, and sharpening our value proposition across products and price points.
We are continuing our investments to accelerate product innovation, platform, and awareness. Our goal is simple: to reach the right consumer with products and experiences that make creating easy, enjoyable, at the right price, while strengthening our competitive position and building a more durable path to long-term growth.
Let me talk about our priorities. In Q3, we continued to invest in marketing to broaden our audience and deepen engagement with the Cricut brand.
We continued to see strong traffic at cricut.com, as more consumers continue to learn about our products and platform. We're also seeing encouraging early signs from our "Think it.
Make it. Cricut."
brand campaign. The campaign brings our broader creativity platform positioning to life, showing how Cricut can help anyone turn an idea into something personal and meaningful.
Our goal is to make the brand feel more relevant, approachable, and accessible to a broader audience, while strengthening engagement with our existing community. A significant part of our marketing efforts this quarter was the introduction of Cricut StickerPics, our new line of machines that enables users to create high-quality, full-color stickers at home in minutes.
We supported the launch with one of our largest influencer activations to date, engaging creators alongside a robust paid media campaign. During the launch period, these efforts generated significant awareness and excitement around StickerPics, while introducing Cricut to new audiences at scale.
The increased awareness and new product activity supported a strong consumer response. Connected machine sell-out grew double digits year-on-year in Q3, building on the momentum we saw in the first half and benefiting from our newest connected machine launches.
Sell-out is a key measure of consumer demand and the effectiveness of our marketing investments. Recall, we don't have perfect coverage for sell-out data in all channels, treat this as directional.
We continue to work hard to build momentum and engagement across our platform. Active users grew approximately 2% year-on-year, and 90-day engaged users were approximately flat for the same period.
These results reflect the cumulative impact of our investments to improve onboarding and make the Cricut experience simpler and more compelling throughout the user journey on our platform. Improving onboarding remains one of our highest priorities, because an early, successful creative experience is critical to long-term engagement.
We continue to see progress in engagement among new users during their first weeks with Cricut. During the quarter, we further strengthened onboarding across our cutting machine portfolio by making educational content more visible, like pop-up training videos, and introducing features that help users explore, learn, and complete their first projects with greater confidence.
We also enhanced our AI-powered chatbot to provide more accurate, useful support. Adoption of guided flows continues to increase, particularly among new users, as we expand the supporting template library.
Internationally, improved search and localized language template discovery are making it easier for users to find relevant projects and inspiration. Together, these investments are helping reduce friction and make Cricut more approachable.
A major focus for our platform and engagement teams in Q3 was supporting the launch of our newest connected machine. For StickerPics Print and StickerPics Print and Cut, we introduced a redesigned end-to-end experience in Design Space that builds on platform capabilities developed over the past several years.
We also expanded the creative possibilities within our platform with new photo, sticker, and card project types. AI-powered tools can now turn a consumer's own photo and a simple prompt into polished, ready-to-print sticker sheets and photo prints.
With machine interactions purpose-built for dye sublimation, we are making the experience feel less like printing a picture and more like preserving a moment. That is a meaningful distinction.
While most photo printers offer utility, Cricut and StickerPics help people create something personal, expressive, and worth keeping. As we move into the fourth quarter, we're pleased with the return to year-on-year growth in active users and stability with 90-day engaged users.
While there is still work to do, we believe our continued investments in onboarding, localized content, and AI-powered creative experiences are building a stronger foundation for sustainable engagement and long-term growth. Our platform business continues to build momentum, with revenue of $85.9 million, increasing approximately 4% year-on-year in the quarter.
Premium tier plans are contributing positively, and we expanded their rollout across our largest international markets at the end of the quarter. Adoption has been encouraging, with limited impact on overall subscription sign-ups.
As we move forward, we will continue scaling premium plans, testing additional offerings and pricing structures, and expanding the AI-powered tools and benefits that differentiate our subscription experience. These investments are designed to improve member value and support continued platform growth over time.
Paid subscribers increased by approximately 2% year-on-year to just over 3.07 million, and declined modestly quarter-on-quarter, in line with our seasonal expectations. We continue to expect to grow paid subscribers and platform revenue in Q4 and for the full year.
We continue to invest in making our subscription more valuable and more central to the Cricut experience. For StickerPics, we introduced AI-powered templates that make it easy for members to create personalized photo and sticker sheets using the credits included with their subscription.
We also launched a dedicated library of StickerPics templates that simplifies the creation of photo collages and custom stickers. Beyond StickerPics, our Creative Labs team introduced an exclusive library of crochet patterns from leading fiber arts designers, along with an AI-powered tool that creates personalized paint-by-number sheets.
These additions reflect our focus on delivering a steady pipeline of differentiated tools, content, and creative experiences that help members get more from Cricut and deepen the value of their subscription over time. Looking ahead, we see significant opportunity to drive platform growth by expanding premium offerings and delivering an increasingly differentiated subscription experience through AI-powered tools, curated content, and new product experiences.
Our accessories and materials business remains challenging. We continue to work our plan to strengthen our product portfolio and improve our competitive position.
While the category remains highly competitive, we continue to gain share in some segments, including printables and Cricut accessories. Printables remains our fastest-growing category, reflecting growing consumer demand for personalized stickers, labels, photos, and gifts.
We expect to see help in this category as adoption of our new StickerPics product line drives consumables. Our Q3 innovation also supported the broader machine ecosystem.
We introduced engraveable blanks designed for Maker 5, taking advantage of its expanded material capabilities and improved engraving experience. We also introduced the StickerPics ecosystem, with refill packs that support photo printing and personalized sticker creation.
Through Cricut software experience and materials innovation, including die-cut shapes, we believe StickerPics brings differentiated capabilities to the dye-sublimation printer category. Looking ahead, we will remain focused on pricing and promotions, as consumers continue to prioritize value, while expanding our presence internationally through localized assortments and stronger channel execution.
We saw momentum in Q3 across our business. We saw strong machine sell-out and ongoing platform growth, continuing stabilization in engagement, and promising early response to StickerPics.
Innovation across products, content, AI-powered experiences, and services, combined with more effective marketing, is building a broader, more compelling Cricut ecosystem that can attract new users and deepen engagement with our existing community. We believe this strategy positions Cricut to deliver sustainable, profitable growth and create long-term value for our shareholders.
With that, I will turn the call over to Kimball.
Kimball Shill
Thank you, Ashish, and welcome, everyone. In the third quarter, we delivered revenue of $188.6 million, up approximately 11% compared to the prior year, with growth in our products and platform businesses.
Launch of new products in the quarter helped drive products revenue. We generated $27.8 million in net income, or 14.8% of total sales in Q3.
Breaking revenue down further, Q3 2026 revenue from platform was $85.9 million, up approximately 4% year-on-year. ARPU increased approximately 3% to $56.70 from $54.88 a year ago.
Platform revenue was up primarily due to the year-on-year increase in paid subscribers and the impact of higher-priced options. Q3 revenue from products was $102.7 million, up approximately 17% year-on-year.
Products revenue was up primarily from higher volumes of connected machines. Recall in Q2 2025, we had the opportunity to accelerate revenue in the face of tariff uncertainty, potentially lowering products revenue in subsequent quarters.
As a result, the growth in Q3 2026 likely includes some tailwind from an easier year-on-year comp. Even without any tailwind, we experienced solid products revenue growth.
As Ashish mentioned, global machine sell-out units grew double digits. Continued sales of Joy 2 and Explore 5, and the launch of Maker 5 and our new StickerPics products drove growth in the quarter.
International sales were $52.8 million, up 30% year-on-year compared to Q3 2025, driven by new product launches in more mature markets and the continued growth in our emerging markets. International revenue represented 28% of total revenue in Q3 2026, up from 23.8% in the prior year.
We continue to see positive results from our focused investments in key emerging markets, with significant year-on-year connected machine sell-out growth in Asia and LatAm. While these markets remain a relatively small portion of our total business, they are contributing positively across several key operating metrics, and continue to represent attractive long-term growth opportunities.
We were pleased to see double-digit sell-out growth in some of our more mature markets, such as Europe and Australia. Looking ahead, we plan to continue investing in international markets, with a focus on increasing brand awareness, expanding our reach, and driving member acquisition throughout 2026.
As Ashish mentioned, we ended the quarter with just over 3.07 million paid subscribers, up approximately 2% year-on-year. The sequential decline remained in line with normal seasonal expectations.
We remain focused on driving growth for the full year, supported by new product introductions, improved onboarding, ongoing investments in engagement, and promotional support. Moving to gross margin.
Total gross margin in Q3 was 57.7%, which was up 2.5% year-on-year, mainly due to benefits from scale, from growth in our products business, along with monetization of excess and obsolete inventory, and the last of our IPA tariff refunds. Breaking gross margin down further, gross margin from platform in Q3 was 89.9%, an increase compared to 89.2% a year ago.
As we've mentioned previously, there may be some gross margin pressure as we continue to ramp AI features. Gross margin from products was 30.8%, compared to 23.1% in Q3 a year ago.
The increase in gross margin for Q3 was primarily driven by the three factors we just mentioned. Total operating expenses for the quarter were approximately $75 million, and included $5.8 million in stock-based compensation.
Total operating expenses increased by about 5% from $71.4 million in Q3 2025. As Ashish mentioned, we are focused on increasing our speed of execution, and are accelerating investments across our business that will help drive future revenue growth.
Operating income for the quarter was $33.9 million, or nearly 18% of revenue, compared to $22.7 million, or 13.3% of revenue in Q3 last year. This reflects an increase of almost 50%.
The effective tax rate was 23.5% for Q3 2026, compared to 20% in 2025, in line with expectations. For the quarter, net income was $27.8 million, or 13 cents per diluted share, compared to $20.5 million, or 10 cents per diluted share in Q3 2025.
Turning now to balance sheet and cash flow. We continue to generate healthy cash flow on an annual basis, which funds our inventory needs and investments for long-term growth.
In Q3 2026, we generated $23.7 million in cash from operations, compared to $20.5 million in Q3 2025, reflecting the growth of our products business and seasonal ramp of peak inventory. We ended Q3 2026 with cash and cash equivalents of $273 million.
We remain debt-free. Subsequent to quarter end, we renewed our $300 million credit line through October 22nd, 2031.
During Q3, we used $6.5 million to repurchase 1.3 million shares of our stock. As a result, $15.1 million remained on our approved $50 million stock repurchase program.
Given our continued strong profitability and strong cash generation, the board of directors recently approved three capital allocation items: approval of our recurring semi-annual dividend of 10 cents per share, a special dividend of 70 cents per share, and the replenishment of our stock repurchase program up to $50 million, which incorporates the unused portion from the prior approvals. Both the special dividend and the recurring semi-annual dividend will be payable on January 21, 2027, to shareholders of record on January 7, 2027.
Recall, we do not give detailed quarterly or annual guidance, but we do want to offer some color on our outlook. We continue to expect platform revenue and paid subscribers to increase sequentially and year-on-year in Q4 and for full year.
For products, channel fill ahead of new product launches drove strength in Q3. Looking to Q4, we remain cautious about the consumer.
That said, so far, we are seeing positive sell-out data, which should translate to replenishment orders, and we expect products revenue to be up sequentially. We also expect to post full-year revenue growth as a company for the first time since 2021.
We expect to be profitable in Q4 and generate significant positive cash flow for the year, helped by our latest product introductions and continued strength in platform. Recall, Q4 is historically our most promotional quarter of the year.
Subject to stock price, we also expect to be active with our authorized $50 million stock repurchase program. We are focused on extending the current momentum by continuing investments in innovation across our products and platform, broadening awareness globally, and making Cricut more accessible across various price points.
Through "Think it. Make it.
Cricut." , we are introducing new consumers to a growing creative ecosystem that spans cutting machines, StickerPics, content, AI-powered tools, and services.
Our goal is to reach the right consumers with the right creative solutions at the right price, to deepen engagement across our platform, and build a more durable path to sustainable, profitable growth, and create long-term value for our shareholders. With that, I'll turn the call over to the operator for questions.
Operator
Thank you. At this time, we will conduct the question-and-answer session.
As a reminder, to ask a question, you will need to press *11 on your telephone and wait for your name to be announced. To withdraw your question, please press *11 again.
Please stand by while we compile our Q&A roster. Our first question comes from the line of Katherine Murphy with Goldman Sachs.
Your line is now open.
Katherine Murphy
Thank you for the question. It was encouraging to see the uptake and early momentum in new product categories like Cricut Maker 5 and StickerPics.
First to start, as we think about these new products being introduced, some at lower price points than historical, how should investors think about the trade-off between managing unit growth or product revenue growth with the profitability of these platforms? Then I have a quick follow-up.
Ashish Arora
Kimball, do you want to take the question, or do you want me to take it?
Operator
His microphone might be muted, one moment.
Kimball Shill
Our phone's not muted.
Operator
Oh, I can hear you now. Thank you.
Kimball Shill
Can you hear me now? Okay.
Sorry about that, guess we had a technical glitch, because we weren't muted. Cat, thanks for the question.
We're really excited about our new StickerPics category. It's the first new product category that we've entered in many years.
We're excited to bring innovation to an already established category, and using our AI-driven approach to creating a fresh approach for consumers. That said, it will take investment to establish ourselves in a category that's already pretty competitive.
Early feedback so far is very positive. It's too soon to tell kind of overall impact, and at this stage, it's not having a material impact to our margins.
It's something where we have an opportunity over time to drive costs out of that supply chain. It's also worth noting that initial production is happening in China, because that's where we could get the innovation done more quickly.
Over time, we expect to migrate production out of China to reduce the tariff impact and to drive lower costs on that new category. As it comes to Maker 5 and our core cutting machines, the team has done a great job of driving costs out of those supply chains as well, and re-engineering those to be much less expensive to manufacture, while still delivering an excellent experience.
One of the things that that has allowed us to do is include more consumables and accessories in the box, to support our bundle-only strategy. For our historical products, we continue to have strong margins, even while giving the consumer more value, and on the new products, we're innovating quickly and will drive cost efficiencies over time.
Ashish Arora
Cat, let me just add to what Kimball just stated. I think you talked about the prices, and I think there was a hint of are the prices lower than the existing products?
The prices for the two products, the Cricut StickerPics Print and the Cricut StickerPics Print and Cut, are mostly in line with our historical products. One of them is at the same price as Joy 2 when you look at the base product, and then the other one is at $299.
Because of our bundles-only strategy, and I was just on Google a few minutes ago before the call, the average price of everything that shows up, because a lot of these products are offered in bundles on top of the base SKU, roughly, at least for StickerPics Print, for example, were $299 to all the way to $349 to $369, or at least to somewhere in that price range, I don't misquote numbers, but at least there's been in the $300-plus range. I think they're not necessarily significantly lower than the existing portfolio.
The second is, again like Kimball said, the value proposition that we are creating, with the new tools and new experiences, especially given templates are being significantly more used in StickerPics Print family than in some of our even historical products. We're really excited about all the opportunities these products create.
Don't want to read too much into the data, but we're very encouraged by the data.
Katherine Murphy
Great, thank you for the thoughts. This is a quick follow-up.
On the product gross margins, understood in the prepared remarks you talked about the strength in the quarter as being attributed to scale, some monetization of excess inventory, and tariff refunds. Is there any way we can think about the opportunity for at least the scale benefit of those three factors to help as we think about the fiscal fourth quarter and any puts and takes to fourth quarter product gross margins we should be mindful of?
Thank you.
Kimball Shill
The thing about the scale benefit, part of it is we're building inventory, and we capitalize our procurement costs. As we build inventory levels, we capitalize more of that cost as opposed to expense it.
That is a margin help for the quarter. We also got the last of our IPA tariff refunds, which was a bit of a benefit.
As we move to Q4 and think about those margins, I would go look at prior Q4 activity, because it's our most promotional quarter. We just launched new products.
We're going to be spending marketing dollars to support those new products, and we'll be active with promotions. It tends to be a lower gross margin quarter.
Then, as we flow through inventory, where we have the procurement costs capitalized, that flows through and it bounces out over time, but ends up putting pressure on the quarters wherever we're taking inventory levels down.
Katherine Murphy
Thank you very much.
Operator
Thank you. Our next question comes from the line of Erik Woodring of Morgan Stanley.
Your line is now open.
Hi, this is Ralph on for Erik. Thank you for taking my question.
Product revenue grew nicely in the quarter, with Maker 5 and StickerPics contributing. Is there any way to quantify how much of that growth came from these new launches versus you called out easier compares, and or if there's any promotional activity?
Then also, I know it's might be early, but for 2027, any kind of directional framework you can provide around, say, active user growth, OpEx, and margins? That would be helpful.
Thank you.
Kimball Shill
Ralph, thanks for the question. We were really pleased with the quarter.
Like I said, we were up 11% for full year, or for full company, and 17% on products. That benefited from channel fill ahead of product launches.
We launched three products: a Maker 5, which is our flagship cutting machine, and so that's the third of our four cutting machines that we have launched in a new architecture for the year. We also launched StickerPics.
That did help. Haven't really broken out publicly the difference of the brand-new products in the quarter versus existing products.
We did see sell-out of all of our products that are new this year continued to remain strong. As you called out, we did see some tailwind related to the pull-forwards we had in Q2 of last year.
Recall that we had the opportunity to accelerate some revenue around tariff uncertainty as we support some of our channel partners with inventory. That, we didn't quantify it then, and so it's hard to really say how much that benefited Q3 this time and even Q4 next time, because we're pulling revenue into Q2 last time.
As I think about next year, it's a little bit too early to talk about what we think profit will be there. We have a number of one-time items that help this year, right?
We had IPA tariff refunds, we had a legal settlement that boosted profitability this year. As we think about Q4, we've already talked about that in the prior question, that we think that will be similar to prior Q4s.
As we look ahead to growth and where we think that comes from, it will continue to look much like this year in terms of continued new product investment and new products, right? We're continuing to invest heavily in a rich roadmap to drive innovation that we think will provide freshness and consumer interest.
International was an important vector of growth for us this quarter. We're up 30% and we expect international to continue being a long-term vector of growth for us.
Then we will continue investing in the awareness with our "Think it. Make it.
Cricut." campaign to bring a broader consumer to Cricut.
Those three things, product innovation, international growth, and increasing awareness, is ultimately what will help drive growth as we look to '27 and beyond.
Ashish Arora
Ralph, this is Ashish. I just want to go back to the first part of your question and just give a little bit more color on top of what Kimball said.
Right, StickerPics only launched towards the end of the quarter in the last few weeks, really kind of didn't really impact the whole quarter. In fact, the emerging markets, which grew very significantly for us, and at a very healthy run rate, didn't even get the product for majority of the quarter.
I think the comments that I would kind of zero in on is the things that Kimball said, right, that the POS from some of the existing connected machines, we feel really good about the momentum it showed, not just in the developed markets, but definitely POS of the connected machines, which are the kind of majority of the machines that were sold in the emerging markets, also showed a lot of strength.
Operator
Thank you. Our next question comes from the line of Adrienne Yih with Barclays.
Your line is now open.
Angus Kelleher
Hi, this is Angus Kelleher on for Adrienne Yih. Thanks for taking my question.
I wanted to ask about OpEx leverage. I think this was the first quarter of operating expense leverage since 2Q '24, congrats on that.
How sustainable is that leverage, and maybe remind us of what level of growth or what revenue base you need to approach the longer-term margin targets, or otherwise just get leverage in the business? Thank you.
Then I have a follow-up. Thank you.
Kimball Shill
Again, the leverage this quarter really is related around we're building inventory levels related to new product launches. For the last few years, we've been bringing inventory levels down as we worked through kind of post-COVID inventory levels, right?
As we go through a normal cycle of building inventory and selling through that inventory, we're capitalizing costs as we build inventory levels, and then that will flow through. We still think meaningful leverage comes when we hit about $1 billion in scale.
Not just from manufacturing and inventory, but in terms of spend on marketing and the other forms of OpEx. A billion dollars in revenue is still kind of we think the inflection point for scale.
Angus Kelleher
Got it. Go ahead.
Sorry, was I interrupting someone?
Kimball Shill
No, I was wondering if it was part of your question I hadn't answered, I was looking at my team.
Angus Kelleher
No, that was great. Thank you.
My follow-up will be for Ashish. Look, I understand it's still kind of early days on the Maker 5 and StickerPics, but any information you could share about who is buying?
Is it existing users upgrading, lapsed users re-engaging, or are these new customers? I guess does StickerPics reach a meaningfully different consumer?
Ashish Arora
Yep. Good question, Angus.
Let me start with first marketing and engagement. I'm incredibly proud of the team both around the world, right?
If you look at there's so much content that is generated, the engagement is incredible, and we've definitely stretched the brand in a very meaningful way. We have lots and lots of examples of where we are going after new audiences.
This is a gender-neutral marketing launch, lots of male influencers, lots of mega-influencers. We had more influencers by factors than we've ever had, both in terms of the number of influencers, the type of influencers, the categories of influencers, was just a shining moment for the company and the team overall.
Now, I think the answer is yes to all of those things that you mentioned, right? We have a very passionate audience.
In the first few weeks, obviously, there was existing members that went in to purchase the product, but very quickly, and, even compared to historical results, new members are coming in at a faster rate than they have come in for the past products. I think existing members are buying it because they're just passionate, and this is again a different product for them.
New members are starting to increase in terms of the percentage of customers who are new and are coming into the category. Actually, what's one of the most encouraging things is that, even from an subscription standpoint, folks that have not engaged with some of those, and again, I don't want to overproject the data, it's still cautiously reading into the data, but users that have in the past not engaged with the subscription product who bought the machine are actually engaging with that product.
I think the answer is yes to all of those categories that you mentioned, and I think we're going to continue to double down and going after new demographics. I think we definitely stretched the brand, and we will continue to stretch it even with not just with this first version of the products, but the products and the innovation we're planning to launch in the future.
It's a big part of our strategy.
Angus Kelleher
That's awesome. Great color, and best of luck with the holiday.
Ashish Arora
I'm going to have to send you some very, very entertaining influencer content.
Angus Kelleher
That's great. Looking forward to it.
Operator
Thank you. As a reminder, to ask a question, you will need to press *11 on your telephone and wait for your name to be announced.
To withdraw your question, please press *11 again. This concludes the question-and-answer session.
Thank you for participating in today's conference. You may now disconnect.