Digi Power X Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 13, 2026
Moderator
Good morning, and welcome to the DigiPowerX Inc.' s third quarter 2026 financial results conference call.
Please note that this event is being recorded, and a transcript will be available on DigiPowerX Inc.' s website.
At this time, all participants are in a listen-only mode. A brief question-and-answer session will follow the formal presentation.
Unless noted otherwise, all amounts referred to during this call are denominated in US dollars. Certain comments made during this call may include forward-looking statements or forward-looking information within the meaning of applicable US and Canadian securities laws, including statements regarding the company's 2027 outlook, capital plan, and anticipated financing.
Such statements and information reflect current expectations, and as such, are subject to a variety of risks and uncertainties that could cause actual results to differ materially from current expectations. Those risks and uncertainties include, but are not limited to, factors discussed in DigiPowerX Inc.'
s report on Form 10-Q for the three and nine months ended September 30th, 2026, and the annual report for the year ended December 31st, 2025, as well as the company's other disclosure documents. Except to the extent required by applicable law, DigiPowerX undertakes no obligation to publicly update or review any forward-looking statements.
During the call, management may make reference to certain non-GAAP financial measures that are not separately defined under GAAP, such as EBITDA and adjusted EBITDA. Management believes that those non-GAAP measures, when considered in conjunction with GAAP financial measures, provide useful information for both management and investors.
Reconciliations between GAAP and non-GAAP measures are presented in tables accompanying the press release highlighting DigiPowerX financial results for the quarter ended September 30th, 2026, which has been filed and made accessible under the company's continuous disclosure profile on SEDAR+ at www.sedarplus.ca, and is also available on the SEC's EDGAR website at www.sec.gov/edgar. I'd now like to turn the call over to Michel Amar, CEO of DigiPowerX.
Please go ahead, sir.
Michel Amar
Good morning, everyone, and thank you for joining us today as we share our results for the third quarter of 2026 for DigiPowerX. Our third quarter results show that DigiPowerX transformation into AI infrastructure company is beginning to take hold.
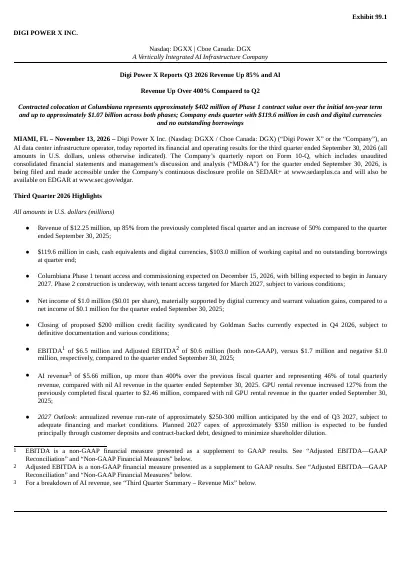
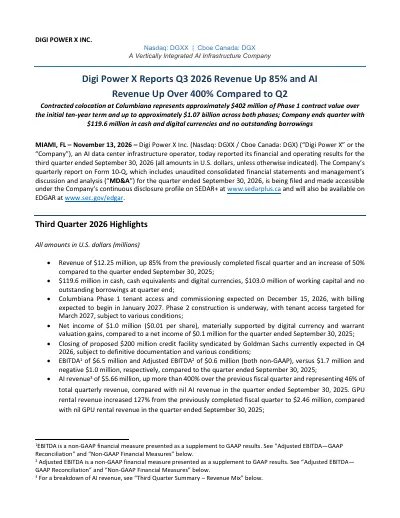
Third quarter '26 highlights: our revenue went up 85% to $12.25 million from the second quarter of 2026 and up 50% from the third quarter of 2025. AI revenue of $5.66 million, up more than 400% from the second quarter and representing now 46% of total revenue, compare with no AI revenue in the third quarter of 2025.
GPU rental, bare metal, through NeoCloudV, of $2.46 million, up 127% from the second quarter, compared with no GPU rental revenue in the third quarter of 2025. Energy sales through our power plant of $3.29 million, up 68% from the second quarter and 9% year over year.
Legacy Bitcoin activities fell to approximately 27% of revenue from 63% a year ago. AI revenue more than offset that decline.
Positive EBITDA of $6.5 million and positive adjusted EBITDA of $0.6 million compare with $1.7 million and negative $1 million, respectively, in the third quarter of 2025. Positive net income of a million dollars materially supported by digital currency and warrant valuation gains compare with net income of $0.1 million in the third quarter of 2025.
Let's talk about the balance sheet and liquidity as of September 30, 2026. Cash and cash equivalents and digital currencies of $119.6 million.
Working capital of $103 million compared with $17.5 at September 30, 2025. Digital currency holding of $24.5 million, up 56% year over year.
Net fixed assets of $145.6 million, up 646% year over year, reflecting infrastructure investment primarily at the Columbiana, Alabama facility. No outstanding borrowing as of today.
Balance sheet and liquidity as of today, November 13: the company's cash, cash equivalent, is approximately a little bit above $100 million cash. $168 million year-to-date capital expenditure deployed towards GPU equipment and data center build-out at the Columbiana, Alabama facility.
Operational highlights and outlook: Columbiana, Alabama AI campus. Construction of Phase 1 remains on schedule.
We expect to give our tenant access to the Phase 1 facility on December 15, 2026, basically in four, four-and-a-half weeks from now, and we'll start commissioning all the liquid cooling and power system at that time, with Phase 1 billing expected to begin in January 2027. Work on Phase 2 has started already for a few months, and subject to various conditions, we are targeting tenant access for Phase 2 in March 2027.
We are on schedule to be also on time to give access. A lot of investment has been towards Phase 2 already.
Our 10-year take-or-pay colocation agreement with our tenant, Cerebras, our AI colocation tenant at Columbiana, is expected to provide Phase 1 fees averaging approximately $40 million per year over the 10-year term or approximately $402 million in total. Phase 2 would add approximately $58.5 million in annual fees, bringing combined average annual fees to approximately $107 million per year and a total contract value to approximately a billion point 07 for both phases.
The agreement also includes an option to expand the relationship for an additional term, which could increase the total potential contract value to approximately $2.5 billion. NeoCloudV token factory is live.
We launched this quarter, from Berlin, our token factory taking DigiPowerX from AI infrastructure provider to direct seller of AI tokens. Running on our own power, data centers, and GPUs, the platform sells AI inference straight to customers.
The huge advantage of that are the margins. We see margins anywhere from 85% to 90%, actual margins.
It's a business that will create a lot of positive cash flow as we invest in it. Because we own the full stack, we keep the value of every token we serve, instead of renting out compute at wholesale prices.
We expect the token factory to unlock a new, fast-growing revenue stream with meaningful, higher margins, a major step in turning our infrastructure into full-scale AI business. Let's talk about the $200 million project-level debt financing.
As announced on October 13, 2026, we received a commitment letter from a major lending institution for $200 million in debt financing, syndicated by Goldman Sachs, to support the development of our 40-megawatt AI data center in Columbiana, Alabama, and to strengthen our balance sheet. The financing is expected to be structured at the project special purpose vehicle level with an unsecured company guarantee through project completion and other limited matters.
The proceeds are intended to support completion of the Columbiana project and related project costs. Closing is currently expected to close in the fourth quarter of 2026, subject to definitive documentation and the satisfaction of various conditions, including the lender's completion of its deep due diligence.
2027 outlook and capital plan: we expect to reach an annualized revenue run rate of approximately 250 $200-$250 million to $300 million or approximately $21 million to $25 million per month by the end of third quarter 2027, subject to adequate financing, market conditions, and various other conditions. Approximately $143 million of that run rate is supported by current operations and the Columbiana tenant agreement.
The balance is expected to come from additional AI colocation and GPU capacity currently in development and in customer negotiations. CapEx: we expect 2027 CapEx of approximately $350 million, primarily for approximately 10 megawatts of AI inference or token factory at 85%-90% margins capacity, and the completion of our Phase 2 Columbiana.
We intend to fund this principally through customer deposits and prepayments and contract debt financing, including the proposed $200 million facility together with cash on hand. This approach ties capital deployment to contracted revenue and is designed to minimize shareholder dilution.
I want to remind every shareholder that in 2016, I invested from my personal cash, $8 million, and I never sold one share. Just to tell you that I have a long-term vision of a huge return on my investment.
US Data Centers update: DigiPowerX owns approximately 48% of US Data Centers Inc., which design and deploys the ARMS modular AI data center system, and is developing URP-1, a robotic platform for automated deployment and maintenance. USDC is raising capital independently, which will further dilute our ownership interest, without capital contribution from DigiPowerX, without the issuance of DigiPowerX shares.
In order to fund our growth, which is very promising on US Data Center, we're going to raise capital without diluting DigiPowerX or without getting any allocation to DigiPowerX. I think that's very important for everyone to understand that DigiPowerX today is very focused on power, on GPU bare metal, on colocation deal, and cannot afford to allocate extra dollars to expand robotics or modular systems.
That's the reason why we have a different setup to raise capital. What are the opportunity for growth and expansion?
We continue to prepare our New York infrastructure assets for conversion to AI data center operation, and we are targeting the transition of these sites beginning of third and fourth quarter 2027. These sites are powered one is powered for the last 10 years, 18.7 megawatts, and another one where we have a total of 120 megawatts including our generation of power is been powered for 30 years in terms of generation.
We got an allocation from the utility, which is great because it's all green power, hydropower, and we got an allocation of 63 megawatts there. Because of our financial discipline, we haven't rushed to develop it simultaneously with the Alabama Columbiana AI center in order to control our CapEx.
We don't want to rush and be out of cash. As we transition from a project to execution, which we have been sharing videos of our progress and I was there actually a few days ago and it's really we are very close to finalize Phase 1, few weeks.
As we transition from project to execution, to live, then we can keep on going with our other assets. In North Carolina, we own now two sites, about 40 acres adjacent to one of the state's largest electrical switchyard.
Our current development plans contemplate two times 75 megawatts, about 150 megawatts, for 2029 and 2030. That will secure our growth over future years.
Between New York and North Carolina, we can expand to over 400 megawatts worth of capacity, which, depending how we optimize each megawatt, is huge revenues. Currently we own the assets to grow 2x, 3x every year for the next few years.
Revenue increased 85% over the previous quarter, and AI now accounts for nearly half of our business, all before the expected start of Columbiana colocation billing in January 2027. Our priority now is execution, financial discipline, and then we expand our compute capacity and convert our power assets into long-term contracted revenues.
We ended our quarter with approximately $120 million in cash and cash equivalents that give us a strong foundation for this next phase. We are building this business with a clear focus on value per share.
Our approach is to secure bankable customer commitments, deploy capital against attractive returns, and fund expansion through customer contribution and contract-backed financing. Our ambition is substantial, and our discipline is equally clear: grow recurring revenue and cash generation while minimizing shareholder dilution.
Thank you for joining us today. We will now take question.
Moderator
Thank you. Our first question is: What do Q3 results demonstrate about DigiPowerX's AI transformation?
Michel Amar
It's really an incredible quarter for us. If you think that last year we were a basically dying Bitcoin company, and we had very little cash January 2025, I think $1.7 million, very little assets, net fixed assets were $30 million.
In a year, we went from no cash, little assets, a Bitcoin dying business, to cash, $130 million, $140 million of net fixed assets, CapEx this year already invested of $160 million, and AI revenues that represent almost half of our total revenue. We believe that it was a transformative year and quarter, as we are growing accordingly to our pace.
We started to process data bare metal rental in May, very successfully, and a lot of companies came to our site to see our execution, and everybody's very impressed.
Moderator
Thank you. How much revenue is reoccurring or contracted?
Michel Amar
Columbiana, Alabama provides our strongest long-term contractual revenue visibility, with a 10-year take-or-pay agreement. Phase 1 represents approximately $402 million in contractual fees, increasing to approximately $1.07 billion with Phase 2.
NeoCloudV and our other operating business also generate ongoing revenue, although contract duration and utilization vary anywhere from two to five years. We are focused on increasing the share supported by long-term commitments: five years for NeoCloud and 10 to 15 years for colocation.
Moderator
Thank you. What does the December 15th Columbiana milestone represent?
Michel Amar
December 15th is a key number, and considering that we signed the deal with our tenant, Cerebras, early May, which is really few months ago, it's really incredible that we managed to design and finance and set up Phase 1 in basically 7 months. I believe we are one of a kind to be able to execute on such a short period of time.
December 15, tenant will have access to the data hall, and we will start commissioning the power and all the liquid cooling systems that are basically done. It's a very important delivery milestone for us, as a landlord, after the commissioning, we can start billing.
Moderator
Thank you. What is the financial value of the Columbiana agreement over 10 years?
Michel Amar
As stated a few minutes ago, the 50 megawatts first phase represent about $402 million over 10 years, and the second phase of 25 megawatts represent an additional a little bit over $600 million, for a total of $1.07 billion, averaging about $107 million annually.
Moderator
Thank you. Is Phase 2 on track for March 2027 tenant access?
Michel Amar
Construction of Phase 2 has already started. There's a lot of common denominators between Phase 1 and Phase 2.
The data hall has both phases in the data hall. It's there.
All the fire suppressing requirements, all the chillers are already there for both phase, Phase 1, Phase 2. All the equipment has been purchased for both phase, Phase 1, Phase 2.
We designed that contract to be able to do two-phase so we can financially support it no matter what. We're very advanced in the Phase 2 as well.
We don't see any issues to be giving access to Phase 2 in March 2027. The commissioning will be easier because all the liquid cooling commissioning will be done this month and early December.
We believe that the time of commissioning will be shorter in March, and we expect to bill in April the full total monthly contract.
Moderator
Thank you. What additional value could the renewal options under the Cerebras contract provide?
Now
Michel Amar
it's a little bit under $1.1 billion for the initial term, and we can go to a total of $2.5 billion as an option. We believe that the investment of a tenant is so huge.
They're going to locate in that data hall billions of dollars of equipments of servers and GPUs, and it's very costly for a tenant to move out. Not only it's costly, it's their economic interest to stay as much as they can, as the power shells are very scarce these days.
The value, in our opinion, will be much greater in 10 years from now.
Moderator
Thank you. Where does the proposed $200 million financing stand?
Michel Amar
It's interesting because earlier we had an approved financing that I denied in July from a very big, one of the biggest world institution, because I didn't like the terms. Then we decided to deny an approved financing to move and syndicated through Goldman Sachs, and which saved us on this financing about two points, which is incredible.
As the interest rate went up, we managed to save two points on the financing. We are pretty close to close the financing.
We got the long documents, we expect to close in the near future, definitely in Q4 '26, but we are pushing to close earlier. I think we are the one of the best candidates for a lender, as we invested our own capital, we have cash, and we are executing on time.
We are a pretty good candidate for a lender. We managed to be in single-digits interest, which is rare these days.
Moderator
Thank you. How will the approximately $350 million 2027 capital plan be funded while minimizing dilution?
Michel Amar
Our funding strategy combines customer deposits and prepayments. With the crisis that happened in the last four, five weeks, which was torture for our stock price, but misery likes company, the entire market went down.
It also gave us an opportunity to ask for bigger deposits on new contracts. Now the few discussions that we have, and we're finalizing to set up new contracts, we are getting much more than we used to, 6 months ago.
If 6 months ago, a tenant or a bare metal renter was willing to give you 15%, now they're willing to give you 30%. Sometimes up to 50%.
Sometimes, as we are negotiating now, up to 70%. Then, financing from the customer perspective becomes so easy for us to grow, because we achieved something incredible.
We are credible. We are not a company that talks about power and may have a connected power with the grid in '28, '29.
We are [laughter] executing. A lot of very big companies came to our sites, very large companies came to our sites, and understand that we are for real, that we are credible.
Now they are willing to support us and give us bigger deposits, and help us finance our growth. That's the major accomplishment that we are realizing by execution.
Moderator
Thank you. What supports the $250 to $300 million annualized revenue target?
Michel Amar
We already have about $143 million on the contract, and the remaining $107 to $150 million are expected from our development of the other sites through colocation or GPU capacity. If we had a open bank checkbook, we could have done it for Q1 or Q2, but considering the market condition and our financial discipline, if you want to go fast, we have to walk slowly.
We have to be careful. We survived all the Bitcoin cycles years since 2016.
We always survived. We don't want to be exposed to a financial issue by growing too fast.
We have time. There's plenty of market share for us to get, and we believe that Q3 will be in the run rate of what we announced.
Moderator
Thank you. Can operations generate sustained positive cash flow?
Michel Amar
Let's talk about Q3. We generated $4.7 million of positive cash flow in Q3 with the help of a $12 million non-refundable tenant infrastructure contribution.
We believe that next quarter we will also be cash flow positive between the business and additional non-refundable contribution, a bigger one this time because of the relationship from 15 to 25 megawatts. When we are live, then we have cash flow coming in.
We believe we are in a good position today to create positive cash flow.
Moderator
Thank you. What drove NeoCloud's growth, and are its margins sustainable?
Michel Amar
We started with bare metal GPU rental, and you saw the increase of 127% sequentially to $2.46 million as NeoCloudV scaled. The opportunity of bare metal and GPU as a service and token factory is to increase your revenue per megawatt and your margins per megawatt.
Considering the environment, the political environment, and by the way, we're very lucky to be in Alabama. I was at the election night last Tuesday with the governor-elect, the coach Tommy Tuberville, which I have a great relationship, and he reiterated directly to me that he's welcoming data centers in Alabama.
He's welcoming our contribution. He's welcoming our job creation.
He's welcoming the incredible science and technology of AI that will save lives, cure cancer, and cure most of incurable diseases. He's very pro-technology and he's welcoming growth in Alabama.
We're very excited because we definitely can expand in Alabama and contribute to the communities, and create a lot of jobs. Now in our campus, in a very small city, we have about 250 construction workers, highly paid jobs that are going to restaurants, that are going to hotels, that are creating an economic boom locally.
It's really interesting and we're really excited to be in Alabama there. To go back to this business of maximizing and optimizing per megawatt, considering the scarcity of power and the upcoming regulations of power, where they're going to start to, basically state-to-state, limit powers below 50 megawatts, I don't think you're going to see 500-megawatt campus or 1-gigawatt campus.
I think the strategy is more into the 50-megawatt, 25-megawatt campuses, which is very big in if you do GPU bare metal, very big revenues. Bare metal to today, bare metal, we can book short-term B200 at $7.75 per hour, bare metal.
If we do tokens, it's $15 to $20 per hour equivalent, per token. The pricing is booming on the GPU as a service.
It makes sense because the bottleneck, the struggle, the constraint, is permitted, available power. Why it creates an opportunity for small company like ours is that we do own the power.
We understand all stacks, from power generation to token factory, which is very rare. Not a lot of companies generate power and are able to sell tokens.
Every megawatt now we know how to maximize revenue and the value. We can get easily $2 to $3 million a month per megawatt.
If I just convert 50 megawatts, that's $100 million a month, okay, at, by the way, very high margins, 85% to 90% margins. Our catalyst is execution, which we are 95% there, and financial discipline.
We are an incredible company.
Moderator
Thank you. What is the path to securing an AI customer for New York?
Michel Amar
The market is such that there's so much demand, and there's much more demand today than 6 months ago. As we shifted from training to inference, it's exploding.
The demand is exploding. We have many potential contracts now that we could sign, and we are being very, very cautious and making sure that we leverage the scarcity of our powered assets.
Like New York is permitted and running, Bitcoin still, legacy business, as a data center. It's there.
We just have to shift it to a redundant data center. We want to make the right deal for the company.
We were not in a rush because of the financial discipline, and we want to close our debt financing, and then we're going to develop our New York asset, which going to be an incredible revenue asset. There's plenty of demand.
There's no issue of finding a customer, plenty of demand and including few IG, investment grade, customers. We're very excited about New York.
Moderator
Thank you. How does the 48% USDC ownership create value for DGXX shareholders?
Michel Amar
The value and the protection of DigiPower capital. Of course, DigiPower could want to produce everything, transformers, switchgears, and will be without any capital left for the focused business.
By being a major shareholder, the biggest shareholder of US Data Center, that's now planning to produce parts system, which are very adequate, by the way, the timing is incredible because you're going to see we are getting, on the US Data Center, a lot of action on smaller sites. Because that's what's available and that's what is under the radar politically.
A lot of action for us for '27 and '28. It's going to be an incredible company, by the way.
Related to this modular system that are housing all the different brands of GPUs, not only Nvidia, but the B200, the Vera Rubin, the Vera, NL4, NL8, the Cerebras CS-4, CS-5, the AMD, the Helios, the GB300, we have everything set up, and under the US Data Center, we are also getting deposits from customers to finance the growth along with debt financing in the future. The slight dilution to get capital does not affect whatsoever DigiPowerX.
Now on US Data Center, we are looking to create a nice-sized value for that company, as we are developing as well robotics. We actually have industrial robots that will be live this quarter, 2026.
They're going to be related to industrial sites for maintenance, variation of temperature or humidity, or all the different basic data that is needed in the data center. We're going to start to lease these robots to different industrial sites.
By creating value there, DigiPower has a free take on a big piece of the value of the growth of US Data Center without any risks that, by the way, cannot afford to take. We don't have the money allocation to go and invest in new ventures.
We have to focus on our core business on the DigiPowerX and execute. We have a 3- to 5-year plan that take us to a very high level, and that's what we should do.
Moderator
Thank you. What milestones should shareholders use to judge execution over the next two quarters?
Michel Amar
It's very simple. It's purely execution.
Phase 1 tenant access in basically 5 weeks, 4 to 5 weeks; commissioning starting December 15 or earlier; billing starting January; closing of the proposed financing in the next few weeks, but in quarter 2026; progress of Phase 2 and access in March '27; commissioning and live and billing in April '27; and adding few AI customers with huge deposits, we don't have to, A, dilute, and we can negotiate the best financing, debt financing, if necessary. This milestone will show how effectively we are converting our investment into recurring revenue.
Moderator
Thank you. Do you anticipate continued growth in the NeoCloud sector going forward?
Michel Amar
We believe that this is the best use and the best ROI of our investment. Because when you work at 85% to 90% margins and you have scarce power connected, this is the best use of your dollars, and we don't see any slowdown in the next 3 to 5 years.
We're actually negotiating contracts now, 5-year contracts that are huge, and with very little power. We can execute.
We see a continued growth in that sector. We just have to make sure we figure out the financing properly.
Moderator
Thank you. Our final question: How do Cerebras 3Q results impact DigiPower?
Michel Amar
A lot of shareholders call me and say, "But are you sure about Cerebras? Their stock was $360, it went down to $100.
Aren't you worried?" I said, "How can I be worried about one alternative of Nvidia?"
Their result yesterday showed that they are doing great. They are up 55% year over year.
Their cloud services revenue, 255%. They have close to $8 billion in cash.
We have an incredible relationship with Cerebras, from management, CEO, to everyone. They're very, very happy with us.
We are very happy with them. We can grow further with them.
The only reason that we did not grow are for the same reasons I mentioned earlier. We need to go step by step and be disciplined financially.
As they announced that they have 700 megawatts contracted, and 700 megawatts is hard to find today. They would definitely take more colocation from us, 100%.
We just want to make sure that we have a diversified base of customers so we can be more valued. You have to understand one important factor.
In March, when our data center is done, state of the art, by the way, designed by the one of the best designer in the US, when our data center is done, our value for a liquid cooling data center today is about, in my opinion, $30 to $35 million a megawatt of IT. I'll tell you how I base my valuation.
Blackstone paid before the election $27 million a megawatt for a data center in West Virginia. After the election, it's worth easily 20% to 30% more because of the scarcity and potential regulation in Texas and so on.
A finished data center alone, the value of it, excluding the contract value, is $30 to $35 million a megawatt. Multiply by 40, okay, and you get an idea of what it's worth.
Deduct the $200 million debt financing out of a billion-two or billion-four, then we have a net equity there of a billion-two. That's what it's worth.
Add now the contracted value that brings monthly EBITDA, recurring revenues, guaranteed, and you have another few hundred million dollars there. We are very confident that our relationship with Cerebras has detonated our credibility.
I believe that Cerebras GPUs are very powerful in token-per-second, TPS, inference, and with all the trouble in Nvidia, Cerebras is very well positioned to grow and take market share. Considering Nvidia has 90% of market share, I wouldn't be surprised that Nvidia start to go down in market share and Cerebras start to grow in market share.
They're going to need good partners that they trust, and we are one of them. We're very excited about our relationship with Cerebras.
Any more questions?
Moderator
No. That was our final question.
Michel Amar
Okay. Thank you, guys.
Thank you, shareholders, for your patience and your support. I know it gets very frustrated to go through the cycles of ups and downs on the stock price, but we are very committed.
We have an incredible team. I really want to thank my team, Alex specifically, who's not a big talker, but he does a lot of work.
He's the one who triggered that Cerebras deal and negotiated that Cerebras deal since last year. He has a lot of incredible deals on lab now that we're going to convert in the short term.
We have a great team in West Coast. We acquired a building, 18,000 square feet in Sunnyvale, very close to Cerebras, very close to Supermicro, Google.
Beautiful building that we are renovating and making beautiful, state-of-the-art offices, where we're going to have our racks of B200, Vera, and we're going to be able to use it as a showroom and demonstration of our capabilities. We're going to have a small token factory there, and we are building an incredible team with Jack and his different engineers.
Of course, again, we make sure to grow related to our revenue growth, as a ratio of revenues. I forgot to mention also and close the statements, we lowered our SG&A expenses 30% from Q2 to Q3.
We are trying to be very disciplined in how we allocate dollars, and everybody knows that we have a entrepreneurial approach to business, not a very corporate approach. I let the lawyers be corporate, the accountants be corporate.
As far as speed of execution, we are a very small team that can communicate and execute and make decisions very, very quickly, we can compete. We have a good shot of getting market share here.
Thank you so much, everyone, and let's hope we get a great day today. Thank you, guys.
Moderator
Thank you. This concludes today's conference call.
You may disconnect your lines at this time. Thank you for your participation.