Devon Energy Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 6, 2026
Operator
Welcome to Devon Energy's third quarter 2026 conference call. At this time, all participants are in listen-only mode.
This call is being recorded. After today's prepared remarks, we will host a question and answer session.
I'd now like to turn the call over to Mr. Dan Guffey.
Dan, you may begin.
Dan Guffey
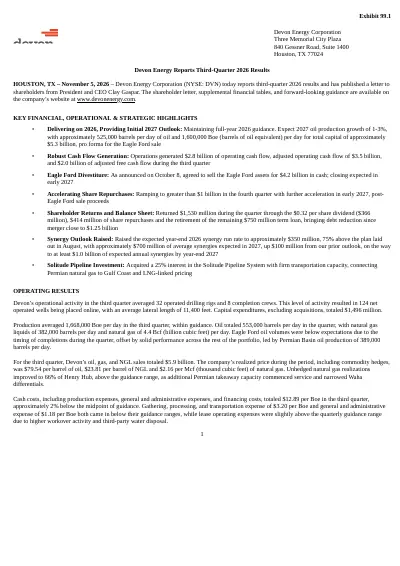
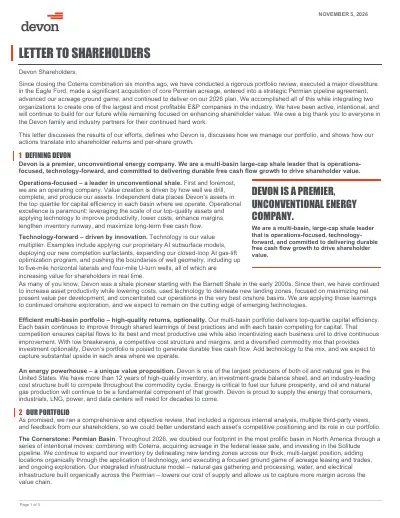
Good morning, and thank you for joining us. Last night, we issued our third quarter earnings press release, a letter to shareholders, and our investor presentation, all of which are available on our investor section of our website.
Joining me today are Clay Gaspar, our President and Chief Executive Officer; Shane Young, our Executive Vice President and Chief Financial Officer; and other members of the executive management team. As a reminder, this call will include forward-looking statements as defined under U.S.
securities laws. These statements involve risks and uncertainties that may cause actual results to differ materially from our forecast.
Please refer to the cautionary language and risk factors in our SEC filings and earnings materials. With that, I'll turn the call over to Clay.
Clay Gaspar
Thank you, Dan, and good morning, everyone. I'm excited to talk to you this morning.
Today, we will define Devon's strategy and value proposition, discuss the results of our portfolio review, highlight our 2027 outlook, and outline the three strategic pillars that will create additional value for our shareholders. Shane will discuss the financial results and the guidance, and provide an update on our accelerated buyback and shareholder returns plan.
Tomorrow will mark six months since the closing of our Coterra merger. I'd like to first thank the entire Devon team for the incredible hard work and focus during this very demanding and productive time.
While balancing challenging day jobs, the team has made massive progress on the integration of two very large companies, conducted a rigorous and objective portfolio review, executed a major divestiture of the Eagle Ford, made a strategic acquisition of core Permian acreage, entered into a value-enhancing pipeline agreement, advanced our acreage ground game, and made significant progress in capturing synergies. We have not, and we will not, stand still at Devon.
First, let me define who Devon is, because it frames every decision we make. The short version is that Devon is an operations-focused, technology-forward, energy powerhouse.
Let's go deeper on what that means. First and foremost, we're operations-focused.
Differential value in our business is created by how we find, drill, complete, and produce our assets. Our teams share best practices and compete for capital, which sends every dollar to its best and most productive use, and pushes each business unit to drive continuous improvement.
Next, technology. Operational and digital technology is our value multiplier.
Devon continues to be an industry leader in applying AI to create value. This includes our proprietary subsurface models, real-time monitoring, smart gas lift, enterprise-wide adoption, and hundreds of homegrown apps.
Put together, Devon is an energy powerhouse, one of the largest producers of both oil and natural gas in the United States, with a deep and high-quality inventory, a fortress balance sheet, and industry-leading cost structure built to compete throughout the commodity cycle. Next, I'd like to discuss the results of our post-merger portfolio review.
Leveraging the benefit of two independent perspectives from Devon and Coterra, we ran a comprehensive and objective review of each asset. This review included a rigorous internal analysis, multiple third-party views, and feedback from our shareholders, so that we could better understand each competitive positioning and potential role in our portfolio.
As a result of the work, we have defined our assets into two buckets. The Permian Basin is our cornerstone, and the Anadarko, Marcellus, and Rockies play complementary roles.
Finally, we saw an opportunity to capture enhanced market value and quickly acted to monetize the Eagle Ford, resulting in meaningful accretion for our shareholders. Cornerstone: let me be clear.
The Permian is the gold standard for any resource play on the planet, and our position in the Delaware is truly industry-leading. In 2026, we more than doubled our Permian footprint through a series of intentional moves.
The first and most significant was the combination with Coterra. Then just two weeks after we closed, we acquired a once-in-a-generation acreage position via the federal lease sale, which is completely untouched from grass to granite, and it boasts some of the highest returns in the industry.
Additionally, we were the lead E&P company in making the Solitude pipeline a reality, taking a 25% equity stake and firm transportation that will enhance our future natural gas netbacks, moving prolific Permian gas to the premium-priced Gulf Coast region. We continue to expand our inventory in the basin by delineating new landing zones across our expansive multi-target position, adding locations organically through the application of technology, and executing a ground game acreage of leasing and trades, as well as ongoing exploration in the incredible downhole potential.
We also continue to benefit from our integrated infrastructure model. With our extensive gas gathering and processing, water super-system, and electrical infrastructure across New Mexico and Texas, we are able to lower our cost of supply and capture more margin across the value chain.
Our complementary assets in the Anadarko, Marcellus, and Rockies provide high-return investment opportunities that generate significant and durable free cash flow at low reinvestment rates. We expect to create meaningful upside from the continued application of technology, operational efficiencies, and synergy capture.
Projected well economics in these basins are highly competitive and provide significant optionality between oil and gas investments. The Eagle Ford divestiture fits the same logic.
Over the past several years, we have created substantial value in the Eagle Ford by lowering costs, increasing productivity, and coring up our acreage position. The market valued the asset meaningfully above our internal view, we opportunistically chose to divest the position and create immediate shareholder value.
This strategic sale actually increases inventory life, lowers our breakevens, reduces our base decline, and is accretive to per-share free cash flow and NAV. While our post-combination portfolio review is complete, our active portfolio management remains one of our three pillars to enhance go-forward value.
We will not stand pat. We will continue to explore and execute ideas that are in the best interest of our shareholders.
High-grading our portfolio has long been a core competency of our strategy, and the multiple actions that we have executed in 2026 have further strengthened the quality, depth, and returns of our portfolio. Next, I'd like to spend some time discussing our go-forward plans to enhance shareholder value through strong execution and disciplined growth, underwritten by our deep, high-quality inventory.
Over the next few years and beyond, we expect to generate low single-digit oil growth with conservative reinvestment rates of 45% to 60% of cash flow. This will result in 5% to 10% annual growth in free cash flow per share, fueling accelerated shareholder returns.
This modest oil growth will be driven by the Permian, where we will direct roughly 75% of our 2027 capital program. Furthermore, as we look ahead, we're excited to get to work on the federal lease sale acreage acquired earlier this year.
We expect to spud our first wells around mid-year, and we'll have meaningful production in early 2028, which will provide a noticeable step change in capital efficiency. Synergies from the Coterra combination compound these gains as we apply shared learnings and leverage our expanded scale and infrastructure across our Delaware and Anadarko positions.
Shareholders should expect sustained multi-year improvement in our capital efficiency. We are excited to accelerate and enhance our shareholder returns program through buybacks, future dividend increases, and debt reduction.
We see substantial value in our equity today, and accelerating buybacks creates immediate and lasting value for our owners. Finally, I would like to discuss how Devon is fueling our future.
As we show on slide 4, we have three pillars that will guide us. Pillar 1: make Devon a better Devon.
This is a focus on improving our core business every day through engineering, innovation, and technology. As a top operating company, this means increasing productivity, driving down costs, improving our margins, and never settling for status quo.
Pillar 2: organic growth opportunities. Leveraging our differentiated scale and skill set to capture ground-floor, value-creating opportunities have the potential to deliver the highest risk returns of anything we do.
Examples include investing in our leasehold ground game, shale exploration, midstream enhanced value like Solitude. Pillar 3: active portfolio management.
High-grading our portfolio has long been a core component of our strategy, and the multiple actions we've executed in 2026 have further strengthened the quality, depth, and returns of the assets we own. Our leadership team and board remain objective and will not hesitate to explore and execute any future opportunities that are in the best interest of the shareholders.
As I wrote in my letter to shareholders, I'm extremely proud of what the team has accomplished to date, but we are never satisfied. We will not settle for anything less than being the best E&P company.
With that, Shane, I'll let you take us through the numbers.
Shane Young
Thank you, Clay, and good morning, everyone. The third quarter was our first full quarter as a combined company, and we delivered strong results.
Today, I'll focus on how we increased free cash flow during the quarter, accelerated our share buyback program, developed our capital-efficient preliminary outlook for 2027, and how we continue to methodically improve on our fortress balance sheet and our liquidity position. Let me first share a few thoughts on third quarter numbers.
Oil and total production were both within guidance and reached all-time highs. Importantly, we saw a strong rebound in natural gas realizations to almost $2 per Mcf during the third quarter.
This was largely driven by the Permian Basin, where realizations averaged $1.74, or almost 60% of Henry Hub. At the same time, we beat our cash cost guidance midpoint by 2%.
This all resulted in discretionary cash flow for the quarter of $3.5 billion, which was over 20% higher than the prior period. At the same time, we invested $1.5 billion of capital, for a disciplined 43% reinvestment rate, resulting in $2 billion of free cash flow during the quarter, up meaningfully from both the first and second quarters.
Now turning to the remainder of the year. For the fourth quarter, we expect oil volumes of 550,000 to 560,000 barrels per day and total production of 1.66 to 1.7 million BOE per day.
We anticipate capital will be between $1.29 and $1.395 billion, which puts us right near the midpoint of our 2026 guide. For the full year 2026, we are reaffirming our production ranges, as well as cost and capital guidance, with efficiencies offsetting modest inflationary pressures.
For clarity, we have included Eagle Ford activity for the remainder of the year in all of these figures. Now to our initial outlook for 2027, which is based on current market conditions.
Assuming the Eagle Ford sale closes in early 2027, we expect oil volumes of approximately 525,000 barrels per day, total production of approximately 1.6 million BOE per day, and capital of approximately $5.3 billion, of which 75% would be directed to the Permian Basin. This number excludes potential land acquisitions or ground game, and our equity investment in the Solitude pipeline, which we expect to be approximately $400 million next year.
In total, we expect Devon's Solitude investment to be $500 million for the entire project, including almost $100 million we have invested year-to-date. On a full-year basis, we'll have a disciplined, low single-digit production growth on both oil and total volumes on less capital than the pro forma combined company spent on the same assets during 2026.
In other words, 2027's capital program will show meaningful improvement in capital efficiency over 2026. That $5.3 billion of capital compares to a pro forma 2026 baseline of $5.9 billion.
The Eagle Ford sale removes a little over $400 million, and synergies and efficiencies, net of modest current inflation, take out another $300 million. This is partially offset by a small increase in infrastructure spending in 2027 for an investment in our Permian water super-system, which has a great return and will further enhance basin margins in the future.
As I'm sure many of you saw on slide 15 of our investor deck, we project that based on current costs and commodity prices, we will generate approximately $12 billion of cash flow in 2027. When paired with our $3.5 billion of Eagle Ford net proceeds expected in early 2027, we could have $15.5 billion of cash inflows during the year.
After funding our capital program, paying our dividends, handling debt maturities, and investing in the Solitude pipeline and our ground game, we could have $6 billion of excess free cash flow that we could use to support our buybacks and for enhancing liquidity. Turning to the balance sheet and shareholder returns.
Our philosophy has not changed: leverage at or below 1x through the cycle, strong investment-grade credit ratings, a gross debt target of approximately $9 billion, all while maintaining a strong liquidity position. In the third quarter, we retired the remaining $750 million of our term loan, bringing total debt reduction since the merger closed of $1.25 billion.
In 2027, we plan to retire an additional $1.5 billion of long-term debt and achieve our gross debt target of roughly $9 billion. Regarding third quarter shareholder returns, we paid our quarterly dividend of 32 cents per share, or $366 million, and repurchased nearly 9 million shares for $414 million of stock.
This was over double the second quarter's buyback activity, and when combined with dividends and debt retirements, resulted in over 75% of free cash flow returned. We expect share repurchases to further increase to more than $1 billion during the fourth quarter, well over doubling again.
We continue to view our shares as an attractive use of our free cash flow and expect to continue to lean into repurchases during 2027. To re-highlight our framework, we intend to use up to 70% of our annual free cash flow returns, including dividends, repurchases, and debt repayments.
With the net proceeds from our Eagle Ford sale, we'll be deferential towards buybacks and work closely with the board on the pace and timing of those buybacks during 2027. Expect to hear more on this early next year.
In summary, we used our strong third quarter results to accelerate our buyback program, and Devon is set up for a great finish to 2026. Our outlook for 2027 provides disciplined growth with a conservative reinvestment rate and increased capital efficiency.
That, coupled with our Eagle Ford sale, sets up nicely for robust shareholder returns program in 2027. Our balance sheet and liquidity are in great shape and will position us to thrive throughout the commodity cycle.
Finally, looking forward, Devon is a multi-year rate of change story with regards to improving capital efficiency. Capital reallocation to the Permian, activity starting on our recently acquired New Mexico leasehold beginning in the second half of '27, coupled with synergy capture hitting a run rate at year-end 2027, uniquely positions Devon with visible, multi-year improvements in our capital efficiency.
With that, I'll turn the call back over to the operator for our first question.
Operator
We will now begin the question and answer session. Please limit yourself to one question.
If you would like to ask a question, please press *1 to raise your hand. To withdraw your question, press *1 again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by while we compile the Q&A roster. Your first question comes from the line of Doug Leggate from Wolfe Research.
Doug, please go ahead.
Doug Leggate
Oh, thank you. Good morning, everybody.
Clay, the letter was quite informative. Obviously, there's a lot of news on the screen today, but I wonder if I could try and address the kind of the 100-pound gorilla in the room, which is the decision after the portfolio review to basically, as you put it, we're not standing pat, but there seems to be an interpretation that the end of the portfolio review means the end of the portfolio high-grading.
There's a big difference between those two, I wonder if you could address that and maybe share any color on how far down the road you got to exploring potential alternatives, whether it be selling other assets or whatever, and what the barriers were that prevented you from doing that, whether it be value, gas prices, or whatever. Thanks so much.
Clay Gaspar
Thanks, Doug. Great question.
I know that's on everyone's mind. Let me address it.
As I think about the portfolio review, the opportunity that we had, it's rare in a company's history where you have two high-quality teams that have been working so intently to evaluate each other. We took full advantage.
We said, "Look, how do we take all of the best ideas and challenging perspective from the Coterra side of the family and the Devon side of the family, and let's do a fulsome review. We're going to be very open and transparent with our investors that we're going to be open and transparent to new ideas."
That served us in a couple of very strong and positive ways. First, we were honest about exactly what we're saying.
This is incredibly objective. There were nothing held back.
We had rigorous debate internally, we had rigorous debate with our board, we had great outside perspective. The other real significant advantage that we brought in is when you're so open and transparent, there's all kind of ideas that come out of the woodwork.
We heard from everybody in the industry, "Hey, Clay, old friend, old pal, let me help you out on this." I can tell you, some of it, these are all wonderful people, but some of it was certainly trying to just take advantage of the situation.
We were absolutely clear that we were never desperate sellers on any of this. Starting with a really strong balance sheet and a strong financial position allowed us to capitalize on opportunities, and so it was easy to dismiss any of those that were just kind of way out of bounds on completely value-destructive.
I will tell you, there was lots of ideas that came our way that we said, "You know what? That's something we really need to evaluate."
The teams ran through, again, a very rigorous process to understand the validity of those opportunities, how would it ultimately make us a better company, and I can tell you, we went down several paths. That is a strong opportunity for the company, and we took full advantage of it.
Now, the downside of running such an open and transparent process is it is taxing on the investors, and it is taxing on the organization in multiple levels. Let me start with the investors.
From the investors' perspective, the question was very simply, "Are you this, or are you that? What's the go-forward company?
Are you selling this? I hear from one angle you're selling this asset, or combining this asset, or doubling the size of this asset."
What we had to say very routinely was, "Guys, we are in the process. We are wide open to who we are going to be, okay?"
The second part I want to address is the challenge for the organization. As you can imagine, these are all exceptionally hard-working individuals that care about their families, that think about their own best interests, and we're challenging them with day jobs and night jobs, and how do you think about the best tool or process or even piece of software as we're doing this integration.
This is 3,000 families that we were dealing with. It is a massive distraction and overhang to think that maybe it's my asset that they're talking about selling.
We owe it to our investors to, one, be thorough, very transparent, and very open, but we also found it very important that we drew a line and said, "This is the close of this period, this chapter, okay?" This chapter being everything's on the table, we don't know who we are, we're going to be very open and transparent that we could go right or we could go left.
What we wanted to do is close the box on this portion, and then reiterate there's great ideas that come through our door every single day, and we remain objective and very open to whatever those opportunities are to create shareholder value, as we always have been, as we always will be. While this is the end of this chapter, this in no way means you shall never see another opportunity for us to proactively move in the shareholders' best interest.
That's core and part of who we are, and while it feels a little bit like we're talking out of both sides of our mouth, I think this is a clear and present turning of the page to our new go-forward three-pillar strategy. Of course, one of those pillars is always thinking about how do we transactionally enhance shareholder value.
Thanks for the question, Doug.
Operator
Your next question comes from the line of Neil Mehta with Goldman Sachs. Neil, please go ahead.
Neil Mehta
Thanks so much. Clay, appreciate all those comments.
Would just love your perspective on how you interpret the market. All right, it's been a frustrating period, I think, since the close of the transaction and the stock has underperformed over the last six months and you see in the valuation as well.
Do you think it's just the market is looking for clarity of who Devon is going to be on a pro forma basis? What do you make of the market reaction?
Then how do you build that confidence going forward?
Clay Gaspar
Again, great question. This is on the top of folks' mind, and I appreciate us hitting this right up front.
Absolutely, we are not satisfied with how our shares have performed. I personally have met with nearly 200 investors in the last six months.
Our team has met with over 300 investors. What I would tell you is there is not a single, monolithic view of, "Here's what we need to do."
What we hear very often, especially from those investors that have probably better alignment with our long-term shareholder value creation focus, is, "We need to know who you are and what you're doing. Are you pure-play this, or focused on that?
Are you more gas-oriented or oil-oriented? Are you doubling down in this basin or that basin?
Meanwhile, we're going to sit on the sidelines near the hoop, and ready to understand who you are, and then be able to make an intelligent investment decision." What we hope is, after this very methodical, very transparent process, that we are open with the investors.
This is it. This is who we are.
This is the opportunity, the investment opportunity that we present. By the way, we're going to work on getting better every single day for the best interest of the shareholders.
I think that clears the path to close this valuation gap, and we look forward to being on the road as soon as Monday to meet with more investors, get that feedback, and really talk to the opportunity ahead, and really, I think, excite the organization and the shareholders about our clear path forward.
Neil Mehta
Thanks.
Operator
Your next question comes from the line of Arun Jayaram with J.P. Arun.
Arun, please go ahead.
Arun Jayaram
Good morning, Clay. Maybe just a follow-up to Neil's question.
You've clearly done an exhaustive review [laughter] of your asset base post the merger and as part of this portfolio review. I was wondering if you can help us think about your view of the intrinsic value of the company.
Your stock right now is trading in the low $40s, and maybe just help us think about where you perceive that gap is, what do you think the market is missing, and maybe Shane could talk a little bit around thoughts around the buyback and how you maybe take advantage of this perceived dislocation in the share price.
Clay Gaspar
Thanks for the question, Arun. I think there's two points to it.
One, I think what the shareholders have missed is a clearly articulated strategy on here's who we are and here's how we're going forward, and hopefully we've taken the first step in delivering that today. I think the second piece, and Shane's welcome to pile on this, we've been very clear we're going to move differentially towards share buybacks.
This is a great opportunity for us to buy back shares. We've talked about a billion-dollar-plus share buyback in the fourth quarter, and accelerating from there, and beyond that.
We have really a great opportunity to invest in ourselves in this period, and we're not going to lose that opportunity. Shane, other comments?
Shane Young
Clay, and Arun, look, as we sit here today, we see very compelling value in our shares in the marketplace, and we believe that buying our stock is an attractive use of our free cash flow, and we just happen to be in a fortunate position where we have a lot of free cash flow coming. That's why we've accelerated, we've really leaned in, leaning in last quarter, the third quarter, continuing to lean in this quarter, and frankly, probably leaning in further in 2027 as we go.
I can tell you, I, for one, cannot wait to be out of our blackout period so that we can continue to get after it.
Clay Gaspar
Thanks, Arun.
Operator
Your next question comes from the line of Devin McDermott with Morgan Stanley. Devin, please go ahead.
Devin McDermott
Hey, great. Good morning, and thanks for taking my question.
I wanted to shift over to that capital efficiency, attractive rate of change, and one of the drivers of that is just the synergy and integration opportunity. Alongside the release today, you did take up the 2027 expectations.
I was wondering if you can just talk about where you're seeing delivery of synergy faster than plan, some of the milestones you're focused on for next year, and should we take this progress and accelerated timing as potential upside to that $1 billion target as we look out over the next year or two?
Clay Gaspar
Devin, I really appreciate the question. I was afraid we were going to have to just talk about the portfolio or the lack of moves on the portfolio all day, but I can tell you the team is doing some incredibly, incredibly good work that could get buried in this news flow.
Man, I'm incredibly proud of the team. We're ahead of track, as you saw in the projections, and Blake's here.
He can talk about some of the specifics on what's going on and his view of that rate of change that's incredibly exciting.
Blake Sirgo
Thanks, Devin. Really, really excited to be here and be able to talk about just frankly a lot of the wins we've had since bringing these two companies together.
Our operating teams have come together really fast, and it's really showing in our results. Right out of the gates, we leaned in hard to Devon's embedded AI tools, and really what those have allowed us to do is just capture best practices, identify top performance, and then immediately extrapolate it.
We're currently running 34 rigs and nine crews. There's a lot to extrapolate on, and we're seeing the results in the field.
Just since coming together, the amount of wells we're simul-fracing has increased from 68% to 75%. As we walk into 2027, our average lateral length is going up over 10%.
That's on the back of 53 4-mile wells across four different basins. You roll all that up, and it's allowing us to deliver an expected dollar per foot in 2027 around $750 a foot.
That's all in: drilling, completions, facilities, flowback. That's the number we use to make an investment decision.
At the same time, we are leaning into larger fracs, driven by our AI subsurface models. We're adding surfactants, and we're continuing to fight off cost pressures.
When you add all that up, it is truly more for less. That's what we're delivering in the field, and we couldn't be more excited to see where the teams take us next.
Clay Gaspar
Thanks, Blake.
Operator
Your next question comes from the line of Betty Jiang with Barclays. Betty, please go ahead.
Betty Jiang
Hi, good morning. I want to talk about and ask about the leasehold, the ground game, the spending that you guys are doing.
Can you maybe talk about how you underwrite the return of that investment, and how does that compare to drilling or buying back stock, and how does that impact your long-term inventory or replenish what you guys draw down every year?
Trey Lowe
Betty, this is Trey. Thank you for the question.
We continue to be excited about what we're doing on the ground game across the board. We've really focused a lot of that investment in the Permian Basin, in the Delaware, where we already operate.
One of the things that we came out of the merger with was a really aggressive growth team based out of our Midland office, and they have been very active picking up what we think are some of the best-returning dollars that we've spent. To the second point that you raise, all of these investments, whether it's our ground game, our infrastructure investments, or whether or not we're drilling a new well, these all compete against each other on a heads-up basis, and we continue to look at all of those both on a PVI basis, rate of return, and a net present value basis.
The team has a really I would say sophisticated and now mature process for evaluating the financials on those, but you're going to continue, just as we signaled in this earnings release, to lean in and to find new opportunities. We're excited about the opportunities that the team has been able to uncover, and we expect to do more of that in the Permian.
Betty Jiang
Thanks. Appreciate it.
Operator
Your next question comes from the line of Neal Dingmann with William Blair. Neal, please go ahead.
Neal Dingmann
Morning, Clay, Shane, team. Clay, my only question is on the organic opportunities specifically.
Could you speak to the types of midstream investments, I know you have some current and maybe looking at some non-E&P ventures, and then even exploration. There's a host of things in there.
Just wondering what type of things these days you find attractive out there.
Clay Gaspar
Neal, I think this is really important. When we think about how do we expand the multiple, our trading multiple, and really create value for the shareholders, I think one of the things that E&P companies can really do is, one, display a high-quality and deep inventory, and then as a complement to that, display a capability to creatively and constructively invest for the extension of that quantity and quality of inventory.
When I think about that, we did a really strong exercise really over the last year and a half, kind of broadening what that can mean. Does that just mean how do we create more oil inventory or BOE inventory?
What we really came up with is how do we create more really strong investments so that the product we create is sustainable free cash flow. What are those opportunities as we broaden the sense to really think about how do we invest our precious dollars into systems, into processes, into opportunities that allow a full-cycle return that's competitive, that's accretive, and that really extends the quantity and quality of inventory.
That's how we started really opening up to think about, for example, the Solitude pipeline. If we were just solely focused on driving oil production, Solitude would have never ranked.
What we saw was an opportunity for us to lean in to some of the best gas inventory in the world was already under our feet in the Delaware Basin. The challenge was it was constrained by a limited infrastructure system.
We went to our good friends and partners at WhiteWater, put this concept together, and really created something that's groundbreaking, that's forward-leaning, and is incredibly value-creative. As we look through the full cycle of that value creation, that's how we create value for our shareholders.
There's lots of other things on the list. We'll have more to come in time.
I just want to put that placeholder together that leveraging our scale, our differentiated scale and skill set can really create value above and beyond just drilling that next horizontal well. As we've opened that aperture, we have lots of exciting things kind of on the list.
As Trey just talked about, every one of these things has to compete full-cycle on a fully-risked basis for capital, and I think that's the work that we've done over the last year in particular has really differentiated our ability to compare apples and Chevrolets, and really get to the heart of what's the best investment for our shareholders. More to come on that, some exciting opportunities, but know that we hold these to an exceptionally high standard, that on a full-cycle, risk basis, they have to deliver return to the bottom line.
Neal Dingmann
Thanks, buddy.
Clay Gaspar
You bet, Neil.
Operator
Your next question comes from the line of Phillip Jungwirth with BMO. Phillip, please go ahead.
Phillip Jungwirth
Good morning. Thanks for taking the question.
I think the multi-year outlook you presented here of low single-digit oil growth, 45% to 60% reinvestment with improving capital efficiency and 5% to 10% free cash flow per share is highly competitive across peers, can be achieved at a conservative price deck. The question is just more in the portfolio review, I know you ran a lot of different scenarios.
Was hoping you could talk about why this portfolio outlook is a better longer-term outcome for the company versus what you could have achieved with less scale or fewer assets.
Clay Gaspar
When you look at slide 8 of our deck, the left side of it, we talked about some of the attributes of the Permian, and it's really the same attribute list that we started looking at when we start talking about other assets. We think about the scale, the depth of inventory, kind of that ability to create value.
We have this recent merger. We're just on the front end of capturing all of these synergies, specifically in the Permian and the Anadarko, but I can tell you it doesn't limit there.
We're learning things and transferring skills every single day between all of these assets. When we think about how do we build a better company, we think about these characteristics, and we think about how do they stack up not just for this quarter or calendar year, but as we run through this next decade of opportunity and we continue to build for the future of Devon, how do these attributes really stack up?
We love the Eagle Ford. It's a high-quality asset, but I can tell you the steepness of the base decline was very challenging, and it drugged the overall maintenance capital of the organization.
The inventory, as it became challenged late in life, look, teams are incredible, we're going to drive more value, we're going to get smarter every single day, but I can tell you the differential value creation that we were able to make was probably in our rearview mirror, and this was more valuable to the market than internally. I have no hesitation, and when we see that opportunity, we're going to act on it, accelerate that value for shareholders, and then go redeploy that into more share buybacks, future dividend funding, and then, of course, building liquidity in this volatile industry displayed over the last few days in perfect form.
You certainly want to have your financial house in order, and a little bit of cash on the sidelines never hurts in this business as future opportunities come our way.
Operator
Your next question comes from the line of Josh Silverstein with UBS. Josh, please go ahead.
Josh Silverstein
Thanks, guys. Clay, you mentioned the significant gas growth coming out of the Permian and your asset contributing to that.
I'm curious how that makes you think about the value of your Marcellus asset, capital allocation there, and the role that has in your portfolio. Thanks.
Clay Gaspar
To me, it's exciting. This is a perfect example of you have one side of the family that's lived with this asset, that knows this asset, and then you've got another side of the family that's brand new to the asset and have our own kind of maybe outside-in looking perspectives.
When those teams really sat down and started just tearing apart what's the inventory, what's the quality, how does it compete, what's the upside potential, where do we take these synergies and apply them there, how do we think about the evolving technology, both operational and digital, to further enhance value, how do we think about vertical integration and application of all of the tools in our toolbox to create more value, we get pretty excited. I think there is true incremental value creation in that asset.
There's no doubt about it. It's a coveted asset, like all of our assets are.
Understanding how that the market values it, and what I could tell you is, I feel very confident that we have exceptional upside value in this asset that we will create for the shareholders. Again, I'll go back to the words that we used in our prepared remarks.
The leadership remains objective on any and all of these assets as opportunities present going forward. Man, our first and foremost priority is pillar 1: make Devon a better Devon.
It's a perfect example of how do we drive even further value from this high-quality asset.
Operator
Your next question comes from the line of John Freeman with Raymond James. John, please go ahead.
John Freeman
Thanks. Good morning.
The slides 19 and 20 are really interesting in the deck on the lateral lengths and the progress that y'all are making. Just trying to make sure that these aren't like apples and oranges, the slides I'm looking at, but it would appear that based on the guidance for the Delaware in '27, it sort of implies about $765 a foot.
As y'all move toward more and more of the program being 3-, 4-, 5-mile laterals, and all, like the 4-miler you highlighted, $630 a foot, if we look out 2, 3 years, is there anything I'm missing? Otherwise, just as the program gets longer on average, you've got a pretty good line of sight toward that cost per foot's going to go down, pretty dramatically.
Clay Gaspar
Go ahead, Blake.
Blake Sirgo
John, this is Blake. Happy to take that one.
Our teams just continue to push the edge on what we can do in the long-lateral game. This really started up in the Marcellus where, kind of driven by our land position, you had to get creative on how you're going to access untouched rock, and we started putting 5-mile wells in the ground, and it wasn't long before the other basins were chomping to get there also.
The name of the game is try to grab that capital efficiency everywhere we can with lateral lengths. We're really excited about the 4-milers going in the Permian.
We're calling out some pretty creative well geometries. They're 2x2 U-turns, they're 4-mile wells, but it actually has a U-turn in the middle.
Where our acreage position is really defined and maybe we don't have the opportunities to extend the acreage, we can still chase these long-lateral efficiencies with really creative wellbore geometries. I think you see that in these numbers, you see it in the 53 4-mile wells we're going to execute next year.
My hope is exactly what you said: we're going to keep pushing the limits on this, which will, of course, drive our dollar per foot down.
Operator
Your next question comes from the line of Scott Gruber with Citigroup. Scott, please go ahead.
Scott Gruber
Yes, good morning. It sounds like that the low single-digit growth can be sustained here for several years at flatish capital.
I'm curious on the drivers, and how would you compare the drivers? How would you compare the benefit from developing the newly acquired federal acreage and overall well productivity relative to base decline management, relative to more kind of process driven efficiency gains?
Kind of how would you rank the key drivers behind delivering some growth at flatish capital?
Clay Gaspar
Man, Scott, I appreciate the question. This was a difference between how Devon saw the world and Coterra saw the world.
This was one of the outstanding questions that, honestly, we needed to do the work. Number one, you need to understand the portfolio.
Two, you needed to really think about the macro. What is the world calling for?
Do these barrels really need to go incremental barrels onto the market? When we did the work, we came back together, we said, "You know what?
We got the quality and the longevity of the inventory. We got the confidence in our ability to recreate quantity and quality of inventory beyond this, that we can lean in."
That was different than what we saw from Devon. What you heard from me even a year ago was, "Man, it feels like the world is pretty saturated in oil.
I don't know that there's an incremental need for our incremental barrels." Also, objectively, we didn't have the length of inventory that the new combined company does.
Part of that is certainly the benefit of the Coterra merger, certainly the acquisition of the federal lease sale, but I can tell you it's also the incredible synergies that we're creating from this combined company extend that inventory run life. What it gives you is the confidence to say, "Hey, we've got 12-plus years of fully understood, delineated opportunities, really 15-plus when you start thinking about some of the downhole potential that we're continuing to work today."
That gives us confidence that we can accelerate some of that for the shareholders in a market that, I can tell you looks pretty radically different than it did a year ago when it comes to inventory global storage and supply-demand numbers. That's how we feel good about the low single-digit growth.
That's a rough guide. The oil side is where we start.
Certainly, BOEs are going to be even higher than that. Then, of course, we talked about the very impressive 5% to 10% growth when you talk about per-share free cash flow.
Shane, is there something else you'd like to add on that?
Shane Young
Look, Scott, I would just say, goes without saying, we looked at a whole range of scenarios that we could potentially look at, and we found that low single-digit growth actually maximized free cash flow over the near and the longer term, particularly with, as you highlighted, some of the paybacks on some of the newer acreage acquired in New Mexico. The other thing I would say, or I want to just make sure it's clear, we didn't lean into low single-digit growth strategy because oil price was higher.
This is something that's very durable down to $60, $70 a barrel. We still have very, very competitive reinvestment rates on this capital program.
It's something that's not just for the oil price we see today, but frankly through the cycle.
Scott Gruber
Yeah. Thanks for that, Scott.
Appreciate the color. Appreciate it.
Thank you.
Operator
Your next question comes from the line of Chris Baker with Evercore ISI. Chris, please go ahead.
Chris Baker
Hey, thanks. You all have described the Anadarko, Marcellus, and Rockies as complementary assets that have strategic value to Devon.
You started to talk about this, Clay, a minute ago with the Marcellus. We'd just love to hear more about the strategic value that you all see in the Anadarko and Rockies, and how you plan to capture it.
Clay Gaspar
I think the Anadarko is one that's just very obvious. There is so much synergy potential.
You look at the quality of the wells that Coterra was drilling, you look at the D&C costs from the Devon side, you start marrying those things together, and it's like, wow. I have to tell you, six months ago, I was excited about the Anadarko Basin, but I feel much more excited today seeing what that combination and this is a perfect synergy example.
How do you combine two great teams and take the best of and really lean that together? It's pretty compelling.
You compound that, we've talked for the last six months about the potential of the midstream opportunity. Both sides of the history have opportunities to renegotiate some pretty long-dated contracts.
We're working with counterparties now. I think there's real value creation in more vertical integration.
There's no doubt about it, the Anadarko Basin being more gas-oriented and a very good position in the country geographically can really satisfy a lot of that Gulf Coast call for gas, as well as all of the electrification that we see a lot around the planet. You put all that together and it's like, wow, this is really compelling.
There's no doubt about it, there's a lot of interest in the market. We are absolutely 100% aware.
What I would tell you is, we look at this as we can create more value than what we see in the market today, and, as with anything, we remain really focused on driving value first. When I think about the Rockies, we have two complementary pieces of business there, the Williston.
Man, still just the same story that Blake was talking about with the Marcellus. In the Williston, we're driving longer laterals, we're improving well costs, it's in that graphic, I think that might have been slide 20 or so, on what we're doing with well costs, extending those laterals.
We do have a preferred, a little better midstream position there extracting more value. I think that just is a great opportunity for us to also create incremental value from a very oily-oriented asset that generates a ton of free cash flow.
The Powder is unique. It is the least mature of all of our assets.
It gets the benefit of all of this knowledge in the technological innovation, both on the operational and digital side. Then those long laterals, I was in a meeting the other day and the team pointed to a map and they said, "This is the shorter laterals over here."
I said, "Wait a minute, I thought that was the 3-mile laterals." They said, "Yeah, yeah, that's the 3-mile."
I said, "Wait, when did short become 3-mile?" They said, "No, no, standard's now 4-mile and we're going out further than that."
Again, operational innovation is really unlocking future potential in these incredible portfolios.
Operator
Your next question comes from the line of Gabe Daoud from Truist. Gabe, please go ahead.
Gabe Daoud
Thanks, operator. Morning, Clay and everyone.
I appreciate all the responses so far, and the shareholder letter is very informative. Thanks, Clay.
Was hoping we could maybe just talk a little bit about Permian inventory. You mentioned earlier the 12 years inventory overall, but could you maybe just unpack the Permian, some of the deeper zone testing that you guys are kind of embarking on, and maybe just highlight what you're seeing in the Woodford and maybe even the Penn Shale?
Thanks, guys.
Trey Lowe
Gabe, this is Trey. Appreciate the question.
We continue to be just amazed all the time with what we're finding in the Permian from the entire stack. We're going to continue to work through our inventory.
We're collecting data. We're obviously watching all of the industry activity that we see, both in the Woodford and the Penn, and all the deep Wolfcamp as well.
We will start to appraise that. We're going to start understanding where it fits in our longer-term portfolio as we de-risk these things.
It will continue to be evaluated over the next year. Strategically, our development programs are going to move forward in the way that we have been, which is co-development, maximizing the value of the assets that we have.
We also, just as a reminder, we have a giant position in the BLM lease acreage that we just picked up last year that we're going to insert into the program this year as well. We've got lots of moving pieces, we're continually looking at the upside, we think it's promising, the asset teams are excited about it, and we're excited about where that will take us over a longer period of time.
Operator
Your next question comes from the line of Matt Portillo from TPH. Matt, please go ahead.
Matt Portillo
Good morning, all. Picking up on your comments for Solitude and gas resource in the Permian, as we add up the pipeline capacity that's been announced and look at the impact to egress out of the Permian over the next 5 years, it looks like we'll probably see a 50% increase in capacity.
I was just curious, given your size and scale in the basin and your position on pipes, what your perspective is for your oil cut for your assets through the end of the decade, and thoughts around the zone mix moving forward, as I know that's been quite topical. Then should the market expect Devon's gas production to keep up with that industry CAGR from an egress perspective?
Clay Gaspar
Yeah. Matt, there's a lot there.
Let me start with the deep and high-quality inventory we have today is driven by the oil economics, okay? Right now, with the price realizations, even with a relative run-up in gas price, man, we are limiting our gas production.
For much of the last couple of years, we've tried to really really limit our amount of gas production, and every quarter it continues to increase. There is such a hydrocarbon-rich environment in the Permian Basin that it's incredibly valuable.
The challenge has been the realized prices aren't where we wanted them to be. We made the proactive step, and then when we get this locked in, when the pipe's in place, we lock in our value, we're able to maximize the value potential of that not on the Waha side, but on the Gulf Coast side.
That really unlocks even further potential, kind of firming up the realizations, and that's where I think the upside is just unlimited in the position that we have. Incredibly excited about that position.
When I think about our current just under 50% oil cut, there's a few things at work. As we start digging a little bit deeper into the section, certainly that will be more gas-oriented, and then the natural tendency of the gas-oil ratios of these wells also get a little gassier over time.
That'll continue to migrate that way, but until we have the real value creation steps in place, you're not going to see us move differentially into gas production. When those real material steps are in place and we have the full realized prices, I don't know of another basin in the U.S.
that will compete for gas valuations because it's always going to come with a nice complement of oil that will probably carry the economics and you essentially get all the gas for free. I think there's tremendous value creation.
Our position, specifically on the Delaware side of the Permian, I think there's just so much more runway, and get so excited about the additional value creation and the steps that we're making proactively to really get the true value of these precious resources for the U.S.' s benefit and beyond.
Look forward to more steps on that and more value creation from this incredible resource.
Operator
Our final question comes from Kevin MacCurdy with Pickering Energy Partners. Kevin, please go ahead.
Kevin MacCurdy
Hey, good morning, Clay, and thanks for getting me on. For my question, I wanted to come back to the ground game spending in 2027.
If I'm doing the math right, I think you've implied about $500 million, which is higher than the historic run rate. Maybe you can expand on the opportunities you're seeing there and how that's different than before, and is this part of the lateral length increase, or are these brand-new locations?
Thanks.
Clay Gaspar
I'll start, and then Trey, you may want to add some comments. This is another, I would put it in the category of synergies.
Devon didn't have a Midland office; Coterra had a Midland office. Trey talked about the outstanding team that we have on the ground doing this work, and we've really leaned in.
In fact, in 2026, we'll have about $500, $600 million. Is that right, Shane?
Shane Young
That's right.
Clay Gaspar
In that about $500 $500 million of investment. $600 million of investment in 2026.
These are incredible returns, as you talked about. Maybe it's extending that lateral, which we see from Blake's slide, the value creation opportunities there.
Maybe it's some trade without even cash out the door that enhances our position, that moves opportunities that are a little further out in our portfolio to something more near-term. We always have a little more incremental value creation perspective.
We talked about the very sophisticated infrastructure we have from gas gathering, processing, water infrastructure. That can change the economics of these positions, and we're really leaning forward, and that team in Midland's doing a fantastic job, we'll continue to lean in.
We count as about $500 million is the plan for next year, but honestly, I hope that team continues to be as successful as they are because it's such phenomenal returns, full-cycle returns on those investments. We're taking stuff down at roughly about $2 to $3 million per stick, last time I looked at the math, which is highly competitive and exciting, and something that, honestly, we're doing better than either legacy company, and it's a great synergistic win for the combined team.
Trey Lowe
The only thing I would add to that is the pace of change or the rate of change that we're seeing in the Permian right now continues to give us confidence that performance improvement from the long laterals that Blake mentioned, the success we're having with surfactants today, with a lot of the other subsurface work, really gives us the ability to marry that up with our infrastructure and our scaled position that we have in the basin to be really competitive in our ground game. You marry that with this team that we've got they have the mandate to go help find us opportunities, and that's driving some real success for us across the business.
We've got all of these synergies coming from the merger, as well as just the cultural benefits that we're seeing right now around technical excellence and putting our people together, and they're finding new opportunities for us to go pursue these new ideas, and that's what's paying off. That's where we're trying to give everyone a peek at where we think we're headed with our ground game.
Great question, though. Thank you.
Clay Gaspar
Thanks, everybody.
Operator
There are no further questions at this time. This concludes today's call.
Thank you for attending. You may now disconnect.