Eastman Chemical Company
Q3 FY2026 · Earnings Call TranscriptOctober 30, 2026
Operator
Good day, everyone, and welcome to the third quarter 2026 Eastman conference call. Today's conference is being recorded.
This call is being broadcast live on the Eastman website at www.eastman.com. I will now turn the call over to Mr.
Greg Riddle, Eastman Investor Relations. Please go ahead, sir.
Greg Riddle
Thank you, Joel, and good morning, everyone, and thanks for joining us. On the call with me today are Mark Costa, Board Chair and CEO; William McLain, Executive Vice President and CFO; Jake LaRoe, Director, Corporate Finance and Investor Relations; and Mason Tentschert, Investor Relations Manager.
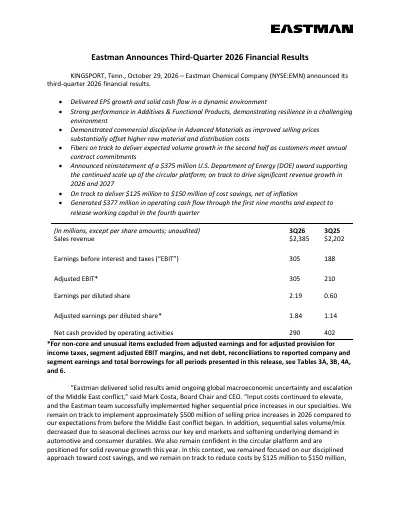
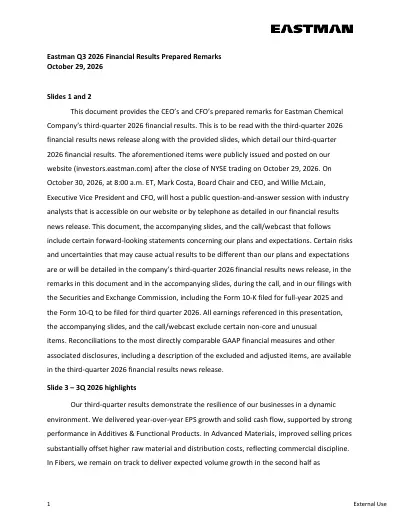
Yesterday after market close, we posted our third quarter 2026 financial results news release and SEC 8-K filing, our slides, and the related prepared remarks in the Investors section of our website, eastman.com. Before we begin, I'll cover two items.
First, during this presentation, you will hear certain forward-looking statements concerning our plans and expectations. Actual events or results could differ materially.
Certain factors related to future expectations are or will be detailed in our third quarter 2026 financial results news release, during this call, in the preceding slides and prepared remarks, and in our filings with the SEC, including the Form 10-K filed for full year 2025 and the Form 10-Q to be filed for third quarter 2026. Second, earnings referenced in this presentation exclude certain non-core and unusual items.
Reconciliations to the most directly comparable GAAP financial measures and other associated disclosures, including a description of the excluded and adjusted items, are available in the third quarter 2026 financial results news release. As we posted the slides and accompanying prepared remarks on our website last night, we will now go straight into Q&A.
Joel, please, let's start with our first question.
Operator
Thank you so much. We will now take our first question from Vincent Andrews with Morgan Stanley.
Your line is now open, please go ahead.
Vincent Andrews
Thank you, and good morning, everyone. Congratulations on getting the DOE grant back together.
Would be curious to hear a little more details on how that can be allocated in terms of how much can you put towards the Kingsport expansion. Then, there was some discussion of restoring underutilized American recycling assets, and so what does that actually entail?
Are those going to be also chemical recycled or methanolysis assets that you're going to somehow be able to do, or is that the more traditional recycling? Thank you.
Mark Costa
Good morning, Vincent. We are very excited to get the grant back.
I would say that the Department of Energy has been a phenomenal partner in coming back to us and talking about how we could collaborate on a reinstatement. I think we're fully aligned in their vision, which is priority on reindustrializing the US supply chains to America, building resiliency.
When you look at this project, it's creating US manufacturing jobs directly as well as in all the collection recycling industry that feeds into it. It's providing security on a critical material without security on things like PET, when China is getting to be 75% of the industry, you have a serious issue about how you can put food and water on the shelves, and so security is incredibly important.
It also allows us to be another leader and demonstration of technology leadership in creating a unique position in this that allows us to also create a regional economy. When you think about the grant coming back at the full value, it's really exciting.
Now the grant does require Eastman to provide at least sort of 50% of the CapEx, but it is structured where up to 50% of the capital, if we can get the number at the right target, can be paid for by the DOE. That's a great place for us to be.
As you mentioned, the scope has materially changed. The original scope was centered around building the second plant, and all the capital would have been sort of devoted to that in their support.
This actually pulled in the scope of the current plant. All the debottlenecking of the current methanolysis plant to get to that 30% extra production, the expansion of the feed processing capability in front of it, the additional add of polymer and infrastructure that goes around producing more product and getting it to the market across both specialty and in the PET section, those kind of incremental expansions are covered under DOE, where we will get a 50% share from them on those investments.
That's great. It helps us minimize CapEx in the short term in this environment and allows us to build momentum to the second plant.
Then it also, of course, covers the second plant, and that will be a project that I think will have substantially less CapEx than what we talked to you about in Longview, Texas, for one of the reasons that you just mentioned. You have to remember that the Longview project was not just a methanolysis plant.
It was also a polymer line, it was feedstock processing in the front end, it was infrastructure to support all that together. About 40% to 50% of the capital is actually not the methanolysis plant.
It's all the other things: the processing, the polymer lines, the infrastructure, etc. Those kind of assets exist today.
There are recycling plants that have shut down in this country that we can purchase for a very low price. There are polymer lines that have been shut down, and there's infrastructure around both of them that are sitting there in those sites.
We have made great progress in finding a way to acquire those sites at very low capital and have that replace a significant amount of new build capital associated with the second plant. We're very excited about that, and we'll tell you more about that once we get it fully completed.
Also I would mention on the methanolysis plant itself, we believe we can build it at a much lower capital cost than the first plant because of all the learnings we've had in how to design it better, how to execute the construction better. I would also note that the solar facility is out of the scope of the project.
The other thing to keep in mind is given the insights we have about building a 130,000-ton plant, we build a 130,000-ton plant, not a 100,000-ton plant, with incremental extra capital from all the learnings we've had for the first plant. The output you're going to get out of this plant is far greater for a similar amount of capital.
You can get the capital number down a lot, and when you put it all together, it basically says to complete the expansion and debottlenecking of the first plant and building this second plant, the DOE will probably cover 30% to 50% of the capital cost associated with that combined investment.
Vincent Andrews
That's great news. I'll pass it along.
Thanks so much.
Mark Costa
Yep.
Operator
Your next question is from Patrick Cunningham with Citi. Your line is now open, please go ahead.
Patrick Cunningham
Hi, good morning. I guess just on Advanced Materials, where do you stand in terms of price-cost for the business?
How much of the planned price recoveries have you gotten year-to-date, and is this more of a headwind in 4Q as costs start to ramp up and prices start to stick in other areas? Just in terms of the January 1 price increases, how should we think about the levels that you're targeting there?
Mark Costa
I'll start with just on a full-year basis, and then I'll talk about Q4. The commercial teams have done a phenomenal job on managing price in this environment, and as we talked about back in April when the Iran conflict was driving raw material prices up in a significant way, we leapt into action across the whole company, including AM, and started increasing prices in a pretty significant way to keep up with that higher raw material costs as well as distribution costs that come with this crisis.
I think we've done a great job, and the implemented prices that we did, especially in the specialty plastics side of things, I think was keeping up with those raw material increases with the actions we took through July. I think we've made very good progress on that.
When it comes to the SP side of it, we were pretty much catching up in September, and then, of course, with the Iran conflict escalating, had a new spike up in PX prices, because they were back in the July-August timeframe, prices of oil were down in the $80s. We were expecting a raw material tailwind in the back half of the year in our guidance back in the second-quarter call as prices sort of got implemented at higher level and raw materials were expected to come off.
Obviously, that didn't happen. Prices have held, but we have much higher level of PX that's really impacting Q4.
We are taking actions, but it's a little difficult in the middle of the quarter to sort of address the problems that higher cost creates. We'll probably have about a $15 million headwind that's really associated with a bit in Q3 at the end of the quarter and mostly in Q4.
We have a $15 million headwind relative to what we expected would have been a greater than $15 million tailwind, so that's quite a swing from where we were in July. On the film side, there were some prices that were locked in annual contracts in the interlayer side and some adjustments we have made in prices to regain some share in a few places.
We talked about that to you in the beginning of the year. That's been a all-year thing.
Of course, raw materials higher there, that's led to some compression, and some of that has been offset by some price-cost expansion in performance films. When you put all that together, it's about a net $15 million.
You've got on a full-year basis about a $30 million headwind in price-cost for the segment. Half of that is really a Q4 thing with specialty plastics, and the other half is spread across the entire year.
The January 1 pricing increases that we'll put in place will address that raw material cost challenge that we're facing and we feel confident we can sort of cover the raw materials as we go into next year. I would mention if the war comes off and prices go back to the $80s, we'll be in a position to have a pretty significant tailwind in price-cost next year relative to this year.
Patrick Cunningham
Understood. Very helpful.
Then maybe just on some of the operational constraints with the delays on the Tritan startup and the polymer line conversion, I guess, how substantial are these delays? Does this persist into next year?
Maybe just in terms of the size of the plant shutdown in terms of the earnings impact, pushing that from 3Q to 4Q, if you could help size that, that'd be helpful as well.
Mark Costa
Sure. The the line delays are are solely an impact in the quarter of in third quarter.
We had two lines. One was the large Tritan line that we we've been constructing as part of the circular program, and we had finished the construction of it and desperately needed it to ramp up and serve the Tritan demand that we had in the quarter.
We were, pushing hard to start it up, and we ran into some issues with some bad pumps that had to be replaced, and that delayed us, by about a month in getting the line started up. That impacted, both the cost of, fixing that as well as missing some orders at the end of the quarter.
The conversion of a polymer line to make PET, which we talked about to you guys a long time ago for making PET to serve all the Pepsi demand and other customers that really wanted product in the Q in Q3, we ran into some startup issues in that line, which also delayed us about a month. Both lines are up and running and running incredibly well, it's no issue for Q4, but it did impact creating some additional expense in the quarter, and then it also impacted, sort of the volume we could have sold in the quarter, that that was part of why we were, not, a little bit below Q2 as opposed to being, above Q2 in our original guidance.
Greg Riddle
Can we have our next question, please?
Operator
Your next question is from Josh Spector with UBS. Your line is now open, please go ahead.
Josh Spector
Hi, good morning. Maybe this is related with the prior question, but just your commentary around reiterating 3% volume-mix growth this year implies fourth quarter you need about high-single-digit volume growth, understanding it's an easy comp in fourth quarter, but 3Q was an easy comp as well.
I imagine it's more than just the polymer lines that you need to pick up to get there. What drives that confidence to say that now?
Mark Costa
That's a great question. I'm going to answer it first on sort of full-year basis, and then come back to sort of Q4 specifically, cuz I think context matters.
Overall for the full year, we expect to be about 3% up in volume-mix in Advanced Materials, which is a really impressive performance in the context of the year that we're in. Two-thirds of our revenues in discretionary markets in Advanced Materials, and you've got challenges in auto, of course, where automotive demand is challenged both on the sales and the production side, especially in China, which is extraordinarily challenged.
The innovation has just done a great job on the interlayer side of holding revenue flat when the market is probably down sort of 2%, 3%, 4%, depending on who you ask, but it's certainly down. That innovation in HUD and getting more territory on an EV versus an ICE car that we've told you about before, etc., is certainly playing out.
Then on the performance film side, that's been the more challenged part. The majority of our profit in performance films is sort of split between North America and China.
Obviously, things have been fine and holding up well in North America, but in China, with the market being down about 20% in sales, that's a pretty material headwind, and so we faced that headwind, and it really impacted us in Q1, where we served the high-end market. We responded, and told you about this back in the Q1 call, of broadening our position into the mid-tier because our low-cost asset we brought online in China allowed us to penetrate that market.
We had drama, we had a significant headwind with low demand, dealers destocking in Q1, and then a significant improvement in business as we went from Q1 into Q2, the actions that we took, along with optimizing the cost structure of that business in Q2, and all that carries forward. Carries forward into Q2, which was very strong.
Q3 was a little less strong because Q2 was very strong, and sort of how the dealers had loaded some inventory and they were expecting the market to grow, and it didn't, sequentially. They're managing inventory.
That's a big part of the story on Q3. Overall when you look at it, and that momentum still continues with that broader market position into Q4.
We have a broader market position in a tough market. We have innovation delivering growth in autos.
We'll be a contributor year-over-year in Q4, but also on a full-year basis, but it's lumpy across the quarters. On consumer durables, same story: mid-single-digit growth in a down market, and that's all about winning applications in Tritan, that's part of the renew value proposition that's allowing us to win with customers, and just the great performance Tritan has, and our teams just out there fighting every day, picking up market share versus other materials.
Great story, volume growth there, steady markets. Are obviously giving sort of modest growth.
On a full-year basis, I would note there's also about a $15 million revenue loss relative to last year of some business that we walked away from last year, this is not Iran conflict-oriented, but just walked away from in medical that just didn't have much value. That sort of masks some of the growth that you're seeing across all these other areas.
In Q4, you just have the momentum and pickup of all the renew volume going into the quarter, which is pretty significant as we're driving to our up to $100 million of revenue. A lot of that's in Q4, so that's part of how Q4 is better.
You've got the continued innovation across the durables that's delivering value, and you've got some more stability in market presence in PF. All of those come together to give you the ability to have some better volume growth year-over-year and not as much of a sequential decline as you would normally expect.
Josh Spector
Got it. Thanks, Mark.
Operator
Your next question is from Frank Mitsch with Fermium Research LLC. Your line is now open, please go ahead.
Frank Mitsch
Thank you. If I could piggyback on a couple of things: one, the congratulations on getting the DOE grant.
Mark, obviously you're saying that you're going to grow the circular sales in 2026 up to or approaching $100 million, and I believe in the prepared remarks, it was expecting another $100 million in 2027. I guess I would have thought that 27 would have been higher than 26.
Can you speak to the expectations there and what we can expect in 27 and beyond?
Mark Costa
It's a great question, Frank, and we are seeing a lot of great revenue momentum in the circular economy as you're highlighting. It's important to keep in mind that it's sort of half specialty, half PET.
I think on the specialty side, it's going to be continuing to deliver the performance we've delivered this year, right? Mid-single-digit growth in a challenge market is great.
That momentum should just continue as we go through next year and continue to build in the specialty side of things. When it comes to packaging, I think that's where the big step-up in volume is.
This line that we just converted in Q3 is now available for a full year next year. We certainly have more capacity to support growth in the rPET space, with Pepsi, with some other major brands that are very engaged with us, and when we get to January, we'll be able to talk more about some of those customers and what we're doing with them as we get their commitments finalized.
We have a very clear line of sight that the revenue there will be stronger. I would say $100 million is a minimum for what we need to deliver next year relative to this year when you look at that momentum.
It's early and we don't know what the state of the economy is going to be with the Iran war, at this stage, it's good to be a bit conservative until we have clarity on the economy and can give you better insight in January.
Frank Mitsch
That's very helpful. Makes sense.
Then Willie, the expectations on operating cash flow for the full year went from $900 to $850 million. I was just wondering what accounted for that decline, and if you care to offer a sneak peek on your expectations for 2027?
Thank you.
William McLain
Thanks, Frank, for the question. As Mark already highlighted, we've had continued inflationary pressures with the Iran conflict and what's going on in the Middle East.
That's putting a little bit more pressure on working capital as we wrapped up Q3 and early Q4. We expect a release as you think about how much working capital has been built through the year.
That's almost $500 million year-to-date, $560 million to be exact, and we expect that to release in Q4 and have our traditional strong Q4 cash flows. Again, we think that's around $850 million, but that also sets us up for stronger cash in 2027.
Even if you don't even have to release cash next year, as long as we avoid headwind or re-escalation and things normalize, we will have significant cash flow above the 850 in 2027. We'll be talking more about that on the year-end call when we have I'll call it our complete outlook pulled together.
Frank Mitsch
Thank you so much.
Operator
Your next question is from John Roberts with Mizuho. Your line is now open, please go ahead.
Hey there, John, your line is now open. You can go ahead.
John Roberts
Sorry, I was on mute there. Yep, my apologies.
I think you initially announced the ethylene-propylene flex unit at the December 2021 Investor Day. What took so long for that project to reemerge, and if you had had it up for 2026, would the EBITDA benefit have been at the lower or higher end of that 75 to 125-plus range you gave on slide 10?
Mark Costa
John, first of all, the EP project, the flex unit that we're talking about, is a phenomenally great project and a huge value-adding investment, and it's a fair question around why didn't you do it sooner? Back when we originally had this idea and the concept of what we're trying to do was sort of limited, and we were very focused on CapEx when we were driving the organic investments in circular and some other growth projects across the company.
Being responsible about capital allocation, as we always are in our discipline, and not spending more than we have, we had to make some tough trade-offs, right? We focused on the circular economy versus this investment, and I still believe that was the correct choice to do in the information we had at the time when we're making the decision.
We didn't exactly see four years of stagflation ahead of us when we were making this choice. Where we are today, this is a great investment.
Actually because of the way time has gone by, we've developed more insight around the technology and realized that we could double the scale of the investment from what we were intending to do in the beginning to create a lot more value for shareholders from that investment. To get $100 million of earnings, sort of on average, 75 to 125 in range, for something that is repurposing an existing cracker that's very capital-efficient approach and a payback in one to two years is great, especially in this business that certainly has its volatility.
It not only delivers $100 million, roughly in value, it also takes a lot of volatility out of the earnings because a lot of the volatility in our earnings comes from the ups and downs of the bulk ethylene sales, and we sort of now minimize that and take that volatility out. It's great both in volatility and value.
We did actually run the numbers, cuz we thought someone might ask, of what the value would have been in 2026, and if the capacity had been online all year, it would have added, coincidentally, about $100 million of earnings to this year in this current volatile context. It's a great investment over time, it's very capital-efficient, reduces volatility.
We're looking forward to having it online in the middle of 2028.
William McLain
John, I would just add, as we think about capital efficiency that Mark just referenced, I think we highlighted also that on the high end, the simple payback's a year, and on the low end, it's about two years, which is great as we think about capital going forward.
John Roberts
Good. I'll pass on.
Operator
Your next question is from Salvator Tiano from KeyBanc Capital Markets. Your line is now open, please go ahead.
Salvator Tiano
Yes, thank you very much, and good morning. I wanted to understand a little bit better the AM and FP price-cost situation.
There are a lot of comments about how you have contractual pass-throughs, but the implied, I guess, price-cost spread seems to be widening every single quarter. Firstly, when it comes to your pricing mechanisms, how do we reconcile the view that most are just contractual for the cost versus the widening spread?
Secondly, specifically on Q3, when we look sequentially versus Q2, you have 4% more price, 7% lower volume. It seems that this is pretty much resulting in the sequential EBIT increase, and there was no incremental sequential cost, that's kind of at least what a model would spit out.
How were you able to get sequentially 4% more price when your inflation didn't rise materially Q3 versus Q2?
Mark Costa
It's not all cost pass-through in this business. Roughly half is CPT, if you will, and the other half is where we make price choices like everywhere else in the portfolio.
The team has just done a phenomenally good job in commercial execution across the entire portfolio, managing price in this context. Their ability to sort of be commercially excellent is also supported by being in a lot of very stable markets, right?
Two-thirds of AFP are in stable markets that don't have as much economic stress in them as B&C or auto or durables does. You have a calmer, more sort of straightforward relationship with customers in that market as they're pursuing delivering steady growth year-over-year.
That helps. The CPTs certainly do help in the nature of those CPTs, with the level of volatility in raw materials that we're dealing right now certainly continues to create some tailwind and I think that as we go into next year, won't turn into a headwind, just to be clear, but I think it'll stabilize out as we're catching up to these raw materials or in this quarter, getting ahead of them.
I think that we're in good shape that this is a durable improvement this year, and then we can hold on to it next year from what we can see. Then, of course, the volumes being stable gives you a certain amount of growth on a full-year basis.
On a sequential basis, there's obviously seasonality that you see in the numbers on the volume coming off, and that's just seasonality as far as we can tell from Q2 to Q3, but it's just excellent performance. Operations have run really well.
There was a big shutdown in Q2, and so they have a lack of shutdown headwind that was in Q1 to Q2, and then we have that as a tailwind across two large shutdowns that are giving us some help there.
Operator
Your next question is from Alexey Yefremov with Barclays. Your line is now open, please go ahead.
Ryan Weiss
Thanks, and good morning. This is Ryan Weiss on for Alexey.
Mark, a couple questions for you all related to acetate tow. I believe in the prepared remarks, you guys are talking about some form of price degradation in '27.
I guess just how much you kind of expecting there? Then I believe you also mentioned that you have some confidence that you can grow volumes in acetate tow next year.
I recall this is a pretty competitive market, and some of your customers have been comfortable running it at lower inventory levels, just trying to level set kind of what's going on there. Then lastly, just in this market, I think a competitor in the East recently acquired some assets that are in Europe, any commentary there?
Thank you.
Mark Costa
Sure. You embedded about three questions in there, we'll try and answer all of them.
On the tow side, I just want to talk a little bit about context for this year before we get into next year. This year, as we went into it, about 20% of the industry contracts were open for competition, if you will, as we went into the year.
A lot of those contracts were at relatively high prices compared to sort of the market average, if you will, and that led to a certain amount of price degradation as we held on to our volume. The good news is, tow volumes are stable to 2025, but came with mid-single-digit declines.
That is a context. We also were expecting tech sales to grow this year, which obviously they didn't as we had hoped, and we didn't realize that stream utilization benefit for that reason, as well as some slower demand in a few other places across the company on the stream.
Those were sort of what drove the challenges, as we think about market context. Something we also mentioned last call is that Eastman is by far the low-cost leader in the industry with the scale and integration that we have with our site in Kingsport, given the nature and scale of the entire site benefiting our cost position.
It does come with a need for the stream to run at a certain level of utilization for it to be economic and for other operational reasons. We had to keep a close eye on that, and we were pretty clear about that in past comments.
When you put those two together, we have to think about what's our strategy for going into '27, and we do believe volumes will improve next year. It's a mixture of the destocking seems to have played out with the independents, which are often more on an annual contract basis, and therefore, they were more aggressive in their destocking.
We still see the multinationals that have more multiyear agreements and contract minimums that are going to have to continue doing more destocking next year. We're certainly going to pick up a tailwind from that destocking finishing.
For the stream reasons, we've been looking at our market position where we lost a lot of market share from '24 to '25 when we're being disciplined in our pricing, and we're intending to regain some of that in this context. There's a lot more industry contracts open this year.
Fortunately for us, quite a bit less of our contracts are actually open relative to the overall market. As these contracts are playing out, we are regaining a bit of our share in some places.
When you put all that together, we have better volume next year, and then you've got the natural adjustment of these new open contracts where the prices are coming off. We expect another mid-single-digit decline in prices, but differently, improvement in volume, and this combined with a couple of other growth programs that are now getting into gear, we expect a pretty meaningful asset utilization tailwind to go with all of this.
When you put all that together, it allows us to keep earnings in 2027 stable to this year. Oh, and you asked me about the Jinan-Cerdia combination.
I forgot to answer that. We obviously can't comment on what their plans are, and we're certainly still evaluating what they intend to do and how it might impact the industry.
A couple of high-level industry perspectives I would suggest is combination of those two would increase their capacity to serve the market, but it will include some high-cost assets. We expect them to be focused on cost synergies, as anyone is in an acquisition, and as they look at integration when they put that together to make sure they're supporting the debt they've taken on and delivering a good return on investment.
When you look at their situation, I think it could lead to higher capacity utilization, and they certainly don't have any reason to add capacity. I think that could be a stabilizing force in the industry, but it's way too soon to really know and we're going to have to see how customers respond to this announcement.
That's sort of our view on it at this point.
Operator
Your next question is from Jeff Zekauskas from J.P. Morgan.
Your line is now open, please go ahead.
Jeff Zekauskas
Thank you very much. Yes?
Hello?
Operator
Hi there, I just was making sure you were unmuted, you can go along with your question.
Mark Costa
Go ahead, Jeff.
Jeff Zekauskas
Thank you very much. Thank you.
Now that you've received this DOE grant, is it likely that the trajectory of your capital expenditures will go up or down or stay at the same rate? In other words, will you spend more capital over the next three years, less capital, or the same amount of capital now that you have the grant?
William McLain
Jeff, thanks for the question. The first phase of the project, as Mark's highlighted, the investment scope is really focused on expanding our Kingsport methanolysis operations and supporting the collection of feedstock and processing infrastructure.
We expect this first phase of investments to be incremental, as we've already previously stated, and now with the DOE support, to remain within our planned CapEx for 2027. No major changes on '27, and if I think about CapEx overall, while we're doing the metathesis project, we also have completed the Tritan project, we'll be disciplined out of the gate depending on the economic scenario for '27.
Effectively, the grant cuts the additional investments as we think about going forward in '28 and the future at roughly 50%. We've also highlighted that we'll be disciplined, and ultimately, it'll be a good scenario as we think about moving forward with the second facility as we deliver on the first facility and fill out the expanded capacity.
I'm not going to state more about the future, but that'll be a good opportunity for us as we meet those milestones.
Mark Costa
What I'd say, it's a great way to sort of reduce the capital and the efficiency in our ability to be competitive in the circular economy to drive volume growth and earnings growth, we're really happy about it. Overall capital allocation depends on your cash flow each year, we'll have to see how things play out in the economy.
Jeff Zekauskas
Okay. In terms of your inventories, I think year-over-year maybe they're up $250 million.
Do you have to cut back on your operating rates to bring them down, or do you think you can operate your businesses normally and still work your inventories down through the course of 2027?
William McLain
Jeff, a couple of things. One, I would just highlight that earlier in the year, we've talked about how we've added raw materials for security of supply.
I would highlight there it was paraxylene, as well as wood pulp. Also, as you think about in Q2, we did actually reduce some of our finished goods inventory so that we could take on more of that.
As Mark has also highlighted here again, the inflation that we've seen here at the end of Q3 going into Q4, we would expect not only the raw materials to go up, but as we convert those raws into finished goods, that'll put pressure across the work stream. We expect to have and also had a planned turnaround in Q3.
That planned turnaround got pushed out into Q4. Naturally, the key takeaways are inflation, security of supply, as well as the timing of our turnarounds.
I see all of that ultimately normalizing. We're going to release inventory in Q4 as we deplete that during our turnarounds, as well as as we go to 2027, we have ultimately a level of inventory on raw materials that we can work through and create a tailwind in 2027.
I would highlight also that our days inventory from year-end '25, it was, call it, 115 days; at the end of Q3, it was about 105. There's been a lot of inflationary pressure.
We're working through it, and that's what'll give us some additional tailwind in 2027.
Mark Costa
Where the real opportunities for inventory reduction are Advanced Materials and fibers. Those two places, as we look at next year, we have confidence that volume is going to be greater next year than this year, you've got that volume growth to contribute and manage that.
I just addressed the fibers growth, and then Advanced Materials, if we deliver similar growth as we did this year or better, that gives us the momentum to sort of pull down that inventory as well.
Jeff Zekauskas
Great. Thank you.
Operator
Your next question is from David Begleiter with Deutsche Bank. Your line is now open, please go ahead.
David Begleiter
Thank you. Good morning.
Mark, just in CI on the propane-propylene spread, you mentioned in the prepared comments how it should be a temporary condition. Can you talk to why you think it'll be temporary, and talk about the impact of the spread not just in CI, but in the rest of the portfolio in Q4?
Thank you.
Mark Costa
Sure. Thanks for the question.
Good to hear from you, David. In general, high oil is a very good thing for the olefin complex in North America, and that has been true in 20 in Q2 and Q3 as sort of went through those dynamics, driven by the Iran conflict.
Q4 has turned into a very sudden and unusual situation. What's happened in the propylene side of the chain, which is where we're concentrated, you had a situation in September where propane was 80 cents a gallon, oil was $80, PGP was 40 cents a pound, and that economics, the advantage that we have as a North American producer, was good.
Today, we're at $1.20 propane per gallon and 43 cents in PGP, and this is where it gets interesting, Asia, principally China, is at 61 cents in the value of propylene. You've got a 20-cent-per-pound arbitrage that's open between China and the US, and that is extremely unusual.
In fact, the last time it was this big was in 2004. It lasted about two months.
As you look over the last 20 years, which we did in preparation for this question, every time you see the arb open between Asia and North America in this context, it closes very quickly. You guys can do your own math, but you can see it.
It's pretty clear that these arbs, when they're that wide open, get closed. Today you've got the cash margins in European crackers, in the naphtha part of the refinery, are negative, right?
European production is being materially reduced. I think at these prices, youre going to start seeing even PDH reductions here in the US.
Supply is going to start getting constrained. That will reinforce the close of this arb.
I will admit that time to sort of close it is difficult because the ships to move propane around are constrained by all the Iran war drama. That's a complexity, and it's also hard to solve in a Q4 dynamic when you're seasonally low in volume, there's a lot of customer caution out there about the future economy.
When you put all that together, it's hard to close that arb instantaneously. What we are doing is shifting our focus to offset some of this by shipping exports of olefin derivatives into Europe, where the prices are going up because China's disadvantaged at the 61 cents plus logistics to get there relative to the US and getting to that market.
We're taking actions as much as we can within the quarter to get that export out there and offset some of this arb at the propylene level, cuz, remember, we don't sell propylene, right? We sell propylene derivatives.
That's our focus on how we manage that. When you look at this context, it looks pretty much like this arb will get closed, and that will make a difference.
When you think about that as you think about next year, you can't use Q4 as a proxy because of this, even if you closed half of the arb that's open right now in this quarter, per the logic I've laid out, you'd add $30 million to $40 million of earnings to next year relative to Q4, and Q4 is seasonally very low in volume anyway, you can't annualize the volume side of it either. Q4 is not a very good proxy when you're trying to look at how you want to do this.
When you're thinking about next year, I think Q3 is probably a better place to start at some level. If you look at the propylene-propane spreads there, they're about 27 cents.
10-year average is about 28 cents. Pretty similar to historical average, where Q4 right now is about 14, which is way disconnected from anything that is remotely normal.
Some degree of return on that, I think, is logical to expect. Asset yields will get better next year because of some of the capacity shutdowns that have been announced.
When we put all that together, I would say that we could be earnings next year somewhat moderately below this year, but it's not likely to be a significant headwind as we're growing the specialties in the portfolio. I don't expect CI is going to be a, from what we can know today, a big headwind to sort of offset that.
David Begleiter
Very very helpful. Just on circular, you mentioned the incremental sales for next year.
Can you just discuss the incremental earnings you would expect with those sales and maybe overall total earnings from this platform in 2027? Thank you.
William McLain
David, what I would first highlight is with the up to $100 million this year, we think the earnings on an incremental basis is going to be around $20 million. Also as you think about the current economic environment and the value that we're getting from I'll call it processing feedstocks versus paraxylene, we would expect to continue to run the plant hard here in Q4 and look to grow that into next year.
We'll be building upon those, and expect it to be at or above those, as Mark already highlighted. At this point, we're looking at being at the conservative end, but we'll be building upon that incremental growth in 2027, and we'll be more specific as we get the economic scenarios and plans in place at the beginning of the year.
David Begleiter
Thank you.
Operator
Your next question is from Matthew DeYoe with Bank of America. Your line is now open, please go ahead.
Matthew DeYoe
Yeah. Good morning, everyone.
It feels like or at least directionally, we've seen some commentary around different degrees of interlayer capacity expansions coming maybe from some of your Japanese competitors. Can you talk a little bit about some of the dynamics around that?
I'm not 100% sure if it's the same polymer strains or not, but demand isn't necessarily super robust for some of these markets, I was just kind of wondering how you think that plays out.
Mark Costa
For the markets we play in with the Japanese that we compete against, we don't see any sort of material capacity expansions coming from them. I think in this market, where demand has been pretty challenged, there's not a lot of incentive to add capacity to that market until we have more clarity around market growth.
Matthew DeYoe
All right, I appreciate it. Otherwise, all my questions were asked.
That's fine. Oh, wait, did have another one.
If I can drill in on Jeff's question a little bit on CapEx, Willie, I think you'd made a comment that '27 CapEx will kind of be in line with plans. I think in our model, we had you marked up a bit for '27 versus '26, just given some of the ramps.
Can you give maybe a little bit more clarity on the absolute dollar spend planned for '27?
William McLain
A couple of things. As I think about within plan, that was really more around the I'll call it the capacity expansion of our methanolysis facility and the spend on that front, and that ultimately we would receive some funds through the DOE.
On the absolute amount, I would expect with this year coming in at $400 million is what we expect to be. Also as we think about how do we move forward within the circular as we think about the broader feedstock assets and we look at the metathesis, I would say the baseline starting point will be around $500 million.
Mark Costa
I would note just,
Matthew DeYoe
we're
Mark Costa
always disciplined about our cash flow and our CapEx, and our view of '27 is we can deliver pretty reasonable growth in earnings and cash flow, and release cash, obviously, out of working capital on top of just the earnings growth, and so we feel good about where we're headed, but we always are going to be disciplined to look at the situation, and if I'm right, we've got that kind of growth, and we'll be able to support that kind of CapEx.
Matthew DeYoe
Thanks for that.
Operator
Your next question is from Abigail Eberts with Wells Fargo. Your line is now open, please go ahead.
Abigail Eberts
Morning, thanks for taking my question. Just clarification on Chemical Intermediates, it looks like your full-year assumption for Brent crude implies slightly lower pricing quarter over quarter for the fourth quarter, but you're expecting CI spreads to be a tailwind to fourth quarter?
If you could just clarify some of your underlying assumptions there, thanks.
William McLain
I would just point out, Abigail, on the assumption, I think you're looking at the full-year average. The Q4 average is actually quite a bit higher than the full year.
Abigail Eberts
Got
Mark Costa
it, thanks. Willie's right, right?
You've had a pretty challenged market situation in Q1, then you have the Iran conflict, and that drives everything up, then the oil prices collapse through the summer, and everyone thinks it's going to be okay because the conflict's going to be moderated in some form or fashion, and then suddenly that turns out not to be true, and we are today. It's a roller coaster, to be polite, on sort of what's going on to the market, and how that all flows through.
It actually averages out to that number through all of it.
Operator
Your next question is from Laurence Alexander with Jefferies. Your line is now open, please go ahead.
Kevin S.
Hey, good morning. This is Kevin Estok on for Laurence.
Thank you for taking my question. I guess just on underlying demand, how much of the weakness recently, at least in auto and consumer durables, I guess how much of that actually reflects actual end-market deterioration versus, let's say, maybe customers reducing inventories, delaying orders?
I guess and just what are you assuming for your end markets, let's say, as we enter maybe the first half of 2027?
Mark Costa
That's a great question. From an end-market point of view, obviously, the end markets have been challenged, and we've been in a version of stagflation since 2022, right, that has not had any improvement.
I think that as you look at the auto market, obviously it's impacted by interest rates, the price of gas, and everything else going on this year, but the challenge in demand has been in place for quite some time. We expected the beginning of the year autos would have been similar to last year.
Turns out they're going to be, from a sales point of view, probably down 3% to 4%, and that's a function of interest rates and gas prices, which I think all connect to some degree the Iran war. I think when you look at building construction, it's been down 20% on total home sales in the US, starting in '23, and it's stayed there, and it continues to be weak.
Also true, about the same percent of 20% down in Europe, and obviously China being worse. Consumer durables are to some degree connected to home sales as a transaction moment and just overall affordability.
Those also remain somewhat challenged, and I'd say, at least in the back half, are going to be a bit down relative to last year. Overall if you look at it, it's been down, but it hasn't gotten a lot worse this year.
It's just not gotten better, right? In the beginning of '25, before the trade war, the economy was recovering, and then the trade war hammered it down.
Things, I think, were stabilizing with consumers and it was getting a bit better, and first quarter of this, the Iran war hammered it down. Unfortunately, those two events have prevented some market recovery, but underneath it, what it tells you is consumers are resilient, because everyone still has a job, and that's the key difference between other sort of recessionary moments where a lot of people lose their job and really cut back on spending.
People have their job. They're just moderating how they've spend money, to manage that affordability.
That's the good news. Then if you actually add up the area under the curve of things they've not have bought, since 2020 to now, there's a lot of pent-up demand if we could just get to some stability and where they feel safe.
In this context, we're demonstrating our innovation still delivers a lot of growth, as we said it would, and have proven year-over-year. When you got mid-single-digit growth in consumer durables in a down market, when you got autos flat in a down market, you've got all this renew growth creating new markets for us to sort of grow in and expand our corporate addressable markets, accessing the packaging market in a profitable way, etc., we feel good about how we're delivering growth this year in this context.
If this context, which is very challenges, continues into next year, we're confident we can keep delivering that revenue growth in this context. That's one context.
It could stabilize if the Iran conflict gets resolved. I think that would be a big stimulus in consumer behavior, feeling safer about the future, so that could happen, but that would be upside in how we plan for next year.
The revenue part feels like we're in a good shape to drive growth in revenue. Then, as we mentioned, we have ways to stabilize fibers.
I don't think CI is going to be a big headwind despite the drama we're in here in Q4, and then we've got tailwinds in spread, tailwinds in asset utilization, it all lines up to being a pretty good year with that volume, and importantly, when you think about that and the working capital can be released, a much better cash flow year next year.
Kevin S.
Great, thank you.
Operator
Your next question is from Kevin McCarthy with Vertical Research Partners. Your line is now open, please go ahead.
Kevin McCarthy
Yes, thank you very much, and good morning. Most of my questions have been asked and answered, but I was curious, Mark, within ANFP, do you have in your mind that functional amines is likely to be appreciably better or worse moving into 2027 based on what you're hearing from your agricultural customers in particular?
Mark Costa
Our functional amines business, first of all, it's been a phenomenal acquisition and delivered consistent earnings growth just year-over-year since we've had it, and it's on track to have a record earnings this year. I also mentioned AFP is on track to have a record earnings for this year to anything in our past.
We feel really good about how the overall segment's performing in this context, and amines is a real contributor to that steady, continuous improvement. A lot of that goes into personal care kind of products and home care products that's very stable and has growth.
Obviously, there's some up and down in ag, but from what we've seen so far from our ag customers is they feel like next year will be a stable year, and planning on sort of modest growth there. We're not seeing any big spike up or drop.
There's a lot of dynamics around ag, as there is every year, I'd rather not predict next year on the ag market until we get into January and have a little more clarity about how the season is expected to play out.
Kevin McCarthy
Fair enough. Then just as a clarification, Mark, if I may, is the projected cost of your metathesis plant likely to be roughly $100 million, or would you steer us to a different level over the next couple of years?
William McLain
Kevin, this is Willie. You may have missed earlier when I commented that it's a one-year payback at the high end of the EBITDA, and it's a two-year at the low.
That should give you a pretty good range on the capital.
Kevin McCarthy
All right. Thank you.
Greg Riddle
Let's make the next question the last one, please.
Operator
Thank you so much. Your final question is from Arun Viswanathan with RBC Capital Markets.
Your line is now open, please go ahead.
Arun Viswanathan
Great, thanks for taking my question. Hope you guys are well.
I just wanted to clarify on the volume outlook. It sounded like you said that you do expect volumes maybe slightly up next year.
I guess I was just wanting to clarify if that was AM and AFP specifically. Then, in the past, I think there's been some confusion between primary demand and restocking/destocking, could you just address, maybe just clarify that, and sorry if I missed that, but if it's positive volume growth for next year in those two segments and if it's actual primary demand or maybe some restocking?
Thanks.
Mark Costa
Sure. Yes, we are expecting volume growth in AM, AFP, and fibers next year relative to this year, and we'd expect volumes to be similar to this year in CI.
On the end-market question around the behavior of customers versus end markets, what I'd say right now is that we see the customers, our direct customers, the OEMs, the brands, being more cautious than the end-market demand, right? The end-market demand's pretty stable right now across a lot of markets.
It's off a little bit, but we're certainly seeing normal seasonality in the back half, which always happens as customers are managing inventory. I think we're also seeing much smaller orders, more frequently, there's a certain amount of caution they all feel in this environment with the uncertainty about the Iran war, about what that could do to consumer demand next year.
I think that softness that we have in our demand the back half of this year is a bit driven more about that fear of the future than in-market consumption in the current fall that we're in right now. There is that dynamic right now.
In theory, that could mean there's some destocking inventory, certainly it is relative to current demand. I think they're destocking and would need to replenish if demand holds up next year.
It's understandable with all the uncertainty that that dynamic is playing out across any of the discretionary markets in particular. In that context, though, I think as we looked at, that happened this year relative to last year, by the way, with the Iran conflict creating additional stress on top of the trade war, and so we've seen that impact, and yet we still found a way to have volume growth in Advanced Materials, as we've described, and AFP has about $20 million of discontinued products, and were able to replace that with growth.
They are also doing reasonably well in that underlying growth, market development efforts. I think that we're in a position in a stable market to this year, which is certainly currently challenged, we'll grow volume in AM, we'll grow volume in AFP, you've got the whole circular program delivering a lot of revenue growth, told you what we're going to do in fibers.
We feel pretty good about how that can play out. It sets us up for at least having a good running start at next year and delivering earnings and cash flow growth.
Arun Viswanathan
Thanks.
Greg Riddle
Okay. Thanks again, everyone, for joining us.
We very much appreciate your interest in Eastman, and I hope everybody has a great day.
Operator
This concludes today's call. Thank you so much for your participation.
You may now disconnect.