Esquire Financial Holdings, Inc.
NNASDAQ:ESQQ3 FY2026 · Earnings Call TranscriptOctober 27, 2026
Operator
Hello everyone. Thank you for joining us, and welcome to Esquire Financial Holdings Q3 2026 earnings release conference call.
After today's prepared remarks, we will host a question-and-answer session. If you would like to ask a question, please press star one to raise your hand.
To withdraw your question, press star one again. I will now hand the conference over to Andrew Sagliocca, CEO, Vice Chairman, and President.
Andrew, please go ahead.
Andrew Sagliocca
Thank you, Kenneth. Good morning, everybody.
I'm joined in my office by Michael LaCapria, our SVP and CFO, and Eric Bader, our EVP and COO. I'd like to start the call by thanking and welcoming everybody, including our investors, analysts, board members, managers, and employees, including our new business partners from our new Signature division out of Chicago.
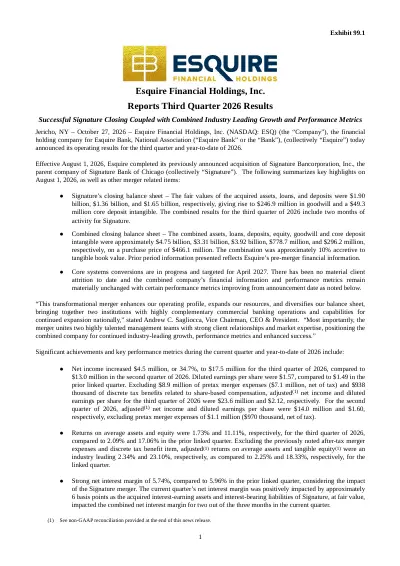
I'm going to start the call with some high-level thoughts and comments, then turn the call over to Michael for a financial update, and then we'll address any questions from those on the call. During the quarter, we successfully closed the Signature Bank merger on August 1, '26, which diversified our loan portfolio and funding sources, and we also continued to show strong organic growth and performance on a combined basis.
At closing, Signature had total assets, loans, and deposits of approximately $1.9 billion, $1.4 billion, and $1.7 billion respectively. The combined results for Signature for the third quarter includes only two months out of the three months of Signature activity.
Most importantly, the merger unites two highly talented management teams and employee bases with a strong client relationship and market expertise, positioning the combined company for continued industry-leading growth, performance metrics, and enhanced success. Regarding the conversion, our core system conversions are in progress and targeted for April 2027.
There has been no material client attrition to date. Our growth and performance metrics remain materially unchanged from announcement, with certain performance metrics improving as noted in our earnings release.
Couple of quick highlights. Excluding the merger, we still experienced strong organic growth in loans and deposits over the past 12 months, totaling approximately half a billion dollars in loan growth and about $450 million in deposit growth.
Also, on a linked-quarter basis, we continue to demonstrate similar organic loan and deposit growth as the 12-month period. We have solid credit metrics, asset quality, and reserve coverage ratios.
When we exclude the merger expenses and certain discrete tax benefit items in the tax line, our adjusted diluted earnings per share was $2.12, and our adjusted return on average assets and return on average tangible equity was 2.34 and 23% respectively. The Signature merger, coupled with our combined asset size, enhanced resources, and diversified loan and deposit platforms, positions our company for continued strong growth and performance.
We believe we will exceed our initial earnings expectations when we announced the merger on March 12, 2026. With that said, I turn it over to Michael to give you his financial update and financial highlights.
Michael?
Michael Lacapria
Thank you, Andrew, and good morning. I will provide a brief overview of our third quarter 2026 financial results as highlighted in our earnings release and investor presentation published earlier this morning.
Like Andrew said, please note that our this is our first quarter reflecting the post-merger combined company, and the results include two months of Signature's activity from the August 1st closing dates. This successful merger closed at a purchase price of $466 million, which is 10% accretive to tangible book value on day one, giving rise to a combined company that is $4.8 billion in assets, $3.4 billion in loans, $4 billion in deposits, and $492 million in tangible equity, net of $247 million in goodwill and a $47 million core deposit intangible as of September 30th.
Let me start with net income. For the third quarter, we reported GAAP net income of $17.5 million, or $1.57 per diluted share.
These results included $8.9 million of pre-tax merger expenses, which is $7.1 million net of tax, and $938,000 of discrete tax benefits related to share-based compensation. Excluding these items, our adjusted our adjusted net income is $23.6 million, or $2.
or $2.12 per diluted share, which is which exceeds consensus estimates. This compares to an adjusted net income of $14 million, or $1.60 per diluted share on a linked-quarter basis, representing a 69% increase.
Our adjusted returns on on average assets and average tangible equity were 2.34 and and 23.1% respectively for the quarter. These remain industry-leading metrics while we continue to invest in our current resources to support future growth and maintain excellence in client service our that our customers have come to expect.
Our net interest margin for the quarter was $5.74, 5.74%, compared to 5.96% for the trailing quarter. That being said, our normalized net interest margin was approximately 5.68%, or 6 basis points less than the full quarter's result, since Signature was included for two of the three months in the current quarter.
This decline from current from prior quarters appropriately reflects the change in the combined asset and funding mix following the acquisition. Loans increased $1.5 billion or 80% to $3.43 billion from June 30th, of which $1.4 billion was attributable to the Signature merger, while the remaining increase was primarily attributable to organic litigation-related loan growth of $160 million or 49% annualized, bringing our litigation book to $1.46 billion.
Our litigation book now represents 42% of loans as compared to 67% in the trailing quarter, provided for by the expected diversification benefit of the combination. On a year-over-year basis, organic loan growth was $497 million, or 32%.
As it relates to our litigation loan portfolio, we continue to see strong organic growth, healthy client activity levels, and a tremendous opportunity in the untapped Midwest market. The litigation vertical remains a primary strategic focus, which is a key source of low-cost core funding to the bank that supports asset growth across the balance sheet.
Deposits increased $1.8 billion or 83% to $3.8 billion from June 30th, of which $1.65 billion was attributable to the Signature merger, and the remaining $147 million was primarily organic litigation-related deposit growth. From the June From the August 1 closing date, deposits increased $55 million, or 8% annualized.
On a year-over-year basis, organic deposit growth was $447 million, or 24%. Our litigation-related deposits concentration decreased from 79% to 54% as the merger diversified our exposure as expected.
Our cost of funds for the quarter, including demand, was 113 basis points. Off-balance-sheet sweeps remain a reliable source of liquidity at $776 million, with approximately $255 million, or 33%, available for liquidity if needed.
Administrative service payment fee income on these balances totaled $1.1 million for the quarter. Total liquidity, including cash, off-balance-sheet sweeps, and other borrowing capacity, was approximately $1.6 billion as of quarter end.
Turning over to credit, credit quality remains solid. Our allowance for credit losses remained at 1.3% of loans, consistent with the prior quarter, and we have six non-performing assets totaling $9.7 million, representing 20 basis points on total assets.
The 4% increase in NPAs from the trailing quarter is due to the merger. There were also no material no material charge-offs or significant downgrades to report.
Non-interest income increased $1.5 million or 24% as compared to the trailing quarter to $7.9 million, representing 7 representing 13% of total revenue. Our payments platform continues to be a meaningful contributor to earnings and client engagement.
During the quarter, we supported 94,000 small business clients nationwide, processing approximately $10.5 billion in payment volume volume across 152 million transactions. Operating expenses increased 4.9 $14.9 million or 71% as compared to the trailing quarter to $36 million, which is attributable to normal Signature operating expenses of $5.2 million, incremental merger expenses of $7.8 million, and $1.8 million of core deposit intangible amortization.
Excluding merger expenses and CDI amortization, the adjusted efficiency ratio was an industry-leading 41.1%. Merger expenses incurred inception to date was $11.6 million and is consistent with the guidance at announcement date.
Our capital foundation remains strong. The bank Tier 1 leverage and total risk-based capital ratios were 11.2% and 13.65% respectively, positioning us positioning us well above regulatory well-capitalized standards.
Now I'll turn the the call back over to Andrew for his remarks.
Andrew Sagliocca
Thank you, Michael, for that thorough update. Kenneth, we're going to turn the call back over to you for the Q&A session.
Operator
Great. Thanks, Andrew and Michael.
We will now begin the question-and-answer session. If you would like to ask a question, please press star one to raise your hand.
To withdraw your question, press star one again. We ask that you pick up your handset when asking a question to allow for optimum sound quality.
If you are muted locally, please remember to unmute your device. Please stand by while we compile the Q&A roster.
Your first question today comes from the line of Justin Crowley with Piper Sandler. Justin, your line is open.
Please go ahead. Hey,
Justin Crowley
good morning, guys.
Andrew Sagliocca
Good morning, Justin. With
Justin Crowley
some noise with Signature in the numbers, but still growth obviously looks really, really good here with the litigation vertical running on all cylinders. Wanted to maybe get your thoughts on that vertical.
In particular, the opportunity in Chicago, which I know is a big reason for the deal. Just curious what you've learned so far in terms of what had to be done, maybe anything additional that needs to be done, to penetrate that market as you bring the Esquire lending model to Signature markets.
Andrew Sagliocca
Great, Justin. Absolutely.
First and foremost, as you're aware, Signature, Mick and his team in Chicago run an excellent commercial banking platform. There is tremendous opportunity in the commercial market itself, in the Chicago and greater Midwest area.
We start there by saying that's a market that we can continue to tap and continue to grow non-litigation C&I loans and and select CRE, too. The Chicago market for the litigation-related C&I loans or plaintiff law firms that we primarily bank in our litigation vertical, very robust market.
According to our numbers, the third or fourth largest plaintiff law firm market in the country. Signature has done a good job before we've come along in penetrating that market on the depository side.
They have a small lending book in this market, but they have a lot of contacts. Mick and Brian and Kevin, the executives over there, and key members of the business development and relationship management team in the lending area have long-standing, deep relationships not only in the Chicago metro area, but in the litigation area.
That's what we've learned since we've announced the deal in March, I think it was March 12th, through today. We've spent myself, Ari Kornhaber, who runs our litigation division, Franklin Arto, who is our chief credit officer and heads up the lending area with Bonnie Doherty, who is our new CLO over the past year, have spent a lot of time in Chicago with Mick and his team, primarily on the business development side, and they have really strong relationships in the market and with plaintiff law firms that I believe we're going to be able to leverage as we move forward.
I'll end with, cuz you've heard me say this, Justin, and it's proved itself out on our business development team that we hired prior to announcing the Signature deal, it's a long sales cycle. With plaintiff law firms, they're all banked.
They have to be banked. Their operating and escrow accounts are already banked somewhere.
The goal is to get them over to Esquire and attract them not only with our lending products and what they see as capital in the form of loans we give, but also attract them over because we understand the market and understand their depository needs either/or or both.
Justin Crowley
Got it. That's super helpful.
Then, I feel like I kind of know the answer here, but just to confirm how you're thinking about growth looking out here, somewhere in the 15 to 20% annual growth, is that still the right way to think about the combined company going forward here?
Andrew Sagliocca
You should think of the combined company around 15%. We're modeling '27 at about half a billion dollars of loan growth.
Somebody may say that's conservative. You just did a half a billion ex-Signature.
We may be able to print those type of numbers, but it's anything but easy. It's a big, heavy lift to get a half a billion dollars worth of growth done because it usually means we're double or more in notional originations to get that done, because our stats on our lending side for our litigation-related loans clearly plays out at about 50% draws on the notional balance.
We're comfortable with half a billion dollars worth of growth, which is about 14%. That's a good way to think about growth going into '27.
Justin Crowley
Got it. Then just pivoting a little, as far as the margin, I know it's a moving pieces with Signature only in there for two months.
If we think about that 5.68 on an adjusted basis, how do you see that trending from there? I think you previously talked about the margin settling out in the 5.40 to 5.50 range.
Obviously the rate environment has shifted a fair bit since then, just kind of curious for your updated thoughts there.
Andrew Sagliocca
Yeah. We're using FHN Financial's model, as of September 4th, '26.
They're looking at one more rate increase to 7.25%, if we're looking at prime. If we're looking at Fed funds, from 4 to 4.25%, which takes prime from 7 to 7.25%.
Then they hold steady through the end of the third quarter, and then they have rates coming down 25 basis points in the fourth quarter and the first quarter of '28. With that said, we're looking at a margin of about 5.70, maybe as high as 5.75.
A pretty stable margin from what we printed in the third quarter, even though Michael gave you the adjusted number of, I think, 5.68.
Justin Crowley
Okay. That 5.70 to 5.75, is that kind of where it reaches, or are you giving a full-year number for '27?
Andrew Sagliocca
I'm looking at '27 saying we're going to be somewhere between 5.70 and 5.75 for '27.
Justin Crowley
Okay. Perfect.
Then maybe just one last one. I think on a combined basis you're running with what I think you'd probably describe as some excess liquidity, which I know had also been the case standalone as well.
How do you see that cash position trending and what would be the sweet spot if you're able to deploy that liquidity?
Andrew Sagliocca
I guess the best answer I can give you is we're looking at about 14 to 15% growth. In order to achieve half a billion dollars worth of growth, we're going to have to raise about half a billion dollars worth of core deposits, maybe a little less, 400, 450.
Deposits always lag loan growth, but the deposit base is higher than the loan growth, cuz our loan to deposit ratio is about 86%. We see both of those commensurate: half a billion dollars worth of loan growth, about 400, maybe a little bit more, worth of deposit growth.
That will deploy some of the excess liquidity, but we're not sitting on a lot of excess liquidity when you look at cash. We prefer to grow naturally with core deposits and invest it in loans.
Obviously for liquidity purposes, we'll continue to stay in the bond market because they're pledgeable at the Federal Home Loan Bank and the Federal Reserve discount window. We maintain a strong liquidity level.
That's how we see it. We've played out '27, and we believe we're comfortable with where earnings is coming out in our revised numbers, along with our expense base and our other fee income base.
If that's something you want to talk about, we're open to talking about '27 and how we view it.
Justin Crowley
Great. I'll leave it there and let others ask questions and circle back if needed.
Andrew Sagliocca
All right, Justin. Thank you.
Operator
Your next question comes from the line of Tim Switzer with KBW. Tim, your line is open.
Please go ahead.
Tim Switzer
Hey, good morning. Thanks for taking my questions.
Hope you guys are doing well.
Andrew Sagliocca
Good morning, Tim. Thanks for joining.
Tim Switzer
Yeah. My first one, I'm sorry if you already mentioned this, but I'm trying to understand from the press release, the 6 basis points within the NIM that you guys were talking about, was that the purchase accounting benefit from closing Signature?
Andrew Sagliocca
No. If you think about it, our margin was around 6, and their margin was south of 6.
Mathematically, they're included in our margin for two months, not three. If they were included for three months on a pro forma basis, Michael and I see the margin coming out at about 5.68, give or take a couple of basis points either way.
It has nothing to do with the loan mark. It has nothing to do with the securities and the accretion related to loans and securities.
It has everything to do with them being mathematically included in the margin for two out of three months.
Tim Switzer
Okay. That makes sense.
What was the purchase accounting benefit on either a dollar or basis point basis? Purchase accounting,
Andrew Sagliocca
well, the purchase accounting on the securities was the mark I think, Eric, was about $64 million,
Eric Bader
and
Andrew Sagliocca
we wound up liquidating most of that at market and buying back in opportunistically at market. We're not tracking the purchase accounting on securities, Tim, which was a material piece, because now it's embedded in the bonds that we want to own as a $5 billion company.
Eric's goal, liquidating their position, was simple. We're a $5 billion bank, we want to own larger blocks that are easier to pledge at the Home Loan Bank or the discount window.
At the same time, we wanted to buy new issuances with shorter duration. That was the goal.
Eric expedited trading out of those bonds at the purchase accounting mark and buying into new bonds. What that leaves us with is the loan mark.
The loan mark, the accretable loan mark, was about $16 million. Its average life is about three years.
Tim Switzer
I think Michael,
Andrew Sagliocca
that might impact the margin by
Tim Switzer
It's a 13 basis points.
Andrew Sagliocca
Again, that's a three-year mark, we'll be living with that for three years as we grow.
Tim Switzer
That was 14 basis points to the NIM this quarter. Should we expect a similar amount in Q4 or is it a little bit higher to get the full-quarter impact?
Andrew Sagliocca
No, you should expect the NIM to be around 5.70, 5.75. If we surprise on the upside, then I'll be as surprised as you and we'll obviously change our guidance.
That's a pretty strong NIM considering we all believed on our side, management, when we announced the deal that we'd be operating somewhere in the high 5.40s or low 5.50s. It's been a great run to the closing.
We were opportunistically, like I said, able to trade into new issuances of bonds that made us very comfortable. The purchase accounting came out materially close to what we thought it was going to be when we announced the deal.
Tim Switzer
No, it's all good to see. What kind of deposit beta assumptions do you guys have embedded within your guidance, and can you also talk about how the pricing power you have on the loan side if rates continue to move higher from here?
Andrew Sagliocca
Yeah. About at this point, with the diversification in the loan book, I think it's about 60% of the total loan book is variable.
All right? As opposed to probably close to 85 or 90 pre-acquisition, but it's 60 now.
As rates move up, which again our guidance that we're using is FHN Financial, we only see rates moving up on Fed funds 25 basis points more according to their projections, which is minimal for anybody's model, if we're going to use that. The reason I keep giving guidance around 5.70, 5.75 is we've already had one rate move, and that's played into where our NIM is winding up now, at about 5.68 adjusted.
If there's another rate move, I know Eric Bader going to come in my office and tell me that it'd be prudent to move up our IOLTA rates in certain material states, which would be prudent for those states that we operate in. We want to be a good corporate steward in the states we operate in and have IOLTA powers in.
We're comfortable with the margin hanging around 5.70, 5.75, considering we only have one more rate increase built into our models.
Tim Switzer
Got it. Very helpful.
Thank you, Andrew
Andrew Sagliocca
welcome, Tim. Again, like I said to Justin, Tim, if at any point on the call or after the call you want to talk about '27, both Michael and I have modeled that out and are comfortable with the revised guidance, which is why we put in our earnings release that we believe we're going to exceed the guidance we printed on March 12th with the deal.
Tim Switzer
Good to hear. Thank you.
Andrew Sagliocca
All right.
Operator
Your next question comes from the line of Steve Moss with Raymond James. Steve, please go ahead.
Hi,
Steve Moss
good morning, guys. Nice quarter here.
Andrew Sagliocca
Good morning, Steve. Thank you.
Steve Moss
Morning, Andrew, Eric, Michael. Maybe just on that subject of looking out to '27 here and I know you have the integration the systems conversion and stuff coming up next year, just kind of curious how you guys are thinking about expenses with regard to the moving parts there.
Then also just kind of curious, what are your thoughts on additional investments in both franchises as you put them together.
Andrew Sagliocca
Excellent. Excellent.
I'm glad you asked. I really am, because I'm going to start the way I never start, which is with what we believe our diluted EPS is going to be in '27.
I want to do that on this call, Steve, cuz as not only is September not a clean quarter, the obvious noise is the merger charge, but there's only two out of three months of Signature in there. We haven't even printed a full quarter combined, which as you know is going to be the fourth quarter.
The way we're looking at '27 is approximately $9 a share. If you walk through the components of that, you're looking at about a half a billion dollars worth of loan growth, starting with about a $3.5 billion starting point at the end of December.
Again, you're looking at about a 5.70, 5.75 margin. On a combined basis, we're looking at about $33, $34 million of fee income.
On a combined basis, we're looking at about $138 to $140 million of non-interest expense. Our run rate on the tax side is about 28.5%, as long as we don't have any discrete-type items in option or restricted stock-type exercises.
On a normalized basis, we're modeling that tax rate at about 20.5 28.5%. That comes out to about, give or take, $9 a share on diluted EPS for '27.
You hit it right on the head, Steve. Us long enough.
We're going to continue to invest in resources, and that is people and technology because at these kind of growth rates, starting with a $3.5 billion loan book and a $4.8 billion combined asset base and size for the company, printing about 14% loan growth or half a billion dollars, which again means we're going to print about a billion or more of notional to get about half a billion dollars worth of loan growth, we are going to continue to invest in business development, relationship managers where they're managing the ongoing clients. We're going to continue to invest in the lending area, especially on the C&I side, both litigation and commercial, where we see growth.
We have and Signature had a great commercial real estate team. We think that the combined team will be able to handle the growth in that portfolio on a combined basis across those two regions.
Obviously, we continually invest in technology, which when I say that, it could be as simple as investing in data, which we continuously do to make sure that our digital marketing platform is leading and in front of our business development officers nationally around the country.
Steve Moss
Appreciate all that color there. I guess just kind of, as you guys continue to invest and grow here and you put up a really good quarter here in terms of growth, it feels like the loan growth guidance maybe a little bit conservative, maybe just getting a little spoiled here with the numbers you're putting up.
If the pipeline is strong, I know you put on a lot this quarter, I hear you in terms of a billion in commitments. Is that just you guys being conservative here on the loan growth, or are there maybe a few takes that we're not thinking of?
Andrew Sagliocca
I think in any year or any quarter, we always have a minority of larger opportunities and a majority of smaller opportunities. I can't always count on the minority of larger opportunities happening on a continuous basis.
I am very comfortable with what I say the small loans, those loans, call it, if I had to pick a number, I'd say $25 million in notional and below. Those loans that are greater than $25 million in notional and above, I can't build and run a company counting on those type of opportunities over and over again.
Am I being conservative? I think I'm being realistic with half a billion dollars worth of loan growth.
I think we just closed the deal on August 1. We, as a combined entity where now we have not only doubled the size of the company effectively, but we've doubled the employee base.
We have not gone through system conversions. Core system conversions isn't the only thing that any bank has to focus on as they look towards April '07 for conversion.
There are water management systems we need to convert, there are CRM platforms and loan underwriting platforms and deposit and loan origination platforms. There's culture we have to align.
There's a lot of work in deals that goes unnoticed that the numbers don't reflect. I don't think we're being conservative.
I think we're being realistic. I think 14, 15% growth is a great print.
I think $9 a share, give or take, is a great print right after the deal. What I don't want to do is overpromise on a call like this, knowing how much work we have to do that has nothing to do with originating the next loan.
Steve Moss
Great, Andrew. No, I appreciate all that color.
Really helpful here. Great quarter and good luck with the integration.
Andrew Sagliocca
Thank you, Steve. As as we get through the fourth quarter and into the first, if we're feeling better about growth, and we think half a billion dollars is on the conservative end, people like you and Tim and Justin will be the first to know.
Steve Moss
Appreciate that. Looking forward to it.
Andrew Sagliocca
All right, Steve. Thank you.
Operator
Your next question comes from the line of Alan Strauss with Ithaca Capital. Alan, your line is open.
Please go ahead.
Alan Strauss
Hi. Good morning.
A few questions. One, on the system conversion, are the two companies on the same core operating system, or are you on different systems that makes this even heavier lifting?
Andrew Sagliocca
We are on Fiserv Signature, they are on Jack Henry. We are on two different core systems.
Not sure if it makes it a heavier lift. It obviously does, compared to us being on the same platform.
Jack Henry is Signature, and we are on Fiserv.
Alan Strauss
Okay. Which one's going to be the winning system?
Andrew Sagliocca
Fiserv. The Fiserv Signature system will be what our new clients at the former Signature Bank will be converted to.
Alan Strauss
Great. Looking out, say, 18 a year to two years, is it feasible to take out some of the asset sensitivity of the bank, or will the combined entities always be asset-sensitive?
Andrew Sagliocca
The combined entity will always be asset-sensitive. As starting with today, obviously, our concentration is less.
It's about 60%, and I think 100 basis points up, we're looking at about a 6.7% increase in net interest income, which we put in the investor deck on page 11.
Alan Strauss
Okay. All right.
Then last question, on the combined company, given the loan growth that you see, what would be the appropriate payout ratio on the dividend looking out?
Andrew Sagliocca
That's a good question, and that's a discussion we need to have at the board meeting. We've traditionally paid out about 10 or 12% dividend payout ratio based on earnings.
That's our traditional pre-merger ratio that we re-evaluate going into the end of the year and typically announce in early the following year. With these growth projections, our focus is not necessarily on tangible capital to assets or the leverage ratio.
Our focus is on our total capital ratio, since we are heavily weighted towards C&I loans, which are 100% risk-weighted. When we look at dividends, we're not only looking at a dividend payout ratio, but looking at capital preservation as we balance it between using capital towards growth or using capital towards dividend, with a keen eye on the total risk-adjusted capital ratio.
That about right, Michael?
Michael Lacapria
Sounds right to me.
Alan Strauss
Yeah. Thanks.
Andrew Sagliocca
Thank you.
Alan Strauss
That's it.
Operator
There are no further questions at this time. I will now turn the call back to Andrew for closing remarks.
Andrew Sagliocca
Great, Kenneth. Thank you.
I want to thank everybody on the call. I know that we have some investors and analysts, obviously, board members, managers, employees.
I hope our friends and our new business partners at Signature in Chicago were able to join us. I want to congratulate everybody: our board, our management team, our employee base.
This was a very heavy lift, as you could imagine. The bank prior to the acquisition was about a $2.7 billion bank.
Again, effectively not only doubled the size of assets and loans and deposits, but we doubled the employee base. As you're aware, Chicago is about 850 miles away from New York, there's been a lot of traveling back and forth between management group and employees to make this happen, and also plan for the system conversion scheduled at this point for April '27.
I just want to take a moment to thank all of our employees for their focus, their care, their dedication, and their diligent and hard work to get us to this point. We are very pleased with the company's combined performance, and we are very positive about our earnings expectations and performance as we look forward.
Thank you, everybody, and thank you, Kenneth.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.