Edwards Lifesciences Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
0
Operator
As a reminder, this conference is being recorded. It is now my pleasure to introduce Jeriann Sarte, Senior Vice President, Investor Relations.
Thank you. You may begin.
Jeriann Sarte
Good afternoon, and thank you for joining us. With me on today's call is our CEO, Bernard Zovighian, and our CFO, Doretta Mistras.
Also joining us for the Q&A portion of the call will be Dan Lippis, our global leader of TAVR, and Daveen Chopra, who has global responsibility for TMTT, Surgical, and IHFM. After the close of regular trading, Edwards Lifesciences released third quarter 2026 financial results.
During today's call, management will discuss the results included in the press release and accompanying financial schedules, and then use the remaining time for Q&A. Please note that management will be making forward-looking statements that are based on estimates, assumptions, and projections.
These statements speak only as of the date on which they are made, and Edwards does not undertake any obligation to update them after today. Additionally, the statements involve risks and uncertainties that could cause actual results to differ materially from those expressed or implied by the forward-looking statements.
Factors that could cause these differences can be found in today's press release and Edwards' other SEC filings, all of which are available on the company's website at edwards.com. Unless otherwise noted, our commentary on sales growth refers to underlying sales growth, which is defined in the financial results press release issued earlier today.
Reconciliations between GAAP and non-GAAP numbers mentioned during this call are also included in today's press release. Quarterly and full-year growth rates refer to continuing operations.
With that, I'll turn the call over to Bernard for his comments.
Bernard Zovighian
Thank you, Jeriann, and welcome, everyone. We delivered third quarter results that exceeded expectations, with both our businesses and regions driving strong, broad-based performance.
Even more importantly, we achieved meaningful progress on several of our most important clinical, regulatory, policy, and commercial priorities, strengthening our outlook for durable, long-term growth. The consistency of our top-tier financial performance is a reflection of our focused strategy, as well as our commitment to innovation, speed and agility, and the strength of execution by our 17,000 dedicated employees across Edwards.
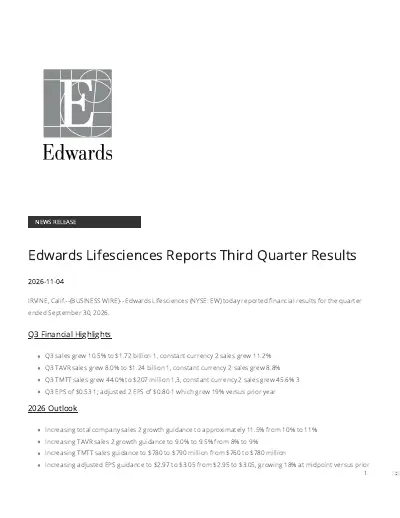
Third quarter sales of $1.72 billion grew 11.2%. This performance was driven by our structural heart portfolio, including continued strength in TAVR and growing contributions from our portfolio of TMTT therapies, with PASCAL, EVOQUE, and SAPIEN M3.
Based on our strong performance this quarter, we are raising our full-year sales growth guidance to approximately 11.5% and our adjusted EPS guidance to $2.97 to $3.05, growing 18% at the midpoint versus prior year. As I reflect on 2026 so far, I am proud of what our teams have accomplished and how we are positioning Edwards for the future.
We are clear on our strategy focusing on structural heart, a large and growing space with significant unmet patient needs. We invest early, taking a long-term view with conviction to create entirely new categories of treatment that push the boundaries of what is possible for underserved patients.
At the same time, we are moving with intention, sharpening how we are operating, embracing science and technology advancements, accelerating decision-making, and executing against an important set of priorities. Our focus continues to deliver meaningful progress across the company, underpinned by our foundational patient-focused culture.
All of this together set us apart and is why we are confident in our long-term success. We are pleased to see our strategy deliver particularly impressive progress over the last few months, with five meaningful therapy approvals that offer new options to physicians.
In addition, we continue to elevate the clinical evidence standard for structural heart care, including the release of two new practice-changing datasets. In TAVR, the SAPIEN platform continues to set the benchmark for valve performance and durability, supported by ongoing innovation and world-class clinical evidence.
The PROGRESS trial marks a turning point in our collective understanding and management of moderate AS. Taken altogether, the PROGRESS trial results, EARLY TAVR clinical outcomes, and long-term cost-effectiveness data, and PARTNER 3 seven-year durability data are advancing the understanding of aortic stenosis as a disease and reinforcing the differentiation of TAVR with the SAPIEN platform as a compelling treatment strategy for severe AS.
As a result, this changes how the clinical community looks at the disease: how to evaluate, who to treat, when to treat, and ultimately, this underscores the value of proactive disease management with the SAPIEN platform. In addition, the modernization of the NCD represents an important step toward expanded access to TAVR for timely, high-quality care for all AS patients.
In TMTT, our years of pioneering development and strategic investment have resulted in a portfolio of therapies allowing our teams a unique opportunity to collaborate with physicians to personalize care for the clinically diverse patients suffering from mitral and tricuspid diseases. With the recent US approvals of PASCAL for tricuspid patients and next-generation Capture Clarity for mitral patients, we are further strengthening the portfolio of treatment options.
In Surgical, we continue to see strong adoption of our RESILIA portfolio of therapies, and we continue to introduce new therapies to address unmet patient needs, including ARTUS for congenital patients and ECLIPSE for surgical left atrial appendage occlusion. At the same time, we are applying our proven innovation playbook to new areas of significant unmet need within structural heart, including structural heart failure and aortic regurgitation, creating additional opportunities for long-term growth.
When I reflect on all of this, I am proud of our impact. When Edwards leads, everyone benefits: physicians, providers, payers, and most importantly, patients, who enjoy a restored quality of life and live longer.
Now let's dive a little deeper into the recent presentation at TCT. Physicians presented compelling new evidence on SAPIEN, PASCAL, EVOQUE, and SAPIEN M3 that deepens the clinical community's understanding of these therapies and underscores their significant potential to transform care for AS, mitral, and tricuspid patients.
The breadth and quality of this evidence reflects the strength of our innovation strategy and our commitment to setting the benchmark for clinical evidence in structural heart disease. Putting all of this in perspective, these advancements represent meaningful, multiyear opportunities that we expect to build over time, and which underpin our long-term growth target of approximately 10% average annual sales growth, alongside leveraged EPS growth.
Now I will provide more detail about the performance of our product groups. TAVR third quarter global sales of $1.2 billion were stronger than expected and increased 8.8% over the prior year.
Edwards' growth rates were similar in the US and outside of the US. Globally, procedural growth benefited from a heightened focus on TAVR and data supporting proactive disease management of severe AS.
Exiting Q3, we saw encouraging signs of procedure growth. After several quarters of modest share gains, we are pleased with how our competitive position, supported by our differentiated SAPIEN platform, has contributed to year-to-date TAVR performance.
Average selling prices were stable globally. At TCT, results from the PROGRESS trial were presented and published in The New England Journal of Medicine, marking a turning point in the management of moderate AS.
The remarkable performance and unparalleled safety of the SAPIEN platform, coupled with the superior trial results, validate TAVR as a treatment strategy for moderate AS patients with at-risk features. These findings challenge the longstanding assumption that moderate AS patients can be managed by the current practice of passive surveillance and encourages the clinical community to embrace earlier referral to a valve clinic for comprehensive testing and advanced management for optimal outcomes.
PROGRESS builds on Edwards' decades-long commitment to generating rigorous clinical evidence that advances the understanding of the serious impact and unpredictable progression of aortic stenosis, and continues to validate the patient benefit of proactive disease management. Also presented at TCT was ACTIVATE, a large, real-world, investigator-initiated study of more than 53,000 patients with AS who were identified within an advanced healthcare system using EHR.
The study demonstrated that patients with moderate AS outnumber those with severe AS nearly 2 to 1. Additionally, among the patients with moderate AS, approximately 80% had at least one at-risk feature, which was associated with an increased risk of death and hospitalization.
The evidence from PROGRESS and ACTIVATE suggests that the in-system and out-of-system moderate opportunity is at least as large as the severe AS opportunity. We will continue to share our perspectives on the moderate patient opportunity as the evidence continues to grow and the clinical community gains experience managing these patients over time.
Additionally, new long-term economic data from the EARLY TAVR trial reinforced the value of proactive disease management. In patients with asymptomatic severe aortic stenosis, Edwards TAVR delivered exceptional economic value compared with clinical surveillance and remained highly cost-effective even after accounting for potential future valve reintervention.
Notably, these results were achieved in a highly controlled trial setting, where patients benefited from optimal care and treatment, with a median time to intervention of just 32 days, compared with approximately 157 days observed in real-world practice. Taken together, the practice-changing EARLY TAVR and PROGRESS studies deepen our understanding of aortic stenosis and continue to validate the patient benefit of proactive disease management.
This evidence is now clear that intervening before the disease progresses avoids significant health decline and serious cardiovascular events, such as heart failure-related hospitalization and death. Let me now turn to some commentary on US TAVR.
In Q3, procedure growth continued to benefit from a heightened focus on TAVR therapy as the clinical community further incorporates into practice the meaningful evidence supporting proactive disease management. Edwards' competitive position in the US was stable sequentially and increased modestly year-over-year, enabled by strong adoption of our differentiated SAPIEN 3 Ultra RESILIA.
During the quarter, CMS released the final updated NCD for TAVR. We are pleased that the updated policy represents an important step toward improving and expanding timely, high-quality access to care while reinforcing the value of a multidisciplinary heart team.
We believe there are four important elements within the NCD. First, the policy will enable greater flexibility for the heart team at every step of the patient journey, from evaluation to treatment.
Second, it will support appropriate site expansion over time through updated hospital procedure volume requirements. Third, the NCD will expand coverage to asymptomatic patients.
Finally, the policy provides a pathway to coverage for Medicare Administrative Contractors, or MACs, to address reasonable and necessary coverage when future TAVR indications are approved. Taken together, these changes establish a strong foundation that will expand timely, high-quality access to care, support the continued evolution of TAVR, and ensure that more patients with aortic stenosis will benefit from treatment for many years to come.
Outside of the US, we continue to see strong adoption of our SAPIEN technology. In Europe, updated ESC and EACTS guidelines are helping shape clinical discussion around earlier intervention and proactive disease management, further reinforcing the role of TAVR across a broader patient population.
Edwards' competitive position increased modestly year-over-year in Europe. In Japan, we continue to be encouraged by the growth and the continued adoption of SAPIEN 3 Ultra RESILIA.
Also in Japan, we secured new and dedicated reimbursement for SAPIEN 3 Ultra RESILIA, which recognizes the value of our innovation and helped contribute to Japan's strong performance in the quarter. In summary, we are pleased with our TAVR performance in the quarter, which was a reflection of procedure growth and competitive position.
Given our better than expected third quarter performance, we are raising our full-year TAVR guidance to 9% to 9.5%. In the fourth quarter and going forward, we are assuming that growth will be mainly driven by continued increases in procedure volume and less by share gains.
Putting it all together, the robust evidence and emerging indications validating the patient benefits of proactive disease management for AS, and with the opportunity that comes from the modernized NCD in the US, we have reinforced confidence in the durable mid- to high single-digit growth of our SAPIEN platform over the long term. Now let me turn to TMTT.
Our differentiated portfolio of mitral and tricuspid repair and replacement therapies drove third quarter sales of $207 million, an increase of 45.6% year-over-year. Globally, mitral and tricuspid procedure volumes continue to grow in the double digits.
The value of our TMTT portfolio is evident as our mitral and tricuspid therapies advance along their adoption curves, allowing our teams to collaborate with physicians to personalize care for each patient's unique needs. With the recent US approval of PASCAL Precision for tricuspid regurgitation, our full portfolio of repair and replacement technologies for the mitral and tricuspid valves is now available in the US, as it has been for physicians in Europe.
Growth was strong globally. As the US scales, it is becoming a more significant driver.
New clinical data across the entire portfolio continues to strengthen the growing body of meaningful evidence supporting long-term adoption of our TMTT therapies. This was evident at TCT, where seven clinical presentations featured compelling new data from across the portfolio.
Turning to an update on each of our TMTT therapy areas, starting with PASCAL: adoption continues to strengthen, supported by the differentiated design and clinical outcome of the platform in our portfolio approach. The CLASP II TR pivotal trial presented at TCT met its six-month primary endpoint, demonstrating the superiority of the PASCAL system plus optimal medical therapy compared with OMT alone in patients with severe or greater TR.
This was driven by significant improvements in health status for those receiving PASCAL. During the quarter, PASCAL Ace with Capture Clarity received US approval for use in DMR TEER procedures, and a major rollout of the technology is underway.
PASCAL Ace with Capture Clarity is the first FDA-approved TEER device to include novel indicators that provide confirmation of a challenging step of leaflet grasping. In October, PASCAL Precision for tricuspid regurgitation received approval in the US, expanding access to this important therapy for patients.
Early clinician feedback is very positive on both PASCAL Capture Clarity and PASCAL Tricuspid. Clinicians value the simplification of device placement with the new feature of Capture Clarity.
With PASCAL Tricuspid, physicians are recognizing that unique features, including device elongation, are particularly beneficial for patients with complex tricuspid anatomy. Our focus on continued innovation with PASCAL represents a positive step forward for patients in need for mitral and tricuspid repair.
Moving to tricuspid replacement: EVOQUE delivered another strong quarter of growth. As physicians gain experience with EVOQUE, they are more consistently achieving mild or less residual TR, a result that is increasingly linked to better outcomes for patients.
We also recently received US approval and CE Mark for EVOQUE for transjugular access, enabling patients with complex femoral access to benefit from the EVOQUE procedure. In addition, at TCT, results from EVOQUE patients in the TVT Registry with CMS linkage demonstrated that the real-world clinical outcomes of patients with more complex disease replicate those observed in the TRISCEND II clinical trial.
In more than 1,100 patients who were followed through one year, EVOQUE delivered sustained elimination of TR and quality of life improvements, excellent valve durability, and high rate of procedural success. Building upon the body of clinical evidence supporting tricuspid intervention, the Edwards-supported TRIC-HF study demonstrated statistically significant reduction in the combination endpoint of heart failure hospitalization and mortality for tricuspid intervention compared with optimal medical therapy at one year.
Together, the meaningful evidence focused on tricuspid intervention advances clinical practice by highlighting the importance of interventional therapy for TR. Moving to SAPIEN M3, we continue to see strong demand for patients who are not suitable for mitral TEER, and we are encouraged by the excellent early clinical outcomes delivered by the therapy.
Two-year results from ENCIRCLE presented recently at TCT reinforced the durability of SAPIEN M3, including sustained reduction of MR, functional improvement, and quality of life benefits. In addition, we introduced SAPIEN M3 with RESILIA in Europe this quarter.
RESILIA tissue is a key element of Edwards' innovation, extending durability for patients who receive our valves, and we plan to incorporate this advanced tissue treatment across all TMTT valve replacement therapies. In summary, based on our strong performance, we now expect full-year TMTT sales to be between $780 and $790 million.
Our full portfolio of innovative technologies is now available to patients across the US and Europe, and we are just beginning to realize the opportunity ahead. Together, PASCAL, EVOQUE, and SAPIEN M3 provide layers of durable growth that support our path to $2 billion in TMTT revenue in 2030.
In Surgical, third quarter global sales of $264 million increased 3% over the prior year, driven by continued adoption of RESILIA portfolio of surgical therapies. Our expectation of full-year mid-single digit sales growth for Surgical remains unchanged.
We are expanding the surgical portfolio with innovative technologies that address additional unmet patient needs in structural heart surgery. During the quarter, ARTUS became the first FDA-approved surgical pulmonary valve designed specifically for pediatric anatomy with the ability to expand as a child grows, potentially reducing the need for repeat open heart surgeries.
We are also advancing a major rollout of ECLIPSE, our surgical left atrial appendage technology in the US, prioritizing exceptional outcomes for patients through physician training and procedural excellence. In summary, we are pleased with the continued strength of our surgical portfolio and the progress we are making to reach new patients best treated surgically.
With that, we'll pass it over to Doretta to cover the detail of our financial results.
Doretta Mistras
Thanks, Bernard, and good afternoon, everyone. As Bernard mentioned, we are pleased with our financial performance in the quarter, including strong top-line growth and earnings leverage.
Total sales of $1.72 billion grew 11.2% year-over-year, reflecting the strength across product groups and regions. Adjusted EPS in the quarter was 80 cents.
As a result of our strong third quarter, we are increasing our full-year sales guidance for total company to approximately 11.5%, increasing TAVR to 9% to 9.5%, and increasing TMTT sales to $780 to $790 million. For the fourth quarter, we're projecting total company sales of $1.67 to $1.75 billion, with adjusted EPS of 61 to 69 cents.
This bridges to a full-year increased adjusted EPS range of $2.97 to $3.05, which, at the midpoint, represents EPS growth of 18% year-over-year. I'll now cover additional details of our Q3 results, starting with EPS.
Adjusted EPS of 80 cents in the quarter benefited from our better than expected top-line performance, as well as our planned phasing of strategic investments in R&D and SG&A throughout the year. Our GAAP EPS for the quarter was 53 cents, primarily driven by the impairment of a certain research and development asset.
A full reconciliation between our GAAP and non-GAAP measures, including adjusted EPS and other items, is included with today's release. Moving on to other elements of the P&L: for the third quarter, our adjusted gross profit margin was 78.7%, compared to 77.9% in the same period last year.
Expected impact from the scaling of newer therapies was more than offset by manufacturing efficiencies and foreign exchange. Foreign exchange benefited our third quarter gross profit margin by 50 basis points compared to the prior year.
As mentioned in Q2, we continue to expect adjusted gross profit margin to be at the lower end of our full-year 78% to 79% gross margin guidance, driven by the impacts of currency fluctuations through our hedging program. SG&A expense in the quarter was $561 million, or 32.7% of sales, compared to $515 million, or 33.1% of sales in the prior year.
This was in line with our expectations and reflects continued investment in resources to support patient access and care. R&D expense was $281 million in the third quarter, or 16.4% of sales, compared to $281 million, or 18.1% of sales in the same period last year.
This investment in innovation reflects our focus on our expanding structural heart portfolio. We expect R&D expense as a percentage of sales to be approximately 16.5% in 2026.
Third quarter adjusted operating profit margin was 30.3%. Our year-to-date operating margin benefited from strong underlying business performance, as well as the planned phasing of strategic investments in SG&A and R&D during the course of the year.
We continue to expect full-year operating margin to be at the high end of the original 28% to 29% guidance, resulting in approximately 150 basis points of constant currency operating margin expansion for the full year. This implies a fourth quarter operating margin in the mid-20s, consistent with our own expectations and with prior year phasing.
Beyond 2026, we continue to prioritize leveraged EPS growth and plan for 50 to 100 basis points of underlying operating margin expansion while continuing to invest in the business. Turning to our tax rate, we continue to expect an effective tax rate at the high end of our 16% to 19% guidance.
This reflects an expectation that side-by-side safe harbor taxation legislation alongside Pillar Two does not come into effect before the end of the year. As a reminder, our tax rate is also impacted by changes to California law permanently limiting the usage of R&D credits.
If legislation is passed before year-end related to Pillar Two, we may see a benefit to this rate. Foreign exchange rate changes in the third quarter decreased reported sales by approximately $10 million, or 70 basis points versus the prior year, which was $9 million better than our expectation.
On a constant currency basis, sales in the third quarter were near the top end of our guidance range. If foreign exchange rates hold at current levels, we estimate FX to be a fourth quarter headwind of approximately $15 million compared to the prior year.
Turning to the balance sheet, we continue to maintain a strong and flexible balance sheet, with approximately $3.1 billion in cash and cash equivalents as of September 30th, 2026. Edwards has performed share repurchases of approximately $700 million through the third quarter.
Additionally, we have approximately $1.3 billion remaining under our share repurchase authorization. Average diluted shares outstanding during the quarter were 578 million.
We continue to expect average diluted shares outstanding for 2026 to be between 575 and 580 million. The strength of our year-to-date performance across TAVR, mitral, tricuspid, surgical, and our regions gives us confidence in delivering on our increased 2026 outlook and targeting 10% longer-term sales growth on average, with EPS leverage.
With that, I'll hand it back to Bernard.
Bernard Zovighian
Thanks, Doretta. In closing, this was an important quarter for Edwards, marked by category-shaping milestones across TAVR, TMTT, and Surgical, as well as compelling clinical evidence presented at TCT that will inform and impact clinical practice.
These accomplishments reflect the strength of our strategy and the breadth of innovation across our businesses. We enter the future confident in our ability to impact even more patients and deliver strong, sustainable growth.
With that, I will turn it back over to Jeriann to facilitate Q&A.
Jeriann Sarte
Thank you, Bernard. Before I move to Q&A, I'd like to remind you about our 2026 investor conference on Friday, December 4th at the New York Stock Exchange.
We hope you'll join us as we discuss our patient-focused innovation strategy and the opportunities ahead. We're ready to take your questions now.
As a reminder, please limit the number of questions to one, plus one follow-up, to allow for broad participation. If you have additional questions, please re-enter the queue, and management will answer as many participants as possible during the remainder of the call.
Operator, we're ready to take questions.
Operator
Thank you. To ask a question, press *1 on your telephone keypad.
A confirmation tone will indicate that your line is in the question queue, and you can press *2 to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
Your first question comes from Travis Steed with Bank of America. Please state your question.
Travis Steed
Hey, congrats on a good quarter. TAVR accelerating once again in Q3.
I wanted to ask about the quote that you said exiting Q3 saw encouraging signs of procedure growth. Is this what are you seeing on the ground?
How much is this EARLY TAVR starting to play out and some of the early referrals starting to come through into better market growth rate?
Bernard Zovighian
Yes, thanks for the question, Travis. We have been talking in the last few quarters about the heightened focus on TAVR, which was driven by the evidence we brought to the clinical community, starting with SAPIEN long-term performance, EARLY TAVR, and now PROGRESS, but also the NCD.
We have been seeing that in the last few quarters. It was a leading indicator.
Now, what we believe we can say is that we have strong dynamic in the market. As a matter of fact, exiting the quarter, in the last few weeks of the quarter, we saw early indicator of positive procedure signal, which give us confidence that all of this heightened focus, all of this evidence, all of this positive evidence is having an impact on the market.
We also have seen a modest share gain in the quarter year-over-year, but it was mainly market growth.
Travis Steed
Right, that's helpful. There was also the comment I think you made, growth's going to be driven by more procedure volumes and less by share gains going forward.
Just wanted to understand that comment a bit more. Did the procedure volumes improve and share gains stabilize so the total is better going forward, or is it that you've had the benefit of share gains and that goes away?
Bernard Zovighian
No. Let me start high level, then I'm going to ask Dan to give some more details into this one.
We were very pleased, a year ago, more than a year ago about our competitive position. In the last few quarters, we gained share, and our competitive position improved.
We believe that we have reached a plateau here, but I'm going to ask Dan to explain why.
Dan Lippis
Thanks, Bernard, and hi, Travis. I think if we look back, May 2025, that's when we had the Boston Scientific exit in Europe and OUS.
Now we've annualized that now. We've had multiple quarters, more than four quarters of year-over-year benefit, but that's now fully annualized.
If you think about it relative to our other competitors in our competitive position there, we've also observed four quarters of modest share gains. If you couple all of that with the most recent quarters, the last two quarters, we're seeing sequential stability there.
This is why we're thinking that going forward, it's more about the underlying fundamentals of the market growth. It's really important to note that we feel really good about that.
The underlying signals there are really positive. We're happy with how Q3 went, and we'd expect that to continue into Q4.
Bernard Zovighian
If you look at the big picture here, this made us very confident. It is not dependent on share gain.
It is truly dependent about growing the number of patients who can get access to the best TAVR, having the best performance and best durability. We have all of the evidence to educate, to make sure physicians can treat their patient the best way possible.
We have been working hard to be where we are today. This has been the company strategy for years to bring evidence, to grow the market, to make sure that many underserved patients can have access to this best therapy.
It is why, one, we are confident, but we are also very pleased about our leadership in the space.
Operator
Thank you. Your next question comes from Larry Biegelsen with Wells Fargo.
Please state your question. Larry, are you on the line?
He dialed in a second line. Let's try that.
One moment.
Larry Biegelsen
This is Larry. Hello?
Operator
We can hear you now on this line. Go ahead, sir.
Larry Biegelsen
All right. I'm sorry about that.
Bernard, congratulations on a strong quarter here. I just wanted to ask a follow-up question on Travis's question there.
You're guiding to TAVR growth of 9% to 9.5% in 2026. You talked about positive procedure trends exiting Q3, but less share gains going forward.
Are you signaling that TAVR growth will slow next year? How should we think about the contribution from the NCD and PROGRESS next year?
I had one follow-up.
Bernard Zovighian
Yeah. I think it is a little bit too early to talk about next year, Larry.
I'm not signaling that a slowdown or whatsoever. I'm signaling confidence.
I'm signaling a difference in mix. If there is one thing we have is confidence.
We are trying to provide detail into the mix here, and which is truly aligned with our strategy that we have been talking for years.
Larry Biegelsen
If people are trying to understand, what's your expectation for the NCD and PROGRESS next year? Do you expect any benefit from those two?
I'll drop.
Bernard Zovighian
No. Thanks, Larry.
No, I understand everyone of us wants to try to update the model. We are so close to investor conference.
We are going to talk about that at investor conference. Are we going to have some impact from the NCD and from asymptomatic next year?
Yes, probably. We have an NCD, it is official, but we also know that it takes time for all of the centers to implement the new NCD.
We have a new indication with asymptomatic. We know that we might have some impact also, but it is going to be a gradual impact, progressive impact year-over-year.
It is the beauty of these two catalysts here. It is not going to be a peak and then a valley the year after.
We are going to see progressive trend year-over-year. Yes, confidence.
Yes, some impact, progressive impact. The mix is going to change a little bit, less about share, more about market.
We are going to give you more clarity in December.
Doretta Mistras
I would just add, Bernard, that one of the reasons why we provided the longer-term mid- to high single-digit expectation for TAVR over the longer term is it does incorporate a lot of these factors that we're talking about. To Bernard's point, we'll be able to provide more specificity around 2027 in a few weeks, but all of this gives us confidence in that mid- to high single-digit growth rate for TAVR over the longer term.
Bernard Zovighian
Yeah. In summary, I know what you are asking yourself.
Are we confident about 2027? Yes, we are.
Look at 2026. We are going to exit the year as a company growing about 11.5% and with EPS leverage, with multiple catalysts.
We are confident, and we are going to provide a reasonable guidance in December.
Operator
Your next question comes from Robbie Marcus with JP Morgan. Please state your question.
Robbie Marcus
Oh, great. Congrats on a good quarter.
Two for me. Just wanted to ask on Moderate.
You had great data earlier this week on Monday. How should we think about timing of submission and expected approval for that?
Then I have a follow-up.
Bernard Zovighian
Let me start, and then I will ask Dan to bring some clarity about the timing since he is very close to the action here. I would say one is yes, thanks, Robbie.
Great quarter. Very pleased about what we did across the company and for the company.
Two is PROGRESS is a big study. It's a big moment for us, pivotal moment, turning point for so many patients here.
Very excited about it. You had the chance to listen to the PIs on Monday night.
I'm going to let Dan give a little bit more clarity about what's in front of us here.
Dan Lippis
Thanks, Bernard, and hi, Robbie. Look, clearly, it's a turning point.
This data is important. It's powerful.
The indication is important. The work can't be done without it.
It's an important indication for us. It's a priority for us for sure.
We don't usually comment on exactly where we're at with indications, the conversations being had with the FDA, etc., and we won't do that. I think in a few weeks at investor conference, we'll be able to give a broader update on how we're thinking about the timing of that indication and how that impacts both how we're looking at 2027 and beyond and our longer-term thinking.
Hopefully, more to come.
Bernard Zovighian
In my mind, the big message, and I know Doretta talked about it, but I think it is important to remind everybody. A few years ago, we gave this long-term guidance for the company: about 10%, EPS leverage.
We said what we need from TAVR is about mid- to high single digit. It was a clear message.
And 2 years later, today, all of the things that we wanted to achieve to deliver that has happened. This is why, one, it is exciting.
Two, it is the result of our flawless execution. Three, we are confident.
We are confident about next year. We are confident about the next many years here.
Because all what we do here, it is changing the practice of medicine. We know that changing the practice of medicine takes time, it is progressive, we are going to benefit from it every year for many years.
Robbie Marcus
Great. Maybe a follow-up for Doretta.
You're newer to the company. I think a lot of people are still trying to learn your guidance philosophy.
The guide on second quarter implied not a whole lot of sequential growth into the second half. You put up a pretty meaningful beat, over 200 basis points on TAVR, a big TMTT beat, and total company organic sales growth beat, along with EPS, well above the implied and consensus.
I look at the fourth quarter guide here, it looks even to get to the high end of the TMTT range is step down sequentially on a dollar basis, not a whole lot of growth in TAVR. I think it'd be helpful to touch on that, and just your guidance philosophy overall as investors get used to this moving forward.
Thanks a lot.
Doretta Mistras
Great. Thanks so much for the question, Robbie, and it's very important.
I would say at a high level, our approach to guidance really remains grounded in the same principles that we've had as a company. The priority is really the ability to give you and our investors an appropriate and credible outlook.
We continue to update our outlook as we see our performance and we look at our underlying trends. Always it's grounded in that view of making sure it's appropriate, it's credible, and we're really guiding to the midpoint.
To the point as it relates to the fourth quarter, I would echo a lot of the comments that Dan made earlier. We feel good about the underlying fundamentals of the business, but we believe going forward, our growth is going to come from market versus share.
All of this is grounded in confidence to be able to deliver on what we say.
Daveen Chopra
Thank you. Maybe I'll just make one comment because it's Daveen, just to jump a little bit over on the TMTT side of things.
I'll just make one nuance comment on this of saying, with TMTT, obviously, we're in a high-growth situation, where, for us, we think a lot about the year-over-year portion of TMTT versus the quarter-over-quarter. It's a better indicator of the health of the businesses because catalysts can happen anytime during the year.
When you're in a high-growth business like TMTT, it kind of throws you off a little bit. If you pull back up and you say, 'Hey, man, how are we looking year-over-year, increasing sequential dollar growth?'
That's at least how we think about TMTT as we move forward within the context of what Doretta said.
Bernard Zovighian
I think closing on the topic, it is an important topic. We pay attention at guidance all together as a team, as a leadership team.
I will add only one thing. I want to make sure that we are delivering on our commitment, always.
I want you to have trust and confidence. Good question, Robbie.
Thanks.
Operator
Your next question comes from Matthew Taylor with Jefferies. Please state your question.
Matthew Taylor
Hi, good afternoon, and thanks for taking our question. This is Matthew on for Matt.
I just wanted to start and ask, as you expand into asymptomatic and in the future expand into moderate, do you expect to kind of maintain a similar share to these historical indications, or do you see an opportunity to take even more competitive share? Thanks.
I have one follow-up.
Bernard Zovighian
Thank you. Maybe I can start at the high level, and then Dan again can provide some additional comments here.
What we have said over the years is that, over time, we can expect us losing slightly some share. More competition is coming, and we all know that.
If you ask me in the next 10 years, a slight loss of share, but largely offset by what we are doing to grow the market, what we are doing to have more indication, what we are doing to make sure the penetration of TAVR is also improving. That's the way to think about at the highest level.
We have been saying that for a long time, and it is going to be the same, again, largely offset. Dan, go for it.
Dan Lippis
Yeah. I think if we look where we are now and where we have been historically, we've always had differentiation on indication.
We have always had differentiation on durability. I think that these things are interesting, but not necessarily what drives market position.
It's a complex combination of lots of things that go into your market position, as you might well know, including your premium that you might offer and all other things. What I would say, though, is the indications are super important, right, especially for the indications like asymptomatic and moderate, because these indications don't have a predicate for treatment.
These are new indications, right? For the last 15 years, whether it be high-risk indication or intermediate-risk indication or low-risk indication, these were all indications where the predicate was surgery.
You've got a transcatheter option that is being considered as a reasonable or better alternative to a predicate. Now we're getting into indications that require market development, and those indications are important to put muscle behind, to build markets, to educate physicians to understand the data better, to allow us to treat patients who are underserved.
I see that more of an opportunity to expand the market and to continue to build on positive underlying fundamentals, but probably less of a competitive differentiation I guess lever in the short- or medium- or even long-term.
Bernard Zovighian
Let me add something purely from a strategic standpoint. We have been working hard to be where we are.
Asymptomatic indication, now the PROGRESS data, a new NCD in the US, and if you think about strategy, if you think about focus, the team focus, this is where we are going to spend our time. This is where we are going to have the resource allocation to make sure we are going to educate, train, bring awareness, drive the adoption.
Having said that, obviously, we're very proud about the SAPIEN: best valve performance, by far, there is no one competing with it, and best durability, there is no one competing with it. That's truly basically our 10-year strategy coming to a reality this quarter and this year.
This give us big confidence, for sure.
Matthew Taylor
Great. Thank you.
Maybe now that you've had some time to digest the PROGRESS results and the initial physician feedback, what do you think is most either underappreciated or misunderstood about either the opportunity with Moderate or the result itself? Thanks.
Bernard Zovighian
Dan, you want to take it?
Dan Lippis
Yeah. I think, first of all, the feedback from physicians who are every day dealing with structural heart patients and running valve clinics, I think from their perspective, this is very positive results and results that they would tell you after the fact that, 'Oh, that was expected, and congratulations, and they're amazing.'
One of the reasons why it's super positive for them is because this is a patient population whose echocardiographic severity doesn't match their clinical severity or their clinical prognosis. Without the data and without knowing, it's hard to change guidelines, and it's hard to make treatment decisions.
Now that data exists, and there is a clear understanding of who would benefit with an Edwards TAVR, and the performance of the TAVR in the arm was so positive. This is reassuring and generates confidence for both physician and patient.
I think what's underappreciated is further upstream, right? Because now it's about not only recognizing the moderate patient, but how to recognize the at-risk features within this moderate patient population.
That's not easily done in a community setting, right? Now I think what is being digested and underappreciated is there's a difference between passive clinical surveillance in the normal setting of patient care, whether that be in primary care physician or even general cardiology settings, to advanced surveillance, whereby you have multiple sources of information and you can go into further detail to make the correct assessment about what that relative risk is for each individual patient.
I think this is what is being digested now. I think that that's something that's going to advance patient care over time.
Operator
Your next question comes from Vijay Kumar with Evercore ISI. Please state your question.
Vijay Kumar
Hi, Bernard. Good evening, and thank you for taking my question.
I guess my first one was on PROGRESS, right? Next year you'll have FDA approval.
Post approval, Edwards will be in a pretty unique position, right? You'll have the broadest label in TAVR covering severe symptomatic, asymptomatic, and moderate AS.
How will having that breadth of label, right, change your contracting process? Why shouldn't Edwards continue to gain share for the foreseeable future?
Bernard Zovighian
I like your question, and I like how excited you are about it, and we are, too. Indeed, you are right for asymptomatic, because we got the indication already, and we have been the only company running this kind of high-level evidence disease study to be able to have this kind of indication.
On PROGRESS, we don't have yet the indication for moderate, but we might be in the similar situation later next year. Too early to speculate on this one yet.
We feel good about it. I think, again, I understand your question, but we are clearly focusing, like we have been doing, on making sure TAVR is better adopted.
If you think about where we are today for severe symptomatic patients, 15 years later, all the data we are having, the penetration in the US is about 15%, 1-5. We have a lot to do here.
Then you add asymptomatic, then potentially moderate. Yes, there is a lot of work, there is a lot of opportunity, and this is where we are going to spend our time here.
I know that many people are asking us about share. We are very pleased also about the differentiated feature of SAPIEN, and because of that and the durability, we gain share.
It is not the way we are going to be focusing, Vijay. Maybe things will happen on share, but we are not going to push for it.
Then I'm going to ask Dan, who is obviously the one right now putting all the thinking behind the plan for '27, '28, '29, '30, because this is what we have in front of us: five four, five, six amazing years. Dan, you want to add anything here?
Dan Lippis
It's a similar question to the previous question on this topic. I think it's important to recognize that as we go further upstream and go with these indications and earlier in the disease pathway, the concept of lifetime management does come into play a lot.
Now we're not necessarily talking about always younger patients, right? Even with the PROGRESS trial, these were 78-year-olds.
Even in asymptomatic EARLY TAVR patients, they're not super young. The concept is we are going earlier in the disease pathway, and lifetime management does make a big difference.
I think the conversation around share is more about trust in the platform, whether it be for the acute result or the durable result, more than how many indications you have. It all gives us a lot of confidence.
I think we have an enormous amount of confidence in our platform. We're very, very pleased with our acute performance, as well as our longer-term data, which continues to differentiate.
We feel pretty good about our relative competitive position. The indications themselves, I'll go back to it, these new indications, asymptomatic and moderate, pending, gives us the opportunity to put our muscle and our effort behind educating the market, developing the therapy, developing the market, and creating access for patients who are underserved.
This is also very, very important from our durable strategy of growth.
Vijay Kumar
Understood. Maybe one quick follow-up on do you see moderate AS as expanding the TAM, or is this more of because AS is progressive, are we just pulling forward patients?
How do you see it?
Dan Lippis
Thanks for that question. I've been getting that one a bit, and you can give yourself a bit of a headache on it.
The way that I look at it is very, very simply is you can either look at this through the lens of the data and the contemporary literature, which says that the moderate patient population is 1 to 2 times bigger than the severe population, or you can look at it through the lens that the severe population is 2 to 3 times bigger than what we thought it was. Either way, it's the same math.
We look at it as a sizable number of patients who have unmet clinical needs and are largely underserved today. However you look at it, it's a lot of opportunity.
Operator
Thank you. We have time for one more question.
That question comes from Pito Chickering with Deutsche Bank. Please state your question.
Pito Chickering
Hey, good afternoon, guys. Thanks for fitting me in here.
Can I ask a bit more on Europe? If I look at the constant currency growth in the first half of the year, about 13.3%, and 3Q is about 8.2%.
Should we think about the first half of the year as market share gains plus the market growth, and going forward, Europe's going to be more of high single-digit growth now that there's no more market share gains?
Bernard Zovighian
I am not sure about the number you are quoting here, Pito. What I can tell you is that in the quarter, between US and Europe, we don't see any difference.
It was about the same. In Europe, the only thing that they have that we don't have in the US is they have a new guidelines that happened a few quarters ago.
We have seen a heightened focus also in Europe. We have seen the same, some modest share gain year-over-year.
I'm not sure I can give you detail here. Maybe I'm going to ask Dan here.
Dan?
Dan Lippis
Yeah. If the question is regarding front-half growth, back-half growth, whether it's Europe or one of the things that we at least from a TAVR perspective, and we have to recognize that we had a highly unusual seasonality last year over the summer.
We saw more seasonality this year, wasn't as expected, it was slightly better than expected. Interestingly, over the last 3 years, we've seen three different types of seasonality over the summer.
The front-half, back-half growth, as we've been saying all along, we knew that it was going to be stronger in the front half than the back half because of those comps, and there's other factors at play here as well, which you've noted.
Pito Chickering
Fair enough. Getting the early feedback from docs have been using TriClip, and how willing they are to try PASCAL for TR?
I guess how is the training backlog looking there? Looking at the new 4D ICE catheters that can speed up these procedures significantly in the CLASP II trial, do you think that's going to act as an inflection point for you guys in the near term?
Daveen Chopra
Hey, thanks, Pito. This is Daveen.
I'll first start by saying, obviously, with the addition of PASCAL Tricuspid, we're excited in the US that we've now completed our portfolio of both repair and replacement technologies for each the mitral and tricuspid. Now, specifically in the tricuspid, having both repair and replacement, I think we can really partner with physicians to personalize the therapy for the patient and get the right technology for the unique anatomy and clinical situations for each patient.
We obviously just got PASCAL recently approved, not that long in the US, though we had been doing clinical trials, obviously, in the US for a longer period of time. Basically, what we're seeing is that people continue to be excited about the technology.
We've had this technology in Europe for quite a few years with quite a bit of usage. We see that there's certain features that PASCAL has: the ability to elongate in the dense chordae of the tricuspid valve that make it potentially really beneficial.
I think we also saw in the CLASP II TR data, the randomized dataset that we just saw, that PASCAL performed very well with high TR reduction, great improvement in health status, and obviously a very safe procedure. I think so far I'd say is that, yes, physicians who have used it recently commercially, or previously in clinical trial settings, are believers in the technology.
They enjoy its differentiated features, and they really think it's a complementary technology to EVOQUE to really treat their tricuspid patients with the best possible solution.
Operator
Thank you. I will now turn the call over to Bernard Zovighian for closing remarks.
Bernard Zovighian
Thank you, everyone. Clearly, we had a great quarter.
Also, we are on track to have a phenomenal year. We increased the guidance for the company to be about 11.5%.
This, in my mind, represent top-tier performance in medtech. In addition of the financial aspect, we achieved so many milestones, clinical, regulatory, commercial milestones, that put us in a position to having this kind of sustainable top-tier performance.
Again, we are very confident about the years to come. Thanks for your continued interest in Edwards.
Doretta, Jeriann, and I welcome any additional questions by telephone. Have a great day, everyone.
Thank you.
Operator
Thank you. This concludes today's conference.
You may now disconnect.