First Business Financial Services, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 30, 2026
Operator
Good morning. Welcome to the First Business Financial Services Third Quarter 2026 Earnings Conference Call.
After today's presentation, there will be an opportunity to ask questions. If you would like to ask a question, please press *1 to raise your hand.
Please note, this event is being recorded, and today's comments may contain forward-looking statements that are subject to risks and uncertainties. Actual results may differ materially from those discussed.
Please refer to the company's earnings release, investor presentation, and SEC filings for additional information, including risk factors and reconciliations of any non-GAAP financial measures. I would now like to turn the conference over to First Business Financial Services, Inc., President and CEO Dave Seiler.
Please go ahead.
Dave Seiler
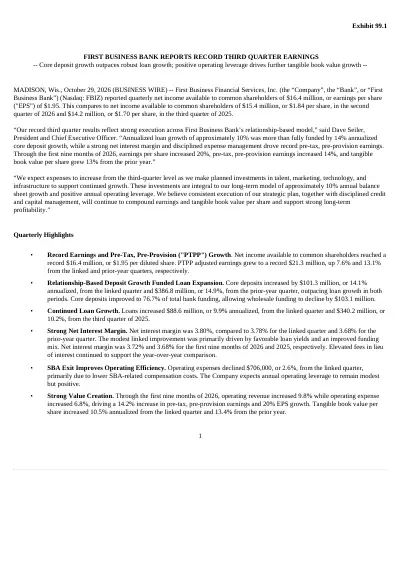
Thank you, and good morning, everyone. We appreciate you joining us today, and I'm pleased to report an outstanding third quarter of 2026 for First Business Bank.
We produced record pre-tax, pre-provision and bottom-line earnings that reflect our consistent execution against our long-term strategic plan. Our earnings per share grew 6% compared to $1.84 in the second quarter, or 15% when you take out the 14 cents of net one-time benefits last quarter.
Earnings per share were also up 15% year-over-year. On a year-to-date basis, EPS grew 20% over earnings for the first nine months of 2025.
These outcomes were driven by strong operating fundamentals as reflected in pre-tax, pre-provision earnings that grew 13% year-over-year and 14% on a year-to-date basis. This record performance and double-digit growth shows the compounding earnings power our team has produced through high-quality, well-priced loan growth that is predominantly funded by relationship-sourced core deposits.
For the third quarter, total loans were up 10% annualized, marking our 20th consecutive quarter of loan growth. Core deposits were up 14% annualized, outpacing loan growth and further strengthening our funding profile.
Tangible book value per share grew 13% year-over-year and 13% on a compound annual basis over the past five years, reflecting the consistent value creation that is central to our long-term strategic plan. These results reflect a consistent theme: we are a focused business bank executing at a high level, growing the right way, and building long-term shareholder value.
Our five-year strategic plan is our operating manual and our North Star. Our current plan runs through 2028, last quarter represented the halfway point of our plan period.
You can reference slide 5 in the earnings supplement, which shows our progress against the plan's key metrics that define success for First Business Bank over the long term. On revenue growth, we're tracking at 10% year-to-date, in line with our long-term annual target of 10% or better.
This is despite a modest fee income headwind related to our exit from our out-of-footprint SBA business last quarter. Other areas of fee income have grown meaningfully, and our strong net interest margin and balance sheet growth have supported 11% growth in year-to-date net interest income.
On the efficiency ratio, our outstanding year-to-date result of 57.87% was helped by Q3 coming in at an impressive 55.12%, which Brian will cover. These results include some benefit from Q3's favorable expense timing and robust net interest margin, but more importantly, they demonstrate the compounding benefit of positive operating leverage: revenue growing faster than expenses quarter after quarter, yielding meaningful efficiency gains.
We do not manage to a single quarter's efficiency ratio, and we expect to see this metric tick up in the short term as we invest for profitable and scalable growth. Our priority is to operate with modest positive operating leverage on an annual basis.
If we do that right, as we have historically, the efficiency ratio continues to improve over time. On core deposits to total funding, we ended the quarter at 76.7%, above our long-term target of greater than 75% and meaningfully improved from the 74% we reported at midyear.
This reflects a favorable mix shift, which included substantial growth in non-interest-bearing deposits in the third quarter. While some of this increase was temporary in nature, the overall improvement in funding mix reflects the successful execution of our treasury management strategy.
Our year-to-date return on average tangible common equity of 16% is ahead of target. As pre-tax, pre-provision earnings continue to compound and our balance sheet scales, our internal capital generation grows as well.
You can see this in the tangible book value growth line. We will prudently deploy this capital to ensure we grow shareholder value in tandem.
You saw in our release that we executed our buyback program this quarter. We'll continue to repurchase shares under the plan as it makes sense given our stock price and other capital priorities over time.
We are on target or ahead of target across every major dimension of our strategic plan, and we're doing it the right way: through relationship-driven growth, a funding profile that continues to improve, disciplined expense management, and prudent capital allocation. Turning to production, our 10% annualized loan growth reflects true new business production across our markets and niche C&I lending businesses during the quarter.
CRE loans were the primary source this quarter and were up approximately $77 million, or 14% annualized, from the second quarter. Our South Central and Southeast Wisconsin markets showed particular strength.
These are markets where we have deep relationship infrastructure and experienced teams. The production we're seeing there is a direct reflection of the investments we've made in banker talent over the past several years.
It's also a model for the growth we believe we can achieve over time in our other, smaller markets. We also saw solid contributions from our higher-yielding niche C&I lending businesses.
For example, floor plan lending added $13 million of new loan outstandings during the quarter, up 9% from the second quarter. Our new originations have been more than sufficient to absorb the industry headwind of elevated payoffs and still deliver on our 10% loan growth target.
I'll point out that year-over-year loan growth was also 10%, reflecting consistent relationship-driven production across our bank markets and specialty lending businesses. Our loan pipelines have moderated somewhat heading into the fourth quarter, primarily reflecting the timing of client activity.
That said, our longer-term growth outlook remains strong, and we continue to target approximately 10% annual loan growth. We remain confident in achieving that level of growth for 2026 and 2027.
On the funding side, deposit growth in the third quarter was outstanding and continued to reflect the underlying strength of our relationship model. Core deposits grew $101 million during the quarter, representing 14% annualized linked-quarter growth and marking the fourth consecutive quarter of growth exceeding $80 million.
This outpaced loan growth for the third quarter and followed a robust first half of 2026. Non-interest-bearing deposits were notably strong, up $57 million from June 30th.
While a portion of these balances may be temporary, treasury management fees provide another measure of underlying growth in new deposit relationships. These fees, which are included in service charges on deposits, increased 15.9% during the first nine months of 2026 compared with the prior-year period, providing further evidence of strong relationship growth.
Winning the primary operating account is competitive work, and we're pleased with the outcomes our bankers are earning across our markets. Looking ahead, we expect core deposit growth to remain healthy through the remainder of 2026 and into 2027.
Turning to asset quality, nonperforming assets increased $2.2 million during the quarter. The primary driver was an additional $5.7 million nonaccrual multifamily loan tied to a previously disclosed relationship in Southeast Wisconsin.
In total, that relationship had $22.7 million in nonperforming loans and $3.3 million in performing loans as of September 30th. The broader portfolio remains stable, and we are not seeing systemic stress across any particular industry or geography.
I'd characterize overall asset quality as stable. Our year-to-date net charge-offs remain well controlled, and allowance for credit losses stood at 1.06% of total loans at September 30th, which we believe is appropriately calibrated to the risk profile of the portfolio.
With respect to our two largest nonperforming relationships, both are actively being worked through, but we do not expect resolution on either of these in 2026. The foreclosure process on the land parcels of our $22.7 million nonperforming relationship in Southeast Wisconsin has been extended from Q4 of this year into Q1 of 2027.
Our $6 million asset-based lending loan continues through the legal process. The court date for resolution of this loan has also been extended into Q1 of 2027.
We continue to believe that we will have full collection of that loan. Finally, I'll reiterate our commitment to our four key objectives: prioritizing high-quality relationship-based growth, diversifying our revenue streams, maintaining long-term positive operating leverage, and preserving a culture that attracts and keeps the highest-quality talent.
We believe consistent execution of these growth strategies will continue to support strong shareholder returns. Now I'll hand it off to Brian.
Brian Spielmann
Thanks, Dave. Good morning, everyone.
Our net interest margin came in at 3.80%, up two basis points from the second quarter and up 12 basis points from 3.68% in last year's third quarter. You can see a breakdown of this on slide 8 of our earnings supplement.
The linked-quarter improvement reflected a stronger contribution from loan yields, apart from fees in lieu of interest, along with a more favorable funding mix as strong core deposit growth reduced our reliance on wholesale funding. These benefits more than offset a lower contribution from loan fees.
Fees in lieu of interest, primarily prepayment fees and asset-based lending fees, declined $468,000 from the second quarter to $2.8 million. Even with that decline, they remained above historical averages and contributed 31 basis points to our third quarter margin.
Together, balance sheet growth and margin expansion supported a $4.2 million, or 12%, increase in net interest income from last year's third quarter. This reflects the compounding benefit of balance sheet growth combined with disciplined pricing and an improved funding profile.
Looking ahead, we expect the fourth quarter NIM to decline from the third quarter level of 3.80%, primarily reflecting a more normalized prepayment fee contribution and modest upward pressure on funding costs as certain deposit relationships reprice and we compete for new business. That said, we expect NIM to remain comfortably above our long-term target range of 3.60% to 3.65% for the next few quarters.
Longer term, our branch-lite business banking model gives us flexibility to compete for deposit relationships while maintaining attractive overall profitability. We intend to use that flexibility to fund our annual loan growth goal of approximately 10%.
As elevated loan fees normalize and we continue to compete for relationship deposits, we expect some moderation in margin over time. We therefore continue to view 3.60% to 3.65% as an appropriate long-term NIM target range.
Over the longer term, we are generally interest rate neutral. In the near term, however, that neutrality depends on our ability to manage deposit betas amid heightened competition.
Turning to fee income, we saw a modest decline from the second quarter. As a reminder, prior periods included revenue from the nationwide SBA lending business we exited in the second quarter.
The second quarter also included unusually elevated income from a limited partnership investment totaling $729,000. Swap fee income increased $393,000, reflecting fluctuations in the interest rate environment and deal timing.
Private wealth fees declined $82,000 from the second quarter, reflecting the absence of $247,000 in seasonal tax processing fees recognized last quarter. New money growth remained strong at $80.6 million.
Limited partnership investment income was lower this quarter, reflecting normal variability in the timing and amount of realized and unrealized gains. We continue to expand and invest in our diversified fee income sources, including private wealth, treasury management, and SBIC limited partnership investments.
Private wealth continues to be the standout contributor. Its year-to-date fee income increased 13%, and the business now represents approximately half of our quarterly fee income.
That growth was consistent with an 11% year-to-date increase in assets under management and administration, which reached approximately $4.2 billion at quarter-end. Private wealth provides capital-light, recurring revenue that grows alongside our clients' wealth and benefits from its increasing integration with our commercial banking relationships.
We view private wealth as one of the most durable and differentiated growth drivers in our fee income portfolio. As our commercial relationships deepen and our clients' financial needs become more complex, we see meaningful opportunities to expand those relationships into private wealth.
We also expect limited partnership investment income to grow over time as our SBIC portfolio matures, although the timing and amount of quarterly income will remain variable. Overall, our fee income mix is more recurring, relationship-driven, and diversified than it was several years ago, giving us confidence in its ability to support sustainable revenue growth.
Turning to expenses, total expenses decreased $1.7 million from the second quarter. The decrease included a $381,000 SBA recourse benefit recorded as a reduction of expense and approximately $250,000 of lower tax credit investment impairment expense.
Excluding those items, expenses decreased approximately $1.1 million, or 4%, primarily reflecting a full quarter of lower compensation expense following the reduction in FTEs associated with our exit from nationwide SBA lending. The decline in compensation expense also reflects the absence of approximately $405,000 of severance expense recognized in the second quarter.
We also benefited from favorable expense timing, as some planned spending shifted into the fourth quarter. We therefore expect expenses to increase next quarter.
That increase will also reflect planned investments in marketing, selective banker hiring, and technology, all intended to expand our capacity for future growth. Some of those initiatives are launching in the fourth quarter and will build during 2027.
At the same time, we remain disciplined in managing expenses. Our strategic plan targets approximately 10% annual revenue growth, with expenses growing at a modestly slower pace to deliver positive operating leverage on an annual basis.
On taxes, our 14.8% effective tax rate for the third quarter was within our normalized operating range. That compares to 7.2% in the second quarter, which included a $1.5 million benefit from the reversal of a deferred tax asset valuation allowance.
Including that second quarter benefit, we expect our effective tax rate for full-year 2026 to be between 13% and 15%. Looking ahead, we currently expect a normalized effective tax rate of approximately 15% to 17%, reflecting our business mix, tax credit investments, and tax-advantaged income from our investment portfolio.
Our tax credit investments support the communities we serve while contributing to stronger after-tax returns. For the 12 months ended June 30th, our adjusted effective tax rate was approximately 16.7%, compared with a peer median of 22.3%.
While the benefit varies from quarter to quarter, our tax strategy has consistently strengthened after-tax returns and supported our return on average tangible common equity. Turning to capital, we ended the third quarter with a strong capital position and continued to generate capital through earnings.
We remain disciplined in deploying that capital to support long-term growth and shareholder value. As shown on slide 15 of the earnings supplement, our CET1 ratio was 9.65% at September 30th, compared with our internal target of 9.5%.
Our total capital ratio was 12.25%, also above our internal target of 12%. Our first priority for capital remains reinvesting in the franchise by funding attractive loan growth and supporting broader organic growth.
We believe this is the most effective way to compound earnings and create long-term shareholder value. When our capital generation exceeds the needs of the business, we also have the flexibility to return capital to shareholders through dividends and share repurchases.
We view share repurchases as an attractive use of capital when our stock trades below our assessment of its long-term value, and when repurchases compare favorably with other capital deployment opportunities. During the third quarter, we repurchased 12,000 shares for approximately $835,000 at an average price of $69.55 per share.
We repurchased another 29,058 shares from October 1st through October 23rd. In total, we've repurchased 41,058 shares for approximately $2.9 million at an average price of $69.70 per share over that period.
We will continue to evaluate capital deployment opportunities based on their relative risk-adjusted returns, while maintaining capital levels to support our growth plans and provide appropriate flexibility across economic conditions. Now, I'll hand it back over to Dave.
Dave Seiler
Thanks, Brian. This was an outstanding quarter.
Our strong balance sheet growth and efficient execution combined to produce record earnings, outstanding profitability, and continued tangible book value expansion. We focus on controlling the controllable, and today that means driving high-quality loan and deposit growth, adding talent opportunistically, diversifying our revenue sources, investing in technology, and protecting the strong First Business Bank culture that drives our success.
We have a strong outlook for the remainder of 2026 and 2027, and we look forward to updating you on our progress. Thank you for taking the time to join us today.
We're happy to take your questions now.
Operator
We will now begin the question-and-answer session. If you would like to ask a question, please press *1 to raise your hand.
To withdraw your question, press *1 again. We ask that you pick up your handset when asking a question to allow for optimum sound quality.
If you are muted locally, please remember to unmute your device. Please stand by while we compile the Q&A roster.
Your first question comes from the line of Damon DelMonte with KBW. Your line is open, please go ahead.
Damon DelMonte
Hey, good morning, guys. Hope everybody's doing well.
Thanks for taking my questions here. I guess, just first question on the outlook for loan growth.
Dave, it sounds like you expect the fourth quarter to be slower than what we've seen the first three quarters of the year. Could you just give a little bit more color around that, please?
Dave Seiler
Sure. Hi, Damon.
Right now, our pipeline is showing a little like it's a little softer than it had been in some of the previous quarters. One thing about us is, we tend to do fairly good-sized loans, so, and one or two loans could get us back in line with where we would expect to be.
I don't think it's anything systemic. We're not seeing any changes in our market that we think bode for slower loan growth into the future, but just that our pipeline right now, as we look at Q4, is a little bit softer.
Does that answer your question?
Damon DelMonte
Yep, that's helpful. Thank you.
Then maybe with regards to the margin, Brian, can you just kind of unpack again the 3.80% reported number and kind of the fees in lieu of interest impact this quarter versus what a normalized level is?
Brian Spielmann
Sure. Happy to.
So 3.80% reported this quarter, that includes 31 basis points of the fees in lieu of compared to 36 last quarter, five basis points less there. Actually a little bit of improvement in, well I'd say, the core margin in the quarter.
The last five-quarter average is about 25 basis points. That's where we think we'd be assuming normalized prepayments.
We've had above-average prepayments the past two quarters. That's where, if you kind of use 25 instead of 31, that brings you down to 3.74%.
Then, while there may be some temporary benefits from the deposit betas as we see some rate hikes, we will continue to compete on both sides of the balance sheet, and we continue to think that long-term target is appropriate.
Damon DelMonte
Got it. Okay.
That's helpful. Then, I guess, if I could quickly squeeze in on expenses here.
I heard the commentary about why it was down this quarter and kind of the reinvestment expectations. Do you think all that kind of materializes here in the fourth quarter, or we maybe have a little step-up in the fourth quarter and then those investments carry over into the beginning part of '27?
Brian Spielmann
I would say it's probably more of a little step-up in the fourth quarter. I can specifically talk to marketing, where we know we have some initiatives that were planned for earlier in the year that are going to happen now in Q4.
That's going to be about $300,000, we think, of marketing increase, and so all else equal, that's kind of the modest increase in Q4. Then we have other initiatives going on that will carry into '27.
Like we talked about, the result revolve around new bankers and some technology and some additional marketing spend.
Damon DelMonte
Okay. Do you think total expenses for next quarter could stay under $27 million?
Brian Spielmann
Yes.
Damon DelMonte
Great. That's all that I had.
I'll step back. Thank you.
Dave Seiler
Okay. Thanks, Damon.
Operator
Your next question comes from the line of Nathan Race with Piper Sandler. Your line is open, please go ahead.
Nathan Race
Hi guys, good morning. Thanks for taking the questions.
Dave Seiler
Sure, Nathan.
Nathan Race
Just going back to your comments on the kind of healthy core deposit gather and expectations you expect to continue into 4Q and next year. Curious kind of what you're seeing in terms of kind of incremental cost of deposits these days.
Obviously, you guys have a higher cost of deposit base relative to most peers, but just curious kind of what the incremental cost of deposits is relative to kind of right around 2.70% all-in in the third quarter?
Dave Seiler
Big picture, I think for us deposits are always competitive, right? We're going out and we're talking with commercial clients and larger commercial clients are very aware of what the market is.
That said, we haven't seen a big shift in the deposit costs. I wouldn't say it's more competitive than it has been for the past three or four quarters.
It's about similar. Brian, do you want to talk about specifically?
Brian Spielmann
Yeah. I would say we monitor money market funds as a proxy as well for alternative rates, and that's really around 3.80% right now through a basket of funds we look at, and so I would say that's close to what we're seeing, and just more in line with SOFR at this point for new money on the liquidity side.
Then on the CD side, they are over 4% right now, but we're able to match fund those on the asset side.
Nathan Race
Got it. That's helpful, thanks.
Brian, can you just remind us the beta expectations on the deposits you call out on slide 9 that are kind of not indexed, but managed to some degree?
Brian Spielmann
Yeah. We planned for an 80% beta on existing business, and we have been better than that over time.
If you look on slide, I think it's slide 10 of the materials, over our rate cycle, we've beaten that. We conservatively plan for 80% knowing that we're going to have to compete, knowing that we're going to want to fund that 10% loan growth with core funding.
Nathan Race
Got it. Then if I could just sneak one last one in on wealth management.
Obviously, nice momentum year-to-date, and I think you guys are probably tracking for kind of low double-digit year-over-year growth this year. Just based on some of the hires that you guys are alluding to and just the momentum in that line of business, do you foresee anything on the horizon to derail kind of low double-digit growth into next year, assuming equity markets behave?
Dave Seiler
Did you say, "Do we anticipate low double-digit growth for next year?"
Brian Spielmann
Derail
Nathan Race
it. Just trying to think about the sustainability of that, Dave.
Oh,
Dave Seiler
no. We think that growth is very sustainable based on the hires we made and the progress we're making, particularly in our non-Madison markets.
The majority of our private wealth business is in Madison, and we are now growing our Southeast Wisconsin market and our Kansas City market. We feel good about that.
Nathan Race
Great. I appreciate all the color.
Thanks, guys. Congrats on a great quarter.
Dave Seiler
Thanks.
Operator
Your next question comes from the line of Jeff Rulis with D.A. Davidson.
Your line is open, please go ahead.
Jeff Rulis
Thanks. Good morning.
One of the questions on the credit side, the Wisconsin relationship, I just want to understand that as that resolution comes in first quarter and beyond, can that come in kind of piecemeal? As I recall, there were sort of pieces of land there that maybe as you get resolution, those can be in other words, not all at once, but it might be kind of measured pieces of that as it resolves.
Is that fair or no?
Dave Seiler
I think that's fair, Jeff. There are five land parcels we're talking about.
We expect to get control of those at about the same time, and then it's a matter of finding buyers for those parcels. That could happen at the court date, and that could happen sometime after the court date.
I wouldn't expect them all to happen at exactly the same time. Then in terms of...
Jeff Rulis
Oh, go ahead.
Dave Seiler
I was going to say there are also several multifamily projects that will take a little bit longer, but we feel good about where we are, our ability to resolve those.
Jeff Rulis
Great. Thanks.
I guess legally you can't really advertise those pieces. I don't know if you could put feelers out if there's any sense for the reception of that land in the market.
Do you feel pretty good, I would imagine, on valuation, but just wanted to check in on that piece as you unload it in any initial conversations?
Dave Seiler
Right. You're right, we can't advertise it, but it's a little different for this relationship getting land back at a time Usually when you get land back and land deals go south, it's typically because of low demand for land and no building and that sort of thing.
That's not what we're seeing in the markets, we feel like there is some demand for the land, and when we do get control of it, we know a lot of folks that we can talk with about those. It is a little bit known in the market.
Several people have expressed interest.
Jeff Rulis
Great, thanks. Maybe just a housekeeping, you kind of mentioned the run rates on fees and expenses, but at this point, the SBA exit is fully in the run rates of Q3.
Is that correct?
Brian Spielmann
Yes, that's correct.
Jeff Rulis
Great. Just the last one, Brian, you rattled through those buyback numbers.
What was that in the quarter, and what was it quarter-to-date?
Brian Spielmann
In the quarter, we bought back 12,000 shares for a total, I think, about $835,000, and then an additional 29,058 shares in October to date.
Jeff Rulis
Okay. Just checking in on that appetite, obviously, it seems like you're leaning in a bit, and it sounds like that's a pretty viable tool for you going forward.
That's outside of funding for growth. Sounds like you're pretty committed, and I guess checking in on the price sensitivity of valuation.
If you could just kind of talk about the buyback a little bit more going forward?
Brian Spielmann
We've used $2.9 million to date of the $5 million authorized, and we think there could still be opportunity going forward too. We evaluate kind of like we talk about the intrinsic value of the stock relative to our other opportunities, and, thinking about our 12-month forward expectations internally, we feel that there's still opportunity relative to the other capital allocations.
Jeff Rulis
Appreciate it. Thanks.
Operator
Your next question comes from the line of Brian Martin with Brean Capital. Line is open, please go ahead.
Brian Martin
Hey, good morning, everyone.
Dave Seiler
Morning. See
Brian Martin
maybe just, can you talk a little bit about, maybe it's more Brian, just on the I think you talked about some of the dynamics with the margin this quarter, Brian, but just in terms of it sounds like it's elevated for a bit and it's going to maybe trend lower. I guess kind of timing-wise, just how you're thinking about there, kind of what that inflection is.
Is it just the funding side that kind of brings it back ultimately to the range, and just broadly, how you're thinking about that over the next, call it five quarters or so, just trending?
Brian Spielmann
I think what you stated is accurate, and I would expect on the funding side to be where we see more of the pressure going forward based on what we're seeing in the quarter so far, one or two days of the first rate hike and with expectations of another hike in December, and just understanding how we value core deposit funding. Historically, that's where we've seen the pressure to, what I'll say, compress our temporary elevated margin from a rate hike, a rate movement, right?
We still believe in our neutrality on the yield curve, but on the short end of the curve, we do have some of that temporary benefit in the rate hike that will give back with growth in core funding.
Brian Martin
Okay. Kind of back in your range sometime next year, just we'll see how rates go and I guess that's how to think about it for now?
Brian Spielmann
Yes.
Brian Martin
Yep. Got you.
Then maybe just about loan growth. Can you talk about, as you talk about some of the hires you're anticipating, just kind of what drives loan growth in '27 and do higher rates impact that?
Is it less real estate, more other lines? Just kind of curious how you're thinking about growth next year.
Dave Seiler
We are looking at adding a few producers in various markets, particularly where we've had some success, for example, asset-based lending, where we've had some really nice growth over the past few years, our Kansas City market. One of the things that we think allows us to have the kind of growth that we do is kind of our diversified growth engines, right?
I think last quarter, our growth was coming from Kansas City and Northeast Wisconsin and asset-based lending. This quarter, it's Southeast and South Central Wisconsin along with our floor plan finance.
I think one of the benefits of our model is the ability to grow from multiple channels, and I think that allows us to have smoother growth, and that's what has allowed us to be successful from a growth standpoint. Yep.
Brian Spielmann
Brian, I would add, too, that we're always comfortable with our CRE growth, but I think we're really excited about the C&I side, too, just based on what Dave mentioned with asset-based lending and factoring, ABL particularly with the leader we have in place there. We also have a new leader in place in our floor plan finance area, and so some of those C&I areas, we're really excited about in terms of the runway they have there, and you combine that with some of these smaller markets that we're seeing a lot of nice growth in like Kansas City, really makes us feel comfortable with our continued 10% growth rates.
Brian Martin
Got you. Just remind me, Brian, where is the specialized kind of those segments today as a percent of the whole portfolio?
Brian Spielmann
It's right around 23% total.
Brian Martin
23%, got you. Perfect.
Then maybe just last one for me was, obviously, the efficiency ratio is really trended great here. Your comments, Brian, about operating leverage next year, I guess expectations are still that, I guess we see some improvement, even given that the significant benefit you've seen this quarter, improvement?
Brian Spielmann
When I think about that, I look at kind of year-to-date 2026, we're at just over 58% efficiency ratio. Like we talked about, we're going to have a little bit of a pick-up in expenses in Q4, but our goal, and how we plan, is to continue to look for positive operating leverage on an annual basis.
That's what we will plan for, and that's how we'll look to '27.
Brian Martin
Got you. Okay.
Perfect. That's all I had, and again, congrats on the quarter, guys.
Dave Seiler
Thanks, Brian. Thanks.
Operator
Your next question comes from the line of Nicholas Holowko with Raymond James. Your line is open, please go ahead.
Nicholas Holowko
Morning, guys. Thanks for taking my question.
Most of them have been asked and answered already, but maybe one just thinking about the next couple of years here. You've alluded to the expectations for operating leverage to continue.
You've demonstrated this ability to produce a 16% return on tangible common equity year-to-date. Any thoughts about how much further that could continue to expand as we look out to 2028 relative to your goal of above 15% by 2028?
Dave Seiler
If we continue our growth and we continue positive operating leverage, those numbers will get better, right? We're not quite ready to give a target in terms of efficiency ratio of where we think that could go in the next five years.
When we did release our last strategic plan, our goal was to get that number below 60%. We've done that.
We're a little bit ahead of schedule. Something we may look at is adjusting that.
We're about halfway through our strategic plan. We may adjust our target on that.
We're just not ready to do it at this point, but obviously with our goal of positive operating leverage, that's our goal, is to improve it.
Brian Spielmann
Yep. I would add that our current five-year plan goes to '28, and we by no means think we can do positive operating leverage into perpetuity and drive our efficiency ratio down to zero.
In the current five-year plan, we think that's possible. We are a growth company.
We want to be a growth company. That's going to incrementally have some step-up costs along the way that then will grow into that growth.
Through the current five-year plan, we think it's achievable, and we're ahead of plan.
Dave Seiler
Right. We think on some of the operating expense areas, we are working hard to increase productivity using technology tools like AI, robotic process automation.
All of those things are helping us drive that number down a little faster than we expected in terms of efficiency ratio.
Nicholas Holowko
Awesome. That's helpful.
Thank you very much.
Dave Seiler
All right. Thanks.
Operator
We have reached the end of the Q&A session. I will now turn the call back to Dave Seiler, CEO, for closing remarks.
Dave Seiler
Thank you for joining us today. We appreciate your time and interest in First Business Bank.
Have a great day.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.