Fluent, Inc.
NNASDAQ:FLNTQ2 FY2026 · Earnings Call TranscriptAugust 10, 2026
Operator
Good afternoon and welcome. Thank you for joining us to discuss Fluent's second quarter 2026 earnings results.
With me today are Fluent Chief Executive Officer Don Patrick, Chief Financial Officer Ryan Perfit, and Chief Strategy Officer Ryan Schulke. Our call today will begin with comments from Don Patrick and Ryan Perfit, followed by a question-and-answer session.
I would like to remind you that this call is being webcast live and recorded. Additionally, there is a slide presentation that accompanies today's remarks, which can be accessed via the webcast and is also available on Fluent's website.
A replay of the event will be also available following the call on Fluent's website. To access the webcast and slide presentation, please follow the investor relations page at fluentco.com.
Before we begin, I would like to advise listeners that certain information discussed by management during this conference call will contain forward-looking statements covered under the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Any forward-looking statements made during this call only speak of the date hereof.
Actual results could differ materially from those stated or implied by such forward-looking statements due to risks and uncertainties associated with the company's business. These statements may be identified by words such as expects, plans, projects, could, will, estimates, and other words of similar meaning.
The company undertakes no obligation to update the information provided on this call. For a discussion of the risks and uncertainties associated with Fluent's business, we encourage you to review the company's filings with the Securities and Exchange Commission, including the company's most recent annual report on Form 10-K and quarterly reports on Form 10-Q.
During the call, management will also present certain non-GAAP financial information relating to media margin, adjusted EBITDA, and adjusted net income. Management evaluates the financial performance of the company's business on a variety of indicators, including these non-GAAP metrics.
The definitions of these metrics and reconciliations to the most directly comparable GAAP financial measure are provided in the earnings press release issued earlier today. With that, I'm pleased to introduce Fluent's CEO, Don Patrick.
Don Patrick
Good afternoon, and thank you for joining us today. I'm here with Ryan Schulke, our Chief Strategy Officer and company co-founder, and Ryan Perfit, our Chief Financial Officer.
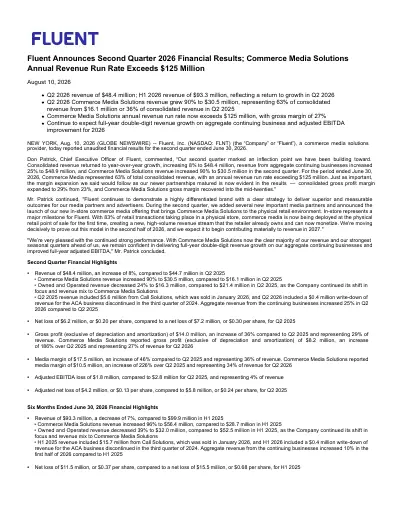
Our Q2 financial results marked an important milestone in the execution of our business strategy. Fluent returned to year-over-year revenue growth.
On an aggregate continuing business basis, revenue grew 25% year-over-year in the second quarter, and even on a reported basis, inclusive of the Call Solutions divestiture, total revenue grew 8%. This is not an isolated data point.
As we discussed in previous earning calls, this was part of our strategic plan that we have been aggressively investing to capture the significant opportunity in front of us in commerce media. We are solidly positioned to accelerate as we've become a recognized brand in the industry based on results we provide our partners.
This quarter is the proof: revenue growth paired with improving margins, the signature of a sustainable business strategy showing up on a consolidated level, not just within a single business line. Looking ahead, we believe that we are well-positioned to drive double-digit growth in revenue on an aggregate continuing business for full year 2026.
Q2 was also a quarter where we leveraged our credentials and extended our platform into new adjacent commerce media markets with innovative first-mover advantage. In June, we announced our in-store partnership with Bilt, extending commerce media beyond digital post-transaction moments and into physical checkout.
More than 80% of retail transactions still happen in the physical store, and this gives us a way to engage our partners' most valuable customers wherever they shop, online or in person. I'll go deeper on this in a few minutes.
Let me take you through the quarter, starting with the financial results, and then spend time on where Fluent will continue to innovate and lead in commerce media. Q2 2026 results were as follows and consistent with what we advised last quarter: revenue of $48.4 million, up 25% year-over-year on an aggregate continuing businesses, excluding the impact of the Call Solutions divestiture and other divested and run-off revenue.
Year-over-year revenue was up 8% on a reported basis. Our Commerce Media Solutions business again led that growth with revenue up 90% year-over-year.
Gross profit of $14 million, up 36% year-over-year and representing 28.9% of revenue, a 650 basis point improvement from Q1 2026, driven directly by improved monetization with certain key Commerce Media Solutions partners and those partnerships becoming a larger share of our business. Adjusted EBITDA of negative $1.8 million, a margin of negative 4%, a sequential improvement of $1.8 million from Q1 of 2026.
Commerce media continues to be the lead story of our company. It is where we will deliver shareholder value by expanding our footprint in the rapidly growing marketplace.
What gives us increasing conviction isn't just the growth rate, it's the momentum we're building with world-class brands combined with new, innovative, adjacent solutions we're beginning to build in loyalty and in-store. The marketplace continues to expand, and we're leading in meeting our partners' current and future needs.
That strategic combination, a growing roster of premier partners plus real future product innovation beyond our core, is what positions Fluent to be a market leader in the commerce media industry. Commerce Media Solutions revenue grew 90% year-over-year in the second quarter, our 10th consecutive quarter of high double-digit to triple-digit growth.
That growth in Q2 was driven by continued momentum in online post-transaction as we ended the quarter with an annual revenue run rate of over $125 million. A second strategic breakthrough with in-store lays the foundational platform for additional future growth, and it's not part of our successful Q2 financial performance.
In-store represents a large market opportunity we're moving decisively to prove out in the second half of this year with material revenue impact beginning in 2027. Let me walk you through both.
Our core online post-transaction business remains the largest and most mature piece of our Commerce Media Solutions, and it continues to do the heavy lifting. This isn't a new thesis.
It is validated based on the continued superior execution by our team and built on our ability to deliver superior results through our data and performance marketing industry leadership. Our foundation is uniquely grounded in our owned and operated marketplace, which our competitors simply cannot replicate given our decade-plus of industry experience.
The first-party data, performance marketing expertise, and consumer and advertiser relationships we've built there are the competitive advantages we're now leveraging to deliver superior, measurable results for our commerce partners. That foundation is driving our growth as established a competitive moat.
We continue to add world-class partners to our commerce media network in Q2. We believe we are a reflection of the partners we do business with, and our partner pipeline has grown significantly in both size and quality.
Given the seasonality of the retail partner sales cycle, we expect that pipeline to convert and accelerate in the second half and will take that redefined baseline into fiscal year 2027. As validation of our business and brand momentum, one of the largest retail pharmacy chains in the country, CVS, has chosen us to partner with Fluent, and they came online in Q3.
We are excited to enrich the checkout experience for their customers with an eye towards deeper loyalty integration over time, which will add value to an already best-in-class experience. A meaningful trend that we're seeing in our online post-transaction business is bringing non-endemic advertising demand into traditional captive retail media networks.
As those networks continue to look for new growth opportunities, they're beginning to turn to partners like Fluent for non-endemic demand. Our partners understand that their customers enjoy products and services that they don't directly sell, and our post-transaction business enables them to do so successfully on their behalf.
These captive network relationships are more bespoke compared to our traditional enterprise partnerships, but they meaningfully expand our addressable market and further validate Fluent's competitive position in commerce media. We're already delivering non-endemic demand into one of the largest retail media networks in the world, a proof point of how we expand these captive networks' addressable market.
Our partner sales pipeline is expanding with other retail media networks. Importantly, working directly with captive retail media networks gives us a differentiated avenue to unlock massive new audiences for our advertisers.
During the second quarter of 2026, we introduced in-store, a strategic marketplace opportunity that will lean on loyalty for success. Loyalty data is what lets us recognize the same shopper whether they're checking in online or standing at the physical register, and this is the connective tissue between the two moments.
That matters because we're not building two separate online and in-store businesses, we're building one commerce platform that follows the shopper wherever they transact and that makes both sides of the marketplace more valuable to the shopper and to our retail partners. A first proof point here is our expansion into in-store commerce media through a partnership with Bilt Technologies, a nationwide commerce and loyalty network that offers in-store point-of-sale systems for retailers.
In an estimated $140 billion commerce media industry, in-store remains the hardest segment to measure, and this partnership is built to close that gap. The in-store offering is a first-mover position for Fluent, and we're deliberate about how we're going to build it.
The partnership launches later this year with Beyond, Inc., operator of Bed Bath & Beyond, buybuy BABY, and The Container Store. We've developed a strong pipeline of potential additional partners for onboarding in early 2027.
In the second half of 2026, we are committed to testing and learning, proving out the consumer experience, the measurement, and the advertiser return on ad spend. We are not expecting any meaningful financial contribution from in-store this year.
We expect that in 2027 once we've validated the model at scale. To put this in perspective, online post-transaction is driving our results today.
In-store is what we're building for tomorrow, a vast market that allows us and commerce partners to tap into 83% of transactions that do not happen online, which represents an initial 70 to 80 billion annual transactions in the U.S. This is a 5x unlock across commerce, and for media partners in pharmacy, grocery, and home improvement retail sectors, this can mean a 10x increase over monetizable transactions.
In short, this is a huge market opportunity and one where being first matters. Returning to year-over-year growth this quarter, layered on top of accelerating and now two-prong commerce media business strategy, gives us more visibility than at any other point since we've completed our strategic pivot.
We remain confident in our stated financial targets for the full year. We expect continued double-digit consolidated revenue growth on an aggregate continuing businesses and to maintain the gross margin expansion reflected in Q2 as our higher-margin business becomes an increasingly dominant share of the mix.
We also expect continued improvement in adjusted EBITDA as that revenue growth and margin expansion flow through the P&L. With that, I'll turn it over to Ryan Perfit for a deeper look at the financials.
Ryan Perfit
Thank you, Don, and thanks to everyone for joining us today. I'll now provide a deeper review of our second quarter financials with commentary on year-to-date results where relevant.
Total consolidated revenue was $48.4 million in the second quarter of 2026 compared with $44.7 million in the prior year period. Notably, total consolidated revenue increased by 8% compared to the second quarter of 2025, and revenue from our aggregate continuing businesses increased 25% when compared to the second quarter of 2025.
As Don mentioned, we view this as a key milestone that demonstrates the impact Commerce Media Solutions is having on the overall business. Accordingly, we expect to continue to drive double-digit growth in revenue from aggregate continuing businesses through the balance of the year.
Commerce Media Solutions revenue grew 90% to $30.5 million in the quarter when compared to Q2 2025 and represented 63% of total consolidated revenue compared with 36% in the prior year period. Demand is strong, and we're very encouraged by the interest we're seeing from leading brands across diverse industries, including some of the largest retail chains in the United States, as we continue to strategically invest in our growth, specifically in the launch of our new in-store offering that we expect to significantly expand our addressable market.
Commerce Media Solutions is now firmly established as the main driver of total consolidated revenue across our business. With our visibility to date, we expect CMS to continue to grow at high double digits and increase as a percentage of total revenue going forward.
As expected, owned and operated revenue decreased 24% to $16.3 million compared to $21.4 million in the second quarter of 2025. Media margin in the second quarter was $17.5 million, representing 36% of total consolidated revenue, compared with $11.9 million or 26.7% of revenue in the prior year period.
Commerce Media Solutions media margin in the second quarter of 2026 was $10.5 million or 34% of Commerce Media Solutions revenue compared with $3.2 million or 20% of revenue in the second quarter of 2025. Commerce Media Solutions gross profit was $8.2 million in the second quarter of 2026, an increase of 186% compared to the second quarter of 2025 and representing 27% of revenue.
This is especially encouraging given our stated expectation that CMS margins would return to the mid-20s range over the course of 2026 as we continued to scale and grow this business as a percentage of total revenue and newer partnerships and placements move beyond early term incentive periods. The major driver of the increased media margin and gross margin was improved monetization and scale of certain media partners that do not operate on rev share agreements.
Total operating expense in the second quarter of 2026 totaled $17.3 million compared with $14.9 million in the second quarter of 2025. The year-over-year increase was driven largely by higher incentive-based compensation, which scales with our results and steps back if performance moderates, rather than adding to our fixed cost base.
Interest expense in the second quarter decreased 9% to $637,000, down from approximately $702,000 in Q2 2025. This decrease continues to reflect the lower average daily outstanding loan balance and lower amortization of debt costs under the new Bayview facility.
We reported a net loss of $6.2 million in the second quarter of 2026 compared with the net loss of $7.2 million in the prior year period. Adjusted net loss, a non-GAAP measure, was $4.2 million, or a loss of 13 cents per share, compared with adjusted net loss of $5.8 million, or a loss of 24 cents per share, in the second quarter of 2025.
We reported an adjusted EBITDA loss of approximately $1.8 million in the quarter compared with a loss of $2.8 million in the second quarter of 2025, reflecting our ongoing commitment to improve adjusted EBITDA throughout 2026. Shifting now to our balance sheet and cash flow.
We had $6.9 million cash and cash equivalents at June 30th, 2026, compared with $12.9 million at December 31st, 2025. Accounts receivable was $39.4 million compared with $48.7 million at year-end 2025, contributing to total assets of $75.1 million.
We also drove operating cash flow of approximately $300,000 in the first half of 2026 and reduced short-term debt from $30.8 million at year-end to $26.8 million as of June 30th, 2026. Our liquidity continues to be supported by our accounts receivable financing facility, and we remain focused on improving free cash flow and liquidity as Commerce Media Solutions scales.
Overall, we're very pleased with our results this quarter and the progress that we've made year-to-date. Commerce Media Solutions continues to grow at high double-digit rate on a year-on-year basis, and we're validating the Fluent brand with interest from tier-one media partners and advertisers across diverse market verticals and now with our in-store offering.
Our execution has been strong, and with our visibility today, we remain confident in our stated goals for 2026 to deliver double-digit consolidated revenue growth on aggregate continuing businesses and improved full year adjusted EBITDA supported by continued growth in Commerce Media Solutions. With that, I'll turn it back over to Don.
Don Patrick
This was a milestone quarter for a number of reasons: consolidated revenue growth turned positive, commerce media grew 90% powered by continued strength in post-transaction and captive retail media network expansion, margins expanded, adjusted EBITDA improved, and we planted the flag on our second major commerce media growth front, in-store, that we believe will matter a great deal in 2027 in further differentiating the Fluent brand as a market leader in our space. Our business model is accelerating, and we are encouraged by the results we are driving for our stakeholders.
Operator
If you'd like to ask a question at this time, please press *11 on your telephone and wait for your name to be announced. To withdraw your question, please press *11 again.
Please stand by while we compile the Q&A roster. Our first question comes from Maria Ripps with Canaccord.
Your line is now open.
Maria Ripps
Great. Good afternoon, and thanks so much for taking my question.
I just wanted to ask about your CVS partnership, which was great to see. Maybe just talk about sort of what does that mean for your commerce business.
Just maybe talk about the integration that's required to bring that partner sort of on board. Then maybe more broadly, what does it mean for attracting other partnerships similar to CVS?
Thank you so much.
Don Patrick
Yeah. Hi, Maria.
Thanks for the question. Specifically, what does it mean to the commerce, it is going to be one of our largest partner wins.
More importantly, it brings us into a different vertical, obviously, heavily into pharmacy and heavy into along with their retail pieces. It expands our audience, which obviously plays well into our diversified advertiser strategy.
It's a great partner to bring on that diversifies our marketplace and continues to make it stronger. The integration on the online is no different than any of our other integrations.
Our ad tech and our ad module will be placed within their post-transaction site. It's a fairly straightforward integration in terms of how we worked through it from a technical perspective.
There's nothing unusual from that. As far as what that means to us in terms of, A, we're in a new vertical, which you guys know we land that vertical, we prove out superior results in a case study, and then go deeper.
We certainly expect that to continue to allow us to get deeper into that vertical. At the same time, we believe that getting them will also attract other big-name retail partners that we're working with.
Maria Ripps
Got it. Thank you so much, Don.
Don Patrick
Thanks, Maria.
Operator
Our next question comes from Eric Martinuzzi with Lake Street Capital Markets.
Eric Martinuzzi
Hey, congratulations on that return to positive consolidated revenue growth. That's got to feel good.
Given the success of the first half of the year on the aggregate, kind of consolidated business, you're already at 10% growth there for the first half of the year. I get you don't want to overpromise and underdeliver, but that growth rate in the back half of the year, I assume we're talking about an acceleration.
Is there a number that we should be thinking about for the growth rate in Q3, Q4? Anything you can talk to us about beyond just 10%?
Ryan Perfit
Hi, Eric. This is Ryan Perfit.
We're not giving specific guidance on the growth rate. Your point is well taken in terms of us being at double-digit growth already.
Yes, that is something we expect to continue to maintain and even grow upon.
Eric Martinuzzi
Okay. Then the adjusted EBITDA, we can almost reach out and touch breakeven here.
I'm modeling for Q4 to be positive. Is there a chance you could do that in Q3?
Ryan Perfit
We do expect to have a positive Q4. Q3, we're not giving specific guidance on Q3, but we expect continued improvement from where we are now throughout the year, and then Q4 has the seasonality that will bring us positive.
Eric Martinuzzi
Okay. All right.
Then that CVS, congratulations on that tremendous partnership. You've signed them up for the post-transaction.
Is there an opportunity for in-store with CVS?
Don Patrick
It's a great question, Eric. This is Don Patrick.
Yes, the clear roadmap for CVS was both online post-transaction and then getting into in-store in 2027.
Eric Martinuzzi
Okay.
Don Patrick
Go ahead. Sorry.
Eric Martinuzzi
Go ahead. Oh, go ahead.
Sorry. I was I was just going to say, a lot of times the customer can be the barrier to the ramp, to speak.
In other words, you all are ready, willing, and able. They just need to dedicate the people to implement.
Kind of what's their body language on their post-transaction ramp? Are they looking for this to be a big contributor in seasonally stronger Q4 business, from what you can tell?
Don Patrick
Contributor for 2026, absolutely. Yep.
We went live in Q3. We went live last week with them.
We are scaling, and it's going as planned as far as the integration piece. Yeah.
Eric Martinuzzi
Okay. Then lastly, on the gross margin, Ryan, I think we're at 29% for Q2.
I know you talked about kind of mid-20s, I think, is in the press release. Is it the onboarding of partners that's kind of holding that back from expanding?
I'm just wondering why we wouldn't be able to push that higher as we're ramping the businesses that we signed up in '25?
Ryan Perfit
Yeah. Hi, Eric.
That's a great question. In terms of the margin, we were at 27% margin on Commerce Media Solutions.
That was the return to the mid-20s that we had promised earlier in the year. That was ultimately driven by, some strong partnerships, better monetization on a couple key partnerships, and scale of those partnerships.
We've also talked historically about, the early term incentives rolling off for some of these larger partners, and we expect that to continue to happen. That said, we will continue to invest into opportunities just like this one that took us to, took up the margin from Q1 to Q2, where we spent a couple quarters trying to get it right and figuring out the monetization, and then eventually we got there and and it's a huge opportunity for us.
So, there will be cases like that. I think ultimately, we do expect to maintain in the mid-20s, and then hope to grow it from kind of mid-20s to upper-20s.
Hopefully at some point, not in 2026, but eventually, at scale, we would expect to be in the in the 30, low 30s.
Eric Martinuzzi
Gotcha. Congrats again on the breakout quarter.
Don Patrick
Thank you, Eric.
Operator
Our next question comes from Bill Dezellem with Tieton Capital Management.
Bill Dezellem
Great. Thank you.
I have a group of questions. Allow me to start with the in-store, if you would, please.
Since you spent so much time on this, would you walk us through operationally how this works for the retailer? Or maybe another way to ask the question is what training is required for the associate that's standing at the register for the Commerce Media Solution to be executed?
Don Patrick
Yep. Hey, Bill.
Thanks Thanks for the question. We're not surprisingly being very deliberate about not getting too far ahead of this, for competitive reasons.
So, we're not going to go into great detail around this. You're absolutely right.
If you're on online checking out, you're you're either in front of your you're in front of your laptop or on your on your app and your your credit card's out and you're spending, it's a very, different experience than if you're checking out of a store. If you've been a lot of the new stores, as you know, have or a lot of stores that built out either self, checkout kiosks that are bigger screens or they'll have bigger screens in the in the checkout area.
That is sort of allowing us to have a different user experience as someone's checking out of that physical store. So, the exact consumer experience is not, it is not exactly defined, and it will be different by the different audiences.
We expect it to be both in-store instantaneously when you're checking out and also some follow-up afterwards with, with from a CRM perspective in terms of how we continue to engage those those, check those physical store consumers. The thing that we did mention is the loyalty play here, Bill.
If you are in-store and you're a loyalty member and you're checking out, the information that that we will have, both from our proprietary database and our partner's database, will be significant on who you are, what's relevant to you, and how do we make that a meaningful experience. If you're not known, then it's going to be a different it'll be a different consumer journey and a different path for you.
So, the you've been with us for a long time, Bill. Fluent very well.
We're very good at at building meaningful consumer experiences and making them valuable to them. That's what we've been doing for 16 years in our core in our core business, and that's why we're so successful in the on the, on the commerce side, and that's what we're going to bring to this, testing and learning phase that we have with with Bilt in Q3 and Q4 this year.
We will be rolling out slowly with these stores. We'll be testing it, we'll be integrating it, and then we'll be, we plan on being ready to scale, in 2027.
There's a number of new, partners, new new specific in-store partners that will be coming on in 2027 already.
Bill Dezellem
You have those new in-store partners essentially signed up, and they're in the dugout ready to roll when we're ready? That's right.
Don Patrick
Yep, that's right.
Bill Dezellem
Okay. Great.
Thank you. Then you had mentioned your owned and operated business, both here in response to my question and in your opening remarks, the advantage that is giving you.
Would you please quantify how much more conversion, or margin that you provide your customers than competitors do?
Don Patrick
Great question, Bill. We have on our website a case study that's head-to-head against our biggest competitor in the market, and we will drive close to 30% more revenue to our partners or supply partners, and we'll also, equally important, drive close to 30% improvement on the lifetime value of that consumer.
Not only are we driving more revenue for our partners, but we're also, equally important, driving better and more valuable consumers to our advertisers, which obviously makes that marketplace spin. When we look at our ability to drive those results, come from our core first-party data asset, which has been built over 16 years and all the campaign data that we have with our advertisers that we understand deeply about their audiences and how we build it.
Those are the assets that come from that owned and operated piece.
Bill Dezellem
That's helpful. The example or case study on the website, that is not an anomaly.
That is a norm that you experienced across your customers irrespective of the type of business that they run?
Don Patrick
That's right. Yep, that is correct.
Bill Dezellem
Then, I believe you said that Ryan Schulke was on the line, and Ryan, it's been so long since you've been on these calls. I'm feeling like I want to bring you on to this.
What is your focus today? How does that play in to the initiatives that Don and Ryan have been talking about here?
Don Patrick
Your timing's perfect, Bill, because he's coming into the office and has been delayed, he's not in the office with us here. It's a great question that I'll answer, and then you can ask him correctly.
Make sure we answer the right way. Listen, Ryan is Chief Strategy Officer, right?
He is one of the unique assets that can look at how does a consumer connect to a brand that connects to a return on ad spend, and he has the ability to build that processes and build that database and build that strategy in terms of how we execute across any of our businesses, whether it was owned and operated, whether it's in commerce media, whether it's in our other two businesses around audience solutions and drivvun. That's sort of where he plays across the group.
I think we've talked to you about in a previous earnings call, Bill, that we are now going to our advertisers and we're selling across the entire Fluent portfolio. If you're an advertiser and we'll match you up on commerce media, we'll also put you into the owned and operated audiences.
We'll put you into some other solutions that we have. We can now go to our advertisers with a much broader value proposition and much broader solutions.
He's been driving that significantly, along with Matt Conlin, who is another co-founder that's been with us since 16 years, who's been really leading on that outside with our partners and our brands. Still Ryan's very, very active in all the monetization and the audience and strategy and how we monetize best for that consumer and at the same time for that advertiser.
Bill Dezellem
Great. That's helpful.
I know I've asked a number of questions, cut me off if you'd prefer I went back in queue. Following up on what you just said relative to the owned and operated, the revenues there were flat sequentially.
I don't remember the last time that that happened. The year-over-year decline was cut in half.
Would you discuss that and talk about what that's indicating and if that somehow ties in to what you just shared about this broadening advertiser base?
Ryan Perfit
This is Ryan Perfit. I'll handle that.
It was flat sequentially. We had a number of quarters last year that were flat sequentially, Q2, Q3, and Q4 were sequentially flat, and then we saw a falloff again in Q1.
This business has its kind of ebbs and flows and is very much dependent on the competitive marketplace. We look to strengthen margins there through using kind of our programmatic business to help bolster the data set and use the data set to help bolster the margins there.
Margins were up as well, but I think over the long term here, we still don't have enough foresight to believe this is a stable business that can maintain. Again, it could be stable quarter-over-quarter, and we always shoot for that, but over the long haul, I think that we don't have enough view into the future to believe that it is, ultimately a stable business yet.
Don Patrick
Bill, the structural reality of the owned and operated, as you know, got an uneven playing field with our with our FTC settlement back in '23. So, it continues to fight a uneven playing field against competitors that, that, as Ryan said, sort of ebbs and flows in terms of their adherence to compliance.
The The one thing I I want to make very clear is that we're we're we're not managing through headwinds. We've have pivoted this business to support our commerce media, and enhance our commerce commerce media, and as Ryan said, there's two specific mandates.
Number one, continue to be profitable, which they which they have been throughout, for the last three years. Number two, is really be a test-and-learn environment for our commerce media.
I gave the example before in previous earnings that if we go to one of our commerce partners and we want to test something, we have to do an A/B test. We have to run through the test.
It might take a while to get up and running, and then see the results, and then we can plow through. In our owned and operated, if we want to do a test, we can do a test within, literally within hours and have the results within within a day or two days, and we can see how that can how that can be used to both feed our our AI models, but equally important, feed our creative approaches to to driving superior results.
It is a strategic weapon and not a financial weapon for us right now.
Bill Dezellem
That's helpful. That is part of what drives that 30% better return for your customers that you were referring to earlier, correct?
Am I linking that in the right way?
Don Patrick
Yep, that is correct.
Bill Dezellem
Okay. Great.
Then one additional question, please. How much of the call it $15 million of incremental revenue with the Commerce Media business from a year ago was from customers that were with you prior to March 31 of '25?
Or said another way, the opposite would be, what percent of or proportion of that $15 million is from new customers that came online in the last 12 months?
Ryan Perfit
Bill, it's a great question. Without the specific stats in front of us and something that we don't really disclose, I can tell you directionally is that we've continued to bring on new customers and they do add to that run rate on a quarterly basis.
The largest growth we see from bringing on new partners is usually in Q3 where we have the majority of our closes for the year where we bring on the most amount of new partners. For example, CVS will be part of that increase in Q3.
We do see expansion from existing partners, and a lot of the expansion in the last quarter was from existing partners. It can be a mix of both, but the seasonality usually determines that.
Q3, we get a bit of both, and then the other quarters it may be more expansion than it is new partners coming on.
Bill Dezellem
Ryan, that's helpful. Part of the spirit of the question that I was trying to understand is once a partner has signed on, is there meaningful growth after that initial step-up, or essentially, are you capturing their transactions in that initial step-up and then from there it's really how much growth that they see within their online sales, again, keeping the in-store being separate for the future?
What's the right way to think about that?
Don Patrick
Yeah. I'll answer in a couple of different ways, Bill.
First, if we As we've been 100% focused on enterprise partner enterprise partners, right? These are these are strong brands that we partner that partner with Fluent to integrate our technology to build up a commerce media business.
In in that market in that market segment in which we are are focused on, for the most part, we get, we get, 80% to 90% of of their transactions day one. The type of growth that we have traditionally seen is if they're on the on on the web and we get their mobile app live or they are in the U.S.
and they want us to expand into Canada, things like that. There is expansion being within that for, but if you're like Bath & Body Works, and you do X number of transactions last year, it's going to be within close range of what you did the year before.
So, from that market segment, the the type of growth we're going to start seeing from them are the the new solutions that we've talked about. How do we get in-store?
How do we how do we, tie in the loyalty to the in-store? That's where we think we'll start to see more inherent year- a growth from the existing base.
The one thing we did talk about in the earnings call today that I had no one's asked about is what we called about captive retail media networks. So, in in if you, if you go back, the commerce media business was really founded on the basis of these captive retail media networks like Amazon, Walmart, Kroger, Target, etc.
We call these the walled gardens. State These These are companies that that great retailers that built out their own technology, their own data science, their own ad serving and advertiser relationships.
If you want to work with them, you have to If you're an advertiser, you have to go directly to those platforms to to buy and and and integrate with them. As I said, we've not been focused on that segment.
We've been 100% focused on the enterprise, and that's where all our growth is has historically come from. These walled gardens, have been all focused on what I'll call endemic demand.
An endemic demand would be if you're on a grocer's checkout page and they serve you an ad for paper towels, right? That's something they already sell at the grocery store.
Non-endemic is where Fluent has participated and where we've been in for 16 years. That's where the same grocer checkout, we might serve an ad for insurance, we might serve an ad for, for subscription services, etc.
What we're seeing as an as a meaningful trend here is that those captive retail media networks are now They're still growing, but they're growing at a smaller, percentage, and they're starting to look at non-endemic and start to that as a growth avenue for them. One of we've, we we are working with one of the largest retailers in the world on non-endemic into their platform in a post-transaction environment.
That's the type of thing where, it obviously has huge scale in terms of, dem- in terms of supply, and will that's where you'll start to see some of the growth of where we penetrate a smaller percentage of their traffic. We'll start to build that and start to, continue to grow as we deliver superior results.
That's probably the bigger growth, as part of the of what I'll call land-and-expand. We have we're working with one very successfully, we have a number of of them also in the pipeline.
As meaningfully, it addresses a l- it it increases our addressable market size, which obviously, we thought was big to begin with, but cracking into these, retail media networks is big. The second thing is it's a validation of the results we can drive.
When we work with them, we're we're putting up a multiple, performance lift than what they've been doing themselves, which again plays to those unique assets that Fluent has built up over time that drives superior results. A long-winded answer, Bill.
I I think we're we're st- as we're starting to look at the at at our commerce media partners in in in clear industry seg- not industry, but industry segments around commerce media and how we, continue to grow that. The market the addressable market for Fluent has continued to get large.
Bill Dezellem
Congratulations, and thank you on that extra perspective and helping us understand how all these pieces of the puzzle that actually might look disparate are really interconnected. That's quite helpful.
Thank you.
Don Patrick
Thank you, Bill.
Operator
Our next question comes from Frank DiLorenzo with Singular Research.
Frank DiLorenzo
Hi, guys. Nice pivot, and thanks for fielding my questions.
Could you just give us a broad comment on what you're seeing on the consumer spending side of things from your partners and just generally? Thanks.
Don Patrick
Hi, Frank. Thanks for the question.
We have not seen anything meaningful on the consumer spending side. It has been pretty consistent.
We have seen a little bit in terms of certain vertical rotations across, well, I'd say shopping and loyalty and gaming, but for the most part, we've seen fairly stability around the consumer and their ability to spend.
Frank DiLorenzo
Okay. Also, regarding partners
Don Patrick
Obviously, given the environment Given the environment, Frank, obviously, we're watching it very closely, right?
Frank DiLorenzo
Do you think it's stable for the balance of the year as far as visibility? Maybe related to that also, budgeting on the client side, partnership side, do you have a little more visibility?
Do you think it will at least remain stable from what you can see for the balance of the year?
Don Patrick
Yes, we do. Absolutely.
Frank DiLorenzo
Okay. Just one other quick follow-up regarding partnerships.
Seems like that's your focus now more than M&A, and on the partnership side, can you speak to maybe some things you're looking for, minimum hurdles, benchmarks, in order to enter into any new partnerships and kind of how you view the overall partnership landscape? Are there several good partnership targets, or is it more selective?
Thanks.
Don Patrick
Frank, when you talk about partner, you're talking about sort of a supply partner like a CVS, is that where your question is?
Frank DiLorenzo
Yes. Yes.
Don Patrick
Yeah.
Frank DiLorenzo
Thanks.
Don Patrick
Good question. As we talked about before, we obviously are very vertical-focused in our sales, and it's an enterprise sales cycle.
Retail is where we've obviously started, and we believe we have a great vertical which we've grown in and we're delivering results. We've gotten into ticketing, we're into grocery, we're now into retail pharmacy.
We will continue to roll out those verticals, which expands our marketplace, but also diversifies the audience that we have for advertisers. There's nothing that we're outside of that says we have to get into this and we have to land it specifically, but there are obviously continued expansion into the verticals that we've talked about.
Frank DiLorenzo
Thanks. Just one other quick question.
Regarding margins and your opportunities, is there enough room as far as investment back into the business based on opportunities you may have this year into next year where you can do that without hindering what your margin goals may be over the next few years? Thank you.
Don Patrick
The short answer, Frank, is yes. Ryan gave guidance that If you're talking about gross profit or you're talking about operating margins, our gross profit obviously is in the mid to high 20s, which we will manage between the various pieces of investment to bringing new clients on to growing those.
Then I think on the operating side, we've made a heavy investment early on in '23 and '24 and '25 on our technology and our platform, our data science. We will continue to invest in those, but the operating leverage that we now have in the business is much more significant than it has been.
There's going to be more flow-through as we bring that revenue through than it has been in prior years. We think there's plenty of flexibility in terms of our ability to reinvest back into the business.
Frank DiLorenzo
Okay. Thank you.
Operator
That concludes today's question-and-answer session. I'd like to turn the call back to Don Patrick for closing remarks.
Don Patrick
Thank you all for joining us today. Q2 was an important milestone with Fluent returning to year-over-year revenue growth from an aggregate continuing businesses, and we have entered Q3 with commerce media at 63% of our total revenue and growing, and with the strongest part of the year still ahead.
Q3 will have more to say than just the numbers alone. We look forward to demonstrating that for you and look forward to update you all at the end of the quarter.
Thank you so much.
Operator
This concludes today's conference call. Thank you for participating.
You may now disconnect.