Stanmore Resources Ltd
Q3 FY2026 · Earnings Call TranscriptOctober 27, 2026
Operator
Thank you for standing by and welcome to the Stanmore Resources Limited September quarterly activities report investor briefing. All participants are in a listen-only mode.
There will be a presentation followed by a question-and-answer session. If you wish to ask a question, you will need to press the star key followed by the number one on your telephone keypad.
I would now like to hand the conference over to Marcelo Matos, Chief Executive Officer and Executive Director. Please go ahead.
Good
Marcelo Matos
morning, everyone, or good afternoon to those joining from the southern states. Thank you for joining us as we take you through our September quarterly activities report.
With me today, again, is Shane Young, our Chief Financial Officer. The third quarter was another successful one for Stanmore.
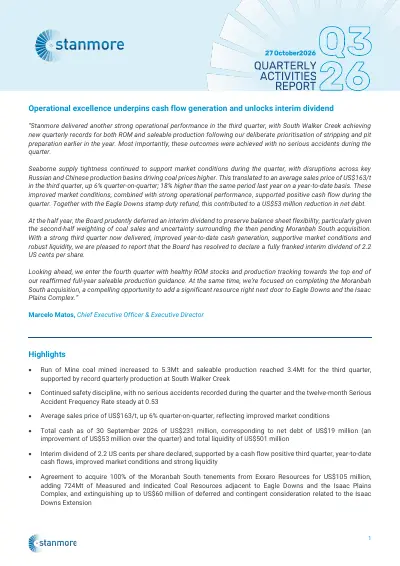
Mining conditions were favorable, with dry conditions and the investment into pre-pit preparation through the first half supporting a record performance at South Walker Creek and solid results overall, with no serious accidents recorded during the quarter. Year-to-date saleable production is tracking well within the guidance range, and with closing ROM stockpiles of 1.7 million tonnes as of 30th September, we are in good shape for the fourth quarter and to close out the year.
As a result, we have reaffirmed our full-year saleable production guidance, and are currently tracking towards the top end of the range. On the market, supply tightness domestically in China and out of Russia supported coal prices, with headline PLV index trading at levels not observed since the first quarter of 2024.
Our average quarterly sales price increased to 163 US dollars per tonne, up 6% on the June quarter. On a year-to-date basis, our average sales price is 18% higher than the first 9 months of last year.
Combined with the operational performance, this culminated in a healthy cash generation, with net debt reducing to 19 million US dollars and total liquidity improved to over 500 million US dollars. Finally, we remained active on the corporate front, with the completion of the refinance and the announcement of the agreement to acquire the Moorvale South tenements.
Overall, since our half-year results, we've gained greater certainty on Moorvale South, delivered a strong third quarter, and benefited from the improved market conditions. These developments have together supported strong cash generation and improved liquidity, giving the board confidence to revisit its early decision and declare an interim dividend of approximately 20 million US dollars.
Moving on to a summary of our operational performance and starting with South Walker Creek. Following the prioritization of stripping and pit preparation early in the year, the mine delivered record ROM and saleable production of 2.8 million tonnes and 1.9 million tonnes respectively.
This surpasses the previous quarterly ROM record set in December 2025 quarter, with saleable production supported by CHPPs performing above nameplate capacity. Closing ROM stocks at South Walker Creek have also increased to more than 800,000 tonnes, positioning the operation well to deliver on the fourth-quarter production and sales plan.
At Poitrel, the quarter reflected the planned CHPP shutdown that we deferred from June to July. As a result, saleable production decreased to 1.1 million tonnes as CHPP feed was constrained during the shutdown before processing rates returned to normal in August and September.
Nonetheless, ROM volumes remained strong at 1.9 million tonnes, which supported a buildup in ROM inventories to more than 700,000 tonnes at the quarter end. Year-to-date saleable production at Poitrel of 3.6 million tonnes remains on track towards the upper end of full-year guidance.
At the Isaac Plains Complex, we assumed operatorship at Isaac Downs during the quarter, as previously announced. We are pleased with the early results, with strong truck-and-excavator fleet performance and an optimization of the dragline dig methodology supporting efficiencies.
Strip ratios, saleable production, and total coal sales each improved quarter on quarter. Turning to the development pipeline.
The key new development has obviously been the Moorvale South deal, which continues to progress through the various stages required for completion aimed for the fourth quarter. As highlighted in the initial announcement, the Moorvale South tenements contain 724 million tonnes of measured and indicated resources, believed to be of premium hard coking coal quality in the [Gunnyella?]
Middle seam, and are located directly to the north of our Eagle Downs project. While we have been keeping the pace on Eagle Downs, including progressing approvals for the connecting transport mining lease between Eagle Downs and our processing infrastructure at Poitrel, we intend to bring the Moorvale South deposit into a broader, more comprehensive study scope.
This includes a potential integrated joint development with Moorvale South to ensure the best development outcome for the combined resource. We plan to update the market on the timeline for that work as it takes shape post completion of the Moorvale South transaction.
Turning now to the coal markets. Pricing during the quarter was driven by concurrent shortages of coal from key Russian and Chinese production basins.
In China, safety inspections and the curtailment of domestic production, combined with a slower clearance of Mongolian land-borne volumes, led to a supply shortage and a rapid escalation in domestic prices. At the same time, Russian exports were materially disrupted from the Black Sea terminals following an escalation of vessel strikes, and these volumes were not fully replaced from the Baltic or Far East terminals.
Higher fuel and labor costs also pushed Russian offer prices up through the quarter, while delays and reduced availability were observed from key North American export terminals. The net effect saw premium hard coking coal and low-vol PCI prices peak at 285 US dollars and 220 US dollars respectively.
The rally began later in the quarter and therefore will take some time to materialize into our realized pricing, given the roughly 30-day lag on our pricing mechanisms. Looking ahead, higher coal and energy prices have placed pressure on steel margins, including in China.
The direction of Chinese steel production after the holiday season and any trade flow outcomes from the tariff discussions between China and the United States will be important factors for the fourth quarter. Notwithstanding that, India's emergence from the monsoon season, together with the commissioning of new large-scale coke oven facilities, is expected to provide ongoing support for seaborne demand.
Following the quarter end, it was pleasing to see the Indian Ministry of Steel draft a national steel policy vision to 2047, which supports India's role as a long-term growth market of metallurgical coal. The draft projects metallurgical coal demand to more than triple by 2047, with Australian exporters expected to benefit from additional demand.
We will continue to monitor how the draft develops through consultation. With that, I'll now hand over to Shane to update you on our financial position and guidance.
Shane Young
Thanks, Marcelo. Looking at the balance sheet, Stanmore concluded the quarter with a consolidated cash balance of 231 million US dollars.
After factoring in the drawn balance of the new $250 million term loan, this translates to net debt of just 19 million as at September 30. This is an improvement of 53 million US dollars on the June quarter, with cash flows supported by the improved market conditions and our second-half weighted production and sales profile.
Key nonoperational cash flow items included capital expenditure of 22 million and the initial $5 million payment towards the acquisition of Moorvale South. These outflows were almost entirely offset by a $26 million refund received during the quarter following our successful objection to the stamp duty assessment from 2025 relating to the acquisition of Eagle Downs.
Total liquidity increased to 501 million US dollars at quarter end, providing financial flexibility to support the remaining $100 million completion payment for Moorvale South. Regarding the dividend, as Marcelo mentioned earlier, the board elected to defer an interim dividend in August given the uncertainty around Moorvale South, our second half weighted sales production profile, and the importance of maintaining our balance sheet flexibility.
Since then, we have gained greater certainty around Moorvale South, delivered a strong third quarter, benefited from improved coal prices, and received the Eagle Downs stamp duty refund earlier than anticipated, all of which have strengthened our liquidity position. Importantly, the decision to declare a dividend today reflects our ongoing commitment to disciplined capital allocation, balancing shareholder returns with the need to maintain financial flexibility as we progress our portfolio of development opportunities.
Future dividends will continue to be assessed in accordance with our dividend policy, taking into account prevailing market conditions and the group's capital requirements. Turning to guidance, we reaffirm our 2026 full-year public guidance with saleable production continuing to track towards the top end of the range.
While there are no changes to FOB cash cost or capital expenditure guidance, both are experiencing upward pressure, particularly from higher diesel prices and a stronger Australian dollar. For reference, year-to-date SGO index diesel prices have averaged approximately 150 US dollars per barrel, which is above the 120 US dollars per barrel assumed as part of our revised guidance range provided in the March quarterly report.
Notwithstanding this, operational cost improvements and hedging benefits, together with saleable production tracking towards the top end of the guidance range, have helped partially mitigate the impacts of diesel and FX. That concludes the prepared remarks for today's call.
I'll now hand over to the moderator so we can take your questions.
Operator
Thank you. If you wish to ask a question, please press star one on your telephone and wait for your name to be announced.
If you wish to cancel your request, please press star two. If you're on a speakerphone, please pick up the handset to ask your question.
Your first question comes from Christopher Creech with Morgans Financial. Please go ahead.
Christopher Creech
Hi, morning Marcelo and team. Thank you very much for your time this morning and well done on the results, especially South Walker Creek that had a really good result.
First question for you guys today is in terms of Poitrel, I noticed that you obviously called out the planned CHPP shutdown in July. Was there any other reason as to why there was a big deficit between I guess the usual ROM and saleable sort of production, the implied yield?
Was there I guess a bit of a delay in terms of coal mining? Was a lot of it back-ended or was it just predominantly the CHPP shutdown in July?
Marcelo Matos
Hi, Chris. Combination of things.
I think obviously the shut is one of the key reasons. As you said, there was a let's say a yield element of the saleable production number as well because we brought forward some of the primary feed in June, okay, by the end of the quarter.
There was a lot of higher yielding volumes washed in June with some thermal and a lower yielding products at Poitrel here at this quarter. I think as a combination, I think they were probably the key drivers of that let's say slightly lower saleable production.
There's nothing let's say unusually happening at Poitrel. I think the things are well on track.
ROM volumes are healthy. It's tracking at the top end of the guidance range and it's expected to finish the year strong and it's a bit early to provide guidance for next year, but we are actually expecting another strong year next year as well.
All going pretty well at Poitrel.
Christopher Creech
Yes, perfect. Then I guess jumping into I guess your full-year guidance, you guys have mentioned that you're maintaining your 2026 guidance and looking it towards the upper end.
With the ROM stocks you guys have got, you're going to have a pretty good run of it for the saleable production in the fourth quarter one would expect. You could potentially see, I don't know, potentially above the guidance if you guys have a good run of it.
Is there any production disruptions that are expected across any of your operations, excluding weather or things that you guys can't control? It should be pretty steady state across the operations in the fourth quarter?
Marcelo Matos
Steady state, Chris. No surprises expected.
Everything is nice and steady. It's been wet for the last 10 days, to be frank, a bit wetter than I expected.
I think as we get to the fourth quarter, we normally make assumptions for, of course, operating hour losses due to weather, and I think we are eating through those assumptions now and those allowances, but other than potential weather, we're not expecting anything to let's say to prevent us to achieve a good strong fourth quarter and finish the year towards the end of the top end of guidance at this stage. That's
Christopher Creech
no worries. If I could just sneak in just one last one.
In terms of Moorvale South, I guess what assuming that that gets completed in the fourth quarter and and everything's ticks gets ticked over on that one, does that change your your time frame for your potential FID for Eagle Downs or does that just is that potential I guess potential upside to the case rather than slowing it down at this stage?
Marcelo Matos
We are not slowing down the work streams for Eagle Downs, okay? If you look at Eagle Downs on a stand-alone basis, I think we are progressing.
I think it's a bit early to say if an integrated development would not, let's say, affect the timetable for an investment decision on Eagle Downs. There are things that we will need to look at if we were to let's say develop both on an integrated basis, especially if there is a potential in the future for us to have, as an example, two longwalls operating, one in Eagle Downs and one in Moorvale South, using the same conveyor infrastructure, drift infrastructure, and the like, on surface infrastructure.
I think obviously we need to get the keys. There's a bit of work to do in Moorvale South on this optioneering work and this integrated development view.
The reality is that Moorvale South will require approvals, there will be a work that will be required to not only get all the ecology and groundwater data to support submission of an EIS, but also of course supporting the development of a plan to be the basis of those submissions. From the moment we lodge an EIS down the track, I think that there's still quite some time to be able to get approval.
Reality is that even if they were projects developed on an integrated basis, there will be a few years until we can mine coal from Moorvale South, we will progress with the view of Eagle Downs on a stand-alone basis, but with Moorvale South as a potential optimized integrated development down the track.
Christopher Creech
No worries at all. Thank you very much for your time, Marcelo.
I'll pass it on.
Marcelo Matos
No worries. Thanks.
Operator
Once again, if you wish to ask a question, please press star one on your telephone. Your next question comes from Glyn Lawcock with Barrenjoey.
Please go ahead.
Glyn Lawcock
Morning, Marcelo and Shane. Just on the cash flow over the quarter, Shane, any feel for what the cost was for the debt program through the quarter?
Was that material?
Shane Young
No, not really. There was some fees associated with that refinance.
That was a few million dollars in that, which is pretty typical for refinancing of that nature, but nothing that sort of jumped off the page beyond that.
Glyn Lawcock
Yeah. When you say few, I've always grew up thinking that was sort of 5 to 7?
Mid-single digit?
Shane Young
Around 5. Yep.
Glyn Lawcock
Okay. Thanks.
Then just on the capex, obviously you're running well behind, 9 months in. Is there something you'd expect to catch up, or you've done a good job on being able to maybe save some capex or defer it into 2027?
Marcelo Matos
Glyn, it's a bit of a timing thing. I think Q4 will be a big quarter capex-wise, there'll be a bit of catching up.
I think we are now looking at being well within guidance. There's potential for us to actually be tracking more towards the let's say the mid to top end of guidance for a few reasons.
I think first obviously is FX, but another one, which is actually good news, is that the demucking at the new pits at the MRAMC area, or especially the G pit, where we actually already mining coal from, actually progressed really well and ahead of schedule. Actually we're going to get additional ROM this year that was not part of the original plan.
That's going to benefit next year as well, and if F pit demucking progresses well, I think it's good news. It's still within plan and with a strong Q4 capex-wise, but still within guidance.
Glyn Lawcock
No worries. Maybe just the last one, Marcelo.
You obviously gave us lots of detail around what happened in Q3 from a pricing perspective, but I guess since the quarter ended, we've seen a roll down in pricing, particularly the PLV. What do you think's happening now and how do you see the remainder of the year playing out?
Thanks.
Marcelo Matos
China's been driving the spot indices, Glyn. I don't think the story has changed.
If we look at it's still at the moment still cheap to buy seaborne coal compared to domestic prices, it is competitive. They are not being too active, though.
There is an expectation that there will be some improvement in Mongolian trucking volumes and even in domestic supplies. Those expectations are somehow reflected in the forward curve, which are looking at a slight backwardation towards the end of the year.
India is pretty quiet. India hasn't come back strongly buying post monsoon.
The PCI market, though, has been mostly driven by India, which is positive. I think the PCI relativities are good.
There's a general expectation that steel demand maybe a bit softer in China as we get to the winter months as well, which is somehow corroborates with this view of maybe some softening prices towards the back end of the year. Obviously weather is something else that needs to play out as well.
Everyone's expecting a drier wet period or end of year and summer in Australia, but October has already started wetter than expected. We will see.
Far, things are reasonably steady.
Glyn Lawcock
Yeah. Just a quick one on India then.
You just think what, they're just reluctant to pay the price at the moment, that or monsoon's gone longer, just your sense, or are they just holding out for lower price as they do?
Marcelo Matos
As they do. I think they're just quiet and holding, and as I said, China is driving that PLV market.
Normally, India drives the mid-vol market and they've been quiet. There's been some additional mid-vol volumes out of Queensland, especially out of the Moorvale North mine ramping up volumes.
They've been producing well. There's been cargoes offered and usually India are buyers of some of those mid-vol volumes, but I think they're avoiding aggravate the situation with China already driving this spot market.
They've been pretty quiet and running low inventories as they've been doing for the past 2 years.
Glyn Lawcock
Yep. No worries, that's great.
Thanks, Marcelo. Appreciate the color.
Marcelo Matos
No worries.
Operator
Thank you. Once again, if you wish to ask a question, please press star one on your telephone.
We'll pause a moment to allow for any final questions. There are no further questions at this time.
I'll now hand back to Marcelo Matos for closing remarks. Yep.
Marcelo Matos
Thank you for your questions and for joining today's call. I also extend my sincere thanks to all our employees and contractors whose hard work and commitment, particularly to safety, made these results possible.
We look forward to updating you on the fourth quarter and the full-year 2026 performance in the new year. Thanks, everyone.
Have a good day.
Operator
Thank you. That does conclude our conference for today.
Thank you for participating. You may now disconnect.