PagerDuty, Inc.
Q4 FY2026 · Earnings Call TranscriptMarch 12, 2026
Operator
Good afternoon, and thank you for joining us to discuss PagerDuty's fourth quarter and full year fiscal 2026 results. With me on today's call are Jennifer Tejada, PagerDuty's Chairperson and Chief Executive Officer, and Howard Wilson, our Chief Financial Officer.
Before we begin, let me remind everyone that statements made on this call include forward-looking statements based on the environment as we currently see it, which involve known and unknown risks and uncertainties that may cause our actual results, performance, or achievements to be materially different from those expressed or implied by the forward-looking statements. These forward-looking statements include our growth prospects, future revenue, operating margins, net income, cash balance, and total addressable market, among others, and represent our management's beliefs and assumptions only as of the date such statements are made, and we undertake no obligation to update these.
During today's call, we will discuss non-GAAP financial measures, which are in addition to and not a substitute for or superior to measures of financial performance prepared in accordance with GAAP. A reconciliation between GAAP and non-GAAP financial measures is available in our earnings release, which can be found on our Investor Relations website.
Further information on these and other factors that could cause the company's financial results to differ materially are included in filings we make with the Securities and Exchange Commission, including our most recently filed Form 10-K, as well as our subsequent filings made with the SEC. With that, I'll turn the call over to Jennifer.
Jennifer Tejada
Thank you, Christine, and good afternoon, and thanks for joining us today. Fiscal 2026 was a transformational year for PagerDuty.
We stabilized ARR in Q4 and accelerated new and expansion business, ending the year with solid fourth-quarter results. In our first GAAP profitable year, we continued to increase operating margin through disciplined execution while advancing our AI-first operations for mission-critical work.
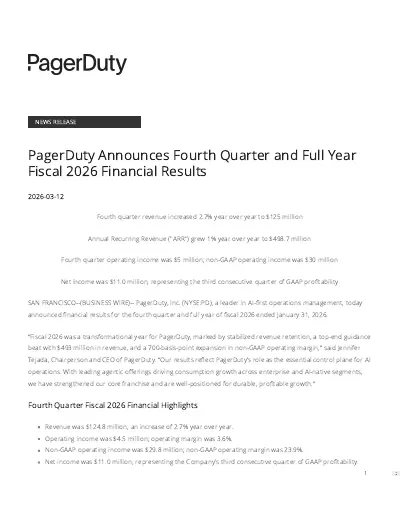
In Q4, we delivered $125 million in revenue, up 3% year over year, and 24% non-GAAP operating margin, both above our guidance ranges. Total annual recurring revenue ended the year at $499 million, with an increasing contribution from enterprise customers.
Throughout the year, we expanded non-GAAP operating margin by nearly 700 basis points through consistent discipline, structural efficiency initiatives, and AI adoption. We see a clear path to our long-term target of 30% non-GAAP operating margin as we increase our own operational AI leverage and drive our customers' consumption of our AI platform.
Leading growth indicators in the quarter were increasingly encouraging. Total platform customers grew significantly to over 35,000 total paid and free customers, up 14% year over year.
Improved conversion from both free to paid and total top of funnel led to over 600 new customers, including AI natives and enterprises, accelerating 17% year over year. These segments combined are high value and high propensity to grow.
We expanded with AI natives and AI-first companies like Anduril, CoreWeave, Snowflake, and Scale AI. Companies across the globe demonstrated deep trust in PagerDuty.
In EMEA, Banco Santander, Bupa, and Vodafone are just a few that expanded. Likewise, our APAC and Japan teams experienced success through strategic deals, including an expansion with JR East Railway Information Systems and one of Australia's largest banks.
New and expansion performance in the quarter was our strongest for the fiscal year, up 6% from the previous year and sequentially up 37%. Underpinning our Q4 new and expansion bookings momentum were large six- and seven-figure opportunities.
We signed over 40 deals worth $100,000 or more in the quarter, almost twice the average of prior quarters in the year, showing progress towards reaccelerating growth. By year's end, the cohort of customers spending $1 million or more in ARR has increased to 79, up 10% year over year, while 861 customers now spend over $100,000 annually, an increase of 1% year over year.
This segmentation is important. The modest growth in the $100,000 customers reflects churn in the mid-sized spend range, but double-digit growth at the $1 million range shows we're making real progress with our highest-value enterprise customers, exactly where we're focused for growth.
While seat-based compression continued to impact some of our install base, we're attracting customers that are higher propensity to grow on the platform with flexible consumption-led pricing. Our new pricing model makes it more compelling for customers to land new business and expand existing accounts on the platform.
As a result, in Q4, we secured several large multiyear agreements with new pricing. Our flex pricing enables frictionless scaling between human responders, agents, and automated solutions, as well as access to new products that are aligning value to business outcomes.
One of the world's largest toy makers was seeking resilience at scale after a $10 million loss in both revenue and costs caused by a manufacturing outage. In Q4, they signed a $4.5 million TCV multiyear renewal with PagerDuty, leveraging our flex pricing.
In North America, we signed a $2.7 million multiyear expansion with one of the world's leading telecommunications providers, more than doubling their ARR with PagerDuty. By aligning the platform with the customer's highest-priority challenges, driving cost efficiency across networks, and capitalizing on AI goals, PagerDuty is now their AI operations platform, addressing both enterprise efficiency and AI risks.
PagerDuty was built for a world where every business is digital, and every digital business at scale needs to anticipate and respond to urgent, critical operational challenges immediately, intelligently, and automatically. That need is not going away.
What is changing is that AI is the new operational risk layer for business, where resilience and automation are paramount. Customers must improve their resilience posture in a more volatile operating environment.
PagerDuty meets the rising standards for platform resilience that large enterprise and AI leaders expect. They trust PagerDuty because we provide the platform to solve these problems.
Incident response, while powerful, is no longer sufficient. Customers need an enterprise-grade platform that automatically and accurately detects and diagnoses issues.
Large enterprises and high-growth AI natives require resilience at scale to engender both customer trust and revenue continuity. PagerDuty provides an autonomous cloud-native engine for mission-critical operations.
By unifying incident, event, and service management, PagerDuty drives efficiency in high-stakes enterprise environments. PagerDuty's customers are consolidating their AIOps, alerting, automation investments into the Operations Cloud, reducing their need for high-cost service desks, people-laden operations centers, and multiple observability vectors.
Our AI value proposition resonates, and customers are doubling down. What differentiates PagerDuty as a platform for action is how we integrate agents, data, governance, teams, and workflows in real-time autonomous operations.
PagerDuty does the work for customers, dramatically reducing observability costs by eliminating noisy, duplicative alerts. Our platform acts immediately on the high-fidelity signals that matter, automatically and responsibly.
AI hyperscalers, including a large cloud and edge computing platform, a frontier large language model provider, and the leading unified data and AI platform provider, didn't just choose us, they expanded multiple times throughout the year. Likewise, AI startups like Decagon, Etched, and Rogo continue to scale on PagerDuty.
This repeat expansion is a compelling leading indicator that AI is a net tailwind as to how Ops Cloud and expansion consumption-based pricing drives growth. During the year, we expanded our relationship with a long-time customer, the world's largest digital infrastructure company.
They signed another seven-figure multiyear expansion, deploying PagerDuty's Process Automation as the central orchestration platform for their new global automation architecture. We won the business because the platform demonstrated both technical security and also met their stringent security and compliance requirements.
Our past innovation led to category creation and leadership in DevOps and digital ops. We're executing on a similar long-game opportunity pioneering the AIOps category for enterprise.
Once again, we have a deep moat: context. Competitors can imitate features or build limited agents on public LLMs, but without PagerDuty's decade-plus advantage of data, incident, and service context, they cannot reliably deliver accurate, high-fidelity, and resilient outcomes.
Our combination of historical incident data and AI agent context gives our customers the benefit of deep operational history and shared agent-to-agent memory in every response. Last year alone, our platform processed billions of events, nearly a billion incidents, and millions of incident workflows.
This proprietary context advantage, combined with our growing AI ecosystem, positions PagerDuty uniquely, especially in the large enterprise segment. Case in point, a global semiconductor supplier that is pioneering agentic automation selected PagerDuty in a landmark $1 million AI-driven expansion on a multimillion-dollar base.
More than half of the investment is attributed to our agentic capabilities as the customer transforms incident management to an AI-orchestrated workflow and also uses PagerDuty to streamline supply and GPU utilization. This deal demonstrates the dual AI opportunity we're capturing: our agents automate incident management, while PagerDuty serves as the control plane for AI operations more broadly.
Two different use cases, both mission-critical, both expanding. AI is the new risk layer for enterprise.
It's more complex, and it fails differently than traditional software. Our platform is designed for the unique scale and materiality of AI operations.
It automatically surfaces the relevant data and context to prevent failures before a human can even engage. We were first to market over 6 months ago with the capability of our Model Context Protocol server and agent-to-agent functionality, advancing AI orchestration to correlate events and drive automated actions.
Early adopters from complex enterprises like NVIDIA are using PagerDuty Advance to speed resolution. IDC's recent report on AI agents in IT service management names PagerDuty and confirms what we're hearing from customers.
Organizations prioritize AI agents that can reason, plan, and take action reliably, exactly what our forages deliver. By enabling customers to operate their critical AI investments, including models, infra environments, and agents, resiliently and confidently, our agents take enterprises to the next frontier of AI operations.
Our SRE agent now acts as a virtual responder for hundreds of clients. It resolves incidents autonomously, it learns from past incidents, it predicts failures, and it progressively automates work.
As these customers burn down their initial credits, ongoing consumption becomes a growth engine. Today, we announce the expansion of our AI ecosystem.
Our platform agents now seamlessly engage with leading AI native platforms and enterprise applications, including over 30 new AI partners. Three marquee partnerships demonstrate the power of the ecosystem in action: Anthropic Claude, Cursor, and LangChain.
Through these partnerships, PagerDuty handles increasing in complexity in customer environments, solves problems faster, and delivers a complete platform based on a level of intelligence no other competitor can match. AI is transforming digital operations to proactive operations.
Issues need to be caught earlier and resolved faster because the complexity, cost, and blast radius of AI failure is higher. AI workflows provide challenges only solvable by a platform offering real-time orchestration and operational maturity.
In fiscal year 2026, the diversity of wins across the AI ecosystem—infrastructure leaders, emerging startups, and AI-enabled enterprises—demonstrate PagerDuty is the operations platform for choice for AI natives to ensure their products scale reliably and responsibly. PagerDuty is the new control plane for AI operations in the enterprise.
In Q4, we strengthened our leadership with the appointment of Scott Aaronson to our board and Chris Farrell as our Chief Legal Officer to our executive team. Both bring functional and business expertise essential to our operational performance.
Our search for a new financial officer is progressing well, with several accomplished financial leaders in advanced stages of consideration. We expect to appoint a candidate in Q2.
In the meantime, Howard remains steadfast in his commitment as CFO and to support a smooth succession during the year. Our innovation and culture earned significant industry recognition again.
PagerDuty ranks number one in Built In's Best Places to Work list. Gartner named PagerDuty as a representative vendor in two recent research reports focused on AI agents for site reliability engineering.
This recognition reflects our position as a credible enterprise-ready platform as AI SREs approach mainstream adoption. PagerDuty now serves more than 650 non-profit organizations worldwide.
SIRUM, the largest redistributor of surplus medicine, uses our Operations Cloud to avail over $300 million in medicine to more than 500,000 patients across the country. Other leading non-profits across critical sectors, including emergency response, healthcare, and education, are leveraging our AI platform to schedule and strengthen their impact.
Throughout the year, we continued to invest in product priorities that drive long-term customer value: first, deepening our AI capabilities and integrating them seamlessly into the platform; second, expanding automation; and third, broadening the ways customers can use PagerDuty across their organizations. We see meaningful opportunities to extend our platform beyond its perception as an incident response solution into an AI operations platform for broader operational workflows like manufacturing throughput, network reliability, AI infrastructure utilization, and FinOps, to name a few, where urgency, intelligent orchestration, and accountability are critical.
As we look to FY27, our business priorities are clear: first, we continue to strengthen our core franchise, digital operations management, where our brand, scale, and enterprise trust remain significant advantages; second, we continue embedding AI and automation into the platform to drive better customer outcomes and increasing differentiation; third, we are expanding the role that PagerDuty plays across enterprise by addressing a broader set of urgent, high-value operational use cases, including AI operations; and finally, we do all of this with continued discipline, leveraging AI ourselves in our own operations to expand capacity and efficiency. PagerDuty drives enterprise resilience with a compounding advantage, where context drives better automation, agents take smarter action, and customers move closer to autonomous operations.
We made significant advancements in our platform and are optimistic that our reinvigorated go-to-market team continues to build momentum in new and expansion business while also improving gross retention. The long-term opportunity in front of us is compelling.
Modern organizations depend on resilient digital and AI operations, and that challenge is only growing for our customers. PagerDuty is positioned to successfully support customers and their leadership teams in navigating AI complexity, mitigating risk, and capitalizing on transformational growth.
As we enter FY27, I'm confident in our people, our strategy, our execution, and our position in the market. We have a category-leading platform, a proprietary data advantage, accelerated product innovation, and a go-to-market transformation that is bearing fruit.
FY27 is about scaling what's working and capturing that opportunity ahead. With that, I'll turn it over to Howard.
Howard Wilson
Thank you, Jen, and good day to everyone joining us on this afternoon's call. Unless otherwise stated, all references to our expenses and operating results on this call are on a non-GAAP basis and are reconciled to our GAAP results in the earnings release that was posted on our Investor Relations website.
Before reviewing our fourth-quarter and full-year financial results, I want to highlight the durability of our business model. We achieved our first full year of GAAP profitability, a testament to our operational discipline.
We expect to maintain full-year GAAP profitability in FY27. This financial strength allows us to return capital to shareholders while simultaneously funding our transformation.
In FY26, we repurchased approximately 10 million shares under our $200 million repurchase plan, leaving roughly $63 million of the authorized amount available at quarter end. Our consistent cash generation and a strong cash position allow us to advance our enterprise transformation and invest in AI regardless of the macro environment while returning capital to shareholders.
Moving to results for the quarter: we delivered revenue of $125 million, up 3% year over year, with international revenue increasing 6% year over year, contributing 29% of total revenue. Annual recurring revenue exiting Q4 grew 1% year over year to approximately $499 million.
Despite the macro headwind of seat compression in some of our customers, our enterprise strategy is working. Customers spending over $100,000 in annual recurring revenue grew to 861, up 1% year over year.
More importantly, the ARR from this cohort, including our largest, most strategic customers, increased to 72% of total ARR. Customers with ARR over $1 million increased to 79, up 10% year over year.
This shift toward larger, stickier enterprise relationships is central to our long-term growth thesis. Moving to profitability, GAAP net income was $11 million, our third consecutive quarter of GAAP profitability.
We're continuing our progress on the path to sustained GAAP profitability. Dollar-based net retention was 98%, impacted by lower gross retention as we had anticipated going into the quarter.
However, we have implemented specific programmatic renewal initiatives and strengthened customer management to reverse this trend. We expect gross retention to improve in Q1 with steady progress through the year.
Consequently, we expect DBNR to stabilize in Q1 and increase gradually throughout the year. Total paid customers grew to 15,351, representing a 2% increase year over year.
Free and paid companies on our platform grew to over 35,000, an increase of approximately 14% year over year, providing a healthy funnel for future conversion. Continuing with Q4 results: non-GAAP gross margin was 87%, exceeding the high end of our 84% to 86% target range.
Non-GAAP operating income was $30 million or 24% of revenue, compared to $22 million or 18% of revenue in the same quarter last year. The outperformance is not accidental; it reflects our rigorous focus on efficiency and operational execution.
In terms of cash flow, cash from operations was $25 million or 20% of revenue, and free cash flow was $23 million or 18% of revenue. This strong cash generation gives us the financial flexibility to invest in our go-to-market transformation and AI product development while maintaining our commitment to shareholder returns.
Turning to the balance sheet: we ended the quarter with $470 million in cash, cash equivalents, and investments. During the quarter, we repurchased 8 million shares for $99 million.
We view our current valuation as a compelling opportunity, and we are utilizing our cash position to reduce share count. On a trailing 12-months basis, billings were nearly $496 million, an increase of 2% compared to a year ago.
At the end of Q4, total RPO was approximately $449 million, increasing 2% year over year. Of this amount, approximately $314 million or 70% is expected to be recognized over the next 12 months, $106 million or 24% over months 13 to 24, and the remainder thereafter.
For the full fiscal year, revenue was nearly $493 million, up 5% year over year. Gross margin was 86%, in line with the year-ago period.
GAAP net income was $174 million; this includes a one-time income tax benefit of $169 million from the release of a valuation allowance. Operating income was $121 million or 25% of revenue, compared to $83 million or 18% of revenue a year ago.
This marks our fourth consecutive year of increased non-GAAP profitability, and we are closing in on our long-term non-GAAP operating margin target of 30%. Operating cash flow was approximately $115 million or 23% of revenue, compared to $118 million or 25% of revenue in the year-ago period.
Free cash flow was nearly $103 million or 21% of revenue, compared to $108 million or 23% of revenue in the year-ago period. In terms of metrics that we provide on an annual basis: ARR from customers using two or more paid products was 66%, up from 65% in FY25.
ARR contribution from incident management was 70% of the total, in line with FY25. Validating our enterprise focus, the contribution from our $100k cohort was 72%, up from 71% in FY25.
We have made sustainable operational progress by transitioning customers to flexible usage-based pricing and programmatic renewal management, which we expect to improve retention. While overall paid users on our platform increased modestly year over year, we anticipate that the macro trends around seat compression will impact some of our customers in the near term.
Our fiscal 2027 outlook reflects a prudent view of this environment. However, the early adoption of our Operations Cloud usage-based pricing and our new AI products gives us confidence that we will partially offset seat compression and drive gradual ARR improvement through the year as customers transition and scale.
Essentially, we are transitioning the business model to be less reliant on seats and more driven by consumption and value. As a result, for the year, the midpoint of our revenue guide represents essentially flat growth, but with a higher quality of earnings and continued margin expansion.
We're expecting modest operating margin improvements and an 8% increase in EPS. For the first quarter fiscal 2027, we expect revenue in the range of $118 to $120 million, with the midpoint essentially flat year over year, and net income per diluted share attributable to PagerDuty, Inc.
in the range of 23 to 25 cents. This implies a non-GAAP operating margin of 19% to 20%.
For the full fiscal year 2027, we are initiating guidance with revenue in the range of $488.5 to $496.5 million, with the midpoint essentially flat year over year. Net income per diluted share attributable to PagerDuty, Inc.
in the range of $1.23 to $1.28. This implies a non-GAAP operating margin of 24% to 25%.
Before moving to questions, I would like to provide assistance with modeling FY27. On cash flow, we expect free cash flow margin to be approximately 2 to 4 percentage points lower than FY26, primarily due to lower interest income, higher facilities CapEx, and timing of payments.
Our EPS guidance now incorporates a non-GAAP tax rate of 20% for each quarter of FY27. The fundamentals of our business are strong.
We have a durable balance sheet, expanding operating margins, and a clear strategy to navigate AI taking center stage. The go-to-market changes we've made, combined with our product innovation in AI operations, positions us to capture the significant opportunity ahead.
In FY27, we are laser-focused on steady improvement in retention, reaccelerating ARR growth, expanding margins, and achieving full-year GAAP profitability. I'm confident in our people and super excited about the future for PagerDuty.
With that, I will open up the call for Q&A.
Operator
Thank you so much, Howard and Jennifer. We're going to turn to questions from the analysts joined into the call.
We'll start with our representative from Morgan Stanley, Sanjit Singh. Sanjit, please go ahead.
Sanjit Singh
Thank you for taking the question. Jen, I wanted to get a sense on the flex-based pricing, the consumption pricing.
What's been the receptivity from your customers, particularly larger ones? They also want to solve for predictability, and so I just want to get the feedback on the receptivity to the flex-based pricing.
Then, as we think about this year, is there a way to think about what percentage of the base will be on the new pricing model by the end of the year?
Jennifer Tejada
Sure, thanks for the question. Flex pricing has been received very positively by large enterprise, and what I mentioned earlier, the strength of large deals in the quarter and the million-dollar-plus spend cohort growing in the teens, I think what is driving it is, one, those customers really appreciate the reduction of friction and access to new products.
By taking away the friction of counting heads or seats, they actually can go after new use cases. We talked about a large semiconductor provider that's using us in their supply chain environment and their GPU utilization.
We've had a very large manufacturer using us for manufacturing operations, and some of these really, really large enterprises that are somewhat asset-heavy are seeing opportunities to not just attack digital operations, but also traditional operations and AI operations, really anything that is software-enabled. In terms of the transition itself, you all have seen these types of transitions in the past.
The leading indicators give us a lot of confidence. Those leading indicators are large deals, ARR improvement through the year, gross retention improvement that we expect through the year, success with AI natives, AI-first companies, large enterprise, as well as new acquisition and expansion.
Those are the measures on which I would track our progress and how we're tracking our progress and moving through the base in that transition. At the same time, we're acquiring very attractive new customers that are expanding with us regularly through the year.
We've talked about large frontier LLM model providers, we've talked about native AI applications, some of the folks in the AI infrastructure space, but again, continuing to win in enterprise. Finally, what I would say with regard to the pricing transition, we're getting much more practice with it.
As we scale that through the sales force, we expect it to continue to improve.
Sanjit Singh
Awesome. Then just more broadly, I'd love to get the team's perspective on what's the best way to create shareholder value from here and the strategy for that.
I guess what I'm moving to is there is a view here that we're going to be focusing on our million-dollar customer cohorts, maybe get smaller from a customer base perspective, but focus on really just the high end and drive margins as you sort of laid out to the 30% over time? Or just want to understand what your view is on the best way to create shareholder value given where you are from a growth and margin, free cash flow?
Sure.
Jennifer Tejada
Revenue and dollar-based net retention are lagging indicators. The leading indicators around growth, particularly in the segments we care about, large enterprise, the AI-first companies, AI natives, which are new, but they grow fast, and they have a higher requirement for resilience and fidelity than the traditional software startups did.
We have a different moat in that segment than we had a traditional VC-backed software startups. Both those segments are important to us, and we see them as high value and high propensity to grow.
Make no mistake about it, we are focused on reaccelerating growth, but being selective in those segments that we think are going to return value to shareholders and help build sticky value in the company. At the same time, you can expect us to continue to execute with a high level of operational efficiency.
I think it's profitable growth. We're focused on the long-term opportunity around capturing this new category we believe is AI operations.
As I said, we have a lot of large enterprise customers that are still trying to get through digital transformation. They're not done with that and have moved on to all things AI.
They actually are still trying to move towards a more efficient way of operating digitally. We're very excited about the products that we have out in the market.
Frankly, software can be a little bit of a depressing place right now. There's a lot of people in Silicon Valley that are gloomy about the sort of rotation out of software.
We are fired up. We just launched our spring release.
We have PagerDuty on tour happening in London today, and it'll be rolling out to other cities. We're out in the market with real agentic products that work on a highly advantageous foundational data model that is very hard to replicate, and performing at really solid gross margins as well as improving our operating margin.
It's a long game. Like I said, you should really measure us and judge the progress that we're making, reaccelerated growth on those large deals, ARR improvement through the year, gross revenue retention through the year, success with those AI natives and large enterprise customers, and then the new logo acquisition and expansion where we saw a lot of momentum in the quarter.
Sanjit Singh
Appreciate the thoughts, Jen. Thank you.
Jennifer Tejada
Nice to see you, Sanjit.
Operator
Thank you. Next, joining us from CGF, Kingsley Crane.
Kingsley, please go ahead.
Kingsley Crane
Thank you. Hi, Jen.
Hi, Howard. Many of us saw the news earlier this week about the all-hands meeting at AWS related to reliability concerns in large part due to AI coding.
As enterprises are shipping faster, but with AI potentially breaking more, this seems like this should play directly into your strengths. The question is, I guess, where are customers at regarding that right now?
Has this dawned on them yet, and then has the impending onset of these issues affected how they view your strategic value?
Jennifer Tejada
I agree with you, and I've said this in the past, I'm going to keep saying it. With AI, the environments that our customers have to deliver products and services in are becoming increasingly more complex and less manageable by human beings, right?
Automation, automated detection, intelligent orchestration of issues and challenges, and auto-remediations becoming increasingly more important because human teams simply can't manage this scale. We do believe that is very much a tailwind for the business.
We are seeing that in some of these larger deals that we're doing. It's not well reflected in a seat-based pricing model.
The transition of moving to a platform model that also benefits from the consumption of more and more of our new products and easier access to those products across new use cases is important. That's where we're seeing those leading indicators, like new customer acquisition and expansion improving meaningfully from Q3 to Q4, and we think they will continue to improve over the course of the year.
To your point, when you ask where customers are, I would say there's still an underestimation of how hard it is going to become to deliver enterprise resilience that customers, regulators, and others expect. I was with a customer at a large global bank the other day, and they were talking about how they're trying to bring together both enterprise resilience, operational resilience, and technological resilience, and they have different manual efforts across all three, but they're sort of colliding as you see complexity enter every function within a business, cyber threats going up, et cetera.
Having a platform that can help manage all of that, but also get you to more autonomous remediation or recovery, I think is going to become increasingly important. In those large enterprises, they tend to want one strategic partner who's best at this, but also who can demonstrate resilience in the face of this complexity.
That's where we have an architectural advantage. We've proven over time that despite public service failures, significant failures in different parts of industry and different parts of the world, we're still able to provide for our customers what they need.
The business has just turned 16, we've never had a maintenance window. We've never said, "Oh, we're going to be down for the next several hours while we ship something new."
Howard Wilson
I think I would also just add to that, Kingsley, today we made an announcement around our AI ecosystem. Three of the partners that Jen mentioned in that are really focused very much on using the Model Context Protocol of agent-to-agent interaction or else even some of these products, whether it's Anthropic Claude or Cursor or LangChain, being able to ahead of code being deployed have it actually be tested for a risk score so that you're actually getting into the cycle of fixing problems before they happen.
That's really what PagerDuty is all about, is being able to help companies have the resilience that they need regardless of what stage in the life cycle the issue could occur. Those are really exciting developments, and the work that we've done around that AI ecosystem is because we recognize the need for the shift left, if you like, in the developer life cycle so that you can, in fact, build for resilience.
We're certainly well-aligned to that, not only when something goes wrong, but actually helping support the prevention of any issues.
Kingsley Crane
It's helpful. It does seem like reliability is getting harder to ignore.
Just one more just to bridge that into pricing, since you mentioned it, and was nice to hear that you signed several multiyear deals with flexible pricing. Just curious on pacing in the strategy around that.
Could you be more aggressive or is there potentially a wholesale shift away from seats toward a like-for-like consumption model? I realize that could be difficult to pull off.
Jennifer Tejada
We're not going to talk about timing per se because a lot of it depends on how customers demonstrate readiness to go. What was encouraging in Q4, coming out of our launch of flexible pricing in previous quarter, is that we're seeing large customers that might otherwise have downgraded based on their seat license requirements actually expand meaningfully because of the access to new products and services and the ability to allow different parts of the organization to deploy PagerDuty against new use cases.
We will be working very aggressively to get that in the hands of our larger customers. Then at the same time, I wouldn't say seats are entirely dead.
We have small customers that want a really simple pricing model, they want a way to be able to frictionlessly get on the platform and get going, and that's still available to them. What the flexible pricing platform has enabled us to do is start with the full Operations Cloud.
A big part of the draw, which is creating the leading indicator momentum there, is the fact that they're able to immediately get access to our agentic SRE, immediately access PagerDuty Advance, and start to get the benefit of the MCP protocol the server and the agent-to-agent engagement. The other thing that I would say is fidelity and resilience and the way our platform operates continues to serve us well in terms of creating a moat that makes it harder for smaller players or less technical players to come into the enterprise space.
We continue to invest in that as well. Our development team, and our infrastructure team is under a lot of stress to constantly deliver that high level of resilience.
What's different is we've seen small AI companies raise their standard because the trust around how their products and services work, making sure their AI doesn't drift, there isn't hallucination, it works the way it's supposed to, their agents are operating reliably, that is a whole new use case for the platform.
Howard Wilson
Kingsley, I'd make just a couple of comments because, as we mentioned before, with any pricing transition, we've been very thoughtful in terms of engaging our customers and understanding what their requirements are. Q4 was the first time that we were specifically targeting customers with our flexible pricing model, and the response has been really positive.
One, as Jen said, it's giving people access across the whole platform. Certainly the momentum that we're seeing there is strong, and that will be our first port of call in terms of how we address with large customers, how they expand and grow with us.
We anticipate by the end of this fiscal year that a meaningful portion of our ARR will be under the new licensing model. Perfect.
Kingsley Crane
Thank you.
Operator
Excellent. Thank you, team.
We do have some additional hands raised, analysts. I'll just remind you to be queued for questions, go ahead and raise your virtual hand in Zoom if you haven't done so.
Next from Truist, we'll hear from Miller Jump. Miller, please join us.
Miller Jump
Hey, great. Thanks for taking the question.
Howard Wilson
Hey, Miller.
Miller Jump
Hey. I guess maybe just pivoting to the go-to-market side a little bit, now we've had a full quarter with Todd as CRO.
I'm wondering kind of where we stand on execution changes there and kind of timeline to impact, and then if you could share anything on incentive changes for the year ahead. Thanks.
Howard Wilson
You're on mute, Jen.
Jennifer Tejada
The old "you're on mute" gets you every time. I'll start, and Howard, if you want to jump in, that's great.
I'm really pleased with how the go-to-market organization has really risen to the occasion here, both in embracing the new flex pricing model, because it's a big change, and really taking that to customers proactively, not waiting to be asked, in more programmatically getting in front of customers three, four quarters out around their renewals so that there aren't surprises if a customer is going through their own business transition and needs a different type of offering from us, and importantly, really focusing on large, strategic platform deals. You see that in Q4, really not just the ability to compose these opportunities with customers and find some of these new use cases, but to convert them and then build on them.
That transformation, which to some extent started before Todd, but has accelerated under his leadership, is something that I'm really pleased with. We are really trying to incent our customer success and post-sale organization to focus on gross retention while incenting our go-to-market organization to focus on growth.
You'll recall we also took our PagerDuty Online or what we would call our product-led growth business and moved it under Katherine Calvert, and that business is performing well. That part of our business is also driving a lot of the new logo acquisition by getting some of our new products and services in front of prospective customers right away.
I mentioned in prepared remarks we're seeing better free-to-paid conversion. The free numbers are up, but we're converting them more effectively, so that part of the funnel I think is performing better.
We're also converting new logos more effectively than we have in the past by having those two teams focused on different things, but moving towards improving gross retention over the year, improving ARR over the year, and continuing to build on the momentum we're seeing in new logos and in expansion. I would say we've put the organization through a lot of change, and I'm really proud of how the employees are rising to the occasion.
It leaves me very energized and encouraged, and frankly inspired. You can go on YouTube and see our SRE agent at work, our new products, our first-class chat experience that we announced in our spring release today.
They're all out there. You can watch them, they're real.
This is not something that we're talking about doing someday, and they're deeply integrated into the platform.
Miller Jump
I know I'm having a little bit of a connection problem, hopefully this comes through, but I do want to double-click. I know it's not at the high end, but the $100k customers that did churn off in that mid-level you've talked about, first of all, was that full churn or partial churn, and then second of all, do you have insight into where they're going to?
Jennifer Tejada
It's always a mix in that mid-range. You have some segments of the market that are under a lot of pressure there where headcounts are really coming down, and so that drives some of the seat-based downgrades.
Also, as a result of being under pressure, they become more and more price-sensitive, right? If they have more basic requirements, they can choose to go to a lower-cost provider because they don't care as much about the resilience per se, although I think that is starting to change.
We can be more aggressive there as well from a pricing perspective. We've got room in our gross margin, and one of the things we talk about is taking a more offensive stance there.
To be clear, I think the value to be had and the drivers of growth for the business are really around driving that platform into large enterprise and continuing to demonstrate that we are the operations platform of choice for AI natives and AI-first.
Miller Jump
Thanks very much.
Jennifer Tejada
Thank you.
Operator
Great. From RSCH AMRS, George Mcgreehan, please join us, George.
George McGreehan
Hey, it's George Mcgreehan on for Koji Ikeda at Bank of America. Appreciate you guys taking our question.
I wanted to kind of double-click on the expectation for gross revenue retention to stabilize. I guess could you maybe share any color you have in terms of how customer conversations are sounding regarding their hiring plans for this year?
Jennifer Tejada
Their hiring plans for this year will matter less and less as we move to more of the platform and consumption-based licensing. Interestingly enough, we have customers that are hiring software developers, we see the mix of software developers on our platform increasing.
I think the role is changing to some extent, but it's really less about what they're hiring for us and more about how do they prioritize enterprise resilience, how are they thinking about continuing to build automation? We're hearing a lot from customers wanting to shift left.
They want to go from simply responding to small events and minor incidents faster to preventing them from even consuming people's time. They're using, when I look at our usage metrics on the platform, more incident workflows, more events flowing through the platform, et cetera.
You can see that demand there. I would also say when I talk to executives, they're in a pinch, right?
They've got boards saying, "Use more and more AI," but they've also got their regulators saying, "You better use that AI responsibly." They're really looking for partners who can help them manage both delivering on that upside opportunity using AI in their products and services and internally themselves, but doing it in a way that's responsible.
When something does go wrong, they can minimize that blast radius, right? That is more of the kind of conversation that we're having.
When Todd came on board, he and I saw over 100 customers in his first 90 days here, and one of the things he said to me was, "Our customers want to do more with us." Continuing to consolidate things like event management, event consolidation, orchestration, automation, runbook automation, workflow automation, and now auto-remediation with our agentic solution is a big part of that strategy so they can start consolidating some of their operational requirements onto us.
The other thing is looking at those new use cases, and that's really been led by our largest customers saying, "I need to figure out how to solve this problem, and we'd like to solve it with you."
George McGreehan
That all makes sense. Kind of just as we move to consumption-based pricing and understanding that that's a smaller piece of the business today, but if you could maybe provide color on how underlying usage trends look for PagerDuty and maybe how that's contemplated in 2027 revenue guidance?
Jennifer Tejada
Howard mentioned this in his comments, our 2027 revenue guidance is conservative. Because we're going through this pricing transition, the leading indicators are somewhat clouded by the lagging indicators in that transition, and we're still operating in a pretty volatile macro environment.
We've tried to be really thoughtful about that. Coming back to your question around how does GRR improve over the course of the year, a lot of the work that we've already done is going to serve us.
One, moving customers to multiyear agreements means that we have less revenue available to renew in any quarter going forward through the year; two, giving customers the option of flex pricing and moving them to products and services that have a very clear ROI. When you start to actually be able to automate work that required people, teams, operations centers to do, it gets easier for executives to show the hard cost savings.
Then also, we're seeing this realization that resilience isn't just about mitigating risks of things going wrong and not responding to them well, but it's also about unlocking value and growth. That's certainly true for the AI natives and the AI-first companies that see if we can demonstrate trust in these products and services, we can sell more.
Howard Wilson
George, just one comment from me is why this pricing change makes sense for us and for our customers is because more work is happening on the platform. The amount of work that happens on our platform compared to our competitors, there's no comparison.
We do billions of events, we have nearly a billion incidents this last year, we do millions of workflows each month. Our customers are using the platform more, and often the discussions that we're having with our customers is that they, in fact, have had to make hard choices around headcount, but PagerDuty has enabled them to do so because we're actually doing more of the work for them.
We're automating work that was previously done by humans. Now, when we start showing them how they can use our platform more broadly, then they have opportunity to expand with us, but in fact generate incremental savings for themselves and get to better levels of resilience.
It's an interesting conversation that we've had, and the early conversations we've had with customers and the success we had in Q4 around the new licensing model have been super positive because there's a very clear correlation to how they're thinking about managing work in their organization, how they're thinking about resilience. I think we'll continue to just see momentum build around that transition.
George McGreehan
That's really helpful. Thank you.
Jennifer Tejada
Thanks, George.
Operator
Got me with those initials. Thanks for joining us from BofA, George.
One more ask for questions, feel free to raise your hands. Next up, we are going to hear from Craig-Hallum, we have Vijay [unclear].
Vijay Homan
Hey, guys. This is Vijay on for Jeff.
I just wanted to circle back to the go-to-market effort. Obviously, you guys have your leadership team set there.
I'm just wondering, should we expect to see any jump in spend commensurate with that sales motion or will the focus be on reallocating existing resources and potentially even seeing savings there?
Howard Wilson
Vijay, it's certainly a case of us reallocating capital. We still, as per our guide, looking at demonstrating improvements in terms of operating margin this next year.
We've done a fair amount of work with Todd and Katherine on the sales and marketing front around how we can be more efficient as a business, how we can leverage AI ourselves, how we're able to organize our teams to be more effective with a very clear distinction in terms of the responsibilities across those teams. We would expect to see, again, improvements in terms of sales and marketing efficiency as we go into this next year.
Vijay Homan
Great. Then just one more from me.
As far as enterprise, I think it was the second consecutive quarter number of customers with more than $100k ARR kind of ticked down. Obviously, you're alluding to some potential improvement in the coming year.
I was wondering if you could just elaborate and kind of the puts and takes in the pipeline there. Thank you.
Howard Wilson
Sure. I'll go first, and then, Jen, you can jump in.
What we do see within that $100k cohort, we obviously had some customers where there might have been a modest contraction, which took them down below the $100k mark. That has sometimes happened, particularly for maybe a mid-market customer who's ended up in that cohort and is now under intense pressure from a cost perspective.
At the same time, we have others that matriculate into that category. A lot of our focus has been, though, on the top end of that cohort, and making sure that we're putting in place contractual arrangements with our largest, most important customers in order to help them take more benefit of the platform, increase the value they're getting from PagerDuty, and typically in large multiyear deals.
What we would expect to see is that that cohort will continue to grow over time, but we certainly going to be focused and a lot more of our attention on sort of the larger six- and seven-figure customers, and how do we help them mature and grow at a greater pace.
Vijay Homan
Fantastic. Thanks for taking my questions.
Jennifer Tejada
Thank you, Vijay.
Operator
Thank you, team. Looks like that rounds us out for the day.
Appreciate your time. Jennifer, we'll turn it over to you for any final remarks to close us out.
Jennifer Tejada
Thank you. AI is the new risk layer for enterprise, and as the control plane for AI operations, we are well positioned to support enterprise resilience across our customers' strategic digital and AI operations, with both large enterprises and AI natives.
The leading indicators in Q4 demonstrate the momentum from new customer acquisition and expansion, our pricing transition, our product velocity, and expansion into cutting-edge use cases that continue to widen our competitive moat. We are energized by the opportunity AI presents for PagerDuty and confident in our ability to capture it.
Before I close, I want to take a moment to recognize Howard Wilson's leadership and his contribution to PagerDuty for nearly a decade. Together with our team, we built the company from a single product, $50 million in revenue, and a few thousand customers to the leading AI operations platform for enterprise, generating nearly $500 million in profitable revenue with over 35,000 customers.
While Howard has been our CFO since 2018, he's been a tremendous partner and visionary leader who has supported almost every function across our company at some point in time. His infinite passion for our mission, his advocacy for our customers as well as for our people, and Howard's unwavering integrity leave an indelible legacy and a strong foundation for us to continue building on.
His personal imprint in our business will continue to shine through the incredible team that he's built and the many capable leaders he has developed and mentored here. I know you all will join me in thanking Howard for his leadership and his stewardship of PagerDuty.
Thank you all, and have a great day.