CapitaLand Investment Limited
Q2 FY2026 · Earnings Call TranscriptAugust 13, 2026
Grace Chia
A very good morning, ladies and gentlemen, and welcome to CapitaLand Investment's first half 2026 results briefing. You can hear a lot of noise here because we have a lot of friends who are joining us here in person.
Before we begin, just please note that this session is actually being recorded. With that, once again, thank you so much for joining us this morning, both in person, as well as friends who are joining us online.
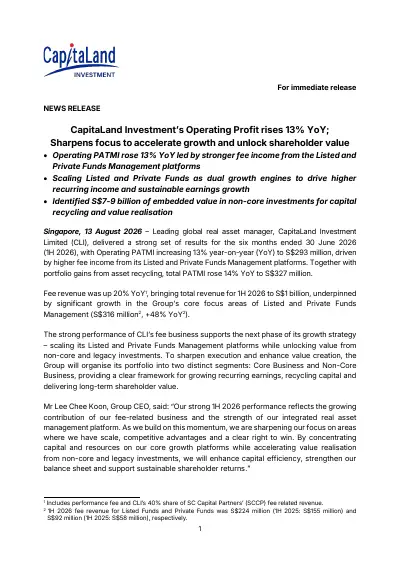
My name is Grace and I'll be moderating this morning's session. As you have seen from our results this morning, CLI has delivered a strong set of results for the first half, and this was driven primarily by strong momentum in our listed as well as our private funds.
Paul will have the pleasure of sharing with you details of our results after this. What's important is that building on this momentum, we are now sharpening our focus to accelerate growth and value creation.
For that, Chee Koon will share with you what are some of our strategic priorities and plans ahead, and we look to share more details with you in the coming months. Thereafter, we will open the floor for Q&A.
With that, Paul, over to you.
Paul Tham
Thanks, Grace. Morning, everyone.
It's lovely to see all of you today. I've been asked a couple of times about why I'm wearing a tie today.
This is my lucky tie, for those of you who don't know. We've had the best operating profit improvement in the last 5 years for us.
If you had seen us in '24, '25 was a pivot year, right? In '24 and '25, profitability started to go up, and we like to think that this year is an indication that that growth is going to continue, and that we should see this continuing in the going years.
I'm wearing my lucky tie to make sure I don't jinx anything today by being too positive. I'm going to go through our results fairly quickly.
It's fairly straightforward set of results, and then I will pass it over to Chee Koon. Let me just jump straight into the numbers.
Revenue for us is about flat. This is directionally exactly how we are trying to grow the business.
On the left-hand side, you see our fee revenue up 20%. This is the part of the business that eventually is supposed to form effectively what is CLI.
20% growth, particularly what you'll see is 50% of that growth or the growth rate of about 50% came from our private and listed funds, which is the part of the business which is really our two main engines which we're trying to grow. On the right-hand side, where you can see our real estate investment business, you would see that drop of 24%.
This is partly due to deconsolidations and divestments. Actually, the main driver was, as some of you may remember from our last results, we divested or deconsolidated a US corporate housing platform called Synergy out of our Ascott lodging platform.
The profit contribution from that entity was actually slightly negative, but from a revenue contribution, it contributed $134 million in the first half of last year. That's really the bulk of the big drop.
Actually, things are moving directionally exactly how we are hoping for on the revenue side. Similarly, on the profit side, what you can see on the left-hand side is profit for the operating side is up 13%, driven with the big uplift coming from the fee business.
I'll spend a little bit more time talking through the fee business on the next slide. It's been very good growth for us there.
The real estate investment business held steady. This was slightly better than we had expected.
We expect the real estate business to come down over time as we divest assets. We reduced our stakes in the REITs and we divested some assets, but the profitability held largely steady, largely from the fact that interest costs is down for us, we took some savings there, which helped uplift that, and we had a little bit of gains from some of the divestments, operating divestments.
On the portfolio gains, largely flat year-on-year. We expect this number to be generally as always around zero, given that we have divested a fair bit of properties over the years.
Going forward, we would expect this to be really slightly above or slightly below on a general run-rate basis. Then you can see total PATMI for us, first half of the year, up 14%.
On the fee income side, this was a large part of the driver for us. As you can see, going from left to right, particularly our two main engines of listed and private.
For the listed side, as most of it had a very good first half, very high transaction volume, more than $10 billion worth of transactions, and this was across multiple REITs and equity fundraisings. We had four of our eight REITs raise equity, and we had five of the REITs active on transactions in the first half, which was why there was so much flow.
To be fair, this is not fully a repeatable number, half-on-half, but we do expect that transaction activity, in general, we've seen this pick up for both the private funds and the listed funds. We expect that that will continue.
We would expect a lot of that 66 you see from the listed funds, a fair bit of that will convert into recurring income, so that will give us a little bit of an uplift going forward, but we do have announced transactions and more expected that will impact the second half of this year. Private funds had excellent revenue growth for us.
A lot of that came from the acquisition of Wingate last year. Private credit is now contributing quite materially to our revenue pickup.
We are quite encouraged to see that, together with our other funds also starting to perform. The second funds in multiple series that we've had, whether it is living or the Asia-Pac credit fund, also starting to contribute higher revenues, which is part of what has been driving that growth.
Then similarly, you'll see a little bit of one-off transaction performance fees. Part of that came from the fact that one of our India funds generated some significant carry for us.
We're very proud of that team. That contributed to the P&L for this half.
We would expect that there will be a little bit more in terms of performance fees and one-offs in the second half. It's a nice uplift, and some of that fees now includes from a Wingate perspective when we originate and structure deals, similar to the REITs, it forms a little bit of what we would consider an acquisition fee or a structuring fee.
Commercial management up 6%. Commercial management had some of their gains from improvement in leasing over the quarter and also improving property performance, which drove their management fees up.
6%, quite honestly, is a little bit faster than we expect them to grow, it was a very good first half, might moderate slightly, but good performance. Also, notably, our margins actually ticked up quite a fair bit from operational improvement and efficiency from the commercial management team.
Lodging numbers here look a little bit stable, but if you exclude the one-offs, a year ago this time, we had some termination fees, some sale of franchises, and actually some write-backs. Without that, we're actually up about 4%.
Lodging continues to grow. More importantly, as we talked through lodging is we are really building for the future on the lodging side.
As a profit contributor, currently it is less impactful than the overall value of the platform as it continues to invest for growth. Overall, strong first half for us, up 20% on the fee side.
On the real estate investment earnings, as mentioned, it held steady. If you look at the chart, what you will notice maybe are just a few things to highlight: listed funds almost completely stable, a little bit of movement because of accounting treatment on how we handle FX.
We think as long as we bring down our stakes, this contribution may come down slightly, but we are expecting from most of our REITs to see organic growth in their performance to help offset some of that stake dilution. Private funds contribution has increased, is expected to also increase going forward as we've been divesting some of our lower-yielding assets and reinvesting into credit, into value-add opportunities, and those generate a higher return.
For instance, we sold a Singapore logistics asset or industrial asset, we also sold some stakes down in China, those may have been contributing between 2% to 4% yields or 2% to 5% yields. For the new reinvested investments for us for the funds, generally, we would be targeting between an 8% to 12%.
Because of that, we expect we'll continue to see an uplift in this portion. Then for the non-fund investments, a lot of this is actually due to a single transaction where we sold one iPark in China, which is one of our last strata commercial assets, which was a legacy asset that we had previously.
It looks like a big movement on an EBITDA basis, but actually, as you saw from the last slide, on a profit basis, there is actually no change. The reason is part of this is accounting treatment for us.
We had to take some of the foreign exchange currency losses in the EBITDA performance, but when we show PATMI for the sector, we offset all of the deferred tax or the land appreciation tax provisions. Oddly enough, while it looks like a big decline, it was actually a slight increase for us in contribution from that asset divestment.
Finally, just on our gearing and debt levels, we still continue to have a fair bit of headroom. Most importantly for us, I think, is interest costs has come down.
We expect it to stay at this level or actually go down slightly further, hopefully that continues to improve for us. Then just very quickly, four slides on business updates before handing the time to Chee Koon.
On our four verticals, just to give you a little bit more qualitative update on what has been going on: on the private funds side, with Andrew and Kee Siew and the team, we've actually had a good first half on multiple fronts. We've seen good fundraising momentum, we're up $1.4 billion in fundraising.
If you combine it with what was raised for the public funds, we've raised $3.7 billion in the first half, which is 50% higher than where we were at this time last year. There's been strong engagement, I would say, particularly in the areas which we are building more and more credibility on.
Obviously, we've had the second raise in the living fund, CLARA II. We've had second raise in our Asia-Pacific credit fund.
We believe we will be able to raise a third fund off the back of that later this year. The fundraising momentum has been there.
The key for us really has been actually making sure that we can do the last bullet point, which is the deployment and looking for opportunities. As you can see, a number of the private funds have been active in living, in India, in logistics.
Deals are starting to move. While there has been fluctuations, I think, in near-term uncertainty, from what we've seen in the market, there is a little bit more confidence or a little bit more certainty on the long-term view, which has allowed a number of these transactions to move.
Then the last bullet point in the middle, we announced just 3 days ago, 2 days ago? 2 days ago about our China private REIT, our China P-REIT, where we raised $3 billion renminbi.
This is important for us in two fronts: one is this grows our platform in China, where we're very focused on still building a renminbi-for-renminbi business, tapping domestic capital to grow, but also this gives us also another avenue to recycle out of some of our legacy assets. As for this one particular mall, CapitaMall Luwan in Shanghai, you'll see that start to show up in our second-half numbers, but this will start contributing meaningfully for us for divestments.
We're still excited that Tze Seong and the China team have more divestments planned for the second half. On the listed funds, I won't spend too much time.
A lot of this is public information on the deal flow. What I would say is what we have been trying to do is, going forward, we would like to see the growth rate of our listed funds platform be faster than historically it has been.
Historically, we've grown at about 3% to 4%. This has been a core anchor for us.
Obviously, first half of this year was very strong, but our expectations is that we should be able to uplift that growth a little bit through multiple avenues. Obviously, our couple of big REITs are growing very well, but even our Ascott Trust, our India Trust have been active in the market as well.
Together with Japan Hotel REIT, which came together when we did the SC Capital acquisition, we expect that we'll continue to see across the portfolio more transaction activity and growth there, together with efforts to launch new REITs, hopefully the first one this year being the second C-REIT that will go out. We expect that this platform will be able to grow as well.
Commercial management, as mentioned, had a very good first half. I would say, as we look at our business going forward of our listed and private funds, commercial management is one of our strongest advantages, particularly here in Singapore, but also in Malaysia, in China, and India.
Something that, as we've been reviewing the business, we thought worth highlighting is if you look on the left-hand side table, we picked just the Singapore selection of assets that are managed under CapitaLand's commercial management team. If you look at the margins versus the market average, you can see that across every asset class, generally, we would have improved performance.
This is actually very important for us as a fund manager. This is one of our operating capabilities that we leverage and we share with investors, and it's one of the reasons they invest behind our funds and our REITs.
We think of commercial management really as a strategic contributor to the funds business for us. While the growth this first half was good, if it moderates or picks up depending on leasing activity, which can be a little bit lumpy for us, this is a very important part of the business that we expect will continue to grow and contribute.
Then finally, on lodging, lodging had a very good signings first half. As you can see, we signed 8,400 new units.
This is a pickup from the previous year, and this is added together with the pipeline of openings. Why this is important for us is while they don't immediately contribute revenue, which is why you have seen a little bit of a slower growth than usual from our lodging side, this builds our pipeline for future revenue growth.
It is one of the things that as an organization, we're able to underwrite that growth a lot more, knowing that the signings have happened and will come online over a 1- to 3- period depending on whether they're conversions or greenfields. We're quite excited for the future on the growth on the lodging platform.
Eventually, we believe we'll start seeing those numbers flow in much more nicely into the P&L. That is the quick update on our performance for the first half, and I'm going to pass this to Chee Koon to talk about how we are looking ahead.
Lee Chee Koon
Hi. Morning.
Thank you, everyone, for joining us this morning. Thank you, Paul, for, I hope, a pretty concise but clear presentation.
I think the results are encouraging, at least for the team. Shows that the efforts last few years in laying the foundation and transforming the business into an asset manager's paying off.
Last year, we have a good fundraising momentum. This year, it continues.
Really, we want to position the company for growth. Again, the large part of our growth today is driven by the REITs business.
We have eight REITs today. Obviously, the big REIT, CICT, CLAR, always running at the front, driving a lot of transaction, and we believe that that will continue to be the case.
We have a handful of smaller REITs, and we want to take a more active approach as a sponsor to work more closely with the various REIT CEOs to see how we can help to improve the returns to all unitholders and see how we can narrow the gap if they are trading below NAV. This is something that Paul has explained about in terms of the possibility and the potential, and we spend some time talking.
In fact, having even had the chance to brief my REIT CEO, I have conveniently asked Paul to help me look after the REITs to drive the REITs growth in a very concerted and dedicated fashion going forward. Paul, thank you.
He has to be accountable for what he says, right? Yeah.
Then moving on on the private funds side of the business, most of you who track in terms of the asset management, fund flows to real estate generally has been low. Even then, I think we are doing relatively well.
I think what we want to do on the real estate side of the equation is to really focus on strategies that we can scale, make a difference, where we can do repeatable strategies, things like living, hospitality products, our commercial management, office, retail that continues to be something that we are strong at. Of course, you can't be investing everywhere.
You need to be very selective in terms of the locations, and also to leverage how to work more closely with the REITs platform. Actually, a number of GPs and LPs are stuck with a lot of their real estate positions, that cannot find liquidity.
The question is, how do the private funds team work closely with the REITs to offer liquidity, of course, for assets that we like, for portfolios that we like, provide liquidity, and then allowing us to build up the private funds at the same time? That's how we are thinking about the private funds.
Real estate itself, the flow will continue to not be strong, simply because a lot of capital is going to tech, AI, and because of interest rates is not going to be strong. What we need to do is to look at the capabilities that we have, the operating platforms that we have built up in the company.
For instance, Pat has built up a very interesting self-storage platform. We are one of the leading players in Asia.
We are looking to broaden that in other parts of the world in active discussions, both in terms of opportunities and with LP. I think that's one area that we can leverage on operating capabilities, together with both assets and operating capabilities, to raise AUM.
That's one sector. The other sector will be in terms of data center.
Data center, it's all the craze everywhere, especially in the US. We have built a distinctive advantage in terms of our data center platform in India.
Kee Siew is helping to look at that ability to get access to land, to get power, and building up quite nicely. We're actually wanting to convert that into a platform where we can bring in partners and to raise capital around it as well.
The other platform that we look at could potentially be our India logistics platform. Very interesting platform that is supported with a strong JV partner.
I think there's an interesting opportunity for us to convert that into a platform and to really scale up very significantly in India. Of course, we spend some time talking about Ascott.
Ascott has been a key pillar of our operating platform for CLI. It's helped us to build Ascott REIT.
Nice platform allowing us to create private equity funds. That's a platform that we believe can potentially be created into a different products or look for ways to bring in partners to monetize the value and to continue to support its growth.
The fee income is growing nicely. I think these are things that we will be looking at in terms of driving the growth of the business.
Of course, the other part that is getting quite interesting is the credit side. When we looked at it, we knew that the real estate side of the business was going to be slow, and that's why we bought the Wingate platform in Australia, have a team, and managed to convince Kee Siew to join us.
He has a very exciting growth plan in terms of our credit, our alternatives side of the business. We will find a time to share more details in terms of the growth plan for the different business verticals, maybe sometime in Grace, when is that going to happen?
Oh, you'll let them know. Okay.
Anyway, she's finding the time, where we will find a day where we will spend some time to go through all the different growth plans over the next few years. Then you can see the growth trajectory.
Really, we are positioning the company for growth. We do understand that flow into the real estate will be slow.
It's a cyclical issue. In the meantime, we need to look for different growth platforms and opportunities so that we can continue to drive the fee income for the group and for our investors.
Then, just taking a step back, if you look at CLI, we did the transformation in 2021. We still have a pretty big balance sheet because a lot of these are legacy balance sheet assets, joint venture funds, development funds that were created during the time when CapitaLand was still a developer.
The way we are going to organize the business is into a core and the non-core side of the business, where the core side of the business really focuses on the REITs, the private funds, and supported by our operating platforms. Then the non-core side, some call it non-core, you can call it legacy, will be a lot of our asset stakes in the REITs, the private funds, and some of our legacy balance sheet assets in markets like China and some other markets that we want to focus to accelerate the divestment of these assets so that we can recycle the proceeds either for growth or to return capital to shareholders.
That's really how we're going to organize ourselves. During the time when we meet all of you during the Investor Day, we will spend more time to explain to you how things will look like and flash out a bit more details in terms of the numbers.
That's really the gist of the key things. In terms of driving the divestment for China, I think the China team has done well.
I think we are probably the only player that has raised Panda bond, that has created a C-REIT in the process of launching the second one, a private REIT, and a dedicated China-for-China private funds, and then creating different channels for us to recycle some of the assets in China while growing the asset management side of the business. That initiative, we will continue.
It's something that we are well positioned to tap the domestic capital. We want to grow the fee income.
It's a big market. There are some older balance sheet assets that we do need to clear, and we will be very disciplined about clearing them, redeploying the proceeds into, I would say, higher-yielding and more better returns opportunities for the group.
That's really setting the stage. Then, maybe I get the rest of the colleagues to join us just to take questions from the audience.
Grace Chia
Thanks. Thanks, Chee Koon.
As Andrew, Kee Siew, and Kevin take their seats upfront, just a reminder, we're now in the Q&A session. For those of us who are here, there are microphones.
Yes, I see you. Number one, number two, number three.
There'll be microphones that'll be passed around. Please state your name and the organization.
For those of us who are joining online, please key in your questions in the chat box, and then likewise state your name and your organization, and we'll take the questions. Mervin, you get to go first.
Mervin Song
Hi, Mervin from JPMorgan. Congrats, Chee Koon and team, on excellent set of results.
Good end to your 5-year journey, or close to 5-year journey, with the demerger with CLD. I'm sure a lot of hard work to deliver this very strong results.
Maybe you can go to slide 15 in terms of the non-core businesses. That $7 billion to $9 billion divestment target, I'm not quite sure whether you can share with us time frame to deliver on that, and in terms of capital allocation, is there a percentage that you may want to return back to shareholders via the dividends or buybacks?
How are you thinking about that? In terms of the non-strategic holding in REITs, what does that exactly mean?
Is it for some of the REITs where you're not quite sure about the growth, or you want to pair down to 15% or even lower? If you were to pair it down, are we thinking about in specie distribution or you like to do a block trade via excellent JPMorgan trading team with attractive commissions?
Those are my key questions. Thanks.
Paul Tham
I will leave the time frame part to Chee Koon, because that puts deliverables on all of us. Maybe just to share a little bit on the numbers.
The majority of the $7 billion to $9 billion that we see as embedded value is largely balance sheet and legacy fund investments for us, which form the majority of that. While obviously a large part of that's in China, that also includes other assets we have in the portfolio, whether in Singapore or in India or in Europe, which we would like to divest as well.
It does include some of what we would consider excess REIT holdings. I don't think this part is any new to any of you.
We have always talked about holding about 15% in our REITs. For Ascendas REIT, we already are at 16%, I don't think that's a big change.
It's just that if you look at our $8 billion of REIT units, if we were to average about 15%, that would bring us down to $6 billion. There's a couple of billion there that, in theory, that can be returned.
I would say we have not quite landed on how we will use that capital. Our expectation is at least half of that would go into reinvestment for growth.
We believe there are a lot of opportunities, whether in living or in credit, where we can invest the money behind for growth. Obviously, from a CFO perspective, I'd like to pay down some debt as well.
I would imagine at least a third is something that possibly could be a return to shareholders. I don't expect us to do a distribution in specie very much, quite honestly.
We find that it is something that we considered, but generally there is such a long period where the DIS gets announced and holding period. We have obviously done block trades on several of our REITs, and we only do big blocks.
We don't like dripping into the market. To be fair, if anybody would like to buy $150 million or more of any of our REIT blocks, that's the type of size where we are a little bit more agreeable to.
We're not looking to do anything that would harm the REIT share prices, right? If we see impact on the REIT share prices, we're not in an urgent need to divest.
I do think that, together with the REIT units, but more the bulk of what we have on balance sheet, it does give us a good opportunity to have capital for growth and really for a return to shareholders.
Lee Chee Koon
In terms of timing, I think we will share more during the time when we meet the investors. Give us a bit of time.
We're going to set up a dedicated team just to look at selling down our stakes in the funds, the balance sheet, including some of the smaller, subscale strategies that were formed, because we just want to focus on the company on doing the big, scalable funds, the strategies where you use fewer head count, do much bigger transactions. The encouraging thing that we are having today is we are in conversations with interesting LPs that want us to focus on deploying capital in a meaningful way on dedicated strategies.
We need to make sure that we channel all our resources and to really sunset on the smaller strategies and to focus on things that give us to build repeatable bigger strategies, higher margins, that can have better flow-through to the bottom line. Yeah.
Give us a bit of time just to come back to you with the details. Yeah.
Grace Chia
Derek.
Derek Tan
Good morning, Derek from DBS. I guess I've got two questions.
First question is on Ascott, Chee Koon. Just your thoughts on the fact that I see Ascott as key to the group.
Just wondering whether, as part of our value unlock strategy, do you need to hold 100%? That's my first question.
Then my second question is, as you pivot to growth, and you also want to sell, are you a seller first or a buyer later? I was just wondering whether, in this environment, how do we balance between the two?
Buyer of new platforms or
Lee Chee Koon
Your second question again, just so
Derek Tan
Are you a seller first, unlocking value first in your next few steps in your strategy, or you concurrently looking at new platforms to buy? For new platforms, are you more interested in FUM or operating capability?
Just two thoughts around that.
Lee Chee Koon
When we look at new investment, it has to make sense. It has to deliver ROE and be accretive to our investors.
Today, if you ask me the place that we are most ready to give a lot of capital to is things like on the private credit. It's easy because, to be honest, the deals that we are looking at, generally we are very comfortable in terms of the underwriting.
The returns are more than 10%. To us, it's quite a no-brainer that we can deploy our balance sheet even significantly, even if we cannot raise third-party capital.
The unfortunate thing is every time we have oversubscription. We have difficulty in deploying more capital to Kee Siew even if we want to, because the returns are good and he can share more with you later.
We are not opposed to getting operating capabilities that can help to drive our FUM growth. In terms of platforms today, we will be selective.
It has to make sense. It has to be accretive.
Today, there are many platforms that, except for the big, big GPs, there are many platforms that actually, I think, are struggling in terms of fundraising. Multiples for many of these platforms are still high.
The question is, do you want to pay multiples for platforms that are no longer raising capital? We want to be careful about that.
Yeah. In terms of divestments, I think the discipline is as long as we can recycle the capital, I think, at a fair price, I think we want to prioritize to get that going, because the capital that's unlocked, if we can redeploy it for better investors or even returning the excess capital to shareholders, I think these are good options that we have.
We just want to be very disciplined in terms of the use of capital. Yeah.
The conversations that we have and the ability we believe to be able to raise bigger funds also means that we don't need such a big balance sheet. Yeah.
We can be a lot more capital efficient in the way we run our business. Yeah.
Because initially, when we first started in 2021 to do this asset management journey, we were confronted with interest rates that were rising, Ukraine war, and a slowdown in China. Suddenly making fundraising so difficult, we really had to work very hard to convince people why they want to work with us.
I think that journey, that difficulty is over, is behind us. That's why we're a lot more confident that we can run with a much smaller balance sheet than needed going forward.
Yeah. You mind if I Yeah.
Kishore Moorjani
You raise a very interesting question, Derek, about acquisition of FUM versus operating capability. For me, I would take the latter in a heartbeat.
For the reasons that Chee Koon mentioned on the FUM side, FUM is expensive now, and if you're paying a forward multiple, you have to be confident that the ability to continue to raise FUM is there, and we question that ability. We're being very circumspect about acquiring FUM, and I think that's the right discipline we should have.
The question around operating capabilities is an interesting one. If you look at the sectors that we have chosen to focus on because we believe that they are secular tailwinds—hospitality, living, logistics, self-storage, commercial—I'll
Andrew Lim
defer to Kee Siew on the alt side, but on the real estate side, all five of these sectors require operating capabilities in order to generate alpha for investors, and our LPs are telling us this very clearly. If you're heading into an environment where your LP capital is increasingly discerning and careful about how they are deploying capital, as a GP, your ability to demonstrate platform alpha, to sweat your assets, bringing operational expertise to the sectors that we have chosen to invest into, is to me a fundamental ingredient in our narrative to LPs and our right to play and right to win.
If you look across our sectors now, we've got two phenomenal, if I may say so, in-house groups: lodging management and commercial management. Lodging management ties very neatly to what we are trying to do in hospitality and to a secondary extent in living.
Commercial management is hand in glove with everything that we're trying to do on the commercial side of the house. As Chee Koon mentioned earlier, we've now got investments in interesting logistics platforms, I think we can do more, and we've got interesting platforms in self-storage.
There is a logic behind what we are investing into, and to your question, where do you see us looking to deploy some of this capital that we're going to recycle, I would certainly expect us to invest more heavily into platforms that can help us deliver that alpha to LP capital, more so than FUM.
Lee Chee Koon
Sorry, I forgot to answer your question around Ascott. Kevin reminded me.
I was not trying to avoid that question. Ascott is growing very nicely.
We actually have different inquiries from investors, LPs wanting to participate in the growth of the platform. It's asset-light.
The fee income is very rich. We will be open-minded to look at this, because there are interesting M&A opportunities that Kevin is looking at.
From a CLI, if we are an asset manager, do we need to think about whether we want to fund all the M&A on our own or we bring in LPs that can help to do that and drive the platform growth in a much more efficient manner as well? Some of the LPs that participate in the platform or investors that participate in the platform could be investors in our lodging or hospitality funds as well.
It has to be a win-win when we look at some of these opportunities. Yeah.
Grace Chia
Joy.
Joy Wang
Hi, Joy from HSBC. If I may just follow up on Derek's question and just this discussion on platform.
You have certain platforms like Ascott that sits at the group level, and you have platforms that sits at the fund level. What is the ideal sort of construct, you think, from a platform?
As a group, do you want to own all the operating capabilities over time and then raise capital below you, or you do want to monetize your operating capability as you build that?
Lee Chee Koon
I don't think there's a one-size-fits-all. It depends on the opportunities.
We have a data center operating capability, which I would say that is an advantage in India. Can I say that our data center capability is one that cuts across to the developed markets?
I would say no. That's an advantage that we have, and we need to focus on how do we organize it to bring in the capital, grow the AUM, that makes sense.
There's no one-size-fits-all. We need to be look at where's our strength, what does the market want, because you also have to listen to the LP, and we need to match it with the capabilities that we have.
Yeah. Kee Siew, you want to add?
Kishore Moorjani
I was just going to add, Joy, there's a couple of really good examples that bear this to life, right? Chee Koon mentioned AFS in India, which is our industrial logistics platform.
By any metric, we're probably number three in the market. The largest player is probably going to go public or trade any day now.
We look at that as very clearly going from assets to a product to a platform to monetizing for our investors, right? Even if we exit that at some point, the IP that has been created and our ability to build and create value and monetize that, that track record is more important to us to redeploy either in the same or different asset class.
Same thing in data centers, right? It's going from assets to product to platform, and again, it'll be very targeted where we have real ability to scale and to win.
I think on data centers you'll see us, both AFS and data centers, you'll see us in the next couple of months come up with clear pathways to how we're scaling that, but that also sets a longer-term roadmap to how we're actually then going to monetize that.
Joy Wang
Thank you. I have two other questions.
One on fee. Very glad to see the fee growth.
Are we at the stage where we can comfortably start to underwrite double-digit fee growth going forward, as your carry and event-driven start to be a meaningful contribution? The second question is on balance sheet.
Chee Koon, you say you don't need such a big balance sheet. Is share buyback still not a topic that we want to talk about?
Thank you.
Kishore Moorjani
All right, I will answer the first question. Chee Koon knows my views on share buybacks, I will let him answer that one.
On the fee growth, I think if we're talking about the revenue line, yes, absolutely comfortable on double-digit growth. We are still investing behind a couple of our verticals.
Private funds, lodging, we are still investing behind for growth, may not contribute directly into a P&L double digit, but we certainly hope to be there on that component. We also need that the fee business to grow faster than historically it has because it's making up for the drop in our real estate investment business.
Certainly, from a revenue viewpoint, double digits. Profit contribution, we hope so.
Lee Chee Koon
In terms of share buyback, I think the important thing is what we look at it is when we recycle capital, we work with a much smaller balance sheet. If we can find interesting growth opportunities, to me that's always the priority to deploy.
If there are not enough good opportunities, our preference is to be able to return money to shareholders through dividend. We are not saying that we are not prepared to, but it's just a means of you do it.
Whether you do a share buyback or you do dividend, our preference is if we don't invest, we prefer to give more back to shareholders via the dividend route. Yeah.
It's just giving back to shareholders, but in different ways, yeah.
Grace Chia
Maybe we go to Rachel behind first.
Hi, good morning, Chee Koon and team. Congrats on a strong results.
Maybe first question on me, could you give us some color in terms of how you envision your geography split to be after all these unlocking value and stuff? More details on this $7 billion to $9 billion split by geographies, how much is actually from China, how much is actually from your private funds?
Just to give us some color on that.
Paul Tham
I would say about 2/3 of the $7 billion to $9 billion comes from China, about slightly less than half, maybe 1/3, sorry. About 30% to 40% comes from our private funds.
The remainder is balance sheet and excess holdings in REITs and platforms. In terms of overall geographical split, I think the longer-term goal for us has not changed.
The idea is that we don't want more than 20% exposure to any market. We would expect, as we look at the different growth markets, we would look to increase in Australia, in Japan, in India.
For the other markets, generally the guide for us is about 20% or less, with the exception being Singapore, where obviously we have more exposure and this being our home country, we're more comfortable with that.
No Europe, US?
Paul Tham
We have about $10 billion of investments in Europe and US right now. I wouldn't say we are excluding growing further there, but our focus is still primarily Asia.
Lee Chee Koon
In Europe, if there are interesting platforms to acquire, we will, if it makes sense, and has to make us competitive in subsequently the fundraising and to be able to create more opportunities. US, we always like US.
It's a deep market. It's a big market.
The issue is they're so competitive. You need to find the right opportunity and the right entry point.
At least when you go in, you're going meaningfully, and you can compete with the big boys. Otherwise, you don't get access to the deals, you don't get access to all the capital, then you just have a platform that can't compete.
Those are the considerations. Yeah.
Okay. Then my next question is really looking at divestments.
I think you have done the China private REIT, right? Potentially a C-REIT II in second half.
Should we look at this divestments to think about your special dividends at the end of the year, 1/3 from coming out from this? Or should we expect more divestments in second half of the year?
Paul Tham
We're certainly working towards more divestments over the next few months. I would say besides China, we are looking at other assets that we have, which hopefully will go out later this year.
I think in terms of capital return, it is something that we are still working through. Whenever Grace comes up with that date, which she doesn't want to share, I think we will be able to share a little bit more specifics on the plans going forward for growth and also for return of capital.
All right. Thank you.
Lee Chee Koon
We hope that during the Investor Day, we can tell you where are the growth sectors, how we're going to be deploying the capital, you have at least a line of sight of what we hope to do, and then how we are thinking in terms of the dividends and all. These are all questions, I know investors will all be asking.
We hope to give clarity by then. Yeah.
Grace Chia
If you don't mind, we'll do Brandon first behind, then we'll come back to Shen.
Brandon Lee
Hey, thanks. Brandon here from Citi.
Just three questions. The first one would be, for the $7 billion to $9 billion, right, can you give us a rough estimate in terms of impact to core PATMI and also the NAV on that 12.5 billion, and also on your earlier forecast of this mid-single-digit growth?
Basically, by doing this $7 billion to $9 billion, what kind of impact will we see on that? That's my first question.
The second question relates to the pace of divestment, especially for the 2/3 of this $7.9 billion. Obviously, we have seen CLI being pretty aggressive and forthcoming in guiding us that you guys want to sell China.
By bracketing these China assets into $7.9 billion, this time around does it mean that you are going to be more aggressive? How can we be assured that this time around you're going to be executing this divestment faster than before?
Yep. My last question would be with regards to the 3% to 4% AUM growth on the REITs.
Any guidance on how you're going to achieve that, especially for the REITs outside of CLAR and CICT? Yep.
Thanks.
Lee Chee Koon
Brandon, maybe I clarify. We want to accelerate the divestment of our China legacy assets.
We still want to grow our asset management business in China. There's still a lot of capital, domestic capital, C-REITs and P-REITs that we can do, that can help to drive the fee income for the group.
There are legacy assets in the past from the development funds that we want to accelerate. It's not that we want to sell China.
I just want to clarify that part. Okay.
Yeah.
Paul Tham
In terms of earnings split, I would say when we look at the $7 billion to $9 billion, and obviously we still need to refine and come through and we'll share more on the numbers during Investor Day. Generally, the core platform, I would say, contributes 75% of our earnings.
That 75% of earnings has been growing at a much faster rate, right, because that's the part that we've been focusing behind: the listed and private funds, including the China private funds business. That growth rate actually is much stronger than our base rate.
I think, as you mentioned, the challenge for us, which we want to do, is we want to be able to divest the legacy portfolio in the right, orderly manner that gets us the right amount of capital to reinvest into growing that core business.
Lee Chee Koon
Brandon, if you look at what happened in China, the real estate market started to slow in the last few years, but at the same time, you see the authorities being constructive in creating a channel for C-REITs, and then allowing private REITs, and more recently, I think for some of you who have been following China closely, Shanghai government announcing the preliminary ideas in terms of land tenure extension. China is a big country, and they want to make sure that things are organized in an orderly fashion.
All these are, I would say, a positive signals that would allow investors to find ways to properly exit. It's just the way the market is.
I think that the team has worked very hard in getting the regulators to first form the C-REIT, and now we are trying to get another C-REIT going, and then with the P-REIT, and that creates a different Now the vehicles are there, it allows us to do things a lot faster. The difficulty is creating the vehicle, because of the conversation with the authorities.
They want to make sure that things are orderly, it's fair to all investors, and because things are new, it just takes a longer time. For CLI today, I would say that our reputation in the REITs market in Singapore is established because we have been around for the last 20-over years.
It takes time, right, to build up the portfolio, constantly doing the right things, and that's why people continue to invest with us. It's the same thing that I think the capital market is going through for the real estate sector.
Yeah.
Grace Chia
Paul, there was the question on how we're going to drive growth in REITs. You want to take that?
Paul Tham
We are looking at a few options. Obviously, the REITs team has done a good job, and we've seen the different REITs grow, particularly this first half.
We've seen a lot of movement. I wouldn't say it's just the big REITs.
Actually, we saw transactions from Ascott Trust. We saw transactions close for CLINT as well and equity fundraisings.
I think across the board, it's been positive. We are looking, from a sponsor viewpoint, how can we strengthen that growth.
I think there are a few ideas that we are considering. One is, I think Ervin put it best, we are looking at the idea of short-term warehousing for rebuilding the sponsor pipeline, working with the REITs so that they can find DPU-accretive acquisitions.
Some of that, potentially we can do in a short-term warehouse to help them with that, so that when they go out for their equity fundraisings, it's DPU accretive. We are also looking at coming alongside some of our REITs for larger transactions, and both so that it's more workable for them, the size is more manageable, but also so that it creates a pipeline for them and potentially for some of the things in a portfolio that have been maybe less ideal can be exited.
There are a number of options we are looking at. As Chee Koon mentioned, this is not something that we have yet spent a lot of time working through, but that is certainly the intent over the next few weeks as we build out that plan and share more.
Kevin Goh
Just to add to that, Brandon, a third component is having the real estate side, private and public, work closely together. We see this model happening in places like Australia, where folks are able to combine products, as long as the mandates are consistent and aligned, and no investor is disenfranchised, right?
Once your interests are aligned, it doesn't really matter where you draw your capital from, because you can then discharge your fiduciary duty. This is something to us, I think we see this as a unique selling feature for CLI, where we've got REITs lined up with the verticals: hospitality, we've got REIT; living, we've got REIT; logistics, we've got REIT; commercial, we've got REIT.
We have big REITs, strong REITs, with a capital that they can deploy. To Paul's point, and because we know that DPU accretion is critical, you can find a way to work together where you can deliver DPU accretion in an orderly and predictable way that your unitholders can see it coming, even if it doesn't happen on day one.
That's something I think we can do better as a house. We have, I would say, quite a unique ability to do so because we have REITs and private equity lined up quite neatly under the verticals.
Grace Chia
Shen. Can we have the mic over here?
Xuan Tan
Hi, morning. This is Shen from Goldman.
My first question is on the lodging management platform. Is that included in the $7 billion to $9 billion non-core?
Can you explain the EBITDA margin decline? Second question is on operating PATMI growth.
First half is at 13% versus earlier guidance of mid-single digit. Any change in guidance?
If not, what will actually drive a weaker second half?
Paul Tham
In the $7 billion to $9 billion, we have not included Ascott. We have not included any of the operating platforms.
I think it is something that potentially we could include, Currently on a balance sheet, the $7 billion to $9 billion, we look at it as balance sheet value. As you can imagine, most of our operating platforms actually carried at a pretty low value.
We do see potential upside from stake sales or divestments, but we're currently not including that in the $7 billion to $9 billion.
Lee Chee Koon
Ascott is core, by the way. Even if you bring in investors, it's still core, because it helps us to drive funds and help us to grow the REITs.
Just to explain, in case some of my Ascott colleagues, including Kevin, think that he's a non-core to CLI.
Paul Tham
In terms of the EBITDA drop, and I don't know if Kevin you'd like to share more. A large part of that was really because of the one-offs.
We picked up termination fees, franchise fees, and we had bonus provision write-backs in the first half of last year, all of which actually impacted the number. If you strip that out, margins actually are about flat.
Kevin Goh
Yeah. Just to add on to Paul, if you take out the one-offs, actually the recurring part of the business is growing at about 16%.
Sometimes one-offs are also a bit of a timing, and we do expect to pick up some one-offs in the second half. This could be like sale of franchise, like what Paul mentioned in Australia, could be some compensation fees that we get in different times of the year.
I think these are all short-term fluctuations, which we are a little bit less concerned. What the bigger picture paints is that with close, just as an illustration, right, about 1,000 properties right now, 60% are operational, 40% are coming online in the next 3 years, right?
If you do the math, you can see the growth that's coming in the next couple of years.
Xuan Tan
Would you be able to guide us on a normalized EBITDA margin?
Kevin Goh
I think, generally speaking, we want to hit towards closer to about 30%. Right now, we're operating about in a 20% level, but that's because really we're still investing a lot in the business.
We're building our loyalty program, our systems, our capabilities, and if you noticed, we've also opened up our addressable market. We used to be just doing serviced apartments.
Today, we're doing resorts, we're signing up full-service hotels, and doing that gives us a lot more signings. You see the signings are up, right?
We want to focus a lot more on the growth bit of the business. We signed about over 40 hotels and serviced apartments year-to-date, first half, and then we opened about over 20 of them.
If we continue at this pace of adding new properties, opening new properties, that is where the growth is coming for us. Once you have that growth, you gain operating leverage, and when you gain operating leverage, your margins will naturally improve.
That operating leverage will come from that 40% that's not opened yet. Sometimes the margins when you compare against other players, you need to compare against like for like, whether it's net margins, gross margins, whether the players include the reimbursable.
The numbers could look a bit confusing. When you compare, you need to compare like by like.
Yeah.
Paul Tham
Just on the earnings guidance, we were mid-single-digit guidance for full year at the start of the year. I don't think we've changed guidance.
Certainly, we hope to be on the higher end of mid-single digits, but we're still keeping that as guidance.
Grace Chia
Mervin again. The mic is behind you, Mervin.
Mervin Song
Sorry. Maybe can go to slide 7.
Obviously, pleasing to see EBITDA margins for the fee business improving to about 56%, fee as a percentage of FUM also going up. If you were to strip out those legacy funds, those subscale funds, how high could this number be?
Any guidance on that?
Paul Tham
I would say when we look at the two business, even though we've combined it here, we look at the two slightly separately. From our listed funds business, given the scale we have with our REITs, generally we expect 60%, 60%-plus margins.
For the private funds, when we get to a steady run rate, excluding carry, we would like a 30% to 40% margin. On a blended basis, actually if you strip out the one-offs and everything else, we don't expect to move too far from this.
We would expect to be about 50%, assuming over time it stabilizes.
Mervin Song
Sure. Appreciate you still forming your strategy for the listed REIT business with the management team there.
How aggressive do you think you can go? Are we going to do onshore India REITs?
Are we going to privatize CLCT? What are we going to do with Malaysia?
Legacy funds, are you willing to take those losses? Keppel's been willing to take losses and move on, return capital back to shareholders, which the market has rewarded.
Just trying to get your sense in terms of how you're thinking about how quickly you want to move. Obviously, cost savings with stripping Paul, we've discussed before, when can we see those cost savings coming through in terms of hitting the bottom line?
Thanks.
Paul Tham
Please come to Investor Day. We'd like to share.
I think some of the stuff, it's not that we haven't necessarily thought it through. I think we've agreed we're not necessarily at the point we want to share.
We want to be able to share a complete plan and to be able to answer all the questions that come in. I do think on the REIT side, we are certainly looking to do more offshore listings, but even listings in Singapore, if we can.
In terms of timing, when are we willing to take some of the potential adjustments, if needed, on some of the divestments, I think all of that we look to share it as a more comprehensive plan.
Mervin Song
I'll definitely register for the date when Grace decides when she'll have the Investor Day.
Grace Chia
One question here. Yew Yu-Keng.
Yu-Keng Shih
Hi, Yew Yu-Keng from CLSA. Just two quick questions.
The $7 billion to $9 billion, can you give a sense of how much it has been written down year-on-year? Then the second question is on Ascott.
I understand that is a core, but does it give any benefits to hold 100% or is 80%, 50%, 60% Would it bring any difference to your bottom line or operating performance?
Lee Chee Koon
No, no, like I said just now, I said that we are open-minded. We don't mind bringing in investor that can be helpful to what we want to do, to help to further the M&A ambitions and to help to strengthen the distribution or the capabilities.
We are totally open-minded about that. Yeah.
Yu-Keng Shih
You don't have to hold 100%?
Lee Chee Koon
I don't think we need to, but it's still an important part of our business, and I think we still need it to help us to set up our new funds, strategies, because today if you look at our CLARA tree or CLARA II, it was a lot of investors come in because of our operating capabilities, the data, understanding where people are staying, the kind of rates that they are doing, it does help us in terms of our fundraising.
Yu-Keng Shih
Yeah. Is it critical to remain as a majority?
Lee Chee Koon
We still want to own it. The question is whether how much stakes we need to own.
I think that's the question. We don't need to own 100%, if you ask me.
Yeah.
Yu-Keng Shih
Okay.
Paul Tham
On the other question, Yew Yu-Keng, of the $7 billion to $9 billion, obviously some of them have no write-downs. The REIT units actually, if anything, some of that value has actually increased.
Then for some of the Singapore or Europe assets, we've had some adjustments. I'd say the bulk, obviously, is the China portfolio.
We've written down about $1.6 billion over the last 5 years cumulatively, which we shared at full-year results. I would say, on average, that means most of the assets in that grouping have probably been written down between 20% to 25%, if not 30%.
Yu-Keng Shih
Okay. Thanks.
Grace Chia
Any more questions? I don't think we have any questions online.
Dexter, you have a question? Okay.
Over here.
Dexter Low
Hi, Dexter from Bloomberg. Can I ask first on the Luwan divestment that you guys did, it's from a development fund that you guys had, am I right to assume then that that development fund is being winded down?
Lee Chee Koon
Tze Seong, you want to take that question?
Paul Tham
Thanks, Dexter. Yes, it's part of our Development Fund III.
There are five assets. We have divested one, which is Qingdao, Innov Center, to our AIA master fund last year.
Then this is the second one. I would call it an orderly finish to a fund that has been recapped once already.
Yeah. There are plans, in accordance to the fund's timeline, to further look at divestments of the final three assets.
Dexter Low
Just two more. One is on the tenure extensions.
Obviously, like you mentioned just now, that there has been some plans laid out. Do you all foresee having to pay more, obviously, premiums to top up the tenures, especially in China?
That's my first question. Second, on your conversations with LPs right now, are more LPs looking for co-investments and more of a kind of equal relationship, JVs, kind of structure rather than more of a blind pool fund kind of format going forward?
Yep. Thanks.
Lee Chee Koon
The land extension policy just came out last week. We are reviewing the details, working through the numbers, what it means.
I think it's too early for us to give a view at this point in time, because first there's a policy. Then the question is, do you need to take the asset?
Then we need to discuss and work out the numbers. Give us a bit of time.
What I do want to say is that at least there's a mechanism. Once the rules are clear, at least you know how to assess, you can put a pricing to it, and whether it makes sense to top up or not depends on what it means for the returns for the asset level and also for the investors.
Then we will look at it on a case-by-case basis. Having that clarity of rules for all investors, I think it's important.
Yeah.
Kishore Moorjani
Can I pick up the LP question? I think and Andrew can probably add on the real estate side.
On credit and alternatives, Dexter, we're seeing a little bit of both. In our ACP program, which is our flagship, Fund I needed about nearly 50%, 45% from balance sheet, it was $250 million.
Fund II, doubled that size and only took 20% from balance sheet. We actually had to scale back LPs.
It's a good problem to have. We've been returning capital on that actually quite quickly.
Fund III, we intend to do a first close hopefully before the end of this year, and you'll see that size increase meaningfully, the balance sheet capacity or contribution go down from 20% again. We're seeing that momentum, and that's from a broader base of LPs.
Separate from that, and specifically with insurance LPs, we have at least three very deep, ongoing discussions around large, managed accounts. They're not entirely credit, but they're dominantly credit.
One is on sort of a programmatic CLI-wide program. The second is specific to a target geography where they're looking for credit deployment and yield.
The third is an aggregation of insurers in a specific market that wants to deploy, again, largely for alternate to fixed income yield. Those will be very deep pools for managed accounts, but at least on the credit side, we're seeing strong demand even on the commingled fund.
Andrew Lim
Broadly speaking, just to supplement, I think what you can see from Kee Siew's explanation is that you have a wide spectrum of preferences from different LPs depending on their needs. Some LPs are actually constrained.
They cannot be more than a certain percentage of a fund. When they come in, they require other LPs, which speaks to the more commingled nature of it.
You can then design a supplemental program for them to deploy what they need to deploy through co-investments or SMA-type programs. The key for us as a house, I think, is to remain nimble and listen to our LPs, and rather than try to force-fit what we think is best for them, we need to let them tell us what it is that they need from us as a house.
Wherever we feel that it is right for us to try to accommodate and design products and programs around their needs, I think that's where we have an ability to sort of differentiate and distinguish ourselves using different types of products as well. We talked earlier about private to private, but we can also do private-public.
Some investors are quite happy to do that. We already have investors in our system that invest in both our REITs and our private equity products, because you can blend a combination of cash-on-cash yields, liquidity, as well as thematics that suit different LPs and what they are looking for.
Sorry, Chee Koon, I think you wanted to say something. Oh,
Lee Chee Koon
no. Andrew has covered most of the points I had wanted to say.
The point maybe just to highlight is that we really want to focus on the bigger fund strategies. The smaller-size-type funds, there's no ability to scale.
You'll really see us sunsetting. We wouldn't even bother to do, because it doesn't make sense.
We need to focus on building up the big AUM and the repeatable strategies for the group. That's the discipline that we have, and it will help to improve margins and negotiate for better, I would say, fairer fees as well.
Grace Chia
Thank you. Maybe one last question.
Maybe we have Rachel, then we'll come back to Mervin for the last question. Rachel over there.
Hi, thank you. I just have one quick question.
What happens to Ascott's target of that 500 million? Are you thinking of spinning off before he hits the target or after he hits the target?
When can he still hit the target?
Kevin Goh
Yeah. I can answer the 500 million question, the spinoff question I cannot answer.
If you look at the 40% contracts that are not opened, these are signed contracts, we have already exceeded the 500 million. It's just a matter of time before the 500 million comes in, right?
I think those are embedded revenue that will come in in the next couple of years.
Lee Chee Koon
The long and short is Ascott, the fee income growth, the EBITDA growth is building up very, very nicely, right? Obviously, because it's doing very well, you have a lot of interesting investors wanting to have conversations about wanting to participate in that growth.
We are open-minded, but we want to be sure that we can bring in the investors. It's not just about unlocking the value.
We want to help it to drive the growth even better, either through M&A or through distribution or help to bring down the cost. It has to make sense.
Then, I mentioned, there's no need for us to own 100%, but it's still a very important part of our business to help us to build new funds and if you look at our lodging assets that we own as a group, if you include the private funds plus Japan Hospitality REIT plus CapitaLand Ascendas Trust, actually lodging is a big part of our business. It started off just doing long stay, but the data now because the Ascott team has done resorts going to hotels, the data, the understanding of where customers are going, how the spending, makes a big difference in the way how we talk to fund investors in building up the fund strategies for the hospitality or the living assets investments.
Yeah.
Kevin Goh
Also just to give a sense, I think the Ascott management platform currently still manages about 60% of the class properties. There's quite a large proportion.
Also the new, for example, CLARA II, we also work with the fund team to actually build up quite a lot of the assets that were brownfield, greenfield. Some of those assets actually give very good returns to investors.
I think some of them are in excess of 30% IRR. Some of those things that we achieve would be difficult to achieve if it's just a arm's-length third-party-type operator who doesn't understand the objectives and what we're trying to get at.
Just one quick follow-up. Are the 40% contracted that you mentioned, how soon can we get to all the 40%?
Kevin Goh
Varying completion timelines. I think some of them are conversion projects quite within the next 12 months.
Some of them are brownfield, maybe 24 months. The greenfield ones are the ones that will take a bit longer, usually about 3 years or so, right?
I think the contracts are there. What we want is to make sure that they open on time.
To be honest, some of them do slip, but the comforting point is that the project is there. It's just a matter of time when it opens.
Another 2, 3 years, then? Yeah.
Grace Chia
Last question. Mervin.
Mervin Song
Maybe I can sneak in two. First question, a big driver of earnings improvement is lower borrowing costs.
Maybe if you have some guidance for second half, and as you pair down debt, paying off more expensive debt, how do you think the interest costs could stabilize down to? Second question, in terms of, wanting to scale up, reduce some legacy funds, is there a benchmark size for a private fund that makes sense for you?
Which are your flagship funds you want to scale up today? Maybe you can describe them, and perhaps some LPs are dialling into this call, they can, send a check in if you're opening the doors for them to contribute, maybe you can just share share your thoughts on that.
Thanks.
Kishore Moorjani
I can take the second one.
Paul Tham
How much time do we have, Grace?
Grace Chia
Just for that. Last one.
Paul Tham
Okay.
Andrew Lim
I will answer that question by looking at the sizing of the market. In as Chee Koon mentioned earlier, we capital raising generally for real estate is, I would say, there's some headwinds there.
Historically, in the last year or so, we've been raising about we last year we did 3.8, I'd say this year we're on pace to deliver roughly about the same. Let's call that an annual cadence of, say, $3 billion to $5 billion a year, all right?
That gives us allows us to punch at or above our weight if you consider that in the context of what Asia-Pacific capital raising generally is able to accomplish in this environment, real estate. So $3 billion to $5 billion a year, you you extrapolate, and you net off the funds that we will roll off and sunset, that's your that's our I would say target organic growth.
Then on top of that, we have what we talked about, platform acquisitions, that allow us to scale FUM in a systematic and disciplined way to support the verticals: hospitality, living, logistics, self-storage, commercial. Then there's the alt side of the house, which is on a high high-growth trajectory, starting from a low base, but lots of interesting being happening, that Kee Siew is building.
What that number is, I think sign up for Investor Day. We hopefully be able to share that for you.
Paul Tham
Just on the interest rates, interest rates did come down, obviously, 40 basis points, which was a nice savings for us. We kind of expect for second half they will be around about this range, maybe down slightly.
Obviously, part of that mix was because we've paid off some of the other currencies, we've got our Singapore float, which is still holding at a very low rate. I think if that doesn't move up, then we would see some of the same savings in the second half.
Grace Chia
Okay. With that, thank you very much.
We now have a lot of work to do so that we can update you on our progress as we look to share more in the coming months. Thank you very much, everyone.
Have a pleasant day ahead.