NowVertical Group Inc
Q3 FY2026 · Earnings Call TranscriptNovember 10, 2026
Moderator
[via?] today's presentation, and on the presentation materials related to today's earnings press release, financial statements, and management's discussion and analysis that are available on the Investor Relations section of the company's website at www.nowvertical.com and on the SEDAR website, www.sedar.com.
All figures discussed in today's call are in US dollars and will be on an IFRS basis unless otherwise noted, and will refer to specific non-IFRS measures including, but not limited to, adjusted EBITDA, adjusted EBITDA percentage, net debt to TTM adjusted EBITDA. Please refer to the cautionary note in the presentation and to the Non-IFRS and Other Financial Measures section of the MD&A for more detail.
Today's presentation will be led by Andre Garber, the company's Chief Executive Officer, who is also joined by Philip Jones, the company's Chief Financial Officer. We'll break for questions at the end of management's formal remarks.
During the question-and-answer session, we'll take questions from analysts over the Zoom audio and all other questions from listeners through the webinar portal Q&A chat box. I'll remind analysts to use the raise-your-hand feature within the portal to ask a question.
Once again, thank you for joining us today. I'll turn the call over now to Andre to begin the presentation.
Andre Garber
Great. Thank you very much, Glenn, and good morning, everyone.
I appreciate you joining us for NowVertical's third quarter 2026 earnings call. My name is Andre Garber, and I am pleased to be speaking with you as NowVertical's newly appointed Chief Executive Officer, following a quarter serving as interim CEO and the completion of the board's formal search process.
Before diving into the third quarter results, I want to take a moment to highlight the significant opportunity ahead of us, and why I'm personally so excited to lead NOW through its next chapter of growth. As we all know and as we're all hearing, AI is fundamentally changing how businesses operate, with new applications, use cases emerging across virtually every industry.
Yet despite the pace of innovation and investment, capex and otherwise, 93% of companies say their data is not ready for AI adoption. That disconnect between AI ambition and enterprise readiness is exactly where NowVertical comes in.
We believe this represents a tremendous opportunity for our business, positioning us to compete in an established market estimated at $550 billion US with a market CAGR exceeding 30%. Importantly, we're not starting from scratch here.
NOW has already demonstrated its ability to deliver meaningful value for global enterprise clients, including Bayer, Mercado Libre, Haleon. We have the capabilities, we have the client relationships, and we have this market opportunity in front of us.
We have these strong capabilities across the data landscape, but we've built real expertise in connecting customer and finance data, particularly across key industries such as healthcare, financial services. Our approach to delivery is equally important.
We start small, we prove value quickly, we demonstrate it, we scale with our clients' organizations, and that allows us to build lasting relationships and expand our presence across the enterprise. At the same time, we embed AI into our delivery process and leverage our global team, we're able to accelerate implementation and deliver much faster time to value for our clients.
That time to value is key. Supporting all of this are our relationships with the world's leading technology providers.
Of course, you may have seen that we're a Google Cloud Premier Partner. We're a proud two-time Data and Analytics Partner of the Year in Latin America.
We also remain technology-agnostic by choice, and it gives us and our clients the flexibility to work across the whole stack, including Azure, AWS, Databricks, and Snowflake, to best meet our clients' needs. Ultimately, our value prop is simple: deep expertise, efficient delivery, and faster time to value for our clients.
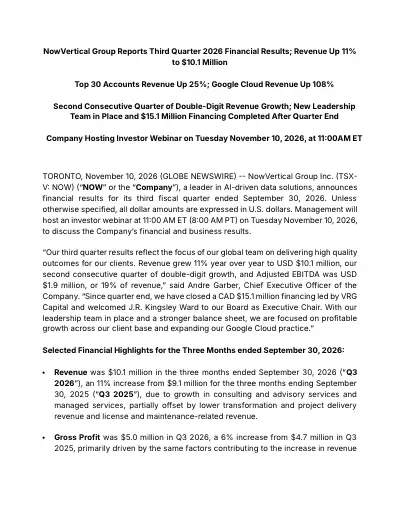
Turning to the quarter itself, we're pleased to report a strong set of results that reflect the continued momentum we're building across the business. Double-digit revenue growth in Q3 with revenue of $10.1 million, up 11% year-over-year.
We did that while holding a 49% gross margin and a 19% adjusted EBITDA margin, about $1.9 million US of adjusted EBITDA, while our operating profit still grew 53% year-over-year to about $0.6 million. We're growing while we're demonstrating greater operational and financial discipline.
Just for completeness, because it's not on the slide, just want to mention that after a tax expense driven by our profit mix in Latin America, we reported a net result for the quarter as a small loss of about $0.2 million against a $0.6 million loss a year ago. We were profitable before tax, and for the nine months we're still net income positive and a $2 million improvement over last year.
Beyond just the revenue headline of 11% growth, what's particularly exciting is where the growth is coming from. Our core services business grew 20% year-over-year in the quarter, reflecting continued demand for our people, expertise, and our high-margin work.
Our top 30 clients generated $8.5 million in revenue, up 25% year-over-year, marking the fourth consecutive quarter of growth in that category. Within the Google Cloud ecosystem, our revenue reached $2.7 million, up 108% year-over-year, more than doubling from a year ago and marking four consecutive quarters of growth in that category.
These are important indicators of the underlying strength of our business. We're not just growing revenue, but we wanted to show that we're seeing sustained growth in the areas that matter most to our long-term strategy.
While we're encouraged by the growth of our business, we do remain equally focused on cash generation and financial discipline. Year-to-date operating cash flow has improved by more than $5 million US, moving from about a $4.75 million outflow at this point last year to positive $380,000 this year, marking our first cash-generative nine-month period in several years.
As of September 30th, prior to our strategic financing, we held about $3.6 million US in cash and cash equivalents, with positive working capital of $1.5 million, and net debt at 1.8 times trailing 12 months adjusted EBITDA. These results demonstrate that we're not only growing the business, but strengthening our financial position along the way.
We're growing, we're maintaining margins, and generating cash, and with that foundation, our focus now turns to accelerating growth and building this business into what we believe it has the potential to become. That's exactly what our recent strategic financing is designed to support.
As you may have seen, in October we completed a CAD $15.1 million financing, approximately $10.8 million US, and it was led by VRG Capital, a group of family offices with a strong track record of building businesses. That financing consisted of about $5.1 million in equity units and $10 million in convertible debt units Canadian.
Most importantly, every member of our management team participated in the financing, demonstrating our collective confidence in the opportunity ahead. Alongside the financing, we strengthened our board, welcoming J.R.
Kingsley Ward as Executive Chair, and I also returned to the board. These proceeds will strengthen our balance sheet, support our growth strategy, including growing our commercial capabilities, growing our Google Cloud business, and building our North American presence.
I want to emphasize one important point: our operations are generating cash, this financing is not about funding day-to-day operations, it's about giving us the capital to accelerate the growth. Behind everything we've discussed today, I just want to give a shout-out to the global team.
We're a team of more than 500 people who are passionate about delivering value for our clients, and that commitment was on full display this quarter. Thank you to the team.
That included client strategy sessions, industry events like Vtex in Brazil, speaking at the Google Cloud Summit in Buenos Aires. Together, our people are strengthening the NowVertical brand and building lasting client relationships and driving our business forward.
This team is building the NowVertical brand in every market we serve, embedded in our communities, and the energy is definitely real. I walked the halls in our offices, all of our offices in the past quarter.
To close, I'm incredibly encouraged by where NowVertical stands today, and more importantly, where we're headed. We delivered 11% revenue growth with our core service business growing 20% while generating positive operating cash flow.
With our recent CAD $15.1 million strategic financing, we now have the capital to accelerate that momentum. Thank you very much to our team, our clients, our shareholders for your continued support.
We're very excited about what's ahead. With that, our CFO, Philip Jones, and me are happy to take your questions.
I'll turn it over to Glenn first.
Moderator
Super. Thank you.
Again, for covering analysts, please use the raise-your-hand feature. We have our first question that comes from Noel Atkinson.
Noel, you are live.
Noel Atkinson
I'm glad for that. Good morning, Andre and Phil.
Thanks for taking questions this morning and well done in Q3. I just had a couple quick ones.
The strength in the Google Cloud Platform revenue, so that looked like it accelerated in terms of growth into Q3. Could you guys talk a little bit about Google Cloud Platform revenue versus your core data revenue platform revenue, and give us a little definition of how the two are different and how they relate to each other?
Andre Garber
Thanks, Noel. Thanks very much.
I would say that the Google Cloud revenue is embedded within that core data revenue that we're talking about, but specifically with respect to Google Cloud, with more than 70 professional certifications on the team, I couldn't be more proud of this team and how we've evolved that relationship. With more than 70 professional certifications, we've got 20-plus success stories and growing.
We have deep knowledge of the GCP catalog, along with, of course, recognition as Partner of the Year. It's our ability to work with the GCP suite of solutions and embed those into our clients that's creating that kind of growth.
Google is the fastest growing hyperscaler, we're very aligned to the roadmap of Google and putting Google into our clients.
Noel Atkinson
Great. Secondly, could you talk at all about, within your client base, any industry verticals that are showing particularly decent demand strength?
Andre Garber
For sure. Of course we work the gamut, but financial services, healthcare, energy, CPG, media, and retail are probably the biggest sectors, if you will, that are just showing really strong demand, and we don't see a sign of that slowing down in those industries.
Noel Atkinson
Great. That's it for me.
Thank you.
Moderator
Thank you, Noel. The next question will come from Rob Goff with Ventum.
Rob, you are live.
Rob Goff
I'm glad to be alive as well, and glad to be unmuted as well. My question sort of layers on with Noel's.
Can you talk about the extent to which the growth in the top 30 accounts is responsible for the growth of the Google Cloud, and how that is embedded?
Andre Garber
For sure. Our top 30 accounts are typically large enterprises or private equity-backed companies that have massive transformation agendas that are sponsor-driven.
The Google Cloud roadmap aligns really well to organizations that want to do deep transformations on their business. It is pretty linked, Rob, in terms of that.
There's kind of an insatiable demand for bringing Google Cloud into these enterprises, so that's kind of how the high growth in Google Cloud and where it's impacting our top 30 is coming into the fold.
Rob Goff
Cool. When you look at the 25% growth in the top 30 accounts, is that evenly distributed across all 30, or so the median, would it be close to that same 25%, or how do you see that?
Andre Garber
I would say it's a little bit more sort of concentrated than that. It's not like the median number is the average number, of course.
That moves around in the cohort, if you will. Certain clients just have certain demands that kind of spike over others, and so we tend to kind of have that top, call it top 15 or so, that top half of it is kind of consuming, and then by the time you're in 30, it can kind of tail downward from there.
Rob Goff
Cool. If I may, another one.
In your slides, you talk about you have a minimum of $50,000 to $150,000, the Big Four have a minimum of $5 million. In your snack bracket, who are you competing with if it's not the Big Four?
Andre Garber
Now, we still do compete, and they still come down occasionally. We are routinely seeing, call it the Big Fours of the world, Accenture, et cetera.
We definitely see them play in our space, especially in the larger enterprises. Then we do compete with some regional players in the different local markets that we operate.
We haven't really seen a kind of a globally integrated player like us compete in the different geographies the way we are.
Rob Goff
Thank you. That's it.
Andre Garber
Thanks, Rob.
Moderator
There are no more questions in the queue. Andre, go ahead and take the Q&A chat box questions.
Andre Garber
Yeah. Sure, thanks.
There is a question, "Congrats on the quarter. My question is regarding customer retention.
What makes these customers stay?" Just showing we have some high retention numbers.
Don't underestimate the lack of—and I'm not saying it's a bad thing, I think it's a great thing and this is how it's evolving in the market—but don't overestimate the preparedness of large enterprises' data environments. Again, only 7% of enterprises say that their data is ready for AI adoption, so that 93% is a massive opportunity.
That also represents a massive amount of work to be done in each of these clients. There's years and years and years' worth of work to be delivered, and that's what makes us stay is that we continue to help improve our clients.
Another question is, "What makes NOW well positioned to benefit from the increase in enterprise AI adoption?" I think it's a good question.
It's mainly the pressures from the C-suite and boards as well to see their operations adopt AI and get the benefits from it. We're seeing more and more senior titles come online with the word AI in them in our client environments, and we are there to support those people in those roles, and make them successful and make their organization successful.
There's a lot of demand pressure that's coming top-down that is where we're going to really see ourselves being well positioned to benefit. Part of that is also with respect to data and AI literacy, AI adoption, being technology-agnostic and enabling AI, we've spent the better part of 20 years, the companies that we've put together here and have now integrated into one business, being expert data practitioners.
We have this strong foundation already, and that's just on the enabling AI side. Then there's the applying AI and its use cases, and we are very adept at applying various AI use cases to our clients.
Question about trade and unbilled receivables and just kind of understanding kind of normalized DSO and percentage there. Maybe I'll turn it over to Phil, our CFO, for that one.
Philip Jones
The unbilled receivables relates to subscription contracts, where somebody signs a contract, it could be multi-year in length. IFRS has us recognize all the revenue and all the cost upfront, even though we may not be billing on a, say, a monthly basis until out into the future, and hence the term unbilled receivables, which we've now switched to calling it subscription receivables.
It's a more accurate nomenclature. To get back to the past due AR, we have under 1% of our AR is past due.
We have very, very good relationships with our customers. Our customers are, for the most part, as Andre talked about, they are blue chip, large corporations who honor their agreements and their contracts.
With the repeatability of the customers coming back to us more and more, we've developed those relationships, cash collections isn't a problem.
Andre Garber
Thanks, Phil. Another question regarding EBITDA conversion: "Generating about $5.1 million of adjusted EBITDA, but not that same dollar-for-dollar on operating cash flow.
Could you walk us through the difference and tell us kind of cash conversion and what that kind of looks like on a normalized basis in the future?"
Philip Jones
The company does carry debt with HSBC as our chief lender. A lot of the difference between EBITDA and operating cash flow does come down to debt service.
We've also had a number of transitional changes, etc., that have taken place over the last quarter, there's been a lot of non-recurring costs. Our capex is quite minimal for a company of our size, and of course, we are profitable across all of our regions, we are paying taxes, which does drain out of our operating cash flow as well.
Andre Garber
Thanks. Then, "Where are you seeing the strongest demand across your business today?"
That demand is coming really from our core services, and our core services outperformed our license and reselling revenue, which was planned. Core services growth is up 20% year-over-year in the quarter, and we see that being, an indicative of kind of the tailwinds in the market and the demand pressures again by the C-suite imposing AI mandates into their organizations.
I think we've answered all the questions, just wait another few seconds and see if there's any other questions, but if not, Glenn, I'll turn it back to you.
Moderator
Super. I don't see any further questions coming in, Andre and Philip, at this point, I think we want to just thank all of our listeners.
If you want any closing remarks, go ahead and state them, and otherwise we'll end the call.
Andre Garber
Great. No, I think we're good.
Thank you very much, and we look forward to seeing you soon. Thanks, everyone.
Moderator
Thank you. This concludes this webinar.