AMERISAFE, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Good day, and welcome to the AMERISAFE third quarter 2026 earnings call. Today's conference is being recorded.
At this time, I would like to turn the conference over to Kathryn Shirley, Chief Administrative Officer. Please go ahead.
Kathryn Shirley
Thank you, operator, and good morning, everyone. Welcome to the AMERISAFE 2026 third quarter investor call.
If you have not received the earnings release, it is available on our website at amerisafe.com. This call is being recorded.
A replay of today's call will be available. Details on how to access the replay are in the earnings release.
During this call, we will be making forward-looking statements intended to fall within the safe harbor provided under the securities laws. These statements are based on current expectations and assumptions that are subject to various risks and uncertainties.
Actual results may differ materially from the results expressed or implied in these statements if the underlying assumptions prove to be incorrect or as the results of risk, uncertainties, and other factors, including factors discussed in the earnings release, in the comments made during today's call, and in the risk factors section of our Form 10-K, Form 10-Q, and other reports and filings with the Securities and Exchange Commission. We do not undertake any duty to update any forward-looking statement.
I will now turn the call over to Janelle Frost, AMERISAFE's President and CEO.
Janelle Frost
Thank you, Kathryn, and good morning, everyone. Joining me today are Guillermo Ramos, our Chief Financial Officer, and Vincent Gagliano, our Chief Risk Officer.
AMERISAFE continues to demonstrate the disciplined underwriting, reserve strength, and capital management that have defined our company throughout multiple market cycles. While competitive pressures in workers' compensation were elevated, the quarter reinforced several key strengths of our franchise.
We grew policy count, we achieved strong renewal retention, we generated favorable reserve development, and maintained exceptional balance sheet strength. These results reflect both the resilience of our business model and the value of our specialized approach to serving hazardous industries.
Our strategy emphasizes risk selection, pricing discipline, and long-term profitability. The workers' compensation marketplace is increasingly competitive, with some carriers prioritizing premium growth over underwriting returns.
Our approach remains unchanged: preserve underwriting integrity through the cycle to create superior value for our shareholders. We believe this positions AMERISAFE exceptionally well to capitalize on opportunities as market conditions evolve.
During the quarter, net premiums earned increased 3% year-over-year, supported by continued growth in policy count, strong retention of existing accounts. Voluntary premium on policies written in the quarter grew 0.8%, led by continued strong pricing.
We renewed 92.3% of the policies for which we offered renewal. However, competition intensified in the quarter in select states, which slowed our new premium growth.
Turning to losses, our current accident year loss ratio remains at 72%. We continue to monitor frequency, severity, and medical trends closely.
As we've discussed in previous quarters, medical inflation remains an area of focus for the workers' compensation industry. Through the third quarter, both frequency and severity for the current accident year were in line with the prior accident year, with growth in claims reported exceeding premium growth.
Our claims team continues to demonstrate their expertise in actively managing claims and finding opportunities to resolve them effectively and efficiently. We experienced $6.9 million of favorable reserve development during the quarter, primarily from accident years 2023 and prior.
We attribute that favorable development to our proactive claims handling and the consistent approach our team takes from time a claim is reported through resolution. Our ability and experience in handling severe claims and our reserve strength continue to be distinguishing characteristics for AMERISAFE.
We remain confident in our long-term outlook for our business and our ability to create sustainable value for shareholders through disciplined underwriting, prudent capital management, and operational excellence. With that, I turn the call over to Guillermo.
Guillermo Ramos
Thank you, Janelle. Good morning, everyone.
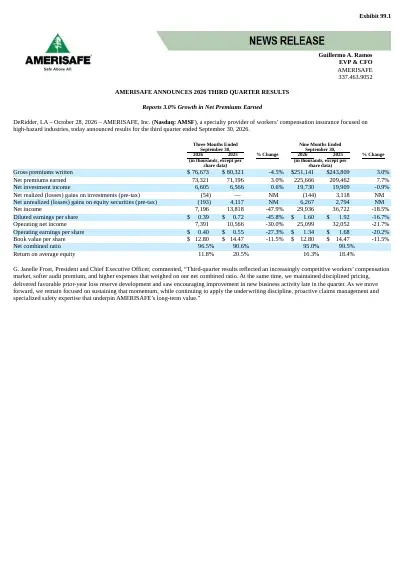
For the third quarter of 2026, AMERISAFE reported net income of $7.2 million, or 39 cents per diluted share, and operating net income of $7.4 million, or 40 cents per diluted share. For reference, in the third quarter of 2025, net income was $13.8 million, or 72 cents per diluted share, and operating net income was $10.6 million, or 55 cents per diluted share.
Turning to premiums, gross written premiums decreased 4.5% to $76.7 million from $80.3 million in the third quarter of 2025. Payroll audits and related adjustments reduced premiums by $1.6 million this quarter, compared with a $0.5 million increase in the prior year quarter.
Prior year quarter, excuse me. Despite the unfavorable audit and related premium adjustments during the quarter, net premiums earned increased 3% to $73.3 million from $71.2 million, supported by strong premium production in recent quarters.
Total underwriting and other expenses were $23.8 million, compared to $22.1 million in the third quarter of 2025, resulting in an expense ratio of 32.5%, compared with 31.1% a year ago. The increase was driven by increased insurance-related assessments, higher compensation costs, and higher commission expense.
Our effective tax rate for the quarter was 20%, compared to 21% in the prior year quarter. The decrease was due to a higher proportion of income from tax-exempt investments.
Turning to investments, net investment income was $6.6 million in the quarter, an increase of 0.6% from the third quarter of 2025. The reinvestment rate environment remained favorable, with yields on new investments exceeding portfolio runoff yields by approximately 146 basis points.
As a result, the tax-equivalent book yield increased to 4%, up 9 basis points from the third quarter of 2025. Our portfolio remains conservatively positioned, carrying an average AA- credit rating and a duration of 4.7 years.
At quarter end, we held approximately $753 million in investments, cash, and cash equivalents. The portfolio was comprised of 58% municipal bonds, 25% corporate bonds, 3% U.S.
Treasuries and agencies, 9% equity securities, and 5% cash and cash equivalents. Approximately 41% of the portfolio was classified as held-to-maturity and carried a net unrealized loss position of $23.8 million.
As a reminder, these securities are carried at amortized cost, and therefore, unrealized gains and losses are not reflected in reported book value. Our diversified equity holdings recorded a modest unrealized loss of $0.2 million, compared to $4.1 million unrealized gain in the prior year quarter.
Statutory surplus was $208.4 million at quarter end, compared to $217.8 million at year-end 2025. Book value per share decreased to $12.80, down 4.8% year-to-date.
During the quarter, we repurchased approximately 5,000 shares at an average price of $30.18 per share, representing $0.2 million returned to shareholders. Overall, the quarter reflected growth in earned premiums and continued improvement in portfolio yields, partially offset by unfavorable audit premium adjustments and higher expenses.
We remain focused on disciplined underwriting, profitable premium production, and improving operating leverage while maintaining a conservative investment portfolio and a prudent approach to capital management. Lastly, we will file our Form 10-Q with the SEC tomorrow, October 30th, 2026, after the market close.
With that, I would like to turn the call over to the operator for questions.
Operator
Thank you, sir. If you would like to ask a question, please signal by pressing *1 on your telephone keypad.
If you are using a speakerphone, please make sure your mute function is turned off to allow your signal to reach our equipment. Again, press *1 to ask a question.
We'll pause for just a moment to allow everyone an opportunity to signal. We will now take our first question from Mark Hughes with Truist Securities.
Mark Hughes
Thank you very much. Janelle, I think you talked on the last call about frequency being up through the six months.
I think you said on the call just a second ago the growth in claims reported is exceeding premium growth. Have you seen any change in that trajectory?
Is it accelerating as you go through the year? Is that a function of premiums being down rather than claims being up, I guess, measured against headcount or payroll or something like that?
Just a little more on what's going on with frequency would be great.
Janelle Frost
Good morning, Mark. Let me start with absolute reported claim counts are up.
I would love to say, "Oh, it's really all risk-premium-related," but that is not true. However, at the same time our reported claims are up, we've written more policies, right?
We have more policies in force. Our in-force policies have grown 4% year-over-year from an in-force basis.
Yes, absolute claim counts are up. I think you'll see that when we file the 10-Q later today, but you'll need also keep in mind we have more policies in force.
That being said, there is certainly pressure on that denominator in terms of premium. As we came into this year expecting mid- to say high-single-digit rate declines.
That has been the experience. The rate filings that are now in force that are going to be I guess for now and for 2027 more of the same.
I think everybody in industry was thinking the rate of decline would slow, but that really hasn't necessarily been the case. That puts pressure on frequency.
Mark Hughes
When you talk about the rate filings, any specific numbers there? I think sometimes you talked about kind of the recent trend.
It sounds like you're seeing if you say more of the same, is that mid to upper single digits? Is that what I heard you say?
Janelle Frost
Yeah. If you look at the latest charts that are out there, the lowest decline is North Carolina down 10.8%.
I think there were three states that had increases: Oregon, California, and Nevada. Nevada was an administrative change, I wouldn't really count that one as much.
Everyone else is a decline. I think on average we're still looking in that 5% to 6% range for loss cost declines going into 2027, into the 2027 premium year.
Mark Hughes
Yeah. In your judgment, you're saying that the industry was hoping for better or thought it would be better?
Janelle Frost
I think we said early on this year that we were expecting the rate of the declines to slow. When I talk about the loss costs.
They didn't slow. More stabilized would probably be the better term.
Mark Hughes
Yeah. Is that because NCCI is looking in the rearview mirror or is because that's what's happening in the marketplace?
Janelle Frost
NCCI is using the data that companies are reporting in. That data is 18 months old, but they apply trend factors to that as well.
I think it depends on individual company experience and what we're going to see in terms of what companies are experiencing in the here and now in terms of frequency, severity, and reserve development from more recent accident years.
Mark Hughes
Yeah. When you say you have more policies, I think your policy size, correct me if I'm wrong, is shrunk a little bit, with a competitive dynamic in the market.
If you looked at it on a headcount or payroll basis, is it
Janelle Frost
No, from the average account size, if that's what you're referring to, I would say it's relatively flat.
Mark Hughes
Okay. Yeah.
Okay. How about the audit premium?
This was the first negative result in a while. What's driving that?
Are there any particular industries and markets where you're seeing more influence?
Janelle Frost
I'll I'll give some color, and then I'll pass it off to Vince to give you a little bit more detail. The audit premium from the quarter let me let me be very clear, even though I know we talked about the decrease compared to the prior year quarter, audit premiums themselves remained positive, meaning, our insured base, their expected payrolls were higher than what they were when they originally estimated for that that premium year and that policy year.
I want to be very clear that they remain positive. They were lower, considerably lower than third quarter of last year.
When I read into that, I I think about what does that mean for the economy of our insured base and is there something happening there. We we have we have seen a slowing of the wage growth itself.
I think for the quarter we saw 4 point Vince'll give more detail, but I think it was like 4.1% in total, and and that really wasn't new employee employee count. I think, and I don't think this comes as a surprise to anyone, I think employers, small- to mid-sized employers, are experiencing the pressures on wages given the margin compression they experience with things that are happening.
I still believe that there is a a positive economic outlook for the people that we insure. There's definitely a labor shortage, so that speaks to potential higher wages, but at the same time there's margin compression.
Obviously, things happening with oil prices and diesel and gasoline are impactful to our industry. I think employers are are, being cautious about wage growth.
I I but I believe, as we've talked about before, particularly during the COVID years, we've talked about is the next job there. I believe the next job is there.
We haven't we haven't seen or heard of project delays and those types of things. I I still feel like that's economically a positive for AMERISAFE going forward.
Vince can talk about the quarter specifically and industries.
Vincent Gagliano
Yeah. Mark, and morning, I'll start with industries.
We do not see any material change in any specific industry's audit premium patterns. The color I would add to the quarter is more about just the mechanics of premium audit.
Keep in mind we're auditing policies that were written over a year ago. We also don't control the timing necessarily of when those audits come through or whether they'll be bigger or smaller than usual.
I can tell you we did have a couple unusually large negative audits in the quarter that on a small audit premium base does move the number significantly. We also had cancellation premium that while it wasn't out of the norm, it was robust, I'd say, and coming in on top of low audit premium, it really just created a pretty negative look for audit and adjustments for the quarter.
We were a little surprised in general, but I will also say that our Q3 audit and adjustment premium is typically our lowest of the year if we look back over about 10 years of history.
Mark Hughes
Is that cancellation premium, is that a little more shopping around?
Vincent Gagliano
Certainly. Competition is intensifying.
We're having to battle more and more to keep the accounts we have, much less write new business.
Mark Hughes
Vince, you had said last quarter you saw maybe some of the package carriers were getting a little more aggressive in the market. Any observations about what's happening this quarter, the intensity versus three or six months ago, and then whether is it the same players doing the same thing?
Vincent Gagliano
It is the same players. I think we've reached a point where we're comfortable saying we're seeing some irrational behavior.
Janelle Frost
We haven't used that term in a while.
Vincent Gagliano
No, we kind of debated if we would say it or
Mark Hughes
not.
Vincent Gagliano
Competition is intense. Some days, Mark, I feel like we're fighting for every single account.
It's not quite that bad, but we see some really bizarre things happening out there where it's apparent to us that some competitors are just chasing premium over profitability. That's where we draw the line, and it's tough for us to walk away, but sometimes we just think if we can't write it profitable, that's what we're going to do.
Mark Hughes
Yeah. I've got a few more.
I'm happy to drop off if that makes sense, I'll say thanks and put myself in the queue, but if there's not much more of a queue, then throw another caller in before I come back.
Janelle Frost
I believe there is a queue.
Mark Hughes
Okay. All right.
Janelle Frost
Thank you.
Mark Hughes
I'm dominating, I apologize.
Janelle Frost
We'll speak soon.
Mark Hughes
Okay. All right.
Thanks.
Operator
Once again, ladies and gentlemen, it is *1 if you had a question. We will go next to David Samar with Citizens.
David Samar
This is David on for Matt. Good morning.
Janelle Frost
Good morning, David.
David Samar
Just on large losses, are you able to kind of let us know where you stand versus last year? Or just a year-ago period?
Absolutely.
Janelle Frost
At quarter end, for the year, we'd had 18 claims over $1 million. Last year, at third quarter, we were at 17, and we ended the year with 25.
We're at 18 through the first nine months.
David Samar
Thank you. On the expense ratio, obviously it was a little bit higher this quarter, driven by those assessments.
Were there any states or areas with outsized assessments that you can kind of point out for us?
Guillermo Ramos
Yeah. What I would like just to mention is that, yeah, the expense ratio was higher, but it has to do as well with the earned premium, we need to take a look at the denominator, okay?
There were three states that had those assessments. The biggest one was Delaware.
David Samar
Got it. Then, I guess, lastly, just kind of digging a little further on the competitive environment, voluntary growth slowed just a bit.
Is this kind of the new normal that we should expect, or is there anything else to comment on there?
Janelle Frost
No, I don't expect that to be a new normal. Vince was talking about certainly we saw the level of competition notch up a bit, if that's the right term to use, in the third quarter.
We compete every day. My expectation is, as we started this year, we said we were shooting for mid- the sing- mid-single-digit growth for the year.
That outlook or that expectation for me has not changed.
David Samar
Perfect. Thank you.
Janelle Frost
You're welcome.
Operator
Once again, *1 if you had a question. We will return to Mark Hughes with Truist Securities.
Janelle Frost
Welcome back, Mark.
Mark Hughes
Thank you very much, Janelle. How about the medical inflation, anything there?
One one theory on a little higher frequency was maybe just overall pressure on medical costs, more people with high-deductible plans that may find it more convenient to work through the comp system with health issues rather than their health plans. What do you think about that?
Janelle Frost
It's a really interesting point, Mark, because when we talk about medical inflation, and we look at our book, and even if you look across industry data, a lot of companies have talked about the inflation increase in hospitalization and hospital costs. I think that's a direct correlation to exactly what you're talking about, just the experience that everyone in the country is experiencing on the healthcare front, what hospitals are experiencing with lower reimbursement rates, what employers are experiencing in terms of their own health insurance costs and benefits.
It's all interconnected. It's all related.
That's probably where other than home health, because I will continue to beat that drum for AMERISAFE, because I do think it's not unique to us, but given the severity of our injuries, that's certainly important to us. Hospital costs are probably where we're seeing the greatest pressure.
Mark Hughes
Yeah. Okay.
I think that was it for me. Appreciate Okay.
Janelle Frost
I'm sorry I cut you off if you just had one more question. We could have done that earlier.
Mark Hughes
No, I had a whole list. As we went through my list, I thought, "Oh my gosh, we've already gone through them.
What am I"
Janelle Frost
David beat you to the punch on the large losses, we'll give him credit. We'll give credit for that.
Mark Hughes
Yeah. Let me ask you this.
You mentioned the point about irrational and kind of contemplated whether to use that word. What are the ramifications of that if somebody says, "Gosh, people are starting to be irrational"?
What does that make you think about as you're running the business?
Janelle Frost
We really internally talked about do we use the word or not because we've seen, and I've talked about this on prior calls, we've seen anecdotally on different accounts where we thought, "Well, how are they charging that?" When we lose something to a competitor, how are they charging that?
Sometimes if it's a multi-line carrier, it's a little bit hard for us to compare apples and apples. Granted, that is true.
I would say the anecdotes were more plentiful this quarter than in past, and so that's why I feel comfortable using the word "irrational." There definitely was a shift that we saw in the quarter is the best way for me to say it.
I should also say this, and I don't think we commented on this earlier, it wasn't just pricing, right? We saw what I would call irrational commission structures
Mark Hughes
and
Janelle Frost
in states where you compete on dividends, dividends. It was all related to how do you win the account from a pricing perspective, whether it's commission, the rate itself, or dividends.
We just saw an uptick in that in the third quarter, and so that's why I would say irrational. Compare and contrast that to AMERISAFE, because again, we compete every day, I don't want to make this all about the competition.
This is how AMERISAFE behaves in the marketplace. We're not, as Vincent said, we're not chasing that price.
We want to win the account. We want to win the account under AMERISAFE's value proposition, what we offer the policyholder, what we offer the agent, but more importantly, what's going to produce long-term profitable growth for AMERISAFE.
It's a balance of all of those things. Guillermo was talking about the expense ratio, and I know this isn't information that's anywhere published, but if you look at our expense ratio, and again, certainly the audit premium hurt the expense ratio this particular quarter, but even if I look at it on a year-to-date basis, we're gaining operational efficiencies and what I would call fixed costs or non-variable costs.
That's something we've really been focused on as we try to find these ways to create ease of doing business. At the same time, are we managing that expense ratio?
We're definitely making progress there on a year-to-date basis. I feel comfortable about that.
Going to the variable cost, if I look at our commission expense on a year-to-date basis, we're 10 basis points higher than we were last year at this point in time. I think we trying creative ways and rewarding those agencies and those policyholders that do bring us profitable business, but at the same time not using it as a premium grab.
Mark Hughes
Yeah. Another question, this is a general question that we've been thinking about, is when you look at some of the package writers, you'll see the profitability, say, in their property, the commercial multi-peril property or non-liability, will be very high, and at the same time the profitability in the liability portion of it is abysmal.
I wonder the extent to which is the same thing happening here in comp that everybody is pursuing the package, but the profit allocation is subject to a lot of discretion. You try to figure out why would you write package business where you get the property at 50 and the GL at 120 combined?
If you look at on direct underwriting basis, it doesn't make sense, or maybe it does, or we're trying to figure out why that happened,
Janelle Frost
but
Mark Hughes
I wondered, do you have any comments on that?
Janelle Frost
I don't know that I have the why behind that. I can say from a workers' comp perspective and a package carrier, why write the comp at maybe something that breaks even is because it's a long-tail line, right?
Where interest rates are now, you can make money off of the cash flow portion of that. Maybe that 100 combined in workers' comp is still more profitable than that 100 combined in property to your point.
If that gives you any color, but again, I can only really speak about it in terms of what it means to the workers' compensation industry.
Mark Hughes
Exactly. Okay.
All right. I'm glad we've had this time together.
I appreciate all your help.
Janelle Frost
Me too, Mark. Always fine talking to you.
Mark Hughes
I [I've?] .
Operator
Ladies and gentlemen, with no other questions holding, I'd like to turn the call back to CEO Janelle Frost for any additional or closing remarks.
Janelle Frost
AMERISAFE has successfully navigated workers' compensation cycles for decades by remaining disciplined when markets become increasingly competitive. That discipline continues today.
Our recent A.M. Best rating affirmation reflects our underwriting discipline, prudent reserving, strong capitalization, and long-term focus on execution, the same fundamentals that continue to drive our performance.
We believe these strengths position us well to serve our policyholders, create sustainable value for shareholders, and navigate current market conditions. We are operating from a position of strength, with a team that remains intensely focused on underwriting profitability.
Thank you for your continued support of AMERISAFE.
Operator
Thank you. Ladies and gentlemen, that will conclude today's call.
We thank you for your participation. You may disconnect at this time.