Aston Martin Lagonda Global Holdings Plc
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Good day and welcome to the Aston Martin Lagonda Q3 2026 results. All lines have been placed on mute to prevent any background noise.
After the speakers' remarks, there'll be a question-and-answer session. If you would like to ask a question during this time, simply press star followed by the number 1 on your telephone keypad.
If you would like to withdraw your question, please press star 1 again. For operator assistance throughout the call, please press star 0.
Finally, I would like to advise all participants that this call is being recorded. Thank you.
I'd now like to welcome Doug Lafferty, CFO, to begin the conference. Doug, over to you.
Doug Lafferty
Thank you. Good morning, everyone.
Thanks for joining us as usual for the Q3 call. Realize it's a busy morning for everyone, I'll keep the introductory comments brief before we open up to the Q&A.
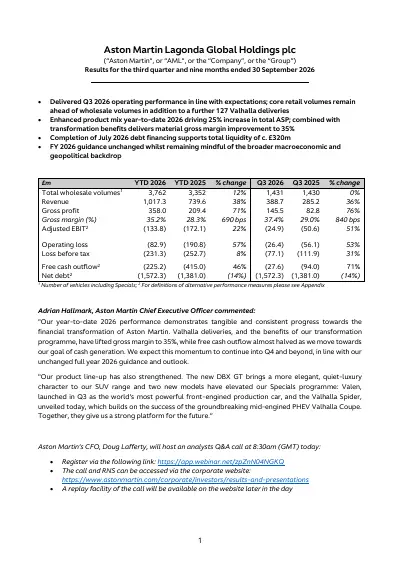
Overall, Q3 2026 year-to-date performance demonstrates continued progress against our strategic and financial objectives. We've delivered improved profitability, significantly reduced free cash outflow, strengthened liquidity, and remain on track to deliver our full-year guidance and outlook.
In more detail, core retail demand continued to outpace wholesale volumes by over 20% year-to-date, demonstrating our ongoing focus on balancing production with underlying customer demand whilst maintaining a stable core order book. Year-to-date revenue increased 38% compared with the prior-year period, supported primarily by the Valhalla Coupe deliveries, which has also driven a 25% improvement in total ASP.
Alongside this, we've been working hard on executing the transformational efficiencies related to our derivative strategy and stock optimization, with a declining trend on dealer support also reflected in core and overall ASP. We continue to expect to see core ASP growth of low to mid-single-digit percentage on a year-over-year basis.
The launch of the DBX GT expands our SUV range and broadens customer choice within the segment. We've also continued to develop our highly successful specials program through the launch of Valiant in August, as well as today's unveil of the Valhalla Spider.
Building on the success of the Coupe, which is now nearly sold out, Valhalla Spider is an exclusive proposition with a strong order book already taking deliveries into Q4 next year. Together, these programs demonstrate the strength of the brand and our ability to continue creating highly desirable ultra-luxury products across multiple segments that when combined gives a strong platform for the future.
This all translates to gross margin improvement, which is one of the clearest indicators of the progress we're making during 2026. Driven by the contribution from Valhalla Coupe, together with the ongoing benefits of the transformation program, year-to-date gross margin has materially improved to 35%.
Compared to the prior-year period, adjusted EBITDA increased by £125 million year-to-date, reflecting the stronger gross profit performance and growing operating leverage within the business. Adjusted EBIT also improved 22% year-to-date, despite a 48% increase in D&A linked to the Valhalla Coupe deliveries.
We expect to see continued positive momentum across both adjusted EBITDA and adjusted EBIT in Q4. A key focus throughout 2026 has been on delivering a material improvement in free cash outflow, and year-to-date this has nearly halved when compared to the same period in 2025.
This improvement mostly reflects the stronger operating performance together with lower capital expenditure. Looking ahead to the end of the year, and as I said back in July at the half-year results, I wouldn't expect our full-year free cash outflow to be a million miles away from where we were at the end of H1.
As a result of July's financing, we entered the final quarter of the year with a total liquidity position of around £320 million. This provides us with greater resilience in what remains a volatile operating environment, whilst also supporting the continued execution of our product and operational plans.
From an outlook perspective, and relying on the enhanced product mix and transformation delivery, we continue to expect to achieve material improvement in full-year 2026 financial performance. Of course, the broader macroeconomic and geopolitical backdrop remains challenging.
We continue to monitor developments relating to a wide range of issues. However, to date this year, we've managed these dynamics and limited or mitigated their direct impact on the business.
Against this backdrop, our full-year 2026 guidance remains unchanged, with wholesale volumes expected to be similar to last year on the core portfolio and also expecting to deliver the 500 Valhalla Coupe deliveries. We expect gross margin to increase into the high-30s percentage range, adjusted EBIT margin to improve towards breakeven, and critically, free cash outflow to materially improve, as already demonstrated year-to-date.
Thanks again for joining us, and I'll now hand back to the operator to open the line for some questions.
Operator
If you wish to ask a question, please press star followed by 1 on your telephone, and wait for your name to be announced. That is star 1 if you wish to ask a question.
Your first question comes from the line of Henning Cosman from Barclays. Your line is open.
Henning Cosman
Morning, everyone. Morning, Doug.
Thanks for taking the question. Have to start with Valhalla Spider, very exciting vehicle.
What can you tell us about it? How many units?
What's the price point? I think there's a little bit of confusion whether the units come on top of the Coupe or if they come out of the original indicated number of the 999.
Perhaps you could clarify that, please. That's the first question.
Second question on the, yeah, just the overall setup with dealer inventory, variable marketing, ASP, where do we stand? I think you just updated us that the ASP increase year-over-year, you're now seeing it at a low to mid-single-digit increase.
Do you expect that to increase further also in '27, '28? That's the second question.
Then finally, on free cash flow, appreciate you repeating the statement there, not a million miles away from H1 in terms of liquidity and free cash flow. Suppose at face value, it would mean a reversal swing to positive territory, liquidity increase in Q4 and positive free cash flow in a similar amount to the free cash outflow in Q3.
Just wondering if that's taking you too literally, or any further color you could add therefore the Q4 development. Thank you very much.
Doug Lafferty
No worries. Morning, Henning.
Look, on the Valhalla Spider, I think everybody is super excited by it. I've seen the sort of launch video went out overnight, and I think everybody who's seen the car certainly that I've heard has very, very positive things to say about it.
Look, I think we're in a good place with that car. In terms of the total volume, I think we'll end up doing slightly more than the 999 that we initially indicated when you combine the Spider and the Coupe.
The Spider will represent around about one in four of those cars, round about a quarter of the total will be the Spiders. The pricing will be around about 20% higher than the Coupe.
That's not unusual for the difference between a coupe and a roadster or Volante, particularly from a specials point of view. It's normally around 20% higher.
Personalization-wise, I think we would expect it to be broadly in line with what we've seen on the Valhalla Coupe, which has been around about 20%. Look, I think it positions us very nicely going into next year.
As I've said, the Coupe is all but sold out, and the Spider has started with a very, very strong order book upon launch today. We're in a good position with that, I think.
On the ASP, yeah, look, I think ASP is trending in the right direction. I think we'll probably end this year with a sort of low to mid-single-digit ASP improvement from a core perspective versus 2025.
Looking at next year, I'd probably expect it to be about the same year-over-year, '27 a low to mid-single-digit improvement on 2026. The sort of driver for that to a certain extent is this sort of reduction in dealer support that we've seen throughout the course of this year.
That's trending in the right direction. Q4 will be the lowest level of support on a per-unit basis, and of course, we'll try and make sure that we carry that trajectory into 2027.
Core ASP is moving in the right direction. Obviously, total ASP is supported by the specials and will continue to be so in 2027 when you think that we'll have the remaining Valhalla Coupes to deliver in the first half, the Valhalla Spiders start delivery in the second half and will probably deliver a shade over 50% of the total Spider volume in the second half of 2027, and we'll also have the Valiant deliveries.
Total ASP will be supported by the specials. On the cash flow, I guess unsurprisingly, I won't be drawn into specifics, but consistent with what I said in July, I think we'll end up from a free cash flow perspective at a very similar level to that we saw in the half years.
Look, steady, and obviously I'd point to the fact that the last two Q4s, I think, in 2024 and '25, were modestly positive. We hope that we can repeat that and end up somewhere very close to where we saw the free cash outflow level at H1.
Henning Cosman
Thanks, Doug. Just a clarification on the Valhalla Spider: is that in any way different from how you would have expected originally?
Were you hoping to sell 999 of the Coupe and then the Spider would have come on top? Is it somehow attributable to tougher market conditions that it's now inside, I think you said slightly more than 999?
I understand it's not completely on top. Is there anything more you can share around that?
Doug Lafferty
No, the plan for a while has been exactly this. We're comfortable with the plan on the Valhalla.
We've invested heavily in a platform which we see working very well in the market. The Valhalla Coupes have been delivered very strongly, positive customer response, expect the same from the Spider.
We've got that platform within our portfolio for future use as well. This is the sort of combined initial run on the Valhallas, and yeah, it's been in line with our plans for some time.
Henning Cosman
Thanks, Doug. All the best.
Doug Lafferty
Thank you.
Operator
As a reminder, if you wish to ask a question, please press star followed by 1 on your telephone, and wait for your name to be announced. That is star 1 to ask a question.
Your next question comes from the line of Harry Martin from Bernstein. Your line is open.
Harry Martin
Hi, morning, Doug. The first question I had, you've referenced it a couple of times, the uncertain macroeconomic environment.
Clearly we've been seeing the impacts that you might have experienced on raw materials or logistics. I was actually more interested in the demand side.
Far this year, the K-shape economy seems to have held for premium luxury brands. I'm interested if you're tracking anything when it comes to order books, pricing, personalization rates, and any pockets where there's some orange flags, some signals of any weakness, or if, yeah, your core customer remains pretty strong so far.
The second one, I actually have a question on China. It's a time when a lot of the automakers are scaling back ambitions.
Maybe this is just reflective of me spending a bit too much time on your media channels, but I noticed you've opened a new dealership in Suzhou, launched the S range in Shanghai quite recently. Are there maybe some more ambitions for the China business even in a declining market where you think you can grow the business?
Any reflections on that would be interesting. Then the final question, I thought I would ask for an update on how the conversations with some of your bondholders are going after they were taken a little bit by surprise over the summer with the refinancing.
Thank you.
Doug Lafferty
Great. No worries.
On the macro, yeah, look, I think everybody knows it's a challenging environment. It's pretty complicated out there.
From our perspective, I think when I look at the business, certainly there's pockets where I think we see more strength, and pockets where there's a little bit more uncertainty or weakness or stretch or challenge. From our perspective, the USA and the UK have remained pretty strong.
Middle East obviously has been a difficult year, but we've managed to sort of redistribute any volume that we would have had going into that market elsewhere. We're managing to mitigate, as I said in my opening remarks, the impact of some of these things during the course of the year.
There's a tipping point, no doubt, but at the moment, we're on top of it. Order book is relatively stable.
We've talked about order book in the past probably for the past 12 to 18 months of being about five months on the core portfolio. That isn't any sort of significant difference to the length of our order book as we sit here today.
It's short of ideal still. You've heard Adrian talk for a while now about wanting that order book to be between six and nine months depending on the derivative that we're talking about in the core portfolio, there's still the appetite to improve it.
We're not seeing any material deviation from where the order book has been for the last number of months and essentially over the last year or two years. The retail demand is solid.
The retails are running ahead of wholesales. We've got a sensible production plan in what is a complicated market.
We're doing the right things with the dealers in adjusting the inventory levels to the ones that we think are now appropriate, and we're on that journey, on that path. I think we're in a good place in that regard.
Obviously cautious and on the lookout, and all the usual sort of caveats that all of the external pressures do tend to apply. As it relates to China, look, I think China, we've rotated through quite a lot of dealers in China over the last two years.
I think the total number of dealerships that we have in China, notwithstanding the fact that we've just opened a new one, is probably 40% down on where it was two years ago. I think we've quite consistently said that, as painful as it's been losing the volume out of China, we've always seen an opportunity.
I think to continue to position the brand and the product in the best possible way that we can in China so that as and when that market returns we can rise with the tide, I think is important to do so. We just need to be mindful of the quality, as we do everywhere, of the dealers that we have in place, and make sure that we've got the right dealer partners in the right parts of the country, geography, to make sure that we take advantage of the opportunity as and when it arises.
There's nothing sort of special or specific, I would say, to read into there, Harry. Keep reviewing the media channels, because you always get some good insight on the company and the brand and the products through those means.
China is, like we do with every other market, where there's opportunity to improve what we think we've got on the ground, we'll take it. Then with regards to the bondholders, nothing really to say, Harry, at this stage.
We are where we were. We outlined the reasons for the refinancing during our first-half results.
I think you can see from the shape of the company the liquidity is in a stronger place. That's what it was all about.
It's provided us with resilience and flexibility and the means to go on and execute the plan that we're focused on delivering. Nothing more to say on that at this stage.
Harry Martin
Thank you very much.
Operator
Your next question comes from the line of Michael Tyndall from HSBC. Your line is open.
Michael Tyndall
Morning, gents. Mike from HSBC.
Two questions, if I may. Just on the dealer destocking, I just want to understand how far through we are, because I think at Q2, the suggestion was that you're pretty much close to being done, there was still a little bit left.
Are we now pretty much completely done, or is there still some more to go? Then that sort of leads into my second question, which is, when we've looked at previous Q4s, we've seen a significant uptick in activity, but the hangover from that is that we've tended to have dealer inventory to resolve.
Not saying the two are necessarily connected, but what's different this year that kind of reassure us that we're not going to have an inventory problem again in the first half of next year? Thanks.
Doug Lafferty
Hi, Mike. Look, I think we're largely through it.
There's always a bit of seasonality in Q4, but I think next year, when we look at the shape of the plan, we're very focused on trying to make it as smooth as possible. I think when I look back at our volumes over the last however many quarters, the retail offtake has been pretty stable quarter by quarter, and that's where we're trying to get the wholesales into that kind of mantra as well.
Yes, there'll be an uptick in Q4, but then the focus next year is to try and make sure that we stay in sync, retails and wholesales, as much as we possibly can, as quickly as we possibly can. Not going to sit here and guarantee that Q1 is going to be looking the same as Q2, Q3, and Q4 next year.
Probably between now and within four or five months' time, I think we will be in sync from a wholesale and retail perspective on a quarterly reporting basis, and also have the dealer inventory at the right level for a consistency. I think the summary, Mike, is we're nearly there.
There's a little bit more work to do, hence the reason there's still some dealer support going in, and getting the variable marketing down remains a focus. We're not far from where we want to be, and we will have made a significant move in the right direction during the course of 2026.
Michael Tyndall
Got it. I'm going to show my ignorance here.
The UK tariff allocation, where does that sit at the moment? When we think about 2027, how is that allocated to you, thinking about your compatriot and what their plans are?
They've been fairly busy, just wondering how does that work for 2027?
Doug Lafferty
As far as I'm aware, it works in exactly the same way as it's worked in 2026, which is we do not have a specific allocation for ourselves. The UK has the ability to ship 100,000 cars into the US with a tariff of 10%, anything above that is 27.5%.
Every quarter, there's an allowance of 25,000 cars. Effectively, on January the 1st, 2027, the slate starts clean, and Q1, there's 25,000 cars that can travel between the UK and the US at that rate.
It's first-come, first-served. Any underdelivery in Q1, if the UK sold 22,500 cars to the US in Q1, then the 2,500 that you didn't deliver would be added to the Q3 quota.
As of January the 1st each year, it starts a clean slate. We start again with the 100,000 and we start again with the 25,000 per quarter.
As far as I'm aware, no OEMs from the UK have a specific allocation within that number. It is first-come, first-served.
Michael Tyndall
Got it. Thank you.
Doug Lafferty
No worries.
Operator
There are no further questions at this time, I'd like to hand back to Doug for closing comments.
Doug Lafferty
Thank you very much. We are focused very heavily on executing the plan, as you'll have seen.
I think we're making good, steady progress. We've got some really exciting things coming.
It's great to get the Valhalla Spider out there and launched, and I'm hoping that we'll have very positive things to say about the progress that we've made in that regard when we speak again with the full-year results. Thanks for your time this morning.
Appreciate it's busy, and all the best to you. Thank you.
Operator
That does conclude our conference for today. Thank you for participating.
You may now all disconnect.