Gladstone Commercial Corporation - Real Estate Investment Trust
Q3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Greetings, and welcome to the Gladstone Commercial Corporation third quarter earnings call. At this time, all participants are in a listen-only mode.
A question-and-answer session will follow the formal presentation. If anyone should require operator assistance, please press star zero on your telephone keypad.
As a reminder, this conference is being recorded. It is now my pleasure to introduce your host, David Gladstone.
Thank you, you may begin.
David Gladstone
Thank you all for calling in. That was a nice introduction, and thank you all for being part of our call.
It's awfully early in the morning on the West Coast, we're going to keep our time at 8:30. At this time we have you on the phone and glad to talk with you, and I'm going to turn you over to Catherine Gerkis, she's Director of Investor Relations.
She's going to provide a brief disclosure regarding certain regulatory matters concerning this call and the report that we're giving today. Catherine, good morning.
Come on.
Catherine Gerkis
Thank you, David, and good morning. Today's call may include forward-looking statements, which are based on management's estimates, assumptions, and projections.
There are no guarantees of future performance, and actual results may differ materially from those expressed or implied in these statements due to various uncertainties, including the risk factors set forth in our SEC filings, which you can find on the Investors page of our website, gladstonecommercial.com. We assume no obligation to update any of these statements unless required by law.
Please visit our website for a copy of our Form 10-Q and earnings press release for more detailed information. You can also sign up for our email notification service and find information on how to contact our Investor Relations department.
We are also on X, @GladstoneCom, as well as Facebook and LinkedIn. Keyword for both is The Gladstone Companies.
Today we'll discuss FFO, which is funds from operations, a non-GAAP accounting term defined as net income, excluding the gains or losses from the sale of real estate and any impairment losses on property, plus depreciation and amortization of real estate assets. We may also discuss core FFO, which is generally FFO adjusted for certain other non-recurring revenues and expenses.
We believe these metrics can be a better indication of our operating results and allow better comparability of our period-over-period performance. Now let's turn the call over to Buzz Cooper, Gladstone Commercial's CEO and President.
Buzz Cooper
Thank you, Catherine, and thank you all for joining today's call. We are pleased to update you on our results for the quarter ended September 30, 2026, our current portfolio, and our future outlook.
Before I turn to our results, I'll comment briefly on the market. Starting with the broader market, industrial conditions were a bit of a mixed bag during the quarter.
On the one hand, industrial occupancy continues to strengthen, which we have observed within our own portfolio as well. According to Cushman & Wakefield, net absorption was 76.6 million square feet, the strongest quarter since early 2023, and the second quarter in a row above 70 million.
Year-to-date, net absorption is 203 million square feet, up 69% from the same period last year. National vacancy declined to 6.8%, down 20 basis points from its late 2025 peak, and asking rents rose 4% year-over-year.
Manufacturers were the second most active tenant group behind 3PLs, making up more than a quarter of leasing volume this year, and indicating continued demand for similar assets which we have in our portfolio. Demand remains concentrated in modern, large-format buildings supporting onshoring, nearshoring, and ongoing supply chain optimization.
Cushman's note it is now starting to spill over into older buildings, as space in newer buildings has become more scarce. New deliveries are 13% below last year's pace.
The development pipeline is growing, up 23% from a year ago, but about 35% of it is build-to-suit, which keeps speculative supply in check. That strength means continued competition for assets of all sizes, particularly those that are well-located and mission-critical.
On the other hand, rates moved sharply higher in the quarter. The Fed raised rates in September for the first time since 2023, and the 10-year Treasury ended the quarter at about 5.3%, up roughly 87 basis points in the three months to the highest level since 2007.
Sellers have been slow to adjust their pricing, the gap between what they ask and what buyers are willing to pay is wide. Thus, fewer acquisition opportunities are meeting our criteria.
Turning to our results during the quarter, we acquired a 146,650-square-foot industrial property in Red Bud, Illinois, leased to Ultra Play Systems for $6.55 million. Term at the time of the acquisition was 8-plus years.
With respect to our existing portfolio, we renewed or leased over 137,300 square feet of office and over 365,200 square feet of flex industrial, with an increase in straight-line rent of approximately $2.3 million annually. We also collected 100% of cash base rents in the period.
Positively, subsequent to the end of the quarter, we renewed or leased 452,234 square feet of industrial and 67,287 square feet of office, with an increase in straight-line rent of $2.89 million annually. As we shared last quarter, we leased 82,000 square feet of vacant space in our Austin office property.
This approximates to probably 25% of the building, and we continue to work on leasing the rest. As relates to the Austin property and others within our portfolio, we acknowledge that office leasing and releasing requires capex dollars.
When office buildings are as mission-critical and well-located as those within our portfolio, we are able to maximize those dollars so as to receive an accretive return on our investment. When we evaluate any office releasing, we review payback period, IRR, and ROI, as well as alternative to selling the property.
We acknowledge that the returns are generally not as attractive to us as industrial properties, but they keep a constant stream of cash flow for our shareholders. We are not looking to grow our office portfolio, but until capital markets return fully, capital expenditures are typically more accretive and revenue-generating than choosing to sell the asset.
Again, we evaluate each opportunity on a case-by-case basis, although we look to have a targeted payback period of between six and nine months. Through the efforts of our asset management team, as of September 30, 2026, our portfolio was 99.3% occupied, up from 98.7% last quarter, with a 7.1-year average remaining lease term.
As of quarter end, the industrial portfolio represented 69% of our annualized straight-line rent, and we continue working toward our near-term goal of 70%. Each of these milestones is a testament to mission-critical nature of the assets in our portfolio, the quality of tenant credits in our portfolio, and our underwriting capabilities.
Our playback will continue as it has: to grow our industrial concentration, adding value in our existing portfolio through renewals, extensions, and strategic capital investments, and disposing of non-core assets and strategically redeploying those proceeds into quality industrial assets. By continuing to execute on these focus area over the long term, again, we will increase our WALT, maintain our strong occupancy rates, grow straight-line rent across the portfolio, and decrease cost of capital.
Looking ahead to the last quarter of 2026, we remain focused on evaluating opportunities to acquire high-quality industrial assets that are mission-critical to tenants and accretive to our long-term strategy. We are working toward our near-term goal, again, of 70%-plus industrial annualized straight-line rent.
While we do not have a timeline for the disposition of our office portfolio, we are keenly focused on growing the industrial concentration. At the same time, we will continue to work with our existing tenants to extend leases, capture mark-to-market opportunities, and support tenant growth through targeted expansions, capital improvement initiatives, and we are looking at build-to-suit opportunities.
While we remain aware of the challenging office environment, we will be strategic and intentional in evaluating our specific portfolio, seeking opportune times to dispose of office and non-core industrial as part of our continued capital recycling efforts. With the availability via our increased line of credit, access to private placement bond market, and cash on hand, we have some ability at our ATM, and we are positioned to deploy capital into accretive industrial acquisitions and portfolio improvements.
In closing, the team executed well, and we are focused on continuing the momentum through the remainder of 2026 and into 2027. I'll now turn the call over to Gary Gerson, our CFO, to review our financial results for the quarter and liquidity position.
Gary?
Gary Gerson
Thank you, Buzz. I'll start my remarks regarding our financial results this morning by reviewing our operating results for the third quarter of 2026.
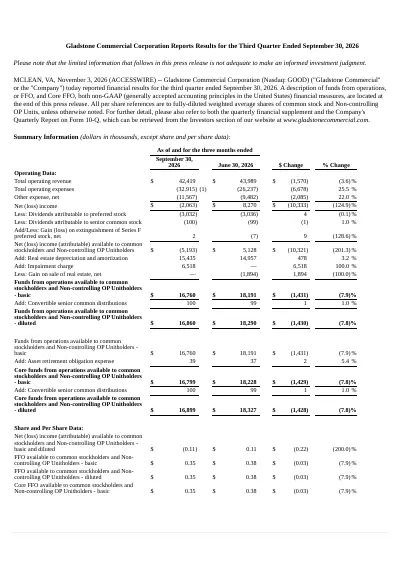
All per share numbers referenced are based on fully diluted weighted average common shares. FFO and core FFO per share available to common stockholders were both 35 cents per share for the quarter.
FFO and core FFO available to common stockholders during the same period in 2025 were both 35 cents per share. FFO and core FFO per share for the nine months ended September 30, 2026, were both $1.07 per share.
FFO and core FFO for the same period in 2025 were $1.02 and $1.03 per share, respectively. Same-store lease revenue increased by 0.2% in the nine months ended September 30, 2026, over the same period in 2025, due to an increase in recovery revenue from operating expenses and an increase in rental rates from leasing activity subsequent to the nine months ended September 30, 2025.
Our third quarter results reflected total operating revenues of $42.4 million and operating expenses of $32.9 million, as compared to operating revenues of $40.8 million and operating expenses of $26 million for the same period in 2025. Operating revenues were higher in 2026 due to an increase in portfolio size, increased recovery revenues, and higher rental rates.
Expenses were higher in the third quarter of 2026 versus the same period in 2025, mainly due to higher depreciation from a larger portfolio, partial payment of a part of an incentive fee, and an impairment charge on our Lake Mary, Florida office property in the third quarter of 2026. At the end of the quarter, we had no properties held for sale.
As of today, we have $7.4 million of loan maturities in 2026 and $99.9 million of loan maturities in 2027. As of the end of the quarter, we had $59.47 million in revolver borrowings outstanding.
Looking at our debt profile, as of September 30, 47% was fixed rate, 46% was hedged floating rate, and 7% was floating rate, which is the amount drawn on the revolving credit facility. As of September 30, our effective average SOFR was 3.9%.
Our outstanding bank term loans are all hedged to maturity with interest rate swaps. We continue to monitor interest rates closely and update our hedging strategy as needed.
During the nine months ended September 30, 2026, we sold 168,868 shares of common stock for net proceeds of $3.2 million under our ATM. We continue to manage our equity activity to ensure that we have sufficient liquidity for upcoming capital requirements and new acquisitions.
As of today, we have approximately $7.7 million in cash and $70.2 million in availability under our line of credit. We encourage you to review our quarterly financial supplement posted on our website, which provides more detailed financial and portfolio information for the quarter.
Our common stock dividend is 30 cents per quarter, 10 cents per month, or $1.20 per year. Now I'll turn the program back to David.
David Gladstone
That was a good report, Gary, and good ones from Buzz and Catherine. The team has performed very well.
Overall very nice quarter, I would say. During the quarter, we acquired a 146,000 square feet foot industrial property in Red Bud, Illinois.
Yes, the city is Red Bud, I didn't know that before. We renewed or leased 137,000 square foot office and over 365,000 square feet of flex industrial, with an increase in straight-line rent to $2.5 million.
Gladstone team is growing the real estate that they have. Remember we're in industrial side mostly.
Our team is strong professionals continue to pursue prudential quality properties on the list of acquisition. In reviewing, our acquisition team is reviewing, seeking strong credit tenants.
I'm going to stop here, and for the quarter we can have some questions from the people who have called in, and go from there. Operator, would you come in and tell them about how they can ask a question.
Operator
Thank you. If you would like to ask a question, please press star one on your telephone keypad.
A confirmation tone will indicate your line is in the question queue. You may press star two to remove yourself from the queue.
For participants using speaker equipment, it may be necessary to pick up their handset before pressing the star keys. Our first question comes from the line of Gaurav Mehta with Alliance Global Partners.
You may proceed with your question.
Gaurav Mehta
Thank you. Good morning.
I wanted to ask if you could comment on the acquisition pipeline, what are you guys seeing in the market, and maybe some comments on the cap rates.
Buzz Cooper
Sure, Gaurav. Good morning.
Obviously, the pipeline, as we have heard from our competitors as well, it is very competitive from the standpoint of acquisitions. With the rise in interest rates, we have seen a little pull back as relates to opportunities.
We also have seen a little deterioration in the credit, not that we have booked, but as we analyze. Obviously, people go and use sale-leasebacks as a financing form.
The market is still robust, very competitive, but at this point in time, we are not seeing the type and quality of assets that we want to put on our books at the moment. We've got about, oh, 15 opportunities within our pipeline that we're reviewing for a combined total of over $200 million.
Obviously, of that, we hope that some will meet our criteria. As is stated before, we're not going to lower our underwriting standards, and we need to look for cap rates going in the door of about 7.5 and average cap over the term of the lease of 10-plus years north of 9.
David Gladstone
Next question. A
Gaurav Mehta
second question I have on the balance sheet: Can you maybe comment on the interest rates on the debt that is maturing in 4Q and next year, and where do you expect to refinance that debt?
Gary Gerson
I'll start, and I'll let Jay Beckhorn, our Treasurer, continue. We have, as we've said, we've got about almost $100 million of mortgage debt coming due, and we have enough availability on our line to take that all down, but that would be a temporary measure.
Jay, some of our alternatives?
Jay Beckhorn
Yeah. As Gary said, we can take it down using the revolving line of credit, and then we'll look at how to put something out there more permanently, whether it be term loan or private placement.
Depends on the interest rates. We're looking at those alternatives actively, and I guess in Q1 we've got about half that exposure is maturing, and then the rest the balances over the other half.
Gary Gerson
Gaurav, as we repay those loans, given the amortization and the way our credit facility works, as we add those to the credit facility, they actually increase our availability.
Gaurav Mehta
All right. Thank you.
That's all for me.
David Gladstone
Thank you. Okay.
Next question.
Operator
Thank you. Our next question comes from the line of Rob Stevenson with Huntington.
You may proceed with your question.
Rob Stevenson
Good morning, guys. Buzz, taking the sort of opposite side of the transaction question, hearing a lot about significant demand from 1031 and especially bonus depreciation buyers heading into year end.
Is there an opportunity here for you guys to take advantage of that and sell some of the non-core assets here in fourth quarter and improve the portfolio that way?
Buzz Cooper
Certainly, Rob, we take a look at that and we track that, because, of course, we want to take advantage where we can. We don't have anything at the moment that we are looking to dispose of toward the end of the year, but our team out in the field, both asset managers as well as our producers from the standpoint of new originations, certainly have that in mind.
There's nothing I can tell you today that we're looking to flip out before the end of the year.
Rob Stevenson
Okay. Then when you look at the portfolio at 99.3% occupancy today, factor in upcoming lease expirations, as well as tenants that might be having some financial issues, is there anything on the horizon that pulls that occupancy back below 99%, or is this where you expect to be across the portfolio for the foreseeable future?
Buzz Cooper
As relates to tenants and their quality and credit, we're very proud of obviously the collections that we have, 100% paying as agreed, both office and industrial, obviously other than the vacancy. As relates to their quality, we have not seen a severe deterioration.
Certainly, we look at it on a quarterly basis. We haven't had anybody ask for relief.
Then as relates to your question on the maturities, we are currently in discussions and our biggest asset, as office concern is down in Texas. We are actually talking to an existing tenant looking to increase their occupancy within the building by another approximately 40,000 square feet, and believe that that will occur hopefully in the early part of the first quarter.
We do know GM rolls out within that building. However, that leaves us at a over 50% occupancy.
It also covers all expenses within the property so we don't have a burn, and we're evaluating whether we will continue to look to increase occupancy. And/or do we, at that point in time, look at perhaps a sale?
We are trying to maximize that building value, and are continuing to evaluate that. As it relates to our overall vacancy, specific to 2027, we have eight properties.
However, within that, in subsequent issues within the quarter, three were renewed at the end of third quarter for a plus-up of approximately $2.8 million. That took those of concern from 12 down to eight.
Into that eight, all have been in contact. We are in discussions with many of them.
One, I believe, is a lease out, and fortunately for a large office building. I feel confident that what currently would be going into 2027 a 5%, that that's going to drop in a very short period of time down to 2.66% as relates to 2027 figures.
Your question, will it go be low 99%? It will.
We're going to work hard to get it back up, but I still would submit it's a very strong number.
Rob Stevenson
Okay. Then last one for me.
Gary, the NAREIT and core FFO was the same in the third quarter. Anything hitting the income statement in fourth quarter that would impact positively or negatively the run rate heading into year end and into the beginning of '27?
Gary Gerson
Rob, don't see anything out of the ordinary coming up, we don't give forward guidance, but that's pretty much the best I could do. I don't think there's going to be anything that would do anything significant either way.
Rob Stevenson
Okay. Thanks, guys.
Appreciate the time.
Buzz Cooper
Thank you.
David Gladstone
Next question.
Operator
Our next question comes from the line of Dave Storms with Stonegate. Your line is now live.
Dave Storms
Morning, and thank you for taking my questions. Wanted to circle back to the comment around the plus-up of, I believe it was $2.8 million on the three that you worked on in the quarter.
I understand that the conversation is ongoing, is that typical of the conversations that you're having, or is there anything unusual there? Just trying to think of how we should think of any renewals.
Buzz Cooper
There is nothing unusual to it from the standpoint of leases that are coming due that have been on books for a period of time. As we know, within the marketplace, especially industrial, there has been rental rate increases.
I wish we had more that I could point to they're saying are down the line coming. We do have some renewals that are coming that will be plus-ups, but I can't tell you, Dave, that that is going to happen with that nice dollar amount here in the next quarter.
It's a function of when leases are rolling and when they were put on the books.
Dave Storms
Understood. Just wanted to make sure there wasn't, yeah.
Then also can we just ask one more? You mentioned earlier that you have nothing in your pipeline that you're maybe too actively looking to dispose of.
Just curious, is that maybe a product of non-availability with the portfolio right around that 70% for office? Just maybe any more information there would be helpful.
Buzz Cooper
Sure. We do look at our dispositions, looking out into '27, '28.
Yes, we do want to match up what we can with acquisitions with dispositions, so that that cash doesn't sit idly by, that we are putting it to work. It is a function also, as we do come here toward the end of the year, and especially now with inflation, with what we, in a quote-unquote "the war", and where we are from a economic standpoint for the country, we've seen a pullback of opportunities.
Where we are looking at potential opportunities would be on the development and construction and origination of sale-leasebacks with the developer at the point in time. That is not going to happen immediately, but we are looking at that deeply.
Dave Storms
That's great. I really appreciate you taking my questions and good luck in the next quarter.
Buzz Cooper
Thank you.
David Gladstone
Okay. Next question.
Operator
Thank you. Just as a reminder, if anyone has any questions, you may press star one to join the queue.
Our next question comes from the line of John Massocca with B. Riley Securities.
You may proceed with your question.
John Massocca
Good morning.
Buzz Cooper
Maybe
John Massocca
stick with that line of questioning around your comments around the investment pipeline. How kind of wide are you seeing that kind of buyer-seller disconnect?
Is there more opportunity in the sale-leaseback side, sale-leaseback potentially counterparties a little more agnostic around cap rate pricing? I guess, long-winded way of kind of asking, we saw kind of a reversal in the interest rate moves we've seen over the last call it three months.
Could that cap rate differential between you and third-party sellers kind of narrow quickly, or do you think there's going to be a period of just kind of rediscovery as to where pricing is?
Buzz Cooper
I would say a little bit of rediscovery, John. We did see a pullback, of course, because the uncertainty, both of inflation and the very rapid rise over 5% on the interest rates.
Heading here into the holidays, the end of the year, we generally do see obviously a slowdown. Then once the allocations, if you will, that come out going into the new year, I believe we'll see an absolute uptick both of third-party transactions, but also sale-leaseback and originations.
John Massocca
I guess maybe just to put it pretty simply, were you seeing deals in the pipeline in August, and just the counterparties don't want to budge on price, or is it deals actually completely falling out?
Buzz Cooper
No, I would say repricing. Again, the seller, I think, the disconnection as relates to on the purchase side.
We did not retrade, but I know there's been retrading going on in the marketplace, and I think that helped create a little pull
John Massocca
back. Then, going back to the Austin asset, is it kind of fair at this point to assume we're going to have a meaningful period of 2027 where that 3% of ABR essentially goes away?
I know you have another tenant in the building who might take some space, I guess how quickly would that rent come on from a cash basis, if you can provide any color there? Just fair to kind of assume that you're losing that ABR for a period of time, and I guess how quickly at this point do you think you can backfill the remainder of the space or a significant portion of the space in that Texas office asset?
Buzz Cooper
As you I'm sure are aware, there has been an uptick of activity in Austin specifically, and we have seen that within our building and with the tours and requests for RFPs that we have looked at. Yes, we're going to see a downtick here as relates to GM, which does leave here at the end of the year.
Of their space, again, we are in deep discussions on adding another 40,000, again, accretive in nature as relates to the cash flow within the building. We are working hard to fill it all, but it's taking time.
The activity in Austin has increased in the last four months greatly.
John Massocca
Then the impairment on the office asset in I think you said Lake Mary, Florida, what drove that? Is that just market comparability?
I thought I remembered that lease being a couple more years left on it. Just was kind of curious why the impairment for that asset.
Gary Gerson
Just is a change in the lease velocity in that area, and really where we are with leasing on that building is what drove us to impair it.
John Massocca
Right. The tenant is still in there for a couple more years, correct?
Gary Gerson
We have a tenant in there. That tenant will be in there through the middle of next year.
Then we have some additional tenancy potentially going forward. They're going to downsize the amount that they have.
The tenant will be in there longer, but the majority of the building they'll look to get downsized into a significantly smaller portion of it.
John Massocca
Okay. That's it for me.
Thanks very much.
Buzz Cooper
Thank you.
Operator
Thank you. We have reached the end of the question-and-answer session, therefore I'll now turn the call back over to David Gladstone for closing remarks.
David Gladstone
Oh, shucks, we didn't get enough questions this time. We like questions, we'd be happy if you'll save up some for next meeting, and we'll see you next quarter.
That's the end of this call.
Operator
Thank you, and this concludes today's conference, and you may disconnect your lines at this time. We thank you for your participation.