Fidus Investment Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 6, 2026
Operator
Good day, and welcome to the Fidus Third Quarter 2026 Earnings Conference Call. All participants will be in listen-only mode.
Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star, then one on your telephone keypad. To withdraw your question, please press star, then two.
Please note this event is being recorded. I would now like to turn the conference over to Jody Burfening.
Please go ahead.
Jody Burfening
Thank you, Megan, and good morning, everyone, and thank you for joining us for Fidus Investment Corporation's Third Quarter 2026 Earnings Conference Call. With me this morning are Ed Ross, Fidus Investment Corporation's Chairman and Chief Executive Officer, and Shelby Sherard, Chief Financial Officer.
Fidus Investment Corporation issued a press release yesterday afternoon with the details of the company's quarterly financial results. A copy of the press release is available on the Investor Relations page of the company's website at fdus.com.
I'd also like to call your attention to the customary safe harbor disclosure regarding forward-looking information included on today's call. The conference call today will contain forward-looking statements, including statements regarding the goals, strategies, beliefs, future potential, operating results, and cash flows of Fidus Investment Corporation.
Although management believes these statements are reasonable based on estimates, assumptions, and projections as of today, November 6th, 2026, these statements are not guarantees of future performance. Time-sensitive information may no longer be accurate at the time of any telephonic or webcast replay.
Actual results may differ materially as a result of risks, uncertainties, and other factors, including, but not limited to, the factors set forth in the company's filings with the Securities and Exchange Commission. Fidus undertakes no obligation to update or revise any of these forward-looking statements.
With that, I would now like to turn the call over to Ed. Good morning, Ed.
Ed Ross
Good morning, Jody, and good morning, everyone. Welcome to our third quarter 2026 earnings conference call.
Today's call will start with a review of our third quarter performance and our portfolio at quarter end, and then share with you our outlook for the remainder of 2026. Shelby will cover the third quarter financial results and our liquidity position.
After we have completed our prepared remarks, we'll be happy to take your questions. As expected, given the pent-up demand in the M&A markets, deal flow picked up in the third quarter relative to the first half of the year.
A number of our portfolio companies continue to be active from an M&A perspective as part of their growth strategies. As our strategy calls for investing in high-quality, growth-oriented companies, typically the need for add-on acquisition capital is often part of the equation and an opportunity for Fidus.
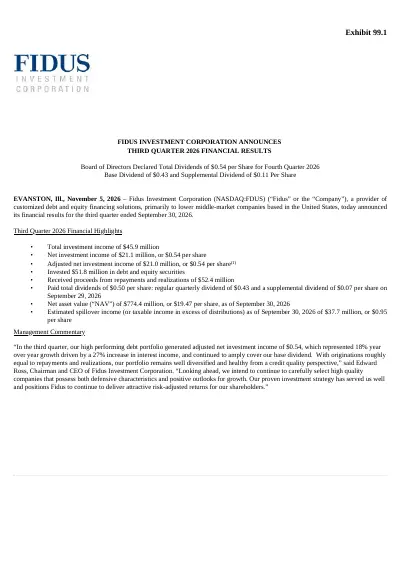
Overall, our debt portfolio is performing well, generating adjusted NII of 54 cents per share in the third quarter that was driven by a 24% increase in interest income on larger average loan outstanding balances. We continue to amply cover our base dividend.
Net asset value was $774.4 million at quarter end, or $19.47 per share. For the fourth quarter of 2026, the board of directors declared a total dividend of 54 cents per share, which consists of a base dividend of 43 cents per share and a supplemental dividend of 11 cents per share, equal to 100% of the surplus in adjusted NII over the base dividend from the prior quarter, which will be payable on December 29th, 2026, to stockholders of record as of December 18th, 2026.
Originations in the third quarter totaled $51.8 million and consisted primarily of first lien debt investments in existing portfolio companies in support of acquisitions. Proceeds from repayments and realizations were $52.4 million for the third quarter.
With originations nearly equal to repayments, our portfolio at quarter end was stable, totaling $1.4 billion on a fair value basis, or 102.8% of cost, and consisting of $1.3 billion in debt investments and $159 million in equity investments. At quarter end, first lien instruments accounted for 88% of our debt portfolio, and the weighted average loan-to-value was approximately 41%.
In addition, our portfolio remains well diversified and structured to produce both high levels of recurring interest income and capital gains from monetizing equity investments. From a credit quality perspective, our portfolio remains healthy overall, reflecting the generally strong fundamentals of our underlying lower middle market portfolio companies.
At quarter end, we did not have any debt investments on non-accrual. Looking ahead to the remainder of 2026, we anticipate a higher level of investment activity from an origination and a repayment perspective due to a more active M&A market.
Our pipeline consists of a number of quality opportunities, sourced from both longstanding relationships with deal sponsors and our portfolio companies, many of which are active in M&A. Since inception, we have focused on the lower middle market and employed the same investment strategy and strict underwriting criteria consistently, both of which has served us well.
As a result, we continue to have a healthy portfolio, well positioned to generate adjusted NII that covers our base dividend and the potential for capital gains from monetizing equity investments. By adhering to our investment strategy and underwriting disciplines, we remain committed to our long-term goals of capital preservation and of generating attractive risk-adjusted returns for our shareholders.
Now I'll turn the call over to Shelby to provide some details on our financial and operating results. Shelby?
Shelby Sherard
Thank you, Ed, and good morning, everyone. I'll review our third quarter results in more detail and close with comments on our liquidity position.
Please note I will be providing comparative commentary versus the prior quarter, Q2 2026. Total investment income was $45.9 million for the three months ended September 30th, a $2.4 million increase from Q2, primarily driven by a $2.2 million increase in interest income driven by increased average debt investments outstanding, a $0.9 million decrease in dividend income from equity investments, offset by a $0.9 million increase in fee income, primarily related to prepayment fees on the repayment in full of our debt investments in Tru-Environmental.
Total expenses, including income tax provision, were $24.8 million for the third quarter, in line with Q2. Q3 expense variations included a $0.7 million increase in interest expense related to higher average debt balances outstanding and a higher average interest rate, a $0.2 million increase in base management fees given an increase in assets under management, a $0.4 million increase in income incentive fees offset by a $0.4 million decrease in the capital gains fee accrual, and a $1 million decrease in G&A expenses, primarily related to proxy solicitation costs for the annual shareholder meeting held in Q2.
Net investment income, or NII, for the three months ended September 30th was 54 cents per share versus 49 cents per share in Q1. Adjusted NII, which excludes any capital gains incentive fee accruals or reversals attributable to realized and unrealized gains and losses on investments, was 54 cents per share in Q3 versus 50 cents in Q2.
For the three months ended September 30th, we recognized approximately $11 million of net realized losses on debt investments in Vertex Enterprises, which had previously been written down. We ended the quarter with $712.2 million of debt outstanding, comprised of $289.5 million of SBA debentures, $320 million of unsecured notes, $92.3 million outstanding on the line of credit, and $10.5 million of secured borrowings.
Our net debt-to-equity ratio as of September 30th was 0.9 times. Our statutory leverage excluding exempt SBA debentures was 0.5 times.
The weighted average interest rate on our outstanding debt was 5.8%, in line with Q2. Now turning to portfolio statistics as of September 30th.
Our total investment portfolio had a fair value of $1.4 billion. Our average portfolio company investment on a cost basis was $14.1 million, which excludes investments in eight portfolio companies that sold their operations and are in the process of winding down.
We have equity investments in approximately 85% of our portfolio companies, with an average fully diluted equity ownership of 2.1%. Weighted average effective yield on debt investments was 12.6% as of September 30th versus 12.5% in Q2.
The weighted average yield is computed using effective interest rates for debt investments at cost, including the accretion of original issue discounts and loan origination fees, but excluding investments on non-accrual, if any. Now I'd like to briefly discuss our available liquidity.
In Q3, we issued accretive shares under our ATM program and raised $35.5 million of net proceeds. In September, we received SBA approval for the new increased SBA debenture fund limit of $250 million, giving our SBIC fund, FMC IV, incremental debt capacity of $75 million.
As of September 30th, our liquidity and capital resources included cash of $32.7 million, $132.8 million of availability on our line of credit, and $83 million of available SBA debentures, resulting in total liquidity of approximately $248.5 million. Now I will turn the call back to Ed for concluding comments.
Ed Ross
Thanks, Shelby. As always, I'd like to thank our team and the board of directors at Fidus for their dedication and hard work, and our shareholders for their continued support.
I will now turn the call over to Megan for Q&A. Megan?
Operator
We will now begin the question-and-answer session. To ask a question, you may press star, then one on your telephone keypad.
If you are using a speakerphone, please pick up your handset before pressing the keys. If at any time your question has been addressed and you would like to withdraw your question, please press star, then two.
At this time, we will pause momentarily to assemble our roster. The first question comes from Robert Dodd with Raymond James.
Please go ahead.
Robert Dodd
Good morning, and congratulations on another very good quarter. A couple of questions.
One housekeeping one before I go into the more detailed ones. On the combined dividend and fee income, obviously basically they offset this quarter, right?
Dividend was obviously unusual, as recognized, and the fee was higher because of Tru-Environmental. Is it fair to say that if you just treat this quarter as quasi-normal or even arguably low when you compare on a combined basis?
Is that the right way of thinking about it? It's not like I should take out fee income next quarter and obviously leave the dividend being unusual.
Just trying to think about what the right combined number for that is kind of on a go-forward basis. The interest expense obviously is conceptually easier to model than dividends and fees.
Ed Ross
I think what I'd say is fee income was actually at a decent level because of Tru-Environmental prepayment fee. That's a decent level of fees, but usually we have more activity that drives even more fees than that.
I think that's a fair number. As the dividend income is more episodic in nature.
It's just tougher to predict. I think not expecting that every quarter probably makes some sense.
Yep.
Robert Dodd
Got it. Okay.
You indicated you expect obviously activity to pick up in the fourth quarter, obviously in your end of the market, right? Are there any particular themes in that?
Have people been waiting on the election? It seems unlikely because that only just happened.
Or is it picking up in more halo or asset-heavy industries, some of which you occasionally done? Or is there any particular thing that's more in favor right now that fits obviously within your portfolio?
Or is it just an overall? Or is in fact a lot of software stuff getting done?
Is there any incremental color on kind of what's driving that?
Ed Ross
Sure. It's a great question, Robert.
I think what happened in the market is things started to pick up midyear. From a deal flow perspective, we didn't have anything close in Q3, really.
We had one holdover from an commitment from Q2. Activity levels really increased.
I think it was generally folks getting more comfortable with the war, the geopolitical situation, and the economy, as we sit here today. I think there was a malaise during Q1 and Q2 that started to lift a little bit, and people are more interested in doing things.
That's the primary driver. I think the second driver is most of the activity is traditional economy related.
Call it let's say business services, maybe niche manufacturing, industrial services, those types of things. That's the second theme is what I would say, as opposed to software investing.
Robert Dodd
Got it. Thank you.
I appreciate that. Then one more, I'll ask you to get your crystal ball out.
Is this sort of a build to a year-end rush, which sometimes happens, or is this, do you think, a kind of a lifting swell and we're going to see more activity overall? Now to your point, if people have gotten comfortable with geopolitics, which might change, and the economy, that 2027 will just be a more active year, not crazy, but more active in general, is that fair to say?
Ed Ross
I think that's our hope, right? We're in a more uncertain environment today than we have been in quite a while, and so it's kind of hard to predict, but our expectation would be if status quo is what happens, that there would be a lift, if you will, in M&A activity.
I don't expect it to be overly robust. There's reasons that people don't want to do that, right?
High interest rates and other things. I think there will be plenty of activity assuming status quo.
Robert Dodd
Got it. Then, sorry, I thought that was the last one, but it's not.
One final one if I can. On pricing and spreads, etc., right?
Obviously, you have a first lien focused portfolio now. If activity does pick up, do expect it to have materially impact on spreads, or you just think this is where they're going to stay, or could they even go down given the forward curve says base rates are going to go up?
Just what do you think on pricing here?
Ed Ross
I think stability is probably where I would come out on that question. We're focused on very high-quality opportunities and high-quality businesses, and there's competition, it's real.
That's how I would think about it, as opposed to widening spreads. I don't think so.
Could there be a slight narrowing if rates do increase? That could happen, adjusting there for the, again, high-quality situations.
You start drifting into riskier situations, that's a different game.
Robert Dodd
Yep. Got it.
Thank you. Appreciate it.
Ed Ross
Thank you, Robert. Good talking to you.
Operator
The next question comes from Mickey Schleien with Clear Street. Please go ahead.
Mickey Schleien
Yes, good morning. Robert stole my thunder on a lot of questions, but I have a couple more that I'd like to ask.
Ed, your software exposure's pretty similar to the average in the BDC sector, it's something you're familiar with. I don't want to beat a dead horse, but AI is advancing very quickly.
I'm interested in understanding, and I think the market's interested in understanding, particularly in the lower middle market, where you focus, how are your borrowers using AI to defend their software businesses from AI competition itself? What are they doing to avoid being replaced by AI, if you understand what I'm saying?
Ed Ross
I do. I'll just maybe comment on just smaller software companies, because we definitely have some of those, and I know the concern is one of is there more risk?
I would say it's true that some, whether it's traditional or new economy, smaller companies can carry more risk, not always. From our perspective, we know the lower middle market well.
We've been investing in it for many years. Part of our historical success comes from finding niche market leaders, people that are leading from a market share and a product perspective, with strong value propositions and great management teams.
That's our focus. These are some of the criteria that we use, right, to build out our software and tech-enabled services portfolio.
We've got what we believe is a very strong and healthy overall software portfolio. The average revenue and EBITDA kind of $43 million and $7 million.
Margins are 15%. We continue to see year-over-year growth in both metrics.
We feel good about the health of the portfolio. What we're seeing from the portfolio companies on the software side is they're working hard and spending money on continuing to improve their business.
Obviously that's encouraging. They're leveraging AI to improve products and create new features at the end of the day, and they're also evaluating acquisitions and channel partnerships, to generate more customers.
I think what I would say is people are investing in AI. What your hope is your portfolio companies are well positioned today, and they can just improve that positioning.
That's what most companies are trying to do.
Mickey Schleien
I understand. A couple of balance sheet questions.
You tapped the common share ATM program again during the quarter, despite limited net portfolio growth. How are you thinking about additional equity issuances versus perhaps carrying a little bit more leverage on the balance sheet, which potentially could help increase your ROE?
Ed Ross
Sure. Great question.
I think what we're trying to do is stick between that 0.9 to 1 and 1.1 to 1, really in the middle. Our goal is not to go too far over 1 to 1.
We do care about our investment grade rating, and I think that's part of the equation as well. I think what we are trying to maintain is a strong balance sheet position, a strong liquidity position, we can take advantage of opportunities as they arise, as opposed to being fully levered and fully invested and maybe more limited from a capacity perspective.
There's a balance that you try to strike, and so that's the goal. Every quarter will be a little different, but I think we feel good about the approach.
Mickey Schleien
If I'm understanding you correctly, if the market were really going to pick up, and, in the current environment I think that's doubtful, but let's say it does, you're holding back some dry powder essentially and would be willing to run with a little bit more leverage if it makes economic sense.
Ed Ross
Yes, to a limited degree. Back to investment grade matters and not getting too levered, as I think is a piece of our equation, but yes, to a limited degree, absolutely.
Sure.
Mickey Schleien
Lastly, if I have the math correctly, the equity portfolio's marked almost 50% above cost, and if I recall, you did a trade a few years ago where you sold several equity positions to capture those gains, which was really interesting. How would you characterize your appetite and the near-term pipeline for exiting some of those equity investments and generating some realized gains?
Ed Ross
Sure. It's a great question, Mickey.
I think, where we are, I think we are happy with the positioning of our equity portfolio, but as you just mentioned, the market is not in a robust state. That will impact our realizations and the timing of those realizations.
Some of those are pushed out from our perspective. It's worth noting just to make sure I get it out there, I think the repayments we expect to be relatively healthy this quarter, most likely less than originations, but relatively healthy, but it's really on the debt investment side, not on the equity side.
We do see some potential realizations on the equity side in 2027. We've obviously had five or six realizations this year, we would expect a continuation of those kind of activities, if you will, as opposed to robust levels at the moment.
It's just the M&A market is not at that level at the moment.
Mickey Schleien
Right, so that would be plain vanilla M&A activity next year as opposed to you proactively trying to sell a chunk of that equity portfolio. Am I understanding you correctly?
Ed Ross
You are. Just to put a little meat on the bone, the reason we sold the equity was we were probably long in the tooth as a percentage of our portfolio.
It was over 20%, equity was. It just made sense to try to get some liquidity and try to drive more recurring earnings at the end of the day.
That was what drove that positioning, not the need for the capital gain. Obviously very good investments overall that we sold, to be honest, but it was to drive a portfolio that had a higher level of recurring earnings.
Mickey Schleien
Sure, I understand. Those are all my questions this morning.
I thank you for your time.
Ed Ross
Thank you. Good talking to you, Mickey.
Mickey Schleien
Likewise.
Operator
Again, if you have a question, please press star, then one. The next question comes from Christopher Nolan with Ladenburg Thalmann.
Please go ahead. Ed,
Christopher Nolan
just to rephrase a question that Mickey asked, for fourth quarter, should we expect some gains from this increased activity?
Ed Ross
No. I don't, and I tried to hit that at the end of that question in Q&A session with Mickey.
We're going to have a relatively high level of repayments, especially as compared to Q3, but it's really going to be on the debt investment side. On the equity realization side, I think it'll be very limited here in Q4 based on what we know today.
Christopher Nolan
Great. Then also, back to the AI for a second, business services is one of your larger industries.
Does that include law firms and consulting firms, industries which basically really could get displaced by AI? What comprises business services, please?
Ed Ross
It's a broad definition. It's a very broad definition.
Law firms we don't have. We obviously did something that's kind of providing a service, a court service, and you saw that in the subsequent events.
That's not something, quite frankly, that can be replaced by AI, if you will, that service. We feel very good about that.
We don't have any investments in law firms. Consulting firms, we really don't have any straight-up consulting firms.
Those aren't the types of business services companies that we have.
Christopher Nolan
Great. Final question is for private equity sponsors, they seem to be sort of under stress given the increase in interest rates and a highly competitive lower middle market lending market.
Are you finding that you might be making sidecar equity investments alongside loans or not?
Ed Ross
When you say sidecar, just to make sure I answer the question, do you mean just a co-investment alongside a private equity group?
Christopher Nolan
Exactly.
Ed Ross
Yeah. What you just hit on is our strategy.
When Shelby said that we have equity investments in 85% of our portfolio companies, she's highlighting that we are co-investing with typically the ownership group, which is quite often, almost always a private equity group. That is the strategy.
What we like about the lower middle market is yes, it is competitive, but it's very, very fragmented, and it's where 90% of where we play is probably where 90% of the M&A activity in terms of number of deals take place. It gives an opportunity to originate very high-quality situations and businesses, which is the goal, as opposed to fewer number of companies and you got a bunch of people that can provide those solutions.
It's a different equation from an origination perspective. We like that aspect of it.
Yes, from an equity perspective, we co-invest with the sponsors. What we're looking for are companies where we like both the debt investment, we also like the equity investment.
That's our general goal, if you will.
Christopher Nolan
I should have clarified it. Are you expecting to invest more equity than in the past for deals going forward?
That's what I was trying to get to. Huh.
Ed Ross
Okay. Great question.
No, I would say the answer to that is no. Our general strategy has been kind of up to 10% of our capital that we deploy over time in the form of equity investments.
On a cost basis, we're at a lower level than that. On a fair value basis, we're 11% now.
Up to 10% on a cost basis is how we think about it.
Christopher Nolan
Thank you.
Ed Ross
Thank you. Good talking to you, Chris.
Operator
The next question comes from Paul Johnson with KBW. Please go ahead.
Paul Johnson
Good morning. Thanks for taking my questions.
In terms of the current vintage, it doesn't sound like necessarily you see any kind of meaningful movement in spreads. Is there anything else, I guess, that you think that you're extracting more of today within covenants or any sort of documentation terms that you think is better in the current vintage?
Ed Ross
It's a great question, Paul, but if you think about it from a recent history perspective, covenants have been there for a while. When we started investing in first lien debt, having two maintenance covenants, and that really started in 2018, was part of the equation, and that continues in the lower middle market.
We have what we believe is real maintenance covenants that give us a seat at the table when there are things like acquisitions going on or things aren't going as planned. We like that aspect of it.
I think pricing, I don't see big changes there. Leverage, I do not.
I think leverage is very much in check for obvious reasons, if not maybe a little bit lower, but let's say it's stable as well. Then loan-to-values are also very healthy.
We're in the 30% to 50% range on our originations, or expected originations in Q4. So 30% to 50%.
That's always been a focus of ours, and something that we really try to stick to, if you will.
Paul Johnson
Got it. Thanks for that.
Last one is maybe a higher-level question, but it's not historically been a part of your business that I'm aware of, but if there is some sort of scenario where maybe M&A is taking longer to recover, and exit timelines are being extended along with loan maturities, is there a scenario where these sponsors potentially create some sort of dividends, not necessarily like a full recap, but start to draw on dividend income to create some sort of DPI for these businesses within those funds?
Ed Ross
I would say to a limited degree. The answer to that is yes.
What we have seen primarily, though, is high-quality businesses sponsors like to hold on to. They do try to generate some form of dividend, and maybe they'll do that two or three times, quite frankly.
We have seen that over the years, and we would expect that to continue at the end of the day. There are times in where you have lower leverage situations where you can generate consistent dividend, but that's I would say the minority for sure, as opposed to the majority of those situations.
Paul Johnson
Okay. Appreciate it.
That's all for me. Thanks.
Ed Ross
Good talking to you, Paul.
Operator
This concludes our question-and-answer session. I would like to turn the conference back over to Ed Ross for any closing remarks.
Ed Ross
Thank you, Megan, and thank you, everyone, for joining us this morning. We look forward to speaking with you on our fourth quarter call in late February 2027.
Have a great day and a great weekend.
Operator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect.