United Utilities Group PLC
Q2 FY2027 · Earnings Call TranscriptNovember 12, 2026
Lou Beardmore
Good morning, everybody, and thank you for taking the time to join Phil and I on the call this morning. Hopefully, you've all managed to read the announcement and see the presentation we released earlier this morning, and could I ask that everybody please stay on mute unless you're asking a question?
With that, let's jump straight into Q&A. If you have a question, please raise your hand.
Brilliant, great to see those coming through. First question.
Morning, Pav, nice to see you.
Pavan Mahbubani
Morning, Lou, Phil, nice to see you too. Thank you for the pre-recorded presentation this morning and for taking my questions.
I'll start with two, please. Firstly, Lou, we've had a few things coming out over the last few weeks, a letter from the Secretary of State talking about the future for the sector, and Ofwat laying out their initial views of the PR29 framework.
It would be great to hear your thoughts on those publications, how you think the water sector reform is going, and maybe some help as to what investors should be looking for in terms of reforms going forward, what you think are the key milestones, that would be helpful. That's question number one, please.
Then secondly, I'd love to hear a bit more about the rain only into Windermere sort of project, how that's shaping up, what the milestones are there, if we should see a big step-up into AMP9. I don't know, Phil, if it's too early to start putting numbers to that project and what that could look like from an investment perspective.
Those are my questions, thank you.
Lou Beardmore
Brilliant, thanks very much, Pav. Look, the first one, I think recognize there's a number of publications out there at the moment in terms of the sector more broadly: the Secretary of State letter, the sort of consultations we've been having from regulators on PR29.
I think what's really clear is we're now starting to see come through, I suppose, Sir John Cunliffe's recommendations. We're starting to see the sort of natural momentum as we progress towards implementation.
I think what's really important is that the stability of the contract that's in place, the five-year process, is expected to stay. I think what is really important is that we have seen movement from Ofwat.
The movement to the annualized reopener process was something that I've talked to you all about, something that we've really welcomed, something that you've seen that we've moved very positively on. As a result of that, I've strengthened the team so that instead of the sort of five-year AMP process being something that's done on a cyclical basis, essentially we have the capability and we have the expertise to step into what I think we will see, which is more annualized reopeners as we move forward.
I think what is clear is that there is a greater focus on place, and we saw that last week in terms of the conversations about water councils. I think we're really, really positive about that, and I've talked at length about the changes that I made to the business, the fact that we're organized around county, is very much because that places us at the heart of our communities.
I think what's really encouraging is that from a GMCA perspective and the work that we did in Greater Manchester with the Prime Minister obviously when he was mayor, has actually provided the blueprint for how those things are going to work. I think we'll see much more focus on place, much more focus on prioritization, but I think we're really, really well placed for how we respond to that.
I was at the Labour Party conference, I took the opportunity to have a conversation with a number of ministers and mayors, and I think it was really important that the Prime Minister himself acknowledged the need for continued private capital in the sector and the emphasis on supporting good companies. I think our county-based model and the position in the region really, really plays to that.
Thanks ever so much for your questions on only rainwater. I'm really pleased with the progress that we've seen on only rainwater into Windermere.
This is a really special place. It's a UNESCO World Heritage Site, it's one of the biggest freshwater lakes not just in the UK, but in Europe.
This was the coming together of a number of parties: so regulators, local businesses, us as the water company, campaigners, environmentalists, looking at essentially what were the long-term options for preservation for Windermere as we go forward. This is an ecosystem that is seeing the level of temperature in the lake rise, that is also seeing the huge amounts of rainfall, more than anywhere else in the UK.
We need to move away from this sort of five-year thinking. We launched the feasibility study a couple of weeks ago, that was really well received, and essentially what we're now doing is moving into detailed design, which we expect to start in April, and that will run for two years.
As part of that detailed design, that will flush out the business case, the detailed design, the construction plan, and essentially the catalyst then to have those conversations with government about approval to ultimately get into implementation. Phil, do you want to pick up the point about funding?
Phil Aspin
In terms of funding, I guess, as Lou said, it's a two-year plan in terms of the design process, and that pretty much aligns it with our PR29 process as well. Really, from a funding perspective, this all sits within that PR29 future sort of bucket in the context of AMP9 and beyond.
Pavan Mahbubani
Great, thank you.
Lou Beardmore
Great, thanks, Pav. Our next question, we've got James Brand from DB.
James Brand
Hello, congrats on the very solid results. Had a couple of questions also on kind of regulation.
I'd say very, very solid results, not too much to ask about there. My questions are, on the water bill, we had some comments from Angela Eagle that it was going to be a tougher water bill, and we also had comments that they wanted to have the ability to intervene in the next price control.
Now there are kind of elements of Cunliffe which you can certainly look at as being tougher, and obviously government sets direction for the regulator anyway through the priorities that they set out in the past for Ofwat. I guess my question is, do you think that those comments suggest something new and different or just kind of continuation with the pathway that was set out by Cunliffe?
That's the first question. Then secondly, on the regulatory review, could you just remind us what the timeline is for the new regulator being set up, if there is one, and kind of how that interplays with the regulatory process, because, as Pavan said, Ofwat kicked it off, but will it be Ofwat that will be completing this regulatory review, or will that be the new regulator?
Thanks very much.
Lou Beardmore
Great, thanks, James. Look, I think on the first question, I think we all recognize that the political and regulatory risk is high at the moment.
There's a number of commentary pieces. I think what I would say is in terms of what am I seeing and what am I feeling, I was at the Labour Party conference, as I said.
I had an opportunity to talk to a number of ministers. We've obviously been working in a way in the North West that is slightly different to others in that we have essentially been organized both around those counties, but around that devolved politics in terms of the mayors and how they work.
I think, as we step forward, how we think that this is going to work in relation to those water councils. I think what you've heard from the Secretary of State is that she's talking about putting place-based planning and oversight at the heart of the regulatory process.
Instead of a one size fits all, which is something as we went through the Cunliffe review, I had a lot of conversations with Sir John about the need to ensure that we were doing the right things for each place. I look after a region that serves 8 million people, but essentially the needs of Cumbria are fundamentally different than the needs of Merseyside or Manchester.
I think you're going to hear an amplification of regional, place-based planning, and that's right, because the things that we're having to do to support the growth that we're seeing in Greater Manchester is very, very different than what's happening in Lancashire, just as an example. I think what's really important, as I said earlier, is the work that we did with GMCA, the way that we're working with the sort of devolved administration, has actually been highlighted by Defra, and was actually used by the Secretary of State herself last week as the example of how this should work in practice.
I think we're going to see much more of that, and I think we moved three years ago to move to be county-based, and that's proved to be really, really well placed, both in terms of the way we're operating and the way that we're interfacing across our communities. I think your second question was actually around what's the timeline and the regulatory process.
In terms of what I'm really seeing at this moment in time, I'm seeing more integration from our regulators than I've ever seen before. Actually, the EA, the DWI, and Ofwat working together in a much more integrated way.
I think in practice we're seeing more of this, and I think that's to be actively encouraged and welcomed, and those levels of engagement are strong with all of those regulators. I'm really encouraged by the approach to PR29 so far.
The letters that we've received, both from the Secretary of State and from regulators, set out the direction of travel, and that direction of travel is very much consistent with what we're expecting to see. For now, look, we're working constructively with all our stakeholders, both regionally and nationally, to make sure we get the right package that reflects the needs of each of those five counties and places that we serve as we step into AMP9.
James Brand
Thank you very much.
Lou Beardmore
Great, thank you. Good morning, Jenny.
Jenny Ping from Citi, nice to see you.
Jenny Ping
Hi, morning. I think somebody else was before me?
Lou Beardmore
Sorry. No, go ahead Jenny, it's fine.
Jenny Ping
All right, okay, sorry. Sorry.
Right, I've got a couple of questions, please, and and thank you for the opportunity. Firstly, just in terms of the reopeners, can you just give us a an update on where we got to on the HyNet funding methodology around the 260 million?
Secondly, just sticking with the bigger picture as per the previous questions, anything you're expecting to come out of the 10-year plan from Burnham that's been touted to to be in just before Christmas? Then a third, just to Phil on net interest.
Obviously, you've indicated a a step-up in terms of the interest for the full year. Can you just give us a a sense of how much of that is arguably coming from inflation, higher net debt, refinancing?
I would have thought, that surprised me, because I would have thought there's a interest earned element coming from your equity raise, which offsets some of that at least. If you can sort of give us a help us to understand where we could look to land for the full year.
If I can squeeze in one very small one, just on the ODI penalties, obviously we've had the draft adjustment mechanism which lower the penalty. When you say you're improving, is it on the old number or on the new number?
Thank you.
Lou Beardmore
Thanks for that, Jenny. I think I've got all four of them, but we'll do them in the order.
Firstly, reopeners. From a sort of reopener process, obviously we stepped into that fulsomely.
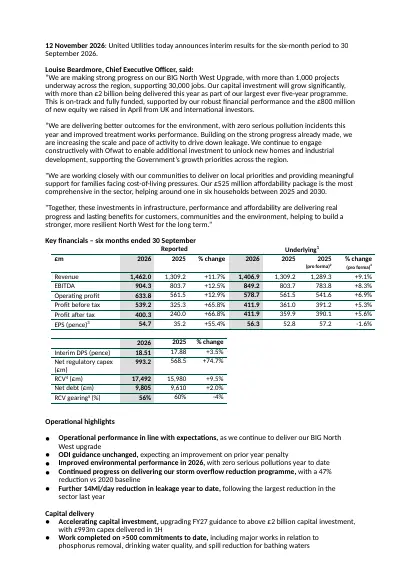
We had the draft determination in August of around 950 million in real 22/23 prices. Adding inflation, that takes the DD to around 1.2 billion.
We've gone back with further evidence after the draft, and specifically, the detail around some of these additional projects. I think you asked the question about HyNet specifically.
We have proposed that there's a couple hundred million of that that essentially will go through a gated mechanism for industrial projects. That's because HyNet is in discussions as to whether it will or it won't proceed.
If it doesn't proceed, we won't put that infrastructure in the ground. We're very, very well versed for going through that gated mechanism process, and we've already started to go through that.
Having lots of conversations with HyNet, and we're obviously waiting the final element of that determination to come through in December. Your second question was about the 10-year plan.
We're still expecting this before Christmas. The 10-year plan doesn't just cover water.
I think it's really important when we see that, it's not perhaps going to have the granular level of detail that we may expect just on water. What this is is essentially it's an integrated plan.
This is consistent with how I've seen the Prime Minister operate when I've worked with him and with his administration in Greater Manchester. Essentially, what he's talking about there is a 10-year plan for infrastructure, for energy and for water, but also essentially for housing and for transport.
The reason it's those four things together is they're essentially the ingredients that you need to ensure that you have the catalyst for growth. I think what we will see is a much more greater articulation about the need for integrated planning, about the need to ensure that if we spend a pound, that we're maximizing the opportunity to do so.
That's very much what we've been doing in GMCA. In other words, if there's a housing development going in, how do we make sure that at the same time we're upgrading the energy network, the water infrastructure, and we've got the right transport networks, too?
I think it's going to be structured in that specific way. I'll let Phil answer the questions on net interest and on ODIs.
Phil Aspin
Morning, Jenny. I guess just unpacking the the net interest bit for you first.
I guess you're quite right in terms of the equity proceeds. That was obviously factored into our guidance at the full year when we gave that guidance.
At that point, we saw the net interest charge, net finance charge being marginally lower than the prior year. A couple of things probably have happened since then.
You'll see that we're tracking really positively in terms of our capex delivery. Really good momentum coming into this second year with the enterprise arrangement we've got in place.
As a consequence, we've uprated our capex guidance to over 2 billion effectively for this year. That's meaning that we are spending a little bit more money earlier than we've perhaps expected to, as a consequence.
Secondly, and probably the bigger driver, is the inflation component. As I sort of said on the presentation this morning, inflation is running higher than we all expected at this point, and that's feeding through.
The net impact of all that is sort of a very marginal sort of increase on the prior-year prior-year position. Sort of we've just have tipped from one side of the prior year to the other side effectively.
Your second question was on the ODI penalties. A couple of things to say on on ODI.
Our guidance sort of remains sort of -35 to 0 is the effective range that we're sort of guiding to, i.e. an improvement on the prior year before the OEM mechanism.
Now, there is some sort of positive news feeding in in terms of things like C-Mex and the Mexes has come through positively. We're tracking well in terms of performance, and, at this at this point, we're we're, we're very very, very comfortable with where we are in our guidance range.
Obviously, we have to go through the winter period. In terms of sort of why why not sort of adjusting that guidance relative to the OEM, the OEM is a function of where everybody else is in the industry, and that can move around.
There's no sort of there's no predictive sort of position you can take from where the OEM adjustment was this year to what it might be next year. Our performance is being tracked against the underlying position.
As I say, we're in a very, very strong position, and we're we're heading into the winter as as positively as we could be, really.
Lou Beardmore
Great, thanks, Phil. Thanks, Jenny.
Look, apologies if Phil and I are slightly out of order in terms of who's got the hands up. It's how you're presenting on the screen to us.
I'm going to keep going down the list as Phil and I see them. Next, I can see Mark Freshney from UBS, nice to see you, Mark.
Mark Freshney
Yep, no, thank you. Good to see you as well, Phil and Lou.
Just, it was a question for Phil, just on credit. As I understand it, credit markets have become a little bit trickier in that, because there's so much utility debt, not just on the bond side, but on the bank loan side, what you're seeing, particularly on the bond side, is that days that big issuers are active in the market, spreads are starting to move some way.
How are you handling that? We've seen other companies go in, like National Grid go in and re-enter Canadian bond markets, etc.
What are you seeing there, and how are you handling it? Are you still confident that you can raise within the allowances, and I accept there's a tracker within the price control, and I accept that Ofwat made some big changes regarding, I think, the halo effect, but are you still confident that you can hit credit markets and outperform the Ofwat indices given what we're seeing now and the risk that hyperscalers just completely move spreads up?
Phil Aspin
I guess the short answer, Mark, is yes. You're right.
Credit spreads have ballooned out, sort of hyperscalers are having a big impact on that. Obviously, some of that feeds into the sort of iBoxx index that we're tracking against.
We do have the benefit of that debt indexation model, which provides mitigation for that risk. The treasury team are a very effective and very agile in terms of how they approach markets.
We sort of have got a sort of full range of options available to us in terms of issuance, and we're in a very, very strong liquidity position. We're never in the space where we feel we have to push a deal out if the markets are not in a great space.
We're in a fortunate position. We can bide our time, issue when the markets are more receptive, and lock in good performance as a consequence.
I guess in the first half of this year, we've done relatively small amount of issuance, recognizing the equity raise that we did in April. That issuance that we have done has been locking in around about 90 basis points of outperformance.
Continue to perform strongly in terms of financing, and the team are very well positioned to carry that forward.
Mark Freshney
Thank you.
Lou Beardmore
Great, thanks, Mark. Next up, we've got Joy at BNP.
Joy Xu
Thanks, Lou. Hi, Phil, congratulations on the solid results this morning.
I have a couple of add-on questions from earlier. Firstly, on the water reforms and sort of broader politics, are you worried at all about the pace of implementation, even though the direction of change is going in the right direction?
Because we've seen a couple of delays so far, and the transition plan seems to be now pushed back even further. Is there a risk that we might not see the new regulator in place before PR29?
Then second question is on water councils. Obviously, you've said that you're quite positive about that.
Do you think that that actually puts you at an advantage, given that you guys were already working in that type of partnership in the North West? Does it change your day-to-day operations in any way, if at all?
Last question is on capex. You've raised your capex guidance slightly to now above 2 billion.
At the trading statement, it was still around 2 billion that you were guiding to. Could you just remind us what are the underlying drivers behind that increase again?
Does it change your profile of future years' spending, as well as your RCV guidance for this year? Thank you.
Lou Beardmore
Brilliant. Thank you for that, Joy.
Right, a couple of things there. I think the first one in terms of pace of implementation, look, I'm always going to say I want things to go quicker.
I want them to go quicker because I've got a restless ambition for the fact that I think we can, we should, we must drive changes quicker than we do. What I would say is that I am seeing behavior and, more importantly, action on the ground that says to me regulators aren't waiting.
When we're having interactions and conversations with regulators, what we're essentially seeing is that that's been done in a way that is much more coordinated than it has in the past. The point of moving at pace, moving at speed, is something that we continue to press for.
As we sit here right now, I don't see there is a risk that that new regulation won't be in place for 2029 at all. I think there is a clarity and, more importantly, an ambition that that will be there.
I think in light of the fact that some of it will require legislation drivers that I think we can expect to see come through next year, in terms of the next reading of the water bill, what I'm seeing in practice is that that's already happening. Your question about water councils is I'd say yes, we absolutely are best placed in the sector, because this is the way that we've been operating.
The move to the five counties has been really at the heart of some of the success that we're seeing. The fact that we've been able to mobilize the significant capital program that we have has been at the heart of the fact that we're organized into these counties, we're clear about what we need to do, we're working effectively with local authorities and stakeholders, and with the supply chain to enable the change in that place.
I think the whole sort of blueprint, if you like, is that people are talking about and referencing, as the Secretary of State did herself last week, the work that we've been doing with GMCA. Essentially it's taking that, it's deploying that more broadly.
Again, each organization or each county, if you like, has slight nuances that it's important that you reflect and you adapt to. I'd say we are absolutely well placed, and further ahead than others because of the way that we've been working.
I think in terms of our day-to-day operations, those relationships are already there, those interfaces are already there. I think we'll have some work to do to get everybody else up to speed.
We're hosting lots of visits at the moment as people want to come to the North West and see how we've been operating, and we're keen to share some of that learning, as well as learn from others, too. In relation to capex and the underlying drivers, look, I'm really pleased that we've upgraded the guidance slightly this morning.
In part, because one of the biggest challenges about delivering this AMP period was always this sense of this is a big step-up. Could you really enable that to happen?
I'm really pleased with what I'm seeing on the ground: the way that the supply chain has responded, and the way that my colleagues have responded, and the sheer amount of work and projects that are live across our region. The fact that we're able to step in confidently with those capex numbers is a reflection of the momentum that we've built, that energy, that ambition, and that determination to get this program delivered.
In relation to, well, what does that mean for future years? Look, I'm really clear: the more we can deliver quicker, the better.
There's two reasons. One is you never have time on your side.
The more we can do quickly means that essentially we make sure we're then well placed to go into AMP9, and do so in a way that manages that transition and manages that transition well. In terms of RCV and the wider financial points of that capital profiling, Phil?
Phil Aspin
Just picking up the capex guidance remains the £11.5 billion over the AMP. This is a phasing and a timing issue, but as Lou said, it's all about momentum, and it's all about having that positive momentum going forward, which positions us really well as we head towards AMP9 effectively.
Lou Beardmore
Brilliant, thank you for that. Next up, we've got Laura from Barclays.
It's lovely to see you, Laura.
Thank you very much, and good morning, everyone. Two questions from my side.
I think UU is now the last company that still has an outstanding enforcement case from Ofwat. Is there any update regarding that, and do you have any views regarding getting rather an incremental investment commitment instead of a financial penalty?
Then my second question is if we can still expect the strategic policy statement to be published by the end of this year, or if you still expect that to come through at all, given the water bill and everything else. Thank you.
Lou Beardmore
Great, thanks ever so much. Look, the first question around the enforcement case.
If you remember, we've got two investigations: one that's with Ofwat, and one that's with the Environment Agency. United Utilities was one of the last companies to go in to the investigation with Ofwat, and we're the last to come out, purely a fiction of timing in terms of the team working through that.
I would expect that that will crystallize in the coming months. Obviously, conversations are ongoing, I'm not in a position where I can share that more broadly, but I think we'll expect a conclusion to that shortly.
In relation to the strategic policy statement, I think we'll see what I call as some slight nuances around timing. I think we had the communication a couple of weeks ago from the Secretary of State and from regulators as well that set out the themes for AMP9.
I think that essentially was an ability to provide that forward sight and that forward view in advance of I think we can expect the 10-year plan first. In terms of what I'm expecting to see, I think it will be that 10-year plan, and then I think we'll see the strategic policy statement then follow on from that essentially as an anchor.
I suppose that's the sort of sequencing that I'm expecting to see, Laura. Bartek, nice to see you this morning.
Thank you very much. Good morning, and thank you for taking my questions.
Let me ask three, maybe, if I may, and just coming back to a topic we used to discuss a lot a couple of years ago, meaning power prices and the impact on earnings. Obviously, this time you are much more derisked, and you will get a recovery at the end of AMP8, but the question here is when are we going to see higher power prices feeding through your earnings?
Because I presume right now you're hedged. Power costs have not increased, but sooner or later we may see an impact on your earnings.
Just to confirm, because obviously on the totex side you will probably not report an underperformance on the power costs, because it will be recovered towards the end of AMP8, but will it impact earnings or you will try to kind of smooth earnings as well, given the fact that there will be a recovery mechanism later on? Second of all, if we just think about totex efficiencies, totex outperformance overall, Lou, if you just look at the last one and a half years, how has your view changed on the possibility and potential to deliver totex efficiencies?
Has something changed? I don't know, inflation is higher, supply chain constraints, etc.
Maybe the last one, back in AMP7, you actually did a one-off capex increase to boost your ODIs. You may remember.
Do you think you can do something similar in AMP8, or what would prevent you not to do it? What would be actually the basis not to do it this time again?
Thank you very much.
Lou Beardmore
Great, thanks, Bartek. Phil?
Phil Aspin
Shall I take the power? Okay.
Morning, Bartek. If I just pick up the power position first.
You're quite right. We've had a long-standing policy of hedging power costs.
As we sit here today, we're 100% hedged for the current financial year, effectively FY27. As I look forward, that hedging sort of the following year sort of is around about 70% to 80%, the year after that 50% to 60%, and the year after that sort of 30% to 40%.
That's very consistent with what you would have expected, because that's the policy that we have that's sort of set out there in the public domain. We've got a very sort of active program of hedging and smoothing that power price position, we're not exposed to sort of extreme volatility.
As you also say, we also benefit from the DESNZ sort of index sort of adjustment mechanism, so that's a further level of protection as well. Power in the current year isn't really a big impact on numbers.
In terms of how that will be reported, clearly power costs will go through totex, and the DESNZ mechanism is something that's outside of totex, because that's an ex post adjustment mechanism for AMP9. Those two things are quite separate.
Lou Beardmore
In relation to totex, and sort of focus on inflation and supply chain, our guidance has remained unchanged. We expect returns to be between 10% to 11%.
The contribution comes from financing, totex, ODIs, and PCDs. We've never sort of provided to that explicit components, but what I'd say is that I'm really pleased with the progress that we're seeing on ODIs.
There is some upward pressure on our expectations, but at the same time, that cost of compliance is rising. Overall the guidance is unchanged, and we're sort of performing in line with those expectations.
You also asked a question about one-off cost increases to sort of bolster or deliver additional ODIs returns. I think this AMP period is different because the actual ranges from an ODI perspective are different in terms of that opportunity for those returns.
Look, we'd look at everything on a case-by-case basis, and would make the right calls based on what those returns would look like. I think that probably covers all of the questions.
Thanks for that, Bartek. I think next up, we've got Alex from RBC.
Alex Wheeler
Morning, two from me, please. Just firstly, as we progress through the first reopener, has anything changed in your view, or any learnings for future reopeners?
Then on that point, does the affordability challenge come into the debate more going forward for reopeners, given how heightened it is politically at the moment? Then my second question is just how we should think about transition capex.
Appreciate you said that the capex buckets are fluid across the plan. Can you remind me, is the transition capex contingent on the evolution of the PR29 regulation at all?
Would a better regulatory outcome lead to a higher ramp-up, or alternatively, does the annual reopener process and a more flexible reg structure reduce the need for that transition capex within the plan? Thank you.
Lou Beardmore
Great, thanks, Alex. Look, I think we learned a lot from the reopeners.
I've said before, I was really pleased to see them, because five years is a long time. I think what we were able to do with that reopener is essentially lean into that growth narrative, and back to the way we're working with GMCA, to ensure that we could then put forward the infrastructure that's needed for the new town that's being built, for the additional industrial growth that we're seeing in the city.
I think the process works really well in terms of your ability to respond in cycle. I was really pleased, actually, with the feedback that we got from Ofwat as a regulator, the way that we engaged other regulators in our reopener process.
We were one of the very few companies that also liaised with the DWI and got their support for the proposals that we were putting forward. I think the way that we both entered into the process, made sure that it was very heavily evidence-based, the fact that we ensured that costs were in line with Ofwat's methodologies and what they were expecting to see, meant that, yes, look, there was a good outcome, and we've consolidated that learning.
We're already working now on the reopener that's going back in March. It's essentially taking those learnings and consolidating them as we move forward.
I know affordability has started to crystallize a little bit more, but I'd also say that for the North West and the customers that we represent and are proud to serve each day, affordability is always really at the heart of both how we operate and, more importantly, how do we ensure that customers are supported. We have one of the biggest and most comprehensive affordability packages in the sector: £525 million worth of support, one in six customers that were able to help with different support packages.
We haven't got a one size fits all. We're I think one of the very few, I think maybe even the only water company that is accredited with Martin Lewis, for example.
We're doing a huge amount in that area, and we continue to do so. I think I'm really pleased that I've heard the government talk more about the national social tariff, and you know where I sit on that about the fact that I think that is something that's needed, and we continue to push for that.
In relation to transition capex and the evolution of PR29, look, I think there are things that we know now that we need to deliver in AMP9 because essentially they're set out in legal drivers. I know there are certain things I have to do by 2035, and some of those are very large and very significant projects.
Therefore, the ability to get going on those in advance of the sort of 1st of April AMP9 start date is always very, very helpful, because again it just gives us that extra time to ensure confidence and ensure delivery. Because they're set out from a legal perspective with very clear delivery drivers, there is a surety that those things, as they sit here today, have to happen.
Phil, would you add anything to that?
Phil Aspin
No, I think that's pretty well covered it. I think clearly the momentum around our capex program and the enterprise arrangement we have positions us really well to be able to step into the discussions with regulators around accelerating transition investment.
All of that sort of is part and parcel of why you've got to build the solid foundation and platform we have today heading into those reopeners and the TI discussions we'll be having with regulators.
Lou Beardmore
Brilliant, thanks, Phil. We've got a follow-up question from Mark at UBS.
Mark Freshney
Hey, no, thank you. This is perhaps a question for Andrew, your corporate affairs manager.
There was a concern back in May, some of the rhetoric on taking back control and what that would mean for water. Andrew and yourselves had understood pretty clearly what Manchesterism is, and were fairly confident as to what Mr.
Burnham's philosophy actually meant for the water sector. I suppose my question is, given the last 6 months and everything we've seen, are you more or less confident in your view that taking back control doesn't mean nationalization or any kind of adverse intervention versus what you're doing now?
Lou Beardmore
Great, thanks for that question. Look, I'm really clear that, and actually I think what's really important, the Prime Minister himself has been really clear.
I was there at the Labour Party conference, and the Prime Minister was very clear that there needed to be continued private capital in the sector. He talked a lot about the place and the fact that we need to be organized and we need to be planning around place, and he also talked a lot about the fact that we need to be delivering the things that local communities wanted and needed.
I think what's also really important is that the communications that we've seen coming out keep referencing us back to GMCA, and the way that we've been working. It's been highlighted by Defra, it's been highlighted by the Secretary of State.
I think what you're seeing is essentially the administration shaping politics and shaping sort of investment away from the center and away from national oversight, much more to be delivering at place and to be delivering the things that those communities want in a way that is enabling growth, in the way that that growth was enabled in Greater Manchester. I suppose, having worked in the model and understanding the administration and what it's trying to achieve, I think it is consistent.
I think we will continue to see sort of noise as we move from one to the other. I don't think that will go away.
There are some real challenges out there for the sector that it needs to deal with. I think the county-based model and, more importantly, focus around place is the right thing, and that's why we were very keen to lean in to the changes that were announced last week.
Phil Aspin
Mark, if I can just build on that also a bit and add, clearly when we had our Capital Markets Day, you and others on the call sort of joined us there, and you got to see first-hand how we were working collaboratively with GMCA and Stockport Council in terms of the urban redevelopment there and the sustainable urban drainage that we put in place at Stockport. That's a really good example of the place-based planning and application that's delivering a win-win solution for the water company and for the local population.
Mark Freshney
I think it's a very good answer. Thank you very much, Lou, thank you very much, Phil.
Brilliant.
Lou Beardmore
Look, thanks very much. Thank you to everybody again for joining us.
If you have any follow-ups, please don't hesitate to let us know. We'll happily take any calls or contacts as we go through the next couple of days.
I suppose last, not but least, I'd just like to say thank you to the team. We've had a great 6 months, a huge amount of hard work.
The capital program is moving with a momentum and a pace that we are keen to ensure that we've got our heads down, we're focused on delivery, on the things that matter, such as serious pollutions. I think we're the only company in the sector that hasn't had a serious pollution.
We're seeing improvements in our underlying treatment works compliance, leakage is coming down, and at the same time, really strong levels of employee engagement. There's a huge amount to do.
I'm conscious we're stepping into the winter, and therefore we need to keep focused on that performance. Very many thanks to everybody in United Utilities that's working so hard.
Very many thanks to everybody for joining us on the call today, and we look forward to updating you again at the full year results. Thank you.
Phil Aspin
Thank you.