ICON plc
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Good day, and thank you for standing by. Welcome to the ICON plc Q3 2026 Earnings Conference Call.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there'll be a question-and-answer session.
To ask a question during the session, you will need to press *11 on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press *11 again. Please be advised that today's conference is being recorded.
I would now like to turn the conference over to your first speaker today, Kate Haven, Vice President of Investor Relations. Please go ahead.
Kate Haven
Hello, and thank you for joining us today. I'm joined on the call by our CEO, Barry Balfe, and our CFO, Nigel Clerkin.
I would like to note that this call is webcast and that there are slides available to download on our website to accompany today's call. Certain statements in today's call will be forward-looking statements.
These statements are based on management's current expectations and information currently available, including current economic and industry conditions. Actual results may differ materially from those stated or implied by forward-looking statements due to risks and uncertainties associated with the company's business, and listeners are cautioned that forward-looking statements are not guarantees of future performance.
Forward-looking statements are only as of the date they are made, and we do not undertake any obligation to update publicly any forward-looking statements, either as a result of new information, future events, or otherwise. More information about the risks and uncertainties relating to these forward-looking statements may be found in the most recently filed annual report on Form 20-F.
This presentation includes selected non-GAAP financial measures, which Barry and Nigel will be referencing in their prepared remarks. For a presentation of the most directly comparable GAAP financial measures, please refer to the section of the press release dated October 27th, 2026, titled Consolidated Statements of Operations.
While non-GAAP financial measures are not superior to or a substitute for comparable GAAP measures, we believe certain non-GAAP information is more useful to investors for historical comparison purposes. Included in the press release and the earnings slides, you will note a reconciliation of non-GAAP measures.
Adjusted EBITDA, adjusted net income, and adjusted diluted earnings per share exclude amortization, stock-based compensation, foreign currency gains and losses, restructuring, transaction, integration-related and other adjustments, transaction-related financing costs, fair value movement on investments in equity, goodwill impairment, loss on disposal of subsidiary undertakings, impairment of non-financial assets, and their related taxation effect. We'll be limiting the call today to one hour, and in the interest of time, we ask participants to keep their questions to one each.
I would now like to hand the call over to our CEO, Barry Balfe.
Barry Balfe
Thank you, Kate. Our third quarter results mark another clear step forward, in line with the plan that we set out to deliver earlier this year.
Strong commercial momentum, continued earnings growth, and disciplined execution continue to reinforce our confidence in the outlook for the business and the opportunities ahead as we move into 2027. Quarter three results were very much in line with our expectations, and I was particularly pleased that we saw progress in the areas that we had previously indicated.
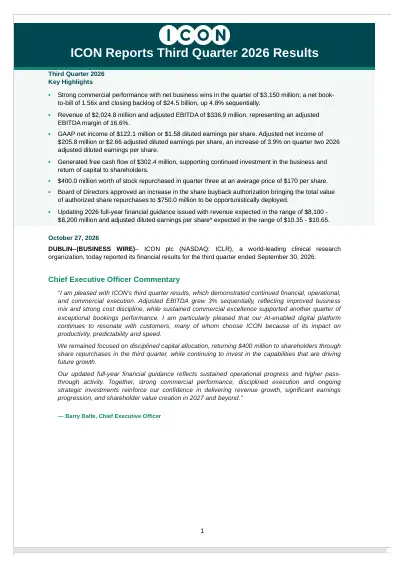
Gross margin improved by 90 basis points sequentially as our direct fee mix improved, and new awards began to burn in line with expectations. Adjusted EBITDA grew sequentially to $337 million, and adjusted EPS was $2.66, an increase of 4% compared to quarter two.
That follows from our commercial performance, which was, again, excellent. Gross business wins increased by 27% year-over-year and 3% sequentially.
Consequently, net business wins were a record $3.15 billion, up 51% year-over-year, yielding a net book-to-bill of 1.56 times. This was ICON's fourth consecutive quarter with a net book-to-bill greater than 1.3 times.
Notably, our trailing 12-month direct fee book-to-bill was also 1.3, an improvement of circa 30% on the preceding 12-month period. This strong execution translated into strong cash generation, with $300 million of free cash flow generated in the quarter, supporting the repurchase of $400 million of shares, and a cash balance of $800 million at quarter-end.
Combined with the $2.15 billion investment-grade bond issuance in August, this creates ample strategic flexibility for ICON to pursue our capital allocation priorities, including organic investments, selective M&A, and return of capital to shareholders. Looking at customer groups, large pharma remained a source of continued strength in the quarter.
We saw strong contributions across both full-service and FSP, including the expansion of an existing alliance through the addition of a large-scale pharmacovigilance portfolio. Multi-year FSP renewals were also notable, reflecting customers' continued preference for flexible partnership models and their confidence in ICON's ability to deliver at scale.
Among mid-size pharma, opportunity flow continued to strengthen, with an encouraging pipeline of partnership activity. With new and expanded mid-size partnerships in the quarter, we are increasingly seeing customers adopt a more strategic approach to partnering in this area, utilizing a broader mix of our clinical, laboratory, and functional capabilities.
In biotech, overall demand remains constructive, supported by a healthy funding environment. We maintained our focus on expanding our universe of biotech targets and are now covering 30% more companies in this sector than was the case one year ago.
The rollout of new intelligence tools to track molecules through the development cycle has enabled us to better calibrate early engagement with emerging sponsors. As these biotech customers advance their pipelines into later-stage development, programs naturally become larger, more complex, and increasingly global in nature.
This benefits ICON as sponsors seek out partners with the necessary scale, breadth, and expertise to execute on these challenging programs, while preserving the agility that they continue to value. We saw evidence of this during the quarter with the addition of three preferred partnerships with enterprise customers in biotech, including a four-year sole-provider arrangement spanning all phases of development.
As established biotech and mid-size companies seek strategic partners to support their long-term development needs, the expertise, governance structures, and alliance management capabilities that have served ICON so well in large pharma are proving increasingly valuable. Fundamental disruption of the clinical development paradigm remains the strategic priority for ICON.
Across all market segments, sponsors' engagement with our tech transformation agenda continues to accelerate. While elements of this transformation may take time, customer decisions are increasingly driven by evidence of innovation that creates value and competitive advantage today.
Our excellent commercial performance has, to a significant degree, been driven by the suite of capabilities that our teams have already put in the field. In biometrics, SDTM programming agents in production since February have cut programming cycle times by 28% on in-scope studies.
Study startup throughput, key indicator of impending clinical activity, grew about 30% year-to-date, enabled by a range of agentic capabilities. SmartDraft is just one example, site contracting cycle time reduction of 10% over the year, with near-term targets extending to an additional 20%.
Our monitoring agent, Meridian, continues to resonate with customers, and is designed to deliver significant gains for both FSO and FSP customers. As we've spoken about before, these disruptive technologies are enabling our customers to meaningfully reduce time, cost, and uncertainty in their ongoing programs, and to redeploy surplus capital to portfolio expansion.
This is fundamentally changing the nature of commercial discussions with customers, with sponsors increasingly focusing on expertise and outcomes, rather than just on effort. Supporting that shift, we continue to make targeted investments in therapeutic and scientific expertise to support the increasing complexity of clinical development, and to press ICON's advantage in some of the most attractive growth areas in the industry.
This includes building on our long-standing strength in oncology, where we've expanded capabilities in patient advocacy, emerging modalities like radioligand therapies, while also expanding capacity in high-growth areas such as endocrinology and neurology. Finally, we have narrowed our 2026 guidance range to reflect greater visibility and disciplined execution, as current trends support positive momentum on revenue and earnings for quarter four.
While we will issue formal 2027 guidance with our quarter four results, at this stage, the leading indicators are moving the right way, with four strong quarters of bookings, a growing backlog, and an improving business mix creating a clearer view of the scope for revenue growth and meaningful earnings progression. Before I hand over to Nigel to take you through a more detailed look at the financials, I'd like to thank all of my ICON colleagues for their continued commitment, energy, and focus.
Their work every day supports our customers in bringing forward new treatment options for millions of patients around the world. Nigel.
Nigel Clerkin
Thanks, Barry. Revenue in quarter three was just over $2 billion, representing a year-on-year decrease of 2.9%, or a decrease of 2.5% on a constant currency basis.
Compared to the second quarter, revenue decreased 1.9%, primarily reflecting the divestiture of Symphony, while adjusted EBITDA increased 3% to $337 million, expanding adjusted EBITDA margin by 70 basis points to 16.6%. As mentioned last quarter, based on year-to-date activity, we believe that pass-through activity levels will exceed our prior assumption of being approximately flat year-over-year.
Our updated full-year guidance reflects this higher pass-through activity, supporting an increase in our revenue outlook to the high end of our prior range. Overall customer concentration in our top 25 customers was broadly aligned with quarter two 2026.
Our top five customers represented 23.7% of revenue, our top 10 represented 38.9%, while our top 25 represented 63.1%. Adjusted gross margin for the quarter was 24.7%, an increase of 90 basis points over quarter two, driven by improved business mix and operating cost management.
Strong cost discipline also resulted in adjusted SG&A expense of $163 million in quarter three, or 8.1% of revenue, compared to $179 million in quarter three 2025, or 8.6% of revenue. Adjusted net interest expense was $43 million for quarter three.
In the comparable period last year, net interest expense was $47 million. The effective tax rate was 18.6% for the quarter.
We continue to expect the full-year 2026 adjusted effective tax rate to be approximately 17%, due to some timing benefits in the fourth quarter. Looking ahead to next year, we'd expect our effective tax rate to be approximately 18% for the year.
Adjusted net income for the quarter was $206 million, equating to adjusted earnings per share of $2.66, a sequential increase of 4%. US GAAP income from operations amounted to $199 million, or 10% of quarter three revenue.
US GAAP net income in quarter three was $122 million, or $1.58 per diluted share. From a cash perspective, quarter three had cash from operating activities of $340 million.
Capital expenditure was $38 million, resulting in free cash flow in the quarter of $302 million. During the quarter, we successfully completed a $2.15 billion investment-grade bond issuance, the proceeds of which were used to repay our senior secured term loan, redeem our May 2027 notes, and repay our bridge secured credit facility.
As a consequence of this refinancing, our total debt of $3.4 billion has a blended annual fixed interest expense of approximately $200 million. At September 30, 2026, cash totaled $809 million, leaving a net debt position of $2.6 billion.
This compares to net debt of $2.5 billion at June 30, 2026, and $2.9 billion at September 30, 2025. We ended the quarter with a leverage ratio of 2.0 times net debt to adjusted trailing 12-month EBITDA.
Our strong balance sheet and free cash flow generation continues to provide flexibility to execute a balanced capital allocation strategy, enabling us to invest in the business, pursue selective M&A opportunities, and return capital to shareholders. Consistent with this approach, we repurchased $400 million of shares in the quarter at an average price of $170 per share.
In addition, our board approved a new $750 million share repurchase authorization, underscoring our confidence in the business and our ongoing commitment to shareholder returns. With that, we'll now open it up for questions.
Operator
Thank you. To ask a question, you will need to press *11 on your telephone and wait for your name to be announced.
In the interest of time, please limit yourselves to one question only. To withdraw your question, please press *11 again.
We will now go to the first question. One moment, please.
Your first question today comes from the line of Eric Coldwell from Baird. Please go ahead.
Eric Coldwell
Thanks very much. Good morning, good afternoon, and congrats on the strong commercial development progress you're making here.
I want to focus on direct fee revenue. It's encouraging to hear that it's recovering.
It seemingly would still be down, though, based on results and the higher pass-throughs you're talking about. Correct me if I'm wrong on that.
Just based on what you're seeing with these very strong direct fee awards over the last year, when would you expect to return to stable direct fee revenue growth? Then would you be willing to give us a ballpark of what level of incremental margin might be expected on the early days of a direct fee recovery, if you will?
Thanks so much.
Nigel Clerkin
Hey, Eric, it's Nigel, and thanks for the question. I think you can start to see the evidence of this in our Q3 results, Eric.
You did see our gross margin increase nicely over the quarter before. As we talked about previously, we always did expect to see our H2 EBITDA increase and our margins improve in dollars as we see improvements in business mix and operating cost control, and that's exactly what we have seen.
To your point, Barry touched on we've had four quarters now of consistent, really strong commercial performance. We've talked before about it does take some time for that to start to show up in the P&L, but we are seeing the first signs of that.
Barry, I don't know if you want to comment in terms of the outlook as we head into next year.
Barry Balfe
Look, I think while direct fees were up very modestly sequentially, the fact that they've returned to growth is an important milestone. I think the underlying business mix and the associated cost controls is what drives the margin expansion.
90 bps on gross margin and 70 on EBITDA margin, I think is certainly encouraging. The question on the relationship between margin recovery and revenue obviously depends on the revenue profile, Eric.
It's I'm sure going to be the first of several questions nibbling at 2027, maybe I'll get that out of the way. We're not guiding today.
I think that's been made clear. In talking about this this morning, is it certainly viable for us to think about mid-single-digit revenue expansion next year and maybe higher-single-digit expansion on earnings?
It's certainly a decent jumping-off point. Like I say every quarter when people ask me, are we going to replicate the book-to-bill, you look at the data, you say there's certainly fuel in the tank to make that a reasonable objective, and then it's about execution.
Whether we finish above or below those numbers will ultimately be determined by how effectively we as a team keep doing what we do best, which is engaging with customers to understand their needs, deploying the platforms that resonate most strongly for them, and then leveraging the best delivery, execution, and expertise in the industry to turn that into a fair return for shareholders. This is a quarter that looks a lot like we expected it to and like we've been saying it would since May, and certainly through June and July calls.
I think if we continue on this path, those sorts of options are certainly in play. As I say, it's a little early for guidance, but we feel good about the trajectory, and we feel good about the underlying points that indicate an inflection that you've alluded to.
Hope that covers it. Thanks.
Operator
Thank you. Your next question today comes from the line of Ann Hynes from Mizuho Securities.
Please go ahead. Ann, your line is open.
Due to no response, I will move on to the next question. One moment, please.
Your next question comes from the line of David Windley from Jefferies. Please go ahead.
David Windley
Great, thanks. Good morning, good afternoon.
I'll pivot off of Eric's question and ask around composition of bookings to try to understand a little bit, Barry, what is kind of driving the really, really strong commercial performance, but also to try to understand how we should expect that to convert. You're talking about beginning to feel that, but obviously under normal circumstances, unless your burn rate plummets, you should see significant revenue acceleration.
I'm trying to understand what about these makes them be accompanied by so much pass-through? What's the duration?
What's the therapeutic area? Just any color that you can help us to understand how they are so strong, and how we should expect them to roll out.
Thank you.
Barry Balfe
I'll answer as many of those as I can remember, Dave. Let me do my best on it.
I think your point is well made. I suppose the first thing to say is trailing 12-month direct fee book-to-bill of 1.3, while it's outstanding, it's certainly industry-leading, and I think it has been in each of those quarters.
It also comes on top of a preceding 12 months that were closer to 1.0. If you think about the revenue build, and you think about the sequential burn rates in the first, second, third, fourth, and then fifth, sixth, seventh, eighth quarters after those awards, it's clearly a combination of those two things, right?
It's why I've called it out in the prepared remarks. The preceding year obviously wasn't as good and has been a weight on that revenue build, it is a blend of those two things, and I think that's certainly important.
The book-to-bill strength is driven primarily in any given quarter, just given the relative scale of the business unit and the bookings policy, by full service. I think it's relatively straightforward to model the kind of burn rates that we've seen on that, and to have some confidence that the revenue recovery now is exactly what you would expect to see in the context of having come out of 12 months on a trailing 1.0 and moved through a 12 months on a trailing 1.3, and moving forward with some confidence next year, which is where I was going with the numbers I was just riffing on with Eric there.
If this business translates these kind of book-to-bills into mid-single-digit revenue expansion next year, that would not be unheard of given the kind of book-to-bills, and also strength elsewhere in the portfolio. Does that give you the opportunity at least to say there's enough gas in the tank to turn a 1050 midpoint into something more like an 1150?
Who knows? There's no reason why not, right?
As I say, execution is everything. In terms of pass-throughs, I guess the only two things I would say is that, yeah, there's a lot of awards come with a lot of pass-throughs here.
I don't know if it's more or less than anyone else. I suspect nobody does, because I think we're the only ones giving you that level of transparency.
We do that for a reason, because I think it helps investors understand the strength, the market share gains, and the phasing of the book-to-bill. I would also say that these are high-class problems.
It just so happens that some of the most sought-after opportunities in the market just now come with a very high pass-through coefficient. While I don't care about the pass-throughs in and of themselves, the complexity around pass-through is a really small price to pay for the kind of execution that the team are delivering.
It's not just commercial, it's operational, it's medical, it's scientific, it's technological, and I'm really pleased with it. To the extent that the world gets really deep into the analytics on this, I don't know how you can do any sort of comparative analytics on it when you think about the changes in bookings policy.
I think you guys are aware we're really conservative on FSP, which doesn't carry any pass-throughs, really. We put in only one year, whereas some of the other very large CROs put in three, four, five years of FSP into backlog, or indeed into the awards in the period, you could get some pretty skewed analytics if you were trying to do a side-by-side.
Hopefully that sheds some light on the nature of your inquiry, Dave. I think these numbers are entirely consistent with what we would have hoped for a year ago, with what you would expect now, and entirely consistent with the kind of indications we're thinking about for 2027 and beyond.
Operator
Thank you. Your next question today comes from the line of Justin Bowers from DB.
Please go ahead.
Justin Bowers
Hi, good afternoon/morning, everyone. Just continuing with Dave's question, Barry, that 1150, is that consistent with your guidance philosophy of excluding buyback?
I know you're not talking about 2027 guidance, but just to clarify that. Then secondly, if I may, could you talk about the demand environment and what the funnel looks like?
Any kind of indications around FSP, FSO mix? There's a lot of noise/questions from investors around that as it relates to large pharma.
Barry Balfe
Justin, thanks for the questions. Look, we're not guiding now, the intricacies of how people build models and what they want to do is really not something I want to be drawn on.
I was really more just trying to build a bridge intuitively around what's the relationship between backlog, bookings, revenue inflection, and earnings potential, right? Take that as a for instance.
I really did mean it when I said we're not guiding today, maybe I'll give you that and leave it there. I think in terms of the demand environment, it remains really robust, at least for us, in large pharma FSO, which I'm not sure everybody expected 18-24 months ago.
I think it's been really robust, and we're really pleased with where that's been. It's never just selling one service, right?
People tend to think about Phase 2-3 clinical when I talk about large pharma, but you look at FSP, you look at labs, which have been posting some great numbers, you look at evidence generation, where book-to-bill has been very strong, you look at a number of partnerships where we've added in new strings to that partnership bow, like the pharmacovigilance program I mentioned being layered onto an existing alliance. These are the things we said we wanted to do.
We're already working at significant levels with, I think, 28 of the top 30. I can't print new pharma companies.
What I can do is open up the number of distribution channels and sell more services along those channels, and I think that's been pretty positive. In mid-size, I think we talked about the demand environment there, and in biotech, I'll refer you to my earlier comments, but across the board, opportunity flow is up high single digits on a trailing 12-month basis, and that's sort of mid-to-high across different ends of the range or different parts of the business.
I think we're pretty satisfied, probably aligned with everybody else, frankly, on the demand environment. We're probably seeing the same demand as others.
I just think we happen to be converting it at a slightly better clip, which is a good thing. On FSP, FSO, obviously the numbers are a little bit different just because of the bookings and backlog policy.
We've said for some time we've been very pleased with the development in our FSP business, as we have in areas like labs and some of the ancillary peri-clinical services that go with that. The area we needed to throw some real fuel on the fire was in FSO, and I think that's been borne out by these bookings, which as I always say, those book-to-bills are disproportionately impacted by sales in FSO, so that's very, very encouraging.
To add one new mid-size, to expand another, and renewed in the quarter, to take three biotech customers from more transactional relationships to these preferred partnership statuses that much more closely resemble alliances, obviously we're talking to more established biotechs now, that's good. I also think the fact that we're engaging with 30% more biotech targets than we were a year ago speaks to our strategic intent that we've been talking about for some time.
Not just about how much demand out there, it's about how much of it you're meaningfully engaged with and at what rate you can convert it from opportunity to award, award to revenue, and revenue to earnings. It was a pretty broad question.
I hope I've addressed the general gist of it, but I'm sure a classmate might jump in for a clarification if I haven't. Thanks, Justin.
Operator
Thank you. Your next question today comes from the line of Charles Rhyee from TD Cowen.
Please go ahead. Oh,
Charles Rhyee
yeah, thanks for taking the question. Barry, just from what you just said there when talking about getting preferred relationships now into biotech as well, you kind of talked, I think, in your opening comments about companies now focusing more on expertise and outcomes versus effort.
Just curious if that kind of focus maybe on outcomes perhaps or expertise, is that changing maybe how contracts are pricing and being structured? Do you foresee, particularly as you also start to deploy more, let's say AI tools as well into the process, can you talk about maybe how you maybe envision pricing in the CRO industry, or at least for you, could change over time?
Barry Balfe
It's a great question, Charles, and it's a really sort of broad church of potential answers, let me drill down to what I think the key points are. One, of course, there's always discussions about rates.
They're never going to go away. We have a very savvy customer base who employ lots and lots of people to make sure they're getting value for money in terms of the rate per hour or rate per unit effort or whatever it's going to be.
I think the point is that there's a much greater potential for saving time, for saving money, and reducing uncertainty by changing the way we work together and committing ourselves to results and to transformation than there is to arguing over the rate per hour of a monitor, a manager, or anybody else. Now I'm not suggesting that pricing isn't incredibly competitive on the rate side, it is, but I think people understand that just because we give our teams much superior tools, simplified workflows, greater data insights, it doesn't reduce the cost of employing those people.
It means those people can do more, better research faster. I regularly start with these negotiations and saying, 'I'm happy to sit in the rate discussion where it needs to be, but I'd much rather have a conversation where we look at a business and say, we think we can make you X% more efficient, more productive, or faster.
We're willing to underwrite the first Y%, but after that, I want Z% gain share because I've got investors, too.' I think these are more productive conversations.
I think when you get above the cut and thrust of individual study or project sourcing into alliances, into preferred partnerships, into the executive tier, where really we're talking about developing a portfolio, and recycling surplus capital back into broadening the portfolio, running more studies better rather than running the same number of studies cheaper, then I think that's the kind of language that tends to resonate. Candidly, the customers who are making the most progress and the most rapid transformation are the ones who are coming around to that way of thinking fastest.
In our experience, I can't speak to everybody.
Operator
Thank you. Your next question today comes from the line of Elizabeth Anderson from Evercore.
Please go ahead.
Elizabeth Anderson
Hi, guys. Good morning, and thanks so much for the question.
Maybe sort of a two-parter. One, just to confirm, it seems like what you're saying, sort of based on your prior commentary, is that on sort of a like-for-like basis, you are getting sort of similar economics, given some of the increase in services, etc., that you're adding on, as you were sort of maybe a year or so ago.
There's no sort of fundamental change, or if there is, it's on a positive side. Then two, cancellations, as you pointed out last quarter, came in a little bit above quarterly.
Is that the right run rate to kind of think about going forward? Thank you.
Barry Balfe
I'll take the second one first. I don't think there's much to see on the cancels line, Elizabeth.
In a world where 5% to 6% is whatever par is, we think it's in around that range. They came in pretty close to 6%, nudge over.
I don't see anything in there, to be candid, no change. I'm not entirely sure I understood the question on economics.
I think when we look at the business, it's about making sure we understand the importance of converting this backlog, to make sure we avail ourselves of some positive operating leverage. I think that's important.
When we think about a pricing environment, I'm not sure if that's where you were going, it's not that the volume of work has changed transformationally, it's that the way we're going to do that work over time is transforming significantly. The economics of how you factor in effort, or how you factor in pricing and contracts will all evolve over time.
I think we're seeing customers vote with their feet. I think increasingly, customers are choosing providers who can a, deliver value, confidence, and results today, at the same time as aligning with and leading that larger transformation, that disruption of the clinical development paradigm that I talked about.
I don't know if there's anything more fundamental than win rates, and I think to a very significant degree, one of the reasons the teams have sustained win rates or book-to-bills that candidly are much better than we need them to be, right, I don't need them to stay that good to deliver the kind of results that we've been talking about, but one of the main reasons they have done, is because sponsors are telling us that the plan is resonating, the capabilities are delivering tangible, incremental gains now, at the same time as joining them on their glide path. There's always a hybridization of our transformation and theirs and making those two things fit together.
When I'm asked how ICON differentiates in the marketplace, there's lots of different ways, but I always call out our approach to partnership. It's one of the things we hear back repeatedly.
It's about the ability and the desire to meet customers where they are and reconfigure your side to match theirs rather than the other way around. I hope I got the nuance on economics, but if not, please let us know.
Happy to follow up.
Operator
Thank you. Your next question today comes from the line of Michael Cherny from Leerink Partners.
Please go ahead.
Michael Cherny
Good morning, and thanks for taking the question. Maybe, Nigel, just one clarification.
I just want to make sure I heard you right. Did you say $43 million of net interest?
I just want to get that right based on the press release. Then maybe building on Elizabeth's question a little bit, but as you think forward relative to what you noted, Barry, is an ongoing dynamic of price and rate conversations, what are you doing proactively to basically offset that, and how much of your push or investment in AI now is part of that managing to an EBITDA dollar profit level going forward?
Thank you.
Nigel Clerkin
Hey, Mike, it's Nigel. I'll take the first one.
Yes, net interest expense, non-GAAP in the quarter, was $43 million. Then, Barry, do you want to take the second one?
Barry Balfe
I think it's a pretty broad church again, Mike, if I understood your question well. The first thing to say is that we manage pricing, cost base, and opportunity conversion in the aggregate, and a lot of it comes back to where we perceive economic value that we can create, and the economic value that we can capture.
I think the teams have done an exceedingly good job on cost control. I'm not surprised by it, but I am pleased with it.
Credit to Nigel and the GBS teams on the G&A cost controls. We've always said we will seek to phase our cost action and our investment agenda within the parameters of business performance in that period, and we continue to do that well, reflects that well.
I also think that the operating teams have done really well to grow operational head count where there's capacity to be done now, or capacity to deliver now, but also sought to offset that where there were other efficiency gains elsewhere in the business where we perhaps didn't need the same weight of head count to deliver the same volume of work. It's a blend of all of those things.
When you get in the room with the customer, it's ultimately about understanding what's important for them. There are times, I've said this before, where we'll walk away from work.
If I stratify the reasons why we lose, price will come out as high as anything else. In fact, I think it was joint highest in the last quarter, if I remember the data well.
There are times when a race to the bottom on pricing doesn't work for ICON. It doesn't work for the sponsor in my view either, but it certainly doesn't work for me, and it doesn't work for our investors.
If that's the case, we are happy to pass on this one, to keep making the argument for transformation, efficiency, better study delivery strategy, and conversion on that basis, and we'll catch you on the next go-round. I don't say that glibly.
We don't like walking away from work. I would much rather lose twice with the right idea and have a customer come back than win once with the wrong idea and have them never work with us again.
That's a bit of a core philosophy around here, and not one I seek to change.
Operator
Thank you. Your next question today comes from the line of Ann Hynes from Mizuho.
Please go ahead.
Ann Hynes
Great, thank you, and sorry about before. I just want to ask about margins.
Margins came in higher than my expectation. Is it tracking ahead of your expectation, and are you still on target to end the year at that mid-16.5% range?
Also, I know you don't want to give 2027 guidance, but is there any major headwinds and tailwinds that we should know about? Thank you.
Nigel Clerkin
Hey, Ann, it's Nigel. I'll take that one.
Look, the margins obviously do reflect what we talked about previously. We did expect to see improvement on the dollars line as we went through the year based on improvements in business mix and obviously operating cost efficiencies and so on, as well, as we talked about before.
The reported margin percent, we've also said consistently, does depend on the degree of pass-through revenue to some degree as well, obviously. Getting on to your point in terms of full year, look, the range we set out reflects that.
We've obviously increased the revenue range reflecting higher pass-throughs as we've gone through the year. I think the last time we spoke, I said we anticipated full-year margin, EBITDA margin, of somewhere in the region of 16% to 16.5%, and that's still on track for that, depending on where we are in that revenue range, which fundamentally will be largely driven by where we are in terms of pass-through activity for the fourth quarter.
Essentially though, underpinning all of that, on track absolutely in terms of our expectations from an operational delivery perspective and progression from an earnings dollars perspective most fundamentally. Heading into next year, Ann, Barry obviously touched on earlier an initial perspective on potential for next year, but obviously not guiding just yet.
The factors remain the same factors, Ann, obviously pass-through activity, we will continue to monitor, but really encouragingly, having seen multiple quarters now of strong commercial performance, it does take some time for that to start to turn into the P&L, as we talked about before, but all those leading indicators do point to a framework that should allow us to see revenue growth next year. Barry gave some perspective in terms of potential for that, and that should translate, we would hope, into meaningful earnings progression as well, as we said, given the strength of the business, given the platform that we have, and given the opportunity for operating leverage.
We'll guide when we get to Q4, but very encouraged with where we are right now.
Operator
Thank you. Your next question today comes from the line of Jailendra Singh from Truist Securities.
Please go ahead.
Jailendra Singh
Thank you, and thanks for taking my questions. First, a quick housekeeping item.
Given a few moving parts below the EBITDA line and so much focus on EBITDA, are you guys even considering guiding on EBITDA maybe for next year, or are going to stick with revenue and EPS? My main question on the following up on the last discussion about the margin outperformance, I believe you guys were expecting SG&A to increase sequentially in third quarter from second quarter, which is because of some one-time items in second quarter, but it was largely flat.
Can you provide any color there? Trying to understand if 3Q SG&A level a good run rate, or we should model anything different?
Nigel Clerkin
Hey, Jailendra, it's Nigel. I'll take both of those.
Look, it's a reasonable question in terms of guidance framework for next year. Obviously, we are thinking about lots of things in terms of guidance framework for next year.
Leave that with us, and we'll be back to you with Q4 results and guidance. Understand your perspective on that.
Certainly what we will absolutely try to do is make sure we give enough commentary that people have a reasonable perspective on what we think the outlook for the business is throughout the P&L, and we've tried to do that as we've gone through this year, I hope you'd agree. To that point on your second question, yes, we did anticipate or we did say that we thought SG&A would increase in Q3.
Having said that, frankly, we're certainly not going to apologize for really strong cost discipline in the quarter. I wouldn't read too much into that, Jailendra.
Partly that was, again, just that strong cost discipline, partly it was some phasing of investments and so on. Looking into Q4, look, I do think SG&A should increase in Q4, my previous comments are probably still relevant for the fourth quarter.
Again, that is one of the things we will be looking to manage hard as we go through the rest of the year. We put out a range for a reason, and let's see where we end up with that within that range ultimately.
Operator
Thank you. Your next question today comes from the line of Kevin Caliendo from UBS.
Please go ahead.
Kevin Caliendo
Thanks, and thanks for taking my question. Really looking forward to covering you in the sector going forward.
Given the improvements in the business, your past year accounting issues, and the like, I guess my question is, we saw one deal already, a decent-sized deal, in the space. What's the appetite that you might have for bolt-on or larger-scale M&A going forward, just given where we are now in the cycle?
Barry Balfe
Hey, Kevin, it's Barry here. You're very welcome, look forward to speaking with you.
We've been pretty consistent on this, as I hope we have on everything else, that the appetite, indeed the priority, is for a balanced approach to capital allocation that will include the continuing return of capital to shareholders, investment in strategic capabilities organically, and selective M&A, where we think that the timing, the valuation, and the strategic fit is right. You should expect to see all three from us.
I don't think we're talking about transformational M&A. I sometimes roll my eyes when I hear some of the postulations on that topic.
I don't think anybody needs ICON to get bigger just for the sake of getting bigger. I think any M&A that we would look at would have to pass a test: are these areas that are potentially high-growth, potentially high-margin, and a highly strategic fit for us, whether that means that they give us a right to win or they are in an area where we have a high right to win, whether it's an enabling function that increases our right to win in other areas, or whether it's simply building on parts of the business that are growing really, really quickly, but we think we can boost that growth or get an injection of inorganic investment.
I think that's really where we are. I'm not too concerned about more transformational M&A in the space.
You shouldn't be thinking about us going out to spend $15 billion on a $10 billion asset. I don't think that would be good for ICON, and it's not something that we would entertain.
Operator
Thank you. Your next question today comes from the line of Luke Sergott from Barclays.
Please go ahead.
Luke Sergott
Great, thanks for the question here. I just want to clear up some things.
Sorry for jumping on a little bit late if you guys have already answered it. Can you just give us what the actual 3Q direct fee book-to-bill was, and can you elaborate a little bit why you guys decided to change the disclosure?
Barry Balfe
I didn't consciously decide, Luke. It's broadly similar with previous quarters, to be honest.
It's ticking along at about the same level as recently, no major departure there. There was no policy on it.
The guys continue to draw on me that the first time I give a number on one of these calls, everyone's going to expect me to give it forever, and maybe you've proved them right. Look, the reason I focused on a trailing 12-month 1.3 was because it stands in contrast to the preceding 12 months, which was closer to one flat on direct fee trailing 12-month book-to-bill.
I think this is particularly relevant to how we model the pace of revenue recovery in terms of direct fee, particularly in full-service outsourcing. I think it's the most relevant thing in terms of managing expectations and pacing that through.
Whether you want to think about as quality of earnings or whether you want to think about it as the composition of bookings, where we're headed, I thought that was the more important number. Candidly, in a world where everyone's only providing a 1.6 I'm happy excuse me, a 0.6, I'm happy to put 1.56 up beside anything anyone else has posted in the last year, but we think it's probably incumbent on us to give a little bit more insight and a little bit more transparency to investors.
That's what we're trying to do. Happy to clarify for you.
Operator
Thank you. Your next question today comes from the line of Jack Meehan from Opera Research.
Please go ahead.
Jack Meehan
Hi, guys. Hope you're doing well.
Wanted to ask about gross margin trends in the quarter. I think some of the sequential step-up might have been lower pass-throughs flowing through, but regardless, it seemed like a nice step-up.
Could you just talk about what's driving that? Is it possible to quantify any automation benefits you're seeing from AI at this point?
Then is it possible to talk about how pricing is flowing through on gross margins and whether you think that's stabilized? Thanks.
Nigel Clerkin
Hey, Jack, it's Nigel. Why don't I take that?
Look, no, the gross margin progression we saw in the quarter again goes back to what we had anticipated, i.e., improvements in business mixes we went through the year, as well as operating cost control, and the measures we took in the first half, starting to impact now in the second half. Those are the major factors really driving that.
AI impact, we obviously are, Barry touched on, seeing some great traction with our customers in terms of the AI capabilities that we're now able to bring to them, but we are also obviously looking at those tools in terms of internal efficiency gains as well. It is both.
That is an element of those investments that we're making and some of the traction we're seeing in the margin, too. Pricing, I think Barry touched on earlier, nothing really hugely different in terms of the broader pricing environment compared to previous periods.
I don't know if there's anything else you want to add to that, Barry.
Barry Balfe
Only to underline, well, a, what you said, but b, to underline that the difference between sold margin and P&L margin is execution and performance. I think everybody tends to come at the question, I'm not suggesting you do, Jack, but from the perspective of where did you price the work?
That's surely an important point, but the market tends to self-regulate on price, candidly. Where it's really, really important is how effectively are you executing on that work?
What level of visibility do you have into your cycle times, into your deliverables, into your productivity utilization on these contracts? This is across a much more diverse business than is perhaps apparent from the outside, it's a pretty complex picture.
Of course, it feeds into the margin performance, and that's why I'm pleased with the step-up, very honest, because we ask a lot of the teams to look hard at these projects, to understand how we can deliver them not just faster and at better value for customers, but with greater predictability so we can decide where to price them in the first place, and we can also better predict where margins are likely to go. If there's one, I guess, principle thing that I'm pleased with around the quarter, it's probably the third quarter in a row that looks a lot like we thought it might, and I think that's an important place for this business to get back to.
It's an important element of our business planning, and honestly, I think it's an important component of calls like today, speaking with yourselves and us giving an indication of where we think the world is likely to go. It's a blend of all those things.
Operator
Thank you. Your next question today comes from the line of Sean Dodge from BMO Capital Markets.
Please go ahead.
Sean Dodge
Thanks. Maybe just on the 2026 EPS guidance, you narrowed the range a bit, but also presumably have some moving parts in there with the debt refinance and higher interest expense, and then you did a lot of share repurchasing, too, in the quarter.
Maybe if you could just bridge for us what's changed beneath the surface in the narrowed EPS guidance, kind of what's new in there and what's not?
Nigel Clerkin
Sean, thanks, it's Nigel. I'll take that.
You touched on two factors for sure. Neither one of them massively material to the overall guidance range, but they would have been a factor, each of them in different directions, obviously.
We also, relative to when we put guidance out originally back in May, FX is a bit more of a headwind now than it was back then, there's an element of that built in there as well. Fundamentally, Sean, I would say the broader underlying operational assumptions that we had when we set the original guidance range are still the same, largely, to be frank.
Obviously, the difference is we're much further into the year now, and that allows us to narrow the range from where it was originally. Some minor moving pieces below the water line, if you will, but nothing really material from an operational perspective.
Obviously, we are very, very focused on where do we finish within that range. There's a bit of time left to go in the year, and Barry has touched on the focus that we certainly have across the business on operational execution, and that is our drive between now and the end of the year, as well as continuing with commercial progress, we hope.
Let's see where we land, but certainly, the range is narrower and tighter for a reason, and the underlying operational assumptions are still very much intact.
Operator
Thank you. Your next question today comes from the line of Jared Haase from William Blair & Company.
Please go ahead.
Jared Haase
Hey, guys. Thanks for taking the questions.
I appreciate all the color you've given so far on innovation and AI. Wanted to pull on that thread a little bit more.
I'm curious, when you speak with customers, is there a broader theme in terms of, I guess, the areas operationally in the study workflow that most resonate with customers in terms of the innovation opportunity, or is it sort of just a broader focus on efficiency? Then I'm also curious, is there anything incremental you would point to where you feel like ICON's uniquely positioned in the market to deploy some of this AI technology for customers relative to your peers?
Thanks.
Barry Balfe
Hey, Jared, very welcome, nice to meet you. Look, I think customers are interested in what they might have missed.
Everybody can look at document AI, everybody can look at medical writing, a lot of people been looking at coding, etc. Most of the more established companies have a clear sense of what's within their capacity to achieve.
Sometimes that sense is accurate, and sometimes it's not. Our job is to support them, but also to fill in gaps around the edge.
Anything that will drive speed, will drive cost, will drive predictability, will drive cycle time reduction is welcome. I think unsurprisingly, therefore, the higher areas in terms of spend or impact on study duration are key.
We talk a lot about feasibility and study design strategy in the first instance, because so much of your study performance is dictated by the quality of your plan before you actually turn a sod. You'd better have a good architect to make sure the plan is good.
Things like study startup, you miss a day at the end of a study, you miss a day. You miss a day at the start of a study, you miss recruitment time, and everything cascades down through the study, so that's really important.
Clinical and project management are still huge. I mentioned Meridian in passing.
I was actually with a customer yesterday doing a demo with one of our teams as part of a partnership pitch, I guess you'd call it, and the feedback I got from the customer was that you guys have fundamentally challenged the status quo, and that this is what we have been longing for. What they were talking about was the ability not just to surface data from 17 or 18 different sources, but to build it into a workflow that effectively makes the human more effective, right?
When somebody's planning a study visit, not to bore you now with operational inside baseball, the ability of the system to intervene and say, 'I see you're planning that, but the facts say you should be looking at this,' that's really valuable. 'I see you've scheduled a two-day visit.
If it's only two days, you'd better bring three people with you, because we think you've got six days' worth of work to do.' The ability to batch communications to a site and then ship it as one email with seven points, rather than seven emails, which drives sites absolutely crazy, drives down engagement, creates delay, and reduces recruitment.
These are the kinds of things that might sound like small, incremental gains, but they fundamentally represent what operational people care about. If we're anything at ICON, we're development operations people.
I go back to the point I made on a recent call, and I'm not sure, it might have been Max I was talking to at the time, we're not just interested in frontier capabilities. We're very fortunate to access some of the very best frontier models, but a lot of the problems we're solving aren't directly influenced by whether you're on the very latest and greatest version of the tech or two generations ago of a large language model.
They're much more about subject matter expertise, about process reengineering, and understanding how to solve problems in the pretty esoteric world of clinical development operations. Pretty broad answer to your question.
We care about all the areas. I'll fight with anybody for a day of time, a dollar of spend, or 1% of the predictability, but really focusing on design, focusing on getting the right sites started faster, and making better decisions, putting insights in the hands of our teams and our sponsors faster and more effectively, these are the areas where we tend to focus our fire.
I think part of what's resonating with customers around the AI story and the tech transformation story is that it's incredibly targeted. I don't think you can just put a sticker on the door and say, 'I'm an AI fan,' and I don't think fandom is going to get us anywhere.
This is about solving really difficult problems in the real world, and to do that, you've got to make some targeted bets and deliver on them, and that's what we continue to do.
Operator
Thank you. We will now take our final question for today, and the final question comes from the line of Ryan Halsted from RBC.
Please go ahead.
Ryan Halsted
Morning, good afternoon. Thanks for taking my question.
Just wanted to come back to the 2026 guidance revision upward. Appreciate that you are now reflecting the higher pass-through, but, I guess, first, can you clarify, as we think about exiting 2026, are we kind of at a leveling off of pass-throughs, at least on a percentage of revenue?
Then, secondly, holding the divestitures and the pass-throughs aside, can you expand on the greater visibility on kind of the growth trajectory of the underlying business exiting the year, and any color on visibility into the types of project work maybe that you're burning through that's kind of giving you confidence on the top line? Thanks.
Nigel Clerkin
Hey, Ryan, it's Nigel. Let me take that.
Yes, you're right. Absolutely, the change in the revenue guidance upwards by about $150 million at the midpoint from where it was before is really driven by the pass-through momentum that we've seen through the course of the year.
Pass-throughs now, we've touched on this I think at the previous call, are somewhere in the low 30s, approaching 1/3 of our revenues approximately. That is roughly where that's at.
Looking into next year, obviously we're not guiding just yet, and we touched on this earlier, that obviously will be one of the factors we get into in more detail when we give that guidance with our Q4 results, but probably somewhere in or around that range is a reasonable place to think about it as a starting point. In terms of the momentum that we're seeing in the business, Barry touched on it earlier, but just to repeat, again, consistency in terms of commercial performance should set us up for a reasonable place heading into next year.
We're not guiding today, but is it reasonable to think that with good execution, you can get to something in the region of mid-single-digit revenue growth next year? Seems like that that's a reasonable proposition at this point.
Again, Barry, I don't know if there's anything you wanted to add.
Barry Balfe
Maybe I'll just touch on that briefly and then pivot to closing thoughts. I completely agree.
Pass-through volatility is what it is. What you win, when you win it, when and how it starts, and how effectively you convert it can have a significant effect on pass-through volatility.
It's one of the reasons why we try and be a bit more transparent around earnings in dollar terms and in EPS terms rather than just in percentage terms. I think we've had a good question earlier on about how to guide for that, and that's certainly something that we'll spend some time thinking about once we're through the budget process and we're thinking about guidance.
The underlying question, I think, is the better one. There is some significant momentum on bookings.
The signs of inflection are there, and they're not just there in the P&L. They're where we expected and indicated they might come: a little bit of margin expansion on the gross line, a little bit of expansion on the EBITDA line, an inflection for slight, albeit small, but an increase in direct fee revenue sequentially, the narrowing of the guidance for Q4, and who knows if we'll finish on, above, or even below that range.
Even at the midpoint, you're looking at another dozen cents or so of earnings expansion quarter-over-quarter. If you take the for instance numbers we've been throwing around for 2027, it's certainly viable for us to grow from there.
I think we feel good about the state of the business. We feel good about the demand environment.
We obviously feel great about how well our teams have done and how hard they've worked to convert that opportunity. That's about the quality of the ideas, that's about the quality of the expertise, and it's about the faith people have in ICON's teams to deliver.
It really is taking the baby and minding it and handing your customer back, safely, a set of data that has integrity and has scientific validity. People don't do that lightly, and we don't take their confidence in us lightly either.
We feel pretty good about it. We're still a pretty understated bunch of folks over here.
It's one quarter and after the next, one foot in front of the other. Looking back on our remarks from our last three earnings calls, I think they've been remarkably consistent on what we thought the shape of that recovery would be, and I'm pleased to say that's broadly what we're communicating here today, and I hope that that will be the case going forward as we continue to execute on what I think is a positional advantage in the industry, where we have the scope, we have the scale, and we have the track record of delivering the types of trials that more and more people want to run, and we have the tools and the teams to run them more predictably, more cost-effectively, and faster.
We're going to leave it there for today, folks. Thank you very much for all the questions, and we look forward to talking with you soon.
Operator
Thank you. This concludes today's conference call.
Thank you for participating. You may now disconnect.