Interfor Corporation
Q3 FY2026 · Earnings Call TranscriptNovember 6, 2026
Operator
Good morning. My name is Sylvie, and I will be your conference operator today.
Welcome to Interfor Corporation's third quarter 2026 results conference call. As a reminder, all participants are in a listen-only mode, and the conference is being recorded.
Following prepared remarks, there will be an opportunity for analysts to ask questions. During this conference call, Interfor's representatives may make forward-looking statements within the meaning of applicable securities laws.
Additional information regarding the risks, uncertainties, and assumptions of such statements can be found in Interfor's most recent press release and MD&A. I would now like to turn the call over to Mr.
Ian Fillinger, Interfor's President and CEO. Mr.
Fillinger, please go ahead.
Ian Fillinger
Thank you, operator, and good morning, everyone. Joining me today is Mike MacKay, our Executive Vice President and Chief Financial Officer.
The third quarter reflected strong execution across our business, supported by modestly improved lumber markets, continued cost focus, higher mill productivity, and disciplined inventory management. While uncertainty remains elevated, we're making solid progress strengthening our business and our balance sheet.
Our two-year company-wide cost reduction program remains on track to achieve our $80 million annualized target. Thomaston delivered another strong quarter, reaching full pro forma production ahead of schedule.
The transformation at that mill is now complete, and Thomaston has become one of the top performing assets in our portfolio. Looking ahead, we expect a gradual market recovery rather than a significant near-term improvement.
Demand remains subdued, while ongoing curtailments and closures continue to rationalize supply. Against this backdrop, our priorities are clear: operate safely and efficiently, align production with demand, relentlessly reduce costs, and preserve the balance sheet strength and flexibility.
With that, I'll turn the call over to Mike.
Mike Mackay
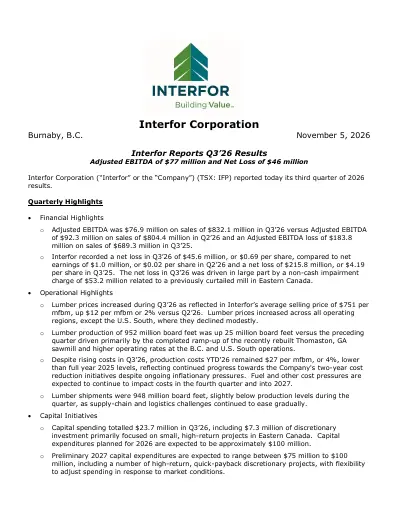
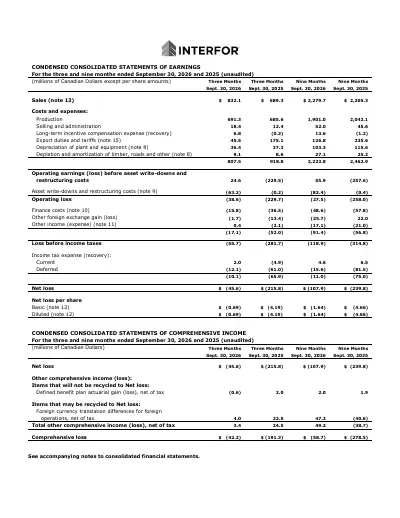
Thanks, Ian, and good morning, everyone. From an earnings standpoint, Interfor generated $77 million of adjusted EBITDA in the third quarter, continuing the strong results delivered in the second quarter.
From a sales perspective, realized selling prices were up 2%, with slight improvements across most regions. Production volumes increased by 25 million board feet, or 3%.
The increase was driven primarily by higher production in the US South, following the ramp up of Thomaston, along with more normalized operating schedules in the BC Interior. This was partially offset by lower production in Ontario.
Shipments were essentially in line with production. Production costs per unit remained below full year 2025 levels, with the year-to-date costs down Operator: Good morning.
My name is Sylvie, and I will be your conference operator today. Welcome to Interfor Corporation's third quarter 2026 results conference call.
As a reminder, all participants are in a listen-only mode, and the conference is being recorded. Following prepared remarks, there will be an opportunity for analysts to ask questions.
During this conference call, Interfor's representatives may make forward-looking statements within the meaning of applicable securities laws. Additional information regarding the risks, uncertainties, and assumptions of such statements can be found in Interfor's most recent press release and MD&A.
I would now like to turn the call over to Mr. Ian Fillinger, Interfor's President and CEO.
Mr. Fillinger, please go ahead.
Thank you, operator, and good morning, everyone. Joining me today is Mike MacKay, our Executive Vice President and Chief Financial Officer.
The third quarter reflected strong execution across our business, supported by modestly improved lumber markets, continued cost focus, higher mill productivity, and disciplined inventory management. While uncertainty remains elevated, we're making solid progress strengthening our business and our balance sheet.
Our two-year company-wide cost reduction program remains on track to achieve our $80 million annualized target. Thomaston delivered another strong quarter, reaching full pro forma production ahead of schedule.
The transformation at that mill is now complete, and Thomaston has become one of the top performing assets in our portfolio. Looking ahead, we expect a gradual market recovery rather than a significant near-term improvement.
Demand remains subdued, while ongoing curtailments and closures continue to rationalize supply. Against this backdrop, our priorities are clear: operate safely and efficiently, align production with demand, relentlessly reduce costs, and preserve the balance sheet strength and flexibility.
With that, I'll turn the call over to Mike. Thanks, Ian, and good morning, everyone.
From an earnings standpoint, Interfor generated $77 million of adjusted EBITDA in the third quarter, continuing the strong results delivered in the second quarter. From a sales perspective, realized selling prices were up 2%, with slight improvements across most regions.
Production volumes increased by 25 million board feet, or 3%. The increase was driven primarily by higher production in the US South, following the ramp-up of Thomaston, along with more normalized operating schedules in the BC Interior.
This was partially offset by lower production in Ontario. Shipments were essentially in line with production.
Production costs per unit remained below full year 2025 levels, with the year-to-date costs down 4%. These improvements were driven by higher operating rates, the ramp-up of Thomaston, ongoing productivity gains from our company-wide cost reduction program.
With that being said, fuel and other cost inflation has been notable this year and is expected to be an ongoing headwind in the fourth quarter and potentially into 2027. Turning to the cash flow and balance sheet, improved earnings, along with non-core asset sales, contributed to a further strengthening of our financial position.
Net debt declined, and our net debt to invested capital ratio improved to 35.5%. This represents a 120 basis point improvement from the second quarter, and a 330 basis point improvement from the first quarter.
We ended September with available liquidity of over $460 million. We continue to anticipate proceeds from divestitures over the next several months, including the ongoing sale of our BC Coast forest tenures, as well as the sale of real estate in the US South.
Looking ahead to the fourth quarter, benchmark lumber prices have moderated in recent weeks, with demand continuing to be constrained by housing affordability, consumer and builder confidence, and broader economic uncertainty, all in addition to normal seasonal softness. The same time, supply rationalization has continued through much of 2026, building on the actions taken across the industry in the prior years.
We believe this has contributed to a more balanced market environment. This ongoing supply discipline, combined with the recent 10% reduction in duty rates on Canadian imports to the US, does provide some optimism heading into 2027.
Lastly, turning to capital allocation, our priority remains on debt reduction, the pace of which will depend on lumber prices and market conditions. Preliminary 2020 preliminary 2027 capital expenditures are expected to range between $75 to $100 million.
Spending will be primarily maintenance-focused, but supplemented with a number of smaller-scale, high-return, quick-payback discretionary projects, which will be advanced and flexed based on market conditions, as appropriate. With that, I'll now turn the call back over to you, Ian.
Ian Fillinger
Thanks, Mike. Operator, we're ready to take questions from analysts at this point.
Operator
Thank you, sir. Ladies and gentlemen, if you do have any questions at this time, please press star followed by one on your touchtone phone.
You will then hear a prompt that your hand has been raised. Should you wish to decline from the polling process, please press star followed by two.
If you're using a speakerphone, you will need to lift the handset first before pressing any keys. Please go ahead and press star one now if you have any questions.
Thank you. First question will be from Sean Steuart at TD Cowen.
Please go ahead.
Sean Steuart
Thank you. Good morning, everyone.
Mike, I'll start with you. Can you give us a sense of I guess the cadence and the overall dollar amount you're anticipating from non-core asset sales, whether it's real estate or the coastal tenures?
Mike Mackay
Hey, good morning, Sean. Absolutely.
From a BC Coast tenure perspective, we're looking at the next several months, most likely into early 2027, in the range of $20 to $25 million, largely some of the timing delays around the BC election, just letting the government settle in as that resets. Real estate, similar type of timing.
We did close on one of the sales in Q3, and it's advancing well, looking at probably late Q4 or early Q1.
Sean Steuart
Dollar amount for the real estate piece of it?
Mike Mackay
That's in the same range as the BC Coast tenures, I'd say between $20 to $25 million.
Sean Steuart
Thanks for that. Ian, looks like from very low levels, you're opening up CapEx plans a little bit with respect to any discretionary projects that are being thought about.
Can you give us some context on what you're looking at, specific mills that are being targeted? I guess, more broadly speaking, does the federal budget yesterday and some of the support that's being talked about for forest products change your perspective on potential investment plans for your Canadian platform?
Ian Fillinger
Hey, Sean, thanks. As Mike said, our discretionary projects, there's several small, ultra-small projects with ultra-high paybacks that are scattered across the US and Canada.
We'll look at those and again can flex those to the bottom end of the CapEx range or the top end, depending upon how the business performs over the next several quarters. These are, again, several small CapEx projects with ultra-high paybacks and supported in many cases by incentives such as grants, straight cash influx from government programs, or tax incentives and benefits in both the US and Canada.
Very small projects, number of them, really good paybacks, and in many cases supported through different initiatives. We'll be able to flex those.
As far as the budget that was announced yesterday in Canada, our view is it's an important recognition, obviously, of the forest industry as a strategic industry for Canada. Appears to be putting some meaningful resources behind the sector's future, which is good.
The details we'll be looking for and have been told in the next several weeks will be more clear through the forestry sector transformation strategy that the federal government launched a number of months ago. As far as clarity on the key industry priorities, we expect to find out more in the next several weeks when that transformation report and strategy is released.
Sean Steuart
Great. Thanks for that detail, Ian.
That's all I have for now.
Ian Fillinger
Thanks, Sean.
Operator
Ladies and gentlemen, a reminder to please press star one should you have any questions. At this time, Mr.
Fillinger, we have no other questions registered. Please proceed.
Ian Fillinger
Thank you, everyone, for joining us this morning. While market conditions remain uncertain, we continue to plan conservatively, focusing in on the areas we can control and strengthening the balance sheet.
As always, Mike and I are available for follow-up, along with Brian Fast, our Director of Investor Relations. Thanks, everyone.
Have a great day and be safe.
Operator
Thank you, sir. Ladies and gentlemen, this does indeed conclude your conference call for today.
Once again, thank you for attending. At this time, we ask that you please disconnect your lines.
Have a good weekend.