Leidos Holdings, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 3, 2026
Operator
Greetings, welcome to Leidos' third-quarter 2026 earnings conference call. A brief question-and-answer session will follow the formal presentation.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
To ask a question during the session, you will need to press *11 on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press *11 again. Please be advised that today's conference is being recorded.
I would now like to hand the conference over to your first speaker, Stuart Davis from Investor Relations. Stuart, please go ahead.
Stuart Davis
Good morning, and welcome to our third-quarter 2026 earnings conference call. The presentation slides we'll be using are on our Investor Relations website.
Turning to slide 2, today's discussion contains forward-looking statements based on the environment as we currently see it, and thus includes risks and uncertainties. Today's press release contains more information on specific risk factors that could cause actual results to differ materially.
Finally, on slide 3, we'll discuss GAAP and non-GAAP financial measures. A reconciliation between the two is included in today's press release and presentation slides.
With that, I'll turn the call over to CEO Tom Bell, who will begin on slide 4.
Tom Bell
Thank you, Stuart, and good morning, everyone. I'm glad you could join us on this US election day to review another strong quarter at Leidos.
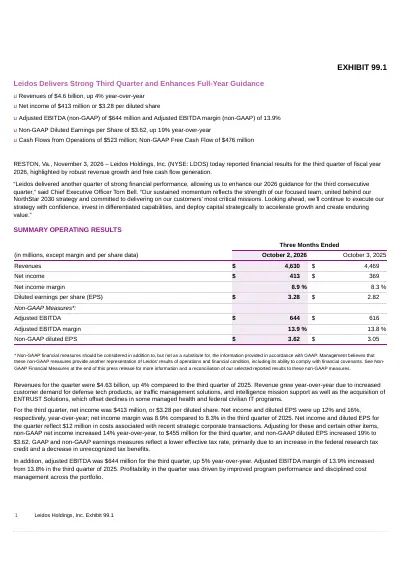
Revenue grew 4%. Adjusted EBITDA improved to 13.9%.
Non-GAAP diluted EPS increased 19% year-over-year, and free cash flow was $476 million in the quarter. I'll note here that this quarter's cash performance already brings our year-to-date cash flow to $1.5 billion, surpassing our original full-year target.
Net awards totaled $5.5 billion, a book-to-bill ratio of 1.2 times, and in Defense and Homeland, two of our growth drivers, book-to-bill was significantly above that. This performance allows us to, once again, enhance our 2026 guidance for the year.
Our sustained momentum in 2026 reflects the strength of our focused team, united behind our NorthStar 2030 strategy, and committed to delivering on our customers' most critical missions. Let me highlight a few examples of our NorthStar strategy in action this quarter.
First, we're continuing to sharpen our portfolio. We closed our joint venture combining our Security Enterprise Solutions business with Analogic.
The new JV is now a scaled market leader, well-positioned to grow in the $5 billion global security products market. Leidos maintains a significant equity share in this JV, our shareholders will share in the venture's long-term upside.
It also lets us focus our people and our investments where they create the most value under our NorthStar 2030 strategy. Second, we're continuing to move quickly in this market with outcome-based commercial offerings.
This is a clear mandate from this administration, and I believe it's a lasting change in how our customers will buy. It's also a strong fit for what Leidos does best.
In Health, where we appreciate the military and veteran healthcare mission end-to-end, we're applying our unparalleled customer knowledge to proactively build solutions for emerging customer needs, opening up new growth opportunities for Leidos. My Service Treatment Record, MySTR for short, is a great example.
We launched MySTR well before the President's September 8th executive order on veterans' benefits and employment because we saw the need coming. MySTR is now in beta test, and we're working toward contract award and full customer rollout.
As MySTR will run in the customer's cloud, we also look forward to adding new capabilities and functionality over time. Military OneSource is another Health example.
Our earlier investments in case management technology and provider networks allowed us to stand up a global support operation for Military OneSource in just 75 days. Military OneSource now serves nearly 5 million service members and their families.
That's what it looks like to build once and reuse at scale. In Intelligence, we're building a portfolio of commercial cyber and AI products.
Parcada, unveiled in July, is the furthest along. It's an automated cybersecurity platform that finds software vulnerabilities across enterprise networks and fixes them without manual intervention.
It completes the whole AI-powered patching process in minutes, far faster than existing options. Today, Parcada is focused on our intelligence community's needs.
We expect to make Parcada more widely and commercially available later this year. We're also investing in an exciting, robust new technology foundation for everything Leidos develops.
Our CTO, Ted Tanner, is leading this effort that builds on the same core Leidos capabilities demonstrated in the real world at Operation Jailbreak, and now also at Operation Revelry Forge. This new Leidos technology foundation will allow hardware, software, products, and services to be seamlessly woven together.
This will serve our customers and help Leidos win in ways we believe few customers and competitors can match. Third, our defense tech business is now consistently winning.
This business of ours is truly in a unique space, where we're increasingly seen as a mature disruptor, pairing our differentiated technology with Leidos' scale, mission expertise, software strength, and delivery track record. This is translating into winning now because our customers simply want it all: fast innovation in a partner they know can integrate, produce, and deliver at scale.
This quarter alone, in Defense, we won another major contract on the Space Development Agency's [Tranche 3?] program for advanced infrared space-sensing payloads; several OTAs for munitions, including a new Air Force Special Operations Command production award for Havoc Spear; and follow-on contracts for the Navy's nuclear-armed sea-launched cruise missile program; and a large contract to begin production of a new Army program that builds on our already unrivaled suite of passive sensing solutions.
This translated into a defense book-to-bill ratio of 1.9 this quarter and 2.0 year-to-date. This gives us the foundation for revenue growth and margin expansion for years to come.
Fourth, Energy is rapidly integrating and scaling into a market leader. Skywire, which we launched earlier, makes electric power distribution engineering more efficient, and it's foundational to our opportunity here.
Another example of commercial offerings. We've now created sister AI-powered tools for gas and power generation projects, and as a result, we're actively pursuing a large number of new projects in a larger addressable market, including opportunities in data centers around the nation.
We're also actively positioning to meet the growing need for stronger grid cybersecurity. Our path to double-digit revenue growth and mid-to-high teens margin in Energy gets clearer every day.
In summary, these four examples show the deliberate portfolio choices we're making as a part of NorthStar 2030. We're investing where our capabilities truly stand out and building repeatable commercial offerings.
That's NorthStar 2030 in action, and it's how we're positioning Leidos to perform through the rest of this decade. Now before I turn the call over to Chris, I'd like to share a few words on the VBA MDE recompete.
As this competition is now active, and the RFP is still in draft, I'll obviously be somewhat reserved. First, we expect the final RFP later this month.
As such, we believe it's highly likely our existing contracts will be extended through the first half of 2027, in line with the customer's planned new contract start date of July 1st, 2027. Second, we will, of course, be putting our best foot forward to win.
We've always been committed to value, veteran experience, and quality, and these are the things that the VBA focuses on. The draft RFP also clearly recognizes the value of demonstrated performance.
I continue to see significant upside in Leidos for our investors as we keep executing our NorthStar 2030 strategy. As such, you can expect us to continue to invest in our differentiated capabilities and deploy capital strategically to accelerate growth and create lasting value.
I look forward to your questions after Chris walks through the numbers. Chris?
Chris Cage
Thank you, Tom. Let's jump right into the results on slide 5.
Revenue for the quarter was $4.63 billion, up 4% in total, and 1% organically year-over-year. Bottom-line performance remained strong.
Adjusted EBITDA was $644 million for the third quarter for an adjusted EBITDA margin of 13.9%, up 10 basis points both sequentially and year-over-year. Non-GAAP diluted EPS grew 19% year-over-year to $3.62.
Cash performance was a noteworthy highlight. In the quarter, we generated $523 million of cash flows from operating activities and $476 million of free cash flow.
That comes to a free cash flow yield of 105% for the quarter and 121% over the trailing 12 months. Let me work through some of the details.
First, as expected, our results were materially shaped by the recent changes on our VBA disability exam contract. Excluding our Health segment, which was fundamentally driven by the VBA, revenues grew 9% and non-GAAP operating income grew 48% for the rest of Leidos.
We've been on a journey to diversify the earnings power of the company, it's great to see that show up in the results. In addition, our entire team acted with urgency around cost controls, which substantially drove margin and earnings, though it put downward pressure on our growth rate on cost-plus contracts.
Second, our team has worked hard on tax optimization strategies to reduce cash taxes and leave more cash available to invest in the business. This quarter's non-GAAP effective tax rate of 15.1% reflects some non-recurring pickups on state taxes, as well as a new approach to calculating our research tax credit that was reviewed and accepted by the IRS.
The research tax credit component is a structural change to our tax rate, though the impact will be more modest in the out years. Turning to the segment view on slide 6.
Homeland led all segments with 32% total and 15% organic growth. Growth was broad-based, underpinned by robust demand in domestic and international air traffic management.
Defense growth year-over-year of 3% reflects the impact of large product component purchases into the third quarter of 2025. The segment continues to ramp production of integrated air defense and counter-UAS programs, which led to 4% sequential growth.
Intel and Digital grew 1% year-over-year, as strong intelligence community demand was offset by reductions in certain federal civilian IT programs. Health segment contraction was driven by the VBA business for the reasons we previously outlined.
Margins were up significantly at Intel and Digital and Homeland, flat at Defense, and down less than expected at Health. This across-the-board performance reflected the cost actions I mentioned earlier, as well as strong award fee scores, more higher-margin commercial work, and positive EACs.
As shown on slide 7, we repurchased $500 million of shares on the open market in the quarter, consistent with our view that our stock is trading below its intrinsic value. The board also authorized a 2-cent increase to the quarterly dividend.
This allocation of capital is wholly consistent with our philosophy. Most important, we will fund the organic growth needs of the business.
Capital expenditures stepped up in Q3 from our first-half run rate, and the fourth quarter should step up even more, primarily from investments in defense tech production capacity. The robust cash generation of the business offers ample capacity beyond capex.
Our strong and flexible balance sheet is an important tool for driving long-term shareholder value through a balanced approach to capital deployment. At quarter-end, we had $6 billion of debt, $630 million in cash and cash equivalents, and a gross leverage ratio of 2.5 times.
Our balance sheet shows the assets and liabilities of SES as held for sale. Immediately after the quarter, we closed on the divestiture of SES and retained a 41.5% equity interest in the new joint venture.
As Tom mentioned, our stake provides a significant value creation opportunity for Leidos and its shareholders as the JV increases market share, drives operating leverage, and ultimately advances to a liquidity event. Finally, on to the forward outlook on slide 8.
Our new ranges reflect the impact of the SES divestiture, our Q3 results, and our updated outlook. Let me walk you through the puts and takes.
Prior to the close, we forecast SES revenue in the fourth quarter to be approximately $200 million, which is directly reflected in the new revenue guidance range. We expected SES to deliver about 12 cents of non-GAAP diluted EPS in Q4, the new, narrowed range is up around 37 cents on an adjusted basis at the midpoint.
With a Q4 cash projection of roughly $20 million for SES and another $30 million in transaction costs, we're effectively raising our operating cash flow guidance by $100 million. Finally, we're maintaining our adjusted EBITDA guidance in the mid-13s.
The guidance assumes that the government is operating under a continuing resolution through the end of the year. For 2026, diluted share count is at 126 million, and the non-GAAP effective tax rate is around 20%.
The guidance implies that Q4 revenues will be near Q3 levels. We will continue to see pressure on cost-plus revenue from indirect efficiencies, and we'll have a full quarter of impact from the VBA contract changes we previously disclosed.
Also, while third-quarter bookings were solid, there were some delays and some decisions that didn't go our way, which will temper our growth momentum in Q4 and into 2027. On the positive side, customer procurement activity appears to be accelerating, and our near-term pipeline remains large.
We expect Q4 Health segment margins to be in the high teens, driven mostly by the VBA contract changes we previously discussed, and we aren't assuming the same level of EACs in the fourth quarter as we saw in the third quarter. Although we haven't completed planning for 2027 and key dependencies remain, we continue to see Q4 as a reasonable jumping-off point for our 2027 performance.
With that, operator, we're ready to take questions.
Operator
Thank you. As a reminder, to ask a question, please press *11 on your telephone and wait for your name to be announced.
To withdraw your question, please press *11 again. Please limit yourselves to one question before getting back into the queue.
At this time, we will pause momentarily to assemble our roster. Our first question is going to come from the line of John Godyn with Citi.
Your line is open, please go ahead.
John Godyn
Hey, guys, thanks for taking my question. I wanted to dialogue a bit more on the bookings environment.
You reported a strong 1.2x book-to-bill in the quarter, and just at the end of the prepared remarks, you mentioned there were some signs of customer procurement activity accelerating. I was just hoping you could talk a bit more about the leading-edge demand signals that are driving bookings, and maybe elaborate a bit on defense tech, intelligence, cyber, some of the things that were highlighted in the press release as kind of being hot right now.
Thanks.
Tom Bell
Sure, John, thanks for the question. As Chris mentioned in his comments, the environment is improving, and we do see customers beginning to move with more alacrity around their procurement decisions.
At the same time, frankly, there are procurement decisions that continue to slide around, but we don't see that as abnormal to a normal-functioning government procurement cycle. We see promise that as we head into the next fiscal year of this government, in it already, we're going to continue to see that momentum being maintained.
On our book-to-bill ratio, I'm glad you picked up on the 1.2 being pretty respectable, and it is. What makes it even more interesting to me is the fact that it's been crescendoing through the year.
You'll recall that in the first quarter, we had a book-to-bill of 0.8; in the second quarter, we had a book-to-bill of 1.1; and this last quarter, we had a book-to-bill of 1.2. I feel very good about the momentum that is being built by the team in growing the business.
Except for that, I would also want to remind everybody, on my very first earnings call as CEO of this corporation, I talked about the more important measure is total backlog. Book-to-bill can be episodic; quarters can come and go.
Total backlog is also a great news story, where it's up to $49.6 billion, 4% year-on-year, and we have excellent growth in funded backlog, $11.1 billion, up 22% year-on-year and 8% sequentially. We're really building the backlog, which is more important to the sustained growth of the company than the episodic book-to-bill.
One area that I'd also like to focus is on OTAs. As probably most analysts know, OTAs are increasingly of interest to our customers as they want to field critical capabilities quickly.
In OTAs, it's a little-known fact that Leidos is actually a market leader here. We have currently 212 OTA contracts, including 33 that were awarded just this year for a $6.6 billion ceiling.
This new mechanism that our customers are leaning on to speed up the acquisition process is something we're very proud to be leaning into also with them. That's what gives us a very positive forward outlook.
We have $28 billion right now awaiting decision, including $21 billion that is new and takeaway business, and we're very happy with where that's all going. As you mention, our book-to-bill in Defense was 2.0 year-to-date, our organic growth in Homeland was 15%, and so the growth engines that we have are growing very responsibly.
As Chris mentioned in his prepared remarks, if you take out managed Health, it's up almost 50% year-on-year. We're very happy about that.
Chris Cage
John, I'd only add, not to throw more stats at you, but if you look at our next 12-month pipeline, from where it was a year ago, that's up 15% too. That's what we talk about when we look ahead and the activity seems to be accelerating.
No shortage of deals out there the teams are focused on. About 40% of that next 12-month pipeline is in Defense.
You also asked about cyber, and we announced the US Cyber Command award, $160 million to Kudu, let us help penetrate, followed that up by another $99 million OTA award in the cyberspace. A lot of good activity going on across the business.
John Godyn
Thanks, guys, very thorough.
Operator
Thank you, and one moment for our next question. Our next question comes from the line of Tobey Sommer with Truist.
Your line is open, please go ahead.
Tobey Sommer
Thank you. I wanted to ask on the defense tech side and related business where you're investing in production capacity.
What does the arc of that look like based on your current wins and maybe near-term pipeline for additional wins on when sort of the investments peak and the profitability with ramping production kind of shines through?
Tom Bell
Sure, thanks, Tobey. Defense tech is a shining star for us, and as I said in my prepared remarks, it is a business that is now winning consistently because the customer is increasingly seeing us as the mature disruptor.
We're not just PowerPoint charts, and we're not just slick T-shirts at tradeshows. We're a company that they understand.
They're a company that's been there in the past, and they know will be there in the future. At the same time, we're able to move agilely and adroitly to make sure that we're responding to the customer's real critical needs right now.
We're investing ahead of that need. As I said at the beginning of this year, we would be increasing our capex to make sure we're positioning the company for that growth in this critical part of our portfolio.
At the same time, I think you're seeing in the numbers that we're being very judicious about the money we're spending. We're not just spending it because we budgeted it; we're spending it as the opportunities actually trigger and they actually unfold.
You'll continue to see us be very disciplined with how we spend our money to fund growth, and make sure that when it's in an organic growth mode, we're funding it on the things that the customer is really going to buy. I mentioned in my comments, the foundation to double-digit growth is intact, and we're growing increasingly confident for that.
Part of the reason for that is we've got more than a dozen programs that are right now moving from development into rate production. For instance, IFPC, something we've talked about for a couple years now, it's on pace to reach full rate potential in 2027.
That's exciting for us since moving only to LRIP in 2025. This program has tripled in revenue and meaningfully expanded its margins, a huge, great base for our team in Huntsville.
There's more than $10 billion in defense tech awards over the last 18 months that we've secured and $6 billion year-to-date. We're very excited about the backlog again we're building in this business.
As Chris was just saying about the whole, we've got a pipeline of over $14 billion of visible opportunities within the next 12 months. We expect Defense's book-to-bill ratio to remain robust and they continue to build backlog.
Chris Cage
Tobey, I'd only add, obviously you're looking for those investments to show up as increased margin in that segment, and we're very bullish that that is the path we're on. You'll see that progress in '27 upward; you'll see that progress over the next several years upward.
There's gas in the tank on the return on those investments showing up over time. The team's focused on that, and the product lines that Tom talked about are all accretive to margins as they ramp up their production volumes here over the next handful of years.
Elevated level of investment won't be for everything you look at that over the next couple years, but the profitability on the other side of that will be showing up here throughout the rest of this decade certainly.
Tom Bell
Thanks for the question, Tobey.
Operator
Thank you, and one moment as we move to our next question, which will come from the line of Ken Herbert with RBC Capital Markets. Your line is open, please go ahead.
Ken Herbert
Hi, good morning. I wanted to first ask on the Health segment in particular.
Tom, you called out that you feel like, as you review the draft RFP, that obviously it plays well to Leidos. I wanted to see if you can drill down on that a bit, and specifically maybe highlight where you see the real opportunity for Leidos relative to that draft RFP you're working through.
Then just as a follow-up, Chris, I think you guided to high teens margins in the segment for the fourth quarter. Should we think about that as a good starting point or run rate into the first half of '27 while the existing contract works through?
Thank you.
Tom Bell
Thank you, Ken. Sure.
As I mentioned in my prepared remarks, I'm going to be somewhat reserved, despite your question, I'm going to remain a little bit obtuse here. We do believe that we're well-positioned to compete for this work.
Leidos comes to this from a position of obvious strength. We're the top provider in this business and we've been for over two decades.
We have an excellent track record of veteran satisfaction and timeliness and accuracy, and we know that those are the things that the veteran and the Veterans Administration and every member of the House and Senate care deeply about. We've invested in this capacity to make sure that we can handle the volume as it's gone up through the years, and we've invested in innovation, and so we're known as an innovator in this space, developing, for instance, the mobile clinics that met the veterans where they were.
Most importantly, what gives us some confidence going into this competition is the fact that we understand the mission, and we understand this is a no-fail mission, and we are locked at the hip with the Veterans Administration in understanding the criticality of making sure, just as this administration has said a number of times, that veterans get the benefits they deserve in a timely way. While we're still dealing with the draft RFP, we know that it looks toward the things that are the strength for us, and we also are buoyed by the fact, if you've read the draft, that it leans into the fact that they want to award two to four companies per service group, and two of those have to be experienced and be able to stand up capacity in 30 days.
That leans well on our incumbency. It also talks very much about rewarding those who deliver the goods for the Veterans Administration in timeliness, quality, and cost by higher work volumes.
Net-net, the draft RFP reads pretty well for us, and we're very bullish about it. At the same time, we're taking absolutely nothing for granted because we also understand that the Veterans Administration is trying to be an excellent steward of the taxpayer dollar, and we need to be their partner in that as we've always been in the past.
Chris, do you want to deal with a few of the specifics also?
Chris Cage
Ken, just to talk more about the margin profile, obviously we're pleased with how the team came through Q3, a little bit better than we expected. Q4 exit rate, I do think is a good place to model out the first half of next year in the high teens.
Then to Tom's earlier comments, expecting a continuation of our current contract through the middle of the year, on the other side of that, all the puts and takes about how we compete, as we get more clarity on where that's landing, we'll be able to give you more indications of what the back half of the year looks like. We'll certainly be able to tackle that in February, but I think you're seeing the team continue to find ways to overdeliver.
That's just what they do, and this business will continue to be an excellent piece of the portfolio for us for years to come.
Ken Herbert
Thank you.
Operator
Thank you, and our next question is going to come from the line of Peter Arment with Baird. Your line is open, please go ahead.
Peter Arment
Hey, thanks, good morning, Tom and Chris.
Tom Bell
Hey, Peter.
Peter Arment
Hey, Intelligence and Digital had really good margin performance this quarter. You called out kind of good execution and cost management.
You also mentioned there was a little bit of EAC adjustments. Maybe you could just talk to the margin performance, how you're thinking about kind of the durable nature here of the margin performance here that we saw this quarter, and expectations as we think about going forward.
Thanks.
Tom Bell
Peter, I'm so glad you asked this question because I need to throw a little sunshine on this team because not only did they have good margins, they had record margins based on excellent execution across the segment. We're very proud of our team there and very proud of the fact that it's coming in even stronger than we had anticipated in our financial planning.
In the Intelligence side, our business grew double digits in the quarter, and in our Digital side, while it contracted modestly, the profitability was very, very robust, and the team's doing a great job there. We also have this segment because it is so critical to the value of our customers going forward.
I think it's sometimes overlooked that the customer spends over $57 billion in this world on an annual basis, just the federal IT spend is up 10% in fiscal year '27 President's budget requests. The money continues to flow into the digital ecosystem of this government, and as we're a very large provider of the digital infrastructure for most federal agencies, we see that opportunity to serve them and to modernize their infrastructure as core to our responsibilities, and then these days, make that infrastructure cyberscure, critical to our country, critical to national security, and critical to the functioning of this government.
We're very excited about the business. We're very pleased with the team's performance to date, record execution and record margins, and maybe Chris will give a little bit more detail.
Chris Cage
Appreciate the question, Peter, and I would say this is the playbook. You look at Digital especially, and they run some of the largest programs in the company, and as typically is the case, as you mature those programs, you deploy technology, you get into the customer's environments, you find opportunities to drive efficiencies, and that's what they're doing, whether that's a concerted effort with what we've been after with our repeatable offerings, now called Mission Drivers, and some of the commercial products that the Intel team is leaning into.
All of those things will give us confidence about the ability to drive the margin portfolio in this part of the business higher over time. We did talk about EACs were very favorable in the quarter, and so as we look ahead to Q4, we're not always predicting that level of sustained success, but this clearly shows you what the art of the possible is, and I like the trajectory of this segment's margin performance.
Peter Arment
Appreciate the color, gentlemen. Thank you.
Tom Bell
Thank you.
Chris Cage
Thanks, Peter.
Operator
Thank you, and our next question is from the line of Jonathan Siegmann with Stifel. Your line is open, please go ahead.
Jonathan Siegmann
Hey, good morning, thank you for taking my question.
Tom Bell
Sure,
Chris Cage
Jonathan.
Jonathan Siegmann
Hey, the defense order is fantastic, and you had talked about high-single-digit defense growth this year, but you have that one offset you're dealing with. Can you kind of walk through the timing of that, and is that all done now, just moving forward, just how good could '27 be for that segment?
Thank you.
Chris Cage
Let me jump in here, Jonathan. You're right.
It's definitely the momentum's building. You've seen the bookings quarter-over-quarter continue to accelerate.
This quarter, from a growth rate perspective, 3.5%, some of that is just a very robust Q3 of last year coming off of an elevated level of long-lead procurements. We're now seeing clear runways for some of the programs that we featured to ramp up, specifically our IFPC program, as Tom alluded to, that has tripled in volume and it's moving up further in '27.
Our ABAD program with some of our ALPS and Marauder technologies, etc., will be accelerating. The customer is looking to add more ceiling perhaps to that vehicle.
Common Hypersonic Glide Body, we're on a clear run rate to accelerated production there of certain units. That's what gives us confidence that you'll see a higher growth rate in the Q4, the team's focused on how do we get this business to a double-digit growth rate over time.
I think the building blocks are there for us to be able to lay that out for you in 2027, and we'll put more meat on that bone when we get to February.
Tom Bell
If you don't mind, Jonathan, I'm going to jump on and also broaden your question a little bit to the rest of the defense portfolio that we're so proud of. There's a lot of discussion in Washington, DC, and around the nation about our weapons stockpile and the magazine depth of the country and the urgency to create new sources of supply for munitions.
We're leaning into that, and we have a pathway for our munitions side of our defense tech business to be a $1 billion business by 2030 annually. We're very excited about where that business is going, and the building blocks are there.
IFPC, as Chris already mentioned, is a big base for Huntsville, but small cruise missile, as I said in my prepared remarks, Havoc Spear, is moving very quickly in LRIP program. Low-cost containerized munitions, we announced before the fact that we have signed a framework agreement for that business.
We've not yet gotten a contract for that, so that's backlog to come. As soon as we translate that framework agreement into a contract, there's going to be a big booking of an order book for the 3,000-plus missiles we expect to make there.
Sea-launched nuclear-armed cruise missile, I mentioned in my prepared remarks, the abbreviation for it is SLCM-N, if you're tracking that. We've got an OTA on that, and we're very excited about where that program is going, and as Chris just mentioned, hypersonics.
I mentioned space and our franchise of space sensor payloads, which is so critical to this nation's defense. Not mentioned yet, but I can't help but say it, is our counter-UAS capabilities.
Counter-UAS capability not only animates the Department of War, but it also very much animates the Department of Homeland Security, and we've had very robust conversations with both customer sets there about the suite of capabilities Leidos brings to bear, from sensors to effectors to command and control to the complete shield of our counter-UAS capabilities. Frankly, that's turning heads in our customers' community as they understand the threat is evolving quickly, and they're looking for solutions.
Just like I was saying before, they're seeing that we have disruptive, relevant, ready-now solutions for these emerging threats, and it's a very exciting place for us to be. Net-net, our defense tech business is a very, very core part of the portfolio that we're very proud of, and it's growing just as we expected.
Jonathan Siegmann
Thanks for the color.
Tom Bell
Thanks, Jonathan.
Operator
Thank you, and our next question comes from the line of Gautam Khanna with TD Cowen. Your line is open, please go ahead.
Gautam Khanna
I had two questions. On the VBA rebid, given the commentary about the first half next year, should we think that earnings for the company, just given the timing of the defense ramp and what have you, will not grow in '27 and '28?
Then as a follow-up, if I could ask about the maritime strategy as part of NorthStar, given the MUSV outcome, what's sort of the plan from here? Thank you.
Tom Bell
Let me take the maritime first, and then we'll work back on the whole. Yes, obviously we were disappointed with the MUSV non-selection in this round, but I would underscore that phrase that I just used.
We were not selected in the first round of 30 boats, but we're in the marketplace and we're actively working several very intense customer engagements where the unique capabilities that we were offering as a part of the MUSV competition, and the timeliness that we were committed to deliver those products with the effects that those products were envisioned to be able to have, is gaining traction both within the Navy and outside the Navy in the Department of War. We were disappointed.
We would have loved to have booked an order for 10 of those vessels. That didn't come our way, but we're in the marketplace and we certainly don't see it as a dead end.
Our maritime ambitions remain robust, and don't forget the fact that it doesn't get talked about a lot, but we have a very robust business also in undersea warfare. While unmanned surface vessels are what people are talking mostly about, the competitive edge for the American Navy continues to be our submarine force, and our effect in that part of the value proposition of our customer is very key.
On the whole, I'll let Chris continue to talk about how you should think of our fourth quarter as our jumping-off point for '27.
Chris Cage
Exactly, Gautam. I think that the implied fourth quarter as the jumping-off point, if you run that out, think through the dynamics of the business, where there's growth and where there might be further step-down in the VBA, it's clear that 2027 is not a bottom-line growth year for the company; it's accelerating top-line growth in other parts of the portfolio.
I'm very bullish on the rest of the portfolio accelerating as we look ahead to '28 and beyond, that there's a lot of momentum elsewhere as we look at a high-margin Energy business, defense tech products ramping up, that it's way too early to suggest that there's not a bottom-line growth story beyond this near-term transition in the VBA. That's the journey we're on.
I think we just demonstrated the power of the portfolio in Q3 absent Health, and we'll continue to focus on accelerating the rest of those business growth drivers in higher-margin parts of the portfolio.
Tom Bell
Thanks, Gautam.
Gautam Khanna
Thank you.
Operator
Thank you, our next question will come from the line of Noah Poponak with Goldman Sachs. Your line is open, please go ahead.
Noah Poponak
Hey, good morning, guys.
Tom Bell
Hey, Noah.
Noah Poponak
Not sure what you're going to be able to say to this, but is there a way to frame the boundaries of the VBA outcome? What happens to Health revenue in the best-case outcome for you?
What happens to Health revenue in the worst-case outcome for you? Then on the margins, this high teens jumping off, but I guess that references the current contract, can they go up again once you're on the new contract?
Do they definitely go down? How much do they go down?
I guess you've referenced the stock price relative to intrinsic value, and I think that case could be made, but stocks just hate uncertainty, and the stock's been having to live with this undefined thing that takes a long time to play out for a while. I don't know if it's possible to bound the ranges of what could happen.
Tom Bell
I'll start, and then I'll let Chris jump in if he's got any color he'd like to add. No, I'm not able to bound it, and I'll remind you that that's because it's still a draft RFP.
We haven't seen the final RFP, and certainly the bounding of what it will be will depend on how we prevail through the first six months of next year in this competition. We expect the customer is going to be making a decision in the, let's call it, April-May timeframe, and at that point, we'll know what we've won and where we're positioned and how much volume is coming our way and how we can continue to be of service to this country.
Frankly, the boundary conditions aren't going to be able to be articulated until the second quarter of this year, probably halfway through 2027, I'm talking about. Here's the big but, like you, we can do a sum-of-the-parts analysis of Leidos, and even if we assume away the whole of the VBA business, which is a pretty amazing conclusion to draw, but if we zero it out, still the valuation of this company and our current valuation is way below the sum of the parts of the rest of Leidos.
I do believe the market has somewhat overburdened the stock price with the fear of the unknown of the VBA, but I think if somebody did some robust analysis, they would see what I said about the sum of the parts, and even if you zero it out, and then you would have to run your own analysis on what's the likelihood that the market leader leaning into this competition gets zeroed out and has no position on this business going forward. I think that's pretty low.
Noah Poponak
What's your 2026, what's your 2026 earnings and EBITDA without VBA?
Chris Cage
No, Noah, we can't give you that level of detail. That's below the disclosure level that we talk about.
Looking ahead, looking at what we think are exciting parts of the portfolio, you could make a case that there's undervalued assets in the portfolio. I would only add to, and Tom was going there, that the way the draft is set up, there is an upside case that Leidos comes out of this with more work share than we have today.
Right. Work share drives profitability; volume matters.
There's absolutely a bullish case that says the best-performing provider could have increased work share in this future contractual decision. We want to be able to make that a reality for you and our shareholders, and we're going to work hard to do that, but it's too early for us to commit to that as a reasonable expectation at this juncture.
Thanks for your question, Noah.
Noah Poponak
Thanks.
Operator
Thank you, our next question will come from the line of Gavin Parsons with UBS. Your line is open, please go ahead.
Gavin Parsons
Thanks, morning.
Tom Bell
Hey, Gavin.
Gavin Parsons
I know you can't size VBA, but you talked about top-line growth being 9% in the quarter excluding. Any way you can frame for us kind of what top line could grow next year ex-VBA?
Chris Cage
Again, you're trying to get ahead of us to '27. I think I just alluded to Defense has a real possibility to be a double-digit grower.
We hope to put a finer point on that as we advance the ball towards February. Energy, our expectations, that's going to be a double-digit grower.
Our cyber portfolio, which is a very robust part of Leidos, has the ability to be a double-digit grower. Those are three important pieces of what we have that we could see that outcome next year.
The other parts of the business, there's some things ahead of us that still matter on the winning front, especially in Digital. We got several irons in the fire there that we need to see play out before we can put a finer point on their near-term growth trajectory.
I think absent the Health business, you'd expect to see a very above-market growth rate across our portfolio, and we'll be able to put more color on that here in time.
Gavin Parsons
Appreciate it. Then in the prepared remarks, you mentioned Parcada as a commercial offering.
Can you just talk about the the broader commercial potential on cyber?
Tom Bell
As we all know, the AI-powered vulnerability detection is a big problem for every company and everybody who has a computer system right now. Parcada is the automated way to do that without human interface.
As I said, we've created this product developed originally through a DARPA challenge and developed by our Kudu subset of Leidos. It's a proprietary AI platform that goes and autonomously detects and patches software in minutes that is without human intervention.
Right now, it's focused on working with our intelligence customers and on their challenges, but very shortly, later this month, later this year, we expect to make that commercially available to other members of the government and potentially outside companies. It is a real-time, very effective patch that makes the speed of detecting, patching, and deploying in minutes, and obviously that's something that the world needs more of.
We're very excited about the opportunity, but at this point, given the speed with which this whole market is moving, we can't exactly bound what that means for us.
Chris Cage
There's more right behind it, whether it's another product called Orbit and there's a third product coming out of Intel. We've talked previously about MySTR, which is essentially a software product, commercially priced offering.
In various pockets of the portfolio, under Ted's leadership and elsewhere, we're going to see more of that in time, not the preponderance of what we do, but a nice complement to how we deliver value for our customers.
Gavin Parsons
Thanks, Gavin.
Tom Bell
Great, thanks.
Operator
Thank you, and our next question will become from the line of Sheila Kahyaoglu with Jefferies. Your line is open, please go ahead.
Sheila Kahyaoglu
Good morning, guys, and thank you so much. I appreciate you don't want to get ahead on '27, maybe without excluding Health, just thinking about your defense business, great book-to-bill in the quarter, some momentum building.
Consensus has about 3% organic defense growth and 10% EBIT growth next year. I guess the drivers of that are really within Homeland and Defense segment earnings.
Can you talk about some of the pieces really stepping up next year as we think about those ramps and some production programs, and I guess within Homeland, what's driving that growth?
Chris Cage
I'll start. Certainly on the Homeland side, the team's been on a tear this year, the last few quarters in particular.
The FAA has been an important customer, and some commercial and some international air traffic customers in the UK, Kazakhstan, etc. There's momentum in the FAA part of that portfolio, and there's long-term potential.
We could see some momentum next year certainly beyond that in what we want to do on the airport modernization side. Getting out of the OEM piece of the security detection business is one thing, but the logistics capability that we offer there to our customers has room to grow.
Of course, the crown jewel in Homeland is what's happening with Energy, and we've seen consistent, strong growth out of our existing business this year. The integration of the Entrust acquisition is now essentially complete, will be finally complete by the end of the year, so that's going to be a growth catalyst for Leidos with a strong market demand signal.
We've talked a lot about some of the defense product portfolio pieces that are accelerating, and from contract actions that have already been decided. Clear line of sight to space accelerating with more wide field of view payloads, clear line of sight to IFPC volumes accelerating, MXR, ALPS product line in the passive detection arena, and then Tom highlighted a lot of the momentum in munitions, which is more '28 than '27, but you'll see some contributions in '27 certainly there too.
Those are the things, Sheila, that I'd focus on at this point in time that says we have confidence in those growth rates accelerating. Tom, you'd add to that?
Tom Bell
Sheila, I appreciate, good talking to you again. As Chris just mentioned, the energy play as a big part of our Homeland Security is critical.
As the surge in capital investments by utilities around the nation is robust as they deal with aging infrastructure and they deal with massive AI-driven increases in demand. Our Entrust acquisition is largely now behind us.
Integration is done. We're now focused on growth, and we're very, very targeted at a pipeline that has grown some 230% since the acquisition.
We now have over $10 billion of orders targeted there. Our Energy business is robust.
Then on the other side of the equation, FAA modernization, we just celebrated 10 straight years of 100% uptime on our ERAM program for the FAA, and the FAA Terminal Flight Data Manager program is really moving out well with this customer, and we're on track to complete deployment of at all 89 airports by the end of 2028. That part of the program is continuing to grow.
We're one of the four competitors in phase two of the FAA's CAP program, and we anticipate they'll be making a downselect in mid-2027 as they work toward doing a brand-new air traffic control system for the United States by 2028. We're very excited about that.
We're very also excited about leaning in with the Department of Homeland Security of rethinking the airport experience. They recently canceled the Gold Plus privatization program.
However, we had always been on the IDIQ called Screening Partnership Program, the SPP program, and there are some rather large airports that are now opting into the SPP program. We believe we have a differentiated capability to deploy at airports to make the passenger experience much smoother, much more efficient, and much more effective for the traveling public, and we look forward to leaning into that.
Both the Homeland business and the Defense business are firing on all cylinders.
Sheila Kahyaoglu
Great. Thank you.
Thanks, Sheila.
Tom Bell
Thank you,
Operator
and our last question is going to come from the line of Louie DiPalma with William Blair. Your line is open, please go ahead.
Louie DiPalma
Tom, Chris, Stuart, Stephen, and Megan, good morning.
Tom Bell
Hey.
Chris Cage
Hey, Louie. Morning, Louie.
Louie DiPalma
Tom and Chris, when you discuss the potential bullish scenario for the VA disability contract, is that scenario primarily the reduction in vendors from from 4 to 2 for the regions, and are there other bullish scenarios?
Tom Bell
The the current draft envisions four vendors between two and four vendors in each service group, and it envisions six service groups. The four domestic regions, they call them now, would be service groups, and then international and pre-discharge would be two other service groups.
Six service groups in total, IDIQ for each, two to four vendors for each of the six. How it's going to work is two vendors per service group need to be ready to stand up capability and serve veterans within 30 days, there's an incumbent preference there, and new entrants, possibly to round out the four, have to be ready to stand up their capability within a year.
That gives you a a year where potentially in a service group you're one of two vendors. Then
Chris Cage
the only thing I'd add to that, Louie, the number of vendors is one element of the upside bullish case, and the other is even in a scenario where there's four vendors in a region, they have not committed to an equal work share. At least in the draft, it contemplates the best-performing vendors get a disproportionate amount of work share.
You could play those scenarios out to say whether it's fewer vendors or you're one of the top-performing vendors on some criteria, you could come out with a work share that's more significant than what we have today.
Louie DiPalma
Excellent. That potential increase in market share would potentially offset the decrease in pricing, and so there are scenarios in which for 2027 or 2028 that your EBITDA would actually increase?
Tom Bell
We don't want to get ahead of that, Louie. Right now, we're still dealing with a draft RFP.
We'll see what the final RFP says, and then we have to create our bid strategy and figure out what's in the best interests of Leidos and how we're going to maximize our service to this nation and our return to our shareholders.
Chris Cage
Thank you, Louie.
Louie DiPalma
Excellent, thanks, everyone.
Tom Bell
Thanks.
Operator
Thank you, and I would now like to hand the conference back over to Stuart Davis for closing remarks.
Stuart Davis
Thank you, Michelle, for your assistance on this morning's call, and thank you, everybody, for spending time with Leidos. Appreciate your interest, and we look forward to speaking soon.
Have a great day.
Operator
This concludes today's conference call. Thank you for participating.
You may now disconnect. Everyone, have a great day.