LiqTech International, Inc.
NNASDAQ:LIQTQ4 FY2025 · Earnings Call TranscriptFebruary 27, 2026
Moderator
Good morning and welcome to the LiqTech International reports fourth quarter and fiscal year 2025 financial results conference call. All participants will be in listen-only mode.
Should you need assistance, please signal a conference specialist by pressing star then zero on your telephone keypad. Please note this event is being recorded.
I would now like to turn the conference over to Robert Blum with Lytham. Please go ahead.
Robert Blum
All right, thank you very much, Drew, and good morning, everyone, and thank you all for joining us on today's conference call to discuss LiqTech International's fourth quarter and full-year 2025 financial results. Joining us on today's call from the company are Fei Chen, Chief Executive Officer, and David Kowalczyk, the company's Chief Financial and Chief Operating Officer.
Before I turn the call over to management, let me remind listeners that there will be a Q&A session at the end of the call. To ask a question through the webcast portal, simply type in your question through the ask a question feature in the webcast player.
Before we begin with prepared remarks, we submit for the record the following statement: This conference call may contain forward-looking statements. Although the forward-looking statements reflect the good faith and judgment of management, forward-looking statements are inherently subject to known and unknown risks and uncertainties that may cause actual results to be materially different from those discussed during the conference call.
The company therefore urges all listeners to carefully review and consider the various disclosures made in the reports filed with the Securities and Exchange Commission, including risk factors that attempt to advise interested parties of the risks that may affect the company's business, financial condition, operations, and cash flows. If one or more of these risks or uncertainties materialize, or if the underlying assumptions prove incorrect, the company's actual results may vary materially from those expected or projected.
The company therefore encourages all listeners not to place undue reliance on these forward-looking statements, which pertain only as of this date and the date of the release and conference call. The company assumes no obligation to update any forward-looking statements to reflect any events or circumstances that may arise after the date of this release and conference call.
With that, I'd like to turn the call over to Fei Chen, CEO of LiqTech International. Fei, please proceed.
Fei Chen
Thank you, Robert, and good day to everyone on the call. 2025 represented a meaningful step forward for LiqTech.
For the whole year, revenue increased 13% driven by a 49% increase in total systems and aftermarket revenue, and we made improvements to drive efficiencies across much of our business. That shift toward higher-value systems sales is central to our long-term strategy and reflects growing adoption of our silicon carbide membrane technology across multiple end markets.
While we fell short of our original revenue guidance, this was primarily due to continued delays with a large oil and gas order that remains active in our pipeline. The project is still under discussion, but as we have constantly communicated, the timing of large oil and gas projects is difficult to predict.
That said, we understand that we cannot rely on unpredictable oil [unclear]. Our focus needs to be, and is, on building a diversified systems portfolio with stronger visibility and improved margin profile going forward.
In many ways, this has been consistent with our approach since I took over as CEO, to focus on more predictable parts of our business, such as swimming pools, which will be a key driver going forward. We are certainly amplifying this approach going forward in terms of how we allocate our resources.
Our commercial pool business was a standout performer in 2025 and delivered the strongest year in the company's history. We sold 34 pool systems during the year, a new record for LiqTech.
Of those, 24 systems were delivered in 2025, with the remaining 10 scheduled for delivery in early 2026. Pool system revenue totaled $2.6 million for the year and represented a driver of growth within our systems segment.
All systems sold during the year were based on our proprietary CleariFlo commercial pool filtration platform. CleariFlo is designed to meet the increasingly complex operational, regulatory, and space requirements facing modern aquatic facilities.
Compared to conventional media filtration, our system delivers stable and reliable water quality, while enabling greater automation and operational efficiencies. Its compact and modular design makes it particularly well-suited for retrofit installations where equipment room space is limited, an increasingly important consideration for operators upgrading aging infrastructure.
The record number of systems sales reflects growing customer acceptance and increasing confidence among both operators and distribution partners. We see clear momentum as facilities prioritizing water quality, automation, and space efficiency, and CleariFlo is emerging as compelling alternative to traditional filtration methods.
We have also made structural improvements to the pool system itself. Our newer, modular design is standardized and cost-efficient, which improves gross margins and simplifies installation.
Unlike oil and gas systems, which oftentimes are highly customized to specific customer needs, pool systems are increasingly becoming repeatable off-the-shelf solutions. This makes the market segment both more scalable and profitable.
From a distribution standpoint, we recently expanded our relationship with Barr & Wray in the UK into an exclusive distribution agreement subject to minimum annual system volumes. In addition, we are seeing interest from US-based swimming pool companies.
In these days, we are working on the final details for the first US swimming pool project. We see potential opening of a very attractive growth market soon.
All told, we have sold pool systems in six different countries in 2025 and look to expand that this year. Based on the guidance we have provided, we expect pool revenue of approximately $5 to $6 million in 2026, which compares to $2.6 million in 2025, reflecting continued market adoption and delivery of systems already in backlog.
Turning to water for energy, oil and gas remains an opportunity, but it continues to present timing challenge. We are engaged with multiple providers, both large and small, and the delayed order that impacted 2025 guidance remains under discussion.
As mentioned, these systems are typically highly customized, which not only make the timing unpredictable, but also impacts our margin profile. While we continue to pursue this segment and see potential opportunities with partner companies such as NESR in the Middle East and ongoing trials through Razorback Direct in North America, we are going to be disciplined in how we allocate resources, and we will no longer base our operating plan on difficult-to-predict customer timings, no matter how promised they may be.
Where we are seeing encouraging and increasingly tangible traction within broader water for industry applications. The successful delivery and commissioning of our advanced membrane-based filtration system for oily wastewater at the North Star BlueScope Steel has been a key proof point.
The system was designed to resolve recurring filtration disruptions of polymer membranes caused by high oil content and variability in wastewater quality, which has given our customer costly and difficult experiences. Our system has demonstrated strong performance.
This project has reinforced our belief that industrial wastewater treatment can become a larger and more stable contributor to our business. Industrial systems tend to be more standardized than oil and gas projects, which supports better margin and shorter sales cycles.
We are seeing increased interest across multiple industry verticals, and to support this growth, we added dedicate sales resource to expanding our industry presence in the US. In further support of our US growth strategy, we also opened a dedicated service center in Texas in partnership with Harrol Systems this past November.
This facility enhances our ability to support customers in the water for energy and water for industry segments by providing certified technicians, spare parts availability, remote and on-site technician support, and system maintenance and repairs. Localized service is critical to scaling in the US market.
The service center not only strengthens customer support, but has already began to contribute to new business development by increasing customer confidence in our long-term commitments to the region. Going ahead, we believe we will see strong contribution from industry side of the broader energy segment, with upside opportunities from the more specific oil and gas markets.
In total, we are expecting broader water for energy, water for industry-related revenue of $5 to $8 million. This compare to $4.1 million for this market segment in 2025.
We are happy to see that our marine segment is building momentum, particularly through our joint venture in China. During 2025, we broke ground on a new marine-focused R&D test center and the localization facility in Haimen, Nantong, and completed a regional spare parts warehouse to strengthen service capabilities for our growing marine customer base.
These investments are designed to support the development and localization of marine silicon carbide membrane water treatment units for dual-fuel engine vessels, on-board wastewater purification, and reuse. By increasing local assembly and sourcing within China, we are improving supply chain resilience and cost competitiveness in the market.
We strongly believe that silicon carbide membrane technology will continue gain adoption in new marine vessels equipped with dual-fuel engine, driven by its durability, chemical resistance, and energy efficiency. We ended the year with three marine orders for eight commercial vessels in backlog scheduled for delivery throughout 2026.
Marine revenue, including service sales, was approximately $1.5 million in 2025, and we are targeting approximately $4 million in 2026, reflecting a good market adaptation of our membrane filtration technology. Look at the broader systems business, including pool, water for energy, water for industry, and the marine side, our expectation is that we will generate revenue of $14 to $18 million.
This would be up from $8.2 million in systems revenue in 2025, showing growth of about 70 to 120%. This is a key reason why we are so excited about the future.
Beyond our systems business, we also have our legacy DPF and membrane business and the plastic business, which remains a stable contributor to our operations. Combined, these segments represented approximately $8 million in revenue in 2025.
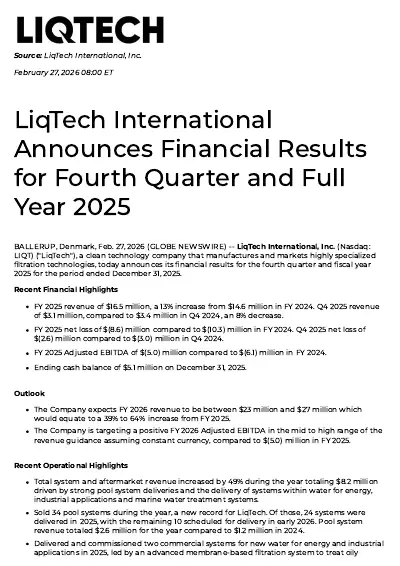
We expect this part of our business to remain reasonably stable in 2026, and in a caution outlook, are anticipating total revenue from the two groups combined to be slightly increased to $9 million in revenue. Looking at 2026, we expect revenue in the range of $23 to $27 million, a positive full-year 2026 adjusted EBITDA in the middle to high range of the revenue guidance, assuming constant currency.
Growth is expected to be driven primarily by continued expansion in pool systems, industry applications, and marine. The range in our revenue guidance largely reflects the continued unpredictability of oil and gas project timing.
Our strategic focus remains clear: scaled, standardized, higher-margin system platforms. We are maintaining disciplined cost control and operational efficiency, with the goal of near-term profitability.
Let me now turn the call over to David to review the financials in more detail. I will then make a few closing comments and look to open the call for your questions.
David.
David Kowalczyk
Thank you, Fei, and good day, everyone. Let me take some time diving into the financial results in a bit more detail and add some color to what was in the press release.
Please note that I will keep my remarks focused primarily on the year-over-year changes. Let's start with revenue.
Revenue for the year came in slightly above $16.5 million, up from $14.6 million a year ago. Broken down by verticals, sales for the year were as follows: Systems and aftermarket sales of $8.2 million, compared to $5.5 million in the prior year.
DPF and ceramic membrane sales were $4 million, down from $5.6 million in the prior year. Finally, plastic components revenue came in at $4.1 million, compared to $3.4 million last year.
The increase was mainly due to increased deliveries of systems, pool, energy, industry, and marine water treatment, and components in plastics, partly offset by decreased sales of filters. The increase in deliveries of systems was mainly driven by increased deliveries within pool filtration and industry systems.
The increase in components mainly within machine building for food industry. The decrease in sales of filters was primarily driven by a refocusing of our strategy to capitalize on sub-segments where we see increased future demand for DPF outside automotives.
As Fei mentioned, the delta between our recent expectations for '25 and actual results is primarily due to the delay in a larger oil and gas system, which remains in our pipeline, but we have not yet received the purchase order for. Turning to gross margins, margins for the year were 7.6%, compared to 1.7% in 2024.
As we continue to be below our optimal revenue level, we continue to have fixed production costs that are not being fully absorbed, and those lower the normalized gross margins. A couple of key notes is that part of the increase in gross margins was due to the higher level of overall revenue, as our contribution margins are typically on average in the 40% area, but we do have some fluctuations between market segments, as you know.
However, this was offset by the investment of resources into deliveries of containerized oil and gas systems to the US, which contributed to lower-than-usual margin, reflecting a strategic decision aimed at demonstrating the validation of our value proposition associated with our technology and seeding the market for future growth. As we move forward, a key focus will be on leveraging our standardized systems, which, inherently, are higher margin.
This means more focus on pools, industrial applications, marine applications, and membrane sales. Turning to opex, total operating expenditures for the year were $9.6 million, compared to $9.7 million last year.
Breaking it down, selling expenses for the year were $2.7 million, compared to $2.7 million last year. This development was partly driven by full-year effects of savings made in 2024 and lower accounts receivable write-offs and provision needs.
These effects were partly offset by costs associated with our newly formed joint venture in China, costs for outbound distribution, including tariffs to the US, and expenditures related to external sales consultancy services, which also increased in 2025. General and administrative expenses for the year ended December 2025 were $5.7 million, compared to $5.7 million in '24.
The underlying development in local currencies, Danish krone, was a 4% improvement compared to '24. This development was due to savings made in '24, partly balanced by filling the CFO position and other open positions.
Research and development expenses for the year was $1.2 million, compared to $1.4 million in '24. The decrease was primarily due to a more focused R&D strategy, with fewer ongoing projects and reduced average number of employees engaged in external research and development activities.
For the year, adjusted EBITDA was -$5 million, compared to -$6.1 million last year. Turning to our guidance, for 2026, we are expecting revenue to be in the range from $23 to $27 million.
As we break this down, we are anticipating that our broader water for energy and water for industry business will be between $5 and $8 million. We believe our pool business will be in the range of $5 to $6 million.
Our marine business will be about $4 million, of which 60% will be from new systems and 40% from our recurring service business. Finally, that our legacy DPF and plastics business will be about $9 million.
We target a positive full-year 2026 EBITDA in the mid- to high range of the revenue guidance, assuming constant currencies. Finally, from a cash perspective, we ended the quarter with $5.1 million in cash.
Everything else was pretty much in line with our normal operating procedures from a balance sheet perspective. With that, let me turn it back to Fei.
Fei Chen
Thank you, David. To close things out before I turn over to questions, our silicon carbide filtration platform is central to how we address increasingly complex global water challenges.
Built on advanced ceramic membrane technology, our solutions are designed to operate reliably in some of the harshest and the most demanding treatment environments, from produced water in energy applications to commercial pool systems and the heavy industry wastewater streams. By helping customers meet strict environmental regulation while lowering water usage and energy intensity, we provide practical, high-performance solutions that support long-term sustainability goals.
The momentum we generated in 2025, including record pool system sales, progress in produced water, marine system deployment, and the industry installations such as our project with a major steel producer, demonstrates the expanding global recognition of our technology's value. As we look ahead, our direction is well-defined.
We are prioritizing growth in our most attractive verticals, particularly pools, industry applications, and the marine. We are maintaining disciplined execution across the organization.
At the same time, we remain firmly focused on scaling the business to achieve profitability and positioning LiqTech for durable, profitable growth over the long term. Again, thank you everyone for your support of LiqTech.
With that, Robert, we would be happy to take any questions.
Robert Blum
All right, thank you very much, Fei and David, for those prepared remarks. I want to remind everybody that is listening through the webcast player to ask a question, simply type in your question through the ask a question feature in the player there, and we'll do our best to get to as many questions here as possible.
There are a few already in the queue here, Fei and David. The first one here is, when can we expect revenue from the large oil and gas order pushout to be booked?
David Kowalczyk
That's a good question, and of course as we mentioned, it's a bit, you can say, in the hands of the customer. We definitely would expect, you can say, the oil and gas project to materialize in the coming or in this year, essentially 2026, yeah, we don't know the precise timing, but towards Q2 finalization ideally.
Robert Blum
Very good. The next question here is, do tariffs affect your US oil and gas business?
Are your products competitively priced?
Fei Chen
This is very good question, and because the tariffs is a moving target, we really have our focus on that. Up to now, we have been able to kind of have very good discussion with our customers, we don't really need to take all the tariffs on ourselves alone.
Going forward, we definitely looking at what is the best way for us to handle the tariffs and how we are able to keep our competitiveness. As mentioned before, we are working very, very focused on the cost reduction of our products and also the standardization and efficiency, and that will somehow balance also to the tariff impact on our technology.
Robert Blum
Very good. Again, quick reminder to everyone, simply type your question into that ask a question feature in the webcast player if you do have any questions here.
Couple of questions here pertaining to your need for capital here in 2026.
Fei Chen
As you have heard today, we actually have laid out a very clear growth plan with the revenue guidance of the $23 to $27 million in 2026. We are definitely evaluating how we're able to support this strong growth plan, and that means we are looking at different financial options.
Robert Blum
Very good. Looks like this may be the final question barring any last-minute that may come in.
I think you've touched on this a few times, but to reiterate, what are the drivers of your 2026 revenue outlook of $23 to $27 million?
Fei Chen
This is very good question also, and as we used some time in our earnings call about this, and what we really have to say to ourselves is we have to make real focus on broader and diversified perspective, and also working more on the verticals which have more visibility and high predictability. We actually looking at the growth in basically all our system segments.
The pool system, we're going to have $5 to $6 million coming in this year, and the marine grow from $1.5 to $4 million. We said water for energy and water for industry will be $5 to $8 million.
There's a bigger range there because the oil and gas project are more difficult to predict the timing. The DPF and plastic plus the membrane area, we expect a slightly increase from $8 million to $9 million.
As you can hear now, the drive is from the different verticals, and this give us much more reliable, predictable revenue growth compared with before.
Robert Blum
Very good. I'm showing no further questions in the queue, with that, I would like to turn the call back over to Fei Chen for closing remarks.
Fei Chen
Thank you, Robert. I would like to say thank you to all of you for being with us today.
We look forward to communicating with you soon again. Thank you.
Moderator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect.