The Lovesac Company
NNASDAQ:LOVEQ2 FY2027 · Earnings Call TranscriptSeptember 10, 2026
Operator
Welcome to Lovesac's second quarter fiscal 2027 earnings conference call. At this time, all participants are in listen-only mode.
A question-and-answer session will follow the formal presentation. We ask you please limit yourself to one question and one follow-up.
You may then re-enter the queue with additional questions. As a reminder, this conference is being recorded.
I'd now like to turn the conference over to your host, Colton West, Investor Relations. Thank you, you may now begin.
Colton West
Thank you. Good morning, everyone.
With me on the call today is Shawn Nelson, Chief Executive Officer; Mary Fox, President; and Andrew Farag, Chief Financial Officer. Before we get started, I would like to remind you that some of the information discussed will include forward-looking statements regarding future events and our future financial performance.
These include statements about our future expectations, financial projections, and our plans and prospects. Actual results may differ materially from those set forth in such statements.
For a discussion of these risks and uncertainties, you should review the company's filings with the SEC, which includes today's press release. You should not rely on our forward-looking statements as predictions of future events.
All forward-looking statements that we make on this call are based on assumptions and beliefs as of today, and we undertake no obligation to update them, except as required by applicable law. Our discussion today will include non-GAAP financial measures, including EBITDA and adjusted EBITDA.
These non-GAAP measures should be considered in addition to, and not as a substitute for, or in isolation from, our GAAP results. A reconciliation of the most directly comparable GAAP financial measure to such non-GAAP financial measure has been provided as supplemental financial information in our press release.
Now, I would like to turn the call over to Shawn Nelson, Chief Executive Officer of The Lovesac Company. Shawn?
Shawn Nelson
Good morning, everyone, and thank you for joining us today. I'll start by sharing a brief review of our strategic roadmap, and then I'll provide a high-level summary of our second quarter fiscal 2027 performance and some of the exciting initiatives we've brought to market.
Mary Fox, our President, will then take you through our customer acquisition engines, operational initiatives, and key growth enablers. Finally, Andrew Farag, our new CFO, will dive deeper into our financial results and provide additional detail on our outlook for the third quarter and balance of fiscal 2027.
Before diving in, I want to welcome Andrew, who joined us as Chief Financial Officer just in June of this year. Andrew brings more than 20 years of finance and operating leadership across retail, consumer goods, and manufacturing.
He is the right partner as we execute the most ambitious product innovation roadmap in Lovesac's history coming up. We are thrilled to have Andrew as part of our #LovesacFamily.
Before discussing the quarter, I'd like to step back and think about the broader state of the category and our business. We are all too familiar with the operating environment for the home category over the past several years, up through our fiscal 2027.
This K-shaped economy, consumer sentiment, and category headwinds appear to occasionally ease, only to pick back up as the macro environment changes. Across the category, we are seeing deeper promotions from competitors than ever before, from some of the industry's strongest brands.
While we have adjusted our strategy to remain competitive, we have never lost sight of a simple belief: consumers do not need more furniture, they need better furniture and better solutions for how they actually live. Even in this challenging environment, Lovesac continues to gain market share, expand relevance, and accelerate innovation.
We built Lovesac as a disruptor by challenging the conventions of a category that had seen little meaningful innovation in decades. Rather than offering another static piece of furniture, we created Designed for Life product platforms that are built to last, designed to evolve, and made to love.
Our unique products solve the real challenges of how people and families actually live. The proliferation of modular offerings and copycat brands seeking to replicate some elements of our model validates the opportunity that we identified, but it doesn't dilute our leadership because our differentiation extends beyond configurability.
It is grounded in fully backward and forward compatible platforms, protected intellectual property, continuous innovation, and a growing ecosystem of products and services that increase the value of ownership over time. We believe these advantages position Lovesac to expand awareness, deepen customer relationships, and take significant market share in this large and highly fragmented market.
The convergence of our foundational capabilities that we began investing in years ago has picked up significant momentum in this Q2 period. Our product platform innovation engine, our digital-first marketing playbook, and our customer data infrastructure are all positioning us to enter this next phase of profitable growth with a stronger competitive advantage than at any point in our history.
Turning to our second quarter performance, we delivered our highest quarterly sales ever outside of Q4 in our company's history. Our record results were within our guidance range despite an operating backdrop that remains challenging.
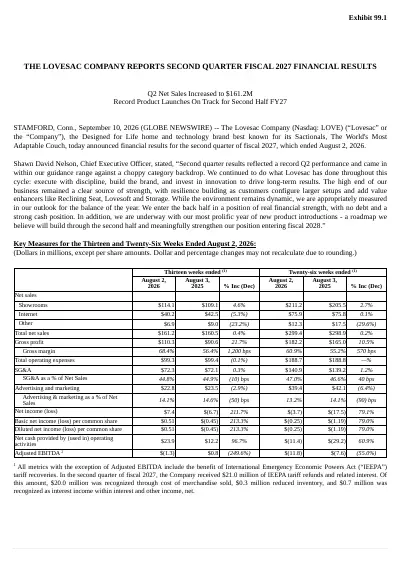
We delivered net sales of $161.2 million, a slight increase to last year. Importantly, we continued to gain market share, reinforcing that our platform model and brand proposition are resonating even in an uncertain consumer environment.
When customers clearly understand the durability, flexibility, and long-term value embedded in our Designed for Life platforms, they continue to engage with our brand. We saw particular strength on larger Sactionals configurations and premium enhancements, which gives us confidence that our value proposition remains compelling when the customer is ready to consider.
We are also thrilled with the early read and attachment rates of our white-glove and room-of-choice delivery programs, which we have recently piloted and plan to roll out nationally in the second half. Innovation continues to be the most visible proof point of our value proposition.
The Reclining Seat addition to Sactionals and our new Snug sofa platform both reinforced the power of our platform approach during the quarter. Reclining Seat deepened engagement with Sactionals, boasting record high attachment rates, while Snug broadened our reach with its more digitally advantaged and incremental offering.
More than 50% of Snug sales are occurring online as intended, with its simpler feature set, simpler shopping experience, and lower entry price point. These are not isolated product wins.
They are evidence that our platforms can expand customer relevance, create new entry points, and compound value over time, all of which increase our confidence as we launch the most prolific innovation roadmap in Lovesac's history that will be rolling out with the introduction starting in the second half. While the macro environment continues to create friction on opening price points for Sactionals, we are encouraged by the improvement that we have seen on those below $6,000 setups, and the engagement we are seeing in the funnel, including quote activity.
We also recognize that in this environment, some customers are taking longer to convert. Our job is to meet that moment with sharper accessibility and value perception while preserving the premium positioning and attachment opportunities that make Lovesac distinct.
As Mary will discuss, we have invested in pricing optimizations that we expect will recapture the opening price point consumer and better position us in the second half. Looking ahead, what excites me most is that we are continuing to challenge the conventions of the category through the acceleration of our product platform innovation engine.
Building on the successful launches of Reclining Seat and Snug, the second half of fiscal 2027 will represent the most prolific period of new product introductions ever. While we can't share all the details, we will be launching innovation that unlocks even more personalization and comfort in our Sactionals platform, extensions to the Snug platform that will enable greater functionality and consumer appeal, and a brand-new seating platform that will broaden our total addressable market and attract a more premium customer segment.
All of this will begin to take effect in Q4. Of course, all this comes ahead of the launch of our new room in FY28, which remains on track.
Preparing for this period of accelerated innovation requires planned investment in inventory ahead of the associated revenue opportunity. While product platforms will always remain a superpower to Lovesac, history has proven that brands become bigger and more valuable than products alone.
We wake up every morning to our stated mission of building the most loved home brand in America. We shared with you in Q1 the launch of our "Here for Life" campaign, and I am pleased that Q2 brought significant momentum as we shifted from simply telling our story to embedding Lovesac into cultural moments and conversations in an authentic and equity-building way.
Finally, as we have discussed the past several quarters, we will be launching our initial onshore production of Sactionals seats in the second half of FY27, bringing with it speed, flexibility, and automation, while remaining forward and backwards compatible with every generation of Sactionals born and yet to come. The net result of these efforts will be improved customer experience, stronger margins, and a further reinforced IP moat.
In closing, as we enter the second half of the year, my conviction in the opportunity ahead of us has never been stronger. The capabilities that we have spent years building are converging simultaneously starting in that second half: product innovation that expands our total addressable market, brand building that turbocharges our new customer acquisition, customer data infrastructure that unlocks quote conversion and LTV, services that build in deeper, longer-lasting relationships, and a supply chain that brings manufacturing closer to the customer.
To reinforce why we are so confident in our second half, particularly Q4, we have four significant innovations to launch even before we get to that new room that is hotly anticipated for next year. Anyone of these four might have been our once-big annual innovation in any prior year, and they represent some of the payoffs from our years of R&D that we have been long investing in.
We will be very focused on bringing all of these to market over these next 6 months. We expect to further dominate sectional sofas with the launch of a Snug corner piece and ottoman that can transform any Snug chair, loveseat, or sofa into a full sectional platform, as well as the reverse-compatible swivel base for the Snug chair.
That Snug chair with the swivel is my new favorite product. I have seven of them throughout my home at this point.
Snug is thus our small-format sectional sofa platform. We also have a significant innovation to introduce on the Sactionals platform as we onshore that will unlock personalized comfort in every seat in a way that is unlike any modular sectional sofa on the planet.
Finally, we will launch an entirely new, very large-format sectional platform that will expand our TAM and attract an even more premium customer. There is another big introduction after the holidays that we are not ready to speak to in any detail yet.
Four of these huge innovations will solidify Lovesac's ongoing and growing leadership in sectional sofas. All of this innovation will begin to take effect in Q4, and combined with the full national rollout of white-glove and room-of-choice delivery services, it positions Lovesac to compete like never before.
We enter the second half of the year from a position of considerable strength. Our balance sheet remains healthy, with a strong cash position, no debt, and inventory that is better aligned to demand.
This merely sets the stage for FY28, when we will be bringing Designed for Life to an entirely new room of the home, which remains on track. While the financial benefits of all this will not arrive all at once, we believe the cumulative effect of these initiatives will become increasingly visible over the coming quarters, reinforcing our confidence in the long-term algorithm that we are building.
Finally, I want to thank our teams, associates, partners, shareholders, customers, and the entire #LovesacFamily for their continued dedication, creativity, resilience, and passion as we continue to live up to our stated purpose: to inspire humankind to buy better stuff, especially our stuff, they can ultimately buy less. With that, I'll turn the call over to Mary.
Mary Fox
Thank you, Shawn. I'll build on Shawn's remarks by focusing on how we are translating our platform advantage into customer acquisition, conversion, and long-term engagement.
As Shawn discussed, Lovesac was built as a disruptor by challenging the conventions of a category that has seen little meaningful innovation. Our Designed for Life platforms continue to set us apart by giving customers adaptable solutions that evolve with their lives and increase the value of ownership over time.
Unlike traditional furniture purchases that depreciate in value and relevance over time, our customers enter our platforms through highly differentiated product offerings and remain engaged through a steady stream of innovation, upgrades, and enhancements that increase the value of ownership over time. This creates a powerful economic model: strong customer acquisition supported by years of follow-on engagement and lifetime value enhancement, all tied to an initial customer acquisition cost that pays back on the first purchase.
As we turn to quarter two, we are proud of how our teams executed, delivering the highest quarter two revenue in our history in an environment and category that remains dynamic. Against this backdrop, we continue to keep one hand on the now and one on the next, strengthening our core business and accelerating customer acquisition to deliver in the near term while building the most prolific innovation roadmap with launches to come every quarter over the next year, alongside the capabilities and infrastructure that will accelerate Lovesac's next chapter of growth.
As Shawn reviewed, demand with our premium customer remains healthy, as reflected in our performance with configurations over $6,000. In quarter two, we saw the segment grow double digits, even against a very strong prior-year lap, led by larger configurations, premium fabrics, and our newest innovations.
These customers are spending more, and our premium mix remains structurally stronger than it was 2 years ago. As we discussed last quarter, the opportunity remains below $6,000, where these customers have been disproportionately impacted by the last several years of inflation and raising rates, as well as the significant spike in gas prices, including Labor Day's all-time high.
In quarter two, the tactics we executed improved the run rate of the under-$6,000 business, but it has not yet been enough to return that segment to growth. In quarter three, we invested in pricing and optimized our promotional strategy to improve accessibility at key opening price points while preserving the premium positioning, innovation, and attachment opportunities that continue to resonate with the higher price point customer.
With our Labor Day events still underway through this weekend, it is too early to get a full read on the performance from these changes, and this is why we are taking a more conservative approach in our outlook, as Andrew will review. Turning then to our customer acquisition engine performance in quarter two, our brand and performance marketing strategy continues to evolve from merely driving transactions to building a modern customer acquisition, lifetime value, and brand love engine.
Our "Here for Life" campaign, a full 360-degree campaign across paid, owned site, store, and retail partners, ran across every major customer touchpoint and successfully strengthened engagement, consideration, and emotional brand relevance. Our marketing efficiency and ROI improved significantly during the quarter, and we are bullish that the foundational work we have put in place will better drive investment towards the channels and journey moments that have demonstrated the strongest demand creation.
Quarter two was among the most visible periods in Lovesac's history, as programming around the World Cup in partnership with Trevor Noah, activating at the CMA Fest, and expanding our creator partnerships generated more than 3.2 PR impressions, significant growth in our social engagement, and increased top-of-funnel strength across awareness and consideration. Now, this is just the start.
The faster we transform our communication from functional benefits into entertainment, fandom, and community, anchored on the universal truth that we do tend to spend our time on the couch with the people that matter most, the faster we will build a brand that transcends category conventions and earns a larger place on consumers' hearts through cultural relevance. This brand transformation is underpinned by investments in new customer data capabilities, AI and search visibility, media mix optimization, and a more sophisticated marketing engine that will allow us to efficiently scale new customer acquisition while improving return on investment.
Just as importantly, we are on the precipice of connecting brand building and customer relationship management through our unified CRM transformation that is being implemented in quarter three. This will unlock the capability to deliver personalized customer experiences at scale, putting the right message with the right incentive at the right funnel moment to support the customer based on their individual journey.
We look forward to sharing more on this critical initiative on our next earnings call. Next is our digital configurations and how we bring Lovesac to life online.
We know many of our customers begin their journey online and often purchase in store. This is the power of our omnichannel model, and we continue to advance our digital playbook to better communicate and bring customers through the purchase funnel, which we believe will bear fruit in half two.
As with Q1, we continue to see record levels of web customer satisfaction, demonstrating that our focus in enhancing customer experience and reducing friction will continue to scale. Our showroom network continues to demonstrate the strength of our model and proves that when customers experience Lovesac first-hand, the power of our platforms become tangible.
Despite the headwinds we mentioned on the under-$6,000 customer, our associates were able to drive a double-digit increase in conversion while building a strong quote pipeline. That conversion performance helped offset the traffic pressure and contributed showroom growth beyond the benefit from new locations.
These results reinforce our core belief that when customers can interact with our brand and platforms in a tangible way, we are able to translate consideration into purchase. Traffic remains our primary opportunity, and the brand investment, activation programs, and customer acquisition initiatives remain paramount focus entering the second half.
Our partnership demonstrations continue to introduce customers to Lovesac and serve as an important awareness driver for our brand. Our performance was driven by the strategic exit of our Best Buy partnership in quarter three fiscal '26, which accounted for 160 basis points of total growth for the business.
For Costco, our operational improvements across segmentation, staffing optimization, and assortment enhancements continue to generate encouraging results, and partnerships remain a key focus for efficient customer acquisition that extends our reach while preserving the integrity of the Lovesac brand and customer relationship. Finally, our customer relationships remain the most important element of our customer acquisition engine.
Unlike the traditional furniture model, we are not built around a single transaction. Our platforms create opportunities to remain engaged with customers through services, upgrades, new products, and resale throughout the life of their ownership.
In quarter two, we gained significant traction across the suite of value-added services. Our white-glove and room-of-choice delivery programs are focused on attracting new customers to the brand and improving the post-purchase experience.
A lack of delivery options beyond our fast and free program have been a friction point for some of our customers in the past, and after successfully piloting these programs in the first half, we will be rolling out nationally in quarter three of this year, and we are pleased to see the growing attachment rates. Loved by Lovesac, as our resale program, continues to gain momentum, with 70% of customers on the platform new to the Lovesac brand.
This creates an attractive entry point to our platforms and an important component of our long-term customer acquisition strategy. Then pivoting to our critical growth enablers, our ability to continue our long history of market share gains depends not only on the products we design, but also on the operating capabilities behind them.
Our supply chain continues to become more efficient, resilient, and scalable, creating a true competitive advantage. We have successfully navigated the pressures of the current inflationary environment, particularly with oil, and are driving improvements to our operational metrics and unit economics while supporting a broader assortment, optimal inventory mix, and a growing innovation engine.
Our ocean freight partnerships have ensured capacity at contracted rates, helping to insulate our P&L from the dynamics of the broader market, while we continue to plan conservatively to mitigate risks on domestic shipping inclusive of last mile. Then finally, on tariffs, our assumptions remain consistent, and we continue to mitigate through sourcing diversification, operational discipline, and Fuel for Growth cost savings programs.
As you saw in our release, we received approximately $21 million of IEEPA tariff refunds to date, and Andrew will discuss the amount received and its financial statement impact. Lastly, as discussed, our initial onshore production of Sactionals seats remains on track to begin manufacturing in quarter three, not only bringing seat production closer to the customer, but enhancing comfort, functionality, and ease of assembly, while expanding our IP moat.
In sum, I will leave you with a few key takeaways. As Shawn shared, we are laser-focused on igniting the core of our business, winning across all pricing segments by improving accessibility and strengthening value perception, while launching our most prolific innovation roadmap in our history.
These new innovations are in the DC and on the water as we speak, and will begin to take effect in quarter four. We are evolving our customer acquisition engines, modernizing our marketing playbook ahead of our big quarter four tentpole events.
We're strengthening our winning omnichannel model and rolling out delivery services nationally in quarter three to remove friction and build customer relationships. All of this is happening in parallel as we finalize our product and go-to-market plans for the new room of the home launching in fiscal '28.
With that, I'll turn the call over to Andrew, who will provide additional details on how these customer, channel, and operating trends translated into our second quarter financial results and outlook.
Andrew Farag
Thanks, Mary, and good morning, everyone. As Mary discussed, our second quarter performance displayed our commitment toward execution of our strategic priorities against a challenging macroeconomic environment and uncertain geopolitical backdrop.
I'll focus my remarks today on three areas: first, the IEEPA tariff refunds; second, our second quarter financial results; and finally, our outlook for the remainder of fiscal 2027. During the second quarter, we received a $21 million benefit related to IEEPA tariff refunds and related interest.
Of that amount, $20 million was recognized through cost of merchandise sold, $0.3 million reduced inventory, and $0.7 million was recorded as interest income within interest and other income, net. As of this call, we have received substantially all of our expected refunds.
We will be opportunistic in leveraging these funds where we see a compelling return on investment, as well as offsetting supply chain cost pressures, while maintaining our commitment to profitability and balance sheet strength. Turning to our second quarter financial results, net sales increased 0.4% to $161.2 million.
This was supported by the contribution from 14 net new showrooms opened over the past 12 months, helping to partially offset the omnichannel comparable sales decline of 1.9%. Our comparable sales performance reflects the demand trends that Shawn and Mary discussed, with strength among our premium customers, particularly for larger Sactionals configurations and newer innovations, partially offsetting the continued pressure below the $6,000 price point.
Showroom net sales increased 4.6% to $114.1 million, reflecting the contribution from new locations as well as the strong conversion performance Mary discussed, which helped offset continued traffic pressure. Internet net sales declined 5.3% to $40.2 million, while other net sales declined 23.2%, primarily reflecting the closure of the Best Buy shop-in-shop partnership.
From a product perspective, Sactionals net sales declined 1.7% and Sacs declined 8.6%, while other products increased 198.2%, supported by continued growth in newer categories, including Snug and accessories. This growth provides early financial validation of Lovesac's ability to disrupt new product categories through innovation and extend the Lovesac platform.
Gross margin increased 1,200 basis points to 68.4%, compared to 56.4% in the prior-year period. The primary driver was the recognition of IEEPA tariff recoveries.
Excluding tariff recoveries, Q2 gross margin was approximately 56%, representing a 40-basis-point reduction in gross margin. This performance reflects approximately 160 basis points of inbound transportation tariff costs, 130 basis points of outbound transportation and warehousing costs.
These pressures were partially offset by approximately 250 basis points of improvement in underlying product margin, reflecting the benefits of pricing and cost reduction initiatives. SG&A expense increased 0.3% to $72.3 million.
As a percentage of net sales, SG&A improved 10 basis points to 44.8%, compared to 44.9% in the prior-year period. The increase in SG&A dollars was primarily driven by approximately $1.9 million of higher payroll-related costs, including severance, and approximately $0.8 million of increased overhead expenses.
These increases were largely offset by a $1.5 million impairment charge related to the Best Buy partnership termination recognized in the prior-year period and approximately $1 million lower equity-based compensation expense. Advertising and marketing expense declined $0.7 million to $22.8 million and improved 50 basis points as a percentage of net sales, reflecting higher efficiency and investment timing.
Operating income for the quarter was $10.9 million, compared with an operating loss of $8.8 million in the second quarter of last year, driven by the factors we just discussed. Before discussing net income and adjusted EBITDA, refer to terminology and reconciliations between our non-GAAP measures and their most directly comparable GAAP measures in our earnings release issued earlier today.
Net income was $7.4 million, or 51 cents per diluted share, compared to a net loss of $6.7 million, or negative 45 cents per share, in the prior-year period. Net income per diluted share in the second quarter of fiscal 2027 includes an 86-cent net benefit from tariff refunds.
During the quarter, we recorded income tax expense of $4.7 million, compared to an income tax benefit of $2.1 million in the prior-year period, driven primarily by the generation of pre-tax income in the current year quarter compared to a pre-tax loss in the prior-year quarter. As a reminder, our effective tax rate can fluctuate based on the level of pre-tax income and the impact of discrete items, including stock-based compensation and other permanent tax differences.
Adjusted EBITDA, which excludes the $20 million tariff refund benefit recognized this quarter, was a loss of $1.3 million, compared to income of $0.8 million in the prior-year period. Turning to the balance sheet, we ended the quarter with $68.8 million of cash and cash equivalents, no outstanding debt, and $34 million of available borrowing capacity under our revolving credit facility.
Operating cash flow was a use of $11.4 million, compared to use of $29.2 million in the prior-year period. The improvement was primarily driven by the receipt of IEEPA tariff refunds, working capital performance, including a $34.3 million increase in accounts payable, partially offset by investments in inventory, accounts receivable, and prepaid assets to support future growth initiatives.
Inventory ended the second quarter at $130.2 million, compared to $124 million in the prior-year period. As Shawn and Mary discussed, we are preparing for a significant cadence of product innovation in the second half of the year.
These planned increases in inventory support those upcoming product launches, platform expansion, and appropriate in-stock positions. We continue to maintain a strong liquidity position and believe our balance sheet provides substantial flexibility to support innovation, growth initiatives, and disciplined capital allocation.
During the first half of fiscal 2027, we repurchased approximately $7.2 million of common stock, leaving approximately $46.9 million remaining under the current authorization. Before turning to guidance, I'd like to highlight the key assumptions embedded in our outlook.
From a macro perspective, our guidance assumes existing home sales and housing-related demand remain generally consistent with current trends, and customer discretionary spending remains in line with recent purchasing patterns. Our outlook reflects the freight, transportation, logistics costs, and tariff rates known today, and with the exception of adjusted EBITDA, includes only tariff refunds already received and does not assume future recoveries.
Finally, our guidance incorporates a more prudent, risk-adjusted approach to our Q3 and full-year outlook. As Mary reviewed, we are in the midst of changes to our pricing and promotional strategy, and while we believe the actions we are taking will continue to improve our performance with the below-$6,000 purchases, we believe it is appropriate to take a conservative view at this stage, particularly as we do not yet have a full assessment on how these will impact our ongoing Labor Day sale.
In addition, with our new products in transit, we now have greater visibility to the timing of these launches, which we now expect to begin in late Q3, with a more meaningful impact expected in the fourth quarter. Importantly, our outlook also reflects our ability to maximize operating leverage to deliver positive net income for the fiscal year.
For the third quarter, we estimate net sales of $140 million to $150 million. This includes gross margins of 54.5% to 55.5%, advertising and marketing of approximately 14.5% as a percentage of net sales, and SG&A of 47.5% to 49.5% of net sales.
We estimate a net loss to be between negative $9 million and negative $12 million. We expect adjusted EBITDA loss of between negative $7 million and negative $10 million, and we estimate basic loss per common share to be between 62 cents and 83 cents, with 14.5 million basic weighted average shares outstanding.
For the full year, we estimate net sales of $690 million to $710 million, which includes fourth quarter net revenues in the range of $250.5 million to $260.5 million. For the full year, this includes gross margins of 58.5% to 59.5%, advertising and marketing of approximately 12.5% as a percentage of net sales, and SG&A of approximately 40.5% to 41.5% as a percentage of net sales.
We estimate net income to be between $14.5 million and $18.5 million. We expect adjusted EBITDA between $31.5 million and $35.5 million.
We estimate diluted income per common share in the range of 98 cents to $1.26, and approximately 14.6 million estimated diluted weighted average shares outstanding. We estimate a full-year effective tax rate of approximately 36% to 38%, which reflects current federal and state tax laws, stock-based compensation activity, and other permanent tax items.
For modeling purposes, we would expect the tax rate for the remainder of the year to remain generally consistent with our full-year outlook, absent significant discrete tax events. In closing, I'm excited to be part of the team at Lovesac at this pivotal moment preparing for our next chapter of growth.
In my first 3 months in the role, I am confident we have the right team assembled, with a clear commitment to creating long-term shareholder value with a meaningful competitive advantage. In my role, I'll be looking to partner with the business to drive profitable growth and operational scale, while ensuring we improve the predictability of our execution and financial results.
With that, operator, let's open the line for questions.
Operator
Thank you. We will now be conducting a question-and-answer session.
We ask you please limit yourself to one question and one follow-up. You may then re-enter the queue with any additional questions.
If you'd like to ask a question today, you may press star one on your telephone keypad, and a confirmation tone will indicate your line is in the question queue. You may press star two if you'd like to remove your question from the queue.
For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. Thank you.
Our first question is from the line of Thomas Forte with Maxim Group. Please proceed with your questions.
Thomas Forte
Great. Shawn and Mary, always nice to hear from you.
Andrew, welcome to Lovesac. I have one question, one follow-up.
I'll go one at a time. Mary, can you give additional thoughts on Loved by Lovesac as a means to capture a customer who's increasingly more focused on value right now given the challenging macro backdrop?
Mary Fox
Yes. Hey, Tom, thank you for the question.
We are, as scaling out Loved by Lovesac. It's been a huge proposition for us, and since we had to build all the processes.
Really for us, this is enabling customers to be able to have access into our brand through our open-boxed inventory. As we grade it at like new and then at good.
I think the challenge for us at this point is whilst we built all the processes, we're now in 32 states, with four more coming actually in the next couple of months, is how we message that and share that with the customer is all upside for us. We're seeing a lot of customers engaging around buying new, getting covers as replacements, and 70% of the customers that are coming in to Loved by Lovesac are new to our brand.
Expect to see a lot more from us. First was getting the foundations in place so that we can build that velocity.
We are also planning one outlet that will be opening in Chicago because we do see that as an opportunity, particularly for customers to come and see the inventory. We'll share more on that, Tom, as we come.
All of it just reinforces what our brand can do that really no one else can do because of the modularity, the ability to ship it with very good economics, and be able to allow people into the platform, but then add on all the amazing innovations Shawn has talked about that is reverse compatible with that product. We'll share more as we go.
To your point, there is opportunity to capture that under-$6K in this way, and that's why we're very committed to continue to drive the program.
Thomas Forte
Excellent, Mary. Now I have a much more fun question.
Can we talk about your efforts to capitalize on higher-income consumers who appreciate the brand, including the upcoming higher-end Sactional, services, higher-end covers, etc.? In addition, how should we think about your couch share in formal living rooms as compared to less formal rooms in the home?
Then lastly, would you consider shop-in-shops with higher-end retailers such as Nordstrom?
Shawn Nelson
Thanks, Tom, this is Shawn. I'll take that.
We are so excited about the new product rollouts and focus on expanding our share of the living room overall before we get to, of course, the new room in early next year. Snug was our first step, trying to shore up our ability to sell into smaller spaces with a lower entry price point.
This introduction of the Snug corner piece and ottoman will really complete that offering, giving us let's call it a small-format sectional sofa solution. We have our medium-format sectional sofa solution that can do everything, right, in Sactionals: washable, changeable, rearrangeable, shippable, endless configurations with all the accoutrements from StealthTech to Recliner and more to come.
On that tried-and-true platform that currently is the lion's share of our business, we have one of the most compelling innovations ever that's linked to our onshoring opportunity that's in motion right now. You'll be seeing that roll out before the end of the year, and it will put further daylight between the Sactionals platform and everything else on the market.
Not to be outdone, your point about the higher-end consumer showing strength through this time of general weakness in the broader category, we have a large-format sectional coming that is amazing. This is a product that I think anyone familiar with Lovesac is going to want in their home.
It's a different profile, it's a different look, it's luxurious, and targeted to that higher-end consumer that's been looking for that profile. We know this through our research.
You'll see that come live in Q4. That's a big piece of our guidance.
A couple of these new innovations we had been targeting Q3 for launch, and while they'll kind of catch the very end of Q3, they won't make a material impact until Q4. This is the reason that we've guided the way we've guided.
Really excited about the notion of further dominating the living room, let's call it. You'll also be seeing some complementary products around the edges launched in Q3 and Q4 as well so that we can shift our focus into the new room in the coming year.
It's really about taking further share in the living room category by anchoring in sectional sofas. We're really excited about all these new innovations and looking forward to producing those results.
Operator
Thank you. The next question is from the line of Eric Des Lauriers with Craig-Hallum.
Please proceed with your questions.
Eric Des Lauriers
Great. Thank you for taking my questions.
First one's here just on the new product roadmap. First, in terms of timing, it sounds like launching at the end of Q3.
I think, Mary, you mentioned launching one new product per quarter. Sounds like the premium Sactional will be out by Q4.
Can you just kind of help us tie us tie this all together? Is it sort of one per quarter?
Should the premium Sactional Should we be thinking of that as kind of first out the gate? Is it correct to think that the premium Sactional is kind of the the biggest impact to the P&L out of these other product innovations that you that you outlined today?
Mary Fox
Yeah. No, thank you, Eric.
I'll take it, and then Shawn, maybe you want to add on to it. I think, first, there's going to be more in innovation launches in some of the quarters.
I think for us it's really just reinforcing Shawn's message around it's the most prolific innovation roadmap that we've ever seen. Typically, as you know us, we might have had one innovation for the whole year.
We now have a very steady drumbeat that's going to continue. I think the first one, as Shawn mentioned, is we have the Snug platform and all the great additions that are coming in that really take this platform that's incredibly elegant, can really be seen in many rooms of the home.
I think Shawn mentioned your most favorite product is the swivel that is reverse compatible with the Snug chair. For everyone who's already bought it, they can add on.
Then everyone forward can have it at the beginning. As well as having the corner piece and the ottoman that really builds this out to just being a beautiful sectional.
That you'll see in Q3 towards the back end. Then as Shawn mentioned, Eric, around the premium sectional, the sectional that's coming through that is just beautiful product and really, having experienced it and sat with it, it is unbelievable.
It is the best seat I've ever experienced, obviously, alongside with our Sactionals. Then the powerhouse of the business, so much of what has brought us here to nearly 28 years is our Sactional, and bringing this incredible innovation around the Sactional, bringing this personalized comfort.
We can't wait to show everyone because I think, Shawn, as we discussed, it really is in a group of just one. No one else has anything like this, and it is going to bring something that is true innovation to the category.
Then as you're right, in terms of then the other cadence, we'll have another launch coming soon after that that we look forward to sharing more with you. Then that continues to the new room.
Maybe, Shawn, you want to add a little bit to that because that's not just a couple of products, that is a full-room complement.
Shawn Nelson
Go ahead. The key takeaway here is that heretofore Lovesac has been seen as a Sactionals company.
Very quickly, just over the next quarter, we will be a sectional sofa company, of course with our leading platform in the Sactionals. Snug has been continuing to grow on itself, continuing to take a little bit of share of business, and it will continue to climb, we think, as our research shows us that the customers want to get more out of Snug, and the corner piece and ottoman is going to unlock that.
Then with this large-format sectional. What was kind of like a one-trick pony in sofa sectional land with Sactionals, as tricky as that pony is, there are silhouettes and footprints that we just weren't addressing that we will be fully locked in on going forward and never looking back.
Surround that with these complementary products, we'll just show up much better against the incumbent competitors that have much more prolific offerings than we have up to this point. That will carry us into next year, where we have yet another really exciting announcement to make just after holiday, and that will all precede, of course, our launch into the new room.
Each one of these individual sectional sofa introductions, as well as the one to come after holiday, would have been one of our anchor launches for a year in past years. They're all culminating over the next couple of quarters.
Four big launches over the next couple of quarters, again, preceding that launch into the new room, which has been a 3- and 4-year investment and drag on our SG&A, to be quite honest. We're really excited to turn on all of this new revenue opportunity that has heretofore just been expense.
Eric Des Lauriers
I appreciate that color. Then related and kind of looking at the lowered outlook for the year here, was there any sort of delay in the new product launches that contributed to the sort of lowered outlook here?
I know promotional environment was kind of cited as the primary driver, but just wondering, I think we were previously just talking about the premium Sactional, and now obviously there's sort of three or four new products. Has that led to any complexity or delays that influenced the reduced outlook?
Just kind of wanted to get a little bit more color on that. Thank you.
Shawn Nelson
Yes, thanks. To be straightforward, we were looking to have the Snug additions, which are meaningful—corner piece, ottoman, and swivel—the Sactionals addition, which is linked to our onshoring effort, and the large-format sectional that is yet to be revealed, all launching in Q3.
The only one that will be live for part of Q3 meaningfully will be the Snug introductions. Both the Sactionals onshoring effort linked to that new Sactionals innovation, as well as the large-format sectional, will be right at the end of Q3, really with no meaningful impact until Q4.
This is the reason for the shape of our guidance. While we never like to pull things down out of an abundance of caution, especially linked to the fact that we're in the middle of our Labor Day event right now, which is one of the top three tentpole anchor events of the year.
With the shift in timing, normally by this earnings call that we're on, we will have already been through that Labor Day tentpole event completely and have a good read, but in this case, we're right in the middle of it. Just out of an abundance of caution, we've taken, as you can see, some of the top-line expectation out of Q3, and just a little bit temperance on Q4 as well.
Therefore, a more conservative outlook for the balance of this year we think is prudent. We have lots of excitement and hope and expectation around these new products, and think they're going to do great.
Mary Fox
I think just one other point, Eric, to add is, as we talked, and we've been working on this for years, really excited is rolling out services nationally. One of the key advantages of services versus fast and free is our customers can select and schedule their delivery.
That does cause a little bit of lag in timing, whereas typically fast and free is shipping out in days, the customers can select. We're thrilled.
We're going to be nationally launched, shipping out to every zip code through white-glove and room-of-choice, but that does cause a little bit of lag as we kind of cycle through a year of having just some of that demand-to-net sales shift. It's a one-time impact.
All in all, I think as Shawn said, really the biggest shift was around the innovation timing. We have very clear line of sight.
Some is in the DC and then some is on the water. Now we're able to be incredibly sharp on all of our assumptions around the guide.
I think Andrew coming in as our new CFO gave us a really good ability to go through all the assumptions, really be surgical on the timing, and then really be committed to give a very pragmatic, prudent outlook for the year that we know we can deliver on, given all of these inputs. Just grateful for that sharpness as we look year-to-go in our execution.
Meanwhile, the teams are incredibly passionate. Every year, we drive to gain share, and we have demonstrated that every year, and you can expect that from the teams.
I really appreciate them for all of their work, because as Shawn said, the most prolific innovation cycle we're going into. There is just great work happening behind the scenes, and we can't wait to be able to share all of that with you soon.
Operator
Thank you. The next question is from the line of Maria Ripps with Canaccord Genuity.
Please proceed with your questions.
Maria Ripps
Great. Good morning, and thanks for taking my questions.
You mentioned sort of some customers are taking a little longer to convert. Can you maybe refresh us on your credit card and sort of other financing programs?
Is this one of the levers that you're able to pull to help conversion? Are you seeing any changes in consumer behavior when it comes to financing options today versus let's say 6 or 12 months ago?
Mary Fox
Yeah. No, thank you, Maria, for that question.
I think certainly we have many levers available for us to help with that final stage of conversion. Some of it has been around the events and sharpening those up, as well as a little bit of what I shared earlier around tightening up our MSRP, particularly in the opening price point.
I think on financing, and then we've shared these trends, is we continue to see a very clear segment of customer wanting financing and really buying into it. There is less in financing for us overall, and I think that really is just a matter of just customers have more and more choices through their own banks and many other vehicles.
We continue to test and learn, always looking in terms of every opportunity to be able to drive acquisition. I think back to kind of the beginning of your question, we're still seeing very similar sentiment and behaviors from customers.
They'll come in, they'll do their research, they'll maybe start online, they go to the showrooms, they build their quote, and then really convert, particularly at key tentpole moments, and really being able to give them the best prices and allow them to drive a lot more on the innovation add-ons and all the other things that only we can really give to them compared to any other brands. Expect us to continue to test and learn through the rest of this year, and obviously financing will be part of that.
Maria Ripps
Got it. That's very helpful.
Then how should we think about incremental marketing spend in Q4 to support your sort of aggressive product launches? I guess broadly for product-heavy quarter like that, what are your thoughts on the optimal mix of brand versus performance to sort of optimize how both sort of work together?
Mary Fox
I think as we've baked everything into our guidance, I think that's number one. Very perceptively, you've picked up that we have shifted some of our marketing spend because to Shawn's point, with all this incredible innovation, normally be one a year, we now have a very steady drumbeat of very significant launches.
We do want to be able to share that out. We have a big campaign coming up and being able to put the money behind that, that not only continues to drive, as you talk, at the very upper end of the funnel on the brand.
We started the campaign Shawn mentioned earlier around "Here for Life." That really is around cementing this brand and all of the options that we give to customers, all based on our Designed for Life product platform.
Then as you dip down into the funnel to be able to have the right level of marketing spend to be able to drive product storytelling and conversion. I think one of the great things that Heidi and her team have been doing is a lot more of the evolution around paid, earned, owned, and also really moving a lot more around digital investments and social-first investments.
You'll continue to see a lot more of us on that versus what you have seen, obviously, traditionally from a heavier linear investment. Quarter four, you will see more of that ramp-up really building on continuing to tell the story about the brand, but also making sure you leverage that story down through the platforms.
Just really excited. Shawn and I got to review the work that the team are doing on the quarter four playbook and how they're going to tell that story.
Just all of, Shawn, to your point, we're just going to have great strength in sectionals as a full category with all the great innovation that's to come, and our job is to tell that story and really stand in a category on our own because it's just a very unique and compelling customer-facing innovation.
Operator
Thank you. The next question is from the line of Matt Koranda with ROTH Capital.
Please proceed with your questions.
Hi, this is Joseph on for Matt. Just as we look at the full-year guide, just can you help us with the EBITDA cut of $7 million at the midpoint?
Just how much of that to the extent you can, how much of that is removing the IEEPA tariffs versus the softer demand outlook and incremental cost pressures from logistics and input costs, and any promotionality is assumed in the new guide?
Andrew Farag
Thanks, Joe. This is Andrew.
I'll answer that. As we think about EBITDA, specifically in the fourth quarter or even for the back half of the year, you will see again, based on our seasonality, you will see an improvement to our EBITDA, and that's what we're showing.
That's really driven by again, like Mary and Shawn mentioned, new product launches around innovation that's also tied to our services, and then there's optimization of our customer acquisition engine that we're factoring in there. All those are driving the profitability pickup along with just normal seasonality of the business.
As it relates specifically to tariffs, tariffs is not part of our EBITDA calculation, not part of our adjusted EBITDA calculation, not in our guidance, nor is it in our actual results. There's no underlying pickup as it relates to that in particular.
As we think about things around costs of fuel and freight, those are all factored in, and those are all steady state. Everything that we know today is baked in there.
If we think about the pricing and promotion, obviously, we're 4 weeks into an adjusted pricing and promotion scheme. We're looking to test the efficacy of that.
That's why you see that we've taken a more conservative approach to guidance overall as it relates to the second half, particularly in Q4. At the midpoint, we're still looking to have modest to flat growth as it relates to the back half of the year, specifically the quarters in question.
We're fairly confident, I think you'll see a guidance that's more rooted in financial discipline, and it's built on credibility from what we can defend and how we execute on that through the remainder of the year.
Got it. All right.
Thank you for taking my question.
Operator
Thank you. The next question is from the line of Brian Nagel with Oppenheimer.
Please proceed with your questions.
Casey McKenzie
Hi, this is Casey McKenzie on behalf of Brian Nagel from Oppenheimer. Thanks for taking my question.
I just wanted to understand outside of promotional activity and the timing of new product launches, could you discuss a little bit the extent to which macro pressures contributed to the reduction in guidance, and whether demand trends turn more challenging during the quarter, and possibly what specifically changed versus prior expectations? Thank you.
Mary Fox
Casey, thank you for the question. I think overall, we're really not assuming any differences in terms of any of the macro impact, consumer sentiment.
It really is very much what we've seen for the first half, and we've been sharing out. Then that continuation through the rest of this year.
Really the key drivers around the updates in the guidance are really around the innovation timings. Obviously coupled with that is then activating through the marketing campaigns, and just that continued customer acquisition engine optimization that we will continue to drive.
Then I think we touched on services, but I also think for us, what we're excited about is recapturing that under-$6K customer is our obsession, bifurcating in terms of also making sure that we continue to really win with that above-$6K customer who loves innovation, loves having the really big setups with all of the great benefits that only we can give them. We really are going to be doing a very heavy testing agenda through the rest of this year to capture back that segment.
Other than that, it really is just the assumptions is that, I think, Shawn, you always phrase it the soggy playing field, and we will continue to focus on what we control and drive the business. Shawn, I don't know anything else you want to add.
Shawn Nelson
I'll just add, and to dovetail the question thrown out earlier to Andrew about EBITDA and also what you put forth, Katie, around these macro pressures, this is where Lovesac is. We've been really holding our SG&A relatively flat.
It's going to be flat, we believe, overall for a long time to come. We've built a business that can scale.
It's not scaling at the moment in these macro pressures, to your point, but we intend to kind of innovate our way out of this and really get back to growth in measures that we can control through innovation, through product launches, through a better deployment of marketing capital in new ways to drive not just top line ultimately before the end of the year, but EBITDA and earnings going forward. This is underpinning, of course, our launch into the new room in the year to follow.
We're not waiting or expecting any kind of recovery in the macro as much as we sometimes see a glimmer of hope. This is the new normal, and our intention is to, again, manage our SG&A tightly and drive some growth through these product innovations, and ultimately, do a better job at returning value to shareholders in this way.
We're really landed on the business at this point and expecting nothing from the macro environment.
Casey McKenzie
Very helpful. Thank you.
Operator
Thank you. At this time, that concludes our question-and-answer session.
I'll hand the floor back to management for closing comments.
Shawn Nelson
Thanks so much to all the investors, customers, and the Lovesac team that continues to support this business and propels us to new heights. Appreciate your support.
Operator
Ladies and gentlemen, thank you for your participation. This does conclude today's teleconference.
You may disconnect your lines at this time. We thank you for your participation.
Have a wonderful day.