Miller Industries, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 5, 2026
Operator
Good day, ladies and gentlemen, and welcome to the Miller Industries third quarter results conference call. Please note this event is being recorded, and now at this time, I would like to turn the call over to Will Miller at Miller Industries.
Please go ahead, sir.
Will Miller
Good morning, everyone, and thank you for joining us for our third quarter 2026 earnings call. I'd like to begin by thanking our employees around the world for their continued hard work and commitment.
Our third quarter performance and continued progress in strengthening the business reflect the dedication of our team and the ongoing support of our suppliers, customers, and shareholders. As always, our remarks today will include forward-looking statements.
Actual results may differ materially. Please refer to our SEC filings and the safe harbor statement included in today's presentation.
Before turning the call over to Debbie for a more detailed review of our results, I'd like to discuss a few highlights from the quarter. We delivered solid year-over-year revenue growth in the third quarter with our continued focus on operational excellence in a dynamic environment.
Although we were impacted by holiday downtime at our European facilities and production challenges with certain domestic chassis suppliers, we anticipate solid revenue recovery in the fourth quarter of 2026. Importantly, while maintaining steady production levels, customer demand and order intake stayed consistent.
We remain confident in the demand for our products as we finalize 2026 production and begin focusing on 2027. Our balance sheet is also exceptionally strong, with a growing cash balance and minimal debt.
This gives us greater financial flexibility to invest in the business and return capital directly to our shareholders, focusing on the areas where we see the greatest opportunities to create long-term value. Together, we believe these factors position us well for continued success.
Our core philosophy remains exactly as it has been since the company was founded: Miller Industries has the best people, the best products, and the best distribution network in the towing and recovery industry. That philosophy has guided Miller Industries for more than 35 years and will remain central to how we operate moving forward.
With more than 1,500 employees across Tennessee, Pennsylvania, France, the UK, and Italy, together with our extensive global distribution network, we have the scale, capabilities, and reliability to continue driving sustained, profitable growth. I want to thank our teams across the U.S., Europe, and the UK for their continued commitment and dedication.
Their hard work is critical to our ability to execute on our near-term priorities while positioning the business for long-term growth and value creation. With that, I'll turn the call over to Debbie to review the quarter in more detail.
I'll then return to discuss our markets, capital allocation priorities, and guidance.
Debbie Whitmire
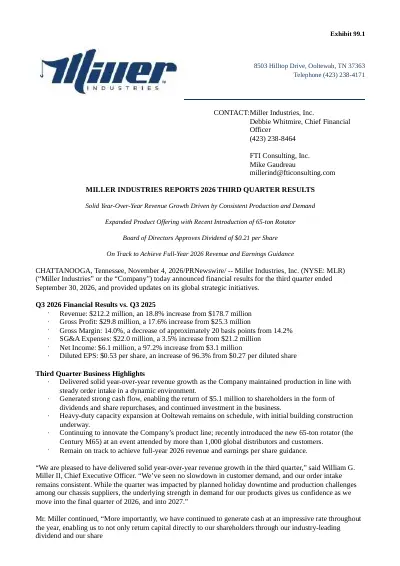
Thank you, Will. For the third quarter, revenue was $212.2 million, up 18.8% from $178.7 million in the third quarter of 2025.
This growth reflects a significant reduction in distributor inventory compared to a year ago. Gross profit was $29.8 million, or 14% of sales, and net income was $6.1 million.
During the third quarter, profitability continued to improve year-over-year, driven by strong execution across our global workforce. Gross profit was affected by product mix, and sales returned to a more historical level of chassis to bodies.
Additionally, OMARS' solid performance, including significant year-over-year growth, reinforces our confidence that the acquisition remains on track to be accretive in its first year. Diluted EPS was 53 cents per share, up from 27 cents per share in the third quarter of 2025.
As expected, EPS during the quarter continued to reflect non-cash expenses related to the OMARS acquisition, which positively impacted EPS by approximately 9 cents per diluted share. These expenses were primarily tied to adjustments of equipment to fair market value, amortization of estimated intangible value of customer relationships, and the associated tax amortization benefit.
The majority of the acquisition and integration expenses were recognized in the first and second quarters of 2026. Now I'd like to shift to a discussion of our balance sheet.
At the end of the third quarter, we had a cash balance of $60.4 million, up from $44.7 million at the end of 2025. Since the start of the year, we have also reduced our total debt by approximately $30 million.
With minimal debt on our balance sheet, we remain confident in our strong financial position. This combination of strong cash generation and a robust balance sheet provides us with greater financial flexibility to invest in our business and allocate capital to maximize value for the company and our investors.
In line with our longstanding commitment to returning capital to shareholders, we were pleased to return $5.1 million to shareholders through dividends and share repurchases under our share repurchase program in the third quarter. Now, I'll turn the call back to Will to discuss our markets and our outlook.
Will Miller
Thank you, Debbie. In the domestic market, current production levels are planned to continue into 2027 to meet consistent retail activity.
Geopolitical tensions in the Middle East have forced elevated diesel prices as well as reduced consumer confidence, which continue to apply pressure on retail demand, though we believe these pressures remain manageable for our customers. We look forward to the potential easing of tensions and will continue to monitor conditions and stay close to our distributors and customers.
As the global leader in innovation, we continue to expand our product portfolio with our most recent addition, a new 65-ton rotator, the Century M65. This latest evolution is without question the most advanced recovery machine ever produced by Miller Industries.
Just last week, we hosted more than 1,000 distributors and customers from around the world in Chattanooga to unveil the latest innovation in the towing and recovery industry. Innovation remains central to our strategy and is driven by a clear understanding of our customers and their needs.
The response at the event reinforced our confidence in both the breadth of our product portfolio, the strength of our distribution network, and our ability to effectively meet customers' needs through innovation. As we continue to invest in capacity, automation, and new product development, we believe that business is well-positioned to capitalize on growth opportunities across our global markets.
Turning to our international business, we continue to see meaningful opportunities across Europe and our broader export markets. Jige, Boniface, and OMARS provide Miller Industries with an established operating footprint in Europe and strengthen our ability to serve customers with products tailored to regional market needs.
This platform remains an important component of our long-term global growth strategy. We recently integrated Jige into our ERP system to streamline operations and improve efficiency as the business grows.
The team did an excellent job keeping production moving throughout the transition. Additionally, the capacity expansion project at Jige is on track to be completed in Q1 of 2027.
As we expand our global customer base, we remain confident in our international market outlook, consistent retail demand, and healthy backlog levels. Our military business continues to gain momentum.
We remain actively engaged with the U.S. and international government agencies on a growing pipeline of opportunities.
While our existing military commitments have now surpassed $200 million, pre-production and test units are currently in production, with serialized production expected to begin in 2027, with the majority of revenue anticipated to be recognized in 2028 and 2029. We believe the opportunity extends well beyond the programs already awarded.
Demand for advanced recovery capabilities continues to grow across multiple markets, and our expanding engagement with military customers positions this business to become an increasingly important component of our long-term growth strategy. In Ooltewah, our manufacturing capacity expansion continues to progress on schedule.
Construction of the new facility is underway, with foundation footings recently completed and building steel set to arrive in January of next year. We remain on track for the facility to be production ready by late 2027.
The more than 200,000 square-foot facility represents a significant investment in our long-term manufacturing capabilities. It will increase production capacity, improve efficiency, and support greater output of heavy-duty recovery equipment, our largest global export category.
The facility will also strengthen our ability to meet growing European demand and support higher volume global defense and military programs that require specialized equipment and advanced manufacturing capabilities. Strong cash flow generation gives us confidence in our ability to fund the majority of this investment through operating cash flow over the next several years.
Our strengthened balance sheet gives us even more flexibility to allocate capital to our five key priorities: our industry-leading quarterly dividend, currently at 21 cents per share, which we've now paid for 63 consecutive quarters; $2.7 million of share repurchases in the third quarter, with approximately $8.7 million remaining under our current authorization; maintaining a strong balance sheet and low debt levels; selective M&A opportunities; and ongoing investment in capacity expansion, automation, and innovation. This balanced approach enables us to continue investing for long-term growth while also returning value directly to shareholders.
Looking ahead, the trends we are seeing in our business give us confidence in our ability to achieve our previously stated guidance of $850 to $900 million in revenue for the full year of 2026. We also continue to expect that our earnings per share will be in line with full year 2025 results.
We now expect full year 2026 gross margins to be higher than previously anticipated, at approximately 14%, which reflects a decrease in chassis sales. We expect future product mix to trend towards historical levels of bodies and chassis.
We will be on the road later this month at the Southwest IDEAS Conference and look forward to connecting with some of you in person. In closing, the entire management team and I would like to thank our global operations team, all of our employees, suppliers, customers, and shareholders for their continued support of Miller Industries.
We are confident in our ability to navigate near-term market dynamics and capitalize on the significant long-term growth opportunities ahead of us. Thank you again for joining us.
Operator, please open the line for questions.
Operator
Thank you. Ladies and gentlemen, we will now begin the question-and-answer session.
Should you have a question, please press the star followed by the one on your touchtone phone. You will hear a prompt that your hand has been raised.
Should you wish to decline from the polling process, please press the star followed by the two. If you are using a speakerphone, please lift the handset before pressing any keys.
One moment please for your first question. Your first question comes from the line of Mike Shlisky from D.A.
Davidson. Please go ahead.
Mike Shlisky
Good morning. Thanks for taking my questions.
Will Miller
Absolutely. Good morning, Mike.
Mike Shlisky
Good morning. I guess I wanted to start just asking about the guidance and what may happen here in the fourth quarter based on what you just said.
You've talked in the past about entering the year at a billion or almost a billion top-line run rate. There's a chance here, given what you just said, that you could be a little bit above that to end the year here.
I'm curious what has to go right for you to get to that 260 or plus level to end the year, and if you do, do you think that's got legs through the early part of 2027?
Will Miller
Certainly, some of the chassis suppliers had a little bit of a hiccup in Q3, which affected revenue, not EPS nearly as much. We still believe we'll be in line with that 850 to 900.
I think moving into next year, we'll still be at that similar quarter-billion per quarter run rate moving forwards. That answers your question?
Mike Shlisky
Just so there may be a catch-up --
Will Miller
There may be a little bit of catch-up this quarter as the chassis suppliers try to catch up on some of the revenue that they didn't capitalize on last quarter.
Mike Shlisky
Got it. Can I just clarify, but we're early in November here, have they caught up a little bit, or have they started to catch up heading towards the holiday season?
Just curious whether the end here.
Will Miller
They had a fairly strong month in October. I wouldn't say they're caught up by any means, but they're certainly, as they all try to get towards the end of the year, they're trying to get trucks off the line and out as well.
Mike Shlisky
Okay. Thank you for that.
I also wanted to ask about the new Century rotator that you just released. I couldn't make it to the launch, it was during your quiet period for sure, just the last week or two.
What does the product mean to the portfolio? Do other products get wound down?
Does kind of cannibalize something else? I'm curious as to what you think that the net annualized impact from the new launch and the older products might be.
Will Miller
We believe there could be some potential cannibalization of our 75-ton rotator that was designed pre-2010. However, it still has some certain needs that fits in the marketplace.
What we believe is that between the two products, we will certainly be more competitive with our 65-ton and our current 75-ton product that we will be more competitive in the marketplace against our competitors and their 65-ton offering. Certainly, our new product is well beyond theirs in capacity and capability.
It also is, in the industry, the first fully greaseless operating system for a movable rotator. It's an engineering marvel in itself.
It went over very well at the event, and I believe we will, although we're waiting for chassis pricing for 2027 to really get quotes in for the product, I think we'll start out with a significant amount of orders for the new rotator coming into 2027.
Mike Shlisky
Oh, great. That was my next question was about the launch cadence here.
Is it already available to order or at least to preorder and to get in line for it?
Will Miller
The unit's available to order, although to get 2027 chassis pricing is still another week or so out. We're certainly hearing some activity, seeing some quotes being generated waiting for some final chassis pricing.
We anticipate chassis arrival for these to be May of next year at the earliest. We get about a half year of production with the new unit.
Looking forward to the back half of next year.
Mike Shlisky
Okay. First sales back half of '27?
Will Miller
Yep.
Mike Shlisky
Is that fair? Okay.
Maybe one last one, just wanted to get a sense on the construction at the new facility in Ooltewah. Every company I talked to so far this earnings season, just about all of them have talked about just having delays in their construction, finding people, finding materials, and also some inflation in what they're using to build their facilities.
It might not be Miller Industries, might be a very tight market for construction in general. Just some thoughts as to what you're experiencing at your facility.
Will Miller
We initially had a slight delay on our building steel. Although our general contractor believes after getting with all of the subcontractors and different experts, the electrical and plumbing and everything else, that they still believe they're on track to have temporary CO by September of next year to allow us four months to renovate our current facility and have increased production capacity by late 2027, early 2028.
We have seen some hiccups, but the team that's managing the project is on top of it daily and seems to be overcoming most of those. We did reach out well in advance for any long-term items, we ordered directly electrical components, switchgear, things of that nature.
Everything that we saw that was over 40 40 to 50 weeks of lead time, we preordered as soon as it was engineered. We were well out in front of some of the lead time issues that other projects are seeing.
Mike Shlisky
Got it. All right, well, I'll leave it there.
Thank you so much for the information.
Will Miller
Absolutely, Mike. Have a wonderful day.
Thank you for the questions.
Operator
Thank you, Mike. There are no further questions at this time.
I'd like to turn the call back over to Will for closing comments.
Will Miller
Thank you. I'd like to thank you all again for joining us on the call today, and we look forward to speaking with you on our fourth quarter conference call.
If you would like information on how to participate and ask questions on the call, please visit our Investor Relations website, millerind.com/investors, or email [email protected]. Thank you.
May God bless you, and may God bless our troops.
Operator
Thank you, Will. Ladies and gentlemen, this concludes your conference call for today.
We thank you for participating and ask that you please disconnect your lines.