Orbia Advance Corp. SAB de CV
Q3 FY2026 · Earnings Call TranscriptOctober 28, 2026
Operator
Good morning, and welcome to Orbia's third quarter 2026 earnings call. As we turn to slide 1, all participants will be in listen-only mode.
Should you need assistance, please signal a conference specialist by pressing the star key followed by 0. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star, then 1 on your touch-tone phone. To withdraw your question, please press star, then 2.
Please note, this event is being recorded. I would now like to turn the conference over to Diego Echave, Orbia's Vice President of Investor Relations.
Please go ahead, sir.
Diego Echave
Thank you, operator. Good morning, and welcome to Orbia's third quarter 2026 earnings call.
We appreciate your time and participation. Joining me today are Sameer Bharadwaj, CEO, and Cristian Capellino, CFO.
Before we continue, a friendly reminder that some of our comments today will contain forward-looking statements based on our current view of our business, and actual future results may differ materially. Today's call should be considered in conjunction with cautionary statements contained in our earnings release and in our most recent Bolsa Mexicana de Valores report.
The company disclaims any obligation to update or revise any such forward-looking statements. Now, I would like to turn the call over to Sameer.
Sameer Bharadwaj
Thank you, Diego, and good morning, everyone. Before we begin discussing this quarter's results, I would like to thank our global employees for their continued dedication and focus on addressing our customers' needs amidst continuously evolving market conditions, as well as extend my appreciation to our customers for their continued partnership and trust in us.
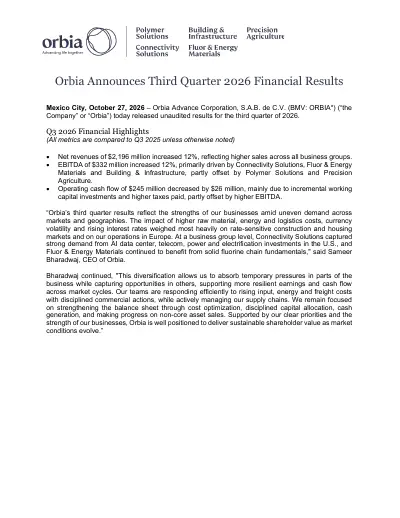
Turning to slide 3, I would like to share a high-level overview of our third quarter 2026 results. For the quarter, revenues of approximately $2.2 billion increased 12% and EBITDA of $332 million increased 12% compared to the prior year's quarter.
Orbia's third quarter results reflect the strength of our businesses amidst uneven demand across markets and geographies. The impact of higher raw material, energy, and logistics costs, currency volatility, and rising interest rates weighed most heavily on rate-sensitive construction and housing markets and on our operations in Europe.
At a business group level, Connectivity Solutions captured strong demand from AI data center, telecom, power and electrification investments in the US, and Fluor & Energy Materials continued to benefit from solid fluorine chain fundamentals. This diversification allows us to absorb temporary pressures in parts of the business while capturing opportunities in others, supporting more resilient earnings and cash flow across market cycles.
Our teams are responding efficiently to rising input, energy, and freight costs with disciplined commercial actions while actively managing our supply chains. We remain focused on strengthening the balance sheet through cost optimization, disciplined capital allocation, cash generation, and making progress on non-core asset sales.
Supported by our clear priorities and the strength of our businesses, Orbia is well positioned to deliver sustainable shareholder value as market conditions evolve. I will now turn the call over to Capé to go over our financial performance in further detail.
Cristian Capellino
Thank you, Sameer, and good morning, everyone. I will start by discussing our overall third quarter results.
Turning to slide 4, on a consolidated basis, net revenues of $2.2 billion increased 12% year-over-year, with growth coming from all business groups. EBITDA of $332 million for the quarter increased 12% year-over-year, driven primarily by strong demand and improved product mix in Connectivity Solutions, and commercial strength in Fluor & Energy Materials, partially offset by higher costs in Europe in Polymer Solutions and unfavorable sales mix in Precision Agriculture.
Operating cash flow of $245 million in the quarter decreased by $26 million compared to the prior year period, mainly due to higher working capital investments and taxes paid, partially offset by higher EBITDA. Free cash flow of $130 million decreased by $40 million year-over-year.
The decrease was driven by lower operating cash flow, partially offset by lower capital expenditures. Working capital increased by $10 million in the third quarter of 2026, compared to a decrease of $40 million in the same quarter of 2025, reflecting increased business activity, as well as the impact of higher selling prices and input costs resulting from the Middle East conflict.
Capital expenditures of $79 million in the quarter decreased by $7 million compared to the prior year quarter, and included ongoing maintenance spending and investments to support the company's targeted growth initiatives. Net debt to EBITDA decreased from 3.28 times to 3.10 times compared to the previous quarter.
The decrease was driven primarily by a decrease in net debt of $115 million, mainly driven by positive free cash flow and an increase of $37 million in the last 12 months EBITDA. Turning to slide 5, I will go through our performance by business group.
In Polymer Solutions, third quarter revenues were $675 million, an increase of 4% year-over-year. The increase was driven by higher prices in general resins, and was partially offset by soft demand for derivatives in Europe.
Third quarter EBITDA was $68 million, a decrease of 14% year-over-year, with an EBITDA margin of 10.0%. The decrease in EBITDA year-over-year was driven primarily by higher feedstock, electricity, and logistics costs, mainly in Europe, partially offset by higher margin in general resins.
In Building & Infrastructure, third quarter revenues were $660 million, an increase of 2% year-over-year. The increase in revenues for the quarter was driven by growth in Latin America and the benefits from the pricing actions implemented to offset higher raw material costs during the last quarter, partially offset by soft demand in Europe.
Third quarter EBITDA was $79 million, an increase of 4% year-over-year, with an EBITDA margin of 12.0%, driven by margin expansion in Latin America as a result of favorable pricing, partially offset by lower volumes in EMEA and the reversal of the timing lag benefit between price increases and rising input costs experienced in the previous quarter. In Connectivity Solutions, third quarter revenues were $373 million, an increase of 47% year-over-year.
The increase in revenues for the quarter was driven by continued volume growth, supported by strong demand across the US telecommunications and data center markets. Revenues improved as well supported by the favorable pricing actions taken to offset higher raw material costs during the last quarter.
Third quarter EBITDA increased 68% to $71 million, with an EBITDA margin of 19.1%, an increase of 234 basis points. The year-over-year increase in EBITDA was primarily driven by higher revenues, a favorable product mix, and high plant utilization.
Moving on to Fluor & Energy Materials, third quarter revenues were $311 million, an increase of 37% year-over-year. Revenue growth was driven by strong volume and the pricing actions implemented to offset the significant cost inflation pressures experienced during the year.
Third quarter EBITDA was $89 million, an increase of 39% year-over-year, with an EBITDA margin of 28.6%, an increase of 48 basis points. Higher EBITDA results for the quarter were driven by higher revenue, a favorable product mix, and the temporary benefit from product life cycle dynamics in part of the medical propellant product portfolio, partially offset by higher raw material costs, primarily sulfur, and higher freight costs.
Finally, in Precision Agriculture, third quarter revenues were $261 million, an increase of 1% year-over-year, mainly driven by higher project revenues in the Middle East and Africa, continued positive performance in Peru and the US, and the impact of pricing actions as a result of higher raw material costs. Third quarter EBITDA of $24 million decreased 21% year-over-year, and EBITDA margin decreased by 262 basis points to 9.2% versus the prior year period.
The decrease in EBITDA for the quarter was driven by an unfavorable sales mix, the reversal of the timing lag between price increases and rising input costs, and was partially offset by pricing actions. With that, I will now turn the call back over to Sameer.
Sameer Bharadwaj
Thank you, Capé. Before I comment on the outlook for the remainder of the year, I would like to take the opportunity to inform you that Orbia is rebranding its Building & Infrastructure business group as Orbia Water & Climate Solutions.
The new name better reflects the business's evolving portfolio, strategic direction, and long-term growth opportunities. It also reinforces our focus on differentiated solutions that advance water security, climate resilience, and sustainable living.
This direction is already visible in the growth and market traction of indoor climate solutions and urban climate resilience businesses, which demonstrate the potential of our upstream strategy. Orbia Water & Climate Solutions helps customers address some of the most pressing challenges facing the built environment and water management today.
Housing shortages persist, climate impacts are intensifying, and aging water systems are under growing pressure. In response, the business serves as a reliable partner in water security and climate resilience, delivering solutions that create value for customers and communities.
Turning to slide 6, I will now provide an update to our outlook for the current year. Based on the results so far and the company's expectations for the remainder of this year, Orbia now expects full year 2026 EBITDA will be approximately $1.25 billion.
Orbia remains watchful regarding demand trends for the remainder of this year and will manage operations accordingly. The company reaffirms its 2026 capital expenditures guidance of approximately $400 million, with a primary focus on investments to ensure safety and operational integrity, as well as selective strategic growth projects, particularly in the Fluor & Energy Materials business group.
Now looking ahead in each of our business segments for the coming quarter and the remainder of the year. Beginning with Polymer Solutions, PVC resin prices have moderated as global supply conditions have eased, although expected to remain above pre-conflict levels.
Recent oil and coal price increases have provided pricing support. However, near-term performance is expected to be tempered by soft demand and higher input costs in Europe and operational challenges in derivatives in Mexico.
The business will remain focused on cost and pricing discipline, operational safety, asset reliability, cash generation, and profitability. In Water & Climate Solutions, formerly Building & Infrastructure, the business expects demand conditions will remain challenging, particularly in Europe, with ongoing pricing pressure and the normalization of material margins.
The business continues to prioritize profitability and cash generation through footprint optimization, new product introductions, cost discipline, and working capital management. In Fluor & Energy Materials, the business expects the favorable fluorine pricing and product mix to continue supporting performance, offset by seasonal volume trends, rising raw materials and logistics costs, and the absence of the contribution from favorable product end-of-life cycle dynamics in part of the medical propellants product portfolio.
The business will maintain its focus on strategic pricing, safe and reliable operations, while advancing investments in next-generation medical propellants, mining infrastructure, and battery materials. In Precision Agriculture, demand is expected to strengthen as input costs stabilize, as well as due to seasonality.
The business expects to sustain solid momentum supported by strong project activity in Africa, continued strong demand in Peru and the US, improving conditions in selected markets, and the ramp-up of recently launched products. The business will focus on disciplined sales execution, cost management, inventory optimization, and cash generation initiatives.
Finally, in Connectivity Solutions, the business expects sustained demand growth, supported by telecommunications networks expansion and AI and data center infrastructure investment in the US. Continued pricing discipline, deeper penetration of higher value applications, and improved plant utilization are expected to support margin expansion and profitability growth.
In closing, Orbia remains firmly focused on its strategic priorities: delivering on our guidance, strengthening our balance sheet through deleveraging, simplifying our portfolio around our core strengths, and driving stronger cash generation. We expect organic growth, continued execution on our cost savings initiatives, and contributions from recently completed growth investments to support these objectives.
Together with disciplined capital allocation, these actions position Orbia to strengthen the business and create sustainable long-term value for shareholders. Operator, we are ready to take questions at this time.
Operator
Yes, thank you. We will now begin the question-and-answer session.
To ask a question, you may press star, then 1 on your telephone keypad. If you are using a speakerphone, please pick up your handset before pressing the keys.
If at any time your question has been addressed and you would like to withdraw it, please press star, then 2. At this time, we will pause momentarily to assemble the roster.
Today's first question comes from Ben Isaacson with Scotiabank.
Ben Isaacson
Good morning. Thank you very much.
Sameer, I just have one question about your stock. It seems like your stock trades at the lowest multiple of your five business lines, which is about 6 times on commodity PVC.
Many would argue that your integrated fluorspar business should trade at a much higher multiple, probably closer to 9 times, give or take. My question for you is, as you continue to allocate significant capital towards growing this business, what needs to be done differently, if anything, for the market to start fully recognizing and rewarding these investments?
My concern is that the market will keep giving you 6 times for the incremental capital that you're putting to work in a higher-multiple business. Thank you.
Ben,
Sameer Bharadwaj
that's a great question, and this is something we've struggled with for a long time, right? Even though we've tried hard to explain to investors and stakeholders our exposure, particularly in the fluorine chain, to battery materials, semiconductor materials in the future, and some of our other exposures, particularly in Connectivity Solutions through the AI data center expansion, in our Alphagary business as well to the AI data center markets, we don't see that reflected in the stock price.
It's hard for me to speculate what the reasons might be. I think we remain focused on executing, delivering results.
Our mantra is to basically deliver results, delever our balance sheet, and simplify and focus our portfolio. As we do that, and we begin to contribute more and more earnings from these higher-growth businesses, hopefully that should be reflected in the stock price as well.
Ben Isaacson
Thank you.
Operator
Thank you. The next question comes from Alejandra Obregón with Morgan Stanley.
Alejandra Obregón
Hi, good morning, Orbia team. Thank you for the call.
I have actually two questions here. The first one is on your fluorine division as well.
I was hoping if you can walk us through the maturity and the rollover profile of your key fluorspar contracts. As these contracts reset, how should we think about the opportunity to reprice the mineral, particularly given it's becoming increasingly critical across multiple end markets?
I'm assuming pricing will be strategic here. Then the second one is on the rebranding of your B&I division to Water & Climate Solutions.
How much should we really read into this strategic change? You did mention it is a better description of the portfolio you already have and the new trends, but what is it really signaling in terms of your capex, of your backlog, of where you want to compete, invest, and grow the business?
If you can be a little bit more specific about what this means for the strategic thinking of the division. Thank you.
Sameer Bharadwaj
Great. Thank you, Alejandra.
Let me take both of those questions. See, in the fluorine chain, we typically do not comment on our long-term contracts.
In any case, we don't have contracts that go very long term either given the tightness in the value chain and the leverage that we have. The team is highly focused on getting fairly paid for the value that we create in every product line that we have.
Right, the fluorine chain essentially operates in maximizing the value for the fluorine atom, and depending on which product it goes into, whether it's mineral or chemical intermediates, downstream refrigerants, and medical propellants. What I can say is this fluorine chain will continue to remain tight as the decade continues.
We will continue to exercise our position in that value chain and be a supplier of critical minerals, particularly in the Americas and to the western world. Now for Building & Infrastructure, the conclusion we came to is, at the end of the day, it's a business that's focused on water security.
We do not only hot and cold, soil and waste, foul water, but we're also providing solutions for indoor climate systems, solutions for urban climate resilience, which include stormwater management, rainwater collection and reuse, blue roofs, green roofs. The fact that many of our customers actually care about the sustainability metrics and the sustainable solutions that we provide, particularly as we have a leadership position in Europe and in Latin America, and our strategy has been focused on going more upstream, directly to architects, designers, and builders, as they think about new projects, these factors are very important to them.
We felt that Building & Infrastructure did not do justice to communicate the strength of the brand and was a primary factor in rebranding to Water & Climate Solutions.
Alejandra Obregón
Got it. If I may follow up, does that mean that you have new customers for the Water & Climate Solutions division now?
Is your backlog starting to look different, or is it something that you want to target from now on?
Sameer Bharadwaj
I think it's both. There are some parts of the world where we are more advanced in terms of working directly with upstream customers.
Now we have reorganized our commercial teams and sales teams to have a strong upstream focus in all parts of the world. We are at various stages of building out the connections and that backlog and that portfolio.
This is how we see we can differentiate ourselves by providing a comprehensive suite of solutions as builders and architects look at new projects.
Alejandra Obregón
Got it. That was very clear.
Thank you very much, Sameer.
Sameer Bharadwaj
Thank you.
Operator
Thank you. The next question comes from Andrés Cardona with Citi.
Andrés Cardona
Hi, good morning, Sameer, Capé, Diego. On the simplification theme, we have been hearing about this possibility for already a couple of years.
I wonder if you have any update about this progress, if you think you could have news over the short term, or if you are facing unexpected challenges to complete any of the divestitures? Maybe a second question, when looking into 2027, 2028 outlook, if you could help us to have some visibility about the ramp-up of the new projects that you may have, what is the expected EBITDA contribution from these expansions?
Thank you.
Sameer Bharadwaj
Very good. Andrés, on the simplification, what I can say is same as before.
From a strategy standpoint, we remain committed to simplification opportunities that create value for our shareholders. These things, as they are protracted efforts and take time.
If and when we have something concrete to say, we will disclose that appropriately along with the stock exchange guidelines. In terms of ramp-up of investments for '27 and '28, I'm pleased to say that we have completed the construction of the next-gen medical propellants larger-scale plant in the UK.
As we start the year, we expect to ramp up production, as well as sales to key pharmaceutical customers in the respiratory drug space through the course of the year. That one's going well.
The project on LiPF6 is in the engineering phase right now, and we're beginning to look at long-lead-time items. The timeline for the project is to execute that by the middle of 2029.
Far, the project is on track and on schedule. All the permitting, the engineering, and all of the detailed activities that need to happen are happening on schedule.
Then, of course, we have smaller projects in the businesses in terms of our downstream businesses, line additions, particularly in Building & Infrastructure, there have been new product introductions. These are ramping up, the Biax lines that we implemented in Europe, the Tigre fittings that we have implemented in Europe as well, and then in the UK the launch of the G5 Hep2O product line.
Those are going as planned. Then finally, in Connectivity Solutions, every new plant that we built in the last three years is operating at high utilization rates, and we're working hard to meet the continuously increasing demand of our customers.
As you can see from the results, that business is doing incredibly well, and the demand outlook for that over the next two or three years is very, very strong. Let me pause there, and happy to take any follow-up questions.
Andrés Cardona
No, thank you. Thank you, Sameer.
Very clear.
Sameer Bharadwaj
Thank you.
Operator
Thank you. The next question comes from João Barcellos with UBS.
Tasso Vasconcellos
Hi, Sameer, Cristian. Thanks for taking my questions.
I have two from my side. First, during the release, you raised the full year EBITDA guidance to $1.25 billion.
However, this imply a 40% sequential decline in results for the 4Q. My question is, what are the reasons for this decline?
In the outlook, you publish a more pressure scenario for Polymer Solutions and Building & Infrastructure. Could you provide more details on what caused this?
Second, based on the current net debt and the expected full year EBITDA guidance, Orbia would still reach the year end above 3 times net debt to EBITDA. What is the company target for leverage level going forward, and when do you expect to reach it?
That's it from my side. Thanks.
Sameer Bharadwaj
Sure, very good questions. Let me take the first one, and then I'll have Capé answer your second question on leverage.
Now in terms of guidance, I will admit that we have been conservative in our guidance for the full year in terms of approximately $1.25 billion. This is primarily given the geopolitical environment that we see and how things can change quite rapidly.
Having said that, if we go by the momentum that we have seen in October, if that continues, we should expect to end the year stronger than we have guided. We totally recognize that people will do the math and assume that Q4 is significantly lower, but once again, this is being conservative in view of the geopolitical environment that we are in.
The second question, Capé, why don't you answer? Yeah.
Thank you, Sameer.
Cristian Capellino
Regarding net debt, we're going to continue this year marginally reducing the leverage, getting very close to 3x. The perspective for the future, we want to operate below 2.5x.
We are committed to getting to a very strong balance sheet that can provide for cash flow generation and funding the growth initiatives that we have in a very disciplined way. About 2.5x is the level that will get us there.
Tasso Vasconcellos
Very clear, guys. Thanks.
Operator
Thank you. The next question comes from Nicolas Barros with JPM.
Nicolas Barros
Hi, good morning, everyone. My question is on this final decision of the antidumping duty from the US PVC imports, right?
Could you clarify whether this decision is now final or subject to any reversal, or if there are any remaining, I don't know, avenues to appeal or seek an increase in the duty rate? As a quick reminder, can you walk through the sensitivity of EBITDA to PVC pricing?
This is my first question.
Sameer Bharadwaj
Very good. Let me comment on the antidumping duty in Mexico.
As people may recall, there had been a provisional antidumping duty of over $600 a ton on US imports into Mexico as it was determined that the US producers were engaging in dumping activity. This has gone through an extensive review, and we've just received the news that the duty has been finalized at around a little over $391 per ton and will be effective for the next 5 years.
Our understanding is this is final. Now in terms of sensitivity of results to PVC pricing, it's a little complicated because it depends on lots of different variables.
Typically, if you are at high PVC prices, $100 a ton results in a $70 to $80 million a ton $70 to $80 million impact on an annualized basis. That's a very generic thumb rule.
It depends on the pricing scenario you're in, whether you're in the $600 range or the $800 range or the $1,000 range. At this point, we can see that PVC prices, which had gone well above $1,000 a ton due to the conflict in the Middle East, retreated back to below $700 a ton, and now I'm talking about the marginal ton, and has since recovered back to above $800 per ton, given the increase in oil prices and increase in coal prices in China.
They seem to have stabilized. The marginal ton appears to have stabilized in the $800 per ton range.
Our portfolio, given that we participate in advantaged markets, particularly in Brazil and in Latin America, in Europe, our average pricing is on the higher side, it's closer to $900 per ton. We hope to sustain that advantage as we go forward.
Nicolas Barros
All right. Thank you so much, guys.
Operator
Thank you. The next question comes from Regina Carrillo with GBM.
Regina Carrillo
Hi. Good morning, Sameer, Capé, Diego.
I was just wondering, given Dura-Line's recent earning growth and stronger results, could this potentially accelerate buyer interest in this division and could that increase your expectations for a potential valuation multiple going forward?
Cristian Capellino
Again, it's a it's a great question. We are seeing accelerated momentum, in our Connectivity Solutions business.
Keep in mind historically, the Connectivity Solutions business was largely focused on the telecom segment with focus on the last mile, fiber to the premises. This has massively changed in the last year alone.
We have seen the massive growth and emergence of the data center segment. Within the data center segment, you have two sub-segments.
One is on campus within the data center, both for data and power, and then what is called data center interconnect, connecting two different cities, two data centers in two different cities. We are seeing massive growth in demand, not only from the large telecom providers who are building these networks for the hyperscalers, but also directly from the hyperscalers.
A lot of this increase is driven by the growth of agentic AI to enterprises and the need for low latency. We expect this growth to continue in a very significant way.
We are in conversations with all of our key customers for their requirements, not only for '27, but for the next several years. Then we are also seeing good growth in the power segment as the the US grid is being power grid is being upgraded and modernized, right?
Quite frankly, there is a transformation going on in the Connectivity Solutions business where it's no longer focused on traditional last mile telecom, but we're seeing massive growth in the data center segments, as well as the power segment. We are positioning ourselves to be successful in this face in this space with, smart debottlenecking of our assets and making sure, we have the capacity to meet the needs of our customers as they grow.
Yes, to answer your question, this would, increase our expectations for this business going forward and hopefully, it has a positive effect on Orbia's multiple going forward as well. I would also say that it's not just, Connectivity Solutions and Dura-Line which will see this AI data center related growth.
Our Alphagary business, the compounds business within Polymer Solutions, provides key compounds for wire and cable applications inside the data center, and they are also seeing significant growth in those segments, and we should be beneficiaries of that as well.
Regina Carrillo
Perfect. That is very exciting.
Just one more quick question on the rebranding of Building & Infrastructure to Water & Climate Solutions. Does this involve any one-time costs or incremental marketing expenses, or is it only an internal rebranding?
Cristian Capellino
I think this will be largely internal, and the cost impact will be minimal at best.
Regina Carrillo
All right. Thank you so much.
Operator
Thank you. The next question comes from Victor Modanese with Bank of America.
Victor Modanese
Hi, good morning. Thank you for taking my questions.
My first question is on the Polymer Solutions business. How do you expect the recent rally we saw in ethane prices to affect the performance of this business unit?
Do you believe that there is scope to pass through higher feedstock costs to product prices, or would you expect potential further margin compression on top of what is already being considered by the company? Then my second question is with leverage declining over the past few years, specifically over the past few quarters, could you update us on your capital allocation priorities?
Does further deleveraging remain the top priority, or is there increasing scope to allocate capital elsewhere as well? Thank you.
Sameer Bharadwaj
Let me take the first question, and then I'll have Capé answer your second question on leverage. As far as Polymer Solutions pricing is concerned, pricing is determined by global demand and supply.
What I can say is that we've been in a generally weak demand environment for actually, I would say, several years, particularly in building and construction. In that context, what happened due to the Middle East conflict was a severe shortage of feedstock supply, which is why prices went through the roof.
Subsequent to that, oil has started flowing again from the Middle East, and feedstocks are available, and there is adequate supply, but the prices of the feedstocks remain high, which is why prices came down to below $700, $600 a ton, and now have recovered back to $800 a ton. Essentially, the marginal player on the supply curve sets the pricing for PVC, and so we would expect it to change as the supply-demand dynamics change.
What I would ask you to focus on is long-term supply-demand fundamentals. If you look at long-term demand, it continues to grow at 2.5% to 3% a year, and long-term supply is only growing at 1% a year at best, and in let's say 2 to 3 years, you would have significant increase in operating rates, as the gap between supply and demand closes, and as operating rates go from the mid-70s to the mid-80s, PVC prices will then go back to the peak, okay, and that is the long-term expectation, and that's a reasonable expectation to have, okay?
Hopefully that gives you a sense for how short-term prices work and what you would expect in terms of long-term pricing. Then, Capé will answer your question on capital allocation.
Cristian Capellino
Thank you. Going to capital allocation, first we have a key priority to deleverage the company, reach a sustainable level of leverage that provides with strength over the cycles.
We want to be able to operate on a free cash flow positive way across the cycles. Then we, of course, have important opportunities for growth in the company, we want to continue with this disciplined capital allocation approach to capex.
We have important opportunities in Fluor & Energy Materials. Sameer described the LiPF6 project for battery materials.
We have opportunities to enhance the performance of key assets in the Polymer Solutions business to continue to strengthen our cost position. We have opportunities of growth in Connectivity Solutions, as Sameer described, that as these fundamentals continue and the momentum continues, there is going to be opportunity for very profitable capital allocation to that business.
Of course, once we start to generate the return from all these investments and start to generate sustainable free cash flow, then of course, we are going to start to think about rewarding shareholders, right, in a sustainable way, and at that point then the board of directors, the shareholders will be talking about a dividend stream for the future. Those will be the key three areas of capital allocation looking forward.
Victor Modanese
Thank you. Very clear.
Cristian Capellino
Welcome.
Operator
Thank you very much. This concludes the question-and-answer session.
I would like to turn the conference back over to management for any closing comments.
Sameer Bharadwaj
Thank you very much. I thank everybody for joining the call, and for your interest in Orbia, and the thoughtful questions.
We remain focused on ending the year strong, and look forward to talking to you again at the end of February. Thanks once again.
Operator
Thank you. The conference has now concluded.
Thank you for attending today's presentation. You may now disconnect your lines.