Newmark Group, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Good day and welcome to the Newmark 3Q 2026 public financial results call. Today's conference is being recorded.
At this time, I would like to turn the conference over to Jason McGruder, Head of Investor Relations. Please go ahead.
Jason McGruder
Thank you, operator, and good morning. Newmark issued its third quarter 2026 financial results press release earlier today.
Unless otherwise stated, the results provided on today's call compare only the 3 months ending September 30th, 2026 with the year-earlier period. Except as otherwise stated, we will only refer to results on a non-GAAP basis, including terms with adjusted EBITDA, adjusted earnings, and adjusted free cash flow.
Unless otherwise stated, any figures discussed today with respect to cash flow from operations refers to net cash provided by operating activities excluding the impact of GSE, FHA loan originations and sales. We may also use the term cash generated by the business, which is the same operating cash flow measure before the impact of cash used for employee loans.
Please refer to today's press release, the supplemental tables, and the quarterly results presentation on our website for complete and updated definitions of any non-GAAP terms, reconciliations of these items to the corresponding GAAP results, and when, how, and why management uses them. For additional information on our cash flow measures as well as relevant industry or economic statistics, the outlook discussed today excludes potential impact of any future acquisitions and assumes no meaningful changes in Newmark stock price compared with yesterday's close.
Our expectations are subject to change based on various macroeconomic, social, political, and other factors. None of our targets or goals beyond 2026 should be considered formal guidance.
Also, remind you that information in this call contains forward-looking statements, including, without limitation, statements concerning our economic outlook and business. Such statements are subject to risks and uncertainties, which could cause our actual results to differ from expectations.
Except as required by law, we undertake no obligation to update any forward-looking statements. For a complete discussion of the risks and other factors that may impact these forward-looking statements, see our SEC filings, including, but not limited to, the risk factors and disclosures required regarding forward-looking information in our most recent SEC filings, which are incorporated by reference.
Now happy to turn the call over to our host and Chief Executive Officer, Barry Gosin.
Barry Gosin
Good morning. In advance, I'll apologize I'm a little bit under the weather, but I'm happy to be here.
Good morning and thank you for joining us. With me today are Newmark's Chief Financial Officer, Mike Rispoli, and our Chief Operating Officer, Lou Alvarado.
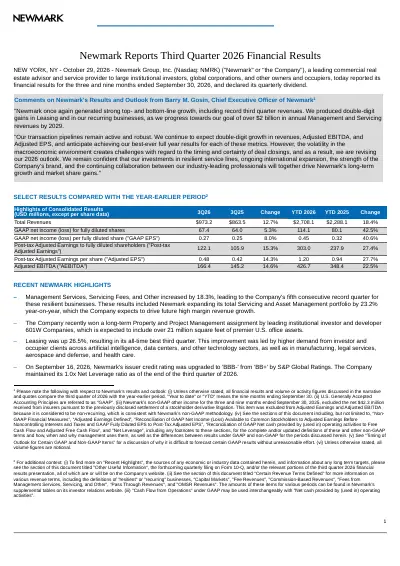
Newmark once again generated strong top and bottom line improvement, including record third quarter revenues. Our growth was led by management and servicing, which increased 18%, leading to the company's fifth consecutive record quarter for these resilient businesses.
We increased leasing by 26%, resulting in its all-time best third quarter. This was led by higher demand across artificial intelligence, data centers, and other technology sectors, as well as manufacturing, legal services, aerospace, defense, and healthcare.
Our transaction pipelines remain active and robust. We continue to expect double-digit growth in revenues, adjusted EBITDA, and adjusted earnings per share, and anticipating achieving the best annual results for each of these metrics.
However, the volatility in the macroeconomic environment creates challenges with regard to the timing and certainty of deal closings. As a result, we are revising our 2026 outlook.
We remain confident that our investments in resilient service lines, ongoing international expansion, the strength of the company's brand, and the continuing collaboration between our industry-leading professionals will together drive Newmark's long-term growth and market share gains. I want to take a moment to talk about our accomplishments over the past 15 years.
Newmark had a simple plan: elevate our brand by recruiting the industry's best talent, provide them with a differentiated platform, build credibility, and earn our way into the rooms where decisions are made. Starting in 2014, we chose to lead with capital markets, because when you are advising a client on capitalizing the most important asset in portfolios, you are helping key decision-makers fully realize their business plans.
Our strategy has worked. Newmark took its share of US commercial and multifamily originations from under 2% then to around 10% now.
We also moved up from number 10 in US investment sales in 2014 to number two for the first 9 months of 2026. Our success stemmed from our relentless focus on talent and from our professionals being innovative and entrepreneurial in everything they do.
You have seen the same focus and market share gains across all of our businesses, including our recent strong growth in leasing and valuation and advisory. Over the last few years, we have used the sturdy foundation laid by these service lines to build out our growing suite of recurring revenue businesses.
As a result, we have successfully driven growth in the following areas: property, project, and facility management; loan servicing and asset management; consulting, technology, advisory, and lease administration; and most recently, our fast-growing managed services solution for real estate lenders and investors. That is why recurring businesses increased from 24% of our total revenue in 2017 to around 40% year to date.
We remain confident that management and servicing will produce more than $2 billion of annual revenue in 2029, which implies double-digit growth. Our next chapter involves additional international growth.
Over the coming 18 to 24 months, we anticipate further expansion of our global footprint across nearly all service lines. Today, we derive approximately 13% of our top line from outside the US, while our large, full-service peers generate more than double or triple that percentage internationally.
We view that that gap as an opportunity. As we expand our geographic footprint, we also make Newmark a more credible alternative to win outsourcing assignments from large, global occupiers.
This has led to our occupier solutions teams competing in more pitches and being awarded more mandates. Over time, our goal is for Newmark to be invited into every room with key decision-makers across nearly all of our service lines globally, not only in New York and San Francisco, but in Berlin, in London, in Milan, in Paris, in Seoul, in Sydney, in Toronto, and dozens of other major markets around the world.
Based on our track record, I would not bet against us. Before I turn the mic the the call over to Mike, I want to briefly address Newmark's leadership.
As previously announced, after 47 years, I am stepping down as CEO at the end of this year. I love this company.
I will continue to be here to help see the transition. Both internal and external candidates are being evaluated, and we currently still expect to identify a new CEO a new CEO at the end of the year, by the end of the year.
I am confident in Newmark's senior leadership, who collectively have decades of experience. With that, I'm happy to turn the call over to Mike.
Mike Rispoli
Thank you, Barry, and good morning. Total revenues were up 12.7% to an all-time third quarter best of $973.2 million, compared with $863.5 million.
We increased management services, servicing and other by 18.3%. This was led by robust organic growth from Newmark's expanding suite of outsourcing businesses, as well as strong same-store improvement in valuation and advisory.
Management services fees also reflect six acquisitions completed since the third quarter of last year. Leasing was up 26.5%.
This reflected higher fees from industrial and office [properties?] across several key West Coast markets and Texas.
Capital markets revenues declined by 4.4% as Newmark's 33.4% rise in investment sales volumes was offset by lower origination activity. Our investment sales growth was led by senior housing and affordable housing, as well as higher industrial and retail volumes.
Our origination business faced a difficult comparison due to the 129.1% rise in our total debt volumes in the third quarter of last year. In addition, GSE industry activity declined by approximately 30% in the third quarter.
Over the trailing 12 months, Newmark gained over 70 basis points of combined Fannie Mae and Freddie Mac market share year on year. Moving on to expenses.
Total expenses were up 13.5%. Without pass-through items, total expenses would have increased 10.8%, with a large majority tied to the increase in commission-based revenues and our global growth initiatives.
Regarding taxes, the company's tax rate for adjusted earnings was 12.9% compared with 12.1% last year. Turning to earnings.
We increased adjusted EPS by 14.3% to 48 cents compared with 42 cents. Adjusted EBITDA was $166.4 million, up 14.6% versus $145.2 million.
With respect to share count, our fully diluted weighted average share count was 252.7 million, up 0.4% year on year. We repurchased 3.9 million shares for $59.4 million towards the end of the quarter.
On October 28th, 2026, Newmark's board reauthorized the company's $400 million buyback program. Given our strong financial position and recent share price, we anticipate further share repurchases.
Turning to the balance sheet. We ended the quarter with $240 million of cash and cash equivalents, $877.5 million of total corporate debt, and 1 times net leverage.
On a trailing 12-month basis, the company increased adjusted free cash flow by 16% to $336.8 million. A key reason we have improved our cash flow metrics has been our increased focus on M&A.
In the first 9 months of this year, our employee loan issuance dropped 36.9% compared with a year earlier. We expect this trend to continue for the foreseeable future.
Turning to guidance. We have revised our outlook due to the challenging macroeconomic environment and its anticipated impact on transaction volumes.
Our full year guidance for 2026 compared with a year earlier is now as follows. We expect total revenues between $3.7 and $3.8 billion, an increase of 12% to 15%.
We anticipate adjusted EBITDA in the range of $629 to $667 million, an increase of 12% to 19%. We continue to expect our adjusted earnings tax rate to be between 13% and 15% versus 11.4%.
We anticipate adjusted EPS between $1.80 and $1.90, up 11% to 17%. These results would be Newmark's best ever full year revenue, adjusted EBITDA, and adjusted EPS performance.
While it is too early to discuss guidance for 2027, we wanted to provide some additional color on how we view the market moving forward. We expect the fundamentals of our recurring businesses to remain strong and continue to expect double-digit growth.
We also expect leasing volumes to improve, albeit with single-digit gains, as compared to this year's strong double-digit improvement. We expect industry capital markets volumes to be down through at least the first half of next year, given the recent rise in the level and volatility of rates.
Given that market view, there could be a wide range of outcomes in terms of Newmark's 2027 results. Excluding any new acquisitions, we currently believe our 2027 earnings will be plus or minus 10% as compared with our record 2026 results.
With that, I would now like to open the call for any questions.
Operator
Thank you. If you would like to signal with questions, please press star one on your touchtone telephone.
If you're joined us today using a speakerphone, please make sure your mute function is turned off to allow your signal to reach our equipment. Again, that is star one if you would like to signal with questions.
The first question will come from Alexander Goldfarb with Piper Sandler.
Alexander Goldfarb
Thank you and good morning down there. Barry, obviously wishing you the best and I don't want to say retirement because I know you're going to stay busy and you love the business.
Your comment about the firm looking outside and inside. Obviously, we've gotten to know a number of the inside folks, but you guys have particular culture, very competitive, but very collegiate.
How does the board think about trying to bring in an outsider who would be new to Newmark versus promoting from within in terms of keeping that robust culture and the tightness intact?
Barry Gosin
We're basically evaluating all those things at the moment. Certainly by 60 days, choice will be made.
Alexander Goldfarb
Okay. The next question is on the data center front, continues to be a hot topic.
As you guys speak with your clients and we've seen more pushback politically across the country, how is this tangibly manifesting into deal flow? Are you seeing projects being pulled or is this more about future deals that aren't even near coming to fruition being pulled back?
I'm just trying to understand the practical implication on the field versus what all the headlines are.
Barry Gosin
The fact that the election is next week has some impact on what's happening. The NIMBYism that is occurring around the country, I believe will be temporary.
Whether it's community development agreements, data centers, deploying additional power to the grid in local communities, creating more jobs. Things are just being pushed.
Our pipeline is incredibly robust. The pipeline is there.
The macro environment is a little confusing, we're just being conservative about what the certainty is. Nobody's walked from the table.
They've just moved the table.
Alexander Goldfarb
Then finally, Mike, on the free cash flow, you talked about broker loans, I think, or something of that sort. Can you just walk back through ex-settlement why the adjusted free cash flow declined in the third quarter year
Mike Rispoli
over year? In the third quarter alone, if you remember last year, we had the settlement, which is about $42 million that was a positive impact last year.
Right. We're down about 10% if you take that out, and that's really just timing.
There's nothing specific going on. On a trailing 12-month basis, we're up almost 36% free cash flow, and we always look at that metric on an annual basis.
There'll be quarters where it might be down a little or might be up a little, but when you look at it on a trailing 12 basis, it's performing better than our earnings performance.
Alexander Goldfarb
Okay. Thank you, Mike.
Thank you, Barry.
Operator
Our next question will come from Jade Rahmani with KBW.
Jade Rahmani
Thank you very much. Just wanted to ask about the 2027 comments.
What scenarios would push earnings to be down 10%? Because you got 40% of the business management services and about 30% leasing.
That's the preponderance of it, and capital markets could be down, you said, in the first half, but maybe it stabilizes and then grows in the second half. I guess are we in a much worse scenario that gets earnings to be down by that magnitude?
Mike Rispoli
Sure, Jade. It's all about the capital markets business, cuz as you rightfully noted, the management business, servicing business, that will continue to grow double digits.
The leasing business, we think will grow, it'll just grow at a little bit of a slower pace than this year. It's really all about capital markets.
A downside scenario would be a sustained interest rate, volatile environment, continued increase in the 10-year Treasuries and volatility in that rate that sustains through the balance of next year. That could drive capital markets down probably in the 20% to 30% range.
That's a downside scenario. An upside scenario is there's some pain in the first half of the year and things get better in the second half.
As fourth quarter is usually the largest capital markets quarter, if things improve in the second half of the year, we could perform towards the higher end of that range.
Jade Rahmani
Wow, down 20% to 30%, that seems quite stark when you look at office has gone through a multi-year cycle and fundamentals are improving. Industrial is seeing a secondary use case with data center storage of all the components and advanced manufacturing.
Retail doing quite well, hospitality as well. Multifamily seems to be the main challenge about 35% of the market.
I think your capital markets comments seem a bit severe.
Mike Rispoli
Again, we gave a pretty wide range cuz I think there's a pretty wide range of outcomes that could happen in the market. The base case is that things get better and we have a pretty good year next year.
Jade Rahmani
Great. Thanks so much for taking the questions.
Good luck to you, Barry. Hope to still be in touch with you.
Hope you feel better as well.
Operator
The next question will come from Julien Blouin with Goldman Sachs.
Julien Blouin
Thank you for taking my question. I wanted to go back to the capital markets comments.
I guess, what are you seeing on the ground so far in October that sort of maybe informs this view of sort of a wide range of potential outcomes, certainly to the downside? Are you seeing real signs of pause in activity levels?
Because I do feel like we've heard sort of differing takes across your peer set in terms of how much of an impact we should expect.
Lou Alvarado
Julien, this is Lou. Look, we've definitely saw deals taking longer to close.
I think when rates moved up another 50 basis points and the 10-year went up, it gives people either an opportunity to re-trade deals or to wonder whether they should go to the market. We do believe that and will continue to advise our clients that I think we're living in the rate level that it's going to be, and therefore this is as good a time as anything if you've been deferred in markets to go to the market.
Definitely the spike in rates has also had a spike on cap rates, right, which then also, on top of everything, the values go down. That's primarily where we're looking at.
We're looking at probably a little slower first and second quarter, depending on how the elections go and how the rates go, and then also, that continued pressure on cap rates and cuz everybody's looking now and even the lenders on, "Hey, what's the exit cap rate going to be if I make this loan?" , right?
Those are really what's driving a lot of the decision-making.
Julien Blouin
Thank you. That makes sense.
As we enter sort of a more choppy period potentially for capital markets, does that change at all how you're thinking about reinvesting into the business? If not, how should we think about the potential for decremental margins sort of on the way down if we do sort of hit more severe scenarios in capital markets?
Lou Alvarado
Look, I don't think it changes how we invest in the business. We've said that we're going to continue to invest in growing our managed services, which work hand in hand, frankly, with capital markets and leasing, right?
It's primarily about driving that cross-selling of the services that we provide and driving our platform matters. As we drive that business more, that margin improves significantly because we've spent a fair amount of money, there's some fixed costs related to that business that as we continue to grow the revenue will further enhance the margin.
Capital markets is not going away. It'll still be a driver and there'll still be a way of how we get in front of folks.
Leasing will continue to help drive the cross-selling of our managed service platform, whether it be facilities, lease admin, workplace, and so forth. I'm not really as concerned about that overall for the plan, and I'm not really worried that we're going to change our investment.
We're going to continue to invest. We're going to continue to grow the platform.
We're going to continue to grow globally. I think we're in a really good path, and sometimes these things create tremendous opportunities for us to invest and grow the business.
Julien Blouin
All right. Great.
Thank you, Lou. Feel better, Barry.
Barry Gosin
Thank you.
Operator
We'll take a question from Brendan Lynch with Barclays.
Annabelle Ayer
Hi. Thank you for taking the question.
This is Annabelle on for Brendan. Thank you for your commentary on leasing expectations for 2027.
How do you think about the contribution from different sub-sectors as availability in office and industrial start to tighten, but you start winning more data center leasing deals?
Lou Alvarado
I think we have been doing more data center leasing deals. I still think there's a lot of running room still for powered land and so forth.
As far as leasing, we've been driving our leasing and continues to grow, and that's also helped grow our managed services, right, the support that goes with it. The challenge for leasing, frankly, is going to be that the demand is still at the Class A level, and the vacancy rates at the Class A level are in the single digits across all the major markets.
It's really more of a, hey, where's the product that we can put people in? There's certainly a lot more investment going in and taking B buildings to A level so that they can become an attractive option for tenants.
That's really where we see the potential slowdown, not slowdown, but just bump in leasing and why we think it won't grow as fast as has in the past.
Annabelle Ayer
Great. Then can you just quantify how much data centers contributed to the leasing volume in the third quarter given that they can be a bit lumpy?
Lou Alvarado
We had some nice data center leases in the quarter that part of the business for us seems to be ramping up, but we haven't put any specific numbers around it at this point.
Annabelle Ayer
Great. Thank you.
Operator
The next question will come from Patrick O'Shaughnessy with Raymond James.
Patrick O'Shaughnessy
Hey, good morning. How would you compare kind of the current market impact from the move higher in interest rates versus what the industry saw in 2022?
Barry Gosin
I think in 2022, everybody was saying stay alive till '25, right? I think today we're looking at a market where this is what it's going to be.
Again, they'll move 50 basis points here and there, but unless you have a really well-leased building that's got long term and you want to hold, I think everybody's going to have to play in this arena. It's just getting the price discovery between where the sellers and the buyers are to kind of meet, right?
It's very different than it was in '23.
Patrick O'Shaughnessy
Got it. That's helpful.
Thank you. Then can you remind us why the capital allocation philosophy has kind of shifted away from hiring and lift-outs and towards M&A?
Mike Rispoli
Sure. We probably started talking about this 18 to 24 months ago.
The main reason is we spent a lot of time building out our US platform in particular and filling a lot of the major gaps that we had on the capital markets side. When we got to the end of that, and we're never completely done, but when we got towards the end of that and we had enough talent to execute business in all major asset classes, we shifted more towards M&A.
M&A mainly has been in the recurring revenue businesses. As we mentioned, we've acquired six companies in the past almost year, and all of them, I believe, have been in the management and servicing business.
That shift started. It doesn't mean we're not hiring talent.
It just means that the majority of our capital will go towards M&A and the recurring businesses.
Patrick O'Shaughnessy
All right. Thank you very much.
Operator
Once again, if you would like to signal with questions, please press star one. Again, that is star one for questions.
Our next question comes from Mitch Germain with Citizens Bank.
Mitch Germain
Thank you, guys. I'm curious.
I think, Mike, you might have mentioned the GSEs seeing a reduction there. Do you expect a bit of a pickup in 4Q?
I know that there's certain levels that they have each year, I'm curious how you think that plays out.
Mike Rispoli
We're not seeing that. It's interesting, if you look at our volumes in multifamily debt in particular, our volumes overall were up.
It's just that the activity shifted from GSE to non-GSE debt. I don't really see the GSEs getting to their caps this year, and the market seems to continue to be a little bit down in the fourth quarter.
We'll see what happens next year. I know they have a mandate to push more volumes through the GSEs, hopefully that'll pick up as we move into '27.
Mitch Germain
Great. Obviously, you've got this dynamic playing out within the investment sales market, given what's happening in the interest rate environment.
I'm curious when you look at some of the M&A deals that you guys are in the midst of negotiating, does this sort of backdrop create an opportunity or does it create a repricing and maybe delay deals there as well?
Barry Gosin
We are incredibly ensconced in large institutional size portfolios, M&A, and the deals. That's probably one of the reason some of those deals just take longer.
Then in a volatile time, they continue to go forward. That side of the business is a little lumpy, but it's hard exactly to predict when they close.
Nothing has left the field.
Mitch Germain
Thank you.
Operator
Thank you. That does conclude the question-and-answer session.
I'll now turn the conference back over to Barry Gosin, CEO. I
Barry Gosin
thank you for joining us, and I really look forward to seeing all of you next quarter.
Operator
Thank you. That does conclude today's conference.
We do thank you for your participation and have an excellent day.