NWPX Infrastructure, Inc.
Q3 FY2026 · Earnings Call TranscriptOctober 29, 2026
Operator
Greetings. Welcome to the NWPX Infrastructure's third quarter 2026 earnings call.
At this time, all participants are in a listen-only mode. A question-and-answer session will follow the formal presentation.
If anyone should require operator assistance during the conference, please press star zero on your telephone keypad. Please note this conference is being recorded.
I will now turn the conference over to Scott Montross, President and CEO. Thank you Scott, you may begin.
Scott Montross
Good morning, and welcome to NWPX Infrastructure's third quarter 2026 conference call. My name is Scott Montross, and I am President and CEO of the company.
I am joined today by Aaron Wilkins, our Chief Financial Officer. By now, all of you should have access to our earnings press release, which was issued yesterday, October 28th at approximately 4:00 p.m.
Eastern Time. This call is being webcast, and it is available for replay.
As we begin, I would like to remind everyone that statements made on this call regarding our expectations for the future are forward-looking statements, and actual results could differ materially. Please refer to our most recent Form 10-K for the year ended December 31st, 2025 and our other SEC filings for discussion of such risk factors that could cause actual results to differ materially from expectations.
We undertake no obligation to update any forward-looking statements. Thank you all for joining us today.
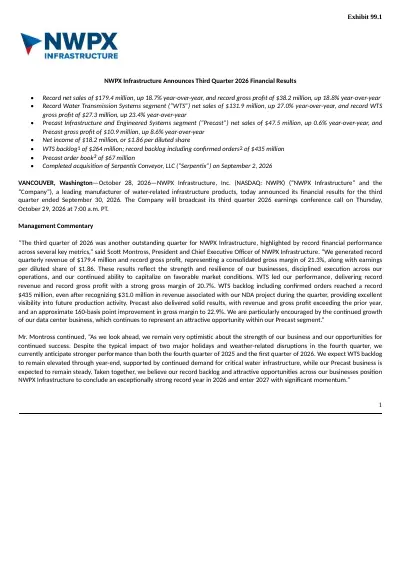
I'll begin with a review of our third quarter performance and our outlook for the fourth quarter of 2026, and then Aaron will walk you through our financials in more detail. Third quarter marked another outstanding quarter for NWPX Infrastructure as we delivered record financial performance across several key metrics.
Net sales were up 18.7% year-over-year to a record $179.4 million, primarily driven by strength in our Water Transmission Systems business. Consolidated gross profit totaled a record $38.2 million, up 18.8% from last year, with our gross margin at 21.3%, consistent with the prior year.
Strong execution across the business drove significant year-over-year earnings growth, with net income increasing 35% to $18.2 million or $1.86 per diluted share. We also generated $20.4 million of free cash flow during the quarter, further strengthening our financial position.
These results reflect the strength and resilience of our business, disciplined execution across our operations, and our continued ability to capitalize on favorable market conditions. Turning to our WTS segment: revenue reached a quarterly record of $131.9 million, up 27% year-over-year, with strong margin performance.
Our performance reflected higher production volume, with tons produced up 7%, supported by strong project execution and favorable project timing. Additionally, selling prices per ton were up 19% year-over-year, driven by changes in product mix.
Steel lead times have remained extended during the quarter, but have begun to moderate. Importantly, our longstanding relationships with domestic mills continue to support reliable access to steel and our ability to serve our customers.
Additionally, the significant NDA project we have discussed throughout the year was a meaningful contributor during the third quarter, generating approximately $31 million of revenue. We expect the project to make additional contributions in the fourth quarter and possibly into 2027 as well.
We had another exceptionally strong booking quarter, with robust bidding activity sustaining continued healthy backlog and reinforcing demand strength across our markets. The WTS backlog, including confirmed orders, ended the quarter at a record $435 million, up from $423 million at June 30th and well above the $301 million level we reported last year at this time.
Importantly, backlog continued to grow as we worked through a meaningful portion of the NDA project, demonstrating the strength of the broader demand environment. This is a good indication of how strong the bidding was in the third quarter and continues to be in the fourth quarter.
Our record backlog provides excellent visibility into future production activity and reflects continued demand for critical water infrastructure. WTS gross profit increased 23.4% year-over-year to a record $27.3 million, resulting in a strong gross margin of 20.7%, compared to 21.3% last year.
This performance reflects higher volumes and strong execution, which continue to drive operating efficiencies across the business. Gross margin was modestly below the prior year, primarily related to project production mix.
That said, year-to-date, WTS gross margin was approximately 180 basis points above prior year period, underscoring the continued strength of the business. Now turning to our Precast segment: Precast revenue slightly increased .6% year-over-year to $47.5 million.
Our performance reflected a 4% decrease in volume shipped. However, selling prices were up 3% over last year, primarily reflecting favorable changes in product mix.
Precast gross margin improved 160 basis points versus the prior year period. Approximately $1 million of revenue contribution came from Serpentech, reflecting only a partial final month of the third quarter contribution from the September acquisition.
While residential construction remains muted and we have seen some softening in portions of the non-residential market, our ability to serve a diverse range of applications continues to help us navigate these conditions. We are particularly encouraged by the continued growth of our data center business.
Through the third quarter, we quoted $33.5 million of data center project, booked in excess of $11 million worth of data center orders, and we are currently working on turning several additional large data center projects into new orders. While still a relatively small part of our overall business, it represents a growing source of opportunity, and we continue to approach the vertical selectively while maintaining our focus on our traditional precast markets.
Our quarter-end Precast order book totaled $67 million, which includes $10 million related to Serpentech. The legacy Precast order book of $57 million is down from $61 million at June 30th and above the $55 million level at September 30th of last year, positioning the business well as we close out the year.
While demand in the order book remains solid, some customer delayed shipments during the quarter amid continued uncertainty around interest rates, fuel costs, and the broader economic environment. This contributed to Precast revenue coming in somewhat below our expectations, but did not meaningfully change our view of the longer-term demand environment.
The resilience of the Precast business was particularly evident in this quarter. Despite the softer residential activity and some pressure within the non-residential construction, Precast revenue remained above the prior year as we continued to pivot between residential, traditional non-residential, and emerging opportunities such as data centers.
Looking ahead at the broader market, non-residential construction indicators remain mixed, but continue to point toward areas of opportunities. The Dodge Momentum Index was up 3.7% year-over-year in September, with the commercial sector down 3% and the institutional sector up 17.2%.
While near-term activity continues to be influenced by interest rates and broader macroeconomic uncertainty, the continued strength in institutional planning supports opportunities across portions of the non-residential construction market as we move into 2027. In addition, during the quarter, we completed the acquisition of Serpentech Conveyor, a manufacturer of engineered conveyor systems used primarily in municipal wastewater treatment plants and industrial manufacturing facilities.
The acquisition expands our participation in the wastewater treatment market and adds specialized engineered conveyance capabilities that fit naturally alongside NWPX Park's existing dewatering, separation, and mixing capabilities. Together, these businesses strengthen the wastewater platform we have been developing and broaden the solutions we can provide to municipal and industrial customers.
Integration is progressing well, with the existing Serpentech management team remaining in place and helping lead the process. We see attractive long-term growth potential in the wastewater market and believe Serpentech provides us with an additional platform from which to pursue opportunities across essential water and wastewater platforms.
With two acquisitions completed this year, our immediate priority is executing a successful integration and ensuring we fully capture the strategic benefits of both businesses. At the same time, we continue to evaluate attractive acquisition opportunities that can expand our geographic reach, enhance our manufacturing capabilities, and broaden our product offering.
Further, we are continuing to advance our Precast product spread strategy across the network, broadening our capabilities and increasing our capacity utilization. Through September of this year, we have quoted $58.3 million worth of projects, and we have booked $9.7 million of product spread orders, exceeding total bookings for the full year of 2025.
Precast gross profit of $10.9 million was up 8.6%. Gross margin improved approximately 160 basis points to 22.9% from 21.3% last year, primarily reflecting favorable changes in product mix.
The margin improvement is especially encouraging given the lower volumes of customer-driven shipment delays as we experienced during the quarter and reflects our continued focus on pricing, cost management, and operating efficiency. I'll now turn to our outlook for the fourth quarter.
On a consolidated basis, we currently anticipate stronger performance than both the fourth quarter of 2025 and the first quarter of 2026, which is particularly notable given the typical fourth quarter seasonality associated with fewer shipping days, holiday shutdowns, and potential weather-related disruptions. The strength of our backlog and the opportunities across our businesses give us confidence in our outlook as we close out the year.
In our Water Transmission Systems segment, we expect WTS backlog to remain elevated through year-end, supported by continued demand for critical water infrastructure. Our record $435 million backlog, including confirmed orders, provides excellent visibility into future production activity.
In addition, elevated bidding levels that have continued into October are providing great visibility into near-term financial performance. Based on what we are seeing today, we expect full year base bidding levels, not including the NDA project, to be stronger than what we saw in 2025.
We also expect additional contribution from the previously discussed NDA project during the fourth quarter. More broadly, the strength of the underlying WTS business gives us confidence that 2026 would have been a record year even without the benefit of this unique project.
Through the first nine months of 2026, without the contribution from the NDA project, WTS revenue would have been approximately 10% higher than the same period of 2025. The pipeline of current and upcoming water transmission projects remains strong, with attractive economics and margins supporting our outlook.
For a more complete view of these projects, please refer to our investor presentation on our website. Turning to Precast: we expect our Precast business to remain steady in the fourth quarter, supported by a solid order book and continued customer activity.
We continue to expect 2026 to be a record year for Precast revenue. While residential constructions remains muted and we are seeing some softness in portions of the non-residential market, we continue to benefit from the diversity of our product portfolio and end-market exposure.
In particular, data centers continue to provide an attractive source of incremental opportunity, helping offset softness in other areas of the business. Looking beyond the fourth quarter, the addition of Serpentech further broadens our capabilities and provides another avenue for growth across wastewater infrastructure and engineered solutions.
In closing, we delivered another outstanding third quarter, setting new records for revenue and gross profit while generating earnings of $1.86 per diluted share. WTS continues to perform at an exceptional level, supported by record backlog and continued demand for critical water infrastructure, while Precast delivered year-over-year growth and strong margin improvement.
With our expanded capabilities, record backlog, and attractive opportunities across our businesses, we believe NWPX Infrastructure is exceptionally well-positioned to finish 2026 on a strong note and carry that momentum into 2027. Equally important, none of these results would be possible without our people.
Our total recordable incident rate at the end of the third quarter stood at 0.8, reflecting the stability of our manufacturing environment and the continued commitment of our employees to execute our strategy safely. I want to thank our teams across the organization for their continued execution, their commitment to our strategy, and to maintaining a strong safety culture.
As we look ahead, our near-term priorities remain: one, maintaining a safe and rewarding workplace; two, focusing on margin over volume; three, intensifying our pursuit of strategic acquisitions; four, implementing cost efficiencies across the organization; and five, returning value to shareholders when M&A opportunities are limited. I will now turn the call over to Aaron, who will walk through our financials in greater detail.
Aaron Wilkins
Thank you Scott, and good morning to everyone joining the call today. Before we begin, I'd like to mention that unless otherwise stated, all financial measures in my remarks refer to the third quarter of 2026, and all comparisons will be year-over-year comparisons versus the third quarter of 2025.
I'll begin with our profitability. We delivered consolidated net income of $18.2 million in the third quarter, or $1.86 per diluted share, up 35% from $13.5 million or $1.38 per diluted share, reflecting the benefits of higher operating leverage on record revenue and disciplined execution across the business.
This is the highest quarterly earnings per share posted in the company's history, excluding the third quarter of 2018, which included a one-time $21 million non-cash bargain purchase gain associated with the Ameron Water Group acquisition. The result demonstrates the earnings power of the business as record revenue translated into a 27.7% increase in operating income.
On the top line, consolidated net sales grew 18.7% to a record $179.4 million, compared to $151.1 million in the third quarter of 2025. Our Water Transmission Systems segment also delivered record net sales of $131.9 million, an increase of 27% from $103.9 million.
This growth was driven by a 19% increase in selling price per ton due to changes in product mix, and a 7% increase in tons produced resulting from project timing. Precast net sales increased 0.6% to $47.5 million from $47.2 million.
The results reflected a 3% increase in selling prices, primarily due to product mix, which was partially offset by a 4% decrease in volume shipped. Third quarter results also included $2.1 million contribution from the recently acquired businesses, Boulton and Serpentech, which were not included in the year-ago quarter.
As a reminder, the products we manufacture are unique, and the average sales prices for both of our operating segments, as well as the Precast shipment volumes and WTS production volumes, cannot be relied upon as comparable metrics due to variations in product mix between periods. We also achieved record consolidated gross profit of $38.2 million, up 18.8%.
Consolidated gross margin remained consistent year-over-year at 21.3%. In Water Transmission Systems, gross profit increased 23.4% to a record $27.3 million, or 20.7% of segment sales, compared with $22.1 million or 21.3% of segment sales.
WTS gross margin declined 60 basis points year-over-year, reflecting a change in production mix between periods. Precast gross profit increased 8.6% to $10.9 million, or 22.9% of segment sales, compared with $10 million or 21.3% of segment sales.
The 160 basis point margin improvement primarily reflected stronger margin performance within the non-residential portion of the business. Third quarter segment sales also included $0.4 million of gross profit from recently acquired businesses, with no comparable contribution in the year-ago quarter.
Selling, general, and administrative expenses were $13.9 million, up 5.8% from $13.1 million, and represented 7.7% of net sales, a 100 basis point improvement from 8.7% of net sales a year ago. For the full year 2026, we now expect consolidated SG&A to range between $55 and $56 million.
Depreciation and amortization expense was $6.3 million, compared to $5.2 million, and we now expect full year depreciation expense to be between $22 and $23 million, which includes the amortization of acquired intangible assets obtained in the acquisition of Serpentech. Interest expense declined to $0.4 million from $0.8 million, reflecting lower average daily borrowings.
Income tax expense was $5.7 million, resulting in an effective income tax rate of 23.9%, compared to $4.7 million or 26% last year. The effective rate in the quarter was primarily impacted by non-deductible permanent differences, partially offset by return-to-provision adjustments.
For the full year, we now expect an effective tax rate of approximately 23% to 24%. I'll now turn to our financial condition.
At September 30th, 2026, cash and cash equivalents were $6.1 million, up from $2.3 million in December 31, 2025. Total debt was $27.7 million, including $18.5 million outstanding under the revolving line of credit.
At quarter-end, we had approximately $105 million of additional borrowing capacity under our credit facility. Following the completion of the Serpentech acquisition in September, our balance sheet remains well-positioned to support organic growth, disciplined M&A, and capital returns to shareholders.
Strong profitability and effective working capital management drove net cash provided by operating activities of $27.4 million during the quarter, compared to $21 million last year, bringing year-to-date operating cash flow to $71.1 million. The year-over-year increase in quarter primarily reflected a $5.6 million increase in net income adjusted for non-cash items.
In addition, changes in working capital contributed $0.9 million to the increase, demonstrating strong working capital efficiency when considered with the 18.7% year-over-year increase in quarterly revenues. During the quarter, we deployed capital across several key priorities, including: $49.7 million to complete the acquisition of Serpentech, $7 million in capital expenditures, and $1.2 million in share repurchases.
These investments demonstrate our ability to fund growth while continuing to return capital to shareholders. For the full year 2026, we now expect capital expenditures in the $21 to $23 million range, including approximately $6 million for investment in projects to support our Precast product spread strategy and broader growth initiatives.
Finally, we generated $20.4 million of free cash flow during the quarter, compared to $13.2 million last year, bringing free cash flow for the first nine months of 2026 to $56 million. We now expect free cash flow for the full year 2026 to be in the range of $62 to $72 million.
To close, the third quarter marked another period of strong execution, highlighted by multiple company records, including consolidated revenue and gross profit, WTS revenue and gross profit, and earnings per share. Our record Water Transmission Systems backlog, including confirmed orders, provides strong visibility, while our solid cash generation and ample borrowing capacity preserve flexibility to invest in growth and return capital to shareholders.
Thank you to our employees for their continuing to prioritize safety and commercial and operational excellence, and to our shareholders for their continued support. I will now turn it over to the operator to begin the question-and-answer session.
Operator
Thank you. We will now be conducting a question-and-answer session.
If you would like to ask a question, please press star one on your telephone keypad. A confirmation tone will indicate your line is in the question queue.
You may press star two if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys.
One moment, please, while we poll for questions. Our first question is from Julio Romero with Sidoti & Co.
Please proceed with your question. ):
Julio Romero
Thanks. Hey, good morning Scott and Aaron.
Scott Montross
Hey, Julio.
Aaron Wilkins
Morning, Julio. ):
Julio Romero
Hey, good morning. I wanted to start on the Precast segment.
You mentioned quoting $33.5 million of data center projects and booking over $11 million year-to-date, I believe. Can you expand on that, and how much has shipped versus is in the order book, what the quoting pipeline looks like heading into '27, and how the margin profile of those data center projects and orders compares with traditional precast work?
Scott Montross
I'll say the margin profile on those is generally higher than what we see on normal precast orders, I think simply because of the speed at which they expect these things to be done. Shipment-wise, and this is I'm going to guess in round numbers, we probably shipped about $7 million of that at this point in this year, but we have a bunch of it still in front of us that we're trying to turn into orders at this point, and there's some relatively large ones that are still going on.
We have the expectations that as we get through the rest of this year, the quoting level is going to go up, the booking level is going to go up, and the shipping levels are going to continue to follow that. Again, this is something that's kind of an ancillary part of our business.
I'm more focused on the precast business at both Park and Geneva, but we've been starting to get to be spec'd in with some of these data center businesses on some of the products that we're providing. As long as we can continue to get those and take advantage of those items, I think we're going to continue to do that.
I think that it's no secret that the residential business has been down a little bit, and even when you look at the momentum index, the non-residential business is only up slightly, and that's really institutionally driven. The commercial side is down about 3% year-over-year, I think 12 months.
It'd be down a whole lot more if it wasn't for data centers. We're filling in the gaps with data centers orders, and the other thing I think that's happened that's a pretty good thing that the people have done at Geneva, generally the Geneva facilities have been about 85% residential business.
This year they're about 40% residential business, and the rest is being filled in by non-residential business and data center orders. We're filling in the gaps with those based on what the environment is for precast.
Obviously, interest rates affect that, fuel costs affect that, but we've been able to pretty effectively fill things in with being able to pivot from one market segment, residential, non-residential, and the data centers, to another. It's worked out really well for our precast business.
):
Julio Romero
Excellent, great color there. Then for my follow-up, I wanted to ask about Serpentech a bit, if you could speak to it a little bit and how it complements Boulton's in Colorado, which I think is about 2 hours away, I believe.
How it complements the broader Precast segment and then, secondly, I believe, based on the cash flow statement, that roughly $50 million in cash used for that acquisition. Was hoping you could also speak to maybe the margin profile and what it's expected to contribute in '27 and beyond.
Thank you.
Scott Montross
You've asked a few questions there, Julio, you may have to remind me which ones you've asked. The margin profile on that business is what I would say significantly greater than what we see on the precast side.
That business is a wastewater business that's a wastewater conveyance business. We already have a wastewater business at Park USA, and the majority of the wastewater business we have at Park USA is directed toward really private applications like large grease traps and things of that nature.
This is directed more toward the municipal side. At Park, we also have a business that's called Park Process that does dewatering, mixing, separation in the wastewater market, specifically in the biosolids and sludge section.
The Serpentech business having the conveyance piece and really a conveyor that is different than with a lot of the competitors because it's a vertical, horizontal, and helical. It's a big space saver.
That's one thing. Really the Serpentech business is directly adjacent to the Park Process business.
That kind of fits together and gives us greater access to more products in the wastewater side of the business. We think it's going to be a pretty solid potential platform for growth going forward, and we're excited about it.
I think the one thing [cough] that we're seeing in the wastewater side, especially in the sludge and biosolids, which is what we're focused on right now, is the amount of potential targets out there for M&A are pretty substantial. It kind of reminds me of the targets that we had when we first got into the precast business, which are obviously have gotten to be quite a bit less.
I think we're pretty excited about the ability to grow. We're excited about the margin profile with being as high as it is because it's quite a bit higher than what we see on the normal precast side, and I think it's a great opportunity for another platform to grow along the precast side of the business.
It's a pretty exciting acquisition. ):
Julio Romero
Absolutely, very fascinating. I'm looking forward to hearing more about it in the future.
I'll pass it on. Thanks very much.
Scott Montross
Thanks, Julio.
Operator
Our next question is from Tomo Sano with J.P. Morgan.
Please proceed with your question.
Good morning, this is Ethan On for Tomo.
Scott Montross
Hello. Hey, Ethan.
Kind of start the .8 TRIR congrats on that. That I believe if that holds out, that's six six year six or more years of declines annually.
Congrats.
Scott Montross
Thank you.
To go off of the previous comments a little bit, Geneva, you mentioned was roughly 40% residential now, if I'm remembering correctly, last quarter you mentioned it was roughly 50/50. If you could talk a little bit more on kind of what you're seeing on both kind of the residential as well as the non-residential business on an end-market basis.
Scott Montross
I think the residential side as we've talked about is slower simply because of the interest rates. As a result, we've continued to fill in our production schedules in our order book with non-residential to replace that slowness.
That's worked out very, very well for us, and we expect that to probably continue for a while, Ethan, especially with the interest rates being what they are. The idea is that when residential comes back, then ultimately, you'll be adding that on top of the growth that we've seen on the non-residential side, ultimately getting to much larger shipping numbers than we've seen in the past out of the Geneva facilities.
What was the other part of the question, Ethan?
On the commercial side, what you're seeing, I believe if you mentioned -3% year-over-year right now year-to-date and excluding data centers that's more where and I believe you also mentioned earlier in the call that you're seeing some pockets of softness. If you could clarify a little bit more.
Scott Montross
That's really on the residential side, and non-residential seeing a little bit of pockets of softness on the commercial side. On the institutional side [clears throat], the institutional side is actually up about 12 or 13% versus where it was last year.
We've also started spinning into more institutional stuff like hospitals and schools. The amount of that stuff that we're doing right now has grown, replacing some of the softness that we've seen on the residential side.
Yep,
thank you. Then on the Precast side as well, you mentioned on the data centers and you clarified on that side, when we're thinking about going into next year, you mentioned on project sizes.
How much larger could these project sizes be than kind of the historical comping to maybe historical commercial or institutional side?
Scott Montross
On data centers specifically?
On data centers specifically.
Scott Montross
I would say that [clears throat] a lot of data centers bidding that we've done, we've seen projects that are $300,000, $400,000, but more recently, we've seen projects that are out there and in front of us that we're working on trying to convert into orders and get the orders that are as big as $3 and $5 million. As far as how large it could be in 2017 We're just working through our 2017 plan now, but as long as the data center business continues to drive forward, I think that it's a good indicator that it's going to continue to grow.
Right now, just in the state of Texas, there's 49 data centers that are under construction, and there's another 114 that are planned, and 72 of those are in the pre-construction phase. Obviously, there's been a little bit of slowdown with political issues related to those, but we're still seeing a lot of those in front of us, and expect that with all of this stuff coming through that next year could be even larger than this year on the data center side of the business, adding to the total potential of our Precast revenue for the year.
Thank you. I'll hop back in the queue now.
Operator
Our next question is from Ted Jackson with Northland Securities. Once again, if you would like to ask a question, please press star one on your telephone keypad.
Ted, please proceed with your question.
Ted Jackson
Thanks, I'm going to say I have a box full of questions. I'm just going to ask a few of them and then get out of queue [laughter] before anyone else jumps back in.
Scott Montross
[laughter]
Ted Jackson
I just want to make sure I don't end the call. I want to make sure I can come back in if there's no one behind me.
All right, [sigh] so I want to start out with the NDA opportunity. When you announced that, it was a $50 million opportunity that was going to ship this quarter.
You popped $39 million of revenue in the last two quarters. If you were to finish it this quarter, that would say let's call it $11 million in the fourth quarter.
You clearly expect to get some revenue out of that and you're expecting to see some revenue in 2027. I guess the question is is it $50 million and some of that remaining $11 million is bleeding into '27, or is it we should still see, call it $11 million, call it $10, whatever you will, and the size of that opportunity may be scaled out a little bit?
Scott Montross
I would say that the total project value of the NDA project was right around $56 million. Far, let's call it $40 million we've done so far through the second and third quarter of the year.
In the fourth quarter, we expect to get some of that $16 million, but it's how fast the contractor can actually take it. Some of that may bleed into the beginning of 2017.
As far as what happens after that with the NDA projects, there's been rumors out there that there's additional ones that are out into the future, but we have not seen anything on any of that yet, and we're just focused on getting this one done and moving on and continuing to get more orders on the water transmission side.
Ted Jackson
That was my follow-up question was, any color on the opportunities in the future. [laughter] They're still out there, just there's been no movement though.
Scott Montross
Yeah, [cough] I think there's stuff that's out there. I think a lot of it's going to depend on the administration and what their stance on those things are.
I would say, even if you pull the data center work out and look at where we are through the first nine months of this year, we're 10 or 12% ahead of where we were last year, which had no NDA work in it. It bodes well, and I think the bigger thing is when you look at what's going on in WTS, Ted, the momentum in that business is tremendous because coming through the third quarter, we converted about $144 million worth of work into backlog.
The third quarter was the biggest bidding quarter of the year, but the second biggest bidding quarter of the year for water transmission is the fourth quarter. The fourth quarter continues to be on a pretty breakneck pace for bidding on the water transmission side.
I think I can safely say that I've never seen this much momentum on the Water Transmission Systems business heading through the fourth quarter and into next year. There's a tremendous amount of momentum in that business.
We're pretty excited about how that looks. Would you,
Ted Jackson
with this NDA project, let's just keep it at $50 million for the year for conversation's sake, if it was kind of a pig in the python for the year, but at the end of the day, you have these facilities that can produce and you have this huge backlog, and I know you're not giving '27 guidance, but if we don't get a follow-on for NDA, I think most people are expecting to see a decline in WTS revenue, just because you're going to have that gap, but is there the possibility that you would backfill that revenue hole with the strong backlog you have and you can keep your WTS, well, let's talk about it on a volume basis, keep it at least flat in '27?
Scott Montross
A lot of it's going to depend on how the bidding goes in the fourth quarter because we expect that to be relatively large in the fourth quarter. Some of it will have the steel pricing will have an impact on what those revenue numbers look like.
Again, as you said it, we're not giving guidance for what we're seeing in 2027. We are currently this week, I've met with both groups, the Water Transmission Systems group and the Precast group, about expectations for the 2027 timeframe.
I would say that the bidding in 2027 is going to remain very strong, and we're going to carry an order book into 2027 where [laughter] we have most of this stuff for 2027 already in backlog, and all we can do is continue to grow that potential with booking more orders. I'm not going to say that we're going to fill all this in at this point, but I think the strength of the business is going to be substantial as we go through 2027, and we're just going to have to see how the variables play out as we go through the year.
We're going to finish a very, very strong year just without the NDA project for Water Transmission Systems, but the question of whether we can fill that in, that's a tall order, not completely impossible, but we're just going to have to see how the variables play out. But 2027's going to be from all views at this point in time, it looks like it's going to be another really strong year on the water transmission side.
Ted Jackson
Okay. I got a question probably more for Aaron, I don't want to leave him out of all the fun.
[laughter] On the balance sheet, Aaron, you had a good jump up in the contract liabilities and assets, which is a good thing because it simply just means you're getting pre-paid for work and it's includes your free cash flow. As we think about that on a go-forward basis, at some point, it has to flip itself around, I would think.
Can you talk a little bit about how we should think about those line items as we kind of maybe march through the, really really probably more '27 or you get where I'm going with this,
Aaron Wilkins
just
Ted Jackson
think about it really from a free cash flow perspective and how that's just flowed through over, I don't know, the next 12 or 18 months.
Aaron Wilkins
Sure. If I'm going to be honest, we have pre-billed the WTS business significantly better than we even expected to, and we had a pretty aggressive plan as we set the year.
That is something that I do just kind of naturally think will kind of moderate a little bit. We currently have a cash conversion cycle for that business that's around 99 days.
To put in perspective, a year ago, for which I thought we were pretty strong on the pre-bills and really kind of driving those contract liabilities through, we were at 150 days. I don't think that 99 days is sustainable long term, but it will kind of depend on the types of projects that we have in front of us, who those are with, and the size of the contracts that we see bidding in 2027.
All in all, Ted, I think the thing that I'm I think proud of, regardless of whether we can kind of keep this pace, I feel like we have fundamentally changed the way that we think about cash flows for that business, and we have made extremely good progress on and prioritizing that. I don't think that sentiment is going to change at all.
We still have that kind of now ingrained, I think, in that business, that we talk about it every single week during staff meetings, and the commercial team is highly conscious of the fact that this is part of everybody's compensation as far as our incentive compensation package, and they are really driving that. So [laughter] I'm certainly proud of the 99 days.
I don't want to promise anything about that like that again, but I think it'll be somewhere between the 150 and the 99 as we go forward.
Ted Jackson
Kind of taking all that and putting it into base terms, it's not like there's a pig in the python and we would expect to see that kind of reverse itself out. It might just trend down to something a little more sustainable.
Aaron Wilkins
I think so, yeah. I think it just kind of moderates back a little bit, yep.
We're still focused on it, we're still trying to drive it, and like I say, they surprised me this year, never would have thought we would have got here. They may surprise me again next year, so.
Ted Jackson
I hope they do. I'm going to ask one more
Aaron Wilkins
I do
Ted Jackson
too. [laughter] That's for sure.
I'm going to step aside after this next question, and it's a simple one, can you give me a sense with regards to the amount of steel that was in the COGS line item for this quarter?
Aaron Wilkins
For this quarter, I believe it was right at around 28%.
Ted Jackson
I'm going to step out and see if anyone else has any questions. I might have a couple more if not.
Operator
Once again, if you would like to ask a question, please press star one on your telephone keypad. Our next question is from Ted Jackson with Northland Securities.
Please proceed with your question.
Ted Jackson
Great, it's good to be back. Couple more quick ones.
[laughter] So Scott, in the guidance when you talk about Precast, basically being steady in the fourth quarter, I don't have my model in front of me, but are you juxtaposing that against prior year or against third quarter?
Scott Montross
I think it's probably more against the third quarter is the way we're looking at it right now. It looks like it's pretty steady.
There's fits and starts in the Precast business right now, Ted, because of interest rates and fuel costs and stuff like that, but we continue to fill in with data center stuff, with moving from residential to non-residential, and that's worked out pretty well. You never can tell what's going to happen because obviously there's a lot in the air with what the administration's doing and things that are going on, but it still looks pretty strong to us, and it looks like it's going to be pretty strong into 2027, too.
I think we're in pretty good shape on the Precast side as we sit right now.
Ted Jackson
Okay. Then on that you said before that, with the current quarter, you had some delayed shipments in the quarter that had affected the revenue number.
Those are delays, they're not cancellations, so that's stuff that's kind of slipping into fourth quarter or maybe first quarter kind of thing?
Scott Montross
Right, I I would say, Ted, the the thing the statement I would make is that both with WTS and Precast, the fourth quarters are are really the fourth quarter's really validated by the orders that we have in hand right now for the first for the fourth quarter. It's it's not a it's the orders are in hand.
I think what you get with some of the delays that we've seen in Precast with with the interest rates and, like I said, fuel fuel charges and fuel costs, you get some a little bit of nervousness amongst the owners and the contractors, and it make them take pause for for a bit of time, and then it just seems to come back. I think we're I think we're we're in pretty good shape.
Then
Ted Jackson
my last question, it kind of ties in the steel and backlog. The simple fact is that the price of steel as we go forward in time just continues to elevate, and I know that's good for revenue and profitability for you.
When we think about the increases that you have had with WTS backlog, can you give us some kind of loose sense, I wouldn't expect you to be able to really take it down to the wire, but how much of that is volume-based as opposed to price-based, which I assume that higher steel cost is helping you on the dollar value of that backlog too? That's my last question, thanks.
Scott Montross
It does help a little bit, but we're looking at an average steel cost in backlog across all of 2026, right? Steel's risen to a different level as we're going into the fourth quarter, now we're at about $1,300 a ton as we go into the fourth quarter.
A lot of those projects that we bid were at lower steel prices. I would also say that the volume in backlog is higher than normal along with the project value because when you look at what's going on in the Water Transmission Systems business, our revenue per ton, if you will, is up about quarter-to-quarter, third quarter this year versus the third quarter of last year, the revenue's up 19% and the steel price is up 12%, okay?
Steel prices helped, but it's the revenue side, and a lot of that's being driven by higher volumes and the prices on these projects right now are pretty high. You really have to tear it down to its basic level, but we have really strong volume in backlog along with price.
Like I said, I think with that, we've got most of the stuff that we're going to be producing in 2027, we've got a lot of it in backlog already, and we expect to have even more of it in backlog as we get through the fourth quarter. It's a long way to answer the question, but our volume's up in backlog.
Ted Jackson
No, no, actually, I think that was really good for me. If I think about it, just going to put some words in your mouth so you can spit them out if you don't like it, but you're saying that you book revenue earlier in the year that you haven't recognized revenue on, and when you book that revenue, you're already locking in your steel prices.
Inside of that backlog, let's just say if I was to go back to say you had stuff in there still that's left over from bookings in the first quarter, that stuff could have been at $1,000 a ton, whereas stuff that you had in the third quarter is more like $1,200 a ton. You see where I'm going with this?
Hence, when I look at that, I need to understand, yeah. I just want to make sure.
So That's
Scott Montross
true.
Ted Jackson
Okay. All right, that's it for me.
Thanks and congrats on the quarter.
Scott Montross
Thanks, Ted. Ted.
Operator
We have reached the end of the question-and-answer session. I would like to turn the floor back over to Scott Montross for closing comments.
Scott Montross
Just a few comments before we wrap up today. Obviously, we had another very, very strong quarter, setting a lot of records and including revenue, gross profit, earnings per share.
Water transmission continues to be what I would say generating very strong momentum, and that business right now is booming, and we're hitting booking levels in this year that we've never seen before. Obviously, some of it is the NDA project, but a lot of it is just straight line Water Transmission Systems business.
We have really good visibility into the future. Again, even without the NDA project, we would be through nine months of this year, we'd be 10 or 12% ahead of where we were last year at the same time.
I think that that's a big deal. The other thing is, as I said before, we converted $144 million into our backlog into the third quarter.
In the fourth quarter is going to be another strong bidding quarter, the second biggest bidding quarter of the year, only second to the third quarter. We've got still strong bidding in front of us.
I think the Precast business continues to look to deliver strong results even with various softness in various areas, up 160 basis points versus where we were last year with an increasing margin, those things are all positive. The data centers continue to add to the Precast business, and we've advanced our long-term strategy with the acquisition of Serpentech, which fits right alongside our Park Process business at Park USA.
We're very excited about the opportunities for that. Looking ahead into the fourth quarter, we expect stronger performance than 2025 fourth quarter and stronger performance than the first quarter of 2026, despite some of the seasonal factors that we see with the two major holidays and always the weather-related things.
We're very positive about finishing the 2026 year at an all-time record level, and very excited about the amount of momentum that we're carrying into 2027. We will see you again in what is this Oh, not until February?
[laughter] We'll talk again in February or early March, whenever the next call is. I'd like to thank everybody for joining us, and be well.
Thank you.
Operator
This concludes today's teleconference. You may disconnect your lines at this time.
Thank you for your participation.