ODDITY Tech Ltd.
Q3 FY2026 · Earnings Call TranscriptNovember 11, 2026
Operator
Good morning, and welcome to ODDITY's Third Quarter 2026 Earnings Conference Call. Today's call is being recorded, and we have allocated time for prepared remarks and Q&A.
At this time, I'd like to turn the conference over to Maria Lycouris, Investor Relations for ODDITY. Thank you, you may begin.
Maria Lycouris
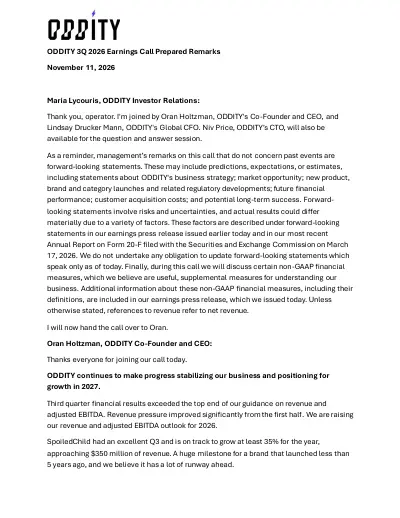
Thank you, operator. I'm joined by Oran Holtzman, ODDITY's Co-Founder and CEO, and Lindsay Drucker Mann, ODDITY's Global CFO.
Niv Price, ODDITY's CTO, will also be available for the question-and-answer session. As a reminder, management's remarks on this call that do not concern past events are forward-looking statements.
These may include predictions, expectations, or estimates, including statements about ODDITY's business strategy, market opportunity, new product, brand, and category launches and related regulatory developments, future financial performance, customer acquisition costs, and potential long-term success. Forward-looking statements involve risks and uncertainties, and actual results could differ materially due to a variety of factors.
These factors are described under forward-looking statements in our earnings press release issued earlier today, and in our most recent annual report on Form 20-F filed with the Securities and Exchange Commission on March 17th, 2026. We do not undertake any obligation to update forward-looking statements, which speak only as of today.
Finally, during this call, we will discuss certain non-GAAP financial measures, which we believe are useful, supplemental measures for understanding our business. Additional information about these non-GAAP financial measures, including their definitions, are included in our earnings press release, which we issued today.
Unless otherwise stated, references to revenue refer to net revenue. I will now hand the call over to Oran.
Oran Holtzman
Thanks, everyone, for joining our call today. ODDITY continues to make progress stabilizing our business and positioning for growth in 2027.
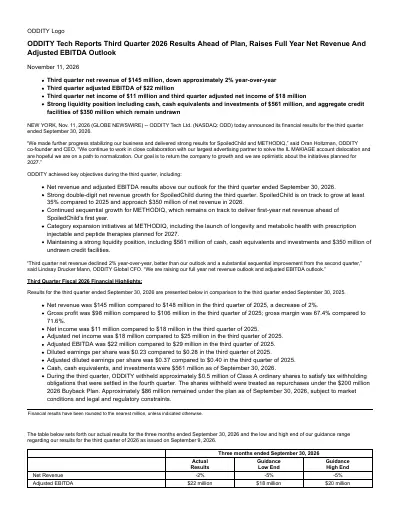
Third quarter financial results exceeded the top end of our guidance on revenue and adjusted EBITDA. Revenue pressure improved significantly from the first half.
We are raising our revenue and adjusted EBITDA outlook for 2026. SpoiledChild had an excellent Q3 and is on track to grow at least 35% for the year, approaching $350 million of revenue, a huge milestone for a brand that launched less than five years ago, and we believe it has a lot of runway ahead.
METHODIC is off to a strong start and is on track to beat SpoiledChild's first-year revenue. We have exciting expansion plans for 2027, including new products and categories that we believe can be meaningful growth drivers.
We made progress at IL MAKIAGE, and we remain hopeful that we are on path to normalization. Taking a step back, our long-term ambitions for ODDITY have not changed.
Our goal is to build one of the biggest beauty and wellness companies in the world. We have a strong foundation for it, starting with our direct relationship with 70 million users, which allows us to identify big demand opportunities and scale into them fast.
We have continued investing in growth drivers like ODDITY LABS, new brands, and technology, and we built out new muscles to expand our scope. In the past five years, we transformed from a single brand into three brands, and soon four, and from the beauty category we added skin care, hair care, and dermatology.
Next year, we plan to add longevity, metabolic health, and more we have not yet announced. Turning to our third quarter results.
Starting with SpoiledChild, which grew strong double digits in the third quarter and continued the trend into the fourth quarter. As I said, it is on track to grow at least 35% for the year.
The success of SpoiledChild is a proof point of the ODDITY platform. Countless other beauty companies tried and failed to add new brands organically, or scale into new categories without M&A.
We did it with SpoiledChild in less than five years, leveraging our user base, our technology, and our brand-scaling machine. It's a repeatable playbook that we believe gets better with time, and we are running it again with METHODIC, with Brand 4, and beyond.
More to come for SpoiledChild, with strong momentum exiting 2026, excellent repeat rates, and an exciting product lineup for 2027. Moving on to METHODIC, which is off to a strong start in its first year since launch.
Our success so far, including high customer satisfaction and retention rates, combined with powerful secular trends in the medical-grade space, makes us bullish on METHODIC's potential. Our plan is to expand into more medical-grade products and categories across 2027, where we see large addressable markets with meaningful demand.
As the first step into longevity and metabolic health, we plan to offer prescription injectable therapies, including NAD+, sermorelin, and others, prescribed by licensed providers and fulfilled through our US-based licensed pharmacy partners. From there, we plan to launch six additional peptide therapies covered by the enforcement discretion policy published by HHS last month.
We have been preparing for this opportunity for a long time. We spent the last several years building out our infrastructure, online clinical intake, transparent national pharmacy fulfillment, and licensed provider networks, and are now in a strong position to expand from here.
We believe the market potential for peptides and therapies across longevity, metabolic health, recovery, and cognition function is highly attractive, and METHODIC is well-positioned to win. With ODDITY's platform and financial muscle, METHODIC's success in dermatology Rx, and the provider networks, pharmacy infrastructure, and supply chain already in place, we believe we can build a leading offering.
This is just the beginning of METHODIC. More categories and products to come.
Moving to IL MAKIAGE, we continue to work extremely hard with our largest advertising partner to solve the algorithm dislocation. While we are not there yet, we remain very hopeful that due to the substantial resource this ad partner is allocating to fix it, combined with our 24/7 efforts, we will be successful.
Turning to ODDITY LABS. Three years ago, we founded our frontier biotech lab in Boston to bring capabilities like artificial intelligence and digital biology, the same tools that pharma uses for drug discovery, into beauty and wellness, and do it at high scale.
With hard work and investment, we've built a strong machine and a pipeline of proprietary molecules that we believe can deliver groundbreaking solutions for consumers. In anti-aging, we are working on molecules that increase collagen, elastin, and NAD+ in the skin.
We believe the early reads from in vitro and ex vivo testing and for focus groups are really promising. We also have projects in hair growth, and we continue to build on our success in hyperpigmentation, acne, and eczema.
Looking for the future, our focus is returning ODDITY to growth in 2027, including growth for IL MAKIAGE. The industry backdrop remains attractive, with large, profitable, and secularly growing markets that we believe are ripe for disruption.
We continue to be bullish on our strategic focus areas, including the consumer shift online and the demand for high-efficacy products. The success for both SpoiledChild and METHODIC shows the power of our platform, with three distinct brands today, each with the potential to achieve billion-dollar revenue.
On the product side, our slate of launches planned for 2027 across all brands is the most exciting we have ever had. Brand 4 is planned to be ready for launch in 2027, with more details on timing as we get closer.
Lastly, we continue to explore new distribution where it makes sense. I'll share more when it's relevant.
With that, I will hand it over to Lindsay.
Lindsay Drucker Mann
Thanks, Oran. Let's turn to our Q3 results, which I'll refer to on an adjusted basis.
You can find the full reconciliation to GAAP in our press release. Net revenue declined 2% versus the prior year to $145 million.
This is better than our outlook for net revenue to decline approximately 5%, and a substantial sequential improvement from the 25% net revenue decline we reported in the second quarter. The sequential improvement was driven in part by improved trend in repeat orders, which stabilized in the third quarter versus the prior year.
More than 80% of ODDITY net revenue in the third quarter was from repeat sales, representing a large majority of our revenue base in the period. First-order net revenue declined by approximately high teens year-over-year.
IL MAKIAGE first-order revenue declined sharply due to the ongoing impact of the ad account dislocation with its largest advertising partner. This was partially offset by increased first-order revenue at SpoiledChild and at METHODIC.
AOV declined approximately mid-single digits during the quarter. The AOV reduction was driven in part by mix.
SpoiledChild revenue increased strong double digits during the quarter versus the prior year. METHODIC revenue continues to build sequentially.
The brand is on track to beat SpoiledChild's first-year revenue performance. Gross margin was 67.4% in the quarter compared to 71.6% in the prior year.
The compression versus the prior year was driven in part by the decline in AOV. We delivered adjusted EBITDA of $22 million, ahead of our outlook for adjusted EBITDA of $18 to $20 million.
The decline versus the prior year was driven in part by the IL MAKIAGE account dislocation. We continue to be disciplined on operating expenses while maintaining investment in critical growth areas like ODDITY LABS, METHODIC, Brand 4, and our tech infrastructure.
We believe these growth investments will be drivers of value creation for us in the future. Moving down the P&L, adjusted diluted earnings per share was 37 cents for the quarter compared to 40 cents in the prior year, on a diluted share count approximately 23% lower year-over-year following our share repurchases.
Free cash flow was $10 million in the quarter, bringing free cash flow for the first nine months of the year to approximately $3 million. Inventory ended the quarter at $158 million.
As we discussed last quarter, IL MAKIAGE continues to work through excess inventory from purchase commitments made in anticipation of stronger revenue, and we plan to be in better inventory balance in 2027. We also continue to invest in inventory to support growth at SpoiledChild and at METHODIC.
We exited the quarter in a strong liquidity position with $561 million of cash, cash equivalents, and investments on our balance sheet. Our $350 million in credit facilities remains undrawn.
Turning to capital return, in the first nine months of the year, we repurchased 11.7 million shares for $163 million, which reduced our ordinary shares outstanding by approximately 20% year-to-date. Approximately $86 million remains outstanding on our $200 million buyback authorization.
Approximately $550 million of our zero-coupon 2030 exchangeable notes remain outstanding, following the $50 million of face value we repurchased in June. We'll continue to be opportunistic in managing our capital structure in order to drive shareholder value going forward.
Turning to our full-year outlook, we're raising our guidance for full-year net revenue and now expect a decline of approximately 18.5%, and we're raising our guidance for full-year adjusted EBITDA to be between $32 and $34 million. With that, I'll turn the call back to the operator for questions.
Operator
Thank you. We will now be conducting a question-and-answer session.
We ask that you please limit yourself to one question. If you would like to ask a question, please press *1 on your telephone keypad.
A confirmation tone will indicate your line is in the question queue. You may press *2 if you would like to remove your question from the queue.
For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. One moment please while we poll for questions.
Our first question is from Scott Schoenhaus with KeyBanc Capital Markets. Please proceed with your question.
Scott Schoenhaus
Hi, team, thanks for taking my questions. Oran, it sounds like you have a lot of opportunity and optimism around the new product launches that you mentioned in '27.
Maybe help us understand why you chose these products, where you see the opportunity, how you defined it within your current population, usually you see traction or able to test things with the current population or at least have a leading indicator of how they're thinking about new products, and just walk us through how you decided on these opportunities for '27 for product launches, thanks.
Oran Holtzman
Sure. When we refer to product launches, it's with all three brands.
We have around eight new products, very promising for SpoiledChild, at least five, six products for IL MAKIAGE that we worked for the past three years to build, and of course we have METHODIC. We launched METHODIC with 30 products, and now we have very promising roadmap for 2027 for METHODIC, including peptides for the first time.
The category itself is in early stage with a lot of growth potential based on what we believe, and we think we can emerge as one of the main winners there thanks to number one, all the advantage that ODDITY platform has, like the user base, the data, the tech, and our track record of unlocking categories for online. This is a new category, and we're waiting for long time and we believe we can be very successful.
Number two is in this category consumer confidence is very important for selling and conversion, and we've seen clearly in our internal studies that there is demand. METHODIC is in very well-positioned here already with proven track record in dermatology Rx with brand identity and highest quality partners.
Number three, because we always have the infrastructure to do it. If you remember back then, I told you that we built METHODIC not just for skin, and we had lots of ambitions there to expand it to other Rx domains.
Peptides is one of them, and with the recent HHS approval, it makes us very easy for us to expand toward that direction, and we are very pleased for that.
Scott Schoenhaus
Okay. Oran, and then my follow-up is IL MAKIAGE is improving here sequentially, and yet you still haven't fully resolved the issue with your advertising partner.
Maybe walk us through how you were able to improve these trends, what you're doing outside of this fix on the advertising side that allows you to see the sequential improvement in IL MAKIAGE? Thank you.
Oran Holtzman
We work really hard on fixing the problem. Those things require lots of tests and iterations.
We work extremely close to our advertising partner. I'm doing it personally every day, many hours every day.
Those things never easy to solve, and especially because it's algorithm learning stuff, but we do a lot there. In addition, we work on other channels and we work extremely hard to launch new product that may help us redirect the algorithm to the right place.
Again, it's at least 60, 70% of my day and my days are long.
Operator
Our next question is from Dara Mohsenian with Morgan Stanley. Please proceed with your question.
Dara Mohsenian
Hey, good morning. First, I just had a clarity question.
You clearly beat Q3 guidance. You'd actually reported fairly late in calendar Q3 the actual Q2 results, I'm guessing the end of the quarter was pretty solidly above what you expected.
Q4, the implied guidance today looks relatively in line with what you implied previously. I just wanted to better understand where the business came in better than expected in Q3, what that sort of implies for Q4 and beyond as we look forward, maybe there's some conservatism baked in for Q4, but just trying to understand that.
Then just second, clearly you're not guiding to '27 today, but just conceptually, Lindsay, given the volatility we've seen this year, can you just touch on some of the key puts and takes you'd be thinking about ahead of time for '27? Maybe within that, given the growth has been so strong on SpoiledChild this year, maybe you can give us a bit of a review on what's driving the strength there and the plans for '27?
Thanks.
Oran Holtzman
I would just start by saying that we are not providing guidance for 2027, but our goal is to return to growth and we hope to deliver that growth with all our brands, including IL MAKIAGE. We work extremely hard to get there.
We still have time, and that's what we do. Regarding the first question, maybe, Lindsay, you can reply.
Lindsay Drucker Mann
Thanks. Hi, Dara.
When we guided Q3, I would say the quarter came generally as we planned. As you mentioned, we spoke to you guys in early September, we had a few weeks left.
SpoiledChild has been a really nice positive driver, it has been coming in better than we planned, and METHODIC also scaling really nicely, those were positives. When we set our guidance, just given the current dynamic where so much of our effort and dollar spend and focus is on resetting the algorithm for IL MAKIAGE, there is naturally some volatility that comes into the return on ad spend and the ad spend itself.
It's not like a normal year for us, and that's why we wanted to embed enough room. I would call it conservatism, but more I would call it room for us to move and do the right thing for the reset.
That's also what you're seeing in the fourth quarter. As you mentioned, this is as we planned based on the last time we spoke to you, and again allows us to focus on fixing the business for the long term, but causes some near-term volatility.
What I would add to Oran in terms of '27, absolutely, like he mentioned, our plan to bring the business back to growth for all our brands, I would just make sure it's clear that that will require investment from us in order to drive the first orders, which will drive the repeat and get our flywheel going again. Too early for us to talk specifically about 2027, but those are the two key drivers.
Operator
Our next question is from Brian Tanquilut with Jefferies. Please proceed with your question.
Brian Tanquilut
Hey, good morning. Maybe just to double-click on IL MAKIAGE, how did CPA change quarter-over-quarter and year-over-year in Q3?
If you can talk about your progress with your ad partner, as we think about how much of that expected 40 to 60% recovery you've said in the past in CPA increase for the partner's side has already been realized? Thank you.
Oran Holtzman
Sure. Listen, it's very volatile because we are in a mode of testing and iterations on a daily basis.
For example, September was the best CPA that we had since 2025, but it's very volatile, October wasn't that good. We are here to fix the problem and not just to improve it slightly, we are making big changes on a daily basis on our ad accounts.
Everything is in full collaboration with our ad partner. We are not doing any change on the ad account without their sign-off.
That's it.
Operator
Our next question is from Anna Lizzul with Bank of America. Please proceed with your question.
Anna Lizzul
Hi, good morning. Thank you so much for the question.
I was wondering if you could talk a little bit more about how Q4 is tracking so far with IL MAKIAGE and if you see any uplift typically from the holiday season, or is this less impactful to IL MAKIAGE and your other brands as well? Then I know you're not commenting fully on 2027, but if you could just give us a little bit more color on how you're expecting sequential improvement post Q4, especially on IL MAKIAGE in light of the algorithm changes that you've been adjusting to?
Thank you.
Lindsay Drucker Mann
I would just say again Q4 is tracking as planned and our primary focus right now is on doing everything that needs to be done to remedy the account dislocation. Normal selling activity is not something that we're focused right now.
It's truly on fixing the algorithm and putting us in a position to return to growth next year.
Operator
Our next question is from Javier Escalante from Evercore ISI. Please proceed with your question.
Javier Escalante
Good morning, everyone. Good reconnecting with you both.
I have kind of a more long-horizon question. How do you see IL MAKIAGE's role within ODDITY's portfolio and evolution of the different business models?
SpoiledChild is coming better than you planned, which is great. Wellness and beauty have different competitive sets, consumer and retail dynamics.
Is it IL MAKIAGE vertical needed for a scale, learning, some kind of bootcamp given the category? Related to that, how do you see whether to keep IL MAKIAGE primarily D2C, or broaden distribution, say, through Amazon, where I believe the brand already sells, and where you can advertise and converge within the same environment?
Thank you.
Oran Holtzman
Hi, Javier. How are you, man?
Thanks for the question. The answer is, we work extremely hard to make sure that IL MAKIAGE is back to growth, okay?
We believe that the problem that we have now is a technical problem with algorithm. We don't think it has nothing to do with softness in color or with anything relate to our brand.
Yes, IL MAKIAGE is down, but we knew it from the beginning of the year, and we work extremely hard to fix it. IL MAKIAGE has a very strong brand equity, high customer satisfaction from millions of customers based on very high product quality.
We don't see anything that signals us that we have any brand damage or anything regarding the category itself. Yes, SpoiledChild is growing better than expected, we are very pleased.
METHODIC is doing great. IL MAKIAGE need to go back to growth, and that's what I do day and night.
Regarding Amazon, we are still 100% D2C, and when we have something to announce on that front, we will.
Operator
Our next question is from Bryan Smilek with J.P. Morgan.
Please proceed with your question.
Bryan Smilek
Great. Thanks for taking the questions.
Just curious, as we look into 4Q and into 2027, can you just help me think about the go-to-market strategy across advertising more broadly? Totally appreciate continuing to work with the current ad partner, but do you see other surfaces and channels more broadly where you can spend to get greater returns overall from an LTV-to-CAC perspective?
Then I would say as well, too, from a peptides perspective, can you just help me understand the potential investments needed there from a sales and marketing side to build brand awareness? Thank you.
Lindsay Drucker Mann
Thanks. I think number one, what we've said before is that this advertising partner is the main place where, for our categories, you see direct-to-consumer activity happening.
While we have been able to diversify somewhat, and we continue to look for other ways to diversify, this is—
Oran Holtzman
This is more than 50%. This ad partner responsible for more than 50% of our category, I would say way more.
We need to fix the issue with that partner.
Lindsay Drucker Mann
Yeah. Our go-to-market with peptides is I would say very similar to what we're doing now already with METHODIC and with SpoiledChild.
As we have said before, the upfront investment in acquisition is a bit higher versus what our current base business looks like, but the paybacks are really attractive. We'll be very thoughtful in understanding what those cohorts look like as we put acquisition dollars to work there.
As Oran said, very attractive categories for us, not just peptides, but many other things that we are looking to do in METHODIC, which follow our typical, when we look for areas of expansion, very big markets where there's a real pain point to solve, and the unit economics work well for online, so that's our filter.
Oran Holtzman
I would just add that we are not spending any dollar against any product or any categories that is not highly profitable on a 12-months basis. Even if the investment is higher, for example, for peptides at the beginning, if the payback will not be materially better than other categories, we will not spend money against it.
Operator
Our next question is from Andrew Boone with Citizens. Please proceed with your question.
Andrew Boone
Thanks so much for taking the questions. I wanted to go to gross profit margins.
Lindsay, with inventory elevated, can you unpack the gross profit margin that was in 3Q '26, and then any expectations as you guys may have to clear inventory looking forward? Then going back to the peptide question, as we think about infrastructure that you guys have built out to be able to support that business, what's done today, and then what are the key steps that you guys need to do as we think about that business ramping in 2027, and how should we think about the timing of those steps being completed?
Thank you.
Lindsay Drucker Mann
I'll start on gross margin. We've had gross margin pressure all year, which has in large part been driven by AOV.
As I mentioned, AOV was down around mid-single digits, and the AOV decline is driven in part by the fact that we've got a big reduction in our first orders, and first-order AOV is higher than repeat order AOV, and so you're seeing that impact gross margin. As we get to next year, we hope that these headwinds will be behind us, at least the worst of the first-order declines, and so you should see better behavior out of gross margin.
It's too early for us to give any real guidance, but in terms of that dynamic, we expect that will be behind us. We feel comfortable with the inventory dynamics now.
As I mentioned, IL MAKIAGE is a bit heavy, but thankfully we have low obsolescence for our inventory based on the categories that we operate in, and we think that we can work through a lot of that as revenue picks up.
Oran Holtzman
As for peptides and the new categories from METHODIC, as I mentioned, we already set the infrastructure in place, and we are ready to play, including compounding pharmacies and telehealth providers. We build it for skin Rx, and we are ready to go with them with the rest of the categories.
Operator
Our next question is from Ryan MacDonald with Needham & Company. Please proceed with your question.
Ryan MacDonald
Hi, thanks for taking my questions. Maybe on peptides, maybe twofold.
First, the peptide opportunity with the six sort of approved peptides from HHS and the PCAC committee is creating sort of a unique market dynamic in that the category is essentially opening up all at once for the entire industry. I guess from an investment perspective and marketing and go-to-market, do you have to maybe break your traditional mold of marketing approach and invest heavier on sales and marketing upfront given there are so many e-commerce and telehealth vendors going after the same opportunity pretty quickly in early '27?
Then as we think about peptides growing as a mix of the revenue stream next year, I would imagine this is a positive impact on AOVs, but how are you thinking about sort of the movement into peptides on the impact of balance between sort of volume growth versus AOV growth as we think about next year? Thanks.
Oran Holtzman
Sure. I view it differently.
I think that the fact that it's new, it's easier for us to compete. Yes, the market is being opening now, but the fact that we are already ready to go, yes, few players are also in the same position as us, but we believe that the potential is huge, and we believe we can be very competitive there.
As for, yes, higher AOV and higher CAC, but as I mentioned before, if it doesn't look very compelling in terms of repeat and cohorts, we are not going to spend money against it. Still very early to know because we didn't start.
It was just approved. In very few months, we will have a read, but overall we are very optimistic.
Operator
Our next question is from Lauren Lieberman with Barclays. Please proceed with your question.
Lauren Lieberman
Great, thanks so much. Wanted to just catch up a little bit on SpoiledChild, who continue to have super strong growth.
When I take a look at kind of just my best proxy for leading products, looking at reviews on the SpoiledChild website, it still seems to be really, really heavily weighted toward the liquid collagen drink. Just curious from your own advertising and algorithm perspective, how much you're emphasizing the drink versus looking to diversify sales across the rest of the portfolio?
Thanks.
Oran Holtzman
We are spending dollars again not only against collagen, also around other products, and we have, as I mentioned, many new products coming in the next two, three months. In terms of why it's so successful so far, it's intense execution of our playbook, leveraging our data, user base, and technology platform to drive acquisition and profitable repeat.
That's what we do. We've done before with IL MAKIAGE, we're doing it now with SpoiledChild.
Yes, it grew faster than we thought, but we believe SpoiledChild is positioned in a very attractive category in wellness where the demand only grows, especially now with the growth of GLP-1. We view it as a tailwind, and we see it in numbers.
Operator
Our next question is from Youssef Squali with Truist Securities. Please proceed with your question.
Nick Cronin
Hey, good morning. This is Nick Cronin on for Youssef.
Thanks for taking the question. Just wanted to ask on METHODIC's customer base, what proportion of that is net new to the ODDITY platform versus existing IM or SC customers, and how are you thinking about cross-selling across the three brands, both introducing METHODIC to existing customers and bringing METHODIC customers into your beauty brands?
Then as a follow-up, just how are you thinking about the growth opportunity ahead in international? I know that was quite a area of focus in the past, but maybe took a step back this year.
Is that something that we should start focusing on again maybe in FY '27? Thanks.
Oran Holtzman
As for METHODIC users, the easiest thing for us at the get-go was to squeeze our user base from IL MAKIAGE and SpoiledChild, but we deliberately acquire METHODIC customers on their own merit so we can read the brand's real potential. Cross-sell for IL MAKIAGE and SpoiledChild is an upside that we are starting to see, but not the base itself.
Second question was international. My focus is to fix North America for IL MAKIAGE and to continue to grow SpoiledChild in the US.
It's still very early, upside for international for SpoiledChild exist. As for IL MAKIAGE, we need to fix first the US market and then to continue to grow in international.
Operator
Our last question is from Bonnie Herzog with Goldman Sachs. Please proceed with your question.
Bonnie Herzog
All right, thank you. Good morning.
Oran, you mentioned a number of new things you're working on. Could you share with us how you'll prioritize and time the rollout of innovation, including investments required to roll them out?
Then will the innovations be phased throughout next year or more 1H weighted? Finally, I guess, how concerned are you about potential execution risk as you roll out or step up innovation while you're still trying to, I guess, return IL MAKIAGE to growth?
Thanks.
Lindsay Drucker Mann
Hey, Bonnie, I'll take that one. I think as an organization, as a company, number one, we're always focused on planning one, two, and three years forward in terms of what our brands will be doing from a product innovation standpoint, and then also on the tech side, what kinds of new tech products will be working on.
Because we have a very strong culture of test and fail fast and bury losers quickly and big swings, it's a nice muscle in terms of identifying innovation that will work, testing it out first before we actually put significant dollars to work in scaling it. On the product innovation side, we've said before as an organization we really do believe in product, and that as an online business that's super important in terms of driving LTV and repeat, and so we're very focused on our product innovation slate to always be bringing products out there that, number one, address big markets with large pain points where the unit economics work for online, but number two, where our innovation itself beats out what else is on the market there and can drive a truly differentiated outcome for the consumer.
We have that as a big muscle in the company, and that's something that we are excited to bring about in 2027. Obviously, this was a more challenging year specifically for IL MAKIAGE, where some of the things we've been working on were on hold, but we hope that we'll be in a great position to play offense next year.
Operator
We have reached the end of the question-and-answer session. I would like to turn the floor back over to Oran Holtzman for closing comments.
Oran Holtzman
Thank you very much, guys. See you next quarter.
Operator
This concludes today's teleconference. You may disconnect your lines at this time.
Thank you for your participation.