Orthofix Medical Inc.
NNASDAQ:OFIXQ3 FY2026 · Earnings Call TranscriptNovember 9, 2026
Operator
Hello everyone. Thank you for joining us, and welcome to the Orthofix Q3 2026 earnings call.
After today's prepared remarks, we will host a question and answer session. If you would like to ask a question, please press star 1 to raise your hand.
To withdraw your question, press star 1 again. I will now hand the conference over to Julie Dewey.
Please go ahead.
Julie Dewey
Thank you, and good morning, everyone. Welcome to Orthofix's third quarter 2026 earnings call.
I'm Julie Dewey, Orthofix's chief IR and communications officer. Joining me today are our president and chief executive officer, Massimo Calafiore, and our chief financial officer, Julie Andrews.
Earlier today, Orthofix released financial results for the third quarter ended September 30th, 2026. The press release and supplemental presentation are available on our investor relations website.
A replay of this call will be posted shortly after we conclude. Before we begin, please note that our remarks include forward-looking statements.
These statements involve risks and uncertainties, and actual results may differ materially. All statements other than those of historical facts are forward-looking statements.
We do not undertake any obligation to revise or update such forward-looking statements, except as required by law. Factors that could cause actual results to differ materially are discussed in our most recent filings with the SEC and may be included in our future filings with the SEC.
We will also reference certain non-GAAP financial measures during today's call, including certain growth rates presented on a pro forma, constant currency basis and excluding discontinued M6 artificial disc product lines. Reconciliations to the most directly comparable US GAAP measures and additional information are included in our press release and supplemental materials.
Here's today's agenda. Massimo will begin with business performance and operational highlights.
Julie Andrews will then review our financial results and guidance. After that, we'll open the call for questions.
With that, I'll turn the call over to Massimo to discuss our third quarter performance. Massimo?
Massimo Calafiore
Thank you, Julie, and good morning, everyone. I appreciate you joining us today.
While third quarter results were below our expectation, we saw continued strength in limb reconstruction and therapeutic solutions, and further stabilization in US biologics. In US spine, market softness and unplanned supplier delays created inventory and instrument set constraints.
We have a clear recovery plan and are accelerating actions to improve execution and position the business for stronger performance. We are concentrating resources behind our strongest partners and highest-value technology, simplifying the portfolio, and aligning costs with a more focused business.
These actions are intended to establish a stronger foundation for growth, profitability, and cash generation over time. To recap this action in more detail, first, we're concentrating resources behind our strongest commercial partners.
We are accelerating exits from non-strategic, lower-performing relationships and redeploying instrument sets to faster-growing core distributors. These distributors now generate around 80% of US spinal implant revenue, with a similar concentration among core products.
We have already seen this strategies work in markets where we consolidated distribution around stronger partners. Our core partners' consigned assets turn around 20% faster than the loaner-heavy model used by many distributors we're exiting.
This allow existing sets to support more procedures and revenue with less incremental investment. Second, we're simplifying our product portfolio and concentrating investment behind our highest-value technologies.
We are focusing inventory, capital, and commercial support on differentiated platform with the greatest growth potential, including Virada. We continue expect the full market launch of our Virada spinal implant system for open procedure later in the fourth quarter.
Third, we are aligning costs and organizational resources with a more focused business. As we simplify the network and portfolio, we expect to reduce support costs and redirect resources towards the opportunities with the strongest growth and return potential.
Fourth, we are focusing our innovation pipeline on technologies with the greatest potential to drive adoption and long-term growth. That include Virada and further integration of our enabling technologies such as the 7D navigation system, for which we received two 510(k) clearances this quarter covering additional software enhancement.
The combination of this action and the supplier delays are creating near-term net sales pressure as we exit lower-value business. We expect this transition to unfold over the coming quarters, with the anticipated fourth quarter impact reflected in our updated guidance.
We are carefully sequencing relationship exits and asset redeployment with the goal of maintaining surgical support and product availability, while position our strongest partners for growth. We expect progress in stages.
First, we anticipate improved inventory and instrument set availability and utilization among core distributors. Next, we expect stronger growth from core products and partners.
Over time, we expect those improvements to support better channel productivity, profitability, and cash conversion. While spine remains our most immediate focus, we continue to make progress in several other parts of the portfolio.
US biologics net sales were roughly flat sequentially despite typical seasonal softness, providing another sign of stabilization. October offered another encouraging data point as the business returned to positive year-over-year growth.
Our priority is to build on this momentum through stronger account execution, higher utilization, and continued focus on priority products, including Osteocel. In global limb reconstruction, growth in the quarter was driven by strong international demand and continued adoption of Fitbone and TrueLok Elevate.
These two platform are driving the majority of the franchise's growth and address large, unpenetrated markets where we believe our differentiated technology can support sustained growth. In the US, we remain focused on increasing distributor productivity and expanding market development activities to convert clinical interest into broader adoption and net sales growth.
As those capabilities mature, we expect improved US growth and greater predictability. We also continue to invest in innovation across limb reconstruction.
In September, we submitted a 510(k) pre-market notification for an automated version of the TrueLok Elevate system, designed to improve the patient experience and support a key growth driver. We also pursuing potential additional indication, including diabetic foot ulcer, a large and underserved market where we believe our core technologies may have broader clinical application.
These investment are intended to expand our addressable market, strengthen our clinical differentiation, and support long-term value creation. Turning to therapeutic solutions, the business deliver 4% volume growth, which was above market growth, while maintaining attractive margins and strong cash generation, reinforcing its role as a stable contributor to the portfolio.
Our priority is to improve prescription conversion and use digital capabilities, including AccelStim 2.0 and STIM onTrack, with the goal of strengthening physician and patient engagement while maintaining investment discipline. Taken together, our immediate priority is improving US spine execution while sustaining momentum across the stronger areas of our portfolio.
Across the business, we remain focused on disciplined execution, thoughtful capital allocation, and measurable progress. With that, I'll turn the call over to Julie Andrews to review our third quarter financial results and outlook.
Julie Andrews
Thank you, Massimo, and good morning. For purposes of consistency, the growth rates I'll reference today are on a pro forma, constant currency basis and exclude the discontinued M6 product lines.
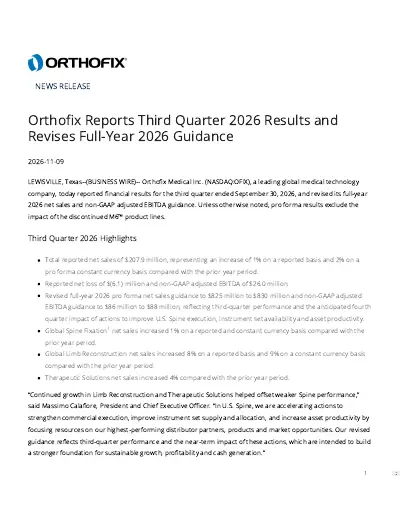
Third quarter reported net sales were $207.9 million, an increase of 2.3% year-over-year. Growth in limb reconstruction and therapeutic solutions helped offset weaker performance in spine.
The drivers varied by business. Let me walk you through the quarter in more detail.
Global spinal implants, biologics, and enabling technologies generated $107.4 million in net sales, a decrease of approximately 1% versus the prior year period. Global spine fixation net sales increased 1% on a constant currency basis, while US spine fixation declined 5%.
Performance was affected by a softer, market-driven procedural environment and continued declines among smaller distributors. In addition, supplier delays and instrument set constraints limited our ability to consistently support demand among our top 30 distributors, whose pace of growth weakened, but remained above the market.
The financial effects of these actions are reflected in our updated guidance, which I'll discuss shortly. In biologics, stabilization in the US continued in the third quarter, with net sales roughly flat sequentially despite typical seasonal softness.
While the recent trend is encouraging, we recognize that sustained improvement is still needed. Therapeutic solutions generated $64 million in net sales, up 4% year-over-year.
The business continued to deliver steady revenue growth, strong margins, and cash generation. Global limb reconstruction delivered net sales of $36.4 million in the third quarter, an increase of 9% on a constant currency basis.
Growth was driven by strong international demand and continued adoption of Fitbone and TrueLok Elevate. US growth was essentially flat in the quarter, but we believe the underlying trajectory and portfolio mix are improving.
Fitbone and TrueLok Elevate each grew in excess of 20%, providing encouraging evidence that the transition toward high-growth limb reconstruction opportunities is gaining traction. The remaining pressure was concentrated in a limited number of product lines and distributor relationships rather than across the franchise.
Moving down the P&L, non-GAAP adjusted gross margin was 70.7%, reflecting an unfavorable geographic mix during the quarter. Adjusted EBITDA was $26 million, or 12.5% of pro forma net sales, compared with $24.6 million, or 12.1% in the prior year period.
The improvement primarily reflected continued cost discipline and resource alignment, partially offset by lower spine revenue, unfavorable geographic mix, and reduced operating leverage. We ended the quarter with $86.9 million in cash, cash equivalents, and restricted cash.
The change in cash primarily reflected working capital timing, investment in instrument sets ahead of the commercial launch of Virada, and inventory to support our European MDR strategy. Let me now turn to our updated full year outlook.
Again, all measures are provided on a non-GAAP, pro forma basis, reflect current foreign currency exchange rates, and exclude the discontinued M6 product lines. Our outlook does not contemplate any additional exchange rate changes during the remainder of the year.
We now expect full year 2026 pro forma net sales in the range of $825 million to $830 million. The revised guidance reflects third quarter performance, continued softness in the spine market, and the anticipated impact of accelerated actions to improve US spine commercial execution, inventory and instrument set availability, and productivity.
It also reflects the timing of international limb reconstruction orders and foreign exchange headwinds. We now expect full year 2026 non-GAAP adjusted EBITDA of $86 million to $88 million.
The impact of lower revenue and unfavorable mix is expected to be partially offset by continued cost discipline, lower incentive compensation, and resource allocation actions. Looking to the fourth quarter, we expect sequential growth from two primary drivers: normal seasonality and inventory purchases under the European distributor arrangement.
As previously disclosed, most of the approximately $15 million 2026 net sales benefit from the European distributor arrangement should be recognized in the fourth quarter. As a reminder, the European distributor arrangement creates a temporary free cash timing headwind in 2026 because inventory-related cash outflows occur this year, while cash receipts are expected in 2027.
This timing does not change our view of the business's underlying earnings power, cash-generating potential, or long-term economics. Consistent with our standard practice, we expect to provide formal 2027 guidance on our fourth quarter call.
As previously disclosed, our European MDR strategy for spine is expected to create an approximately $22 million net sales headwind in 2027 while MDR requirements are completed. This is a temporary, regulatory-driven impact that reflects the timing of revenue recognition, not a change in underlying demand.
As we move through this transition, our focus remains on disciplined execution. Now let me turn it back to Massimo for closing remarks.
Massimo?
Massimo Calafiore
Thank you, Julie. Our priorities are clear: improve US spine execution, stabilize biologics, build on the strength of limb reconstruction and therapeutic solutions, and maintain financial discipline.
The actions are underway, and our focus is translating them into measurable operating and financial progress. We look forward to updating you as we execute against these priorities.
Before we take your questions, I want to thank our employees and commercial partners for their continued commitment to supporting surgeons and patients around the world. With that, let's open the call for questions.
Operator
Thank you. We will now begin the question and answer session.
Please limit yourself to one question and a couple of follow-ups. If you would like to ask a question, please press star 1 to raise your hand.
To withdraw your question, press star 1 again. We ask that you pick up your handset when asking a question to allow for optimum sound quality.
If you are muted locally, please remember to unmute your device. Please stand by while we compile the Q&A roster.
Your first question comes from the line of Matt Blackman with TD Cowen. Your line is open.
Please go ahead.
Drew Ranieri
Hi everyone, it's Drew on for Matt today. Massimo, I'll start with you, and apologies, this is a bunch of questions kind of rolled into one.
We all know about the ongoing efforts to revamp the distributor network in spine, but maybe can you discuss a little bit more of what you're seeing in terms of market softness versus the distributor network, and really what's the lift ahead to get this business even to a market-level growth? What's the steps over the next 3 months, 6 months, and 12 months, just how should we be kind of thinking about that and the impact for the Virada launch as well?
Massimo Calafiore
Thank you for the question. This quarter has been, let's say, more difficult than the precedent, because what you said.
We saw a market softness that normally is not impacting us, but we saw happening in some of our top customers, indicating that the procedural volume was not as strong as we saw the previous quarter. Together, combining the optimization that we are doing around our distributor, we had some delay on delivery of instrumentation and implant from some our key suppliers.
We took measure to make sure they are going back on track, and so this is reflecting on our, let's say, refined guidance. The strategy is not changing.
80% of our business is concentrated in our top distributors. We are moving ahead, stabilizing our supply chain, and we made a lot of investment as previously said, on the launch of Virada, which is on track to be on Q4.
What I'm expecting now is that it's going through this current quarter, but I see that we're going to be pretty well positioned for 2027. In brief, you're going to see an improvement in stage, but the strategy is not changing.
We are laser-focused on making sure our top distributors are well-equipped to drive the growth together with 7D.
Drew Ranieri
Got it. Just as a follow-up there, when you look at the distributor network, I think you're just saying that there was some market softness, but just to push you on that a little bit, what's your confidence that this is actually procedural softness versus any type of market share loss in the quarter or as you're kind of thinking about the fourth quarter?
Massimo Calafiore
Because what I said before. We saw always a pretty stable performance, especially in our top accounts, and just the cases were not here this quarter.
I don't believe that we are losing market share per se. I think that our core distributor are still growing well above the market, and that one for us is our leading indicator of how we are performing.
Because, as said before, everything else is kind of part of our strategy. We talked for several quarters the fact that we are exiting a bunch of distributors that now represent just 20% of our overall business, and this quarter and in Q4, we need just to deal with this temporary disruption our supply chain, but the fixes are underway to be ready to close the year strong and start 2027.
Drew Ranieri
Got it. Julie, just turning to you, obviously we all want to know 2027 and your thoughts there, and there's a lot of moving pieces.
Just as a general framework, should we be thinking that limb recon and therapeutic solutions can grow at or above market levels, and then maybe the fourth quarter spine revenue or implied spine revenue is at least a good way or reasonable way to think about a run rate for 2027?
Julie Andrews
Drew, we're not providing guidance. I think generally our comments and what we've seen in our performance with therapeutic solutions and limb recon is above-market growth.
Then we do have the MDR headwind next year against the spine business that will be impacting that growth rate overall. I think it's early to comment on exactly what spine will look like.
I think generally, once you take out the Q4 or the 2026 MDR revenue, we should expect to see a kind of a Q3, Q4 performance as we enter 2027.
Drew Ranieri
Thanks, all for me. Thank you.
Julie Andrews
Thank you.
Operator
Your next question comes from the line of Tom Stephan with Stifel. Your line is open.
Please go ahead.
Tom Stephan
Great. Hey guys, thanks for taking the questions.
I'll try to stick with 2027. On a core revenue basis, backing out the Europe dynamics, I guess directionally should we still be thinking about positive revenue growth next year, again considering limb reconstruction, therapeutic solutions?
Then it sounds like, Massimo, to your comments, you feel you'll be pretty well positioned for '27 on the US spine side. Again on a kind of core revenue basis, is positive revenue growth kind of directionally the right place to be when thinking about 2027?
I have a follow-up.
Julie Andrews
Again, not providing full guidance on 2027, but yeah, backing out the MDR, we would expect our core revenue to be in the positive territory as we work through these supplier issues in the fourth quarter and come out with a full quarter of Virada launch for Q1 of 2027.
Tom Stephan
Got it. Super helpful.
Then I'll shift gears a little bit. Massimo, this might be for you, but as we look at segment performance, it's been a little varied.
I hope that that's fair to say. Limb reconstruction strong, biologics it sounds like is stabilizing in what appears to be maybe a tougher environment, BGT still solid, and then conversely spine fixation a bit weaker.
Massimo, can you just give us the latest on kind of the company's current view of the portfolio and maybe potential opportunities to monetize, to rationalize, optimize, etc.? Thanks.
Massimo Calafiore
No, thank you for the question, and you're right. Right now, our story, it kind of has two different sides.
The strategy that we implemented in the last couple of years is clearly bearing the fruit in some side of the business, and I was very pleased to see biologic start to perform as we were expecting at ending the year. That one I think that it reflects that the choices that we made are paying off.
Around our spine segment, if you think about, we've been very consistent on the measure that we took. This quarter has been a little choppy for some market dynamics and some unexpected delays from some of our core suppliers.
We don't talk about, and I don't want to comment about strategic decision that we want to take. I want to just comment that we are not changing our strategy.
We need just to go through some temporary condition that we're seeing in spine and keep positioning the organization and all of the segment to perform as we expect. As said earlier, strategically, the decision that we made a couple of years ago in some of the segment are paying off.
We need just to go through some temporary market dynamics.
Tom Stephan
Makes sense. Thanks again.
Operator
A reminder, if you would like to ask a question, please press star 1 to raise your hand. To withdraw your question, press star 1 again.
Your next question comes from the line of Caitlin Roberts with Canaccord. Your line is open.
Please go ahead.
Caitlin Roberts
Great, thanks for taking the questions. Just to start on the supply challenges specifically, what were they?
Were the challenges concentrated in any product lines? Just where are you guys in recovering from that?
Massimo Calafiore
It was, let's say, concentrated, some delay on our instrument manufacturing and some specific product line around interbodies, but we took action and we start a strong collaboration with our suppliers, and we feel that we cross-correct what was supposed to be cross-corrected with them. I think that we are about to be out for this.
Between end of Q4, we're going to be, again, ready to support the end of the year and starting on 2027. Was kind of unexpected, but we all work together in order to rectify.
Caitlin Roberts
Understood. Then just any color on the 7D demand in the quarter and just on also the two 510(k)s that you called out?
Massimo Calafiore
We keep investing in our technology platforms in general, you saw that on the 510(k)s that we got with 7D kind of enhance some of the capabilities that they're already there and we gained some optimization of the workflow. Very pleased about what we did there.
When we started, our customer base increased and we got a lot of feedbacks to make sure that the platform keep improving, and the team create a fantastic job taking the comment and keep upgrading the platform. About this quarter, I don't think that we are not giving any general information about our performance, but what I can tell you is that now you start to see the regular seasonal demand for capital that you see every year.
Julie Andrews
I will add this, Caitlin, our earn-out customers, what we've mentioned before, we still are seeing them exceeding their contracted spinal and hardware and biologics purchase commitments. That continued into Q3 as well.
Caitlin Roberts
Understood. Thanks so much.
Operator
Your next question comes from the line of Mike Petusky with Barrington Research. Your line is open.
Please go ahead.
Mike Petusky
Hey, good morning. Probably this is for Julie.
Just on the supplier issue, when you sort of look at the reduced guidance, what percentage of that reduced guidance is sort of associated with the headwinds associated with the supplier issue?
Julie Andrews
We're not providing exact breakout of all of the components, but I would say we had a miss in Q3 that's contemplated in the guidance. Then as we look into Q4, a combination of the supplier delays, market softness, which we saw in our top accounts, as well as then some international limb recon timing of orders and some FX headwind are the components that make it up.
Mike Petusky
Okay. I'm just curious, it feels like maybe somewhere in the last couple of quarters you've provided this, and I don't think I heard it today, but maybe I missed it, did you guys disclose approximately how much your core distributors, your top distributors, grew in the quarter?
Julie Andrews
We did not. We said they grew above market, but weakened pretty significantly compared to the growth that we've seen, which again, we believe is two things: the supply challenges and then some market softness.
Mike Petusky
Okay. Could you say whether the growth was above or below 5%?
Just in any way give us a sense?
Julie Andrews
I would say it slowed to the mid single digits.
Mike Petusky
Okay. All right.
Then, I suspect I know the answer to this, but when I ask it anyway, last quarter you guys talked about potentially reintroducing longer-term financial targets. It feels like maybe now is not quite the time, but I'm just curious, when you come out with '27, is there any chance that there will also be an LRP there, or is '27 enough work?
Julie Andrews
I think we'll have to play that out over the coming months, Mike. We're not committing to the timeline at the moment.
Mike Petusky
Okay. All right, that's all I got.
Thanks.
Julie Andrews
Thank you.
Operator
There are no further questions at this time. I will now turn the call back to Julie Andrews for closing remarks.
Julie Andrews
Thank you for your questions and for joining us today. We appreciate your time and interest in Orthofix.
If you need any additional information, please reach out. We look forward to updating you next quarter, and this concludes today's call.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.