Outset Medical, Inc.
NNASDAQ:OMQ2 FY2026 · Earnings Call TranscriptAugust 6, 2026
Operator
Good day, and thank you for standing by. Welcome to the Outset Medical Q2 2026 Earnings Conference Call.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there'll be a question-and-answer session.
To ask a question during the session, you will need to press *11 on your telephone. You will then hear an automated message advising your hand is raised.
To withdraw your question, please press *11 again. Please be advised that today's conference is being recorded.
I would now like to hand the conference over to your first speaker today, Tina Jacobsen, Investor Relations. Please go ahead.
Tina Jacobsen
Good afternoon, everyone, and welcome to Outset Medical's second quarter 2026 earnings call. Today's speakers are Leslie Trigg, Chair and Chief Executive Officer, and Renee Gaeta, Chief Financial Officer.
The company issued a news release after the close of the market today, which can be found in the Investor section of outsetmedical.com. This call is being recorded and will be archived there as well.
All forward-looking statements made during today's call are intended to be protected under the Private Securities Litigation Reform Act of 1995. Outset assumes no obligation to update these statements.
For a list and description of the risks and uncertainties associated with the business, please refer to Outset's public filings with the Securities and Exchange Commission, including its latest annual and quarterly reports. With that, I'll open the call to Leslie Trigg.
Leslie?
Leslie Trigg
Good afternoon, everyone, and thank you for joining us. The second quarter reflected steady execution across revenue, gross margin, operating expense discipline, and cash management.
We continued to make meaningful commercial progress while advancing our mission to improve dialysis patient outcomes at a lower cost and with less complexity. We are confident that the impact of that progress will become increasingly evident over time.
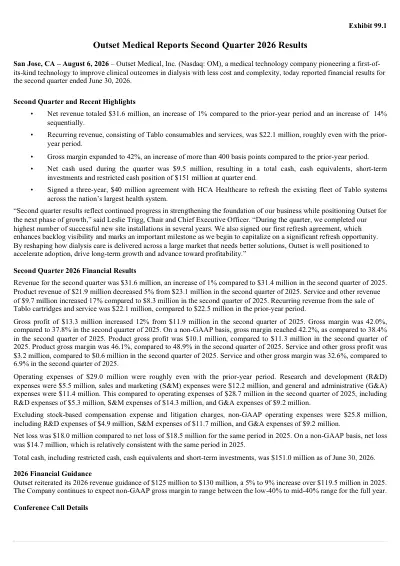
I'll begin today with financial performance in the second quarter. Revenue of $31.6 million was up 1% year-over-year and up 14% sequentially.
Our ongoing margin expansion programs delivered a non-GAAP gross margin of 42%, a significant improvement compared to last year. With the solid second-quarter results, we are reiterating full-year 2026 revenue guidance of $125 million to $130 million.
During the second quarter, we completed our highest number of successful new site implementations in several years. At one system with several sites in Texas, our clinical excellence team trained over 100 nurses, who in turn supported 956 treatments in their first 60 days.
Other successful implementations were completed at a new top-10 health system customer for Outset, as well as at hospitals that are part of large regional health systems and post-acute care facilities. What stands out most is what happened after the initial go-live implementations.
Outset has established a clinical excellence team focused on helping our customers optimize the clinical, financial, and operational value of their Tablo insourcing programs over the long term. Each hospital customer is paired with a clinical excellence team member who works closely with them to identify the outcomes that matter most to their organization, and then trends, tracks, and shares those key performance indicators on a regular basis.
Tablo's unique data ecosystem powers this process, providing valuable treatment and clinical program insights to our customers. The impact of this structured approach to customer success is reflected in both customer satisfaction and customer expansion.
During the quarter, we conducted an independent Voice of the Customer assessment, and when asked how likely they were to recommend Outset, our customers gave us an average score of 8.8 out of 10. Combined with the measurable results we continue to deliver, this strong level of customer advocacy is central to our forward commercial momentum and high customer retention, and creates opportunities for continued growth across our installed base.
We're increasingly seeing customers expand their use of Tablo, both by deploying the technology at additional sites across their health systems and by broadening use within existing facilities. A strong customer experience was instrumental in securing a meaningful recent commercial win.
We are privileged to have signed a $40 million refresh agreement with HCA Healthcare. The agreement reinforces HCA and Outset's long-term commitment to insource dialysis, which extends through 2028.
After carefully evaluating comparative outcomes, HCA opted to recommit to Tablo, underscoring the clinical and operational value that it continues to deliver across their nationwide system. The agreement provides a meaningful foundation of contracted backlog, enhancing our visibility and supporting revenue predictability.
Under the refresh agreement, HCA facilities currently partnering with Outset for insource dialysis will update their fleet. Importantly, the $40 million value does not include the potential to expand over time into additional HCA facilities not yet equipped with Tablo.
This marks our first refresh win, and that's an important milestone as we continue to capitalize on a refresh cycle that over the next several years may include roughly 3,000 consoles and up to $150 million in console revenue opportunity. Given customer confidentiality considerations, we're limited in the level of detail we can provide and don't intend to disclose HCA-specific information today or going forward.
That said, HCA is a recognized leader in healthcare, and we believe its continued commitment to Tablo serves as strong validation that over time can help support broader adoption across health systems of all sizes. We believe the introduction of the next-generation Tablo system will provide a great opportunity to catalyze customer refresh decisions.
Next-gen Tablo combines hardware and software enhancements designed to improve performance and reliability with advanced cybersecurity capabilities that are increasingly crucial for health systems. We're working on the pilot phase now in preparation for a successful broader launch, and we'll continue to share updates as we progress.
Reflecting on the quarter's performance from a commercial perspective, the addition of Derek Elliott as our new Executive Vice President of Commercial has marked our next phase of commercial evolution. Over the last several years, we standardized our sales process, built systems to support it, and refined our go-to-market strategy to create a more disciplined and predictable commercial engine.
We are now scaling that foundation to increasingly execute with consistency, conversion, and impact. Our near-term objectives include further infusing the capital sales organization with the right quantity and quality of talent.
We're expanding sales coverage to further accelerate our inroads into the top 250 health systems, where we believe Tablo can deliver significant impact. We believe we have the right combination of commercial rigor and clinical expertise to guide this next phase.
Derek's impact is being reinforced by our Chief Nursing Officer, Brittany McGill, whose firsthand understanding of our customers' pain points and workflows brings an invaluable clinical perspective. We're excited about our commercial and clinical leadership and expect their complementary expertise to position us well to engage health systems, address their most pressing needs, and accelerate customer adoption and conversion.
With that, I will turn the call over to Renee.
Renee Gaeta
Thank you, Leslie, and good afternoon, everyone. Total revenue in the second quarter was $31.6 million, up approximately 1% compared to the second quarter of last year.
Product revenue was $21.9 million, down 5% against a challenging prior-year growth comparison. Console revenue of $9.5 million grew 6% year-over-year, and consumable revenue of $12.4 million was down 12% against a double-digit growth comparison last year.
Service and other revenue of $9.7 million grew 17% compared to last year on strong volumes and ASP increases. Recurring revenue, which includes consumables, service, implementation services, and freight, was $22.1 million, down 2% compared to last year.
Turning next to the P&L, please refer to the tables in today's earnings release for a reconciliation of GAAP to non-GAAP measures. Second-quarter non-GAAP gross margin was 42.2%, up over 380 basis points compared to last year and driven primarily by product cost improvements, reduced overhead, and service efficiencies.
Product gross margin was 46.1%, down about 280 basis points compared to last year due to a higher mix of console sales within product revenue. Service and other gross margin was 33.4%, up over 2,400 basis points.
Gross margin performance reflects strong execution and keeps us on track towards our next milestone of a 50% company-wide gross margin. Moving to operating expenses, second-quarter non-GAAP operating expenses of $25.8 million increased 1% compared to last year, in line with revenue growth.
Non-GAAP operating loss was $12.4 million, an improvement of 7% compared to last year. These results reflect continued progress as we work to achieve profitability.
Moving to the balance sheet, we ended the quarter with $151 million in cash, cash equivalents, short-term investments, and restricted cash. With ongoing expense discipline and working capital management, cash use was $9.5 million in the second quarter, keeping us on track to use less than $40 million in cash for the full year.
Turning to our guidance for 2026, we continue to expect full-year revenue of $125 million to $130 million, representing growth of 5% to 9% over last year, with most of the growth expected in the third and fourth quarters. Importantly, our confidence in this outlook is supported by a strong commercial pipeline and the foundational contracted backlog provided by the HCA refresh agreement.
With that, I will turn the call back over to Leslie.
Leslie Trigg
Thanks, Renee. I'd like to close by thanking everyone on this call for your continued support.
While the natural variability of capital sales has made our performance less predictable over the past year, we are confident in our ability to continue strengthening our commercial organization and sales process to improve visibility and predictability. The opportunity ahead of Outset has never been more compelling.
With a customer base that now includes all 10 of the largest 10 health systems, all 10 of the largest 10 post-acute providers, and approximately 30% of the top 100 IDNs, we are reshaping how dialysis care is delivered across a large, untapped market that needs better, lower-cost solutions. Over the next few years, we expect several new console growth tailwinds to emerge.
First, the refresh cycle; second, our launch of the next-gen Tablo; third, our newly formalized customer success team and program, which is designed to expand same-store console and treatment sales while also driving new site expansion within our existing customer base. Further, we continue to expand our layers of recurring revenue, starting with consumables and service and buttressed by EMR, annual maintenance, and implementation services.
We're demonstrating traction against a sizable new refresh opportunity and were well positioned to capitalize on it with a next-generation platform and a commercial team strengthened by proven leadership. Finally, we've built a foundation to support scale with improving gross margin, disciplined expense and cash management, and a clear path to profitability.
We have the strategy, the technology, and the team in place to execute consistently and create long-term value, and we look forward to sharing continued progress in the years ahead. With that, we are ready for Q&A.
Operator, please open the lines.
Operator
Thank you. To ask a question, you will need to press *11 on your telephone and wait for your name to be announced.
To withdraw your question, please press *11 again. We will now go to our first question.
One moment, please. Your first question today comes from the line of Rick Wise from Stifel.
Please go ahead.
Rick Wise
Good afternoon, Leslie. Hi, Renee.
It's great to see the quarter, and particularly on the console side. Maybe we can just start there.
Console revs at $9.5 million were nicely above, I think, a consensus number of something like $6.4 million or so. That's really solid outperformance, good to see.
Maybe unpack that for us if you could. How much of that outperformance is tied to the HCA agreement?
How do we break it down between that and the early impact of broadly next-gen Tablo launch versus that first-quarter lingering capital order made to the close this quarter, some of it? Or, he said hopefully, is this a new console run rate, or a one-time pull forward?
Just help us understand all the moving pieces there. Obviously, an important number and it's good to see.
Renee Gaeta
Sure, Rick. This is Renee.
I'll take a stab at that, and then have Leslie jump in if she has any elements to add. I would say it's sort of all of that to some extent, one or another.
I would say, yes, we are definitely pleased with our Q2 performance and coming off of the announcement of the HCA refresh. I will provide some color there in that HCA was a part of our Q2 pipeline and a part of our strong console performance during the quarter.
Due to customer confidentiality reasons, I'm not going to give much more specifics than that. That is not to say that we also had new expansion customers, other console placements included.
We continue to have a broad range within our pipeline of deal size, and we were glad to see the closed completion of certain of those deals in the quarter.
Leslie Trigg
I think that was well said. I would just add that I think this was a quarter when all parts of the business performed as we had expected, and I was very pleased to see the distribution across sort of the two big parts of our commercial strategy, which is: one, current customer expansion; and two, new customer acquisition.
Then you alluded to some of these new growth tailwinds that we haven't necessarily had at our back in the past. I think that be it the refresh opportunity ahead of us, a new commercial leader, this new very sort of structured and formalized customer success program and team, I think this was sort of the first quarter where we were seeing some green shoots of all of those tailwinds coming into play in a nice way.
Rick Wise
Great. Also, what stood out to me, you called out, but maybe you could talk about a little more and help us better understand, consumable revenue growth was down 9%, steeper than the first quarter's decline.
I just want to make sure I'm understanding what that's all about and to what impact, if at all, is this new systems and volume not quite up yet, or does HCA or the next-gen launch reverse that trend, or, again, just what does it mean, and how do we think about the rest of the year from that perspective?
Renee Gaeta
It's a great question, Rick, and a fair one. I would start off with, we are certainly up against a tough comparable from the prior year.
2025 had a really strong Q1 and Q2 on the consumable side, partly driven by the flu season and census in that year, which we have not seen as strong of an impact in 2026. Then, of course, as you might remember, we had some of the ordering cadence volume in 2025, which we believe is now past us.
I think when we take a look at understanding that our consumable revenue is going to be driven by ordering timing, we really look down a layer into the device utilization information that we have, and we continue to see strong utilization across our customer segments. There's nothing alarming or concerning for us.
Again, we're just up against a really hard comp. Then I would say, as we look forward to the back half of the year, and when we talk about our guidance as a whole, consumable revenue growth is anticipated to be sort of in line with total revenue expectations for the year.
We hope that those have tailwinds going forward and utilization not only holds up, but maybe expands beyond that.
Leslie Trigg
The only thing I would add to that, too, that's maybe important to note, we had just mentioned a second ago in the prepared remarks that we did our largest number of new site implementations over the past several years in this past quarter. I think we had talked about this in a past quarter, that is a reflection of a little bit longer delay that we had seen between console sale and the timing of the actual installation and training of the site.
We did actually see a lot of this finally flow through Q2 to install and implementation. We believe that that will also lead to more normal order patterns going forward.
To Renee's point, we have sort of exquisite data on utilization because Tablo is transmitting after every treatment, every day, every console, everywhere in the nation. We can view this on an hour-by-hour and day-by-day basis.
Our visibility into actual console utilization is pristine, and we have continued to see very stable utilization, no material changes in Q2.
Rick Wise
Gotcha. I'm going to be selfish and ask one more if I could.
As I look at the year as a whole on a revenue basis, I'm right in the middle of your $125-$130 million range, that's my number. You just beat my second-quarter number by $2.8 million.
Just help us think through, one, what do I do with the $2.8 million? Or just help me think about the cadence of the second half.
Is because of seasonality or anything else? Is the third quarter more likely in line with this second-quarter performance for some reason, or it's all going to come home in the fourth, or I just want to make sure we know what to do with these moving pieces in a thoughtful way.
Renee Gaeta
It's a great question. I would certainly anchor to your comments around there is an element of seasonality within MedTech in Q3.
I would say that that's also driven by census of what's happening in our hospitals customers. Effectively, certainly Q4 is a stronger quarter for us, is how I would sort of frame it, that, yes, we've kept the full-year guide, so that's the full-year number that we are targeting towards.
While we don't give guidance to the quarters, certainly your thinking about could potentially that the Q3 be impacted by some seasonality, and we would expect a stronger Q4, that is an appropriate assumption. Also
Leslie Trigg
because there's sometimes in Q4 some positive seasonality on the capital sales side, right? For capital equipment businesses like ours, you often see a stronger Q4 as hospitals and health systems spend through budget prior to year-end.
Rick Wise
Great. Thank you so much, and good to see.
Leslie Trigg
Yes, thank you.
Operator
Thank you. We will now take the next question.
The next question comes from the line of Josh Jennings from TD Cowen. Please go ahead.
Hi, this is Brian here for Josh. Thank you for taking the questions.
On HCA, I'm not sure what constitutes specifics, but can you speak broadly about the phasing of the agreement across the three years? I guess my question is really, is it fair to assume that 2027 will likely be the biggest year for revenue recognition from the agreement?
Renee Gaeta
Brian, it's a great question. You're not the only one to ask it.
I would say, we certainly are working very closely with HCA. As you pointed out, it goes all the way through 2028.
We have visibility to 2026 and, of course, our revenue guidance numbers has factored that in when we reiterated guidance for the year. Beyond that, we look forward to providing 2027 guidance at the appropriate time when we do that consistently every year.
Effectively at this point, not going to speak to how much of that is going to be in '27 or '28. Look, I also look forward to having other agreements, other refresh opportunities that we've now started to highlight and think that we're entering this cycle with our customers, as well as continued penetration in existing accounts, such that it isn't necessarily one item that we're going to be highlighting or speaking to.
We've got a robust pipeline, a robust customer list and dynamics and plenty of opportunity to penetrate into customers that we have in hand today.
That makes sense. Thank you for that.
Maybe changing topics to next-gen Tablo, what's been the feedback to date from the initial users, and can you remind us of the milestones you're looking forward to achieve in order to transition to a full launch?
Leslie Trigg
Sure, I'm happy to take that, Brian. This is Leslie.
We are working on the pilot phase right now and looking forward to a full launch. I think maybe taking a half step back, philosophically speaking, given the significance of this update, we obviously want to make sure we really, really, really get this right, and that the experience out of the gate goes exactly as expected, just given the size of the installed base and the size of the customer base that we support.
Now Tablo and our team support about a million treatments a year. It's critically important to kind of take a very measured approach to the rollout and focus on doing it well versus quickly.
The sales team has started to educate our customers about the benefits and the value, and in terms of the other part of your question about what's the receptivity, we are hearing a lot of enthusiasm. The why behind that enthusiasm, health systems really are increasingly looking for medical devices that meet FDA's highest cybersecurity bar, as we do.
This next-gen release is also packed with a couple of really kind of cool new features and functions that both improves the user experience, the clinician experience, but also day-to-day device performance that we're excited about as well. We do expect customer receptivity to be high when we progress to full launch, which we're excited to do.
In terms of the metrics that we're looking for, obviously, I'm not going to get into a ton of detail just for competitive reasons about that, but with any new release, whether it's software, hardware, in this case, both, we're going to make sure that, as mentioned, the user experience, the user feedback, the performance of the system, and the performance of the update are as absolutely perfect as they can possibly be. We will be looking to metrics and data coming out of the pilot phase to ensure that it's meeting the mark before we roll it out in full.
Terrific. Thank you, both.
Leslie Trigg
Thank you.
Operator
Thank you. That was our final question for today.
I will now hand back to Leslie for final remarks.
Leslie Trigg
Thank you, and thanks to all of you for joining today. I'd like to close by thanking our customers and our team for the difference that they make every day in the lives of dialysis patients.
Thank you again, and have a great evening.
Operator
Thank you. This concludes today's conference call.
Thank you for participating. You may now disconnect.