Douglas Dynamics, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 3, 2026
Operator
Good day, and welcome to the Douglas Dynamics Third Quarter of 2026 Earnings Call. All participants will be in a listen-only mode for the duration of the call.
Should you need any assistance today, please signal a conference specialist by pressing the star key followed by 0. After today's presentation, there will be an opportunity to ask questions.
To ask a question, you may press star then 1 on your telephone keypad. To withdraw a question, you may press star then 2.
I would now like to turn the call over to Nathan Elwell, Vice President of Investor Relations. Please go ahead.
Nathan Elwell
Thank you. Welcome, everyone, and thank you for joining us on today's call.
Before we begin, I would like to remind you that some of the comments that will be made during this conference call, including answers to your questions, will constitute forward-looking statements. These forward-looking statements are subject to risks that could cause actual results to be materially different.
Those risks include, among others, matters that we have described in today's press release and in our filings with the SEC. Please note the quarterly fact sheet can be found on our IR website.
Joining me on the call today is Mark Van Genderen, President and CEO, and Sarah Lauber, Executive Vice President and CFO. Mark will provide an overview of our performance, followed by Sarah reviewing our financial results and guidance.
After that, we'll open the call for questions. That said, I'll hand the call over to Mark.
Please go ahead.
Mark Van Genderen
Thanks, Nathan, and welcome, everyone. What can we say?
Far, 2026 has been a great year for the company. In fact, we've already achieved the highest adjusted earnings in our company's history.
We still have one quarter to go. We're entering the winter season with strong momentum.
Before Sarah and I talk about these results, though, I want to offer a heartfelt thank you to our teams across the organization. Their commitment and willingness to go above and beyond to get equipment shipped and trucks out the door have made these results possible.
I'd also like to take a moment to offer my appreciation to the dealer network representing our six brands. For many, this is their busy time of the year as they're working hard installing new snow equipment on trucks, UTVs, tractors, skid steers, and front-end loaders in preparation for the winter.
Now, I may be biased, but we have the best, most dedicated dealer network in the world. It's that dedication from our employees and dealers that's reflected in performance that continues to exceed our expectations, both for the quarter and year-to-date.
Let's talk about this quarter, where we really saw a continuation of recent trends. The headlines from the quarters are clear: Work Truck Attachments generated record third quarter results based on a combination of the robust pre-season demand we communicated over the past several months and continued strong execution by our teams; and Work Truck Solutions delivered record top-line results this quarter, driven by ongoing strength in municipal demand.
These results highlight the earnings power of our business with favorable market conditions and the effectiveness of the strategic actions we've taken over the past several years to enhance our capabilities, improve our resilience, and position the company for sustained growth. All right, there are really three key factors that continue to underpin our performance this year: First, an outstanding pre-season order cycle at attachments following an above-average snowfall winter, including unprecedented demand for parts and accessories, which underscores the strength of our market position and the value we deliver to our customers.
Second, sustained demand for our municipal-focused products and solutions, coupled with targeted investments that are expanding our ability to capture growth opportunities. Third, our teams have consistently delivered strong operational performance, responding effectively to customer demand in the near term while maintaining focus on the initiatives that advance our long-term strategic objectives.
Let's review the segment results, starting with Work Truck Attachments. Looking at the numbers, there are a lot of very large percentage increases, the details of which Sarah will share later in the call.
Suffice it to say, it was a record quarter, exceeding our expectations and allowing us to increase our guidance. The combination of the excellent pre-season demand with the robust operational execution from our team led to higher throughput.
This quarter also includes the contributions of Venco Venturo, which we acquired last November. One number I will point out is the almost 24% adjusted EBITDA margin we produced year-to-date in the attachments segment, which stems from higher demand, throughput, and strong product mix.
Now, this is just one data point, but it clearly shows that when we see the demand, our team steps up, executes our plans, and our margins follow, putting us right in the wheelhouse this quarter of the mid-20s margin we have been targeting for the attachments segment. Now, we aren't expecting these results every quarter going forward, but it's a great sign of the progress we've been making.
Our teams did an excellent job delivering the second half of our pre-season orders. Based on the ordering patterns we've observed and our most recent dealer checks, it is clear that dealer inventories earlier this year were substantially lower than where they have been in recent years.
The orders we've seen this year have likely helped to replenish dealers' stock of snow and ice control equipment. Even so, our plans include building more finished goods inventory compared to last year so that we have enough product available and ready to ship when the winter weather arrives.
When it comes specifically to parts and accessories, the results are even more outstanding. As we explained last quarter, after achieving record P&A sales and shipments in 2025, we've already surpassed that level in the third quarter this year, significantly exceeding our expectations.
It's fair to say that we haven't had this kind of surge in demand for quite some time, and we are proud of the way our attachments team has stepped up to meet this demand. They've responded with a tremendous effort to increase production and ship the equipment, parts, and accessories as quickly and efficiently as possible.
Overall, it's already been an amazing year so far for attachments, better than anyone can remember, and we remain optimistic regarding the fourth quarter, next year, and beyond. In fact, 2027 is going to bring some exciting changes for attachments.
The line of pusher plows we've rolled out over the last two years is really starting to gain traction, and we're on track to start taking orders next year for the sidewalk machine we've developed in partnership with John Deere. Two weeks ago, we showcased this vehicle at the annual Equip Expo in Louisville, Kentucky, allowing many prospective customers the chance to ride it.
In talking with them, their feedback to us was outstanding, and it continues to generate a lot of interest from the dealers in our network and in John Deere's dealer network as well. Congratulations to everyone at attachments, and here is to a great upcoming winter season.
All right, turning to Work Truck Solutions, where the teams once again produced record top-line results. This achievement is particularly notable given the increasingly difficult comparisons we face after several years of strong growth and record performance, including a record third quarter last year.
The strength of these results reflects the sustained, healthy demand we're seeing across our municipal end markets. As we've said before, demand is only part of the story.
During the years when constrained chassis availability limited our throughput and efficiency, our municipal teams invested significant effort in continuous improvement initiatives, operational efficiencies, and process enhancements that are paying dividends today as volumes increase. DDMS, or the Douglas Dynamics Management System, is the foundation for the innate drive to get better every day.
While our continuous improvement efforts may not have been front and center recently as we focused on our strategic initiatives, make no mistake about it, DDMS projects and the philosophy in general remain a crucial part of Douglas Dynamics. At the same time, we're making targeted investments to support future growth and help meet increasing customer demand.
Our new purpose-built facility in Missouri is now operational and contributing toward expanding capabilities. It's achieving exactly what we'd hoped: increasing capacity while helping to drive new business in the state.
In addition, I was recently at Henderson's headquarters in Manchester, Iowa, and I can tell you firsthand that our new logistics facility remains on track to open before year-end. This move will make us even more efficient in responding to customer demand as well as freeing up valuable space at our primary manufacturing location, further improving throughput and operational efficiency.
The relocation of our Ohio outfit center is also progressing well. The larger, purpose-designed location is better suited to our operational needs, provides additional capacity, improves workflow efficiency, and creates a better working environment for our team members.
This change will move Ohio from being our oldest outfit center into one of our newest and most efficient. Collectively, these highly cost-effective investments strengthen our capabilities and position us to capitalize on the growth opportunities we see across our markets.
Just as importantly, these improvements have enhanced our ability to offer industry-leading lead times and consistently deliver on our commitments to customers. That reliability has become a meaningful competitive advantage.
Combined with our U.S.-centric business model, which continues to resonate strongly with municipal customers, we remain confident in the long-term outlook for our municipal operations. Turning to our commercial operations, where we continue to see many of the same trends we discussed last quarter: While demand remains uneven, with pockets of strength offset by areas of caution, the overall measured purchasing activity of end users continues to impact our growth expectations for the business.
In response, we have better aligned our cost structure with current conditions, preserving profitability wherever possible while maintaining the flexibility to capitalize on opportunities. It's encouraging that our dealer network continues to demonstrate resilience across select product lines, and we are working with our OEM partners to schedule chassis delivery to complete these builds.
Although fleet demand remains relatively subdued, we are beginning to see an increase in smaller orders, which bodes well for next year. Taken together, the strength of our municipal operations and the resilience of our commercial business position us to deliver another year of solid performance that remains near the record levels we have achieved in recent years.
With our third quarter results covered, let me switch gears a minute to talk about our ACTIVATE strategic priority. Today marks the one-year anniversary of the Venco Venturo team joining Douglas Dynamics.
As our first acquisition in almost 10 years, we are encouraged by how well the business has integrated and how closely the culture has aligned with our organization. This addition represents exactly the kind of opportunity we envisioned when we established the ACTIVATE strategic priority.
Over time, we remain committed to building a diversified portfolio of complex work vehicle attachments that require professional outfitting and complement the core capabilities and continuous improvement principles which have been hallmarks of our company for over 80 years. Over the past year, we've seen growing recognition across the industry and potential partners of what we are seeking to accomplish through our ACTIVATE strategic pillar.
As a result, we've engaged in a broader range of compelling conversations. That said, while activity levels have increased, our approach to M&A remains disciplined.
We will continue to be highly selective and focused on opportunities that are strategically aligned and capable of creating long-term value. In summary, this quarter was characterized by strong execution, which is clearly reflected in our results.
Far in 2026, we have already broken records and are on track to break more. We're just getting started.
We're building on the momentum with a compelling strategy for future growth, and we are confident in both the course we are charting and our ability to execute it in the years to come. There is a lot we aim to accomplish.
With that, I'd like to pass the call to Sarah.
Sarah Lauber
Thanks, Mark. As a reminder, unless stated otherwise, all the comparisons I'll make today are between the third quarter of 2026 and the third quarter of 2025.
I want to start by thanking our team. They really went above and beyond this quarter, delivering record third quarter performance.
As Mark said, we're going to be saying record quite a lot today. In summary, Work Truck Attachments produced record third quarter results based on robust pre-season demand and strong operational execution.
Work Truck Solutions delivered record top-line results, with strong profitability led by another quarter of robust demand in our municipal end markets. The strength of these results have allowed us to increase our guidance ranges, which I'll walk through later.
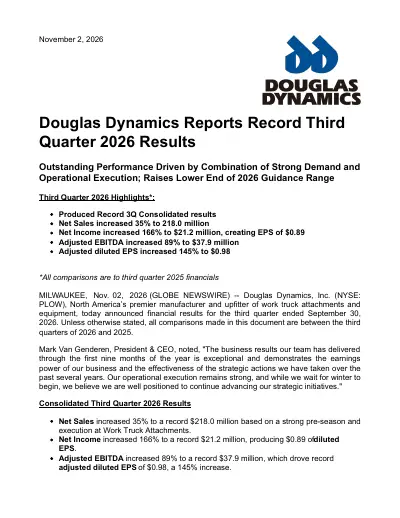
Let's start by looking at the third quarter. On a consolidated basis, net sales increased 35% to a record $218 million, and gross profit grew 57% to $59.8 million.
SG&A expenses increased 19% to $28.6 million. The change in SG&A this quarter was driven by higher stock and incentive-based compensation on increased earnings, increased legal costs, and higher wages due to increased head count, including the addition of the Venco Venturo employees, as well as higher rent costs.
Adjusted EBITDA increased 89% to a record $37.9 million, with margins increasing 500 basis points to 17.4%, which drove record adjusted diluted earnings per share of 98 cents, a 145% increase. Let's look at the results for the two segments.
Work Truck Attachments delivered a record third quarter, exceeding our expectations once again. Demand for equipment and parts and accessories continued to outpace our projections this quarter as dealers stocked up in time for their retail season.
Net sales increased 78% to a record $121.5 million, as robust pre-season demand was matched by the best-in-class operational execution from our teams, plus the addition of Venco Venturo, which we acquired a year ago today. As we expected, the ratio of pre-season shipments was close to a 50-50 split between 2Q and 3Q this year, compared with a 60-40 split last year.
The strength of demand for parts and accessories continues to surpass expectations at almost unprecedented levels. As we predicted in August, year-to-date P&A shipments have now exceeded the previous annual record that we set last year.
Our team matched the strength of demand with equally strong execution. Higher throughput, positive product mix, plus the shift in timing of shipments between quarters led to a 188% increase in adjusted EBITDA to $30.1 million.
Margins increased dramatically by 940 basis points to 24.8%, which really highlights the earnings power this team can drive when demand is strong. All told, amazing performance from Work Truck Attachments.
Turning to Work Truck Solutions, after several years of delivering dramatic improvements and record results, the Solutions team continues to perform well, with net sales increasing by 3% from a record $94 million last year to a new record of $96.5 million this year. While not quite as strong as last year, our adjusted EBITDA of $7.8 million was still very healthy this quarter.
It's worth noting the Solutions business can be choppy. We do expect margins to fluctuate from quarter to quarter.
The important point is we expect Solutions margins to be in the double digits for both the fourth quarter and the full year. The third quarter results are based on continued strong demand and throughput from our municipal customers.
This helped to somewhat offset the inconsistent demand from our commercial customers, which is impacting throughput and efficiency on that side of the business. With our overall backlog still well above historic norms, the full year outlook remains positive.
We do expect to show annual top-line improvement for the segment once again this year. Overall, we're pleased to report another great quarter for Solutions.
With the results for the quarters covered, let's turn to the balance sheet and liquidity. Net cash used in operating activities year-to-date increased $26.3 million to $47.5 million, as working capital increased to support demand across both segments.
Year-to-date free cash flow decreased approximately $29.4 million to negative $58.7 million. The main factors were increased receivables driven by higher net sales and higher inventory, which was needed to meet demand.
At September 30th, we maintained $34 million of total liquidity, comprised of $5.5 million in cash and $28.5 million of available capacity on our revolver, which is more than ample for our needs this year. Year-to-date capital expenditures increased by $3.1 million to $11.2 million, as we invest in the business to drive additional growth.
For the full year, we expect CapEx to be within our traditional relatively modest range of 2% to 3% of net sales. There are no changes for our capital allocation priorities.
We're committed to returning excess cash to shareholders, and on a year-to-date basis, we've returned over $27 million through the combination of our strong dividend and share repurchase program. With that said, let's review our updated outlook.
It's fair to say that our performance this year continues to generate stronger than expected results. Through the first nine months of the year, we've already surpassed two data points: First, we've achieved results above the midpoint of our original full year adjusted earnings per share guidance issued in February.
Second, we've already beaten our previous full year adjusted earnings per share record, which was set back in 2019. Based on the strength of our year-to-date performance and the visibility we have into the fourth quarter, we're comfortable raising the lower end of our guidance ranges.
As we typically establish relatively broad guidance ranges in February and then refine them as the year progresses and visibility improves. This year, we've raised our guidance three separate times since our initial outlook in late February.
That's highly unusual and highlights just how positive this year has been. We have already delivered record adjusted earnings per share.
Clearly, with one quarter still to go, 2026 will be a banner year for our company. In many respects, the progress we have achieved this year has accelerated our trajectory, achieving in 2026 what we originally anticipated accomplishing in 2027.
The logical question is, why has this year been so strong? The rapid acceleration of our earnings is based on two points: One, the Solutions segment has demonstrated that the improvements that they've delivered in recent years can be repeated, remaining on track to be near their record performance from 2025.
Second, following the improved snowfall last winter, the Attachments segment saw a surge in demand this year, more than we originally expected, particularly for parts and accessories. This was met with first-class execution from our teams.
We've said it before, but it's worth repeating: you can have all the demand in the world, but that doesn't matter if you can't manufacture and ship the products efficiently, and our teams have done just that. Hats off to both segments for their ability to execute so far this year.
With all that said, here are the updated guidance numbers: We raised the bottom end of our net sales guidance range by $5 million and now expect 2026 net sales to be between $770 million and $805 million. We increased adjusted EBITDA by $3 million, with the new range of $123 million to $135 million.
We increased adjusted earnings per share guidance by 10 cents, with a new range of $3 to $3.40. The effective tax rate is still expected to be approximately 24% to 25%.
It's worth reiterating that these guidance ranges indicate that we are on track to achieve annual margins in the low 20s for Attachments while maintaining low double-digit margins for Solutions. As always, this assumes average snowfall in the fourth quarter.
While we're pleased with our progress, it's important to remember that the fourth quarter for our Attachments segment can see meaningful variability. An early and severe start to winter across our core markets leads to reorders of both equipment and parts and accessories, but the inverse is also true.
We can't control the weather, but we can control how we operate, and we will continue to drive strong throughput for both manufacturing and outfitting to maximize our performance. At this point, visibility into 2027 remains limited for many reasons, starting with the upcoming winter.
The stronger than average snowfall we experienced last winter has been an important underlying factor contributing to our record 2026 performance. Assuming snowfall patterns return to historical averages this winter, our early view suggests that under the right operating conditions, we are positioned to replicate our anticipated 2026 performance again in 2027.
In closing, we executed effectively and are very pleased with our exceptional year-to-date results. We feel well-prepared, and we will be monitoring reorder patterns closely as winter weather approaches.
With that, we'd like to open the call for questions. Operator?
Operator
We will now begin the question-and-answer session. To ask a question, you may press star then 1 on your telephone keypad.
If you're using a speakerphone, please pick up your handset before pressing the keys. Again, if you'd like to withdraw a question, you may press star then 2.
At this time, we will take our first question, which will come from Mike Shlisky with D.A. Davidson.
Please go ahead.
Mike Shlisky
Yes, hi, good morning. Thanks for taking my question.
Sarah Lauber
Sarah,
Mike Shlisky
you touched on this briefly -- Good morning. at the end of your comments there, you just touched on this briefly, but this does seem to be a pretty big question among investors.
I think folks want to know about the earnings cycle. It's been a great year in '26, but assuming average weather, could there be a chance that '27 could actually beat '26?
I guess I'm trying to figure out the volume of snowplows that are being sold in '26, is that actually average? Has been the pricing and the other brands, the other and solutions and so forth that's been a driver, Henderson, and so forth.
Trying to figure out whether you have a better '26, a better '27 outlook, is there is a good chance that '26 is actually not the earnings peak? Just some thoughts around that would be appreciated.
Mark Van Genderen
Mike, it's Mark. I'll take that, and then I can toss it over to Sarah and see if there's anything she wants to add.
There's no doubt we're having a really strong 2026, and we had a great winter last winter. We're also doing a lot of modeling that's looking at our snowplow sales over multiple years, not just what happened in the last year.
As we're doing that, we see a few years ago what plow sales were. We see what last winter looked like, with an average winter.
Sarah said it in the call, we're not going to make any predictions right now, because certainly there's a lot of things that can happen. We see a path to 2027.
P&A may come down a bit. We could see additional plow sales going up, see strength in the municipal side.
All in all, when we look at our projections, again, with a lot that still needs to be determined, we don't look at 2026 and saying, "Oh, that's going to be our high-water mark, and we're going to go down from there." We think there's opportunity for us to build off the strength of 2026 going forward, with a lot, of course, that is still unknown, primarily related to what happens with snowfall.
Sarah Lauber
I guess the only thing I'd add there, Mike, is as I said in the script, '26, banner year. Hitting that again in '27, it will be a high-water mark.
Assuming average snowfall, we really think that there is a shot that we are right at that level again. As when we go out with our guidance in February, we will know more, and that range will encompass either lower snowfall and/or higher snowfall.
I guess to get at your question on the capability of going higher, operationally and capacity-wise, we absolutely have the wherewithal to do that, very much going to be dependent on what we see from a snow perspective.
Mike Shlisky
Got it. If I can just follow up there, just a few quick details.
Again, very solid year for your core snowplow business. If I recall correctly, Dejana not as robust, but is chances for that to have a come back in '27.
Henderson, I would love to hear if you have a comment on their backlog through '27. You already took comments they're going to see growth in that business already based on what you've booked.
Of course, the ongoing DDMS. It just seems like all the pieces are in place assuming average weather that this is not going to be the peak year in '26.
I'd love to hear some of the details I just mentioned, kind of your thoughts on those comments.
Sarah Lauber
I think you have a good assessment on the points that you made. Dejana, we have room for improvement and strength, as if we see more strength on the demand side.
Henderson, we have a good runway with the backlog, and that team's been operating well, and we're bringing in capacity. Then again, average snowfall, we have the wherewithal, the operations, the capacity to deliver.
The one area that you did not have in your bullet points, which does drive higher margins, is the P&A that we are experiencing this year. We've already surpassed the record.
Fourth quarter remains to be seen on a P&A perspective, but as I sit here today, I would not expect to repeat the same P&A performance next year.
Mike Shlisky
Okay. Thanks for that color.
Maybe one last one for me. Do you hear indications that there are fleets that are at this point planning a multiyear snowplow replacement program?
I guess, in other words, they are buying this year either because there's great cash or there was good snowfall last winter. Are they planning ahead for '27 already, either based on there's a limited dealer supply for this year or they're just trying to get their financial planning kind of in order on a multiyear basis?
I'm curious whether you've got a bit of visibility at this point in the year towards '27 as far as some fleet plans versus what is typical in your business.
Mark Van Genderen
Mike, I would say so. When we look at some of the work we've taken on over the last year or two as it relates specifically to forecasting and demand planning, we really migrated away from simply looking at last year's sales and snowfall as the primary driver to the upcoming year, and digging a lot deeper into understanding what plow usage is over a multiyear period, in some cases down to the specific geographic level where we can match up where we sold plows to dealers and what the weather looked like.
In some places, we know plows haven't been used as much the last several years where it didn't snow. New York was a good example for a couple years.
They didn't see measurable snowfall for I think 600-and-some-odd days. Then you've got other years or other locations like Buffalo and Erie and others.
That level of detail that we're now evaluating with this great team allows us, I think, to do a better job looking out into the future. All that being said, yeah, we think we've got, there's the opportunity for us to continue to have decent sales as we look at the upcoming years assuming average snowfall.
On the municipal side, this is an area that is, I'd say, more weather-resistant or less snowfall-dependent because the municipalities are using those trucks year-round regardless. It's really more on, again, the replacement cycle for the truck and how it's been used, the municipal coffers.
When we look at the backlog there, and we are planning out with municipalities and with state DOTs over a one-, two-, three-year period, when we talk about that backlog, that's where we like to see it, maintain a very healthy backlog. As we've shared before, backlog doesn't mean that those are all trucks that municipalities and state DOTs want right now.
That backlog can include a contract that goes out multiple years where a state may say, "Hey, you know what, I want 225 trucks. I want 75 each of the next three years."
The key with what we're doing and what Chad and his team have done, and are really, really well at Henderson, is making sure that we're shortening the lead times as much as we can to meet the needs of those end users, but then at the same time, if they say they want 10 trucks on March 5th of 2028, that on March 5th of 2028, they've got 10 trucks delivered to them.
Mike Shlisky
Got it. Thanks so much for all that color.
Really appreciate it, and I'll pass it along.
Sarah Lauber
Thanks, Mike. All right.
Operator
Again, if you have a question, you may press star then 1 to join the queue. Our next question will come from Robert Schultz with Baird.
Please go ahead.
Robert Schultz
Hey, good morning.
Sarah Lauber
Good morning.
Robert Schultz
Maybe starting off here, what's implied in the updated guidance ranges for Q4 by segment from a top-line and EBITDA perspective at midpoint of ranges?
Sarah Lauber
Oh, sorry, Bobby. The updated guidance, essentially when you look at the fourth quarter, relatively flat to up slightly in total for the company.
Flat, I've been talking about on the Solutions flat side, relatively flat for the year on Solutions, but for the quarter, we do have growth year-over-year. I mentioned in my script that I expect double-digit margins for the fourth quarter and for the full year.
Then the big one being the fourth quarter, because that's always more challenging for us from a seasonality perspective, last year, if you recall, was a strong fourth quarter. When you look at our midpoint for our guidance, what we're expecting for this year, I would say flat on a dollars perspective from EBITDA, but we don't necessarily expect the whole goods inventory to be at the same level as they were last year, because that was above-average snowfall in the fourth quarter last year.
Robert Schultz
Got it. Then, moving to attachments here, maybe beyond inventory levels, how do you characterize dealers' financial capacity and willingness to place in-season orders should we see normal snowfall this season?
Are things like financing costs or credit availability affecting any stocking decisions?
Mark Van Genderen
We don't necessarily have visibility into our dealers' financials from a quantitative standpoint, but qualitatively, having spent time with dealers down at Equip Expo and talking with them and our sales teams out there, talking with our credit teams here, dealers' health right now is very strong, especially coming off of last winter. Then remember that many of our dealers are also selling green products as well.
They've reported that they're doing well. We're seeing, as evidenced by the results that we're sharing, not just the pre-season is strong, but reorders coming in, too.
Overall, I would say we're pretty pleased with where our dealers are from a health standpoint. I can tell you that in talking with them, they're excited about the sales that they've seen through the dealerships to end users, putting product on the machines, and certainly getting ready for what we all hope to be is another at least average snowfall winter across our core markets.
Robert Schultz
Awesome. Thanks, guys.
I'll leave it there.
Sarah Lauber
Thanks, Bobby.
Operator
Again, if you have a question, you may press star then 1 to join the queue. With that, we will conclude our question-and-answer session.
I'd like to turn the call back over to Mark Van Genderen for any closing remarks.
Mark Van Genderen
Thanks. I'll end our call today by thanking you for your ongoing interest in our company, and we look forward to seeing some of you at the Baird conference in Chicago next week.
Thank you.
Operator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect your lines.