Chicago Atlantic Real Estate Finance, Inc.
NNASDAQ:REFIQ1 FY2026 · Earnings Call TranscriptMay 7, 2026
Operator
Good day, and welcome to the Chicago Atlantic Real Estate Finance, Inc. first-quarter 2026 earnings conference call.
As a reminder, all participants will be in the listen-only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero.
After today's presentation, there will be an opportunity to ask questions. To ask a question, you may press star, then one on a touch-tone phone.
To withdraw your question, please press star and then two. Please note that this event is being recorded.
I would now like to turn the conference over to Lisa Kampf. Please go ahead.
Lisa Kampf
Thank you. Good morning.
Welcome to the Chicago Atlantic Real Estate Finance conference call to review the company's results. On the call today will be Peter Sack, Co-Chief Executive Officer, David Kite, President and Chief Operating Officer, and Phillip Silverman, Chief Financial Officer.
Our results were released this morning in our earnings press release, which can be found on our Investor Relations section of our website, along with our supplemental filed with the SEC. A live audio webcast of this call is being made available today.
For those who listen to the replay of this webcast, we remind you that the remarks made herein are as of today and will not be updated subsequent to this call. During the call, certain comments and statements we make may be deemed forward-looking statements within the meaning prescribed by securities laws, including statements related to the future performance of our portfolio, our pipeline of potential loans and other investments, future dividends, and financing activities.
All forward-looking statements represent Chicago Atlantic's judgment as of the date of this conference call and are subject to risks and uncertainties that can cause actual results to differ materially from our current expectations. Investors are urged to carefully review various disclosures made by the company, including the risks and other information disclosed in the company's filings with the SEC.
We also will discuss certain non-GAAP measures, including, but not limited to, distributable earnings. Definitions of these non- GAAP measures and reconciliations to the most comparable GAAP measures are included in our filings with the SEC.
I'll now turn the call over to Peter Sack. Please go ahead.
Peter Sack
Thank you, Lisa. Good morning, everyone.
This quarter, Chicago Atlantic reported a quarter of consistent results against a backdrop of continuing concerns in the private credit market, the Fed pausing the interest rate easing cycle following three consecutive rate cuts in Q4 of last year, and volatility caused by the Middle East conflict. This quarter's results reflect the strength and resilience of our business model.
We are a leading capital provider in the cannabis ecosystem. Our experience in this industry provides us with the expertise, relationships, and ability to redeploy capital more quickly than the typical mortgage REIT.
Our rigorous underwriting and stringent risk standards, led by our cannabis-focused underwriting, real estate, and analytics team, ensures an acceptable risk versus reward. I continue to be optimistic about the current environment.
The pipeline of cannabis opportunities remains strong and currently stands at $482 million, of which approximately $133 million of this pipeline is backed by real estate collateral. Given the recent medical rescheduling news in late April, I'd be remiss in not highlighting the latest major federal initiative in policy setting for the cannabis industry.
The Department of Justice announced on April 23rd that it is rescheduling certain medical marijuana products to Schedule 3 from Schedule 1. This is the most significant federal policy change in years and perhaps in the history of the industry.
There are nuances to work out as we wait for more definitive framework and how this policy will apply to existing individual state laws, and we expect these policy changes to impact each operator differently based on their medical market exposure. After many years of delays, this is a tremendous step in the right direction.
How we expect to immediately benefit from this order is predominantly through the elimination of the extra tax burden on cannabis companies resulting from Section 280E, and retrospective relief on legacy tax liabilities that should improve operator cash flows and strengthen balance sheets, driving higher valuation multiples and improving the credit profiles of our borrowers. The federal order requires and sets up an expedited process for state-licensed medical cannabis operators to register with the DEA, and in effect, legalizing state-licensed medical cannabis on a federal level.
Additional benefits from this would be lowering barriers to U.S. exchanges, for which we have been an advocate.
An administrative hearing is scheduled for June 29th to July 15th. This hearing provides a pathway to reschedule cannabis more broadly, possibly rescheduling adult-use products.
We will continue to be measured in our outlook for a positive outcome and not jump ahead to any conclusions. We believe Chicago Atlantic is well-positioned to benefit from the initial order, and as I've stated before, the success of our strategy is not dependent on any of these changes.
We have remained conservative and underwrite every investment assuming no regulatory-driven credit improvements. Leading up to the June 29th hearing, we've begun forecasting for a range of outcomes from the rulemaking process, but currently remain in a wait-and-see mode.
Overall, REFI delivered consistent, stable financial results for the first quarter of 2026 against an unstable macro environment. Our differentiated business model, lending to operators and property owners in the cannabis industry, enables us to operate in a niche market with limited competition with favorable terms and delivering competitive yields.
This year is proving to be a transformative time for the cannabis industry following the federal government's rescheduling medical marijuana from Schedule 1 to Schedule 3 and the potential for broader policy shifts for cannabis later this year. We are encouraged by the validation of our business model and the potential impact of regulatory orders flowing through to REFI.
I look forward to updating you on our progress throughout the rest of this exciting year. David will now speak to the portfolio in greater detail.
David?
David Kite
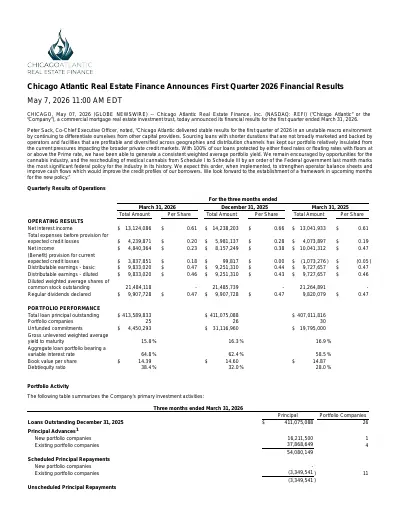
Thank you, Peter. As of March 31, our loan portfolio principal totaled approximately $414 million across 25 portfolio companies with a weighted average yield to maturity of 15.8%, compared with 16.3% for the fourth quarter of 2025.
Gross originations during the quarter were approximately $54 million of principal fundings, of which $16.2 million and $37.8 million were funded to new borrowers and existing borrowers, respectively. These were offset by approximately $52 million of repayments, comprised of $3.3 million in scheduled amortization payments and $48.2 million from full and partial loan prepayments.
As of March 31, 2026, approximately 10.7% of our portfolio is risk rated 4 or higher, compared with 4.8% as of December 31, 2025. This risk rating shift, primarily attributable to loan number 36 being downgraded from 3 to a 4, contributed to an increase in CECL reserves of approximately $3.8 million.
As I mentioned on our last call, we made significant progress on loan number 9 last quarter, funding an advance for the borrower to allow for accretive acquisitions. As of December 31, 2025, the loan was brought current, and as of March 31, we're pleased to announce that we've moved the loan back to accrual status after three consecutive months of timely payment and demonstration of sustained performance improvement, which we expect to lead to the ability to continue to meet debt service obligations.
This is a prime example of how we utilize the operational and workout expertise amongst our team and the broader Chicago Atlantic platform, using creativity and deal management to drive successful turnaround efforts. As of March 31, 2026, approximately 4.8% of our portfolio is on non-accrual status, a decrease from approximately 11.1% as of December 31, 2025, primarily relating to the restoration of loan number 9 to accrual.
As of March 31, 2026, our portfolio consisted of 35.2% fixed-rate loans and 64.8% floating-rate loans. 71.9% and 28.1% of floating-rate loans are benchmarked to the prime rate and SOFR, respectively.
With the current prime rate at 6.75, 100% of our prime rate loans are at their floors, and in total, approximately only 4% of our loan principal is exposed to further rate declines across the total portfolio. Importantly, our floating-rate loans are not exposed to interest rate caps, which, combined with our rate floor protections, provides a structural advantage in portfolio construction that compares favorably to most other mortgage REITs.
Total leverage equaled 38% of book equity at March 31, compared to 32% as of December 31. As of March 31, we had $67.1 million outstanding on our senior secured revolving credit facility and $49.4 million outstanding on our unsecured term loan.
As of today, we have approximately $59 million available on the senior credit facility and total liquidity, net of estimated liabilities, of approximately $54 million. I'll now turn it over to Phillip.
Phillip Silverman
Thanks, David. Our net interest income of $13.1 million for the first quarter represented a $1.2 million or 8% decrease from $14.2 million during the fourth quarter of 2025.
The decrease was primarily attributed to the fourth-quarter collection of past-due unaccrued interest on loan number 9, totaling $1.7 million, which was recognized last quarter. Total interest expense, including non-cash amortization of financing costs for the first quarter of 2026, was approximately $2 million, an increase from $1.8 million in the fourth quarter.
The weighted average borrowings on our revolving loan increased to $48 million, compared to $33.6 million during the fourth quarter. Our CECL reserve on our loans held for investment as of March 31st, 2026, was approximately $8.7 million.
On a relative size basis, our reserve for expected credit losses represents 2.1% of our outstanding principal of our loans held for investment. The reserve increased by approximately $3.8 million from the fourth quarter, primarily due to increases in LTV attributed to specific loans, primarily loan number 4, 34, and loan number 36.
On a weighted average basis, our portfolio maintained strong real estate coverage of 1.2 times. Distributable earnings per weighted average share on a basic and fully diluted basis were approximately 47 cents and 46 cents for the first quarter.
In April, we distributed the fourth-quarter dividend of 47 cents per common share declared by our board. Since inception, the company has distributed $8.94 per common share in dividends, which represents a yield on cost of approximately 11.8% when measured against our IPO price.
Our book value per common share outstanding was $14.39 as of March 31st, 2026, and there were approximately 21.5 million common shares outstanding on a fully diluted basis as of such date. During the subsequent period from April 1, 2026 through today, the company advanced new gross loan principal of approximately $15.8 million, comprised of $13.1 million advanced to one new borrower and $2.7 million to existing borrowers on delayed draw on existing credit facilities.
Additionally, the company received a total of $14.3 million in loan repayments, comprised of $1.8 million of scheduled amortization and $12.5 million in early prepayments, which included the full repayment of loans number 6 and number 30. We expect to continue to maintain a dividend payout ratio based on our basic distributable earnings per share of 90% to 100% for the 2026 tax year.
If our taxable income requires additional distributions in excess of the regular quarterly dividend to meet our taxable income requirements, we expect to meet that requirement with a special dividend in the fourth quarter. Operator, we're now ready to take questions.
Operator
Thank you. We will now begin with the question-and-answer session.
To ask a question, you may press star, then one on your touch-tone phone. If you are using a speakerphone, please pick up your handset before pressing the keys.
If at any time your questions has been addressed and you would like to withdraw your question, please press star, then two. At this time, we will pause momentarily to assemble our roster.
The first question comes from Pablo Zuanic from Zuanic & Associates. Please go ahead.
Pablo Zuanic
Thank you, and good morning, everyone, and thanks, Peter, for the commentary on the regulatory front and of course the positive news that we've been receiving recently. Look, I just want to start with loan number 36.
Obviously, 4 and 34 are Arizona loans, and we know that's a tough market for growers. You mentioned 4 and 34 are in an accruals or a part of the reserve, and in the case of 36, that's an Illinois loan, right?
It's a larger loan, $27 million. Whatever color you can provide more on that loan would be helpful.
Arizona I understand, Illinois of course we've seen 4Front and other companies have issues there, but if you can just give more color on that particular loan number 36 would be helpful, please. Especially in the context that was issued in December 2024, which is not that long ago I think.
All right, thanks.
Peter Sack
Thank you. The Illinois market is experiencing consolidation on the retail front and is experiencing increasing competition on cultivation.
This one in particular has strong real estate coverage and is a vertically integrated operator, and I think the reserving activity reflects our ordinary course evaluation of portfolio company performance and risk. The discussions with the borrower are very constructive, and we expect that this company's performance can be improved and resolved in a constructive and collaborative manner.
I'm hopeful that in the months ahead, we'll find this reserving activity conservative, but regardless, this is part of our ongoing process to show reserving activity that reflects a conservative appreciation of performance and the portfolio.
Pablo Zuanic
Thank you. On the same topic, Peter, can you give an update on loan 4 and 34?
Peter Sack
These continue to evolve. I think it's too early to give specific updates, but they are constructive relationships.
Pablo Zuanic
By the same token, in the case of loan number 9, back into accruals, like you said you were actively involved with them, collaborative basis, I'm just trying to understand the potential for loans in the portfolio that can be equitized or where you can succeed in bringing new buyers to those loans. How should we think about that as an opportunity going forward for the book?
Peter Sack
I think it's important to contrast loan number 9 with other reserving activities in the portfolio, that loan number 9 was a judicial foreclosure process, and that takes a substantial longer amount of time for resolution than when challenging situations within portfolio companies can be resolved constructively and collaboratively. I'd say that the markets for assets that are undergoing challenges have improved significantly over the last year as expectations for rescheduling have moved from speculative to more definitive to, in the case of medical operators, executed.
This is both a environment that is constructive and positive for deploying capital, and for finding solutions within the book, whether that's finding new equity investors executing operational change, or working towards an exit. This is a better environment for both deployment and reorganization and problem solving than really we've seen in the last three years.
Pablo Zuanic
Right. Thank you.
Then on the topic of the unscheduled repayments, thank you for the table you showed in the press release today about $48 million unscheduled repayment in the first quarter, and I think Phil mentioned another $15 million so far in the second quarter. Is that out of the norm?
I'm just trying to understand what's driving those early repayments, or that just normal, par for the course?
Peter Sack
These are par for the course. We've labeled them unscheduled, but unscheduled doesn't necessarily mean a surprise.
These were loans that a few of them were nearing their maturity date.
Pablo Zuanic
Right. Thank you.
Look, a couple of more, and apologies if there's someone else in the Q&A queue. Looking at the 10-Q, loan number 45 in Canada, I don't know if that's the first time you've done a loan outside the US, but can you comment on that, and more in general, opportunities in international, Europe and even more in Canada?
Peter Sack
Maybe the first time that REFI has executed a loan outside the US, but not the first time that Chicago Atlantic as a platform has executed a loan outside the US and in Canada. I think we're finding that in the Canadian market, there has been stabilization of the market in some cases and rationalization of the market in terms of unprofitable operators leaving, and that's given room and air for profitable, well-executing operators to rise to the top, be recognized, to show strong results, and to provide opportunities for lenders to provide capital at very strong risk-adjusted returns.
I think in the past, we haven't seen that opportunity set arise so meaningfully and so specifically and clearly. I think we see this happen in a lot of markets that are oversaturated, that they go through a period of rationalization, and after that rationalization, pockets of opportunity emerge.
Pablo Zuanic
Right. Thank you.
One last one, and I know we've talked about this before--
Operator
Sorry to interrupt, Mr. Zuanic.
May we request you to return to the queue for any follow-up questions, please? Thank you.
You have the next question coming from the line of Chris Muller with Citizens Capital Market. Please go ahead.
Chris Muller
Hey, guys. Thanks for taking the question.
I wanted to ask some clarifications around Schedule 3 that you may or may not know the answers to at this point. I guess, first off, what percentage of your guys' portfolio is medical?
I guess how is that determined? Is that done at the license level, which my understanding is some states have dual-use licenses, or is it determined by the end user being either medical or rec?
Peter Sack
Most of our borrowers that are operating as adult use are also operating as medical operators. Each of them then parse their revenue by medical versus adult use, but of those medical and adult-use sales, in many cases, can be operating out of the same dispensary.
We haven't published what is medical versus adult use. I'm hopeful that within the year of 2026 that it's irrelevant, that the administrative hearings that are scheduled for June and July proceed, that adult use is rescheduled as well, and the industry doesn't have to go through this exercise of analyzing what's medical and what's adult use, that it can proceed to operate each businesses seamlessly.
We shall see. I think if adult-use measures and progress around adult-use rescheduling falters or slows down, then I think you're going to see a lot of work among our borrowers to parse medical versus adult-use operations, to allocate costs optimally between their medical and adult-use operations to maximize tax efficiency.
I think you're also going to see state regulators perhaps adjusting the definitions within their adult-use program to shift more of their operations towards what they can call and designate a medical program. I hope those types of acrobatics are unnecessary because the administration has executed on its pathway to reschedule the entire supply chain.
Chris Muller
Got it. That's helpful, and I think I saw California is doing something along those lines, which I agree with you, hopefully that's irrelevant and full Schedule 3 gets done in June, but we'll see how that plays out.
Then I guess on the CECL reserve increase in the quarter, and I may have missed this in your guys' prepared remarks, but was that increase specific or general reserves? How are you guys thinking about the impact on CECL reserves following Schedule 3?
Peter Sack
That reserve activity was a mix of both specific and general. I should note that that reserve activity reflects the market and discount rates and valuations and loan-to-values as of March 31, and they do not reflect the subsequent events of rescheduling market activity and discount rates thereafter.
I think that rescheduling is a credit positive for all of our borrowers, and even those that don't have significant medical revenues.
Chris Muller
Should we expect to see some CECL releases throughout 2026 as those 280E issues work through the companies?
Peter Sack
It's certainly possible. It would be a reflection, not necessarily directly of rescheduling, but it would be a reflection of market sentiment, loan-to-values, cash flow calculations flowing through to the inputs that drive our CECL reserve policies and behaviors.
Chris Muller
Got it. Appreciate you guys taking the questions, and great to hear we've finally got some positive news in the sector.
Peter Sack
Absolutely.
Operator
Thank you. Your next question comes from Aaron Grey with Alliance Global Partners.
Please go ahead.
Aaron Grey
Hi. Thank you for the question.
First question, obviously, there's a hope that we get the full plant rescheduled, late summer, fall, following the hearings, but potentially in the near term or if full plant rescheduling takes a little bit more time, in this scenario, do you tend to get a little bit more aggressive in medical-only states where you have the removal of 280E, or does that change any of the potential near-term landscape opportunities? Thanks.
Peter Sack
I think it does allow us what what's the it allows us to be to be to reflect in our underwriting the different tax treatment of medical revenues versus adult-use revenues. I think it drives us to we will have to, if if adult use does not proceed on a record on adult-use sales, then it will lead to I think different lenses for medical versus adult use if only because it drives different cash flow dynamics of the operators.
That's the fundamental that is the fundamental basis of which I think all underwriters at this base will need to adjust. Again, I hope it's hope it's hope it's not needed, but if the fundamentals of cash flows are reflect need to be reflected in this, then it'll be it'll be reflected in our underwriting and deployment as well.
Aaron Grey
Thanks. That's helpful color.
A lot of people in the industry talk about potential impact of the hemp ban come to fruition in November having a broader impact on the legal cannabis market. Curious to your view on that and your borrowers, potentially that ban come to fruition and helping out the fundamentals of your borrowers, and your view on that.
Thank you.
Peter Sack
We've absolutely heard anecdotal feedback that the hemp ban has driven revenue increases, particularly in states that have a larger prevalence of smoke shops and these types of black market hemp CBD and cannabis-adjacent products. I think it's been difficult to find a direct link in the data, but certainly anecdotal and correlative links between the hemp ban and in regulated cannabis sales.
Aaron Grey
Okay. Great.
Thank you. Just last question for me, in terms of liquidity and pipeline, any color on timing to having some things in the pipeline come to fruition, with the liquidity you still have available?
Thanks.
Peter Sack
Our pipeline tends to refresh itself every three to six months, and in that period of time, we have the opportunity to explore whether these transactions that are in the pipeline are transactions that we seek to close or transactions that end up not being worthy of closing. I think it's difficult to forecast within that timeframe of what that deployment will be, for better or worse.
I'll point out that in this quarter, I think at investors' request, we have released a breakdown between real estate-backed and non-real estate loans within our portfolio in an effort to give our investors a better view into what portion of our pipeline is more directly a fit for Chicago Atlantic Real Estate Finance,
Aaron Grey
Inc. Very helpful.
Appreciate that disclosure and color in response to the questions. Thank you very much.
I will go ahead and jump back in the queue.
Operator
Thank you. As there are no further questions from the participants, this concludes our question-and-answer session.
Also, the conference has now concluded. We thank you for attending today's presentation, and you may now disconnect.