Revolve Group, Inc.
Q3 FY2026 · Earnings Call TranscriptNovember 3, 2026
Joining me on the call today are our co-founders and co-CEOs Mike Karanikolas and Michael Mente, as well as Jesse Timmermans, our CFO. Following our prepared remarks, we'll open the call for your questions.
With that, I'll turn it over to Mike.
Mike Karanikolas
Hello everyone, and thanks for joining us today. We delivered a strong quarter with outstanding top-line growth.
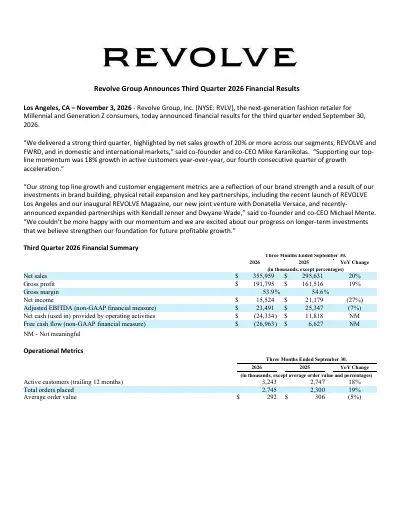
Net sales grew 20% or more across both segments, REVOLVE and FWRD, and in domestic and international markets. Also notable is the great momentum in our underlying business metrics.
Active customers increased 18% year-over-year and grew 202,000 sequentially, the most we've ever added in a single quarter. The year-over-year increase represents an acceleration of 7 percentage points from last quarter, driven by a record quarter for new customer acquisition and increased engagement from existing customers.
Our strong top-line results and the momentum in our customer base in recent quarters is especially noteworthy in an environment where many in our industry have seen softer trends. We believe that it shows our investments are delivering results and reflects the team's disciplined execution against our key growth initiatives.
Another bright spot in the third quarter was product returns. Our return rate decreased by more than 2 percentage points from a year ago, better than we expected.
Category diversification was a big driver, along with initiatives to reduce returns in ways that are good for the customer. That also helped absorb the impact of higher fuel surcharges on our logistics costs this quarter.
We've now lowered our return rate year-over-year in 8 of the last 10 quarters. With that context, let me step back and briefly recap the quarter.
Jesse will provide more details in his remarks. Net sales were $356 million, up 20% year-over-year.
Notably, sales in our mobile app have been growing much faster than our other channels in recent quarters. Strong growth in app downloads has helped, and the app is becoming a bigger part of our overall mix.
That's important, because on average these are our most valuable customers. They order more often, convert at higher rates, and spend more than customers in any other channel.
Coming into the year, we set a goal of returning to double-digit net sales growth in 2026. With three quarters done, we're well positioned to deliver on that goal.
Net sales are up 16% year-over-year through the first 9 months, and this is our fourth straight quarter of double-digit growth, going back to the fourth quarter of last year. We believe that's evidence that our investments in brand, technology and AI, site experience, and category expansion are paying off.
Gross margin was 53.9%, near the high end of our guidance range, and down 75 basis points year-over-year against a difficult prior-year comparison. Adjusted EBITDA was $23.5 million, down 7% year-over-year, reflecting the investments in growth initiatives that we're making this year.
Also recall that our adjusted EBITDA grew 45% year-over-year in the third quarter of 2025, our results still reflect healthy 34% growth on a two-year basis compared to the third quarter of 2024. Earnings per diluted share were 20 cents, compared to 29 cents last year, when we benefited from an insurance recovery equivalent to 5 cents per share.
As we've discussed on prior calls, 2026 is a foundational investment year for us, focused on launching longer-term initiatives that we believe have the potential to meaningfully shape our business over time. I am encouraged by our progress against these large opportunities, such as physical retail, developing our first-ever REVOLVE namesake label within our owned brand assortment, and launching a successful joint venture with Cardi B.
We also continue to invest to extend our track record in deploying AI technology across the business, which has contributed to both growth and efficiency. As a founder-led company bolstered by a rock-solid balance sheet, Michael and I are focused on maximizing value over the long term.
Michael will talk more about our progress on each of these initiatives in his remarks, as well as our new joint venture with Donatella Versace that we are very excited about. Importantly, we expect to resume adjusted EBITDA margin expansion in 2027 after this investment year.
Shifting to our longer-term priorities, I'm excited about our progress on a number of key initiatives. First is brand-building investments to help us grow our customer base and deepen our relationships with existing consumers.
The third quarter was a busy one, highlighted by events celebrating the launch of our inaugural REVOLVE Magazine, which we timed with the third drop of REVOLVE Los Angeles. We believe our investments in brand building contributed to the strong new customers growth and the acceleration in active customers that I discussed earlier.
Second is international. Net sales outside the US grew 22% year-over-year, and every major region grew double digits.
That's the 15th straight quarter international has grown faster than the US. We're seeing particular strength in emerging markets, where we're applying what we learned in Mexico to build customer engagement, and we think there's a lot of opportunity ahead.
Third is category expansion. The handbags, shoes, and accessories and the fashion apparel categories both grew faster than total net sales this quarter, led by wardrobe essentials like tops, pants, shorts, and outerwear.
Our newer product areas, men's and beauty, are together growing much faster than the overall business and are also contributing to the reduction in our return rate. Finally, we continue to leverage AI to drive innovation, growth, and efficiency across our platform and throughout the company.
Last quarter, I discussed AI-enabled enhancements to our on-site search that let customers upload photos to discover products more easily. Building on that, we recently tested and rolled out new AI-powered search filters that allow mobile customers to refine their searches by color, price point, and product category.
This feature was built internally, and we've seen a meaningful lift in the conversion rate among mobile customers who use it. Another example we're especially excited about is the custom mobile app for our store associates.
Using AI, the team built the app in less than a week, and it's already showing great results. Associates scan the styles a customer selects on the sales floor, and the app searches available inventory throughout the store.
It also suggests similar and complementary styles, which helps associates build a complete look for the fitting room. Our operations team uses the same app to pull the styles and stage the fitting room for customers.
Since we rolled it out at The Grove in August, our conversion rate there has experienced meaningful sequential growth each month. In addition to the customer experience and conversion rate benefits, it has further strengthened our real-time reporting and analytics.
Let me close by providing some additional context as it relates to the optimism in our longer-term growth algorithm. We recently commissioned an independent market research study that offered some useful insights.
First, even with trailing 12-month net sales of nearly $1.4 billion, unaided brand awareness for REVOLVE remains below 5%, which we view as a significant opportunity. At the same time, our customers are strong advocates.
Among the 15 well-known retailers in the survey data, REVOLVE ranked first for Net Promoter Score. That fits with what we see within our own data, where revenue retention among tenured customer cohorts has been consistently very high, with productivity from these customers increasing meaningfully beyond their first purchase.
We believe the combination of the opportunity in brand awareness and our strong and growing active customers base further builds on our foundation for continued future profitable growth for years to come. To wrap up, we are encouraged by our business momentum and by the strong progress we're making on our long-term strategic investments, which we believe further strengthen our foundation for profitable growth.
I want to thank our team for their exceptional efforts day in and day out. Michael and I are fortunate to work alongside such a talented, dedicated, and passionate group of people, and they have us well positioned for the opportunities ahead.
Now, over to Michael.
Michael Mente
Thanks, Mike, and hello everyone. It was another quarter of strong growth and meaningful progress on the long-term investments that we believe will strengthen our brands and position us for continued profitable growth in the years ahead.
Today, I'll focus on three of those areas: brand building, partnerships, and physical retail expansion. First, brand building.
It was a busy and productive quarter for brand building, headlined by the launch of our inaugural REVOLVE Magazine, which coincided with the third drop of our REVOLVE Los Angeles label. The magazine is a true complement to our world-class digital content and lets us have a longer conversation with our customers and create deeper connections.
We brought the heat, creating three separate covers that feature REVOLVE Los Angeles on fashion trendsetters Teyana Taylor, Alex Consani, and Kendall Jenner, who have more than 300 million social media followers combined. The magazine beautifully integrates all aspects of our business, including our FWRD, beauty, and men's offerings, connecting our editorial storytelling to REVOLVE's product universe through shoppable QR codes that link to our site.
Featuring aspirational names and fashion that speak directly to the REVOLVE customer, including Irina Shayk, Becky G, Cameron Brink, and Dwyane Wade, it brings our brands to life in exciting new ways. We hosted a magazine launch event during Paris Fashion Week that Vogue called "one of the chicest fashion parties of the season," attended by A-listers such as Kendall Jenner, Rosie Huntington-Whiteley, Amelia Gray Hamlin, Anok Yai, Adriana Lima, and Alandrea.
The launch was orchestrated with a seamlessly executed marketing campaign that amplified our brand across multiple consumer touchpoints, resulting in strong brand signals following the event. For instance, REVOLVE Los Angeles drop number 3 has been our best performing yet.
A video of REVOLVE Los Angeles ambassador Alex Consani featured on our REVOLVE YouTube channel has generated more than 600,000 views organically. This builds on the rapid growth of our YouTube-owned channel views, which increased more than 50% year-over-year in the third quarter.
We also recently announced two key investments that meaningfully advance our brand-building efforts. To build on the continuing success of our men's business that represents an increasing mix of net sales, we've appointed Dwyane Wade, the NBA champion and entrepreneur, to the newly created role of Chief Performance Officer.
He will serve as the face and strategic advisor for our men's fashion initiatives across FWRD and REVOLVE as we look to further accelerate growth. We've also expanded our long-term partnership with Kendall Jenner, who is now FWRD's Global Creative Director.
She'll continue to guide FWRD's creative direction across brand curation, trend edits, and major marketing initiatives. In her new role, Kendall is also an ambassador for REVOLVE Los Angeles and was featured prominently in our inaugural REVOLVE Magazine and marketing campaigns.
Second, partnerships. We're excited to have announced a joint venture with the legendary Donatella Versace, one of the world's most iconic fashion designers, to create a new beauty and fashion business built around how a new generation discovers style, shops, and connects.
Donatella spent decades guiding the creative vision of a global fashion house with more than $1 billion in annual revenue. She will now lead the creative vision of our joint venture as Chief Creative Officer, shaping the brand's identity, products, and collaborators.
REVOLVE will power the business with our capabilities in digital commerce, technology, consumer intelligence, and operations. The announcement drew significant global media attention, generating nearly 6 billion press impressions, according to Cision, the industry standard for media analytics, the most of any announcement in our history.
We believe this reaction, combined with Donatella's global profile, reflects real excitement and anticipation for what we'll create together. We look forward to sharing more about our plans in the months ahead.
Turning to our joint venture with Cardi B, Grow Good delivered strong growth in the third quarter, with net sales nearly doubling sequentially, and ranking among our top 10 selling brands. Repeat purchases among existing customers have increased meaningfully over the past three months, and the products continue to receive strong reviews from customers and beauty editors.
Also, encouraging, even in this early stage, the Grow Good business is already accretive to our bottom line profitability. After selling out several times early on, all Grow Good products are back in stock.
That allows us to begin investing in marketing to build awareness, including mini versions launching later this month to encourage customers to try the product ahead of the holidays. Cardi's profile and significant social following continues to support awareness, including activations around her recent headliner performances at the iHeart Music and Create & Cultivate festivals.
Lastly, we recently disclosed our $11 million investment in the activewear brand 437 that we made in January. This investment is a proven example of our thesis that REVOLVE can bring its best-in-class marketing, technology, and operations capabilities to support emerging brands and founders, helping take their business to the next level.
437's direct-to-consumer business net sales nearly doubled year-over-year in the month of September, and the brand has been our top activewear brand on REVOLVE and FWRD year-to-date. It is performing particularly well in our stores, including at The Grove, where we're currently hosting a shop-in-shop.
The partnership has been great, and the investment has contributed nearly $900,000 in equity earnings so far this year through September. Finally, physical retail.
Our third store, at Aventura Mall in greater Miami, opened ahead of schedule and under budget in late September, and has outperformed our projections in its early weeks. Owned brands are generating nearly 60% of net sales in the store so far, more than double our online penetration.
Because owned brands carry much higher gross margins, this supports our belief that physical retail can provide meaningful margin accretion over time. We celebrated the grand opening with Li-Ning and our new Chief Performance Officer, Dwyane Wade, unveiling a curated selection of footwear and apparel from his Way of Wade brand, including styles exclusively available through REVOLVE.
Fans lined up out the door to meet the NBA and Miami legend in person. We're also very encouraged by the progress at The Grove in Los Angeles and in Aspen, where performance has improved steadily since we opened in early 2024.
Based on that demand, our Aspen store, at about 3,100 square feet, is too small to realize its full long-term potential. With that, I'm excited to share that we've signed a multi-year lease to more than double its size, meaningfully expanding our growth potential in the market.
Ahead of construction, which we expect to begin in early 2027, we'll move into a temporary store of more than 8,500 square feet, nearly three times the size of the existing Aspen store. One metric that illustrates our progress in retail: omnichannel customers who engage with us online and in store spend nearly three times as much as single-channel customers.
This highlights the opportunity to engage more of our e-commerce customers in store as we expand our footprint. Our investments in our team, operations, and retail technology are showing results, and we're increasingly confident in the opportunity in physical retail.
To close, we're energized by the momentum across our growth initiatives. Net sales growth of 20% across the business, accelerating customer growth, and FWRD's outperformance in luxury show our brands resonating with consumers.
Physical retail is off to a strong start in the early innings, and category expansion and our partnerships are adding new growth drivers. We believe all of this positions us for profitable growth and continued share gains in the years ahead.
With that, I'll turn it over to Jesse to discuss the financials.
Jesse Timmermans
Thanks, Michael, and hello everyone. We're delivering strong top-line growth while investing for the long term, and we remain focused on balancing those investments with a return to margin expansion in the near future.
I'll start by recapping our third quarter results, and then close with updates on recent trends in the business and guidance for the balance of the year. Starting with the third quarter results, net sales were $356 million, a year-over-year increase of 20%, our fourth consecutive quarter of double-digit growth.
REVOLVE segment net sales and FWRD segment net sales each increased 20% year-over-year in the third quarter. By territory, domestic net sales increased 20%, and international net sales increased 22% year-over-year.
Growth in trailing 12-month active customers accelerated to 18% year-over-year, a 7-point improvement from our growth rate in the second quarter of 2026. Contributing to the strong top line was 19% growth in total orders placed year-over-year to 2.7 million, and a more than 2-point reduction in our return rate year-over-year.
Average order value was $292, compared to $306 in the third quarter of 2025, a 5% decrease year-over-year driven by initial orders of Grow Good beauty products, which have much lower price points and average order values. Absent the addition of the Grow Good business, AOV would have been relatively flat year-over-year.
Consolidated gross margin was 53.9%, near the high end of our guidance range, and a decrease of 75 basis points year-over-year as we lapped the significant gross margin gains from the prior year resulting from the AI-driven optimization of our markdown algorithms. Now moving on to operating expenses.
Fulfillment costs were 3.4% of net sales, a slight increase from 3.3% in the third quarter of 2025. Selling and distribution costs were 17.8% of net sales, and slightly above our guidance.
The 35 basis point increase year-over-year primarily reflects increased costs for customer shipments, including much higher fuel surcharges year-over-year that are variable with the elevated fuel costs, partially offset by a reduced product return rate. Our marketing investment was 14.3% of net sales, an increase of 60 basis points year-over-year.
Marketing outperformed our guidance by approximately 70 basis points, largely due to timing shifts as certain events initially slated for late in the third quarter moved into the fourth quarter. General and administrative expenses were $46.2 million, an increase of 20% year-over-year, and above our guidance.
Key drivers of increased investments center around our growth initiatives, including strengthening the foundation for physical retail that we feel great about, as well as Grow Good and initial costs related to our new Donatella Versace joint venture announced last month. Below the operating line, other income, net, was $2 million, a significant decrease from $7.3 million in the prior-year quarter.
Recall that results for the third quarter of 2025 included a $4.5 million gain from an insurance recovery. Our tax rate was 27% in the third quarter, 2 points higher than the prior-year period.
Net income was $15.5 million, and diluted earnings per share was 20 cents, compared to diluted EPS of 29 cents in the third quarter of 2025, which included an insurance recovery equivalent to approximately 5 cents per diluted share. Adjusted EBITDA was $23.5 million, a decrease of 7% year-over-year, achieved while investing in several meaningful growth initiatives for the long term.
Moving on to the balance sheet and cash flow statement. Net cash used in operating activities was $24 million, and free cash flow was negative $27 million in the third quarter, primarily due to unfavorable movements in working capital.
For the 9-month year-to-date period in 2026, we generated positive operating cash flow and free cash flow of $17 million and $7 million, respectively. Inventory at September 30, 2026 was $293 million, an increase of 23% year-over-year, and 2 points higher than our net sales growth year-over-year.
This relationship improved sequentially from our 12-point spread between inventory growth and net sales growth year-over-year in the second quarter of 2026. As of September 30, 2026, our balance of total cash and cash equivalents was $285 million, and we continue to have no debt.
Now let me update you on some recent trends in the business since the third quarter ended and provide some direction on our outlook to help in your modeling of the business for the balance of the year. Starting from the top, we're off to a solid start with net sales through the month of October 2026 increasing by a mid-teen percentage year-over-year.
For modeling purposes, I want to point out that we face much more difficult prior-year comparisons for the rest of the fourth quarter. A year ago, we disclosed that our net sales in October 2025 increased by a mid-single-digit percentage year-over-year.
For the remaining 2 months of last year's fourth quarter, our net sales growth rate improved well into the double digits, leading to 10% net sales growth year-over-year for the full fourth quarter of 2025. Shifting to gross margin.
We expect gross margin in the fourth quarter of 2026 of between 52.3% and 52.8%, which implies a decrease of approximately 75 basis points year-over-year at the midpoint of the range, in line with our third quarter performance. Consistent with year-to-date trends, we expect our full-price mix of net sales to remain slightly lower year-over-year, but still very strong relative to the broader market.
For the full year 2026, we have tightened our range to the high end of our prior guidance and now expect gross margin of between 53.9% and 54.0%. Fulfillment.
We expect fulfillment as a percentage of net sales of approximately 3.3% for the fourth quarter of 2026, and for the full year 2026, unchanged from the midpoint of our previous guidance. Selling and distribution.
We expect selling and distribution costs as a percentage of net sales of approximately 17.6% for the fourth quarter of 2026, which implies an increase of approximately 90 basis points year-over-year. For the full year, we have increased our guidance to 17.5% of net sales, reflecting freight cost pressures in the third quarter that have continued into October.
Marketing. We expect our marketing investment to be approximately 16.9% of net sales in the fourth quarter, which includes investments that shifted out of the third quarter due to the timing of brand-building events.
For the full year 2026, we expect our marketing investment to be 15.9% of net sales, unchanged from the midpoint of our previous guidance. General and administrative.
We expect G&A expense of approximately $46.1 million in the fourth quarter of 2026, and now expect G&A expense of $178 million for the full year 2026 as we continue to prudently invest in key growth opportunities for the long term. Lastly, we are narrowing our effective tax rate guidance to a range of between 25% and 26% for the full year 2026.
To recap, as we move through this investment year and look ahead to 2027, I'm encouraged by the momentum we're seeing in the business and the progress on our longer-term growth initiatives, the combination of which I believe lays the foundation for profitable growth, margin expansion, and continued share gains. Now we'll open it up for your questions.
Operator
Thank you. We will now begin the question-and-answer session.
If you would like to ask a question, please press *1 to raise your hand. To withdraw your question, press *1 again.
We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device.
Please stand by while we compile the Q&A roster. Your first question comes from the line of Jonna Kim with TD Cowen.
Your line is open, please go ahead.
Jonna Kim
Thank you for taking our question. Just the first one on October trending mid-teens, could you just characterize what's driving that just versus the 20% that you saw in 3Q?
Anything to call out there? Then just a second question around international, just the outperformance there.
Any color around just the regions and demand by geography would be helpful. Thank you.
Mike Karanikolas
There's nothing to call out with regards to October. We feel great about October performance.
It's well ahead of the targets we set out at the beginning of the year, and there'll be a little bit of fluctuation quarter to quarter and month to month, of course. Q4 is a tougher comp for us, is an important consideration as well.
We think it's off to a great start, and we think the quarter's off to a good start. Then flipping to international, international's been a great growth story and growth driver for many quarters now, and I think the recent quarter is just a continuation of that.
Certainly a lot of pieces coming together, all major regions up double digits. We're very happy with that momentum, and we think we're going to continue to see success in international markets for the quarters to come.
Jonna Kim
Got it, that's helpful. Just one last one, Jesse, on the promotion that you're embedding in the guide, what are you expecting just around the holiday season?
Thank you.
Jesse Timmermans
Thanks, Jonna. Nothing different from years past.
Promotions should be generally in line. I think most of our call it promotions are markdowns through algorithm.
That is again algorithm-driven, no significant change on kind of promotions.
Operator
Your next question comes from the line of Jay Sole with UBS. Jay, your line is open, please go ahead.
Jay Sole
Great, thank you so much. My question is about units per transaction, given it seems like the beauty business is going really well.
How much are you seeing an ability to get consumers to buy across categories? Maybe talk about where you see that going from where you saw it in Q3.
Thank you.
Jesse Timmermans
Thanks, Jay. I think you're right.
Beauty's been performing very well. It's a great way to both acquire new customers and also an add-on item for those existing customers, and we did see in the quarter units per transaction go up.
I think we are seeing that, and we hope to continue to see that over time. Now, on the flip side, it does impact AOV.
You saw that this quarter, primarily due to Grow Good performance. I think business as usual, flattish AOV, and then as we see some of those category diversification plays come into play, and then Grow Good, that will have a negative impact on the AOV, but good overall.
Jay Sole
Maybe just to follow up on that, on the category expansion, you call that so many in the prepared remarks, whether it's beauty or men's or other stuff outside of dresses, international as well. What is your thinking about strategically how these categories fit in?
Do you think these can be full-sized categories where you can have the kind of share in these categories that you have in dresses? Give us a feel for what your ambitions are in some of these newer categories.
Mike Karanikolas
That's certainly the intention and the goal, and obviously we're a lot earlier stages with these categories. Men's we think is performing incredibly well and still quite a small base, but huge opportunity.
Beauty, home, these other categories as well, that's absolutely our goal to get them to the point where dresses and fashion apparel is today.
Jay Sole
If I can ask one more maybe for Michael, a lot of super interesting marketing initiatives and just brand-building initiatives in the quarter, and congrats on the REVOLVE Magazine. Of all these things going on, which ones do you think have the most promise?
Can you just give us a little hint of what maybe prepare for holiday to drive more excitement in that key critical season?
Michael Mente
I think that in this near-term holiday, it's kind of more of the same. It's investments made.
My mindset is usually zoomed out a little bit. The one thing I think that is probably the most exciting for years to come is the Donatella Versace partnership.
She's one of the most iconic fashion designers of all time, and certainly on the planet at this moment. She has massive reach, and the announcement that we had with her was the biggest announcement of any announcement ever, and we have had quite a share of announcements over the years, so that's super exciting.
Her audience might not be as obvious to the world, but her audience is really 18 to 34, which is really right in the heart of our next-generation REVOLVE audience. It's really clear that we're speaking to our customer and our potential customer with the most influential designer with a very, very overlapping kind of brand ethos.
That for me has huge, huge, huge potential.
Operator
Your next question comes from the line of Randal Konik with Jefferies. Randal, your line is open, please go ahead.
Randal Konik
Thanks a lot. I guess question for you, Jesse.
Can you give us some thoughts just high level about how you're thinking through kind of medium-term EBITDA margins and then just maybe the different moving pieces, maybe give us some perspective on where we are with owned brand penetration, where that's kind of likely to go over the medium term, international, how you're thinking about that. The FWRD gross margins seem like spread is narrowing more versus REVOLVE gross margins.
It'd be very helpful to get a sense of just the different moving pieces of margin and how you think those develop over the medium term, maybe more qualitatively if you don't want to get into them more quantitatively. Thanks.
Jesse Timmermans
Sure. Thanks, Randal.
There's a lot there. I'll try to hit them all.
Maybe just first high level. As we've talked about in the past, our first goal is to get into double-digit top-line growth, which we've done for the past four quarters.
Then our second goal is to get to double-digit EBITDA margin. Maybe bridging to that at the high level, if you take this quarter's 6.6%, as we mentioned, this is a foundational year for investments.
We are investing meaningfully in these growth initiatives. That is to the tune of about 2 points across G&A and marketing.
That brings you up close to 9%, within striking distance of that double digit. How do we get the rest of it?
Number one is gross margin, as you mentioned, primarily on REVOLVE with owned brand expansion. We closed last year at about 20%.
Our goal is to grow owned brand mix at 1 to 2 points a year over time at a nice, moderate pace, that will increase margin. Physical retail adds to that.
We mentioned Aventura having a owned brand mix of 60% in store. As we roll out the fleet of stores, that has a incremental positive impact on gross margin.
Not expecting to see as much on FWRD. FWRD's in a good place at that low- to mid-40% range, wouldn't expect to see a ton of gains out of the FWRD business in the near to mid-term.
Now, there is long-term opportunity there, but not in the near to mid-term. Then the other areas primarily on G&A and marketing.
One, as we comp the growth investments that we've done this year, and then two, as we realize the scale and get the returns on these investments in future years. That's kind of the high level on how we're thinking about it.
Randal Konik
I think it's really helpful. Then you talked just in your response, you said, as we roll out a fleet, I guess, of stores.
In the last few quarters, you've talked about the different locations and how they're performing above I guess plans or expectations, and they're sounding like they're doing very well. When do we get to a place or if do we get to a place where you start to really accelerate development of the units by year?
What is that looking like or not looking like? Give us some kind of thoughts again on the medium term there.
Thanks.
Michael Mente
I don't think there's necessarily a threshold where things really turn the corner. I think it's going to be a gradual acceleration.
We are very, very satisfied with the progress made over this past quarter across the two stores, as well as the launch of the Aventura store. Feeling really good.
Again, I think we are crawling quickly. We're not walking or running yet, but we're crawling quickly, we are accelerating.
We really can see, compared to people who have global fleets, we see people opening literally hundreds of stores a year. We're light-years away from that.
I do think that you will see acceleration of our expansion. Not just from the number of doors, but a little bit also another parallel, important lens is from the expansion of square feet.
It doesn't have to be new door, new door; it could be slightly larger stores at the same time. Very excited for what's ahead.
We're making great progress. We also realize it is a big world, we have a big audience, and it is a long journey to get to where we ultimately will be.
Operator
Your next question comes from the line of Peter McGoldrick with Stifel. Peter, your line is open, please go ahead.
Peter McGoldrick
Hey guys, thanks for taking my question. Encouraging to see the continued acceleration on the top line in the third quarter.
I wanted to ask about some of the framing for the 2027 margin recovery. With G&A and shipping costs now higher, does the prior mid-single-digit G&A outlook and the 15% to 16% marketing framework that you pointed to last quarter still hold?
Jesse Timmermans
Thanks, Peter. That generally still holds.
Again, as we lap the investments of this year, we expect to make some meaningful gains on both marketing and G&A, with a goal of increasing G&A on a steady-state basis in that mid-single-digit percent range. Then marketing, again, bringing that back to closer to our historical.
Keep in mind we were coming off a relatively light year in 2025 at just over 14%. We made a lot of investments this year coming in, if you look at the guidance, closer to 16%.
Bringing it back towards the middle of those. I think you're thinking about it right.
Peter McGoldrick
Okay. Then I wanted to ask about the customer base.
Active customer growth accelerating to 18% year-over-year, can you help us think about how much of that came from Grow Good and relative to the core REVOLVE, FWRD business? Then anything that we can just think about as Grow Good begins to scale, how we should be thinking about that contribution to the P&L?
Jesse Timmermans
We had great new customer additions from Grow Good, but even absent the Grow Good additions, we would have seen acceleration in that active customer growth rate from the 11% that we saw in Q2. Even absent Grow Good, we saw really healthy active customers, and coming both from new customers, which, again, absent Grow Good was a near record, and then we also saw increased productivity from our existing customers.
It's coming from both sides. Really encouraging is, as we stack these new customers, as our existing or pre-existing customers are more productive and get more productive with time, adding to the base is really important.
Peter McGoldrick
Thanks, and good luck.
Jesse Timmermans
Thanks, Peter.
Operator
Your next question comes from the line of Michael Binetti with Evercore ISI. Michael, your line is open, please go ahead.
Michael Binetti
Hey guys, nice quarter. Really happy to see it.
Thanks for taking our questions here. Let me just continue that one for a quick second, and then I have a follow-up.
What gives you guys the most confidence in sustaining the double-digit revenue growth that you're obviously very proud that you got there and keep telling us how many quarters you've been there. As you look into next year, you've got tougher comps, always raising the bar on yourself.
What is it? Is it the customer growth that's the leading indicator that gives you the most confidence?
Or maybe you could just talk about that for a second.
Mike Karanikolas
I think there's a number of key things. Obviously the customer growth, particularly new customers, active customers, seeing a new record in the current quarter and acceleration on those numbers.
I think just all the things we've done to really lay the framework for our brand to be successful going forward, continuing to improve the customer experience through various means including AI enhancements and other enhancements, and I think things are only going to get better. Physical retail stores obviously big growth driver for us.
The base is still quite small, but we're starting to accelerate there as Michael mentioned. Importantly, a very large portion of the traffic and customers to those retail stores are new customers.
The overall opportunity, which we spoke about on the call, right, with only 5% unaided brand awareness, but incredible loyalty, incredible Net Promoter Score. We feel we're set up very well for success in the upcoming year in terms of continuing the growth trajectory.
Obviously continuing to invest in some of these big initiatives. I mentioned physical retail, Grow Good is set up for huge success, Donatella Versace.
I don't know if we've shared the timing, but obviously that's something that we could see hitting next year. That's going to be fantastic for us.
Just a lot of really good things. Then obviously layering on a bigger focus on efficiency as we've made some investments this year and really laid some great foundational pieces, and then next year delivering both the revenue growth and nice margin growth.
Michael Binetti
Very helpful. Jesse, maybe I could ask you one.
I know great momentum in third quarter. I know the context of fourth quarter will vary with sales a little bit.
If we kind of take your quarter-to-date trends at mid-teens or a little slower, because you're pointing out the tougher comparisons, is a reasonable range for fourth quarter. Gross margins are guided below where consensus is today.
Most of the cost items are guided unfavorable to where consensus is today. It kind of works to an EBITDA margin in the maybe low to mid-singles, single digits in the fourth quarter.
Maybe just help us a little bit with a wrap-around out of fourth quarter as to what rolls off as we get into early '27. Then on cadence, if you don't see trends slow from that mid-teens level of October, how much variability there is in the cost lines as you've planned them and given them to us today?
Jesse Timmermans
Yeah. I think, as you mentioned, we're pleased with the start to the quarter in that mid-teens percentage.
It is a decel coming off of 3Q, but it's only one month. We're optimistic about customer acquisition, the customer engagement.
We'll have to see how the rest of the quarter plays out, but encouraged with the start. As you mentioned, costs are up in Q4.
I think a couple areas. We did have some shift in marketing from Q3 to Q4, but that stayed in line for the full year.
Selling and distribution, we keep getting hit with this pesky fuel surcharges and freight. If we think about our guidance in Q2, we factored fuel in, but it was coming down in June, July, and then it ticked up pretty meaningfully in August and September.
Said differently, it's very volatile. We would hope that that would roll off soon, and especially into next year, and we could start to comp that.
Then the G&A investments, this year again was a important investment year for us, and then we expect to leverage on that into 2027.
Operator
Your next question comes from the line of Mary Sport with Bank of America. Mary, your line is open, please go ahead.
Mary Sport
Hey guys, could you just give a little bit more of an update on your return rate initiatives and what exactly drove the decrease better than what was planned? Then after that, could you also give an update on your personal shopper program?
Is that still an area that you're really focused on, and what are some of the benefits that you're seeing as a result of that? Thanks.
Mike Karanikolas
We were really pleased with the progress on our return rate initiatives in the quarter. Then kind of diving into the return rate decrease year-over-year, which was substantial, a meaningful portion was due to category mix shift, especially with Grow Good ramping up and things of that nature, and just category shift within the business.
International also carries a lower return rate. At the same time, a very meaningful portion of it did come from essentially what I'd call core return rate decreases.
That's just a continuation of the efforts that we've been continuing to make quarter in and quarter out. As we always say, it's hard to predict exactly what the impact is going to be in any given quarter, but we feel good about the investments we've been making, including I think I alluded to on previous calls, we had some investments that we've been making partnering with brands to work with them to do things that help reduce return rates that we'd seen success with previously, and that we are starting to ramp up.
As we've seen that ramp up, we've seen good success there, and that's something we're going to continue to do in the coming quarters. Then longer term, and we've talked about it before, but as technology improves, I'm very hopeful we're going to start to unlock some even more meaningful movements leveraging AI technology and visualization technology.
Those things are starting to come together. It's maybe a little bit further out, but for me, those are things I'm incredibly excited about, cuz not only can it help the economics of the transaction, but what excites me is that it's great for the customer, right, in terms of helping them make a better choice, better decision.
A lot of continuing investments, very pleased with the progress, and hopefully we can continue to deliver results in the quarters and years to come. I'm sorry, I think you had a part two the question that I missed.
Mary Sport
That was super helpful, thank you. Then just an update on the personal shopper program and some of the benefits that you see from that.
Thanks.
Mike Karanikolas
We're continuing to invest in that program. We think it continues to be a big opportunity.
Certainly, it's been a very important driver of the success we've seen with FWRD, but also REVOLVE, cuz nearly all those customers cross-shop both sites, and many of them are very big fans of REVOLVE. An area we're going to continue to invest in, that we can continue to get better in.
Incidentally, just kind of a nice little anecdote, it's also an area where we've seen the power of AI investments starting to take hold. What's really neat for me personally is seeing some of the personal shoppers within the program itself start to leverage AI technology to help improve the internal tools they use even more.
A lot of progress and momentum there, and I think we're rapidly becoming best in class and we can continue to deliver there.
Operator
Your next question comes from the line of Anna Andreeva with Piper Sandler. Anna, your line is open, please go ahead.
Anna Andreeva
Great. Thank you so much, and congrats nice results.
We wanted to follow up on the fourth quarter. You're calling out tougher November and December, but obviously lots of momentum in the business across the portfolio right now.
Jesse, what's a reasonable sales outcome that we should expect for the fourth quarter? Secondly, on inventories, great to see that spread improve versus sales.
Should we expect that carryover you had at the REVOLVE brand rectified by year end? Are you guys managing inventories tighter and closer to sales as we think about '27?
You've had full-price sales dip a little bit here this year just as a result of that inventory situation. Should we think the full-price penetration is back to growth as we think about next year?
Thanks so much.
Jesse Timmermans
Thanks, Anna. On the fourth quarter, I won't give you an explicit specific number, but if we just look at the comps, something lower than the mid-teens that we did in October, again, just given the comps.
November, December, we went from mid-singles in October to double digit in November and December. Just from a comp dynamic, something lower than the mid-teens that we had in October.
On the inventory spread, yes, we're very pleased with closing that gap in Q3. Just as a reminder too, last year in Q2 and Q3 we were lighter on inventory coming off of Liberation Day and a lot of delays in receipts.
We were down on inventory year-over-year in both of those quarters, less so in Q3, so that helps the spread this year in Q3. In Q4 we are managing inventory tight, and this is largely dependent on sales, but we expect it to be in good shape towards the end of the year, whether that's by year end or in Q1, it's kind of plus or minus one way or the other, but close to year end, yes.
Then full-price sales, again, yes, as the inventory comes back in line, we would expect full-price sales to get back into growth mode. Full-price sales is still very healthy, still starts with an 8 in terms of mix, and the full-price just absolute dollar growth was very healthy as well in the high teens.
Really pleased with the results both on inventory, full price even though it's down year-on-year, it was up against a really tough comp, still very healthy. Things are checking well.
Anna Andreeva
Great. Thank you so much.
Can I just follow up on more? You guys had talked about the markdown algo, and it obviously did a lot of good things for the business last year, especially in 3Q.
Can you talk about how you're using that? Are there kind of additional opportunities from that as we look out?
Mike Karanikolas
We're continuing to use the enhanced markdown algo, and we're continuing to see benefits from it in terms of our ability to liquidate merchandise at optimal sale prices. Feel great about that.
In terms of additional enhancements, with anything R&D based, it's kind of often hard to say what's next and they'll enhance, but it's an area of continued optimization, and as we continue to invest in AI and in tech, I'm confident we're going to get even better at our ability to manage and optimize inventory.
Operator
Your next question comes from the line of Matt Koranda with ROTH Capital. Matt, your line is open, please go ahead.
Matt Koranda
Hey guys, good afternoon. I guess it's been asked in a few different ways, but I want to attack it from this angle.
I guess how do you balance in 2027 sort of what you referenced, which was maybe toggling back on marketing expense a little bit, while preserving the ability to grow double digits on what looks like some tough comps next year? I guess it just seems like there's some inherent tradeoff there usually, and maybe there's something as to sort of how you're allocating your marketing budget underneath the surface that you might help us understand a little better for '27 and confidence in growth there.
Mike Karanikolas
There's certainly some tradeoffs there. A meaningful portion of the marketing increase this year was brand-building investments, which by nature are longer term, things that we think set the foundation for quarters and years to come.
Also importantly, we've invested in some newer things on the brand marketing side. The magazine, which we feel great about, and I know Michael and the team have received fantastic feedback from customers, vendors, people in the industry about the launch of that magazine.
It's the first time we've done it. It's the sort of thing where we believe we'll find some nice efficiencies there as we do it the second time around, which is often the case.
Importantly, including things like we've already been reached out to by brands and others that want to place advertisements with the magazines, which of course was not something that we focused on with the inaugural launch. A lot of opportunities for efficiency, both in terms of kind of leveraging new activities that we've done, and dial in the investments a bit, the investment knobs.
Again, there can be some impact on growth, but we think we have very good ability to manage those marketing expenses.
Michael Mente
The thing I would add, Mike, is that two things that we made from nothing really had to have escape velocity, and now it's kind of like maintenance throttle. The other aspect is that also with both of those areas, REVOLVE Los Angeles and the magazine, we've also learned so much and gotten so much better.
Not only do we think that we can drive continuing growth, we can do a better, more impactful job than we have in times past along with less capital deployed. Excited for the year ahead, feeling really good.
Operator
Your next question comes from the line of Nathan Feather with Morgan Stanley. Nathan, your line is open, please go ahead.
Nathan Feather
Hey everyone, thanks for the question. Encouraging to see the strong customer growth here.
Can you help us break it down into kind of gross acquisitions and churn? As the customer growth has accelerated, have you seen a meaningfully different customer profile that's coming in the door?
Mike Karanikolas
I can speak to that a bit, and then if Jesse wants to jump in. The Grow Good brand itself, which is a new brand and very different brand than REVOLVE, has played a meaningful role in the new customer numbers.
To points made earlier on this call, we would have still seen an acceleration and records on the new customer side and the active customer side absent that. The Grow Good customer of course has a different profile than REVOLVE and it's going to have its own characteristics, which we're still in the early stages of seeing exactly what those are.
We have very short cohort curves for that customer. Although I will say the early read is fantastic, as far as the repeat rates that we're seeing on the Grow Good side of things and that.
Certainly hopeful and optimistic. Then within the core REVOLVE business, we're seeing great new customer ads.
We're not seeing any meaningful difference in profile. To Jesse's point, as we layer those new customers and as they continue with us in the out years, they tend to become more and more productive over time.
Feeling very good about the opportunity ahead of us.
Operator
Your next question comes from the line of Janine Stichter with BTIG. Janine, your line is open, please go ahead.
Hi,
Janine Stichter
thanks for taking my question, and congrats on the momentum. I'm just following up on Grow Good.
I was hoping you could share a little bit more about the go-to-market strategy for that brand. I saw you began testing wholesale there.
Then as we just think about Grow Good and now we have the JV with Donatella Versace, it seems to be the beginning of potentially a platform of other brands or joint ventures. I'm curious how you're thinking about that over the medium to long term, what this could look like in terms of adding new brands onto the REVOLVE platform.
Thank you.
Michael Mente
Grow Good was interesting because it wasn't quite as dead center REVOLVE customer, but it was just the opportunity to work with someone as awesome as Cardi was just an opportunity that made a lot of sense to us, and it's going great. As you mentioned, profitable growing business.
That's in a new stage, and then gives us the confidence to pursue Act 2 with Donatella, which is even more exciting because it is right down the center in terms of REVOLVE customer. Actually rewind 1 second, it's actually the presence of Grow Good and our business with Cardi actually opened the door for the opportunity with Donatella.
She saw what we were doing with Grow Good and thought that, "Oh, we have a potential partnership here." We've explored it, and we're off to the races now.
We do think that the Donatella partnership will open even more doors. I think that momentum begets momentum, and I think that there will be other opportunities in the future.
We will be extremely selective. I think we will have our choice of partners, and ultimately can strategically pursue the opportunities that we assess to be the most lucrative.
I think over the medium term, there will be more to come. Of course, each one is very important and significant, and very similar to stores, we do have to build the infrastructure, the foundation, the team, and ultimately we'll be able to accelerate, but we will be very diligent and very, very focused to ensure that we have the solid foundation that we could build a massive, massive business on.
We're in the midst of that already.
Janine Stichter
Great, thanks very much.
Operator
Your next question comes from the line of Mark Altschwager with Baird. Mark, your line is open, please go ahead.
Mark Altschwager
Thank you. Good afternoon.
Jesse, just first wanted to follow up on the shipping. Guiding to 90 basis points of pressure there in Q4.
Can you deconstruct how much of that is the incremental fuel surcharges relative to the return rate efficiencies? Then separately, I wanted to ask about REVOLVE Los Angeles.
I think that's a big initiative for you heading into 2027. Maybe just frame up for us what success looks like for that next year, what would speed up the owned brand penetration beyond the 1 to 2 points per year, and just talk us through any timing on what that rollout is going to look like for the broader assortment.
Thank you.
Jesse Timmermans
Yeah. Oh, you want to go first, Michael?
Michael Mente
You go first.
Jesse Timmermans
I'll take your freight one, Mark. In Q4, as I mentioned, we did see fuel come down, still very elevated and still very high year-on-year growth.
We did see that year-on-year growth come down in June, July, but then it ticked up meaningfully in August and September and continuing to see that in Q4. I think the other important thing to call out here are a couple things.
One, there is an impact from international mix, with international outpacing domestic. Then even within international, some of our fastest-growing regions are also the regions that are the highest-cost shipping regions.
There is an impact there as well. Then the lower AOV, in large part due to Grow Good, does have an impact on the selling and distribution.
Those are a few of the factors, and those carry on into Q4. How much of that is due to fuel versus return rate?
We do see a nice, meaningful benefit from return rate, but that was completely more than offset by fuel and other shipping charges. Given our success this year-to-date, we are factoring in a slight decrease year-over-year in return rate in Q4, different from what we've done in the past for the past few quarters of assuming a flat return rate.
We are factoring in a slight decrease in return rate, not to the extent of Q3, because we are up against a tougher comp in Q4, but we are factoring that in to selling and distribution.
Michael Mente
Related to REVOLVE LA, definitely this is a very, very strategically important project for us. I think if you focus on 2027, success looks like a lot more REVOLVE label product in other segments across the board on our consumers shopping carts and on their bodies.
I think that REVOLVE LA being our flagship pinnacle line, is designed specifically for a specific customer, a lot of energy and a lot of coolness, but is not architected to be a broadly distributed brand. We do have great projects in the works that will be a little bit more broadly accessible, a little bit more everyday, a little bit more noticeable.
That is a thing that we're all very excited for in the next year.
Operator
Your next question comes from the line of Rick Patel with Raymond James. Rick, your line is open, please go ahead.
Rick Patel
Thank you. Good afternoon here.
Given the inflation we've seen broadly and with fuel prices, curious if you've seen customers behave differently this fall? Are you seeing signs of consumers become more sensitive about paying full price or gravitating towards certain price points?
What does guidance assume in terms of demand from upper-income consumers versus more aspirational ones?
Mike Karanikolas
Now we haven't seen any meaningful change in consumer behavior in October. Certainly the past year and past couple years, consumers have had to endure a lot, but thankfully we haven't seen any signs on our side that that's affecting consumer behavior yet.
In regards to the forecast, I'll let Jesse speak to that. I believe it's mostly just taking current momentum and the comps as we progress through the quarter.
Jesse Timmermans
That's right. Nothing more to add.
Rick Patel
Great. Can you maybe dig a little bit deeper on international markets, where you're seeing the most strength and the opportunities you see in 2027?
Mike Karanikolas
As I mentioned, we're seeing strength across the board, really incredible. We're seeing double digits in every major market, which we're thrilled about.
In terms of some of the biggest opportunities, Mexico continues to be a big growth market for us and has become quite large for us. Then also, I think some of the tactics that we've deployed in Mexico we can start to apply to other markets.
We've started to see success there with some of the marketing tactics in Mexico starting to apply those to the Middle East and to the UK and some other areas. I think we're in the early stages of really leveraging the marketing playbook to its fullest, as well as continuing to build our brand across the world.
Rick Patel
Thanks very much.
Operator
Your final question comes from the line of Ashley Owens with KeyBanc Capital Markets. Ashley, your line is open, please go ahead.
Ashley Owens
Hi, great. Thanks so much.
Maybe just to start, Jesse, on gross profit. I saw that the deck calls out increased valuation adjustments as one of the pressures in the quarter.
Could you just give us a little more color on what drove that, and was it concentrated in any particular categories or parts of the assortment? Then I have a follow-up.
Jesse Timmermans
This is nothing unusual, I would say. We're constantly marking our inventory on a monthly basis.
It just tends to be higher in times where inventory is higher and full-price mix is lower, so that's the dynamic this quarter. I wouldn't call out any specific categories per se.
I would say more on REVOLVE than FWRD. FWRD's in good shape relative to REVOLVE, but that's probably the only thing to call out there.
Ashley Owens
Understood. Then just on the store associate app you've rolled out, you called out the conversion improvements that you've seen.
Just be curious beyond that if you're seeing it show up in basket size or maybe by UPT, and if it's changing productivity or discovery in the store at all in a way that could matter to those four-wall economics as you kind of continue to scale the store base? Thanks.
Mike Karanikolas
The biggest impact we've seen from the rollout of the app has been increasing conversion rates when we have shoppers engaging with our associates in the dressing room or wherever. Increase in basket size and in AOV and all of that.
I think it's just incredible and shows how early stage we are within physical stores and also within AI, that we're able to roll out something like this and the conversion rates were quite meaningful, the increases. Also, just improving kind of store logistics and flow.
It was a much more fluid, easier system for the sales associates than they were doing before. Great success there, and excited to build on that.
Operator
We have reached the end of the Q&A session. I will now turn the call back to management for closing remarks.
Mike Karanikolas
Thank you everyone for joining us. It's been great to see the excitement and momentum build for our brand this year while continuing to invest for the future.
Excited about what's next.
Operator
This concludes today's call. Thank you for attending.
You may now disconnect.