Sea Limited
Q3 FY2026 · Earnings Call TranscriptNovember 10, 2026
Operator
Good morning, and good evening to all, and welcome to the Sea Limited Third Quarter 2026 Results Conference Call. All lines have been placed on mute to prevent any background noise.
After the speakers' remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press star followed by the number 1 on your telephone keypad.
If you would like to withdraw your question, press the star 1 again. For operator assistance throughout the call, please press star 0.
Finally, I would like to advise all participants that this call is being recorded. Thank you.
I'd now like to welcome Mr. Elson Choi to begin the conference.
Please go ahead.
Elson Choi
Hello everyone, and welcome to Sea's 2026 third quarter earnings conference call. I am Elson from Sea's Investor Relations team.
On this call, we may make forward-looking statements which are inherently subject to risk and uncertainties, and may not be realized in future for various reasons as stated in our press release. Also, this call includes the discussion of certain non-GAAP financial measures such as adjusted EBITDA.
We believe these measures can enhance our investors' understanding of the actual cash flows of our major businesses when used as a complement to our GAAP disclosures. For a discussion of the use of non-GAAP financial measures and reconciliation with the closest GAAP measures, please refer to the section on non-GAAP financial measures in our press release.
I have with me Sea's Chairman and Chief Executive Officer, Forrest Li, President, Chris Feng, and Chief Financial Officer, Tony Hou. Our management will share strategy and business updates, operating highlights, and financial performance for the third quarter of 2026.
This will be followed by a Q&A session in which we welcome any questions you have. With that, let me turn the call over to Forrest.
Forrest Li
Hello everyone, and thank you for joining today's call. Our strong momentum from the first half of the year has continued into the third quarter.
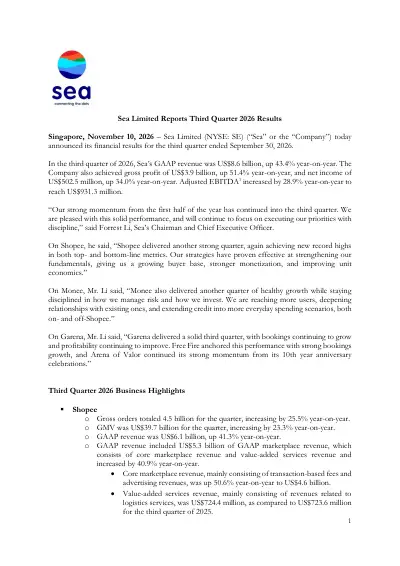
Sea achieved a new record high of $8.6 billion in revenue, up 43% year-on-year, and over $930 million in adjusted EBITDA, up 29% year-on-year. We are pleased with this solid performance and will continue to focus on executing our priorities with discipline.
With that, let me take you through each business's performance. Starting with Shopee.
Shopee delivered another strong quarter, again achieving new record highs in both top- and bottom-line metrics. GMV rose 23%, and gross orders rose 26% year-on-year.
Revenues reached a new high, and adjusted EBITDA reached $269 million, making this our most profitable quarter ever. The acceleration in new user growth we saw in the second quarter has continued into the third.
We engaged and reengaged a broad range of users through both online and offline campaigns, brought our content to more social and video platforms, and widened our service options, especially in delivery, to serve different user needs. With these efforts, new average monthly active buyers grew more than 50%, and the total average monthly active buyers increased by 20% year-on-year.
Monetization has also continued to do well, driven by ads. Sellers are responding well to the greater value they see in our AI-driven ad solutions.
Ad-paying sellers rose more than 35%, while average ad spend per seller increased around 13% year-on-year. Ad revenue grew more than 55%, and our ad take rate improved by over 80 basis points year-on-year.
Our operational priorities to enhance service quality, price competitiveness, and discovery remain consistent, and continue to be driven by our efforts in logistics, Shopee VIP, and our content ecosystem. Each made good progress this quarter.
First, logistics. We expanded our delivery options to serve a wider range of buyer needs, from instant and same-day delivery to low-cost services.
Our instant delivery service can now deliver as quickly as one hour. This has expanded our addressable market by unlocking new spending scenarios where speed matters most.
These tend to be high-frequency categories such as groceries and pharmaceutical items, boosting our overall purchase frequency. In Indonesia, orders using this service more than doubled year-on-year, with cost per order declining year-on-year.
Retailers there have embraced the service. We now have more than 12,000 offline stores on our instant platform, and growing.
Adoption is also growing in Thailand, where instant and same-day delivery now accounts for nearly 15% of orders in Greater Bangkok. We will continue to grow this service in areas where demand is high and unit economics make sense.
At the same time, we have continued to expand lower-cost delivery services to ensure that all users continue to have affordable, convenient options on Shopee. In the third quarter, buyer self-collection order penetration reached more than 30% in Singapore and more than 15% in Malaysia.
In Indonesia, our economical shipping option has gained strong adoption and now accounts for more than half of total orders. Its cost per order is more than 20% lower than the platform average in the market.
These initiatives allow us to offer free shipping at a lower minimum spend, giving our buyers the flexibility to choose between cost and speed, and letting us serve a broader range of buyers' needs. We have also continued to scale fulfillment quickly.
Sellers have responded well to our fulfillment offerings as we help them take on the complexity of storing, packing, and shipping. This represents significant efficiency gains for them, especially during peak campaign periods where orders may be several times higher than normal.
With our services, sellers can scale their businesses more easily without having to increase their own warehouse space or staff size. In the third quarter, fulfilled order volumes accelerated to around 25% quarter-on-quarter.
Unit economics for our Fulfilled by Shopee service improved sequentially in Asia, and we see further room to gain efficiencies through higher warehouse utilization and automation. Fulfillment also drives synergies with delivery, enabling us to deliver more packages more quickly.
The number of parcels delivered by the next day or sooner grew over 50% year-on-year, more than twice as fast as our overall order growth. Second, Shopee VIP is growing fast.
Membership across markets exceeded 21 million at the end of September, up more than 40% quarter-on-quarter, and the members contributed close to 25% of Shopee's overall GMV. The program is demonstrating stickiness, with monthly retention around 80%.
Members show a consistent double-digit percentage uplift in spend on average after subscribing, and with more sellers and partners investing alongside us in membership benefits, the program's unit economics improved sequentially. We have also continued to enhance the program's value proposition through new subscription tiers with more benefits.
In September, we introduced the Shopee VIP Plus in Indonesia, Thailand, and the Philippines, a higher subscription tier that combines core member benefits with a Netflix subscription. Third, our content ecosystem continues to make discovery more engaging.
Orders from livestreaming and short-form video grew more than 40% year-on-year, and accounted for more than 25% of physical goods orders in Southeast Asia. Unit economics also improved sequentially.
Beyond our app, our affiliate program remains an effective and growing channel to bring new buyers to Shopee from other platforms. In the third quarter, orders driven by YouTube content more than doubled year-on-year, and the Shopee affiliate orders generated by Facebook-linked creators grew more than 90% sequentially.
On Instagram, more than 4 million reels have been tagged with Shopee products since we launched the partnership in April, with the number growing more than four times quarter-on-quarter. Shopee is also one of the early connector partners for Meta's Muse AI personal assistant that has just launched in Singapore.
Users will be able to research and compare products on Shopee through Muse, helping them make purchase decisions tailored to their preferences. The partnership is still at an early stage, but we see potential for it to become a solid additional channel for buyer acquisition and incremental GMV growth over time.
Brazil remains our fastest-growing market, and we again grew faster than the broader market in the third quarter. Logistics improvements underpinned this growth.
We continued to widen the range of faster delivery options we offer across the country, with average buyer waiting time improving 12% year-on-year. We have branched into air delivery, cutting delivery times to the North and the Northeast regions significantly.
In Greater São Paulo, around 40% of parcels now arrive by the next day and nearly 50% within two days. Our new instant delivery service there, Shopee Turbo, already delivers in under four hours from more than 7,000 partner stores.
Stronger delivery capabilities have enabled us to onboard more sellers to fulfillment. For example, we rolled out an in-house delivery service for bulky items such as large appliances and furniture.
Combined with our strong service reputation and reliable cross-nation coverage, this has made more large-item sellers willing to fulfill with us. Across the country, fulfillment order volume more than doubled year-on-year.
These service quality improvements have helped drive stronger growth in higher-value categories. More upmarket buyers are joining Shopee, and existing buyers are shopping across more categories with us.
Automotive and home improvement categories grew more than 80% year-on-year, and more brand sellers have come on board. GMV from Shopee Mall sellers was up nearly two and a half times from a year ago, and Shopee Mall orders carried an average basket size almost three times the platform average.
Looking ahead, we see a lot of headroom to grow in this exciting market. In summary, Shopee delivered another quarter of strong growth while generating the highest quarterly profit we have ever achieved.
Our strategies have proven effective at strengthening our fundamentals, giving us a growing buyer base, stronger monetization, and improving unit economics. We still see a long runway of opportunity ahead, and we will keep executing with discipline to capture it.
We remain on track to deliver GMV growth of around 25% and an adjusted EBITDA of $1 billion for the full year of 2026. Next, moving to Monee.
Monee has grown well beyond its origins as a payment infrastructure serving our internal business needs. Today, it has evolved into a financial services business across mobile wallet, credit, digital banking, and more.
Monee has shown consistent, strong growth, and has been profitable for the last three fiscal years. We believe Monee has reached the scale and maturity to stand on its own and would benefit from becoming more independent.
Today, Monee is already one of the largest unsecured consumer lending companies in Southeast Asia, serving nearly 44 million active credit users, with a loan book of over $12 billion. Increasingly, Monee's growth is coming from beyond Shopee, and it is building direct relationships with users through standalone apps across Southeast Asia and Brazil.
Personal cash loans and off-Shopee loans made up around 60% of our loan book at the end of September, and average monthly transacting users on these apps more than doubled year-on-year in the third quarter. Our ambition is to keep growing Monee into a full financial ecosystem with inclusion at its heart, serving users across their lifecycle needs, from unsecured loans to secured lending, insurance, wealth management, and more.
We believe a standalone listing would give Monee the dedicated capital base it needs to build this ecosystem and let it invest for growth while managing risk with discipline. I want to be clear about what does not change.
Monee and Shopee will continue to work closely together as they do today. Monee will remain a key payment and credit partner for Shopee, and Shopee will remain a key platform for Monee to reach users.
Insights from our businesses will continue to empower Monee's growth. We hope to list Monee at the right time in the next one to three years, taking into consideration factors such as market conditions, macro environment, and regulatory requirements.
We will approach this carefully, working closely with our stakeholders in each market. Throughout, we aim to deliver value for our shareholders.
I'm very excited about what lies ahead. With that, let me take you through Monee's performance this quarter.
Monee delivered another quarter of healthy growth. Our loan book grew around 60% year-on-year to $12.6 billion at the end of September.
Unit economics are healthy, and we continue to invest where we see a clear path to attractive long-term returns. We continue to expand our credit business on three fronts: acquiring new users, deepening our relationships with existing users, and expanding our credit use cases.
Our user base continued to grow actively in the third quarter. We added nearly 6 million first-time borrowers, bringing active credit users to nearly 44 million, up around 28% year-on-year.
As borrowers build longer credit histories with us, we can progressively offer them higher limits, longer tenures, and more products. Average loan outstanding per user grew 23% in the third quarter year-on-year, and over 40% of our active credit users were using two or more of our credit products at the end of September.
SPayLater is becoming an everyday way to pay, both online and offline, in many of our markets. Our off-Shopee SPayLater portfolio more than doubled year-on-year to nearly 25% of our entire SPayLater portfolio at the end of September.
In Malaysia, its share is nearly 40%. In Thailand, the ShopeePay Unlimited Card allows SPayLater users to offset their approved SPayLater credit limit wherever Mastercard is accepted.
Monthly transacting users of the card in September grew more than 50% compared to a quarter ago. We are rolling the card out at a pace set by risk performance, and we plan to bring it to Malaysia later this year.
Risk management remains our top priority as we continue to grow our loan book. Our 90-day NPL ratio was 1.3% at the end of September.
The modest uptick primarily reflects an evolving credit environment, especially in Thailand and Brazil, as well as market and product mix, including faster growth in Brazil and off-Shopee SPayLater. Our underwriting is highly responsive to market conditions.
We proactively adjusted our underwriting criteria and credit limit management for selective customer segments at early signs of softness. To maintain disciplined growth and optimize risk-adjusted returns, we are staying close to the data and will keep adjusting as needed, our loan book growth stays healthy and sustainable.
In summary, Monee delivered healthy growth while staying disciplined in how we manage risk and how we invest. Our credit playbook remains consistent: start small, prove the economics, then scale.
We are reaching more users, deepening relationships with existing ones, and extending credit into more everyday spending scenarios, both on and off Shopee. Many of our initiatives are still in the early stages, and we are making good progress capturing the large, underserved opportunity across our markets.
Next, turning to Garena. Garena delivered a solid third quarter, with bookings continuing to grow from the high base set last year.
Profitability also improved. Free Fire anchored this performance with strong bookings growth, and Arena of Valor continued its strong momentum from its 10th-year anniversary celebrations.
In January last year, we released our smash-hit IP collaboration, Naruto Shippuden Chapter 1. This year, by popular demand, we brought it back with upgraded gameplay and fresh rewards rebuilt around top fan-requested content.
Our players loved the original campaign's most iconic moment when the anime's giant Nine-Tailed Fox descended on the battlefield as a threat that everyone had to survive. To build on it, we brought in one of the most important powers from the Naruto universe, the Sharingan.
This is an iconic ability the anime's most powerful characters used to control the Nine-Tailed Fox. Players could use it to make the giant creature attack their opponents, bringing the excitement of the moment to a new level.
We also expanded the map with places fun and apt to explore, like the Ninja School, where the main characters first trained. We continued to pay close attention to detail, including small but important elements like the swing where a young Naruto sat alone in the original anime that gave players an extra boost for the rest of the game.
Our care for authenticity has resonated with the players and the industry alike. Content around our Naruto Shippuden collaborations has generated more than 6.5 billion views on social media to date.
This quarter, we were also honored that our Naruto Shippuden Chapter 2 collaboration won the award for Best Use of IP or License at the 2026 Pocket Gamer Mobile Games Awards. Beyond Free Fire, Arena of Valor is celebrating its 10th anniversary this year.
Instead of one single event, we are making the entire year a celebration with a series of in-game content releases and our biggest-ever real-world events. We hosted AoV's biggest-ever offline celebrations with a concert at Taiwan's largest indoor venue, the Taipei Dome, the first-ever gaming event to be held there.
Around 30,000 fans came to see K-pop and local artists, many of whom had previously collaborated with us on music for AoV. We also transformed parts of Taipei into an AoV-themed city, collaborating with the metro stations and 7-Elevens, putting on anniversary exhibitions, and holding a light show at the iconic Taipei 101.
The campaign went viral, becoming the number-one trending topic on social media in Taiwan. 10 years in, AoV is still winning over new generations of players and deepening its bonds with long-time fans.
With this strong engagement, we believe that just like Free Fire, AoV will continue to be an evergreen game. In summary, Garena's performance this quarter showcases our ability to keep successful games fresh, listen closely to our players, and build lasting relationships with them.
We will remain focused on delivering engaging experiences and strengthening our franchises for the long term. In addition to our three existing business segments, we have always been exploring and experimenting with new businesses.
The most recent of these is SeaCloud, as we announced recently. As AI has taken off, we have built up meaningful capabilities over the past two years across the infrastructure, model, and agentic application layers, and our own businesses have benefited significantly from them.
SeaCloud looks to bring these capabilities to other organizations across all three layers. Today, there is a lot of focus on compute prices and cyclical margins, and having enough compute certainly matters, but we believe the ultimate prize lies elsewhere.
The cost of tokens is falling rapidly and structurally, and as it does, AI becomes affordable for far more organizations and far more use cases. The real opportunity is to build a significant business around the long-term decline in token prices, helping organizations drive much broader AI adoption.
We see much of the lasting value in the layers above bare-metal capacity. One is running AI efficiently, getting more out of every GPU through better utilization, faster deployment, and leaner operations, which we have mastered for our own businesses.
The other, and the more important over time, is the agents, software, and orchestration that help organizations put AI to work, running models reliably and securely, adapting them to their own data and languages, keeping that data close to home, and moving to newer and more cost-efficient models, including open models, as they emerge without having to rebuild each time. Many organizations want this, but few have the specialized teams to build it themselves.
That is where we intend to focus, and it is not theoretical for us. It is what we have had to do for our own businesses running AI at scale in areas such as fraud detection, customer service, and content generation under real commercial pressure, and in Monee's case, in highly regulated environments.
We see this as an opportunity to turn our AI capabilities, today a cost center for Sea, into a profit center. We are already making these investments for our own businesses.
By serving external customers on top of that existing base, we can spread our fixed costs across more users and earn attractive incremental returns on capital. This is consistent with how we have entered new businesses throughout our history, like Monee beginning as a payment infrastructure serving our own platforms before growing into a business serving customers well beyond them.
We are setting up SeaCloud as a frugal startup so that it can stay nimble and respond quickly to market demand. Our focus is the software and customer relationships, not owning large amounts of physical capacity.
Where customers need dedicated computing capacity, we will only pursue opportunities with clear customer commitments and attractive returns. We will mainly look to partners and customer prepayments to fund the physical infrastructure.
As a result, we do not expect SeaCloud to have a significant impact on our financials for now. It is still early, and we will update investors on any meaningful developments.
We also want to give an update on our share repurchase program. As of today, we have almost fully completed our $1 billion share repurchase program announced a year ago.
We are pleased to announce that we plan to buy back an additional $1 billion worth of shares. In conclusion, we have delivered another strong quarter.
Our three businesses have all expanded their addressable opportunity and strengthened their competitive position. Unit economics continue to improve across many of our initiatives, a testament to our financial discipline and operational efficiency.
Our positive momentum across the first three quarters gives us greater confidence for the rest of the year. As always, we greatly appreciate your trust and support.
With that, I invite Tony to discuss our financials.
Tony Hou
Thank you, Forrest, and thanks to everyone for joining the call. For Sea overall, total GAAP revenue increased 43% year-on-year to $8.6 billion in the third quarter of 2026.
This was primarily driven by growth in Shopee and Monee. Our total adjusted EBITDA was up by 29% year-on-year to $931 million in the third quarter of 2026.
On Shopee, gross orders increased 26% year-on-year to 4.5 billion in the third quarter of 2026, and GMV increased by 23% year-on-year to $39.7 billion in the third quarter of 2026. Our third quarter GAAP revenue of $6.1 billion included GAAP marketplace revenue of $5.3 billion, up 41% year-on-year, and GAAP product revenue of $0.7 billion.
Within GAAP marketplace revenue, core marketplace revenue, mainly consisting of transaction-based fees and advertising revenues, was $4.6 billion, up 51% year-on-year. Value-added services revenue, mainly consisting of revenues related to logistics services, was $0.7 billion.
Shopee adjusted EBITDA was up by 45% year-on-year to $269 million in the third quarter of 2026. Monee GAAP revenue was up by 64% year-on-year to $1.6 billion in the third quarter of 2026.
Adjusted EBITDA was up by 15% year-on-year to $298 million in the third quarter of 2026. As of the end of September, our consumer and SME loans principal outstanding reached $12.6 billion, up 60% year-on-year.
This consists of $11.2 billion on-book and $1.4 billion off-book loans principal outstanding. Nonperforming loans past due by more than 90 days as a percentage of total consumer and SME loans was 1.3% at the end of the quarter.
Garena bookings grew 6% year-on-year to $890 million. GAAP revenue was up by 29% year-on-year to $840 million.
The growth was primarily due to the increase in our active user base and deeper paying user penetration. Garena adjusted EBITDA was up by 46% year-on-year to $458 million.
Returning to our consolidated numbers, we recognized a net non-operating income of $123 million in the third quarter of 2026, compared to a net non-operating income of $61 million in the third quarter of 2025. We had a net income tax expense of $280 million in the third quarter of 2026, compared to net income tax expense of $161 million in the third quarter of 2025.
As a result, net income was up by 34% year-on-year to $502 million.
Elson Choi
Thank you, Forrest and Tony. We are now ready to open the call to questions.
Operator?
Operator
We will now begin the question and answer session. If you would like to ask a question during this time, simply press star followed by the number 1 on your telephone keypad.
If you would like to withdraw your question, press the star 1 again. In the interest of time, we will take a maximum of two questions at a time from each caller.
If you wish to ask more questions, please request to join the question queue again after your first questions have been addressed. At this time, we will pause momentarily to assemble our roster.
Your first question comes from the line of Alicia Yap with Citigroup. Your line is open, please go ahead.
Alicia Yap
Thank you. Good evening management.
Congrats on the solid set of results. Quick two questions.
First, wanted to ask on SeaCloud. As Sea plans to invest in cloud and AI infrastructure, how should investors think about the expected return profile for this investment?
What are the key use cases or demand drivers that give you confidence that SeaCloud can become a meaningful business over time? Second questions, Monee has reached a meaningful scale with over $12 billion in loans outstanding, 44 million active credit users, and also an increasingly diversified business beyond the Shopee ecosystem.
As you look ahead, what milestone do you believe are still needed before Monee can be viewed as a standalone financial platform? Strategically, how do you think about the benefits of keeping Monee integrated within Sea versus creating a more independent segment over time?
Thank you.
Forrest Li
Thank you, Alicia. For the SeaCloud business, as I just mentioned in my remark, this is a really pretty new initiative and this is at a very, very early stage.
We've been always thinking what is the potential new business opportunities we may have during the AI era. Continually, and increasingly, we believe eventually because of this new technology, both the consumers and organizations across the whole world, and especially in our region as well, will go through the AI transformation, and every organization need to build up certain AI capabilities, right?
This is including, of course, all the layers, including the compute capacity and including the models, and also how to use the model, how to deploy model, and in an affordable way, even in an efficient way, in a secure way. Also on top of that, what is the software can be used, and what is the agent can be built, right?
This is going to make a meaningful impact. I think actually it's not an easy process, and this will be take time, and this will take quite some effort for that transformation.
In the past a few years, we have gone through this for our own businesses first hand. Although this is very, very challenging, we put a lot of effort, we are also very excited about the impact it can be made, right?
In my remark, I mentioned specifically several cases, like fraud detection, customer service, content generation, this is benefit our business significantly on the daily basis. We have a strong conviction, and what this capability we have built, this know-how and knowledge we have learned through our own use case experience will be valuable to other organizations as well.
Also it's not any other organization has the same technical capability and uses as we have today in-house allow us to build such capability from the scratch. That's why we think the aspiration is really externalize what we already have, and as the internal capability and resources, but become a standard, kind of a new businesses to serve the external customers.
We also believe the adoption will be accelerated because of the model is getting better and better, and the agent can do more and more things, and also the token costs will be continually go down. This is will make the entire kind of this AI demand more affordable and more accessible, and in accelerated pace.
That is a kind of the big picture we are looking at. We think the demand will be huge, and this is just at a very, very early stage.
We want to get into this business early. There's a lot of things we don't know yet, and again, this is very early, this is a kind of a startup, there's a lot of things we need to figure out.
For example, who are exactly the segment we should focus on, who are exactly type of customers we should focus on, and what is the best business model we should use. We think we'll get a better picture when we really get our own feet into the game, and we start to get first-hand experience.
I hope, and also I'm sure the learning will be very, very quick, right? When you really have kind of a real business working on that.
We feel in the past, although this is very early, in the past a few months, we have gained a lot of insight and learning about the potential opportunities we have. I think we're going to keep investors updated.
At the same time, because of this is a very new and there's a very dynamic situation and opportunity, we want to make sure we'll be very, very frugal in terms of the capital expenditure, in terms of the cash flow spending. I think whatever the opportunity we are looking at, the top down, we just shared, we believe in the big potential ahead of us.
Bottom up, when we look at each potential, each project, each customer, each potential deal, we're very much kind of disciplined in terms of what is a return we're looking at, what is it mean to us financially. I don't think at this moment we have a very, very clear as overall as a business, what will be the return on investment look like.
We believe this is will be very, very good. Again, we also want to stay humble.
There's a lot of things we don't know what we don't know. Bottom up, for each project, we'll keep the financial discipline very, very seriously, and we want to make sure every project we work on will be generate attractive return for us, and minimize our potential financial risk, if there's any.
I think that is our overall thinking we have for this SeaCloud businesses, still at a formation stage. It's a very, very different profile compared to the three existing businesses we have.
It's take us a decade to build up the three existing businesses to today's stage. I think the SeaCloud will be really, really a long-term bet, right?
This is one of the bet we have in the AI times. We are very excited about it, and we'll keep our investors and shareholders updated if there's any major development on that front.
For your question about the Monee IPO, again, this is a very, very exciting project. It always has been our aspiration to build Monee into a standalone financial services business, and we believe, and Monee have the potential to be one of the best in the world in the fintech businesses.
I think we are on the right track now. Now we feel comfortable.
The thing is it can reach the stage and scale can be sustainable itself. I think being listing standalone will give more room and more flexibility for Monee to continually grow.
In the past, Monee has been benefit hugely being part of the Sea, and being integrated, being part of the integrated system. I think that is a very, very critical success factor for Monee in the past.
I think moving forward, we expect Monee will continually grow, and it's not only rely on the Sea ecosystem, but really have the courage and have the flexibility and have the room to grow out of it. Meanwhile, please don't get it wrong.
I think as I shared in my remark, whatever the benefit, and being together with the Sea and with Shopee in the past will be still there, right? As I mentioned, there will be still very, very integrated, tight collaborations between Shopee and Monee, right?
There's a huge synergy, we are definitely not give it away. Also at the same time, I think from the Sea perspective, that the capability we built during the AI era, with continually the technical support enabler for Monee's growth.
I think that is kind of our thinking for now. Again, we are not in any rush.
I think we just want to share this directional move with investors, shareholders as early as possible. We are looking at one to three year timeline.
There's a lot of things when we start to take off the process, there will be a lot of learnings and we will weigh the different ways of doing that and the pros and the cons. I think at the same time, we're going to keep all the shareholders and investors updated along the journey as well.
Operator
Your next question comes from the line of Divya Kothiyal with Morgan Stanley. Your line is open.
Divya Kothiyal
Thank you very much. My first question is on Shopee, and really, when does the monetization actually start flowing through profitability?
We saw that despite the strong growth in take rates and advertising, margins are still flat quarter-on-quarter at about 68 basis points. Could you elaborate what absorbed these monetization gains specifically, and which investments should start delivering some sort of operating leverage next year?
If you could also comment on the profitability runway difference between ASEAN and Brazil, as well as between content or ecosystem versus shelves. That's my first question on Shopee profitability.
My second question is just on agentic AI in Shopee. You are an early connector partner for Muse, as you mentioned.
If product discovery moves to an internal agent, how do the economics of a Shopee order change, particularly the advertising revenue and the contribution profit? Do you actually retain the customer relationship and data?
If you could also comment on how Migu is performing on adoption and conversion, and how do you see its role in Shopee as the agentic AI going forward? Thanks.
Chris Feng
On the Shopee side, for the monetization that you mentioned, we do see better monetization over the quarters. As you pointed out that, our EBITDA also remained relatively stable from the quarter to quarter.
I think overall, the thinking we have is that we still see there is quite a lot of growth potential in both South Asia and Brazil market. In fact, that, if you look at our gross rate, we grow 23% plus this year, this quarter.
If you look at the growth without the forex impact, we grow more than 26%, close to 26.5%. We still see a lot of potential in our market.
We would like to grow e-commerce penetration further in both South Asia and Brazil market. At the same time, as Forrest mentioned in the opening remarks, that we commit to have our EBITDA more than $1 billion this year.
I think we still hold that as our standard. We expect going forward, our monetization will also be better, primarily from the ad side, less from the fixed commission side.
Part of that will flow to the bottom-line EBITDA improvement over time. Part of that might go to the investment to grow our market further as well.
Between Brazil and South Asia, I don't think there's a particular difference in term of trend between the two regions. I think both Brazil and South Asia are relatively stable if you look at from quarter-to-quarter perspective.
For content side, content for us comprised of, let's say, both videos and livestreams. Our content ecosystem has been growing year to year and quarter to quarter.
At same time, our profitability also grow better for content as well. If you look at contribution margin perspective, our content part of business has been profitable already for this quarter, which is a very good milestone for us to achieve.
Coming to the second question on the agentic AI, we actually partner with a range of partners, starting from ChatGPT, now as you mentioned, the Muse. At this point of time, all the checkout and a seller relationship and buyer relationship happens within the Shopee platform.
We wouldn't see a meaningful impact to our economics for the near future. At the same time, I would like to point out that we work with many platforms as affiliate partners as well.
For example, we've been working very closely with both YouTube and Meta for Facebook and Instagram as affiliate partners, which works similar to the fashion we work with platform like Muse. Affiliate partner, we've been generating a sizeable new users to our platform, generating a sizeable traffic to our platform, and it has been part of our unit economics in the past years.
We don't see this will dramatically change the picture when we work with Muse or ChatGPT.
Operator
Your next question comes from the line of Piyush Choudhary with HSBC. Your line is open.
Piyush Choudhary
Hi. Thanks a lot and congratulations on a good set of numbers.
Two questions: firstly on Shopee, when do you think the peak investments would pass, considering the ongoing investment in Shopee VIP, instant delivery, fulfillment? Did I hear correctly that content ecosystem is now EBITDA positive?
Or if not, then how much is the drag on profitability? Can you also share what's the progress on fulfillment, both in Asia and Brazil?
Second question on SeaCloud. You have explained in detail your aspirations, but can I check if you have secured any enterprise contracts already?
Just to clarify, would you invest in data center and GPUs, or would it be capex-light, where you will lease these assets? Any guardrails if you have put on maximum capital investment over the next two to three years in this segment would be great.
Thank you.
Chris Feng
Yeah. I think we've been investing in the Shopee VIP and fulfillment, and also the other initiatives like the instant delivery, etc., across our countries.
It's a bit hard to argue when is the peak investment, as we roll out this program in different countries, different market at different timeframe. If you look at our early countries that we started, let's say, some of the program, it has passed the peak investment, but there are some other countries come to later.
The mix of country and the pace of it has a lot of impact to in term of the pace of investment. In any case, as I shared earlier in the previous answers, we do see the bottom line, essentially the EBITDA per GMV, the EBITDA will continue to improve year over year, which includes all the investment to these programs.
We manage it within sort of how much take rate we can take and how much investment we can make while growing the ecosystem and the user base. For content ecosystem, which includes video, livestream, I think it's a bit hard to split a particular segment to the EBITDA level because there are many shared costs below that.
I think, for us, we look at sort of variable cost or contribution margin to our platforms. The content platform that has a positive contribution margins.
Essentially, what we are saying is, if we grow content a bit more in our platforms, we'll have more profit rather than has less profit for our businesses. The fulfillment penetration, I think the overall fulfillment has been growing quite a lot year over year.
We started this in South Asia earlier than Brazil. In reality is, the penetration in South Asia will have slightly higher percentage as overall platform than Brazil.
We do believe that the penetration will further grow in both Brazil and South Asia. The other thing that we spend a lot of time on is to optimize the cost to fulfill, which is very important for us.
We're seeing meaningful reduction in both South Asia and Brazil for our cost to fulfill for our fulfillment businesses. Part of that contributed by the scale that we've been built over time.
Part of that contribution by a better automations, which is very important tools for us to reduce the cost to fulfill compared to many of our sellers. Part of that also comes from how to optimize the way we work with that sellers, the way we inbound the product selection we have, how long do we keep the product in our fulfillment centers, etc.
I think all those contribute to the growth of fulfillment while improving the economics for fulfillment over time. Piyush, for SeaCloud, for your question, as this is just at the very, very beginning of the business.
At this moment, we, we don't have an, any, we haven't secured any enterprise contracts. And, for the investment in the data center and the GPUs, we, let me put in this way, like, we definitely probably will, will invest in the, in the, GPUs, and, primarily, for our own use.
Regardless, there's a SeaCloud business or not, like how, how the business will progress, down the road, we are going to, invest into GPUs, and primarily for all the internal use cases.
Forrest Li
In the data centers, we'll, we'll, we'll see how the opportunity, look like. In generally, we are not interested kind of like, to in-, to spend to invest in data centers, but we may spend money to build data centers for, our own use cases, for our, primarily for our uses.
For example, for, for our financial services business, for Monee, right? And, based on regulations, a lot of, like, data, need to stay in Singapore.
That's the, and, for, for those cases, it could be we'll evaluate the, the, the options, right, in terms of the, build up our own data centers, and because this is a very, very clear, like a usage, and a very, very clear use case, versus, leasing the data center capacity, right? And, I, I would say, we're, we are going to be open-minded on that part.
Again, I would say this is have nothing to do with the, SeaCloud business, it's a, it's in general from Sea perspective, we'll keep those options open. In terms of the, guardrail on capital investment here, as I mentioned, we'll be very, very, cautious, right?
And, the, the good things, like it's a, it's a, it's different from the, consumer business, like you have to, have a, have a spend a huge amount of, investment up front, and then, along the way, like to reach the critical mass, and start to, because of the, the density, because of the, because of the volume, and you start to see the, unit economics from, negative to positive, like we, we have, we have gone through several rounds of that, we know that part very, very well. Like, the, the business nature is a bit different for, from the SeaCloud as I think it's a, will be very much, deal-by-deal driven, at least at the beginning stage, and with very, very specific, like a target in terms of customers, in terms of the, the projection of the revenue, and like what is the timeline for that, and what is the potential investment we put in.
I think it's a, I think we are going to have a guardrail, we want to, as I mentioned in the, in the, in the remark, we're only pursued opportunity, with a clear, like, clear customer commitment and a clear return profile, right? And, we are going to, make the case-by-case judgment if that return is good enough for us or not.
We don't have to pursue the opportunities if we don't like the, the return profile. And, and, and, and at the same time, we are going to, try all the ways to, to minimize the impact on our own financials, and, especially the cash flow, the, the, the balance sheet.
I think there's a lot of ways to work with potential partners, right, and, a lot of things can be worked with the, through the, the, the customer prepayments, right, so, but the, the, the spirit is that we're going to, we're going to, minimize our, our own financial, impact, yeah.
Operator
Your next question comes from Thomas Chong with Jefferies. Your line is open.
Thomas Chong
Hi, good evening. Thanks management for picking my question.
I also have a two question. The first question is also on the SeaCloud business.
Given that we have talk about is a project-by-project basis, and we also look into the return profile, I just want to get some color from management strategic perspective. If we look at three years or five years down the road in terms of our business mix or our profit mix, how significance is SeaCloud to our overall business?
Would that become another very meaningful business three to five years down the road? That's my first question.
My second question is back to Shopee business outlook. Given that we are seeing the macro is very dynamic, fuel price and other macro uncertainties, how should we think about our GMV outlook or growth rate going down the road?
Are we actually expecting a meaningful slowdown, or a gradual slowdown, given all these headwinds? Thank you.
Forrest Li
Thank you, Thomas. For SeaCloud, strategically and in the big picture, we are very, very bullish, we are very optimistic.
As I shared, and so number one, we believe AI, it's a fantastic technology. This will be make huge impact for every single organizations, every single business.
Every organization, every single business will need to right away, they need to figure out their own strategy and the action plans, executions, how to make that the transformation, and how to make them relevant in the AI era. If you look from that perspective, the demand is huge.
The second things we bet on is the AI adoption across all the industries will be accelerated. It's mainly because the model is getting better, and the agent can do more things, and can real make impact in the workflow, and in the day-to-day use cases.
At the same time, the token cost and the token price is going down rapidly. This will give us the conviction, and the opportunity could be huge.
Beyond this, this will happen in three years or five years, as it's depends. I don't have a very, very clear view, and things go very, very fast in this industry, right?
To be honest, I don't have the exact perspective on that specific timeline. We build this business is not only for three years or five years, we want to build it become a sustainable business, become a part of our businesses permanently.
That's the aspiration. Of course, we only do this if we do believe this will generate a very, very meaningful, a very, very sizable revenue and a profit for us down the road, yeah.
Yeah,
Chris Feng
on the, Shopee growth, first of all, we don't see a, a big, Shopee GMV growth rate slowdown, yet. As we shared earlier, in Q3, we do see, a meaningful growth, a similar growth rate as compared to last quarter, from a year-to-year perspective, if we take away the, forex impact.
You are right that there are many, macro factors like fuel price, etc., impacting, the consumptions. The, the overall what we see that, although we have noticed, some more value-seeking behaviors, in, in, in our markets due to all this macro environment, but the, general overall demand has relatively, resistant.
Again, I would like to reiterate that, our competitive advantage will continue to differentiate us from the peers, even in, the macro situation, that we are in right now, giving that we are, we build, our platform around, long-tail products, and also, the pricing in our platform, is a lot more competitive compared to other platforms online or compared to the alternative, offline as well. On top of that, many of our, large part of our, platform's, GMV are driven by, the people has the needs to purchase rather than people has the impulse buying.
All those, make us, put us in a more, resilient positions, on the, the growth for our e-commerce, in our market. I think we will continue to, monitor our market very closely, for any changes.
Again, giving all the things we mentioned above, and also the, e-commerce penetration are still, relatively, low compared to many other markets, we still believe that there is, a big runway, for us to grow our e-commerce in the regions.
Operator
This concludes our question and answer session. I would like to turn the conference call back over to Mr.
Elson Choi for any closing remarks.
Elson Choi
Thank you all for joining today's call. We look forward to speaking to all of you again next quarter.
Operator
The conference has now concluded. Thank you for attending today's presentation.
You may now disconnect.