Sight Sciences, Inc.
NNASDAQ:SGHTQ3 FY2026 · Earnings Call TranscriptNovember 4, 2026
Operator
Good day, and thank you for standing by. Welcome to the Sight Sciences Third Quarter Earnings Results Conference Call.
At this time, all participants are in a listen-only mode. After the speakers' presentation, there will be a question-and-answer session.
To ask a question during the session, you'll need to press *11 on your telephone. You will then hear an automated message advising that your hand is raised.
To withdraw your question, please press *11 again. Please be advised that today's conference is being recorded.
I would now like to hand the conference over to your first speaker today, Hannah Jeffrey, Investor Relations.
Hannah Jeffrey
Thank you for participating in today's call. Presenting today are Sight Sciences' Co-Founder and Chief Executive Officer, Paul Badawi, and Chief Financial Officer, Jim Rodberg.
Also in attendance is Sight Sciences' Chief Operating Officer, Ali Bauerlein. Earlier today, Sight Sciences released financial results for the third quarter ended September 30th, 2026, raised its revenue guidance, and maintained its adjusted operating expense guidance for the full year 2026.
A copy of the press release is available on our website at investors.sightsciences.com. I would like to remind everyone that comments made by management today and answers to questions will include forward-looking statements within the meaning of federal securities laws.
These statements are based on plans and expectations as of today, which may change over time. In addition, actual results could differ materially from projected results due to a number of risks and uncertainties.
For a discussion of risks and other factors that may affect the company's future financial results and business, please refer to the earnings release issued prior to this call and the company's SEC filings. We undertake no obligation to publicly update or revise any forward-looking statements except as required by law.
Also on this call, management refers to certain financial measures that are not prepared in accordance with generally accepted accounting principles in the United States, including adjusted operating expenses. We believe these non-GAAP financial measures are important indicators of the company's operating performance because they exclude items that are unrelated to and may not be indicative of its core operating results.
See our earnings release for a reconciliation of these non-GAAP financial measures to the most directly comparable GAAP financial measures, as well as additional information about our reliance on non-GAAP financial measures. I'll now turn the call over to Paul.
Paul Badawi
Thanks, Hannah. Good afternoon, and thank you for joining us.
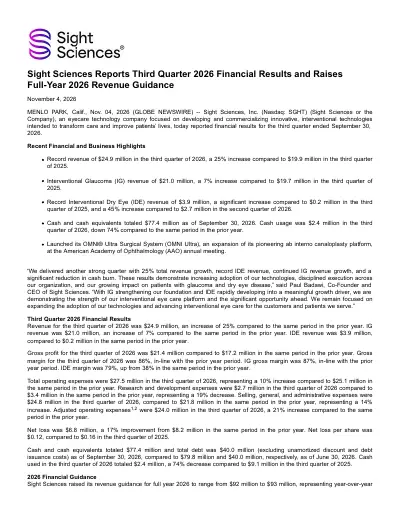
We are extremely proud of our results again this quarter, where we reported record revenue of $24.9 million, growing 25% year-over-year. This marks our third consecutive quarter of double-digit growth, and second consecutive quarter of 20% growth or greater.
IDE revenue continues to scale rapidly, and reached another record quarter, with revenue of $3.9 million. IG continued its momentum and grew 7% to $21 million.
Notably, we delivered this high-growth performance while both investing in our growth drivers and significantly improving our cash burn, highlighting the operating leverage in our commercial model. Based on our strong results and outlook, we are raising our full year 2026 revenue guidance, while maintaining our adjusted operating expense guidance.
At Sight Sciences, we are focused on delivering minimally invasive technologies that address the underlying cause of two of the most common anterior segment diseases, glaucoma and dry eye disease. As the pioneer and creator of two interventional eye care categories within glaucoma and dry eye disease, Sight Sciences has taken an important leadership position in interventional eye care.
To date, our products have now been used in over 500,000 procedures. As the treatment paradigm continues to shift toward earlier procedure-based care, we are well positioned to drive expanded adoption of our technologies and improve access to earlier intervention for the patients we serve.
This opportunity is particularly compelling because glaucoma and dry eye disease are increasingly seen within the same patients, practices, and treatment pathways, reinforcing our conviction that OMNI and TearCare are synergistic interventional growth drivers. Within our company, we have created a third area of focus beyond IG and IDE, called the intersection of intervention, or IX.
IX is where Sight Sciences becomes more than a portfolio of products. It creates a scalable interventional eye care platform with common customers, overlapping patients, and a shared procedure-based model that can create commercial leverage across glaucoma and dry eye.
At last month's American Academy of Ophthalmology's annual meeting in New Orleans, we had the privilege of celebrating the IX partners who have adopted both OMNI and TearCare into their practices, and have been instrumental in leading the advancement of interventional patient care. Importantly, our established relationships in glaucoma are helping accelerate adoption of TearCare, creating a powerful connection between our two technologies.
We believe this synergy represents a durable growth driver and reinforces our position as a leader in interventional eye care. Now turning to our segments, beginning with IDE, where we delivered another record quarter and generated third quarter revenue of $3.9 million, an increase of 45% from the second quarter.
This continued traction reflects growing TearCare adoption in the reimbursed market and further progress in building a durable, recurring, procedural revenue model. Based on this momentum, we are increasing our full year IDE revenue outlook to approximately $12 million, up from the previous range of $9 to $11 million.
Looking closer at this quarter's results, the underlying metrics of our IDE business continued to strengthen, with increases in both ordering accounts and utilization. Ordering accounts rose to 222, up from 176 in the second quarter, and those accounts purchased approximately 4,600 SmartLids, up from approximately 3,100 in the second quarter.
Average utilization climbed to 21 SmartLids per ordering account, compared to 18 in the second quarter. Notably, utilization increased as we added new ordering accounts, reflecting deeper adoption of TearCare across our customer base.
Growth in both ordering accounts and utilization is the foundation of a durable, recurring procedural revenue model, and continued progress on both remains central to scaling our IDE business. The early adoption metrics highlight the significant opportunity ahead for the more than 7 million patients suffering from moderate-to-severe MGD.
We continue to sharpen our go-to-market strategy as we learn from the commercial adoption of TearCare in areas with market access. We are focused on practices that already manage a high volume of dry eye patients and have embraced a procedural approach, and we are adding targeted sales and clinic support capacity to help practices quickly establish workflows and build a consistent patient flow.
This disciplined, focused model allows us to grow efficiently today, while positioning us to scale rapidly as market access expands. Earlier in the quarter, we announced an FDA label expansion for TearCare, making it the first and only treatment for MGD indicated to improve meibomian gland function in patients suffering from dry eye disease.
This updated label marks an important milestone for TearCare. While the benefits of the procedure already resonate with our customers and their patients, this label expansion recognizes TearCare's ability to improve physiological function and ultimately address the underlying cause of disease, enabling our team to strengthen the message around the benefits of the procedure for patients.
Expanding equitable market access to the only reimbursed procedural intervention for the millions of patients suffering from MGD remains a top priority. We continue to advance this priority through productive dialogue with multiple payers, and anticipate that they will establish fee schedules and/or coverage policies in the coming quarters.
To this end, we continue to invest in our team to drive the expansion of market access for TearCare through heightened engagement with MACs and commercial payers. In our conversations, we continue to highlight TearCare's robust clinical evidence, favorable health economic profile, and increasing adoption in everyday clinical practice.
At the same time, we remain focused on commercially executing within the serviceable market already in front of us. We believe continued execution in these regions can drive meaningful growth, with additional positive payer decisions serving as important accelerators.
Overall, IDE delivered another record quarter, with growth in both ordering accounts and utilization, and an expanded FDA label that better reflects TearCare's full value. Our results to date have come from a focused commercial team operating in a limited reimbursed footprint, and we believe they demonstrate the significance of this opportunity when patients have access to it.
As market access expands, we believe our commercial model can scale efficiently into new regions, positioning us to pioneer and lead this category and drive significant growth in the years ahead. Moving to IG, third quarter revenue was $21 million, an increase of 7% compared with the prior year period.
This was our fifth consecutive quarter of growth, and importantly, active accounts reached another all-time high in the quarter. Based on this performance, we now expect increased full year IG revenue of $80 to $81 million, compared to our prior range of $79 to $81 million.
Our strategic priorities remain unchanged as we continue to focus on training new surgeons, driving deeper utilization across our existing customer base, and capturing a larger share of combo-cataract cases, while also continuing to activate the standalone opportunity. We were also encouraged by the expansion of OMNI and SION coverage through Aetna earlier in the quarter, adding approximately 25 million additional covered lives.
Together, these efforts are strengthening our implant-free glaucoma franchise, deepening our customer relationships, and creating a solid foundation for our leading interventional eye care platform. Shortly before our last earnings call, we announced FDA 510(k) clearance of OMNI Ultra, the next-generation technology in our OMNI product line.
Following an initial limited rollout, we launched Ultra commercially in the US at the AAO annual meeting in New Orleans in October. We are excited about the launch and believe Ultra can support sustained growth in our IG business by appealing to a broad range of surgeons and deepening engagement across our customer base.
Developed with direct input from surgeon customers, Ultra includes single-pass canaloplasty, TruSync Plus for automated viscodilation, and improved catheter visualization. Early users have responded very positively to its versatility, ease of use, and meaningful improvements over the prior generation of OMNI.
Ultra builds on our legacy as the pioneer of ab interno canaloplasty, and demonstrates our continued commitment to innovation, further strengthening our leadership position in implant-free MIGS. In standalone, our market development work continues to focus on helping practices implement a repeatable interventional glaucoma activation workflow.
This workflow was designed with the cataract workflow in mind, a familiar and effective model for practices, and is intended to help move the standalone opportunity from physician education to practical activation. We believe this helps providers identify appropriate patients, integrate the procedure into clinic operations, and build more consistent adoption.
The standalone market is growing, and it remains a large, underpenetrated opportunity. We believe the work we have done is beginning to contribute to growth today, and is an important step toward expanding the role of interventional glaucoma in the treatment algorithm.
In summary, we are proud of the performance across both of our interventional segments in the third quarter. In IDE, we are driving significant growth with a concentrated commercial team as we prepare to scale efficiently upon achieving broader market access.
In IG, we are looking forward to the full launch of OMNI Ultra over the coming quarters and sustaining our growth trajectory. Finally, the unique overlap between our two businesses serves as an important growth driver, and we are excited to be leading the intersection of intervention as it further evolves into a compelling catalyst for Sight Sciences.
With that, I'll turn the call over to Jim to discuss our third quarter financial results and updated 2026 guidance.
Jim Rodberg
Thanks, Paul. Third quarter revenue was a record $24.9 million, an increase of 25% year-over-year, and our third consecutive quarter of double-digit growth.
IG revenue was $21 million, up 7% compared to the prior year period, driven primarily by higher volumes, a record number of active accounts, and stronger utilization than the prior year period. IDE revenue reached a record $3.9 million, increasing 45% sequentially from the second quarter, driven by growth in both ordering accounts and utilization as the business continues to scale.
Gross margin was 86%, in line with the prior year period. IG gross margin was 87%, consistent with the prior year period.
IDE gross margin was 79%, up significantly from 38% in the same period in the prior year, primarily due to higher average selling prices. Total operating expenses were $27.5 million in the third quarter, representing a 10% increase compared to $25.1 million in the prior year period.
The increase was largely due to higher personnel-related expenses from additional commercial investments to drive revenue growth. Adjusted operating expenses were $24 million, up 21% compared to $19.8 million in the same period in the prior year.
The increase year-over-year reflects a lower expense base in 2025, following last year's realignment of our cost structure, as well as investments we have made in 2026 for growth in both segments. These investments were most significant in resources to scale the IDE business, and we expect to continue those investments through the end of the year.
Year-to-date, revenue grew 19%, while adjusted operating expenses declined 2% compared to the prior year period. Net loss was $6.8 million, a 17% improvement from $8.2 million in the prior year period.
Net loss per share was $0.12, compared to $0.16 in the third quarter of 2025. We ended the quarter with $77.4 million of cash and cash equivalents, compared to $79.8 million at the end of the second quarter.
Cash used in the quarter was $2.4 million, an improvement of 74% from $9.1 million in the third quarter of 2025. Year-to-date cash usage improved 48% to $14.6 million.
Importantly, we achieved this improvement in cash burn while continuing to invest in revenue growth across both businesses, underscoring the operating leverage in our model. We ended the quarter with $40 million of debt, excluding unamortized discount and debt issuance costs, and in October, we extended the interest-only period on our debt by 6 months to August 2027.
We remain well positioned to achieve cash flow breakeven without the need to raise additional equity capital. Moving to our full year 2026 outlook, we are raising total revenue guidance to $92 to $93 million, up from $88 to $92 million.
This includes IDE revenue of approximately $12 million, up from $9 to $11 million, and IG revenue of $80 to $81 million, up compared to $79 to $81 million previously. Our updated outlook represents approximately 20% full year revenue growth, driven by continued momentum in IG and a meaningfully higher contribution from IDE.
We are maintaining adjusted operating expense guidance of $92 to $94 million, representing full year growth of 5% to 7% compared to prior year. In closing, the third quarter demonstrated the strength and momentum of our business: record revenue growing 25%, sustained growth in IG, continued acceleration of our IDE business, and significant improvement in cash burn.
We are raising our revenue outlook, while maintaining adjusted operating expense guidance, reinforcing our confidence in the growth trajectory and operating leverage of the business. We remain focused on investing to drive strong revenue growth, while simultaneously improving profitability and cash flow.
Operator, please open the line for questions.
Operator
Thank you. At this time, we are ready to conduct the question-and-answer session.
As a reminder, to ask a question, you will need to press *11 on your telephone and wait for your name to be announced. To withdraw your question, please press *11 again.
Please stand by while we compile the Q&A roster. For our first question, we're going to be taking from Frank Takkinen from Lake Street Capital Markets.
Your line is now open.
Frank Takkinen
Great, thanks for taking the questions, and congrats on another really solid quarter. I was hoping to start with one on the 2026 guidance.
Obviously, all metrics are pointing to a lot of momentum in the business, and if you look at the guide, it's kind of implying slightly down quarter-over-quarter, or flat quarter-over-quarter at the high end of the range. Why might this be?
Maybe speak a little bit to each of the businesses, and if there's conservatism baked in, or if there's anything else going on with those businesses that might support that.
Jim Rodberg
Thanks Frank. This is Jim.
I can start here, and others chime in as needed. Look, I think for the full year revenue guide here, we're really proud of getting back to high growth, now at almost 20% for the full year, and both interventional businesses here performing ahead of expectations, and another raise here for the end of the year.
Now, first in IG, the underlying strength of that business, the fundamentals, we're really, really excited about that, and have had excellent execution all year long. We exit Q3 with record active accounts, strong utilization, stable pricing, and excited about the Ultra launch here in Q4 that will be a tailwind as we head into 2027.
On the glaucoma business, really strong fundamentals, have performed really well year-to-date, expect that momentum to continue into Q4, and carry into 2027 with momentum. On the IDE side, we're continuing to scale that business rapidly, and the team's done an exceptional job with revenue reaching record amounts each quarter, a couple of doubles in there early in the year, and the confidence we have in that business, we continue to outperform and raise with revenue accelerating, active accounts now up to 222, and utilization improving.
We look forward to executing well here in Q4 as we've done all year, and exiting the year here with strength, and entering 2027 with a lot of momentum.
Frank Takkinen
Got it, that's really helpful. Maybe for my follow-up, just on that last point you made around kind of ramping accounts relatively quickly and utilization outperforming, can you maybe parse out what some higher-level sites are doing from a utilization standpoint, and try and give us a feel for where this utilization level can go over time?
It feels like there's a lot of room to go on it still, and it's obviously outpacing even a pretty good clip of new accounts. Maybe talk to where that utilization metric can go over time.
Thanks so much.
Ali Bauerlein
Frank, I'll take that one. This is Ali, and we are really proud of the fact that we're seeing growing utilization across our customer base, and that's while we're also adding new accounts, and, obviously, newer accounts typically have lower utilization than accounts who have been doing this for a couple of quarters and have really been building out their IDE business.
We aren't going to provide specifics of levels of utilization, but I think with any type of early stage with early adopters, you see a wider range of utilization, and we do have some accounts doing significantly more utilization than that average metric that we provide, and then we have others that are still very early in their adoption curves and are more cautious in the amount of procedures that they're doing while they're still building out their workflow and testing claims. We do think that there is a lot of room for us to continue to grow utilization over time.
As right now we really are focused on customers that have a larger base of traditional Medicare patients because that's where fee schedules are established, but the larger portion of the market is patients that are on more traditional commercial plans, and so those are opportunities over time to also increase density with our customer base as we expand market access. Hopefully that little bit of color helps.
Frank Takkinen
That's great. Thanks for taking the questions.
Congrats again on the quarter.
Jim Rodberg
Thanks, Frank.
Operator
Our next question comes from Tom Stephan from Stifel. Your line is now open.
Tom Stephan
Great, thanks guys. Appreciate you taking the questions.
I'll start out on 2027, and I'll take a stab here, but not looking for guidance, but I look at consensus, and I think I'm seeing kind of low double-digit percent revenue growth next year. Maybe just your level of confidence in that being the right starting point for street models heading into next year.
Then what does glaucoma look like within that? I think the two-year CAGR for '26 on glaucoma revs might shake out at around 3%, but street has, I want to say, mid-to-high single-digit percent growth next year.
Maybe if you can comment, even directionally, on those consensus numbers and your level of confidence both for total revs and glaucoma as well. Thanks.
Jim Rodberg
Thanks, Tom. I'll take that one.
This is Jim. You're right, we're not going to get into specifics around 2027 guidance today, but I would emphasize we're very proud to be back in growth mode in both of these businesses, and as we mentioned in our prepared remarks, revenue now growing 20% at the midpoint in our updated guide.
We exit '26 with a lot of strength and momentum heading into 2027. In IG, our fifth consecutive quarter of growth, record number of active accounts, and Ultra providing hopefully a tailwind here heading into next year.
We're very excited about the launch of that. On the IG side, growing this year 6% to 7% in the updated guide is a really great performance by our team.
It's a healthier, growing market, and we would expect that momentum to continue here into Q4, and that to be a stable, durable growth engine for us in the future. On IDE, very early, as we've said, in that business and scaling it up, and, like Ali said, very proud of the progress we've made there and in delivering record revenue each quarter.
I think as we look at that business, we're focused on a couple things in 2027: one, scaling up within First Coast and Novitas, adding active accounts, increasing utilization, and at the same time, working on expanding market access for additional growth opportunities. We'll get into more specifics on the 2027 guide in an upcoming call, and I just want to say, I think we feel very confident in where the business has performed this year, and looking to continue it here in Q4 and into 2027.
Paul Badawi
Tom, I would just add, as you think about Sight Sciences and look out into the future, the world of ophthalmology is becoming more interventional every day. I think the term interventional glaucoma, or IG, has become a household name within the ophthalmic community.
We're pioneering the reimbursed procedural IDE category, and now even go to trade shows, and IDE is becoming a term that is becoming better understood. As the world of ophthalmology and optometry becomes more interventional over time, we're in a very unique position with two proven interventional technologies in OMNI and TearCare that both address the root underlying cause of disease, very consistently clinically effective.
We have data that helps us educate our customers that intervening earlier is clinically better over the long term. We've got dedicated commercial teams focused on these two businesses and focused on these two categories driving intervention, or in practices around the country educating surgeons, office-based ophthalmologists, optometrists, and all of their staff, administrators and staff, on the benefits of intervention, of earlier intervention.
As we continue to execute on that, and we continue to build a leading interventional eye care company, obviously, very attractive growth is going to follow from that over the years to come.
Tom Stephan
Got it. That's great.
Thanks, Paul. Thanks, Jim.
Then my follow-up, just to zero in on TearCare, I'll kind of ask a utilization question in maybe a little bit of a different way, but for the current ordering accounts today or in the third quarter where the utilization was, I believe, about at around 21 in 3Q, how does that compare to what these same accounts were doing, call it two, three years back, prior to reimbursement being part of the equation here for all practices? I guess I'm just curious, how volumes at kind of the current installed base, how those volumes look and are ramping back up now versus maybe these same accounts' previous run rates?
Hopefully that makes sense. Thanks for taking the questions.
Ali Bauerlein
Thanks, Tom, and I'll take that one. I think it's a great question because, first of all, I would say a lot of the account makeup is very different than it was two years ago.
Two years ago, it was really focused on this cash pay market that was driven primarily by optometry practices. Now, the majority of our accounts are collaborative care practices.
About half of them are also IG accounts, and so we see a lot of synergies there. In general, these are higher quality, more durable relationships that we have, where those practices are ordering on a regular frequency because they're using products in that everyday practice environment, where with the cash pay situation, those patient interactions were much less frequent, and so you had ordering patterns that were very variable by account, and there was a lot of lost accounts where they would start and then maybe wouldn't necessarily see the traction on the cash pay and that the volume would kind of fall off.
The quality of those interactions is much higher. We're seeing great patient outcomes and patient feedback that continues on the value of TearCare, and being able to just have something that is a reimbursed procedural option is very attractive to providers who are looking for a better solution versus just telling their patients to use more daily eye drops.
It really is something that we're proud of in terms of that utilization, and again, as I said earlier, we still believe we are really early stage in terms of those utilization, and as we can increase access, that should continue to grow over time as well.
Tom Stephan
Got it. Thanks, Ali.
Congrats on the results.
Ali Bauerlein
Thanks.
Operator
Our next question comes from Steve Lichtman from William Blair. Your line is now open.
Steve Lichtman
Thank you. Hi, guys, and congratulations on the quarter and progress.
Wanted to ask about the label expansion from August. Given the differentiation there, wondering what feedback you've gotten from the field on this, how sort of the education of that label expansion is going, and is it opening up some eyes in terms of accounts that may have been resistant before?
Paul Badawi
I'll start, and then Ali, you want to add thoughts as well, that'd be great. Steve, this is Paul.
We're very proud of the label. It's very consistent with our mission in interventional eye care.
It's consistent with how we approach developing technologies that can elevate the standard of care. Our goal is to equip eye care providers with best-in-class technologies that address the root underlying cause of disease, and we believe that if we can offer those technologies that are either minimally invasive or non-invasive, and do address that underlying cause of disease, do so in a comprehensive, user-friendly manner, then we can differentiate ourselves from a safety, efficacy, and usability perspective.
We believe that's the right way to develop technologies, and to hopefully ultimately elevate the standard of care. Getting this label expansion for TearCare is extremely consistent with that.
It validates our approach, being the first and only MGD technology indicated by the FDA to improve meibomian gland function. Over the past few decades, dry eye disease has been thought of as a problem of aqueous deficiency, when in reality, far more patients suffer from accelerated tear evaporation, and the meibomian glands, as an anatomy, have been overlooked.
We thought that we wanted to challenge that. That wasn't okay.
There are so many patients, millions of patients out there who have diseased meibomian glands, they're obstructed, they need a targeted treatment that targets that underlying cause, and so that's what we've been doing over the past decade with TearCare, finally culminating in this label expansion. I think it just validates how we approach the markets that we serve, and how we expect to partner with our customers and help them elevate the standard of care for patients.
With that, Ali, do you want to add?
Ali Bauerlein
Just to build on that, the field's reaction has been positive to the label expansion. I think for the customers that we already have, frankly, it was intuitive for them.
It was something that they already believed about the value of TearCare because it makes sense. When you think about the technology and the benefits that it provides to the patient, you can draw the parallels between that and improving the signs and symptoms of MGD.
That is great. I do think that it's important for any of the customers who may be on the sidelines and want more clinical data, and our focus on building both the clinical and the label expansion of the technology.
I think a lot of the clinicians do understand that and believe that to be true even without the label expansion. I do think it is really important when we think longer term about society support, and where TearCare fits into the dry eye disease treatment paradigm, and how payers think about the value of the technology.
All of those things are also benefits in addition to providing the benefits to our customers to show the value of the technology.
Paul Badawi
The last thing I'll add to that, Steve, just one final thought, just reminded me of, our head of TearCare marketing, who's phenomenal and has been with us for a long time, he's recently done significant market research into messaging for TearCare, where they'll test 10 different potential messages for TearCare, and I don't know if it was number one or number two, I think it was actually number one, but the message that resonated with both customers and patients the most was that TearCare addresses the root cause or the underlying cause of disease. From a market research and messaging research perspective, you want to test these messages before you roll it out in a meaningful way, and I believe it was number one in terms of impact.
If it wasn't one, it was number two, but it was at the top. We believe it's going to resonate very nicely with the market when we roll out more focus on this label expansion.
Steve Lichtman
That's great. Thanks, Paul.
My follow-up on the label, something that Ali just alluded to, which is in what way can you now utilize that in your discussions with other MACs and payers to really leverage the label expansion?
Ali Bauerlein
Great question, and it's one of many things that we bring to the attention of any of the payers. Obviously, we focus on the clinical data, the label expansion, the health economic data, the claims data, but we also focus on AAO practice patterns, and TFOS DEWS guidelines, and where we fit into that overall treatment paradigm.
All of that just continues to be building blocks to establishing the appropriate access to the technology over time. I don't think there is one building block that makes a difference, but each one continues to build our case for the support for access to TearCare.
Paul Badawi
I'd add, if you're a payer, would you rather pay for a treatment that addresses the underlying cause of disease or for a treatment that just simply temporarily treats a symptom of the disease? I think payers do appreciate solutions that are getting really just at the heart of the problem.
As we've seen from our SAHARA RCT, when you do treat the underlying cause of disease comprehensively, consistently, you're often able to deliver, in the case of dry eye, very consistent improvements, statistically significant improvements in all signs and all symptoms of disease, and in SAHARA's case, at all time points measured.
Steve Lichtman
Great. Thanks, Paul, and thanks, Ali.
Paul Badawi
Thanks.
Operator
Our next question comes from David Saxon from Needham & Company. Your line is now open.
David Saxon
Great. Good afternoon, and thanks for taking my questions.
Maybe I'll ask one with kind of an IX angle. I'd be curious to hear what you're seeing in terms of docs positioning TearCare alongside cataract procedures as kind of like a pre-op treatment or prep for the surgery, and if you're doing anything internally to develop data on kind of how the ocular surface plays its outcome of a cataract surgery.
Paul Badawi
I'll start off, and then Ali chime in. Again, IX is strategically kind of a proprietary differentiation for us.
We've got two proven interventional technologies in two major categories in eye care. When obviously we're in interventional dry eye, and when I say we're in interventional glaucoma, as I'd mentioned earlier, the vast majority of interventional glaucoma cases and revenue is coupled to cataract surgery.
Our IG team has spent years developing very strong partnerships with high-volume cataract surgeons who also happen to be high-volume MIGS surgeons. Those relationships are very useful.
Our IG and IDE teams have been partnering very nicely to leverage those relationships, as Ali had mentioned. There are many patients who have comorbidities.
They might have cataracts, they might have glaucoma, they might have dry eye. They might have two of those, they might have all three of those conditions.
Often that's the case. You often see glaucoma patients who either just have dry eye independently, or the glaucoma meds are exacerbating the dry eye or causing MGD themselves, as is the case with prostaglandin use.
There's a lot of synergy there and a lot of overlap between these conditions. We are, in fact, seeing in our early commercialization of IDE high-volume cataract surgeons have patients who need cataract surgery who also have dry eye disease.
We're seeing those same customers adopt TearCare and perform those TearCare procedures in advance of cataract surgery to treat the dry eye disease in patients that have those comorbidities. We're seeing quite a bit.
We love it. We can be more helpful to our customers who are sharing those patients in the same practice.
David Saxon
Okay. That was helpful.
Thanks, Paul. Then maybe another one for you, Paul.
Just in the script you talked about expectations for fee schedules or policies for TearCare, I'm talking about, in the coming quarters. I'd love to hear what gives you confidence in that, and based on the conversations or signals you're seeing, like anything you can say around whether that be additional policies in the regions you're in, increasing density, or kind of expanding that and going into new regions.
Thanks so much.
Ali Bauerlein
I can take that question, and we really do continue to be confident that we're going to be able to expand patient access over time. That's really based on both the robust clinical evidence that we have, the health economic data, the label expansion, all of those good foundational pieces.
We also are seeing increasing claims submissions and utilization, and that helps payers evaluate these types of new technologies that don't yet have coverage or fee schedules established. Obviously, we don't control the timing of those decisions, and we are engaged with MACs and commercial payers to get those across the finish line, and believe that we're still close to having that happen, but we can't predict the exact timing.
We will continue to focus on driving that. We are seeing more and more individual payments come across, and so we're really happy with the progress there.
Of course, we all want to see that turn into covered lives and expanded access over time.
David Saxon
Great. Thanks so much.
Operator
Our next question comes from the line of Adam Maeder from Piper Sandler. Your line is now open.
Hi, this is Kyle on for Adam. Thanks for taking our questions.
Maybe I'll start with one for Jim. Just given some of these strong opportunities ahead for top-line growth with Ultra and TearCare, how should we think about OpEx spend in the subsequent quarters and into 2027, given the commitment to driving P&L leverage?
It's a great question. Thanks.
I think the overarching theme here and what we've shown year-to-date is that we're going to invest behind the highest, most attractive growth opportunities. We've done that this year in getting back to growth in IDE and continuing to drive growth in IG.
Year-to-date, revenue up 19%, adjusted OpEx down 2%, have demonstrated significant operating leverage as the business has accelerated this year. As we look ahead, for the full year now our guide, top line approximately 20% and adjusted OpEx growing 6% at the midpoint.
Continuing to drive that leverage for the full year here, and as we look ahead, we're going to continue making targeted investments behind the growth opportunities that are most attractive. In the near term, IDE scale-up, commercial resources, market access there are top of mind, and we want to make sure that we're maintaining the fiscal discipline that we've shown, but go after growth and invest behind attractive opportunities.
Over time, driving the revenue growth ahead of expense growth, and having an eye on cash flow breakeven all the while. Great, that's helpful.
Then for my follow-up, maybe if I could just push a little bit on the implied Q4 guidance specifically around TearCare. The updated guidance for 2026 of $12 million, I think, implies a sequential decel, I think, into about 6% growth from Q4 versus Q3, if I'm doing that math right.
Understand it's obviously still early in the launch, but could you just maybe talk through what exactly there should be? Is it kind of just some conservatism baked in here?
I think we've taken a similar approach throughout the year on our IDE guidance. We are very early in the overall market development of this opportunity, and so we don't want to get out ahead of that from a market perspective, and understanding seasonality and trends.
I will say we are extremely proud of what we've created, and we think we are building a durable business. We have great people, great rep productivity, great durability on accounts, and a growing account base, and that's really what we're focused on.
We just want to make sure that the guidance that we put out there takes into account just the fact that we're very early in this overall curve, and that we set the bar appropriately as a result. Got it, that's helpful.
Thank you. Thanks.
Our next question comes from the line of Yen Shi from Associate Analyst. Your line is now open.
Katie Degen
All right, this is Katie on for Yi-Chen with H.C. Wainwright.
In the interest of not beating a dead horse, looking at your 10-Q, it looks like you pushed out your principal amortization until August 2027. How does that affect your flexibility for investments and liquidity plans?
Are you managing towards operating cash flow breakeven before those repayments begin? Or should we expect cash to fund both growth, investment, and debt repayment starting in 2027?
Jim Rodberg
Katie, this is Jim. Thanks for the question.
Really, I think about that extension of the interest-only period as just providing additional optionality and making sure we're being thoughtful with our capital, particularly with the growth opportunities in front of us. We've got a strong balance sheet in place, and importantly, our cash burn has improved significantly year-to-date.
We're continued to be focused on improving cash flow and on our path to cash flow breakeven, but we view this as a prudent capital management decision more than anything else.
Katie Degen
Perfect. Thank you very much.
Jim Rodberg
Thank you.
Operator
I would be showing no further questions at this time. I would now like to turn the call back over to Paul Badawi for closing remarks.
Paul Badawi
Thank you for joining us today. We're very pleased with the record third quarter performance, the trajectory of both franchises, and the continued improvement in our financial profile.
We remain committed to disciplined execution through the balance of the year, and look forward to updating you on our progress next quarter. Thank you.
Operator
Thank you for your participation in today's conference. This does conclude the program.
You may now disconnect.